
 Europe Fetal and Neonatal Monitoring Market | 2026-2036
Europe Fetal and Neonatal Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Fetal and Neonatal Monitoring Market Foresight
Hospital procurement channels across Europe are reshaping how fetal and neonatal monitoring equipment reaches end users, with centralized purchasing consortia gaining influence over device selection. Draegerwerk AG & Co. KGaA leverages its long-standing relationships with German perinatal centers to sustain premium positioning in ventilation-integrated monitoring. GE Healthcare anchors its European presence through broad diagnostic platforms that bundle ultrasound with neonatal surveillance capabilities. Koninklijke Philips NV competes on connected care architectures that link labor ward monitors to enterprise data systems.
Europe fetal and neonatal monitoring encompasses devices and systems that track fetal heart rate, uterine contractions, neonatal vital signs, and oxygenation status through electrocardiographic electrodes, pressure sensors, pulse oximetry, and Doppler ultrasound transducers operating at 1-10 MHz frequencies, primarily deployed to reduce perinatal mortality and neurological injury during labor and early extrauterine transition. Portable devices now lead volume uptake as maternity units prioritize bedside flexibility and intrahospital transport, while integrated systems command the deepest margin pools through their embedded software ecosystems and multi-parameter fusion algorithms. Telemetry-enabled cardiotocography represents the fastest-expanding technology segment, driven by wireless infrastructure investments in renovated birth centers across France, Italy, and Spain.
The EU Medical Device Regulation (MDR) and CE marking framework administered by notified bodies in Germany, the Netherlands, and Ireland are elevating clinical performance documentation burdens for manufacturers, directly extending product development timelines and tightening market access for smaller device firms. EMA coordination with national health technology assessment bodies in France (HAS) and England (NICE) shapes reimbursement thresholds for novel monitoring modalities. Stakeholders must track how the EU AI Act intersects with emerging machine-learning-based fetal heart rate pattern recognition tools to anticipate compliance costs and competitive differentiation pathways.
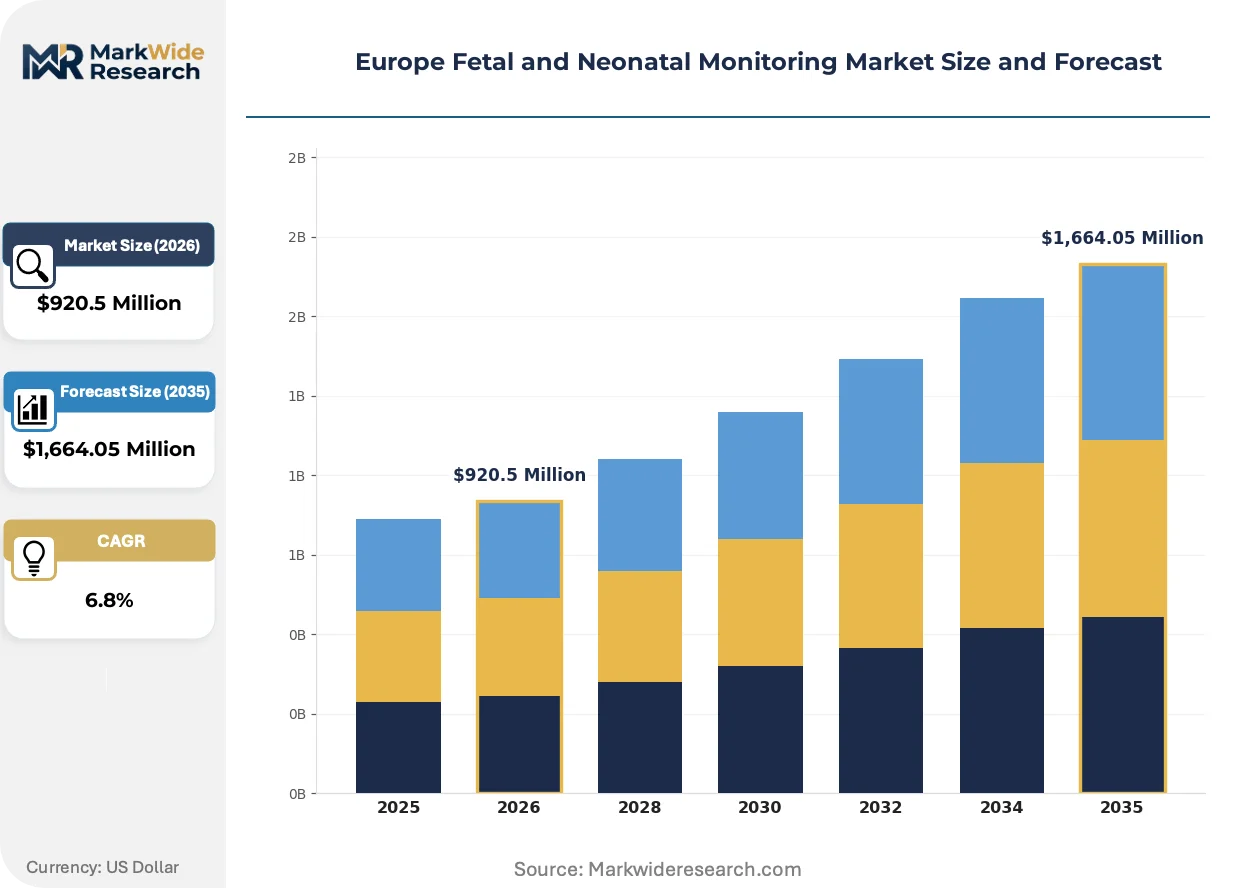
Market Dynamics
Centralized hospital procurement consortia across Germany, France, and the UK are consolidating purchasing power and compressing vendor margins while elevating technical performance requirements for fetal and neonatal monitoring systems.
Growth Catalysts
- EU MDR compliance deadlines:The Medical Device Regulation is accelerating replacement cycles for legacy cardiotocography equipment as maternity wards face 2027-2028 recertification cliffs.
- Telemetry infrastructure investments:Wireless-enabled birth centers in France, Italy, and Spain are pulling demand for untethered maternal-fetal monitoring during active labor.
- Neonatal intensive care capacity expansion:Tertiary perinatal centers in Germany and the Netherlands are adding bed capacity and integrated monitoring suites.
Market Restraints
- Notified body bottleneck:CE marking delays from German and Dutch notified bodies are extending time-to-market for novel fetal heart rate algorithms by 12-18 months.
- Semiconductor supply concentration:Pulse oximetry sensor ASICs depend on concentrated Asian foundry capacity, creating vulnerability for European device assemblers.
- Reimbursement compression:HAS in France and NICE in England are tightening health technology assessment thresholds for premium monitoring modalities.
Strategic Opportunities
- Home-based antenatal surveillance:Portable Doppler and telemetric systems for high-risk pregnancies remain underpenetrated in Spain and Eastern European markets.
- AI-enabled pattern recognition:Machine learning fetal heart rate classification tools align with EU AI Act conformity requirements for high-risk medical device applications.
- Service unbundling:Independent maintenance and calibration providers can capture aftermarket revenue from hospital consortia seeking to reduce OEM dependency.
Industry Challenges
- Clinical engineering talent scarcity:Biomedical technician shortages in UK and Italian maternity networks are delaying device deployment and preventive maintenance.
- Legacy system integration:Proprietary data protocols from 1990s-era installed bases obstruct seamless connectivity with modern enterprise health record architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Fetal and Neonatal Monitoring Market |
| Market Size in 2026 | $920.5 Million |
| Market Size in 2035 | $1,664.05 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrodes, Monitors, Software, Accessories End User: Hospitals, Clinics, Home Care, Research Institutions Technology: Ultrasound, Fetal Dopplers, Cardiography, Telemetry Device Type: Portable Devices, Stationary Systems, Wearable Devices, Integrated Systems |
| Companies Covered | Draegerwerk AG & Co. KGaA, GE Healthcare, Medtronic Plc, F. Hoffmann-La Roche Ltd, Getinge AB, Koninklijke Philips NV, Becton, Dickinson and Company, FUJIFILM SonoSite Inc., Siemens Healthineers, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Fetal and Neonatal Monitoring Market Shifts & Advancements
Wireless telemetry and artificial intelligence are converging to transform how fetal distress is detected and communicated across European labor wards, compressing response times while raising data governance requirements.
Multi-parameter sensor fusion is digitizing cardiotocography by combining fetal electrocardiography, uterine pressure, and maternal pulse oximetry into single-platform displays. German university hospitals are piloting these systems at scale. The technology is digitizing clinical workflow by eliminating manual chart correlation and enabling automated alerts to on-call obstetric teams.
The EU AI Act's high-risk system classification is imposing conformity assessment burdens on machine learning-based fetal monitoring software. Manufacturers must demonstrate algorithmic transparency and post-market performance monitoring. French and Dutch notified bodies are developing specialized review pathways for these applications, creating first-mover advantages for prepared submitters.
Consolidated purchasing by regional hospital networks is displacing single-facility procurement across England and Scandinavia. Framework agreements now bundle fetal monitors with enterprise IT infrastructure and multi-year service contracts. NHS Supply Chain and similar entities in Sweden and Denmark are extracting volume discounts while standardizing device platforms across affiliated birth centers.
Europe Fetal and Neonatal Monitoring Market Segmentation
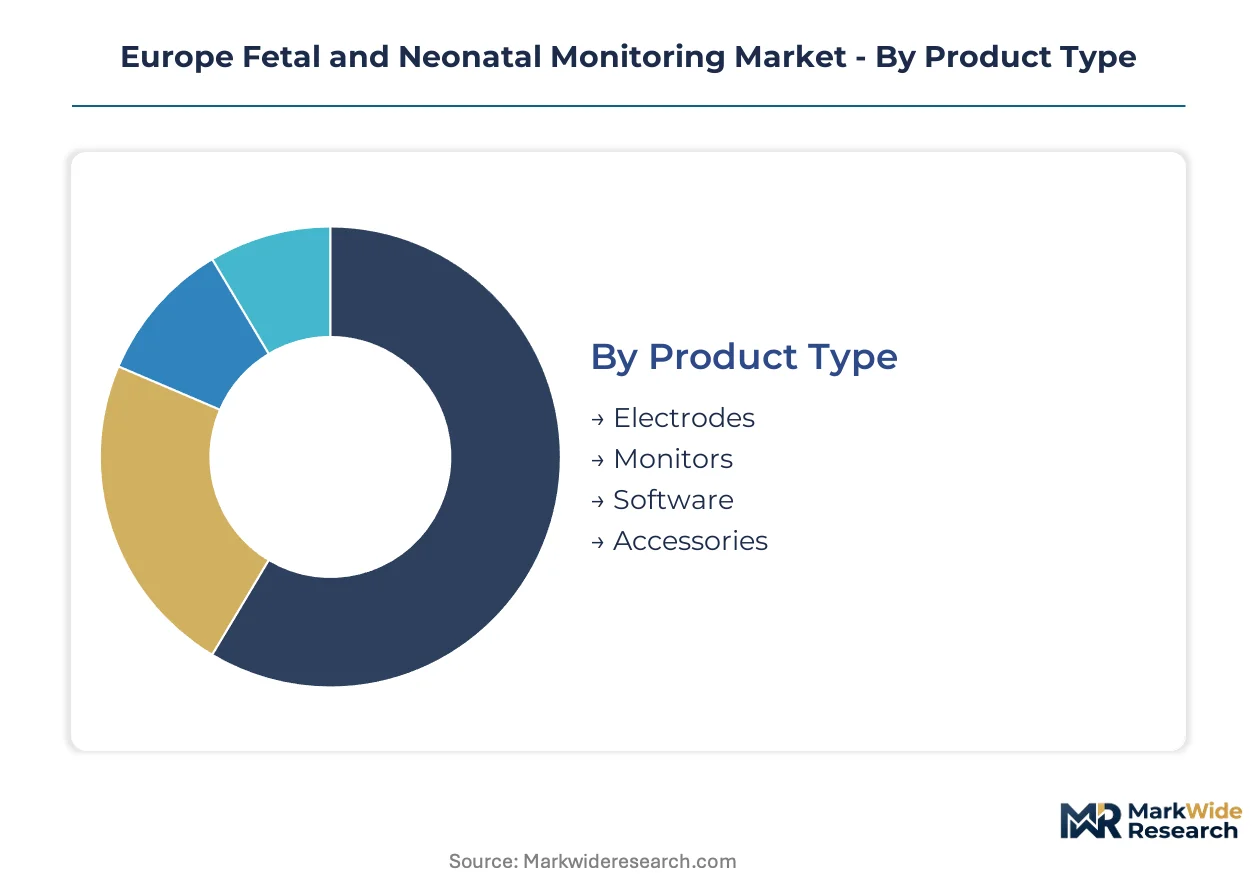
Segmentation in the Europe fetal and neonatal monitoring market reveals how clinical workflow demands, regulatory pathways, and procurement economics fragment purchasing decisions across maternity networks. Understanding these divides exposes where technology investments concentrate and where unmet needs persist.
Product Type:
The use-case spectrum spans disposable consumables through enterprise software platforms, with margin structures inverting sharply between single-use electrodes and perpetual-license monitoring suites.
- Electrodes:Single-use ECG and uterine pressure electrodes with conductive gel interfaces dominate volume consumption. German hospital consortia negotiate multi-year electrode supply contracts tied to monitor hardware purchases, locking in predictable per-procedure costs.
- Monitors:Multi-parameter bedside units integrating cardiotocography, pulse oximetry, and maternal vital signs command premium positioning. French tertiary perinatal centers prioritize monitors with wireless telemetry modules to support ambulatory labor.
- Software:Pattern recognition algorithms and enterprise connectivity layers for labor ward data integration.
- Accessories:Transducer belts, cables, and calibration tools for device maintenance and repair cycles.
The dominant share belongs to Monitors, while Software is closing the gap fastest as EU AI Act compliance creates pull for validated algorithmic tools.
End User:
Procurement authority concentrates differently across facility types, with centralized purchasing in hospital networks displacing independent clinic decision-making.
- Hospitals:Tertiary maternity wards and neonatal intensive care units with 24-hour monitoring requirements. UK NHS trusts bundle fetal monitor procurement with enterprise IT infrastructure, extracting volume discounts across affiliated birth centers.
- Clinics:Outpatient obstetric practices with intermittent monitoring needs and lower capital budgets.
- Home Care:Portable Doppler and telemetric systems for high-risk pregnancy surveillance. Spanish regional health services pilot home-based cardiotocography programs to reduce emergency admissions.
- Research Institutions:University hospitals conducting clinical trials on novel monitoring modalities.
Hospitals absorb the majority of capital expenditure, though Home Care is expanding most quickly as telehealth reimbursement frameworks mature in Southern Europe.
Technology:
Underlying detection principles determine regulatory classification complexity and interoperability requirements under EU MDR.
- Ultrasound:1-10 MHz Doppler transducers for fetal heart rate and movement detection. Dutch university medical centers deploy ultrasound-integrated platforms combining anatomical imaging with functional monitoring.
- Fetal Dopplers:Handheld continuous-wave devices for intermittent auscultation in outpatient settings.
- Cardiography:Direct fetal electrocardiography via scalp electrodes or abdominal sensors for ST-segment analysis. German perinatal centers lead adoption of cardiography-enhanced cardiotocography for intrapartum hypoxia detection.
- Telemetry:Wireless transmission architectures enabling maternal mobility during active labor. Italian birth center renovations prioritize telemetry infrastructure to support water birth and upright positioning protocols.
Ultrasound retains the largest installed base, yet Telemetry is gaining share fastest as wireless infrastructure investments accelerate across renovated European labor wards.
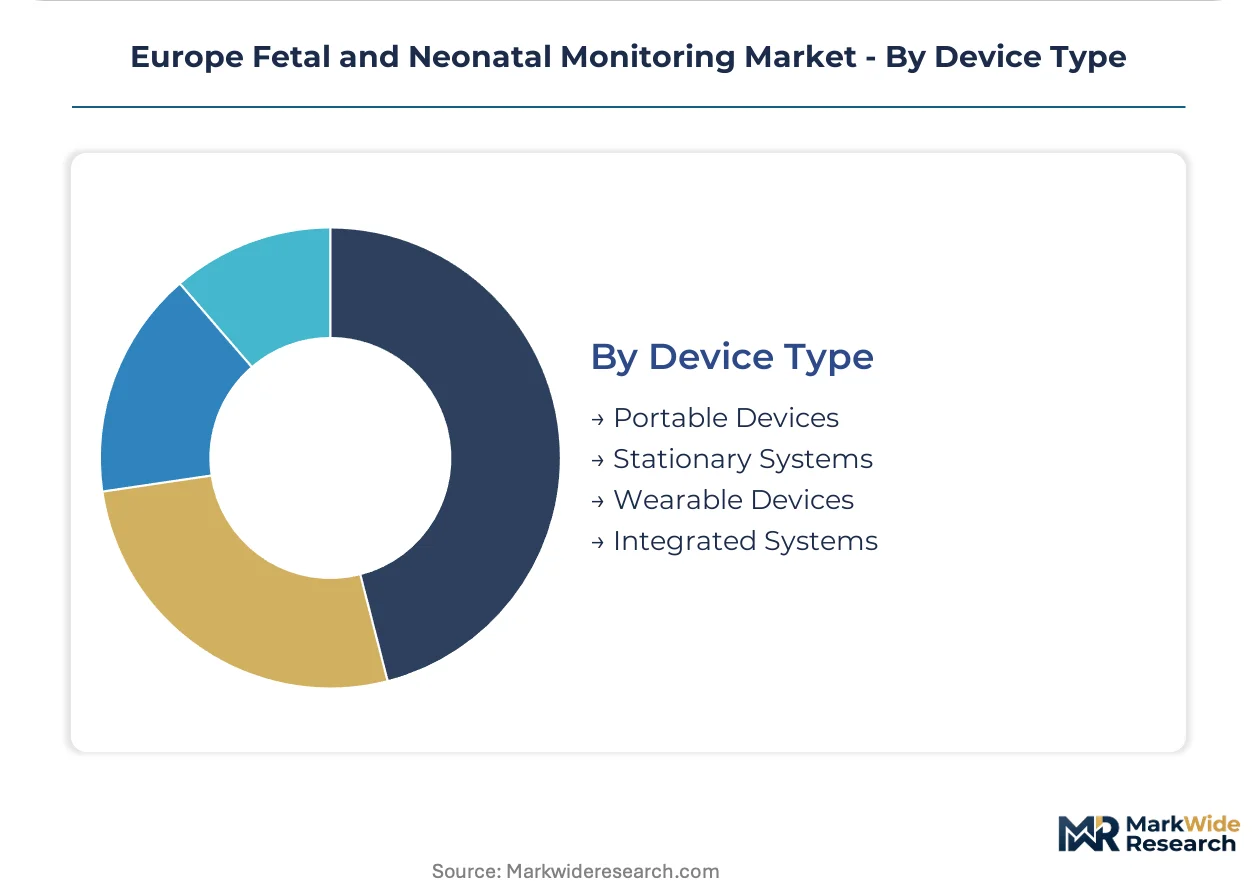
Device Type:
Form factor trade-offs between bedside capability and transport flexibility shape how maternity units configure monitoring fleets.
- Portable Devices:Battery-powered units with detachable transducers for intrahospital transport and emergency delivery. French hospital groups specify portable monitors with identical user interfaces to stationary units, reducing training burden.
- Stationary Systems:Fixed-installation multi-parameter suites with integrated displays and alarm management.
- Wearable Devices:Patch-based sensors for continuous ambulatory monitoring without transducer belts. Research pilots in Netherlands university hospitals test wearable electrocardiography for outpatient fetal surveillance.
- Integrated Systems:Enterprise platforms linking labor ward monitors to neonatal intensive care and hospital information systems. German perinatal centers demand integrated systems with ventilation-synchronized monitoring for complex deliveries.
Stationary Systems maintain the deepest penetration, though Portable Devices are climbing the fastest as maternity units prioritize flexibility across birth center layouts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CE marking administered by German and Dutch notified bodies anchors regulatory compliance across the continent, shaping how fetal and neonatal monitoring equipment reaches maternity wards in Western and Southern Europe.
Germany
Bundesinstitut für Arzneimittel und Medizinprodukte (BfArM) oversees notified body designation for high-risk obstetric devices. Bavarian university hospitals in Munich and Erlangen pilot integrated cardiotocography-ventilation platforms for complex deliveries. North Rhine-Westphalia's perinatal networks consolidate procurement through regional hospital associations, compressing vendor margins while elevating technical specifications.
United Kingdom
NICE technology appraisals determine reimbursement thresholds for novel neonatal monitoring modalities across NHS trusts. London and Southeast England maternity networks bundle fetal monitor procurement with enterprise IT infrastructure through NHS Supply Chain framework agreements. Midlands perinatal centers face clinical engineering talent shortages that delay device deployment and preventive maintenance cycles.
France
Haute Autorité de Santé (HAS) health technology assessments tighten access to premium monitoring modalities in tertiary perinatal centers. Île-de-France birth centers renovate telemetry infrastructure to support ambulatory labor and water birth protocols. Auvergne-Rhône-Alpes regional health services pilot home-based cardiotocography programs to reduce emergency admissions from high-risk pregnancies.
Italy
Italian birth center renovations prioritize wireless telemetry to support upright positioning and maternal mobility during active labor. Northern Italian hospital groups specify portable monitors with identical user interfaces to stationary units, reducing training burden across Lombardy and Veneto facilities. Southern regions lag in infrastructure investment, creating penetration gaps for advanced monitoring suites.
Netherlands
Dutch university medical centers in Amsterdam and Rotterdam deploy ultrasound-integrated platforms combining anatomical imaging with functional fetal monitoring. National perinatal registry data drives quality improvement investments in tertiary NICU capacity expansion. Notified body review specialization for AI-enabled monitoring software creates first-mover advantages for prepared submitters.
Europe Fetal and Neonatal Monitoring Market Competitive Landscape
Diversified medical technology conglomerates and specialized perinatal equipment manufacturers split the market along integration depth and clinical focus vectors. German and US-based conglomerates leverage diagnostic platform breadth to bundle ultrasound with neonatal surveillance capabilities. Dutch and Swedish specialists compete on connected care architectures and ventilation-integrated monitoring. Consolidated hospital procurement across England and Scandinavia forces portfolio diversification and multi-year service contract bundling.
Among diversified conglomerates, GE Healthcare and Siemens Healthineers exemplify platform-bundling strategies that span diagnostic imaging through critical care monitoring. Koninklijke Philips NV occupies a position in connected care architectures linking labor ward monitors to enterprise data systems. Specialized perinatal players including Draegerwerk AG & Co. KGaA and Getinge AB represent ventilation-integrated monitoring expertise anchored in long-standing German and Swedish hospital relationships.
| Leading Market Players |
|---|
| Draegerwerk AG & Co. KGaA |
| GE Healthcare |
| Medtronic Plc |
| F. Hoffmann-La Roche Ltd |
| Getinge AB |
| Koninklijke Philips NV |
| Becton, Dickinson and Company |
| FUJIFILM SonoSite Inc. |
| Siemens Healthineers |
| Others |
Supply & Pricing Matrix
Single-source dependency on Asian foundry capacity for pulse oximetry sensor ASICs determines both the premium commanded by vertically integrated manufacturers and the vulnerability of European device assemblers to supply disruption. CE marking bottlenecks from German and Dutch notified bodies further compress margins for smaller firms unable to absorb extended regulatory timelines.
Pricing Analysis
The customization-premium spread separates configured-to-order integrated monitoring suites from standard cardiotocography hardware. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade under EU MDR and after-sales service bundling. Cost compression in the economy tier is intensifying because hospital consortia extract volume discounts through multi-year framework agreements. NHS trusts and Scandinavian purchasing networks demonstrate highest price sensitivity, while German tertiary perinatal centers prioritize technical specifications over unit cost.
Supply Chain Analysis
Contract-manufacturing concentration for sensor fabrication rests with Taiwanese and South Korean foundries, while final device assembly concentrates in Germany, the Netherlands, and Ireland. Raw material dependencies include medical-grade silicon wafers, conductive polymers for electrode interfaces, and rare-earth elements for Doppler transducer ceramics. Single-source vulnerability in semiconductor supply creates exposure to logistics chokepoints through concentrated Asian shipping lanes. Distribution runs through centralized hospital procurement consortia that bypass traditional medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
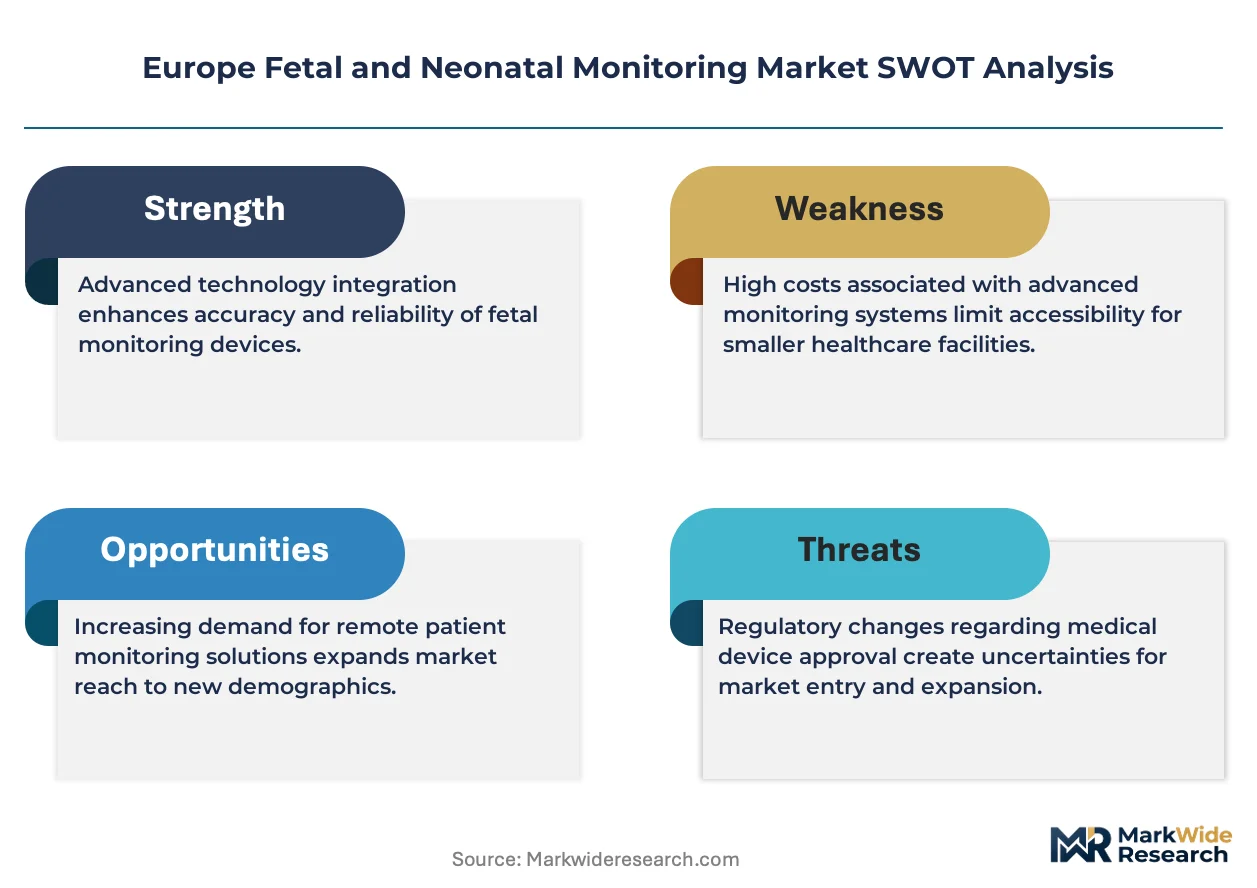
Telemetry-enabled cardiotocography and AI-pattern recognition represent high-growth disruption vectors as EU AI Act compliance deadlines reshape competitive access. The convergence of wireless infrastructure investment and algorithmic validation requirements creates a narrow window for positioning.
For Market Incumbents: Entrench market position through backward integration into sensor manufacturing to reduce foundry dependency, and accelerate CE marking submissions for AI-enabled software modules ahead of notified body queue formation. Draegerwerk and Philips face emerging entrant pressure in telemetry architectures; defensive patent filings around multi-parameter fusion algorithms provide channel control leverage. For New Entrants and Emerging Players: Build out portable Doppler and home-based telemetric offerings for Spain and Eastern European markets where hospital infrastructure remains fragmented. The most penetrable segment lies in high-risk pregnancy outpatient surveillance, where regional health services pilot reimbursement frameworks. A direct-to-clinic go-to-market angle bypasses consolidated hospital procurement gatekeepers. For Investors and Strategic Acquirers: The market sits at a regulatory-inflection phase that favors vertically integrated platforms with established notified body relationships. Long-term viability centers on software-enabled recurring revenue models rather than hardware transaction cycles. Acquisition target archetypes include AI-software specialists with validated fetal heart rate classification tools. The signal to watch is HAS and NICE reimbursement determinations for telemetry-enabled modalities.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | Early engagement with German and Dutch notified bodies secures queue position ahead of MDR recertification cliffs. |
| Hospital System Partnership | Framework agreements with NHS Supply Chain and Scandinavian consortia lock in multi-year volume commitments. |
| Software Companion Development | AI-enabled pattern recognition modules align with EU AI Act high-risk system requirements and command recurring licensing. |
| Backward Integration | In-house pulse oximetry sensor production reduces exposure to Asian foundry concentration and tariff volatility. |
| Reimbursement Strategy | HAS and NICE health technology assessment navigation determines access to French and English tertiary perinatal centers. |
Research Methodology
Initial hypotheses were tested against primary input from obstetricians, hospital procurement committee members, biomedical engineers, and GPO contracts managers, and refined through secondary validation against EMA coordination documents, EU MDR implementation guidance, HAS technology assessment records, NICE appraisal documentation, and hospital procurement databases. Bottom-up demand modeling across product type, end user, technology, and device type segments was cross-checked against top-down macroeconomic indicators.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product category, facility tier, detection principle, and form factor. CAGRs were derived from installed base replacement cycles, capacity expansion pipelines, and technology diffusion curves. Forecast inputs incorporated EU MDR compliance deadlines, telemetry infrastructure investment schedules, and neonatal intensive care bed expansion plans.
Stress conditions across notified body review timelines, semiconductor supply availability, and reimbursement threshold adjustments were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory pathway durations and infrastructure investment commitments. Quarterly review of CE marking queue lengths, hospital consortia tender announcements, and AI Act implementing guidance is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Remote Patient Monitoring Software and Services Market
Patient Monitoring
Multiparameter Patient Monitoring System Market
Patient Monitoring
B-Ketone Monitoring System Market
Patient Monitoring
United States Patient Monitoring Market
Patient Monitoring
Europe Cardiac Holter Monitor Market
Patient Monitoring
Continuous Cardiac Monitoring Devices Market
Patient Monitoring
Europe Wireless Healthcare Market
Patient Monitoring
Blood Temperature Indicator Market
Patient Monitoring
Saudi Arabia Patient Monitoring Market
Patient Monitoring
Pre-Mature Baby Monitoring Equipment Market
Patient Monitoring
North America Patient Monitoring Market
Patient Monitoring
Wearable Cardiac Monitors Market
Patient Monitoring
South America Patient Monitoring Market
Patient Monitoring
Healthcare Biosensors IoT Market
Patient Monitoring
Global Patient Monitoring Market
Patient Monitoring
United States Cardiac Holter Monitor Market