
 Asia-Pacific Respiratory Monitoring Market | 2026-2036
Asia-Pacific Respiratory Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Respiratory Monitoring Market Outlook
Silicone is hardening as the preferred interface material in nasal cannulas and mask assemblies, replacing thermoplastic elastomers across mid-range and premium product tiers. Medtronic PLC leverages its polymer science capabilities to sustain cost advantages in high-flow nasal cannula manufacturing. Dragerwerk AG & Co. KGaA anchors its position through intensive R&D spending on ventilator-integrated monitoring platforms. ResMed competes aggressively in sleep apnea applications with proprietary algorithm-driven diagnostics.
Asia-Pacific respiratory monitoring encompasses devices that measure pulmonary function, gas exchange, and breathing mechanics through sensors detecting flow rates, oxygen saturation, and airway pressure, typically operating across ranges of 0-120 liters per minute for adult applications. Spirometers remain the most mature product category with established reimbursement pathways, while portable monitors represent the fastest-expanding segment as wireless connectivity and battery efficiency improve. Smart technology integration is displacing conventional monitoring in hospital settings, though wearable devices command the strongest margin pools in homecare channels where patient compliance data drives recurring revenue models.
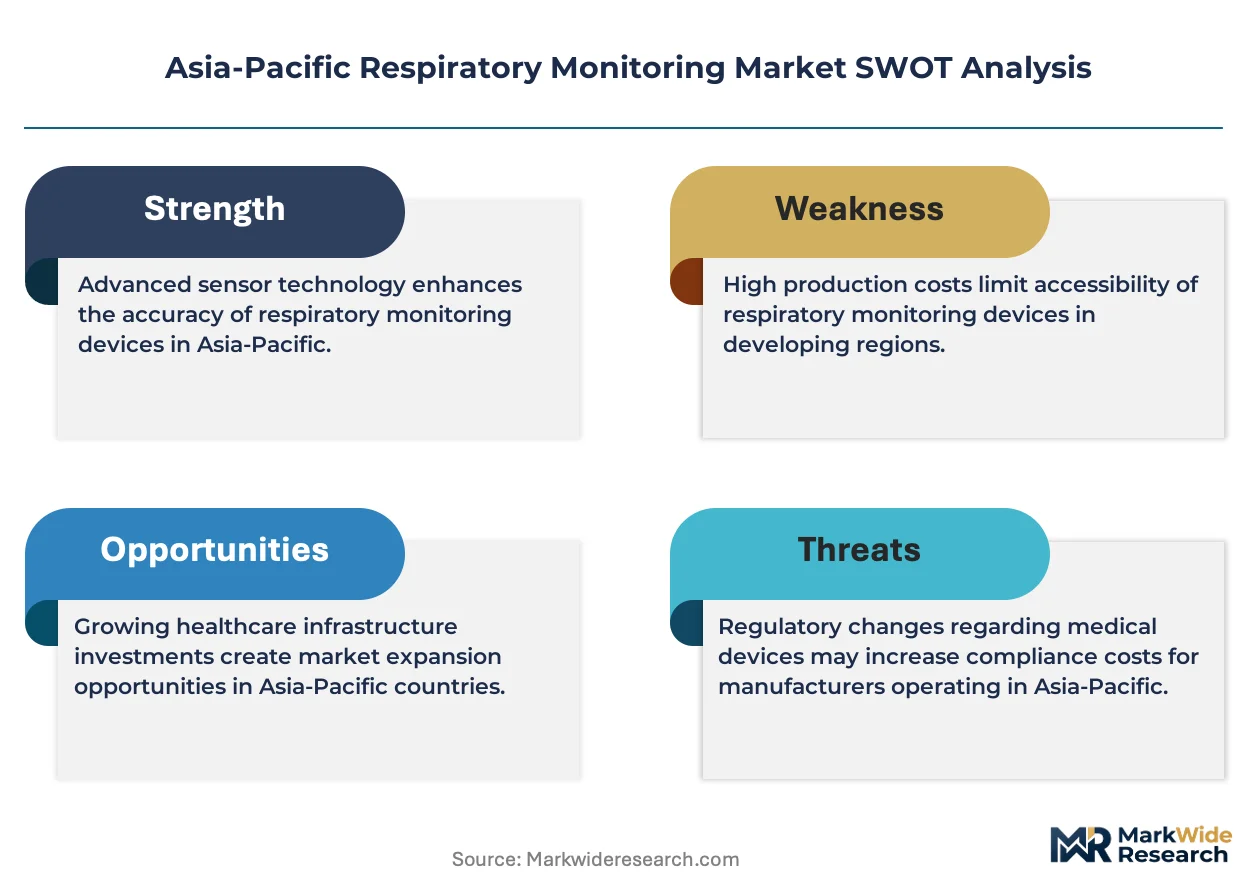
Japan's PMDA and Australia's TGA enforce divergent clinical evidence requirements for software-as-medical-device claims, creating fragmented registration timelines for AI-enabled diagnostic features. India's CDSCO medical device rules and China's NMPA innovation fast-track pathways are reshaping how manufacturers sequence market entry across the region. Stakeholders must weigh regulatory capital requirements against localized production incentives when allocating manufacturing footprint and clinical trial resources.
Market Dynamics
The Asia-Pacific respiratory monitoring market is being fundamentally restructured by India's PLI scheme for medical devices, which is absorbing capital flows toward domestic manufacturing capacity and altering how multinational suppliers configure their regional production footprints.
Growth Catalysts
- Japan's aging demographics:Chronic respiratory disease prevalence among the elderly sustains hospital procurement of advanced monitoring systems with integrated diagnostic capabilities.
- CDSCO medical device rules:India's streamlined registration pathways are accelerating market entry timelines for portable monitors and homecare devices.
- Wireless connectivity advancement:Bluetooth Low Energy and 5G module integration is enabling real-time data transmission from wearable respiratory monitors to cloud-based clinical platforms.
Market Restraints
- Silicone supply concentration:High-purity medical-grade silicone for nasal cannula interfaces depends on concentrated specialty chemical suppliers in Northeast Asia.
- PMDA software-as-medical-device requirements:Japan's divergent clinical evidence standards for AI-enabled diagnostic features fragment registration timelines across the region.
- Spirometer reimbursement rigidity:Established payment pathways for mature product categories limit pricing flexibility for manufacturers introducing enhanced functionality.
Strategic Opportunities
- Homecare channel expansion:Patient compliance data monetization through recurring revenue models offers margin pools superior to hospital procurement in Australia and Southeast Asia.
- NMPA innovation fast-track:China's accelerated approval pathways for breakthrough respiratory devices enable first-mover positioning in the world's second-largest healthcare market.
- Battery efficiency convergence:Solid-state power systems combined with edge computing are creating untapped application space for continuous ambulatory monitoring.
Industry Challenges
- Embedded software certification:TGA's evolving cybersecurity requirements for connected respiratory devices extend compliance timelines for Australian market entry.
- Legacy hospital IT integration:HL7 FHIR interoperability standards remain inconsistently implemented across Japan's fragmented hospital network infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Respiratory Monitoring Market |
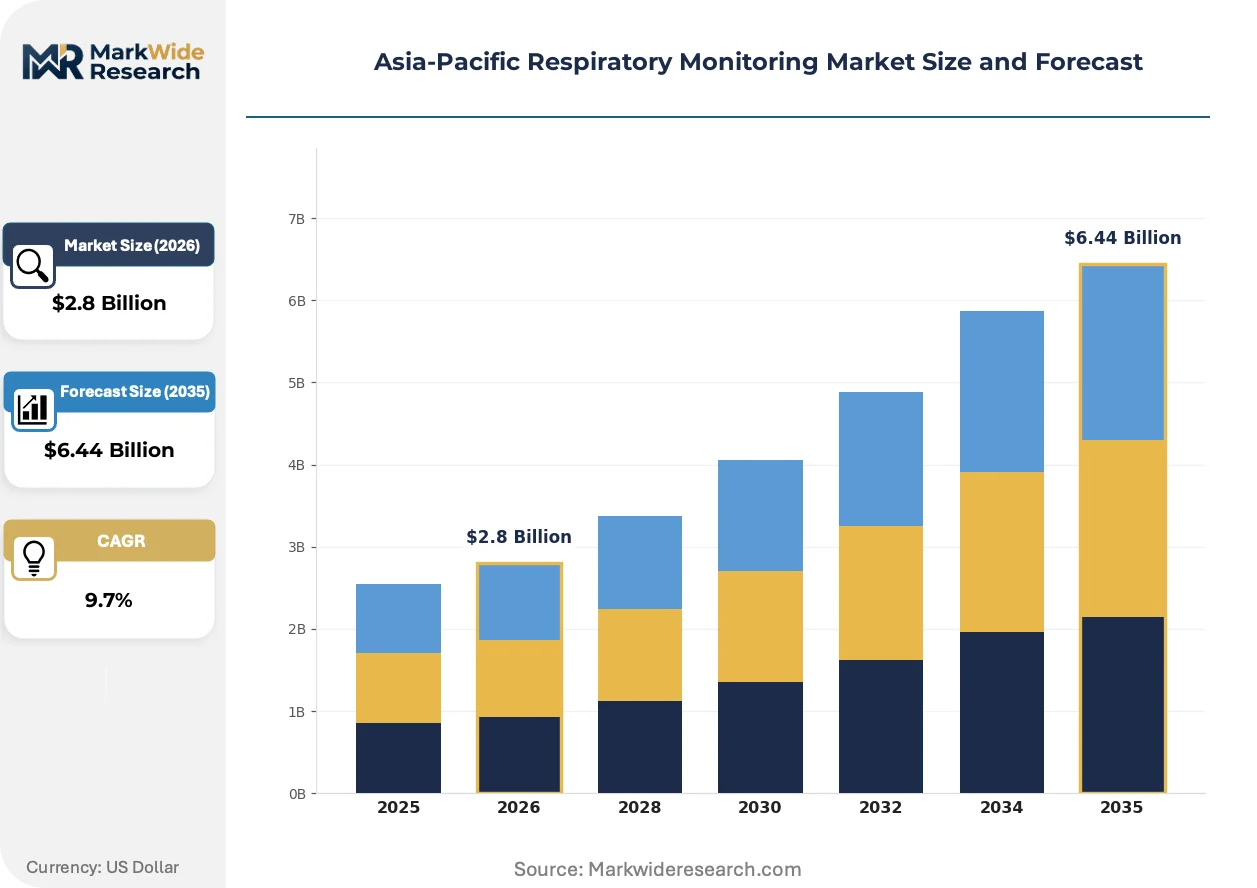
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.44 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Monitors, Spirometers, Oximeters, High-Flow Nasal Cannulas Technology: Smart Technology, Wearable Devices, Conventional Monitoring, Mobile Applications End User: Hospitals, Homecare Settings, Clinics, Research Institutions Application: Chronic Obstructive Pulmonary Disease, Sleep Apnea, Asthma Management, Respiratory Infections |
| Companies Covered | Medtronic PLC, Dragerwerk AG & Co. KGaA, ResMed, GE Healthcare, Koninklijke Philips N.V, Masimo Corporation, Fisher & Paykel Healthcare Ltd, Hamilton Medical, Nihon Kohden, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Respiratory Monitoring Market Strategic Shifts
Sensor miniaturization and algorithmic diagnostic advancement are compressing the functional boundary between clinical-grade and consumer respiratory monitoring, forcing incumbents to defend premium positioning through software differentiation rather than hardware specifications alone.
Optical flow sensing is absorbing the measurement function previously performed by mechanical pneumotachographs in portable spirometers. Homecare providers across Australia and South Korea are adopting these solid-state alternatives for remote patient monitoring programs. The technology is absorbing cost from device manufacturing while expanding the addressable patient population through disposable sensor economics.
China's NMPA has implemented mandatory cybersecurity review protocols for cloud-connected respiratory monitors under its medical device data security framework. Manufacturers must now submit penetration testing documentation alongside traditional clinical efficacy data. Sleep apnea diagnostic platforms with integrated cellular transmission modules face the most intensive scrutiny, with several applicants restructuring their data architecture to maintain compliance.
Hospital procurement committees are consolidating vendor relationships around integrated platform contracts rather than standalone device purchases. This behavioral shift favors suppliers offering ventilator-integrated monitoring ecosystems over point-solution specialists. The pattern is most pronounced in Japan's university hospital networks, where capital budget constraints favor multi-year service agreements with single-source accountability.
Asia-Pacific Respiratory Monitoring Market Segmentation
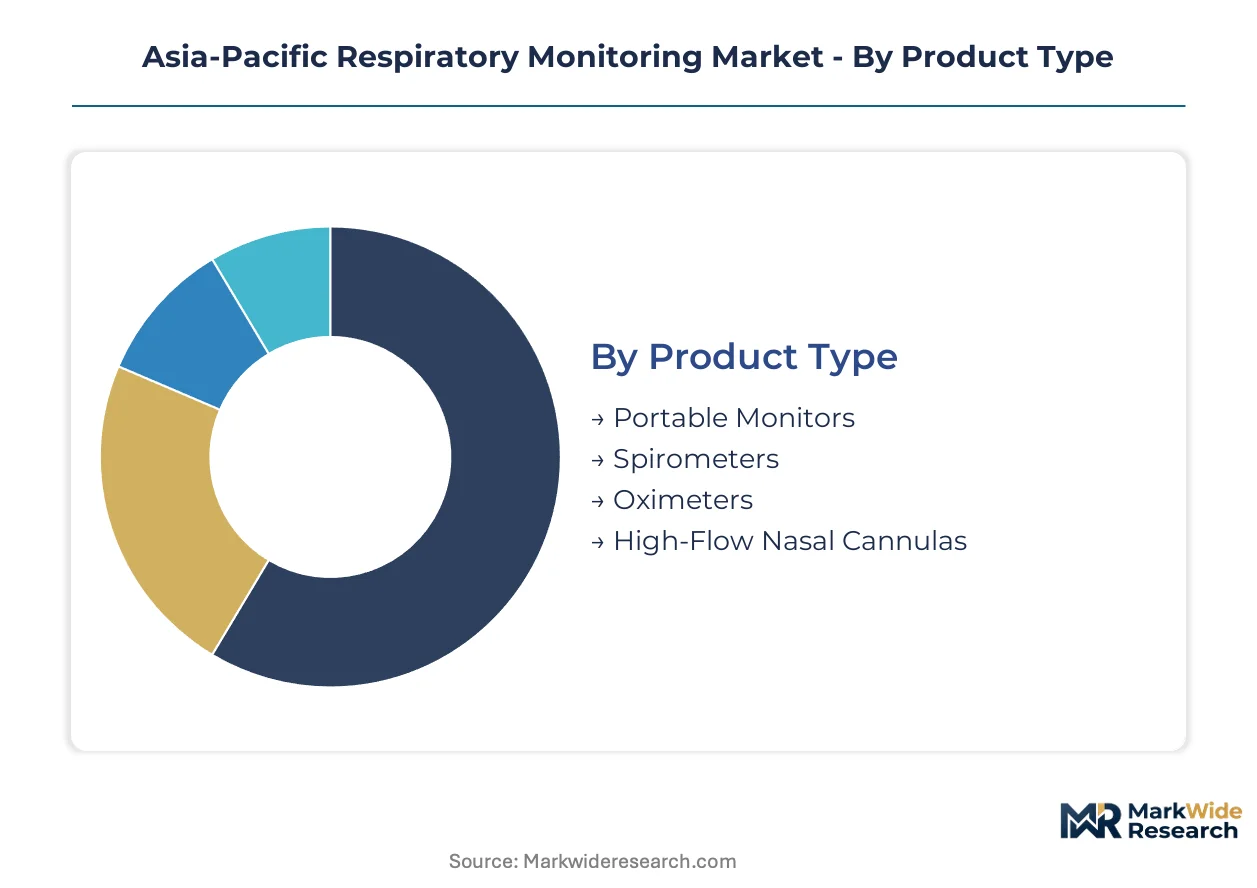
Respiratory monitoring in Asia-Pacific fragments across four dimensions that determine pricing power and channel strategy. Product type separates capital-intensive hospital systems from disposable homecare consumables. Technology tier dictates whether vendors compete on hardware specifications or software-enabled recurring revenue.
Product Type:
Standalone bedside units dominate hospital procurement budgets, while portable and wearable formats embed into broader patient management ecosystems.
- Portable Monitors:Battery-powered devices with wireless telemetry capability, typically weighing under 2 kilograms for ambulatory use. Australian homecare providers and South Korean telemedicine platforms are absorbing these units fastest as remote patient monitoring programs expand reimbursement eligibility.
- Spirometers:Pulmonary function testing equipment measuring forced expiratory volume and peak flow rates through mechanical or optical sensing. Japan's hospital procurement committees favor these for COPD screening programs, though established reimbursement codes limit pricing flexibility for enhanced functionality.
- Oximeters:Pulse oximetry devices for non-invasive oxygen saturation monitoring.
- High-Flow Nasal Cannulas:Heated and humidified oxygen delivery systems with integrated flow sensing.
Spirometers lead volumes today; portable monitors are gaining share fastest.
Technology:
Cost tier stratification separates premium algorithm-driven platforms from basic measurement tools, with mid-range hybrids capturing expanding clinical budgets.
- Smart Technology:AI-enabled diagnostic platforms with cloud connectivity and predictive analytics for early deterioration detection. China's NMPA fast-track pathway is accelerating approvals for these systems, while Japan's PMDA imposes additional software-as-medical-device evidentiary requirements that fragment regional launch timelines.
- Wearable Devices:Continuous monitoring patches and smart garments with embedded respiratory sensors. These command superior margin pools in Australian and Southeast Asian homecare channels where patient compliance data enables subscription-based revenue models.
- Conventional Monitoring:Standalone devices without connectivity or algorithmic processing.
- Mobile Applications:Software-only diagnostic tools leveraging smartphone sensors and cameras.
Conventional monitoring retains installed base dominance; wearable devices show the steepest expansion trajectory.
End User:
Customer type determines procurement complexity, with institutional buyers demanding integration proof points and individual consumers prioritizing ease of use.
- Hospitals:Acute care facilities requiring ventilator-integrated monitoring ecosystems with multi-parameter dashboards. Japan's university hospital networks are consolidating vendor relationships around platform contracts with multi-year service agreements rather than standalone device purchases.
- Homecare Settings:Patient-managed environments where wireless connectivity and battery efficiency drive adoption. India's CDSCO streamlined registration pathways are accelerating market entry for devices targeting this channel.
- Clinics:Outpatient facilities with intermediate throughput and capital constraints.
- Research Institutions:Academic and clinical trial sites requiring specialized data capture protocols.
Hospitals absorb the largest absolute spending; homecare settings are climbing the fastest.
Application:
Disease prevalence patterns across Asia-Pacific geographies concentrate demand in specific monitoring modalities, with aging demographics and air quality driving regional variation.
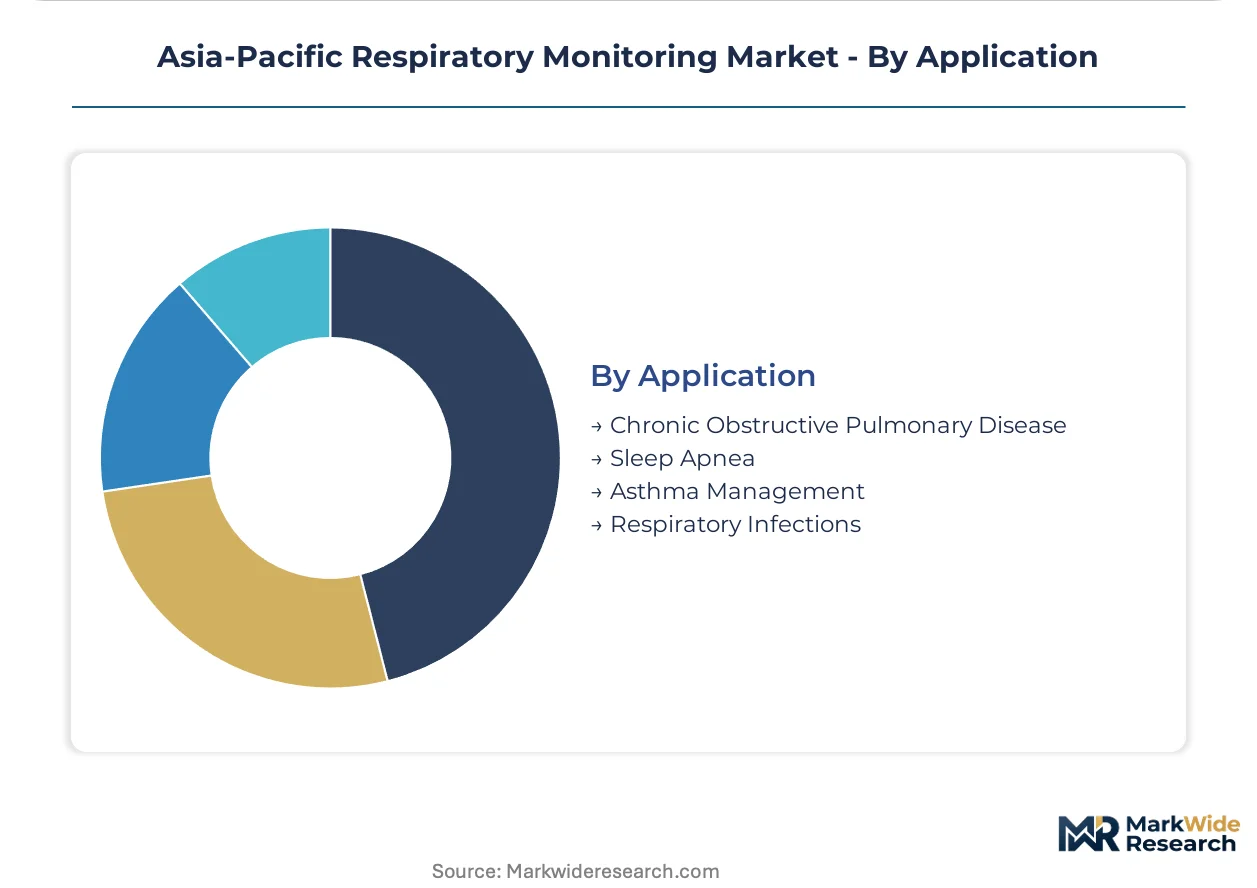
- Chronic Obstructive Pulmonary Disease:Progressive airflow limitation requiring longitudinal lung function tracking. Japan's elderly population sustains hospital procurement of advanced diagnostic systems with integrated spirometry and gas exchange analysis.
- Sleep Apnea:Disordered breathing during sleep diagnosed through polysomnography or home sleep testing. China's NMPA cybersecurity review protocols impose mandatory penetration testing on cloud-connected diagnostic platforms with cellular transmission modules.
- Asthma Management:Reversible airway obstruction monitored through peak flow and symptom tracking.
- Respiratory Infections:Acute viral and bacterial conditions requiring rapid oxygen saturation and respiratory rate assessment.
COPD applications anchor current revenue; sleep apnea diagnostics are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Osaka-Kobe's medical device manufacturing corridor anchors respiratory monitor production capacity across the Asia-Pacific region. India's CDSCO registration reforms and China's NMPA fast-track pathways are accelerating product approvals. Australia's TGA cybersecurity mandates reshape data architecture requirements for cloud-connected devices.
Japan
Japan's elderly population sustains hospital procurement of advanced diagnostic systems with integrated spirometry capabilities. PMDA software-as-medical-device requirements impose additional evidentiary burdens for AI-enabled features. Tokyo's university hospital networks consolidate vendor relationships around multi-year platform service agreements.
China
China's chronic air quality challenges expand the addressable patient population for portable monitoring devices. NMPA mandatory cybersecurity review protocols require penetration testing documentation for cloud-connected respiratory platforms. Shanghai's medical device innovation clusters absorb manufacturing investment from multinational suppliers restructuring data architectures.
India
India's homecare channel expansion drives portable monitor adoption as patients shift from institutional settings. CDSCO streamlined registration pathways accelerate market entry timelines for wireless-enabled devices. Maharashtra's PLI scheme beneficiaries absorb capital flows toward domestic manufacturing capacity.
Australia
Australia's telemedicine reimbursement expansion enables remote patient monitoring program growth across regional healthcare networks. TGA evolving cybersecurity requirements for connected devices extend compliance timelines. Sydney and Melbourne homecare providers adopt subscription-based revenue models leveraging patient compliance data.
South Korea
South Korea's digital health infrastructure investment supports wearable respiratory monitor integration into national telemedicine platforms. MFDS regulatory alignment with international standards facilitates faster approval pathways for Bluetooth-enabled devices. Seoul's healthcare technology clusters concentrate R&D activity for solid-state sensor miniaturization.
Asia-Pacific Respiratory Monitoring Market Competitive Environment
Strategic partnerships dominate the current landscape as manufacturers seek integrated platform positioning. The vendor base separates into three tiers: diversified medical technology conglomerates, respiratory-focused specialists, and emerging regional fabricators. Two strategic archetypes define competitive positioning: ventilator-integrated ecosystem builders and algorithm-driven diagnostic platform developers. Portfolio diversification and geographic licensing agreements represent the dominant competitive moves reshaping market structure.
Among diversified medical technology conglomerates, Medtronic PLC and GE Healthcare exemplify scale-driven platform strategies. ResMed occupies a position within the respiratory-focused specialist tier, anchoring sleep apnea diagnostic applications. Dragerwerk AG & Co. KGaA represents the ventilator-integrated ecosystem archetype through its intensive R&D positioning. These three companies illustrate how competitive advantage separates across hardware manufacturing scale, software algorithm differentiation, and clinical workflow integration depth.
| Leading Market Players |
|---|
| Medtronic PLC |
| Dragerwerk AG & Co. KGaA |
| ResMed |
| GE Healthcare |
| Koninklijke Philips N.V |
| Masimo Corporation |
| Fisher & Paykel Healthcare Ltd |
| Hamilton Medical |
| Nihon Kohden |
| Others |
Value Chain & Pricing Dynamics
China's mandatory cybersecurity review protocols for cloud-connected medical devices gate qualified supply access and premium-tier pricing power for respiratory monitoring platforms with integrated cellular transmission modules. Manufacturers restructuring data architectures to maintain NMPA compliance absorb certification costs that concentrate margin capture among suppliers with established penetration testing documentation.
Pricing Analysis
Input-cost pass-through from high-purity medical-grade silicone suppliers in Northeast Asia shapes margin structures for nasal cannula and mask assembly manufacturers. Three-tier pricing structure across premium algorithm-driven platforms, standard connected devices, and economy conventional monitors separates buyers by integration complexity and software capability. Pricing pressure stems from spirometer reimbursement rigidity in Japan's established COPD screening programs, where procurement committees resist enhanced functionality premiums. Hospital systems demonstrate lowest price sensitivity due to ventilator-integrated ecosystem requirements, while homecare channel distributors in India and Southeast Asia prioritize disposable sensor economics over capital equipment specifications.
Supply Chain Analysis
Regional distribution centers in Osaka-Kobe, Shanghai, and Singapore orchestrate hub-and-spoke patterns for finished device delivery across Asia-Pacific healthcare networks. Manufacturing concentration in Japan, China, and South Korea draws from specialty chemical feedstocks for medical-grade polymers and solid-state sensor components. Single-source vulnerability concentrates in Northeast Asian silicone suppliers serving nasal interface production. Distribution runs through hospital procurement consortiums in Japan, telemedicine platform aggregators in Australia, and PLI scheme beneficiaries in Maharashtra for domestic Indian market fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific respiratory monitoring market reads as a late-cycle quality story justified by hospital procurement consolidation around integrated platform contracts with multi-year service agreements rather than standalone device purchases.
For Market Incumbents: Anticipate margin compression from optical flow sensing displacement of mechanical pneumotachographs in portable spirometers by accelerating software differentiation investments in AI-enabled diagnostic platforms. Defend installed base positions through HL7 FHIR interoperability certification for Japan's fragmented hospital network infrastructure, while deepening backward integration into medical-grade silicone compounding to offset specialty chemical supplier concentration. For New Entrants and Emerging Players: India's CDSCO streamlined registration pathways open a window for wireless-enabled portable monitor market entry targeting homecare channel expansion. White-space concentrates in Australian telemedicine reimbursement expansion for remote patient monitoring programs and South Korean national telemedicine platform integration for wearable respiratory monitors. Pursue disposable sensor economics partnerships with regional homecare providers rather than capital equipment sales cycles. For Investors and Strategic Acquirers: Roll-up economics work for algorithm-driven diagnostic platform developers because hospital procurement committee consolidation favors ventilator-integrated ecosystem suppliers over point-solution specialists. Long-term viability hinges on software-as-medical-device regulatory navigation capabilities across PMDA, NMPA, and TGA jurisdictions. Watch NMPA cybersecurity review protocol expansion to additional device categories as inflection indicator for compliance cost restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Software-as-Medical-Device Certification Investment | PMDA evidentiary compliance enables AI-enabled feature launches in Japan's university hospital networks. |
| Hospital System Partnership | Multi-year platform service agreements with Tokyo university hospitals consolidate vendor relationships against point-solution competitors. |
| Reimbursement Strategy | Australian telemedicine reimbursement expansion unlocks subscription revenue models for patient compliance data monetization. |
| Geographic Manufacturing Footprint | Maharashtra PLI scheme absorption localizes production capacity for India's accelerating homecare channel demand. |
| Software Companion Development | Edge computing integration with solid-state power systems creates continuous ambulatory monitoring applications. |
Study Parameters
Bottom-up hospital and homecare procurement modeling reconciled against top-down medical device manufacturing capacity tracking forms the analytical core of this study. Primary interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and telemedicine platform operators combined with secondary validation from PMDA submission databases, NMPA approval registries, CDSCO device registration records, and hospital procurement contract repositories. Triangulation across these sources ensures segment-level volume estimates align with supplier-reported production figures.
Input-output matrices map sensor component supply through finished device assembly to end-user channel absorption across the projection horizon. Segmentation dimensions modeled include product type, technology tier, end-user category, and application area, with geographic regulatory cluster as the industry-specific overlay. CAGRs derive from installed base replacement cycles, reimbursement pathway expansion timelines, and patient population growth trajectories. Forecast inputs incorporate battery efficiency convergence curves for portable device adoption and cybersecurity review protocol processing durations for cloud-connected platform approvals.
Revisions become necessary when NMPA cybersecurity review scope expansion, PMDA software-as-medical-device evidentiary requirement changes, or PLI scheme beneficiary capacity absorption rates materially diverge from modeled assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Wireless Fetal Monitoring Systems Market
Patient Monitoring
United Kingdom Remote Patient Monitoring Market
Patient Monitoring
Central Patient Monitoring System Market
Patient Monitoring
Heart Failure Monitoring Systems Market
Patient Monitoring
Portable Multi-Parameter Monitors Market
Patient Monitoring
Middle East and Africa Cardiac Monitoring Market
Patient Monitoring
Critical Care Patient Monitoring Products Market
Patient Monitoring
Middle East and Africa Remote Patient Monitoring Market
Patient Monitoring
Respiration Monitor Belt Market
Patient Monitoring
Middle-East and Africa Hemodynamic Monitoring Market
Patient Monitoring
Europe Wireless Healthcare Market
Patient Monitoring
Patient Monitoring Pods Market
Patient Monitoring
Europe Cardiac Holter Monitor Market
Patient Monitoring
Fetal Heart Rate Monitoring Devices Market
Patient Monitoring
RFID Blood Monitoring System Market
Patient Monitoring
Global Intrapartum Monitoring Devices Market