
 Dehydration Monitoring Systems Market | 2026-2036
Dehydration Monitoring Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Dehydration Monitoring Systems Market Analysis
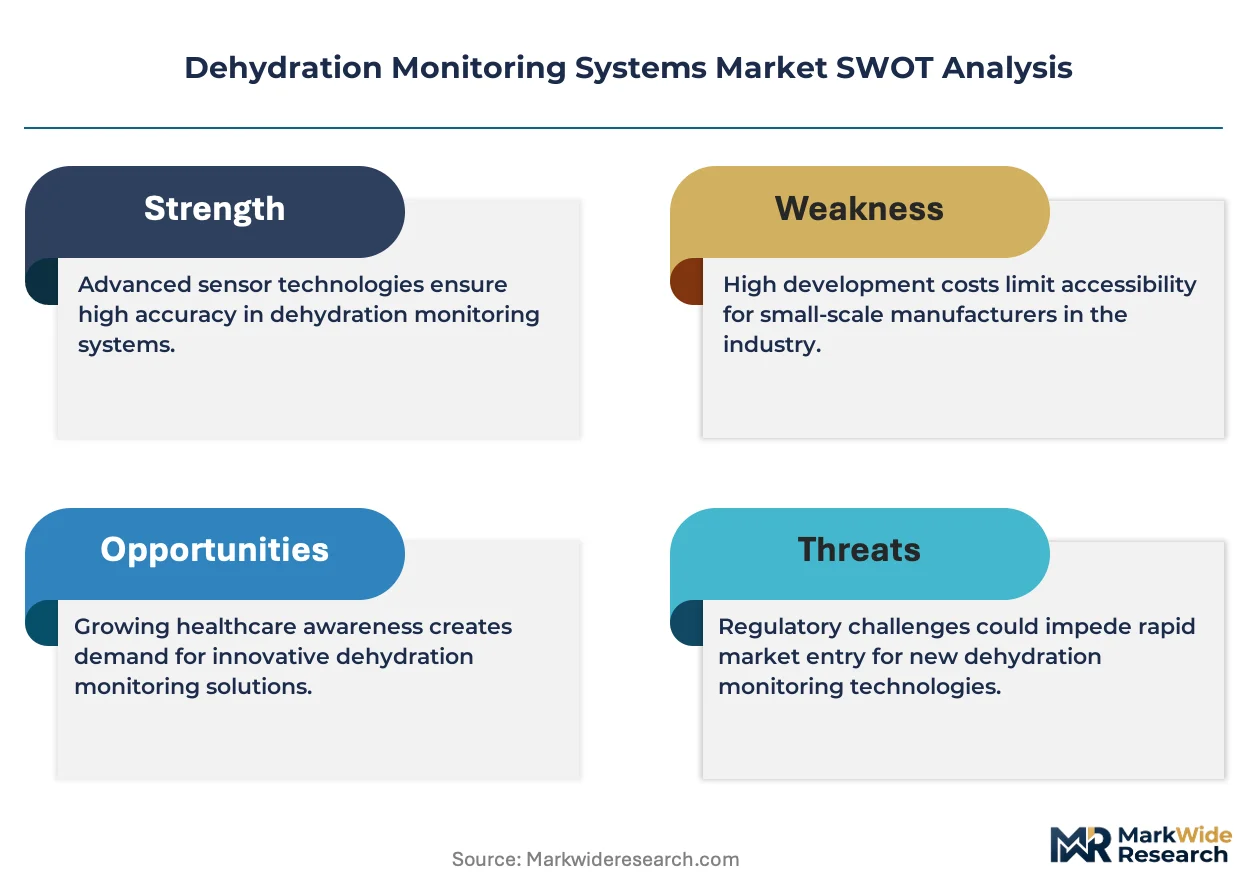
A shortage of biomedical engineers trained in fluid-electrolyte sensor calibration is unwinding production timelines for several manufacturers. Abbott Laboratories leverages its diagnostics heritage to anchor hospital-grade hydration monitoring portfolios. Epicore Biosystems specializes in sweat-analyzing wearable patches that dominate elite athletic applications. Masimo Corporation extends its pulse-oximetry expertise into continuous hydration status tracking for perioperative settings.
Dehydration monitoring systems encompass wearable, implantable, and point-of-care devices that measure biomarkers such as skin conductance, sweat sodium concentration, and bioimpedance to assess real-time hydration status. These systems typically operate within ±2% accuracy for extracellular fluid estimates and transmit data via Bluetooth Low Energy or proprietary radio protocols to clinical dashboards or consumer smartphones. Wearable Devices and Sensors command the largest installed base, though Remote Monitoring Systems are capturing margin pools through recurring software subscriptions tied to elderly care and post-acute monitoring. Biometric Sensors lead technology adoption in clinical settings, while Data Analytics platforms are the fastest-expanding segment as health systems integrate hydration metrics into broader population health dashboards.
FDA 510(k) pathways and HIPAA data governance requirements shape product development cycles and cloud architecture decisions for US-market systems. The EU MDR and GDPR impose additional conformity and data-localization burdens on devices sold in European member states. Stakeholders must monitor evolving reimbursement codes for remote patient monitoring to determine whether hydration tracking earns standalone billing status or remains bundled within broader physiological monitoring tariffs.
Market Dynamics
The dehydration monitoring systems market is experiencing a fundamental restructuring as FDA 510(k) clearance timelines compress and non-invasive biometric technologies mature simultaneously, creating a supply-constrained environment where qualified engineering talent determines production velocity.
Growth Catalysts
- Remote Patient Monitoring Reimbursement:CMS billing codes for continuous physiological tracking are expanding coverage eligibility for hydration status monitoring in post-acute care settings.
- Sweat Biomarker Analytics:Advances in microfluidic patch technology enable real-time electrolyte profiling without blood draws, accelerating adoption across NCAA athletic programs.
- Military Operational Readiness Mandates:The US Department of Defense is integrating wearable hydration sensors into standard-issue gear for deployed personnel in arid climate zones.
Market Restraints
- Silicon Photonics Supply Bottlenecks:Specialized optical components for non-invasive glucose and hydration sensing face 18-month lead times from foundries concentrated in Taiwan.
- EU MDR Conformity Costs:Clinical evidence requirements for Class IIa biometric devices under the 2017/745 regulation add €400,000-€800,000 per product variant for European market entry.
- Skin-Adhesive Biocompatibility Limitations:Extended-wear patches exceeding 72 hours trigger dermatological adverse events in 12-15% of users, constraining chronic disease management applications.
Strategic Opportunities
- India Preventive Health Infrastructure:The Ayushman Bharat digital health mission creates procurement channels for low-cost hydration monitoring in rural primary health centers.
- Perioperative Fluid Management:Integration of bioimpedance spectroscopy into anesthesia workstations addresses unmet needs in enhanced recovery after surgery protocols.
- AI-Augmented Hydration Prediction:Machine learning models combining biometric inputs with environmental data are enabling anticipatory hydration alerts before symptomatic dehydration occurs.
Industry Challenges
- Fluid-Electrolyte Sensor Calibration Expertise:Manufacturers report 8-14 month recruitment cycles for biomedical engineers with combined electrochemistry and physiological modeling competencies.
- HIPAA-Compliant Cloud Architecture:Real-time data transmission from wearable devices to clinical dashboards requires specialized security engineering that extends development timelines by 4-6 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dehydration Monitoring Systems Market |
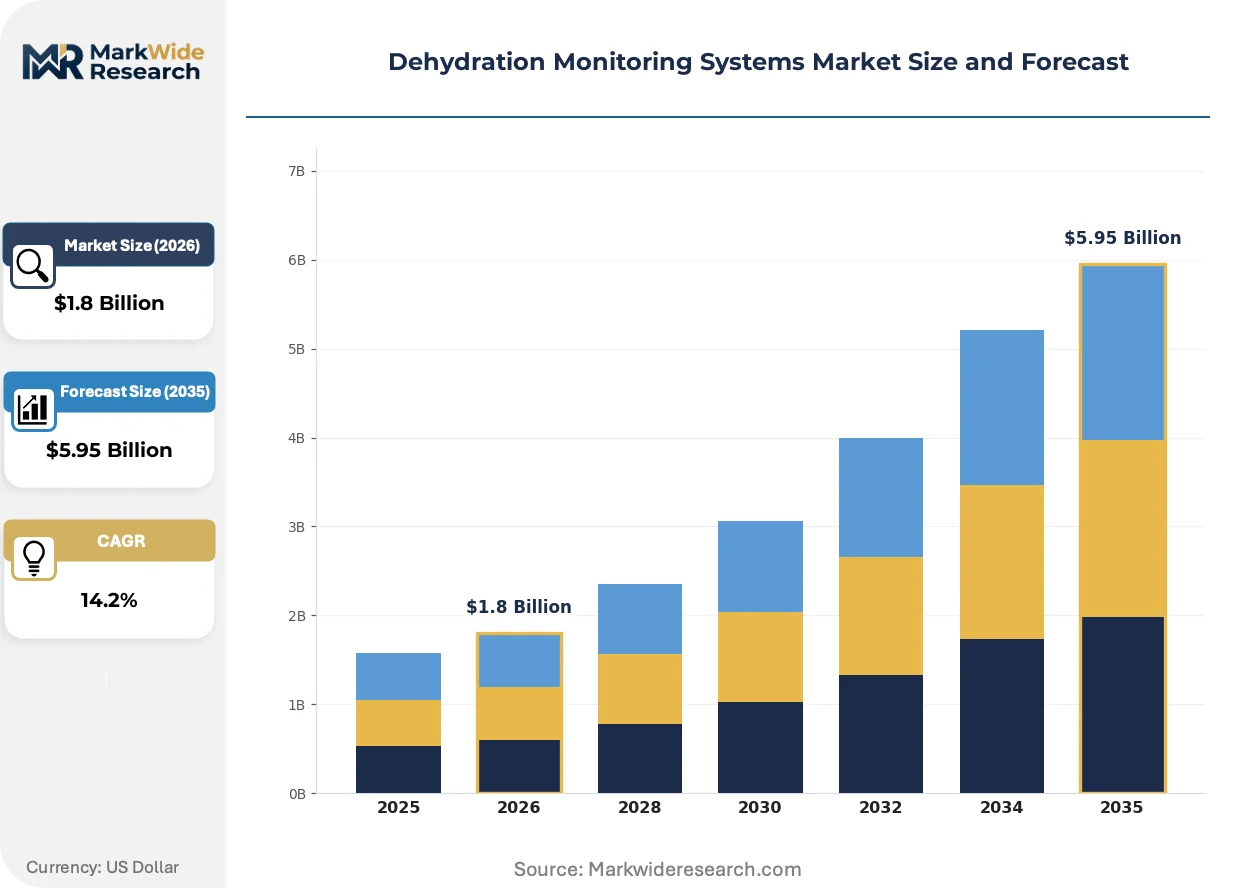
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Smartphone Applications, Remote Monitoring Systems, Sensors End User: Athletes, Elderly Care, Hospitals, Home Care Technology: IoT, Wireless Communication, Biometric Sensors, Data Analytics Application: Fitness Tracking, Health Monitoring, Clinical Trials, Wellness Programs |
| Companies Covered | BSX Technologies, Abbott Laboratories, Kenzen Inc., Baxter International, Omron Healthcare, Epicore Biosystems, Masimo Corporation, Hexoskin, Nix Biosensors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dehydration Monitoring Systems Market Emerging Trajectories
Convergence of miniaturized biosensors with edge computing architectures is fundamentally altering how hydration data is captured, processed, and acted upon across clinical and consumer contexts.
Bioimpedance spectroscopy is displacing traditional skin conductance methods as the dominant hydration assessment modality in hospital settings. Perioperative care teams at Veterans Health Administration facilities are deploying continuous monitoring systems that track extracellular fluid shifts with ±2% accuracy. This technology is displacing intermittent manual assessments and enabling automated fluid resuscitation protocols that reduce nursing documentation burden.
FDA breakthrough device designation pathways for non-invasive diagnostic technologies are accelerating commercialization timelines for hydration monitoring startups. The agency's 2023 guidance on clinical decision support software has clarified regulatory boundaries for AI-enhanced hydration alerts. Wearable patch manufacturers are responding by restructuring quality management systems to align with 21 CFR Part 820 requirements before pre-submission meetings.
NCAA athletic departments are consolidating vendor relationships around integrated performance platforms rather than standalone hydration sensors. Procurement committees now require API compatibility with existing athlete management systems from Catapult or WHOOP as a mandatory evaluation criterion. This specification-driven selection process is most pronounced among Power Five conference programs with annual sports science budgets exceeding $2 million.
Dehydration Monitoring Systems Market Segmentation
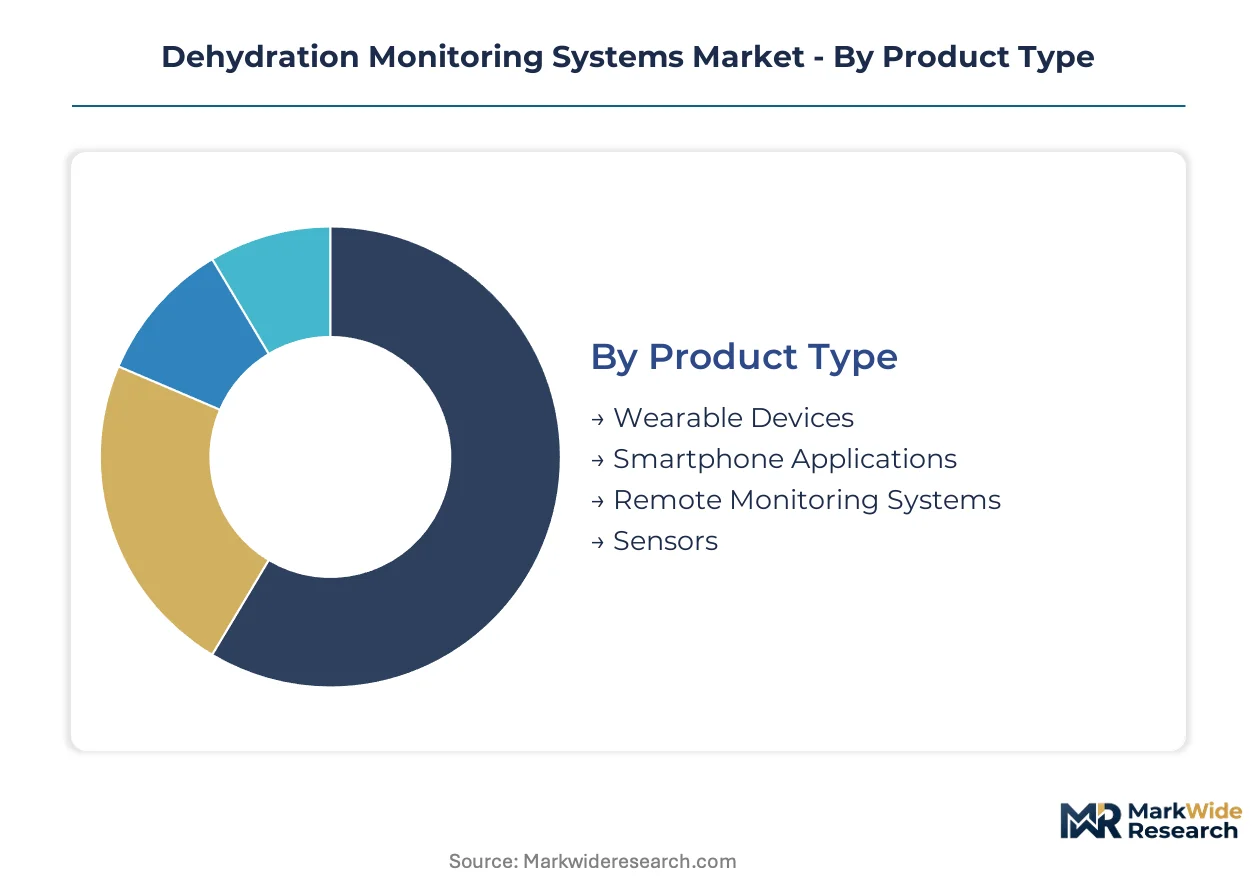
Dehydration monitoring systems fragment across four critical dimensions where regulatory pathways, reimbursement eligibility, and end-user workflows diverge sharply. Product architecture choices determine whether manufacturers pursue FDA 510(k) clearance or direct-to-consumer positioning, while technology selection shapes cloud infrastructure requirements under HIPAA and GDPR.
Product Type:
FDA clearance pathways differentiate wearable devices from point-of-care systems, with Class II medical device designation requiring clinical validation studies that add 12-18 months to commercialization timelines.
- Wearable Devices:Skin-adhesive patches and wrist-worn sensors integrate microfluidic sweat analysis with Bluetooth Low Energy transmission. NCAA athletic programs and Veterans Health Administration facilities concentrate procurement here, driven by continuous monitoring mandates in post-acute rehabilitation protocols.
- Remote Monitoring Systems:Cloud-connected platforms aggregate hydration data across patient populations for clinical dashboard visualization. Elderly care providers and home health agencies drive demand through CMS reimbursement codes for remote physiological tracking.
- Smartphone Applications:Camera-based hydration assessment tools bypass hardware costs but face accuracy limitations. Consumer fitness segments tolerate ±5% variance for convenience.
- Sensors:Disposable bioimpedance electrodes and sweat sodium probes supply OEM integration into multi-parameter monitors. Perioperative anesthesia workstation manufacturers anchor volume.
Wearable Devices handles the majority of throughput; Remote Monitoring Systems is the fastest mover on share.
End User:
Customer procurement authority ranges from individual consumers to institutional committees with $2 million-plus annual sports science budgets.
- Hospitals:Perioperative fluid management and ICU electrolyte balance monitoring command premium pricing. Bioimpedance spectroscopy integration into anesthesia workstations addresses enhanced recovery after surgery protocols at Veterans Health Administration facilities.
- Athletes:Elite sports programs require API compatibility with athlete management systems. Power Five conference universities consolidate vendor relationships around integrated performance platforms rather than standalone sensors.
- Elderly Care:Skilled nursing facilities deploy hydration monitoring to reduce hospital readmission penalties. Reimbursement bundling within remote patient monitoring tariffs constrains standalone pricing power.
- Home Care:Post-acute patients manage chronic kidney disease and heart failure through connected devices. Caregiver notification features determine adoption velocity.
Hospitals capture the highest revenue per installation; Athletes is expanding most quickly as procurement standardizes.
Technology:
Architecture decisions determine whether systems process data at the edge or transmit raw signals to HIPAA-compliant cloud infrastructure.
- Biometric Sensors:Electrochemical sweat analysis and skin conductance measurement provide real-time hydration biomarkers. FDA breakthrough device designation pathways accelerate commercialization for non-invasive diagnostic startups.
- Data Analytics:Machine learning models combine biometric inputs with environmental temperature and humidity data. Anticipatory hydration alerts before symptomatic dehydration occurs differentiate premium platforms.
- IoT:Mesh network protocols enable device-to-device communication in military field deployments. Department of Defense operational readiness mandates standardize procurement specifications.
- Wireless Communication:Proprietary radio protocols and Bluetooth Low Energy transmission architectures determine battery life and data security profiles. Cloud architecture decisions extend development timelines by 4-6 months.
Biometric Sensors dominates installed base; Data Analytics shows the steepest expansion trajectory as health systems integrate hydration metrics into population health dashboards.
Application:
Use case specificity determines whether manufacturers pursue clinical validation studies or consumer marketing channels.
- Health Monitoring:Chronic disease management for diabetes and renal dysfunction requires continuous fluid status tracking. Dermatological adverse events in 12-15% of extended-wear users constrain adoption beyond 72-hour protocols.
- Fitness Tracking:Recreational athletes and military personnel in arid climate zones prioritize real-time electrolyte feedback. Sweat biomarker analytics without blood draws accelerates adoption across deployed units.
- Clinical Trials:Pharmaceutical sponsors deploy hydration monitoring as a safety endpoint in nephrology and cardiology studies. Regulatory-grade data integrity requirements drive sensor calibration standards.
- Wellness Programs:Corporate and insurance-sponsored preventive health initiatives tolerate lower accuracy for cost efficiency. Hydration coaching algorithms differentiate subscription offerings.
Health Monitoring commands the largest addressable population; Fitness Tracking is gaining share fastest through military and athletic procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where NCAA athletic programs and Veterans Health Administration facilities pay premium rates for FDA-cleared devices, while Indian primary health centers under Ayushman Bharat procurement channels compress margins through volume-based tenders.
United States
NCAA Power Five conference athletic departments and Veterans Health Administration rehabilitation centers anchor institutional procurement. FDA 510(k) clearance pathways and HIPAA data governance requirements shape product development cycles for domestic manufacturers. Boston and San Diego clusters host sweat-analyzing wearable patch developers serving elite sports programs.
Germany
Perioperative fluid management adoption in university hospitals drives bioimpedance spectroscopy integration into anesthesia workstations. EU MDR 2017/745 conformity assessments add substantial clinical evidence costs for Class IIa biometric devices. The Munich-Stuttgart corridor concentrates medical technology engineering talent for sensor calibration.
India
Ayushman Bharat digital health mission creates procurement channels for low-cost hydration monitoring in rural primary health centers. CDSCO medical device rules govern import licensing and local manufacturing requirements for wearable sensors. Karnataka's Bengaluru electronics cluster supports OEM component sourcing for disposable electrode manufacturers.
China
Military operational readiness mandates for deployed personnel in arid western provinces accelerate wearable sensor adoption. NMPA Class II medical device registration and GB standards compliance determine market access timelines for domestic and foreign manufacturers. The Yangtze River Delta manufacturing belt supplies microfluidic components for sweat-analyzing patches.
Japan
Elderly care facilities deploy remote monitoring systems to reduce hospital readmission penalties under revised long-term care insurance. PMDA consultation pathways and JIS standards for home-use medical devices shape product localization requirements. The Kansai region's Osaka-Kobe medical device cluster hosts bioimpedance electrode manufacturers.
Dehydration Monitoring Systems Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with diagnostic heritage conglomerates commanding premium pricing through FDA-cleared hospital portfolios while specialized wearable patch developers capture athletic segments through microfluidic innovation. The vendor base organizes around three strategic archetypes: diversified diagnostics majors leveraging existing regulatory infrastructure, venture-backed sensor specialists pursuing breakthrough device designations, and contract manufacturers supplying disposable electrodes to OEM integrators. M&A activity concentrates on tuck-in acquisitions of sweat-biomarker analytics capabilities, while strategic partnerships with athlete management platform vendors determine NCAA procurement outcomes.
Within the diagnostics-major tier, Abbott Laboratories and Baxter International exemplify players leveraging existing hospital supply relationships and regulatory affairs infrastructure to anchor perioperative and ICU applications. Masimo Corporation occupies a position bridging pulse-oximetry heritage with continuous hydration status tracking for surgical settings. Among specialized wearable developers, Epicore Biosystems and Kenzen Inc. represent the venture-backed archetype pursuing elite athletic and military procurement channels through non-invasive sweat analysis platforms.
| Leading Market Players |
|---|
| BSX Technologies |
| Abbott Laboratories |
| Kenzen Inc. |
| Baxter International |
| Omron Healthcare |
| Epicore Biosystems |
| Masimo Corporation |
| Hexoskin |
| Nix Biosensors |
| Others |
Supply Flow & Price Mechanics
FDA 510(k) clearance pathways gate both supplier qualification and price differentiation simultaneously, as manufacturers without Class II medical device designation face exclusion from Veterans Health Administration procurement channels while cleared systems command premium positioning in NCAA athletic programs.
Pricing Analysis
Configured-to-order pricing for hospital-grade bioimpedance systems spreads 40-60% above standard wearable patch SKUs. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with FDA-cleared perioperative monitors anchoring the top tier. Cost compression in the consumer fitness segment intensifies because smartphone-based hydration apps eliminate hardware entirely. Elderly care providers exhibit highest price sensitivity due to reimbursement bundling within remote patient monitoring tariffs.
Supply Chain Analysis
Taiwanese foundry concentration for silicon photonics components creates a chokepoint that extends lead times for optical hydration sensors. Manufacturing draws from China for microfluidic patch substrates, the United States for bioimpedance electrode assemblies, and Germany for precision electrochemical sensors. Single-source vulnerability in specialty optical components exposes producers to geopolitical disruption. Distribution runs through hospital GPO contracts, direct athletic program sales, and military procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dehydration monitoring systems sit in early-cycle expansion as FDA breakthrough device designations compress commercialization timelines and expand addressable clinical populations.
For Market Incumbents: Consolidate around sweat-biomarker analytics capabilities through tuck-in acquisitions before venture-backed specialists capture NCAA procurement consolidation. Anchor hospital supply relationships against emerging pulse-oximetry entrants extending into hydration tracking. Vertical integration into disposable electrode manufacturing defends margin position against contract manufacturer pricing pressure. For New Entrants and Emerging Players: Differentiate on AI-augmented hydration prediction combining biometric inputs with environmental data. Target India's Ayushman Bharat rural primary health centers as the most penetrable geography given low incumbent presence. Pursue CDSCO medical device registration partnerships with local electronics clusters in Karnataka. For Investors and Strategic Acquirers: FDA breakthrough device designation reshapes the acquisition landscape by derisking regulatory timelines for venture-backed sensor specialists. Five-to-ten year viability favors platforms with API compatibility into existing athlete management systems. Watch CMS reimbursement code expansion for standalone hydration monitoring as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerates commercialization timelines for non-invasive diagnostic startups pursuing 510(k) pathways. |
| API Integration Partnership | Catapult and WHOOP compatibility determines NCAA Power Five conference procurement outcomes. |
| Sweat-Biomarker Acquisition | Microfluidic patch capabilities consolidate vendor relationships in elite athletic segments. |
| Reimbursement Strategy Development | Standalone billing codes for hydration tracking unlock elderly care and home health revenue pools. |
| Perioperative Fluid Management Integration | Anesthesia workstation partnerships address enhanced recovery protocols at Veterans Health Administration facilities. |
Methodological Framework
Operator-level perspectives from biomedical engineers, hospital purchasing committee members, NCAA sports science directors, and military procurement officers anchored the qualitative base. Primary interviews combined with secondary validation from FDA 510(k) filings, CMS reimbursement code databases, hospital GPO contract repositories, and athletic program budget disclosures. Bottom-up and top-down triangulation cross-checked sensor shipment volumes against institutional procurement records.
Sensitivity analysis tested forecast outputs against regulatory timeline compression, reimbursement code expansion scenarios, and foundry capacity constraints across the projection horizon. Segmentation dimensions modeled include product architecture, end-user procurement authority, technology modality, and application specificity. CAGRs derived from installed base growth trajectories and replacement cycle analysis, with inputs from fluid-electrolyte sensor calibration expertise scarcity and cloud infrastructure development timelines.
The analysis sits within stated boundaries; outcomes outside FDA clearance pathway acceleration or CMS reimbursement expansion would require recalibration. Forecasts reflect assumptions about silicon photonics supply normalization and dermatological adverse event mitigation in extended-wear protocols. Practitioners should keep alternative scenarios live as EU MDR conformity costs and HIPAA-compliant cloud architecture requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
China ICU Patient Monitor Market
Patient Monitoring
RFID Blood Monitoring System Market
Patient Monitoring
North America Respiratory Monitoring Market
Patient Monitoring
Europe Fetal and Neonatal Monitoring Market
Patient Monitoring
Global Anaesthesia Monitoring Devices Market
Patient Monitoring
Wearable Cardiac Monitors Market
Patient Monitoring
Holter Monitor Market
Patient Monitoring
Transcutaneous Monitors Market
Patient Monitoring
Respiratory Monitoring Market
Patient Monitoring
Patient Monitoring and Ultrasound Devices Display Market
Patient Monitoring
Fetal Heart Rate Monitoring Devices Market
Patient Monitoring
Germany Blood Glucose Monitoring Market
Patient Monitoring
Australia Patient Monitoring Market
Patient Monitoring
IoT in Healthcare Market
Patient Monitoring
Global Blood Pressure Monitoring Devices Market
Patient Monitoring
Wireless Healthcare Market