
 India Patient Monitoring Market | 2026-2036
India Patient Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
India Patient Monitoring Market Foresight
The Medical Device Rules, 2017 is consolidating the cost-of-entry calculus for foreign and domestic manufacturers seeking CDSCO licensing in India. GE Healthcare leverages its installed base of multiparameter systems across government hospital chains to sustain replacement cycle revenues. Medtronic anchors its competitive position through specialized cardiac monitoring portfolios tailored to Indian cath lab expansion. Philips competes on wireless monitoring integration with existing hospital IT infrastructure in tier-1 cities.
Patient monitoring encompasses integrated hardware-software systems that acquire, process, display, and transmit physiological parameters including ECG, SpO2, blood pressure, and respiratory rate with sampling frequencies typically ranging from 125 Hz to 1000 Hz for diagnostic-grade devices. These systems serve the primary commercial purpose of enabling continuous clinical surveillance across acute care, sub-acute transition, and ambulatory settings to detect deterioration before critical events. Multiparameter monitors dominate installed value in tertiary hospitals where centralized nursing station integration drives purchasing decisions. Wearable devices represent the fastest-expanding technology segment as homecare providers and insurance-backed chronic disease programs seek continuous data streams outside facility walls. Software solutions increasingly capture margin pools through subscription analytics and cloud-based alarm management.
BIS certification requirements under the Compulsory Registration Scheme and CDSCO's risk-based device classification framework shape product standards, testing timelines, and import documentation burdens for all market participants. The Ayushman Bharat Digital Mission and NDHM interoperability standards are creating regulated data exchange protocols that determine which monitoring platforms qualify for reimbursement-linked deployments. Stakeholders must track how state-level public procurement tenders incorporate Make in India domestic content thresholds alongside technical specifications.
Market Dynamics
Ayushman Bharat Digital Mission interoperability mandates are forcing hospital IT departments to replace standalone monitoring devices with integrated platforms that feed directly into national health data exchanges.
Growth Catalysts
- Remote Patient Monitoring Infrastructure:Tertiary care networks in Maharashtra and Karnataka are deploying continuous glucose monitoring and cardiac telemetry systems under ABPM-JAY reimbursement protocols. Homecare providers now qualify for insurance-linked device procurement.
- CDSCO Risk-Based Reclassification:The Medical Device Rules, 2017 amendment pathway is accelerating registration timelines for Class A and B patient monitors, reducing market entry delays for domestic manufacturers seeking ISO 13485 alignment.
- Cath Lab Expansion:Interventional cardiology suites across South Indian metropolitan hospital chains are driving replacement demand for hemodynamic monitoring systems with invasive pressure measurement capabilities.
Market Restraints
- Semiconductor Import Dependency:Analog front-end ICs and MEMS sensors for SpO2 and ECG modules concentrate in Taiwanese and South Korean fabs, exposing domestic assemblers to input cost volatility and forex risk.
- BIS Testing Bottlenecks:Compulsory Registration Scheme laboratory capacity constraints in Mumbai and Chennai extend pre-market certification timelines by four to six months for wearable monitoring devices.
- Smartphone-App Substitution:Consumer-grade pulse oximetry and heart rate variability applications on iOS and Android platforms are capturing price-sensitive preventive health segments outside clinical oversight.
Strategic Opportunities
- Tier-2 and Tier-3 Hospital Penetration:District hospitals in Uttar Pradesh and Bihar remain undersupplied with multiparameter monitors, creating whitespace for rental and equipment-leasing models tied to PLI scheme domestic production incentives.
- AI-Enabled Predictive Alarm Systems:Machine learning integration with cloud-based central monitoring stations is enabling false alarm reduction algorithms that differentiate premium software subscriptions from hardware-only vendors.
- Make in India Procurement Mandates:State-level public health tenders under the Ayushman Bharat program are incorporating domestic content thresholds that favor local assembly of patient monitoring accessories and disposables.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Clinical engineering departments at AIIMS and JIPMER report acute shortages of technicians trained in wireless protocol troubleshooting and cybersecurity patching for connected monitoring devices.
- Legacy System Integration Complexity:Government hospital chains with 1990s-era central nursing station architectures face prohibitive retrofit costs to achieve NDHM-compliant data interoperability with modern HL7 FHIR standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Patient Monitoring Market |
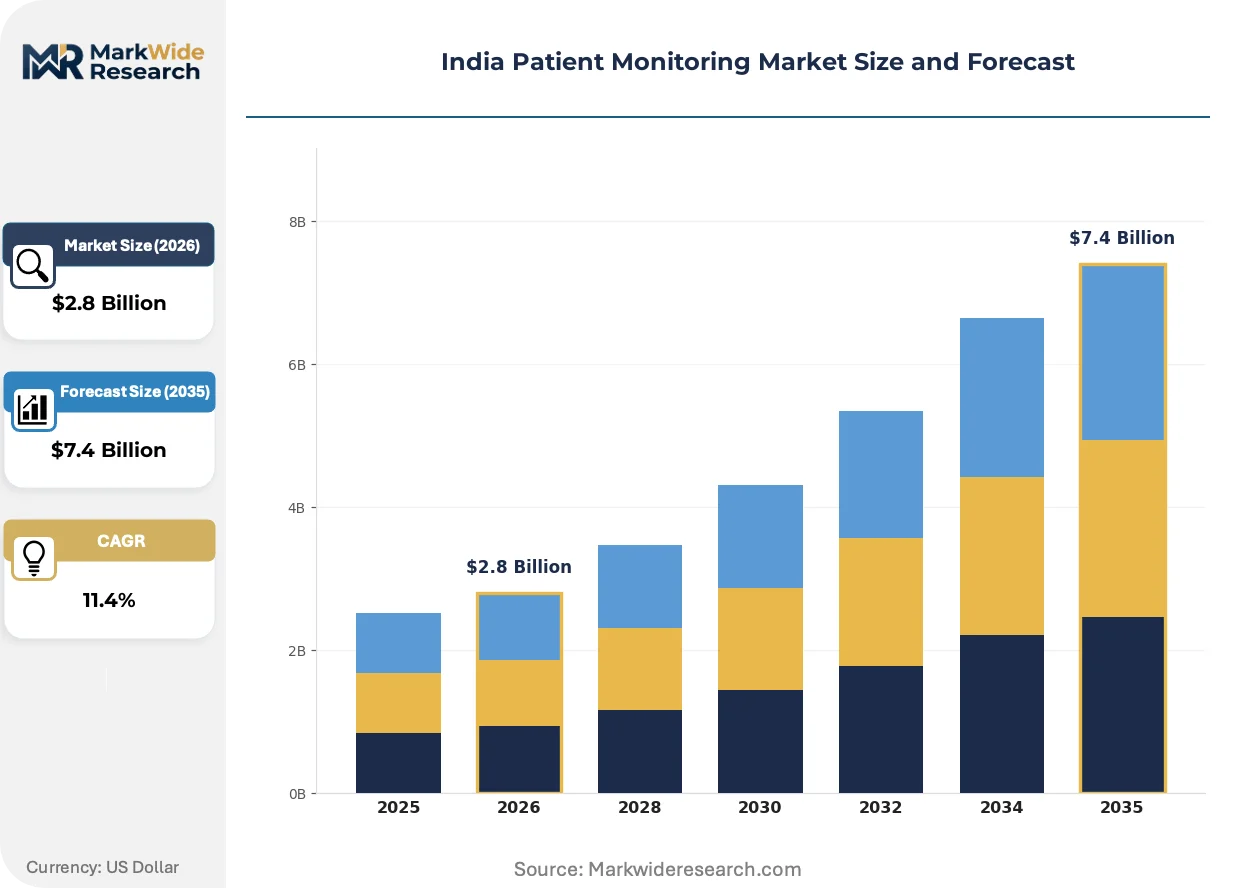
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vital Signs Monitors, Cardiac Monitors, Multiparameter Monitors, Fetal Monitors End User: Hospitals, Homecare, Clinics, Ambulatory Surgery Centers Technology: Wireless Monitoring, Portable Monitoring, Wearable Devices, Software Solutions Application: Chronic Disease Management, Postoperative Care, Emergency Care, Neonatal Care |
| Companies Covered | Mindray Medical International Limited, Drägerwerk AG & Co. KGaA, Koninklijke Philips N.V., OMRON Healthcare, BPL Group, GE Healthcare, Medtronic, ResMed Inc., Nihon Kohden Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Patient Monitoring Market Shifts & Advancements
Wireless connectivity standards and edge computing architectures are compressing the traditional separation between bedside monitors and cloud analytics platforms, enabling real-time clinical decision support outside intensive care settings.
Edge AI inference chips from Qualcomm and MediaTek are modularizing patient monitoring hardware by embedding arrhythmia detection and respiratory pattern analysis directly into wearable patches and portable monitors. District hospitals in Kerala and Tamil Nadu are piloting these systems to reduce dependency on centralized server infrastructure. The technology is modularizing vendor business models from capital equipment sales toward per-patient-per-day analytics subscriptions.
CDSCO's 2023 guidance on software as a medical device is requiring algorithm-based monitoring systems to undergo clinical validation trials at Indian Council of Medical Research-accredited sites before market authorization. Cardiac monitoring AI platforms face the steepest compliance burden, with validation datasets requiring representation from South Asian demographic cohorts. Domestic developers in Bengaluru and Hyderabad are establishing captive clinical trial partnerships with multi-specialty hospital chains to accelerate regulatory clearance.
Hospital procurement committees are unbundling after-sales service contracts from device purchase agreements, creating standalone annual maintenance contract markets for third-party biomedical engineering firms. Corporate hospital chains in Mumbai and Delhi are consolidating vendor panels to three preferred monitoring suppliers with mandatory seven-year spare parts availability clauses. The shift is most pronounced in cardiac catheterization labs where downtime costs exceed equipment replacement value within eighteen months.
India Patient Monitoring Market Segmentation
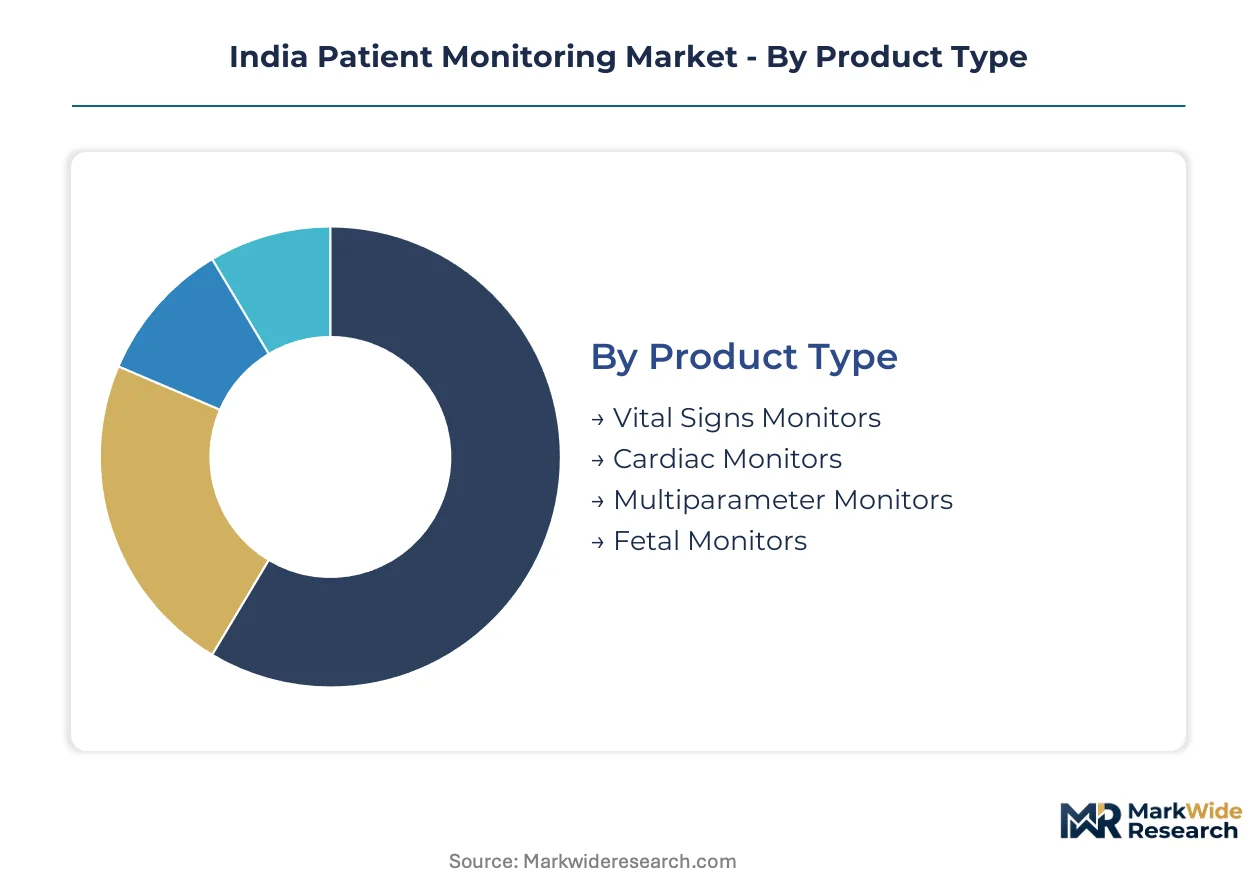
Patient monitoring systems fragment across hardware configurations, care settings, connectivity architectures, and clinical use cases. Each dimension carries distinct procurement criteria, regulatory pathways, and margin structures that determine vendor positioning within India's hospital and homecare channels.
Product Type:
Replacement cycles for legacy bedside units are accelerating as tertiary hospitals pursue NDHM-compliant data integration and wireless telemetry capabilities.
- Multiparameter Monitors:Integrated systems acquire ECG, SpO2, NIBP, and respiratory rate through modular parameter boards with 125-1000 Hz sampling frequencies. Central nursing stations at AIIMS Delhi and CMC Vellore drive procurement of networked platforms with HL7 FHIR output.
- Cardiac Monitors:Arrhythmia detection systems with 12-lead ECG acquisition and ST-segment analysis capability anchor cath lab installations. South Indian metropolitan hospital chains prioritize hemodynamic monitoring with invasive pressure measurement for interventional cardiology suites.
- Vital Signs Monitors:Compact NIBP-SpO2-temperature units serve ward-level spot-checking at district hospitals in Uttar Pradesh and Bihar.
- Fetal Monitors:Ultrasound Doppler and tocodynamometer systems track fetal heart rate and uterine contractions during labor and delivery.
Multiparameter monitors sit at the top of the volume ranking, with cardiac monitors climbing the fastest.
End User:
Procurement authority concentrates in institutional purchasing committees with divergent technical specifications and reimbursement linkages.
- Hospitals:Tertiary care networks in Maharashtra and Karnataka deploy enterprise-scale monitoring platforms with centralized alarm management. CDSCO Class C device registration and BIS certification requirements filter vendor participation in government hospital tenders.
- Homecare:Insurance-linked device procurement under ABPM-JAY protocols is expanding continuous glucose monitoring and cardiac telemetry outside facility walls. Rental and leasing models are emerging for price-sensitive chronic disease management.
- Clinics:Primary care settings in tier-2 cities favor portable vital signs monitors with simplified user interfaces.
- Ambulatory Surgery Centers:Short-stay facilities require compact pre-operative and recovery monitoring with rapid deployment capabilities.
Hospitals command the dominant revenue share, though homecare is gaining share fastest as reimbursement protocols mature.
Technology:
Connectivity architectures determine data monetization potential and subscription revenue attach rates.
- Wireless Monitoring:Wi-Fi and proprietary RF protocols enable bedside-to-cloud transmission without tethered connections. Kerala and Tamil Nadu district hospitals pilot edge-computing variants to reduce server infrastructure dependency.
- Software Solutions:Cloud-based alarm management and predictive analytics platforms capture recurring subscription revenue from corporate hospital chains in Mumbai and Delhi.
- Wearable Devices:Patch-based ECG and continuous glucose monitors integrate with smartphone applications for ambulatory patient surveillance.
- Portable Monitoring:Battery-powered multiparameter units serve emergency transport and rural outreach programs.
Wireless monitoring leads installed value, while software solutions show the steepest expansion trajectory as hospitals unbundle service contracts.
Application:
Clinical use cases determine sensor configuration, alarm threshold protocols, and regulatory classification intensity.
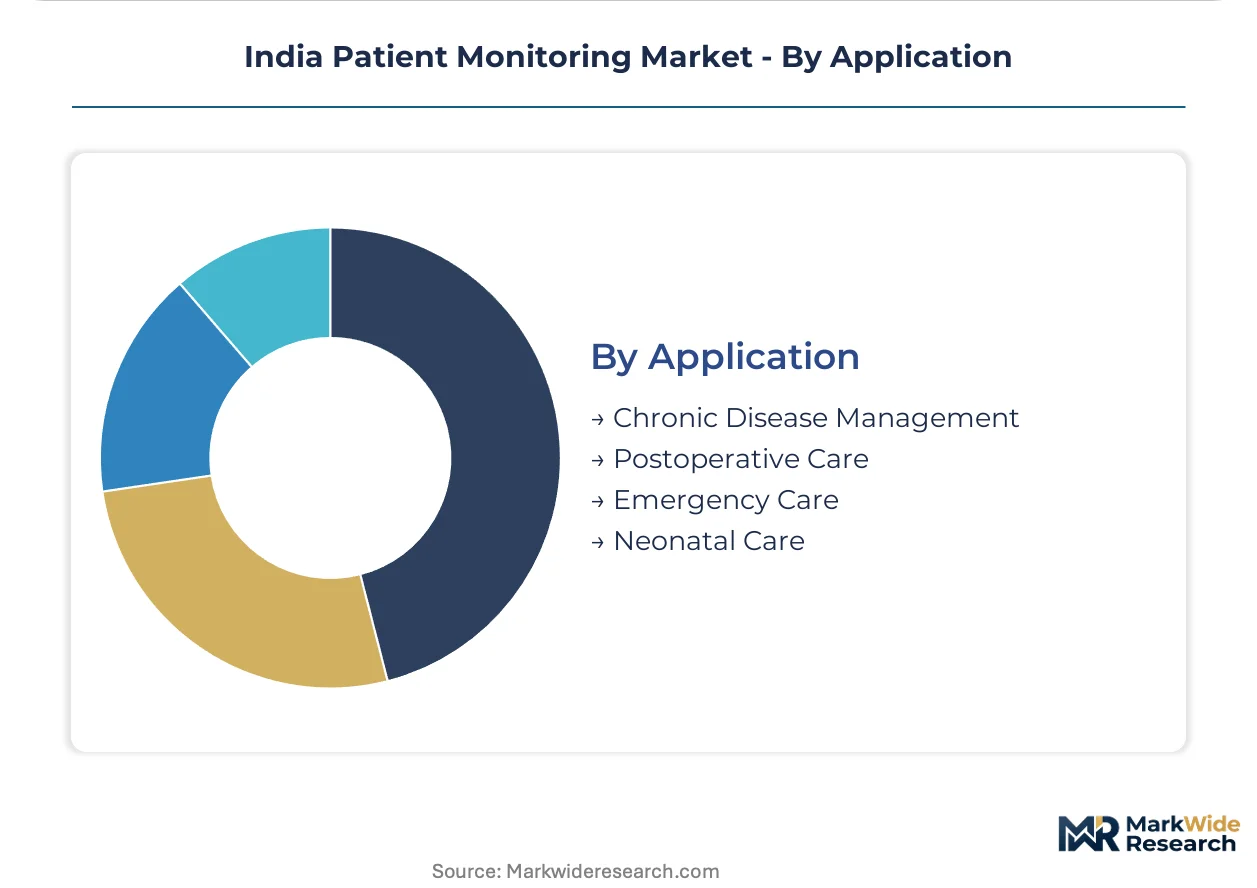
- Chronic Disease Management:Continuous glucose monitoring and ambulatory blood pressure systems support diabetes and hypertension protocols at scale. ABPM-JAY reimbursement eligibility is expanding addressable volume for home-based deployments.
- Postoperative Care:Step-down units require intermediate-acuity monitoring with automated early warning score integration.
- Emergency Care:Triage and resuscitation bays demand rapid-deployment vital signs acquisition with defibrillator synchronization.
- Neonatal Care:Incubator-integrated monitoring with specialized SpO2 and temperature probes serves NICU installations.
Chronic disease management dominates addressable patient volume, with postoperative care expanding most quickly as surgical capacity rises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biomedical engineering talent clusters in Maharashtra and Karnataka anchor India's patient monitoring manufacturing and deployment networks. CDSCO regulatory expertise concentrates in Mumbai and Bengaluru, creating compliance advisory ecosystems for domestic and foreign device manufacturers. State-level health procurement authorities in these hubs shape technical specifications that cascade to district hospital networks nationwide.
Maharashtra
Mumbai's tertiary care hospitals drive enterprise-scale multiparameter monitor procurement under ABPM-JAY reimbursement protocols. CDSCO headquarters proximity accelerates registration timelines for Class C cardiac monitoring devices seeking market authorization. Pune's medical device manufacturing corridor hosts domestic assemblers sourcing SpO2 and ECG modules for government hospital tenders.
Karnataka
Bengaluru's health technology ecosystem integrates wireless monitoring platforms with NDHM-compliant data exchange infrastructure. The state's biomedical engineering workforce supports cath lab expansion across South Indian metropolitan hospital chains. Mysuru and Hubli-Dharwad districts pilot edge-computing patient monitoring systems to reduce centralized server dependency.
Tamil Nadu
Chennai's corporate hospital chains unbundle after-sales service contracts from device purchase agreements, creating standalone maintenance markets. BIS testing laboratory capacity constraints extend pre-market certification timelines for wearable monitoring devices. Coimbatore's medical device component suppliers feed into multiparameter monitor assembly operations serving Kerala and Andhra Pradesh.
Telangana
Hyderabad's life sciences corridor attracts AI-enabled predictive alarm system developers seeking clinical validation partnerships. The state's district hospitals participate in ABPM-JAY remote patient monitoring pilots for chronic disease management. Medchal and Sangareddy industrial zones host domestic manufacturers targeting PLI scheme incentives for patient monitoring accessories.
Delhi-NCR
AIIMS Delhi anchors clinical validation requirements for CDSCO software-as-a-medical-device guidance on algorithm-based monitoring systems. The region's procurement committees set technical specifications that propagate through central government hospital chains. Noida and Gurugram host third-party biomedical engineering firms servicing unbundled annual maintenance contracts.
India Patient Monitoring Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across India's patient monitoring procurement channels. The market structures around three tiers: multinational healthcare technology conglomerates with installed base advantages, regional medical device specialists with cost-optimized portfolios, and emerging domestic assemblers leveraging PLI scheme production incentives. Two competitive moves dominate vendor positioning: integration with hospital IT infrastructure to meet NDHM interoperability mandates, and unbundling of software analytics subscriptions from hardware-only sales.
Among diversified healthcare technology conglomerates, Koninklijke Philips N.V. and GE Healthcare exemplify archetypes competing on wireless monitoring integration with existing hospital infrastructure. Medtronic occupies a position within the cardiac monitoring specialization tier, anchoring competitive positioning through hemodynamic system portfolios. These three companies represent distinct strategic postures: infrastructure integration, cardiac specialization, and enterprise-scale platform deployment.
| Leading Market Players |
|---|
| Mindray Medical International Limited |
| Drägerwerk AG & Co. KGaA |
| Koninklijke Philips N.V. |
| OMRON Healthcare |
| BPL Group |
| GE Healthcare |
| Medtronic |
| ResMed Inc. |
| Nihon Kohden Corporation |
| Others |
Supply & Pricing Matrix
Backward integration into analog front-end IC sourcing anchors both supply resilience and pricing power for domestic assemblers competing against multinational installed bases. CDSCO registration timelines and BIS certification requirements create tiered compliance costs that stratify vendor positioning across government and private hospital procurement channels.
Pricing Analysis
The bundled-versus-unbundled service split is compressing hardware margins while expanding recurring revenue pools. Corporate hospital chains in Mumbai and Delhi now separate device purchase agreements from seven-year annual maintenance contracts, forcing vendors to price hardware transparently and compete on software analytics subscriptions. Price differentiation stems from ISO 13485 certification tier and after-sales service bundling. Cost compression in economy-tier vital signs monitors is intensifying because smartphone-app substitutes capture price-sensitive preventive health segments. District hospitals in Uttar Pradesh and Bihar exhibit highest price sensitivity; tertiary cath labs in South Indian metropolitan chains show lowest.
Supply Chain Analysis
Analog front-end IC and MEMS sensor supply rests on Taiwanese and South Korean fab concentration, exposing domestic assemblers to input cost volatility and forex risk. SpO2 photodiodes, ECG electrodes, and lithium-polymer battery cells draw from Chinese and Japanese component suppliers. Single-source vulnerability concentrates in high-precision pressure transducers for hemodynamic monitoring systems. Distribution runs through medical device distributors serving state-level public health procurement authorities, with direct-to-hospital sales dominating corporate chain accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's patient monitoring market compounds steadily as ABPM-JAY reimbursement protocols expand addressable volume for remote patient monitoring outside facility walls.
For Market Incumbents: Deploy cloud-based alarm management subscriptions to capture recurring revenue as hardware margins compress. Consolidate vendor panels at corporate hospital chains through mandatory seven-year spare parts availability clauses. Counter smartphone-app substitution by integrating predictive analytics with existing hospital IT infrastructure under NDHM interoperability mandates. For New Entrants and Emerging Players: The premium-to-economy price-point gap in district hospital multiparameter monitors enables rental and equipment-leasing models tied to PLI scheme domestic production incentives. Target undersupplied tier-2 and tier-3 hospitals in Uttar Pradesh and Bihar with portable vital signs monitors featuring simplified user interfaces. Pursue GPO contracts managers at state-level public health procurement authorities as primary channel entry point. For Investors and Strategic Acquirers: Roll-up economics work for third-party biomedical engineering service firms because hospital procurement committees are unbundling after-sales contracts from device purchases. The five-to-ten-year viability window favors platforms with captive clinical validation partnerships at ICMR-accredited sites. Watch CDSCO software-as-a-medical-device enforcement intensity as inflection indicator for AI-enabled monitoring platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO Class C Registration Pathway | Accelerates market authorization for cardiac monitoring systems with invasive pressure capabilities. |
| Hospital System Partnership | Locks in replacement cycle revenues through centralized nursing station integration at AIIMS and CMC Vellore. |
| Software Companion Development | Enables per-patient-per-day analytics subscriptions distinct from hardware-only vendors. |
| Reimbursement Strategy | Qualifies continuous glucose monitoring and cardiac telemetry for ABPM-JAY insurance-linked procurement. |
| Backward Integration into Component Sourcing | Reduces MEMS sensor import dependency and mitigates Taiwanese fab concentration risk. |
Research Methodology
Multiple input streams — primary interviews with hospital purchasing committees, biomedical engineers, and GPO contracts managers; secondary validation through CDSCO registration databases, state-level tender documents, and hospital procurement records; plus customs data on medical device imports — were reconciled through bottom-up and top-down triangulation. Clinicians at tertiary care networks in Maharashtra and Karnataka provided clinical use case validation. SEC filings of listed medical device manufacturers and PLI scheme beneficiary disclosures supplied production capacity benchmarks.
Historical shipment data cross-referenced against panel input from distribution channel partners anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end-user setting, connectivity architecture, and clinical application. CAGRs were derived from installed base replacement cycles, reimbursement protocol expansion timelines, and domestic manufacturing capacity buildout under PLI incentives. Edge AI chip integration timelines and NDHM interoperability compliance deadlines fed industry-specific forecast inputs.
Caveats apply where semiconductor supply disruptions, BIS testing bottlenecks, or ABPM-JAY reimbursement scope revisions could materially shift the outlook. Forecasts reflect assumptions on regulatory clearance timelines and state-level procurement tender participation rates. A small set of triggers — CDSCO software-as-a-medical-device enforcement, Make in India domestic content threshold adjustments, and smartphone-app clinical validation pathways — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Holter Monitor Market
Patient Monitoring
North America Patient Temperature Management Market
Patient Monitoring
IoT in Healthcare Market
Patient Monitoring
Ambulatory Heart Monitor Market
Patient Monitoring
Global Ambulatory Blood Pressure Monitoring (ABPM) Devices Market
Patient Monitoring
Fetal Heart Rate Monitoring Devices Market
Patient Monitoring
Global Biomedical Sensor Market
Patient Monitoring
Oman Blood Glucose Monitoring Market
Patient Monitoring
Abetalipoproteinemia Monitoring Systems Market
Patient Monitoring
US Remote Patient Monitoring and Care Market
Patient Monitoring
Sleep Tracking Devices Market
Patient Monitoring
Global Blood Pressure Monitoring Devices Market
Patient Monitoring
United States Patient Monitoring Market
Patient Monitoring
Wearable Patient Monitor Market
Patient Monitoring
Middle East and Africa Fetal and Neonatal Monitoring Market
Patient Monitoring
Italy Patient Monitoring Market