
 Sleep Tracking Devices Market | 2026-2036
Sleep Tracking Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Sleep Tracking Devices Market Intelligence
South Korea's sensor manufacturing corridor is narrowing the component supply gap for advanced sleep trackers. Samsung leverages its semiconductor foundry capacity to sustain captive production of bio-sensing chips. Apple Inc. anchors premium positioning through proprietary heart rate variability algorithms. Garmin Ltd. competes in the endurance-athlete niche with extended-battery form factors.
Sleep tracking devices comprise sensor-embedded hardware and algorithmic software that capture physiological signals—principally accelerometry, photoplethysmography, and peripheral temperature—to estimate sleep architecture and recovery metrics. These systems serve commercial purposes spanning consumer wellness optimization, clinical sleep-disorder screening, and longitudinal research cohorts. Wearable trackers occupy the dominant revenue position due to wrist-worn convenience and all-day health-data continuity, while bed sensors capture higher-fidelity movement and respiration data for clinical-grade applications. Heart rate variability technology commands premium pricing as a validated proxy for autonomic nervous system recovery, whereas smartphone apps face margin compression from free-to-download distribution models.
FDA Software as a Medical Device frameworks and HIPAA data-privacy standards shape product-development roadmaps and channel access for US-bound manufacturers. The EU MDR and GDPR impose parallel conformity and consent-management burdens for European market entry. Stakeholders must monitor evolving regulatory distinctions between wellness-general and disease-specific claims, as this boundary determines clinical-channel eligibility and reimbursement potential.
Market Dynamics
FDA Software as a Medical Device clearance pathways are tightening validation requirements for algorithmic sleep staging, forcing manufacturers to rebuild software pipelines around prospective clinical trials rather than retrospective validation cohorts. This regulatory inflection is compressing development timelines and raising capital barriers for new entrants.
Growth Catalysts
- Remote Patient Monitoring:Healthcare providers in the United States are deploying validated wearables for obstructive sleep apnea screening. Medicare reimbursement codes for home sleep testing are expanding channel access for prescription-grade devices.
- Photoplethysmography Advancement:Multi-wavelength optical sensors now capture peripheral oxygen saturation and respiratory rate from wrist-worn form factors. Sleep medicine clinics are adopting these systems for longitudinal patient monitoring.
- Employer Wellness Programs:Large self-insured employers in the United States are procuring sleep trackers as preventive health investments. Bulk purchasing agreements are driving volume through occupational health channels.
Market Restraints
- Bio-Sensing Chip Supply Concentration:Advanced photodiode arrays and analog front-end integrated circuits concentrate in South Korean and Taiwanese foundry capacity. Geopolitical friction or fab utilization spikes create input volatility for hardware manufacturers.
- Algorithm Validation Costs:Prospective clinical trials for FDA SaMD clearance require multi-site polysomnography correlation studies. Small developers face capital constraints that favor incumbents with existing trial infrastructure.
- Smartphone Substitution:Accelerometer-based sleep estimation applications distributed through mobile app stores capture price-sensitive consumers. Free-to-download models compress margins for dedicated hardware entrants.
Strategic Opportunities
- Pediatric Sleep Screening:Underpenetrated demand exists for child-appropriate form factors and normative algorithm training data. Developmental sleep disorder clinics represent a channel expansion vector.
- EU MDR Convergence:The Medical Device Regulation creates harmonized pathways for clinical-grade wearables across European member states. Manufacturers with notified body relationships can leverage single certification for multi-country deployment.
- Heart Rate Variability Integration:Convergence between autonomic nervous system analytics and sleep architecture scoring enables premium positioning. Athlete monitoring platforms and corporate wellness portals are integrating these combined metrics.
Industry Challenges
- Polysomnography Correlation Talent:Sleep staging algorithm development requires specialized expertise in clinical neurophysiology and signal processing. The intersection of these skill sets commands premium compensation and lengthens hiring cycles.
- HIPAA Technical Safeguards:Cloud-connected devices must implement encryption, access controls, and audit logging that satisfy federal security rule requirements. Compliance engineering adds development overhead and ongoing operational cost.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sleep Tracking Devices Market |
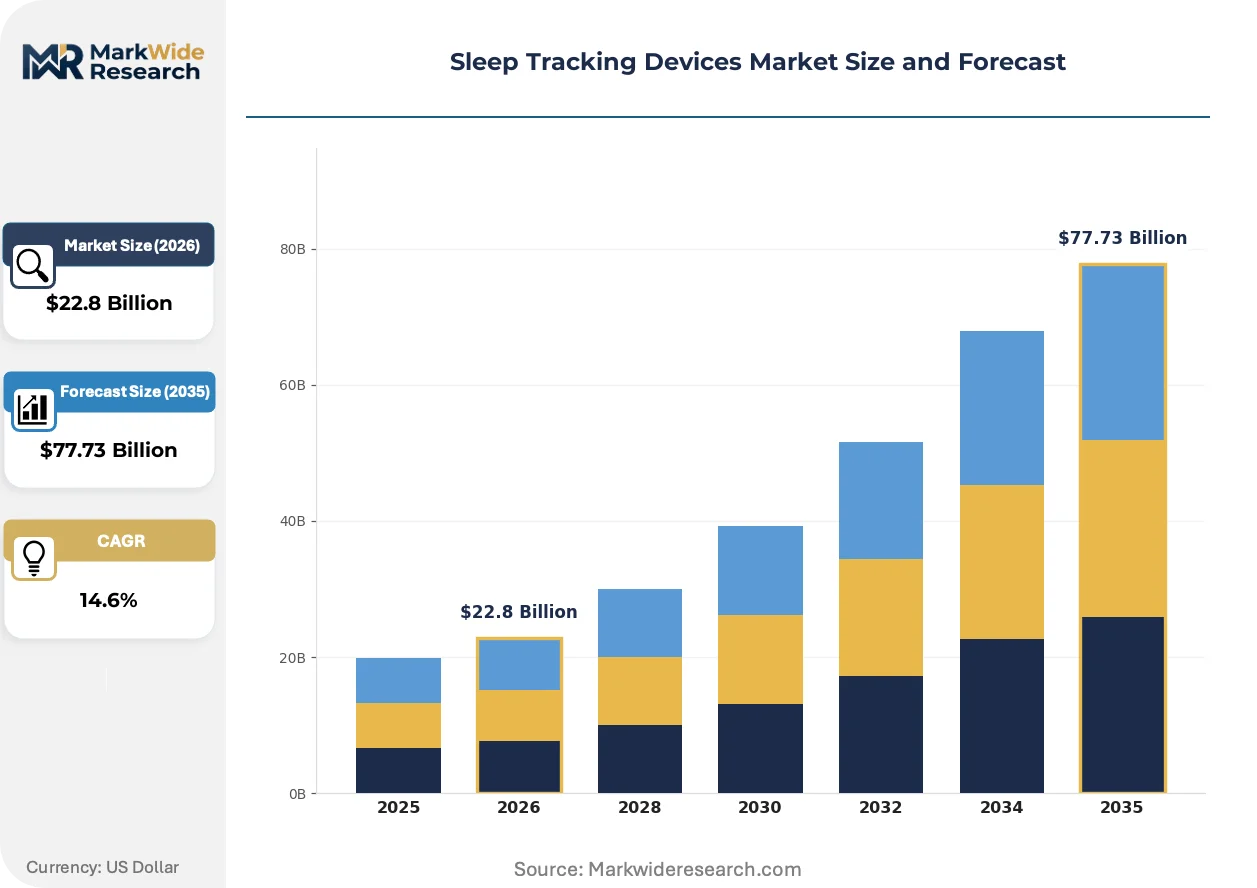
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $77.73 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Trackers, Bed Sensors, Smartphone Apps, Sleep Monitors Technology: Accelerometer, Sleep Stage Analysis, Heart Rate Variability, Ambient Light Sensors End User: Consumers, Healthcare Providers, Fitness Enthusiasts, Researchers Distribution Channel: Online Retail, Specialty Stores, Pharmacies, Direct Sales |
| Companies Covered | Garmin Ltd., Withings, Apple Inc., Huawei Device Co., Ltd., Samsung, Fitbit, ResMed, Philips, Oura Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sleep Tracking Devices Market Strategic Shifts & Innovations
Sensor fusion architectures and machine learning inference at the edge are transforming how physiological signals become actionable sleep metrics. These technical advances are compressing the gap between consumer convenience and clinical validity.
Multi-wavelength photoplethysmography combined with accelerometry and skin temperature sensing is digitizing sleep architecture estimation. Sleep medicine clinics in the United States are adopting wrist-worn systems that previously required laboratory polysomnography. The technology is digitizing patient throughput by enabling unattended home testing with automated scoring pipelines.
The EU Medical Device Regulation and its accompanying guidance on clinical evidence for software are reshaping European market entry requirements. Manufacturers must now compile clinical performance data through prospective studies rather than literature-based equivalence arguments. Prescription-grade wearable developers are responding by establishing European investigator sites and notified body relationships earlier in product lifecycles.
Employer wellness programs are consolidating vendor relationships around platforms that integrate sleep data with medical claims and productivity metrics. Benefits administrators are displacing point-solution vendors with integrated health analytics contracts. This concentration is most visible among Fortune 500 self-insured employers in the United States negotiating multi-year population health agreements.
Sleep Tracking Devices Market Segmentation
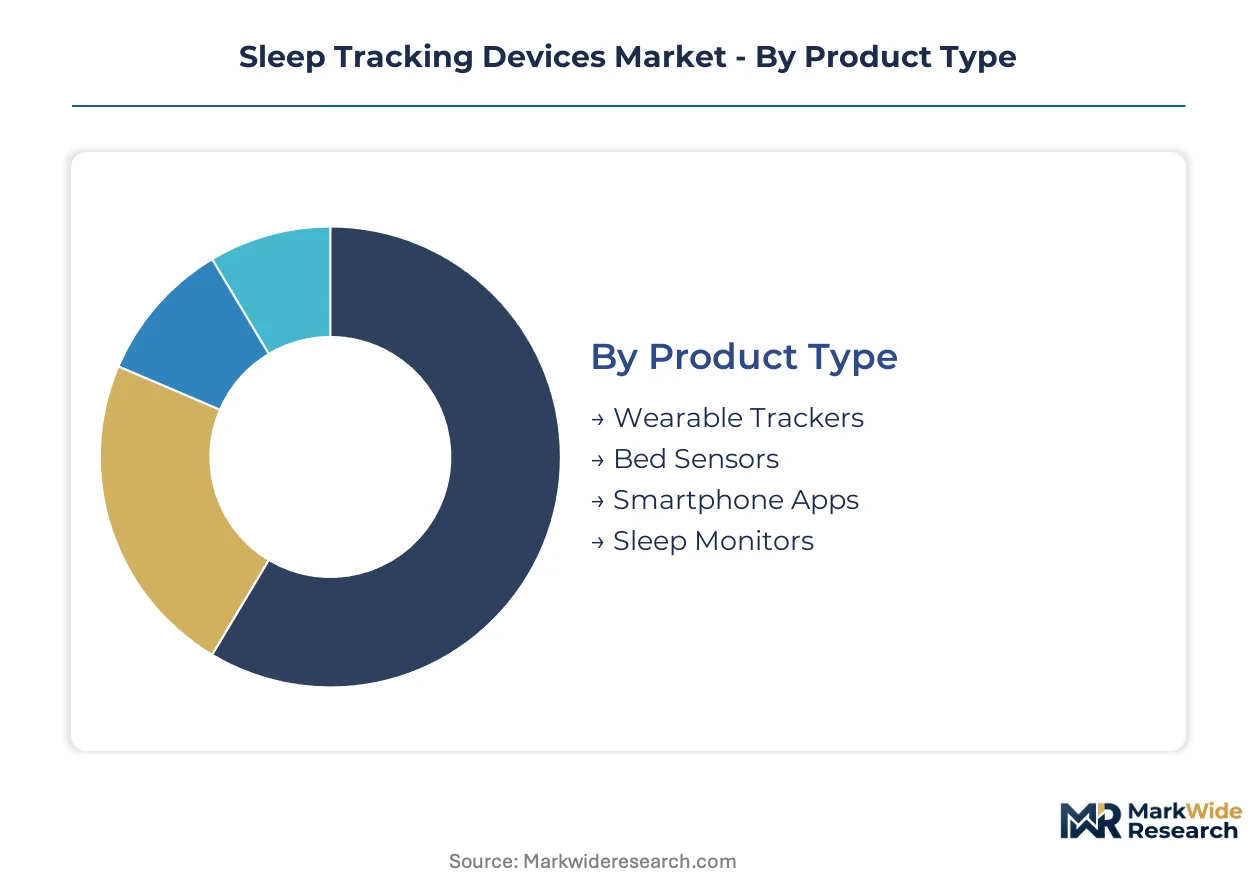
Sleep tracking devices fragment across hardware form factors, sensing modalities, and channel economics that reshape service intensity and margin structure. Each dimension carries distinct regulatory burdens, replacement cycles, and customer lifetime value profiles.
Product Type:
After-sales service intensity varies sharply across form factors, with clinical-grade hardware demanding calibration support while consumer apps require minimal ongoing intervention.
- Wearable Trackers:Wrist-worn devices integrate accelerometry with photoplethysmography for continuous physiological monitoring. Demand concentrates among employer wellness programs in the United States seeking validated metrics for population health contracts. Battery replacement and strap wear drive recurring service touchpoints.
- Bed Sensors:Non-contact systems capture movement, respiration, and ballistocardiography through pressure or radar arrays. Sleep medicine clinics in the United States deploy these for unattended home sleep apnea testing reimbursed under expanding Medicare codes. Installation complexity elevates service intensity relative to wearables.
- Smartphone Apps:Accelerometer-based sleep estimation distributed through mobile app stores captures price-sensitive consumers with minimal hardware overhead. Freemium monetization compresses margins and service obligations.
- Sleep Monitors:Dedicated bedside devices combining audio, environmental, and physiological sensing for comprehensive sleep environment analysis. Direct-to-consumer channels dominate with limited clinical validation requirements.
Wearable trackers hold the largest share; momentum sits with bed sensors as clinical reimbursement pathways mature.
Technology:
Cost tier stratification separates premium multi-sensor fusion from basic motion-based estimation, with pricing power concentrated in validated autonomic nervous system metrics.
- Accelerometer:Foundational motion sensing enabling sleep-wake detection through actigraphy principles. Ubiquitous in entry-level wearables and smartphone apps where hardware cost minimization drives selection.
- Sleep Stage Analysis:Algorithmic estimation of NREM and REM architecture through multi-signal fusion. FDA Software as a Medical Device clearance requirements for clinical claims are compressing vendor margins through prospective trial mandates.
- Heart Rate Variability:Inter-beat interval analysis serving as validated proxy for autonomic recovery and stress load. Athlete monitoring platforms and corporate wellness portals command premium pricing for this metric integration.
- Ambient Light Sensors:Environmental circadian rhythm tracking through melanopic lux measurement. Smart home integration and lighting control systems represent emerging demand channels.
Sleep stage analysis holds the largest share; momentum sits with heart rate variability as recovery optimization expands beyond clinical settings.
End User:
Customer type determines pricing architecture, with institutional procurement favoring validated devices and subscription analytics while individual consumers prioritize upfront hardware cost.
- Consumers:Individual purchasers seeking wellness optimization through direct-to-consumer channels. Price sensitivity and feature breadth dominate purchase criteria over clinical validation.
- Healthcare Providers:Sleep medicine clinics and hospital systems requiring FDA-cleared devices for diagnostic and monitoring applications. Reimbursement eligibility and polysomnography correlation data drive procurement decisions.
- Fitness Enthusiasts:Amateur and professional athletes prioritizing recovery metrics and training load management. Endurance sports demographics favor extended-battery form factors with robust environmental resistance.
- Researchers:Academic and pharmaceutical cohort studies demanding raw signal access and data export capabilities. Longitudinal validation and publication-grade methodology compliance shape vendor selection.
Consumers hold the largest share; momentum sits with healthcare providers as remote patient monitoring reimbursement expands.
Distribution Channel:
Volume concentration in direct digital channels is displacing traditional retail, with pharmacy access gated by clinical certification status.
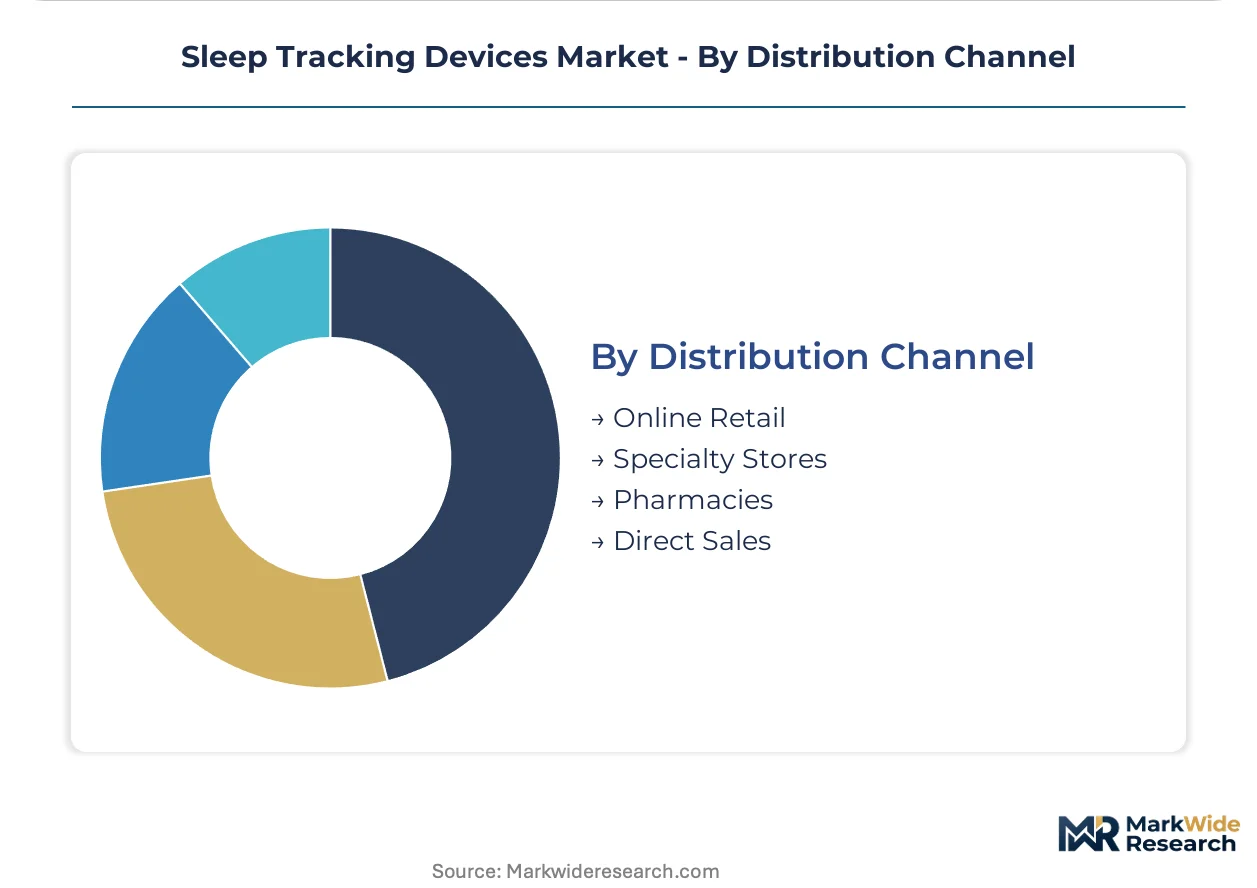
- Online Retail:E-commerce platforms and manufacturer direct-to-consumer storefronts capturing majority volume. Review aggregation and comparison tools intensify price transparency.
- Specialty Stores:Consumer electronics and outdoor recreation retailers providing hands-on evaluation for premium wearables. Staff expertise on sensor accuracy differentiates positioning.
- Pharmacies:Retail and mail-order pharmacy chains for prescription-grade devices requiring clinician involvement. HIPAA compliance and insurance billing integration determine partnership eligibility.
- Direct Sales:Enterprise contracts with employers, health systems, and wellness platforms bypassing retail markup. Population health analytics bundling drives multi-year agreement structures.
Online retail holds the largest share; momentum sits with direct sales as employer wellness consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States healthcare providers deploy sleep trackers for remote patient monitoring and home sleep apnea testing, while Asian manufacturing clusters supply sensor components and European regulators enforce stricter clinical validation standards.
United States
Medicare reimbursement expansion for home sleep testing drives demand from sleep medicine clinics and employer wellness programs. FDA Software as a Medical Device frameworks tighten algorithmic validation requirements for clinical-grade claims. Boston and San Francisco anchor digital health innovation clusters where sleep-tech startups cluster near academic medical centers.
Germany
Industrial employer wellness programs and statutory health insurance integration create institutional procurement channels. EU MDR conformity requirements reshape clinical evidence standards for software-based medical devices. Munich and Berlin concentrate medtech engineering talent and notified body relationships for European market certification.
South Korea
Captive semiconductor foundry capacity supports bio-sensing chip production for wrist-worn and bed-based sleep monitors. MFDS medical device regulations align with international standards to facilitate export-oriented manufacturing. Seoul Capital Area hosts Samsung's integrated sensor-to-device production ecosystem.
Japan
Aging demographics and government preventive health initiatives expand demand for home-based sleep disorder screening. PMDA consultation pathways guide developers through clinical trial design for software medical devices. Tokyo and Osaka metropolitan areas concentrate sleep research institutions and medtech distribution networks.
United Kingdom
NHS long-term plan commitments to digital-first primary care create procurement opportunities for validated remote monitoring tools. MHRA post-Brexit regulatory autonomy maintains alignment with international standards while streamlining domestic clearance. London and Cambridge clusters fuse academic sleep research with health-tech commercialization.
Sleep Tracking Devices Market Key Industry Players
Capability concentration sits with technology-integrated conglomerates possessing proprietary algorithms and semiconductor assets; scale advantage sits with specialized health-device manufacturers with established clinical distribution. The market structures around three tiers: consumer electronics giants with captive sensor supply, dedicated health-technology firms with FDA-cleared portfolios, and emerging specialists targeting athlete monitoring and pediatric applications. Dominant competitive moves include algorithmic differentiation through prospective clinical validation and strategic partnerships with employer wellness platforms and sleep medicine clinic networks.
Within the consumer electronics tier, Apple Inc. and Samsung exemplify integrated hardware-software positioning through proprietary sensing architectures and ecosystem lock-in. Garmin Ltd. occupies a specialization position targeting endurance athletes with extended-battery form factors and recovery analytics. ResMed represents the clinical-grade archetype with established FDA-cleared devices and reimbursement pathways for sleep-disorder diagnostics.
| Leading Market Players |
|---|
| Garmin Ltd. |
| Withings |
| Apple Inc. |
| Huawei Device Co., Ltd. |
| Samsung |
| Fitbit |
| ResMed |
| Philips |
| Oura Health |
| Others |
Cost & Logistics Intelligence
Incheon-Seoul freight corridors carry photodiode arrays and analog front-end integrated circuits from South Korean foundries to assembly plants, with logistics cost volatility amplifying margin pressure for hardware manufacturers while enabling tiered pricing stratification across FDA-cleared clinical devices and consumer wellness trackers.
Pricing Analysis
Long-term offtake agreements dominate procurement between sleep tracker OEMs and South Korean semiconductor foundries, locking in multi-year pricing for bio-sensing chips while spot-market exposure concentrates in memory components. Three-tier pricing structure across premium, standard, and economy levels separates prescription-grade devices with polysomnography correlation from employer wellness bulk contracts and direct-to-consumer wristbands. Pricing pressure stems from Medicare reimbursement compression for home sleep testing devices. Healthcare providers show lowest price sensitivity due to reimbursement eligibility, while individual consumers drive cost compression through app-based alternatives.
Supply Chain Analysis
Contract manufacturing concentrates at Foxconn, Jabil, and Pegatron facilities across Vietnam, Mexico, and Malaysia, with wrist-worn device assembly migrating toward tariff-advantaged locations. Raw material dependencies center on gallium arsenide photodiodes from South Korea, analog front-end ICs from Taiwan, and lithium-polymer cells from China. Single-source vulnerability in advanced photodiode arrays creates input risk for multi-wavelength sleep staging hardware. Distribution runs through direct enterprise sales for employer wellness contracts, online retail for consumer devices, and pharmacy channels for prescription-grade systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates entry niches as FDA Software as a Medical Device pathways bifurcate vendors into clinical-grade and wellness-general camps, with reimbursement eligibility determining sustainable margin pools.
For Market Incumbents: Harden algorithm validation infrastructure against tightening FDA prospective trial mandates by establishing captive polysomnography correlation capabilities or exclusive academic medical center partnerships. Deepen backward integration into bio-sensing chip design to insulate margins from South Korean foundry utilization spikes and geopolitical friction. For New Entrants and Emerging Players: Pursue pediatric sleep screening as the most penetrable white space, where child-appropriate form factors and developmental normative data gaps disadvantage established adult-focused vendors. Target direct-to-clinic sales models bypassing retail markup, with developmental sleep disorder centers as the initial beachhead. For Investors and Strategic Acquirers: Algorithm-native startups with FDA breakthrough device designation and existing notified body relationships in Germany represent the priority acquisition archetype for platform consolidation plays. Watch Medicare reimbursement code expansion velocity as the signal distinguishing sustainable clinical-channel revenue from wellness-general margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software as a Medical Device Submission | Unlocks prescription-channel access and Medicare reimbursement eligibility for sleep staging algorithms. |
| Notified Body Relationship Establishment | Enables single EU MDR certification for multi-country European deployment of clinical-grade wearables. |
| Employer Wellness Platform Partnership | Secures multi-year population health contracts with Fortune 500 self-insured benefits administrators. |
| Multi-wavelength Photoplethysmography Integration | Differentiates premium positioning through peripheral oxygen saturation and respiratory rate capture. |
| Pediatric Algorithm Training Data Investment | Builds defensive moat in underpenetrated child sleep disorder screening segment. |
Research Approach
A spread of perspectives from sleep medicine clinicians, biomedical engineers at wearable OEMs, GPO contracts managers, and employer benefits administrators converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, and EU MDR notified body guidance documents. Bottom-up demand modeling across consumer, healthcare provider, and employer segments triangulated against top-down market sizing from trade flow data and semiconductor foundry capacity disclosures.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with sleep tracker hardware shipments reconciled against photodiode array production capacity and lithium cell supply. Segmentation dimensions modeled include product form factor, sensing technology tier, end-user archetype, and distribution channel economics. CAGRs were derived from logistic diffusion curves fitted to reimbursement expansion timelines and employer wellness program adoption patterns. Forecast inputs incorporated Medicare code creation velocity and EU MDR clinical evidence requirement phase-in schedules.
Sensitivities concentrate around FDA SaMD validation timeline delays, South Korean foundry utilization spikes, and Medicare reimbursement compression for home sleep testing. Forecasts reflect documented assumptions regarding regulatory pathway evolution and semiconductor supply normalization. Cross-checking against CMS physician fee schedule updates and notified body capacity constraints is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Global Smart Pulse Oximeters Market
Patient Monitoring
Asia-Pacific Cardiac Arrhythmia Monitoring Devices Market
Patient Monitoring
Body Fat Measurement Market
Patient Monitoring
Infusion Rate Monitoring Market
Patient Monitoring
Global Patient Positioning System Market
Patient Monitoring
Brain Tissue Oxygen Monitoring Systems Market
Patient Monitoring
Middle East and Africa Cardiac Monitoring Market
Patient Monitoring
Global Hemodynamic Monitoring System Market
Patient Monitoring
Patient Monitoring and Ultrasound Devices Display Market
Patient Monitoring
Global Arrhythmia Monitoring Devices Market
Patient Monitoring
IoT in Healthcare Market
Patient Monitoring
ECG Monitoring System Market
Patient Monitoring
Global Fetal and Neonatal Monitoring Market
Patient Monitoring
Wearable Heart Monitoring Devices Market
Patient Monitoring
Online Patient Observation Market
Patient Monitoring
Italy Patient Monitoring Market