
 ESR1 Mutated Metastatic Breast Cancer Diagnostics Market | 2026-2036
ESR1 Mutated Metastatic Breast Cancer Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
ESR1 Mutated Metastatic Breast Cancer Diagnostics Market Foresight
Oncology reference laboratories is redrawing procurement priorities as hospital systems build in-house NGS capabilities for ESR1 mutation detection. Guardant Health leverages its circulating tumor DNA platform to sustain leadership in minimal residual disease monitoring for hormone receptor-positive metastatic disease. Foundation Medicine anchors comprehensive genomic profiling workflows that span solid tumor indications beyond breast cancer. Illumina competes through instrument placement strategies that lock in consumable revenue across academic and community hospital settings.
ESR1 mutated metastatic breast cancer diagnostics encompass molecular assays that detect activating mutations in the estrogen receptor 1 gene, particularly D538G and Y537S substitutions that drive ligand-independent receptor signaling and endocrine therapy resistance. These tests employ digital PCR, bead-based emulsion amplification, or hybridization capture sequencing to achieve allele sensitivity below 0.1% variant frequency in cell-free DNA. Liquid biopsies capture the fastest expansion as blood-draw protocols replace repeated tissue biopsies in progressive disease monitoring, while next-generation sequencing platforms command the deepest margin pools through bundled reagent-instrument contracts. Diagnostic laboratories represent the most concentrated end-user channel, though hospital-owned labs are eroding third-party volumes through vertical integration of molecular pathology services.
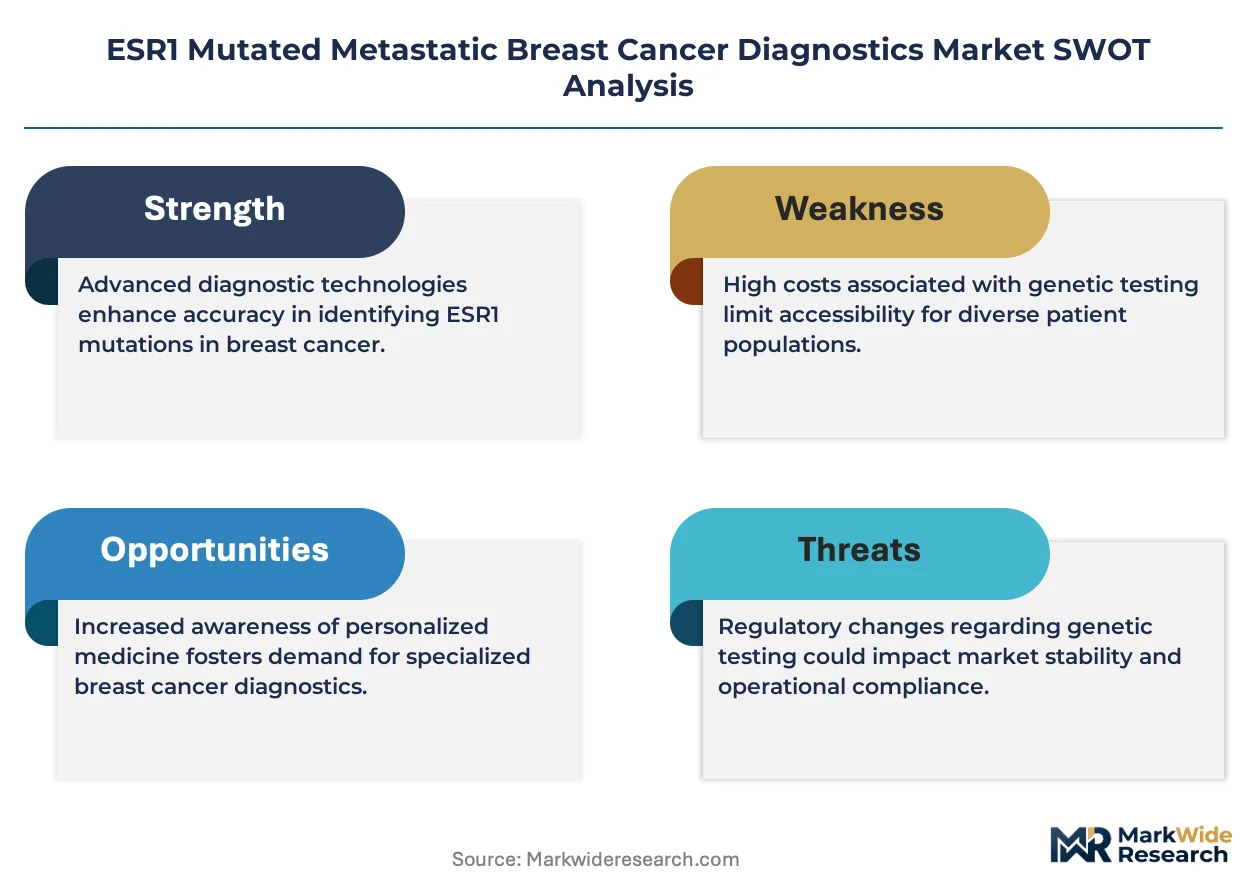
FDA oversees companion diagnostic co-development requirements for ESR1-targeted therapies, while EMA's In Vitro Diagnostic Regulation imposes stricter clinical evidence standards for Class C devices detecting cancer biomarkers. The country's national pharmaceutical regulator in Japan evaluates somatic mutation tests under the Sakigake designation pathway, accelerating reimbursement decisions for innovative diagnostics. Stakeholders must monitor evolving payer coverage policies for ctDNA-based monitoring, as Medicare contractor determinations and German G-BA benefit assessments will set precedents for routine clinical adoption without prospective trial evidence.
Market Dynamics
Liquid biopsy platforms are compressing tissue-based testing volumes as academic medical centers prioritize blood-draw protocols for serial monitoring of endocrine-resistant metastatic breast cancer patients.
Growth Catalysts
- FDA companion diagnostic mandates:Co-development requirements for ESR1-targeted therapies are accelerating assay validation investments and standardizing clinical evidence thresholds across oncology pipelines.
- Digital PCR sensitivity thresholds:Sub-0.1% allele frequency detection in cell-free DNA is expanding the addressable patient population to earlier-stage resistance monitoring.
- Academic medical center consolidation:Hospital system vertical integration of molecular pathology is creating captive demand for in-house NGS workflows.
Market Restraints
- Reimbursement uncertainty:Medicare contractor determinations for ctDNA-based monitoring without prospective trial evidence are constraining routine clinical adoption in United States community settings.
- Consumable cost concentration:Illumina's instrument placement strategies lock laboratories into bundled reagent contracts that erode margin flexibility for high-volume testing.
- Technical specificity limitations:ESR1 D538G and Y537S mutation detection in low-shedding tumors requires orthogonal confirmation, adding workflow complexity and turnaround time.
Strategic Opportunities
- Japanese Sakigake pathway:PMDA's accelerated reimbursement designation for innovative somatic mutation tests offers first-mover advantage for liquid biopsy entrants in Asia-Pacific's second-largest oncology market.
- Minimal residual disease monitoring:Post-adjuvant hormone receptor-positive patient surveillance represents an untapped application beyond progressive disease settings.
- Hybridization capture-NGS convergence:Combining amplicon speed with comprehensive genomic profiling breadth enables single-workflow ESR1 detection plus co-occurring alteration identification.
Industry Challenges
- Bioinformatics pipeline standardization:Variant calling algorithm discordance across laboratories complicates inter-institutional result comparability and clinical decision consistency.
- Pre-analytical variable control:Cell-free DNA stability during shipping and processing requires cold-chain infrastructure that community hospital labs struggle to maintain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ESR1 Mutated Metastatic Breast Cancer Diagnostics Market |
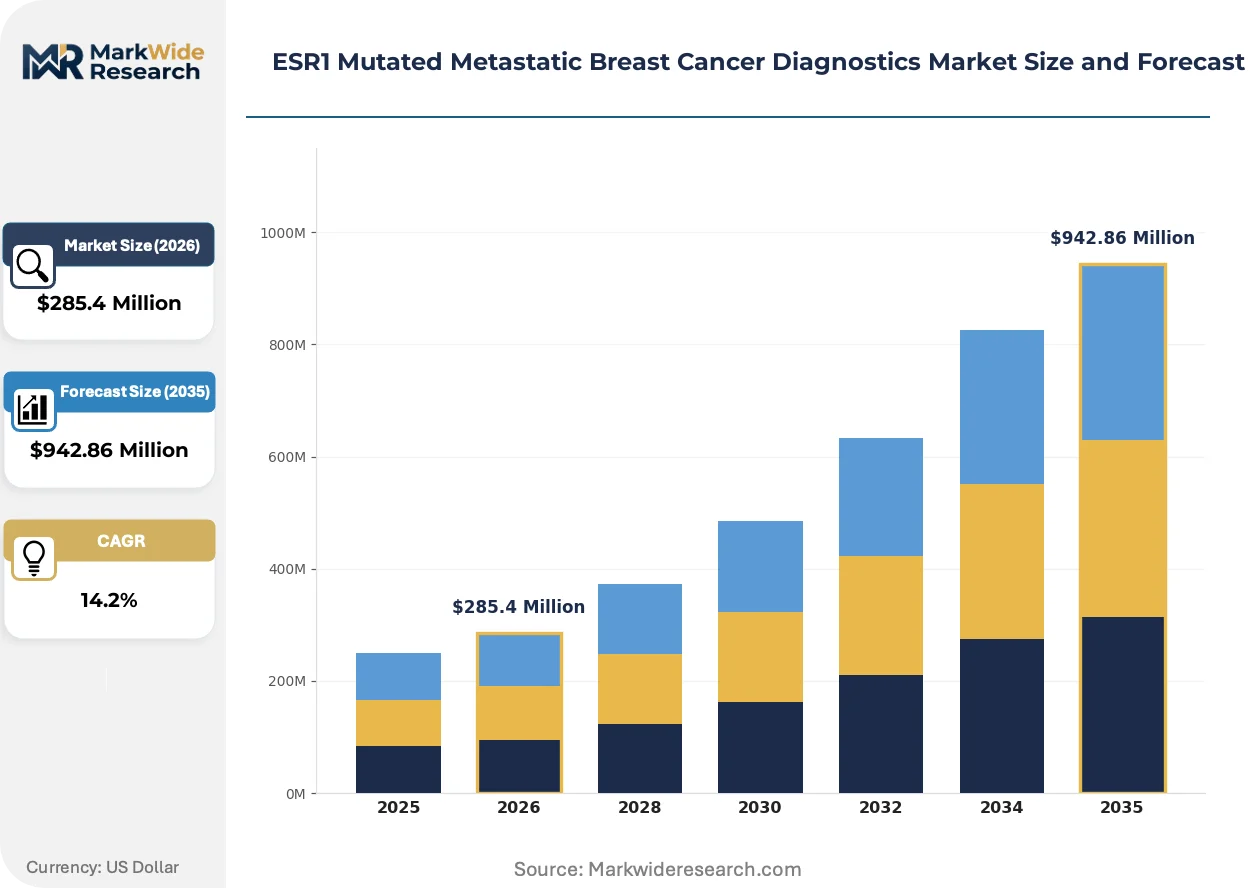
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $942.86 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biomarker Tests, Imaging Techniques, Next-Generation Sequencing, Liquid Biopsies End User: Clinics, Hospitals, Research Institutions, Diagnostic Laboratories Technology: PCR, FISH, NGS, ELISA Application: Early Detection, Treatment Monitoring, Prognostic Evaluation, Clinical Trial Enrollment |
| Companies Covered | ASURAGEN, Inc., Sysmex Corporation, Illumina, Inc., RainSure Scientific Co., Ltd., GENCURIX, NeoGenomics Laboratories, Foundation Medicine, Bio-Rad Laboratories, Inc., Guardant Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ESR1 Mutated Metastatic Breast Cancer Diagnostics Market Shifts & Advancements
Multiplexed mutation detection architectures are redefining competitive positioning as laboratories trade off sensitivity against breadth and cost per reportable result.
Bead-based emulsion amplification is fragmenting the digital PCR landscape by enabling higher plexity without sacrificing the single-molecule resolution required for rare variant detection in plasma. Community hospital laboratories are adopting these platforms faster than academic centers, driven by simpler workflow integration and reduced bioinformatics overhead. The technology is compressing addressable market share for pure-play dPCR vendors who lack sequencing adjacency.
EMA's In Vitro Diagnostic Regulation imposes stricter clinical evidence standards for Class C cancer biomarker devices, forcing manufacturers to retroactively compile prospective performance data for existing assays. German notified bodies are processing certification backlogs that delay market entry for novel ESR1 detection kits. Laboratories in France and Italy are prioritizing CE-IVD marked alternatives over laboratory-developed tests to mitigate compliance risk.
Hospital-owned laboratories are consolidating send-out testing volumes previously directed to oncology reference laboratories, reversing a decade of outsourcing momentum. United States health systems with captive NGS infrastructure now capture ESR1 mutation profiling internally, eroding third-party revenue pools. This concentration is most visible in integrated delivery networks across Texas, California, and Florida where capital deployment into molecular pathology preceded payer coverage expansion for liquid biopsy monitoring.
ESR1 Mutated Metastatic Breast Cancer Diagnostics Market Segmentation
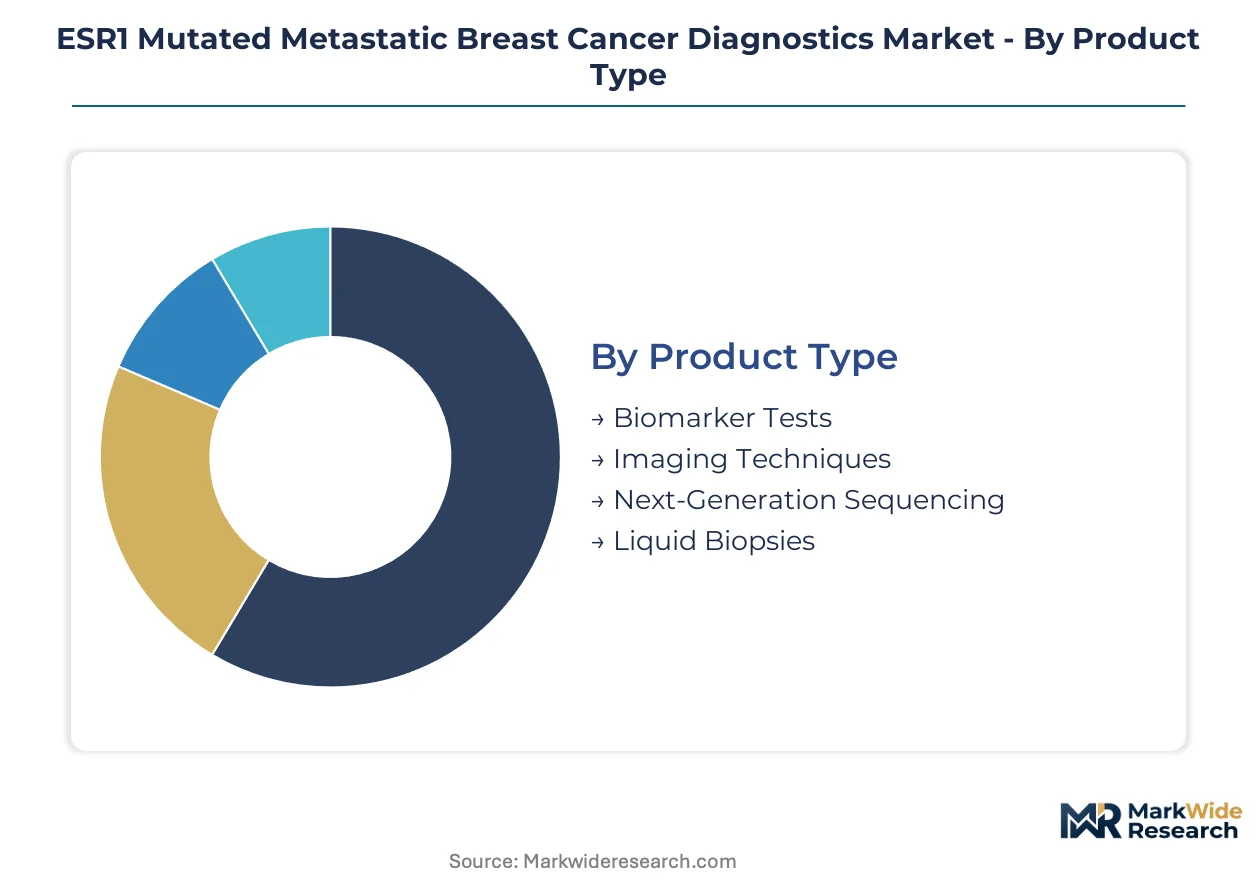
ESR1 mutation detection technologies fragment across sensitivity requirements, workflow complexity, and reimbursement pathways that reshape procurement decisions at hospital systems and reference laboratories. Segmentation reveals where liquid biopsy platforms displace tissue-based alternatives and which customer channels retain pricing power.
Product Type:
Liquid biopsy platforms face the strongest substitution pressure from in-house NGS buildouts, while imaging techniques confront reimbursement compression as molecular diagnostics claim clinical utility.
- Liquid Biopsies:Circulating tumor DNA assays detect D538G and Y537S mutations in plasma with sub-0.1% allele frequency sensitivity. Academic medical centers in the United States and Germany prioritize blood-draw protocols for serial monitoring of endocrine-resistant patients, though Medicare contractor determinations constrain community hospital adoption.
- Next-Generation Sequencing:Hybridization capture and amplicon-based workflows enable comprehensive genomic profiling beyond ESR1 alone. Hospital systems with captive NGS infrastructure capture testing volumes internally, eroding third-party reference laboratory revenue across Texas, California, and Florida integrated delivery networks.
- Biomarker Tests:Targeted PCR assays deliver rapid turnaround for treatment selection decisions.
- Imaging Techniques:Functional and anatomical imaging retains role in disease staging rather than mutation characterization.
Next-Generation Sequencing retains volume leadership; Liquid Biopsies hold the steepest expansion curve.
End User:
Customer concentration tilts toward institutions with capital deployment capacity for molecular pathology infrastructure and cold-chain logistics.
- Diagnostic Laboratories:Third-party oncology reference laboratories face volume erosion as hospital systems build in-house NGS capabilities. Community hospital labs struggle to maintain cell-free DNA stability during shipping and processing without adequate cold-chain infrastructure.
- Hospitals:Academic medical centers anchor precision oncology workflows with integrated molecular pathology services. Vertical integration of testing services reverses a decade of outsourcing momentum as health systems capture ESR1 profiling internally.
- Research Institutions:Translational research programs drive assay validation for companion diagnostic co-development.
- Clinics:Outpatient oncology practices depend on send-out arrangements for molecular testing access.
Hospitals command the highest revenue per test; Diagnostic Laboratories face the steepest volume pressure.
Technology:
Detection sensitivity thresholds and workflow automation requirements segment technology adoption across laboratory sophistication tiers.
- NGS:Hybridization capture sequencing achieves comprehensive co-mutation detection alongside ESR1 variants. EMA's In Vitro Diagnostic Regulation imposes stricter clinical evidence standards for Class C cancer biomarker devices, forcing retrospective compilation of prospective performance data.
- PCR:Digital PCR and bead-based emulsion amplification enable single-molecule resolution for rare variant detection. Community hospital laboratories adopt these platforms faster than academic centers due to simpler workflow integration and reduced bioinformatics overhead.
- FISH:Fluorescence in situ hybridization retains utility for gene amplification assessment rather than point mutation detection.
- ELISA:Protein-level detection methods lack specificity for ESR1 mutation characterization.
PCR retains installed base dominance; NGS captures the steepest share gains.
Application:
Clinical utility validation and reimbursement coverage segment addressable demand across the patient journey.
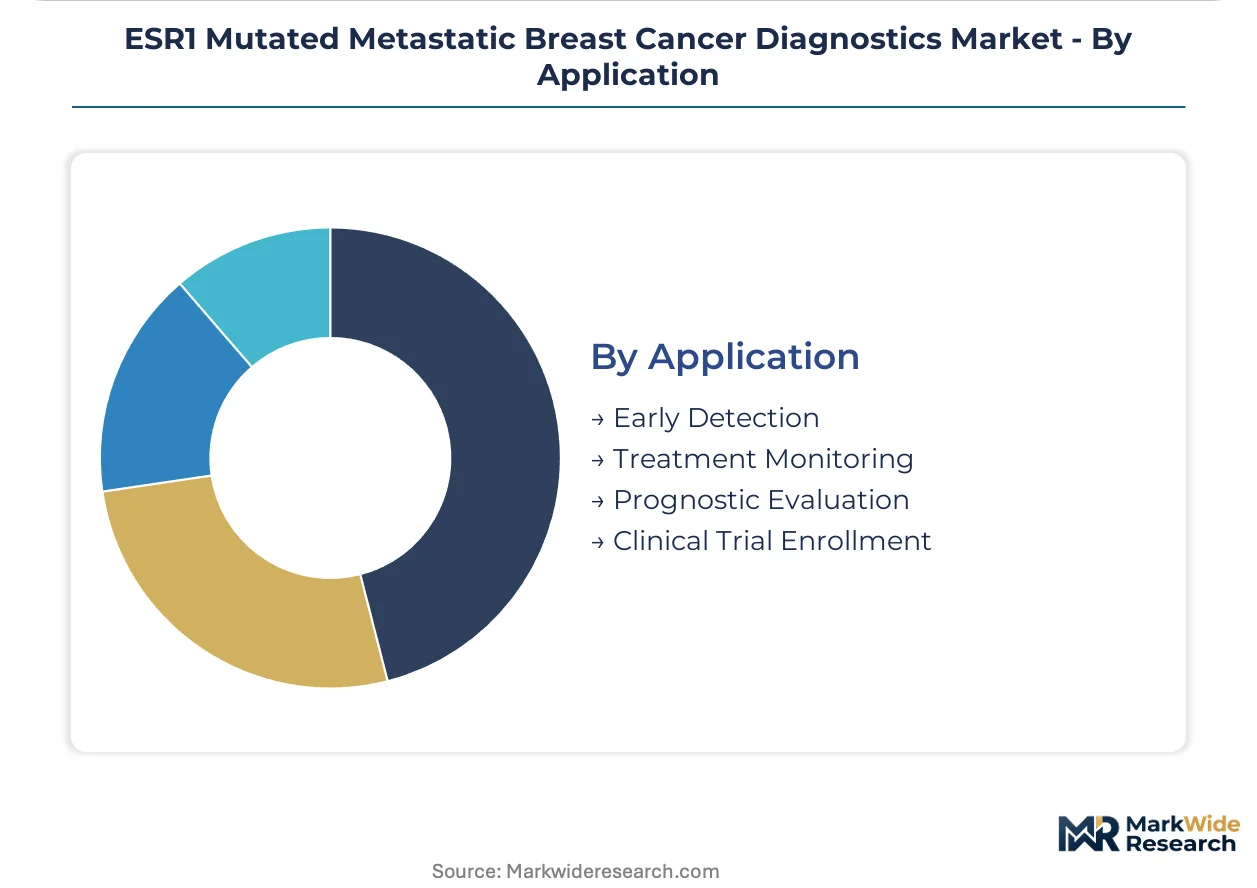
- Treatment Monitoring:Serial ctDNA assessment tracks clonal evolution and endocrine therapy resistance. FDA companion diagnostic mandates for ESR1-targeted therapies accelerate assay validation investments and standardize clinical evidence thresholds.
- Early Detection:Minimal residual disease surveillance in post-adjuvant hormone receptor-positive patients represents an untapped expansion beyond progressive disease settings. Japanese PMDA Sakigake designation pathway accelerates reimbursement decisions for innovative diagnostics in Asia-Pacific's second-largest oncology market.
- Prognostic Evaluation:Baseline mutation profiling informs expected treatment duration and resistance risk.
- Clinical Trial Enrollment:Biomarker qualification requirements shape pharmaceutical pipeline access.
Treatment Monitoring retains procedure volume leadership; Early Detection holds the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Los Angeles anchors North American logistics for precision oncology reagents, while Frankfurt Airport's cold-chain cargo terminals enable just-in-time consumable delivery across Central Europe. Japan's Kansai International Airport biopharma corridor accelerates Sakigake-designated diagnostic kit customs clearance.
United States
Integrated delivery networks in Texas, California, and Florida deploy captive NGS infrastructure for ESR1 mutation profiling. FDA companion diagnostic mandates for ESR1-targeted therapies standardize assay validation investments across pharmaceutical pipelines. The National Cancer Institute's designated cancer centers in Houston and Boston anchor liquid biopsy adoption for endocrine-resistant patient monitoring.
Germany
University hospital networks in Munich and Heidelberg prioritize hybridization capture sequencing for comprehensive genomic profiling workflows. EMA's In Vitro Diagnostic Regulation imposes stricter clinical evidence standards for Class C cancer biomarker devices, forcing retrospective performance data compilation. The Rhine-Main biotech cluster around Frankfurt concentrates notified body certification expertise for CE-IVD marked assay entry.
Japan
PMDA's Sakigake designation pathway accelerates reimbursement decisions for innovative somatic mutation tests in hormone receptor-positive metastatic disease. Academic medical centers in Tokyo and Osaka integrate circulating tumor DNA platforms into precision oncology workflows. The Kobe biomedical innovation cluster houses specialized logistics infrastructure for temperature-controlled diagnostic reagent distribution.
United Kingdom
NHS England's genomic medicine service consolidates molecular pathology testing within designated laboratory hubs across London, Manchester, and Cambridge. The Medicines and Healthcare products Regulatory Agency evaluates companion diagnostic submissions alongside ESR1-targeted therapy approvals. The Cambridge life sciences cluster anchors translational research programs driving assay validation for pharmaceutical pipeline access.
China
NMPA's innovative medical device approval pathway compresses timelines for liquid biopsy platforms detecting endocrine resistance mutations. Hospital systems in Shanghai and Beijing build in-house digital PCR capabilities to reduce send-out dependency for ctDNA monitoring. The Zhangjiang Hi-Tech Park concentrates domestic diagnostic kit manufacturers targeting allele-specific detection sensitivity thresholds.
ESR1 Mutated Metastatic Breast Cancer Diagnostics Market Competitive Landscape
Concentration sits with comprehensive genomic profiling specialists and liquid biopsy platform developers who anchor hospital system procurement decisions. The vendor base stratifies across three tiers: multinational sequencing instrument incumbents with consumable lock-in contracts, cancer-focused reference laboratories with companion diagnostic co-development relationships, and emerging digital PCR specialists with simplified workflow architectures. Dominant competitive moves include strategic instrument placement programs that secure long-term reagent revenue streams, and vertical integration of bioinformatics pipelines to reduce laboratory overhead.
Within the liquid biopsy platform tier, Guardant Health and Foundation Medicine exemplify divergent positioning strategies for circulating tumor DNA commercialization. Illumina anchors the sequencing infrastructure layer through bundled instrument-consumable contracts across academic and community hospital settings. Sysmex Corporation represents the Japanese diagnostic conglomerate archetype with established distribution networks for oncology assay deployment in Asia-Pacific markets.
| Leading Market Players |
|---|
| ASURAGEN, Inc. |
| Sysmex Corporation |
| Illumina, Inc. |
| RainSure Scientific Co., Ltd. |
| GENCURIX |
| NeoGenomics Laboratories |
| Foundation Medicine |
| Bio-Rad Laboratories, Inc. |
| Guardant Health |
| Others |
Supply & Pricing Matrix
Instrument placement contracts with bundled reagent commitments lock hospital laboratories into multi-year consumable supply agreements that anchor both cost visibility and vendor switching costs for ESR1 mutation detection platforms. These arrangements concentrate pricing power with sequencing infrastructure incumbents while compressing margin flexibility for high-volume testing operations.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the ESR1 diagnostics market by detection sensitivity and workflow automation. Premium tiers command positioning through FDA companion diagnostic co-development status and sub-0.1% allele frequency detection thresholds, while economy tiers serve community hospitals with basic PCR assays. Cost compression in the standard tier intensifies as in-house NGS buildouts at integrated delivery networks erode third-party reference laboratory volumes. Community hospital laboratories exhibit the highest price sensitivity due to constrained capital budgets, whereas academic medical centers prioritize clinical evidence quality over per-test economics.
Supply Chain Analysis
The United States and Germany anchor precision oncology reagent manufacturing and cold-chain distribution infrastructure for circulating tumor DNA assays. China and Japan supply critical components including digital PCR consumables, hybridization capture probes, and fluorescence detection chemistries. The supply chain draws from specialized polymerase enzymes and synthetic oligonucleotide libraries that face single-source vulnerability from concentrated bioreagent foundries. Distribution runs through oncology reference laboratories and hospital-owned molecular pathology services, with temperature-controlled logistics required for cell-free DNA stability during transit.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ESR1 mutated metastatic breast cancer diagnostics function as a service-attach market where consumable reagent streams and bioinformatics subscriptions expand faster than capital instrument placements. Recurring revenue from assay-specific reagent kits and cloud-based variant interpretation platforms outpaces hardware growth curves.
For Market Incumbents: Shield installed base positions by deepening bioinformatics pipeline integration and securing exclusive companion diagnostic co-development partnerships with ESR1-targeted therapy developers. Digital PCR specialists with simplified workflow architectures threaten reference laboratory market share through faster community hospital adoption curves. Regulatory certification investment in Japan's PMDA Sakigake pathway and EMA's In Vitro Diagnostic Regulation CE-IVD marking represents the critical defensive lever against emerging platform competitors. For New Entrants and Emerging Players: Post-adjuvant minimal residual disease monitoring for hormone receptor-positive patients represents an underserved service layer where incumbents lack validated clinical evidence and established reimbursement pathways. Community hospital laboratories in United States states with limited cold-chain infrastructure offer the most penetrable channel, accessible through bead-based emulsion amplification platforms with reduced bioinformatics overhead. A go-to-market angle anchored on orthogonal confirmation workflows for low-shedding tumor detection addresses unmet technical specificity needs. For Investors and Strategic Acquirers: Liquid biopsy platform developers with established circulating tumor DNA regulatory submissions and Asia-Pacific distribution networks present the highest strategic value acquisition archetype for pharmaceutical diagnostic co-development pipelines. Long-term viability across the analysis window hinges on Medicare contractor determinations establishing routine reimbursement for ctDNA-based monitoring without prospective trial evidence. The signal to watch is German G-BA benefit assessment precedents that could validate clinical utility and unlock European commercial expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | FDA submission alignment with ESR1-targeted therapy pipelines secures exclusive assay positioning and reimbursement priority. |
| CE-IVD Regulatory Certification | EMA In Vitro Diagnostic Regulation compliance enables European market entry and mitigates laboratory-developed test substitution risk. |
| Hospital System Partnership | Integrated delivery network contracts in Texas and California anchor captive testing volumes against reference laboratory erosion. |
| Software Companion Development | Cloud-based variant calling algorithms reduce laboratory bioinformatics overhead and lock in recurring subscription revenue streams. |
| Reimbursement Strategy | Medicare contractor determination navigation establishes precedent coverage for liquid biopsy monitoring in community oncology settings. |
Research Methodology
Desk research of FDA 510(k) filings, EMA CE-IVD certification databases, and ClinicalTrials.gov companion diagnostic protocols preceded structured interviews with molecular pathology laboratory directors, regulatory affairs specialists at diagnostic manufacturers, and hospital procurement managers at integrated delivery networks. Primary fieldwork with oncology reference laboratory executives and payer access specialists validated secondary findings on reimbursement trajectory and competitive positioning. Bottom-up testing volume estimates from hospital system data and top-down market sizing from instrument placement records were triangulated to constrain forecast variance.
Variance decomposition across product type, technology platform, end-user channel, and application segments shaped the analytical framework over the projection horizon. Modeled dimensions included detection sensitivity tiers, workflow automation levels, and regional regulatory cluster adoption patterns. CAGRs were derived from segment-level volume trajectories and pricing elasticity assumptions informed by consumable contract structures. Forecast inputs incorporated companion diagnostic pipeline advancement timelines and liquid biopsy reimbursement coverage expansion curves.
Material uncertainties — Medicare contractor determination reversals, EMA notified body certification delays, and pre-analytical variable control failures in community hospital settings — sit outside the modeled envelope. Forecasts reflect assumptions regarding clinical evidence accumulation and payer policy evolution that could shift materially with regulatory guidance updates. Recalibration cycles align with material shifts in FDA companion diagnostic mandates and national reimbursement authority benefit assessments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
Circulating Biomarkers Market
Clinical Diagnostics
Latin America Melanoma Diagnostics and Therapeutics Market
Clinical Diagnostics
Mitochondrial Myopathy Diagnosis and Treatment Market
Clinical Diagnostics
Global Cardiac Biomarkers Testing Market
Clinical Diagnostics
Clinical Microbiology Market
Clinical Diagnostics
Global Nasopharyngeal Swab Market
Clinical Diagnostics
Lupus Anticoagulant Testing Market
Clinical Diagnostics
Global Cervical Cancer Diagnostics and Therapeutics Market
Clinical Diagnostics
Bone Metabolism Test Market
Clinical Diagnostics
Clinical Refractometer Market
Clinical Diagnostics
Cytomegalovirus Assay Market
Clinical Diagnostics
Global Colorectal Cancer Diagnostics and Therapeutics Market
Clinical Diagnostics
Lactate Dehydrogenase Test Market
Clinical Diagnostics
US Clinical Chemistry Analyzer Market
Clinical Diagnostics
Global Allergy Diagnostics and Therapeutics Market
Clinical Diagnostics
Global Monocyte Activation Tests Market