
 Artificial Intelligence in Cancer Diagnostics Market | 2026-2036
Artificial Intelligence in Cancer Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Intelligence in Cancer Diagnostics Market Analytics
The EU AI Act is broadening compliance requirements for clinical decision-support software across European oncology networks. Siemens Healthineers AG leverages its imaging installed base to integrate AI workflows directly into radiology operations. PathAI anchors its position in digital pathology through specialized contract research partnerships with pharmaceutical developers. GE HealthCare competes by embedding AI analytics into its ultrasound and molecular imaging platforms.
Artificial intelligence in cancer diagnostics encompasses computational systems that analyze medical images, genomic sequences, and clinical records to identify malignant patterns, quantify tumor characteristics, and recommend treatment protocols with diagnostic accuracy rates exceeding 90% in validated cohorts. Deep learning algorithms process whole-slide pathology images to detect cellular anomalies invisible to human pathologists, while natural language processing extracts structured cancer staging data from unstructured electronic health records. Software solutions command the dominant share of commercial deployments due to lower capital requirements and faster update cycles, whereas integrated platforms capture premium pricing by combining hardware, algorithms, and cloud infrastructure into single-vendor contracts. Hospitals represent the most mature end-user segment with established procurement committees, though oncology clinics are expanding fastest as precision medicine programs decentralize diagnostic capabilities.
FDA premarket review pathways and EU MDR conformity assessments determine market access timelines for AI diagnostic devices, with both regulators intensifying scrutiny of algorithm training data diversity and clinical validation protocols. ISO 13485 quality management certification and IEC 62304 software lifecycle standards form baseline requirements for vendor participation in regulated markets. Stakeholders must monitor evolving reimbursement codes for algorithm-specific professional fees and hospital outpatient payments.
Market Dynamics
Deep learning architectures trained on multi-modal oncology datasets are compressing diagnostic timelines from weeks to hours, forcing hospitals to restructure pathology departments around algorithm-assisted workflows rather than conventional histology review.
Growth Catalysts
- FDA breakthrough device designation pathway:Accelerated premarket review timelines for AI diagnostic algorithms are compressing commercialization cycles for vendors targeting the United States oncology market.
- Diagnostic laboratories:High-throughput pathology operations in Germany and Japan are deploying AI-powered whole-slide analysis to manage rising cancer screening volumes without proportional staffing increases.
- Foundation models:Self-supervised learning architectures trained on unlabeled medical images are reducing dependence on scarce annotated datasets across European oncology networks.
Market Restraints
- GPU compute costs:Training and inference workloads for pathology foundation models require sustained access to NVIDIA H100 clusters, concentrating vendor capabilities among capitalized players.
- Training data diversity gaps:Algorithm validation cohorts skew toward academic medical centers in wealthy geographies, limiting generalizability to community hospital populations.
- EU MDR conformity assessment backlog:Notified body capacity constraints are extending CE marking timelines for clinical decision-support software beyond 18 months.
Strategic Opportunities
- Rural oncology clinics:Telepathology platforms combining cloud-based AI inference with low-cost digital slide scanners are penetrating underserved regions in India and Brazil.
- EU AI Act compliance services:Third-party auditing and risk management tooling for high-risk medical AI systems represent an emerging revenue layer adjacent to core diagnostics.
- Multimodal fusion architectures:Integration of radiology, pathology, and genomic data streams is enabling synthetic biomarker discovery beyond single-modality detection.
Industry Challenges
- Computational pathology talent scarcity:Dual expertise in deep learning and histopathology remains concentrated at MIT, Stanford, and select European research hospitals.
- Legacy PACS integration friction:Hospital information systems built on DICOM standards predating AI workflows require expensive middleware development for seamless algorithm deployment.
- Algorithm update validation protocols:Continuous learning systems face regulatory uncertainty regarding what constitutes a substantial change requiring new premarket submission.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Intelligence in Cancer Diagnostics Market |
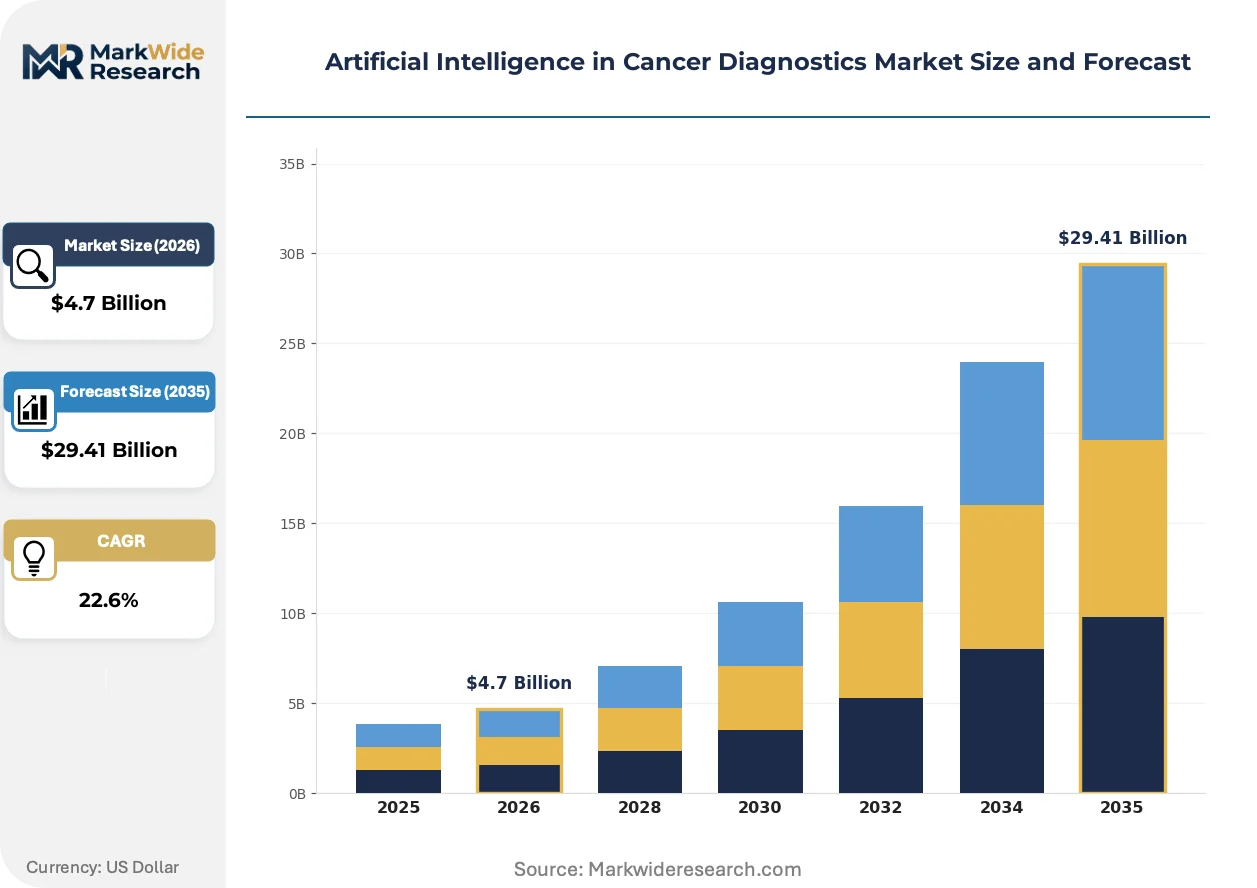
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $29.41 Billion |
| CAGR (2026 – 2036) | 22.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Machine Learning, Deep Learning, Natural Language Processing, Computer Vision End User: Hospitals, Diagnostic Laboratories, Research Institutions, Oncology Clinics Application: Image Analysis, Biomarker Discovery, Genetic Testing, Treatment Planning Solution: Software, Integrated Platforms, Cloud-Based Solutions, Mobile Applications |
| Companies Covered | PathAI, Paige AI Inc., Tempus AI, Inc., iCAD, Inc., Siemens Healthineers AG, GE HealthCare, ibex-ai, Lunit Inc., Aidoc Medical, Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Intelligence in Cancer Diagnostics Market Evolving Landscape
Generative AI architectures are moving from research curiosity to clinical deployment, with diffusion models now synthesizing histological images for rare cancer subtype augmentation and transformer-based systems extracting structured oncology data from unstructured clinical narratives.
Vision transformers processing gigapixel pathology slides are overtaking convolutional neural networks as the dominant architecture in academic and commercial laboratories. Major cancer centers in the United States and Germany are retraining their screening pipelines on Swin Transformer backbones. This shift is overtaking vendor roadmaps that had standardized on ResNet-derived architectures, compressing model development cycles and enabling self-attention mechanisms that localize cellular anomalies across tissue contexts.
The EU AI Act's risk classification framework for medical devices is mandating conformity assessments for clinical decision-support software that previously operated under lighter-touch medical device regulation. European oncology networks must now document algorithm training data provenance and post-market monitoring protocols. Germany's university hospitals are responding by establishing centralized AI governance committees that pre-validate vendor submissions before procurement.
Oncology clinics are consolidating diagnostic procurement around integrated platform contracts that bundle hardware, algorithms, and cloud infrastructure from single vendors. Community hospitals in Japan and the United States are displacing point-solution purchasing that required internal IT integration. This consolidation is most visible in precision medicine programs where pathologists require seamless workflows spanning molecular profiling and digital pathology without multi-vendor troubleshooting.
Artificial Intelligence in Cancer Diagnostics Market Segmentation
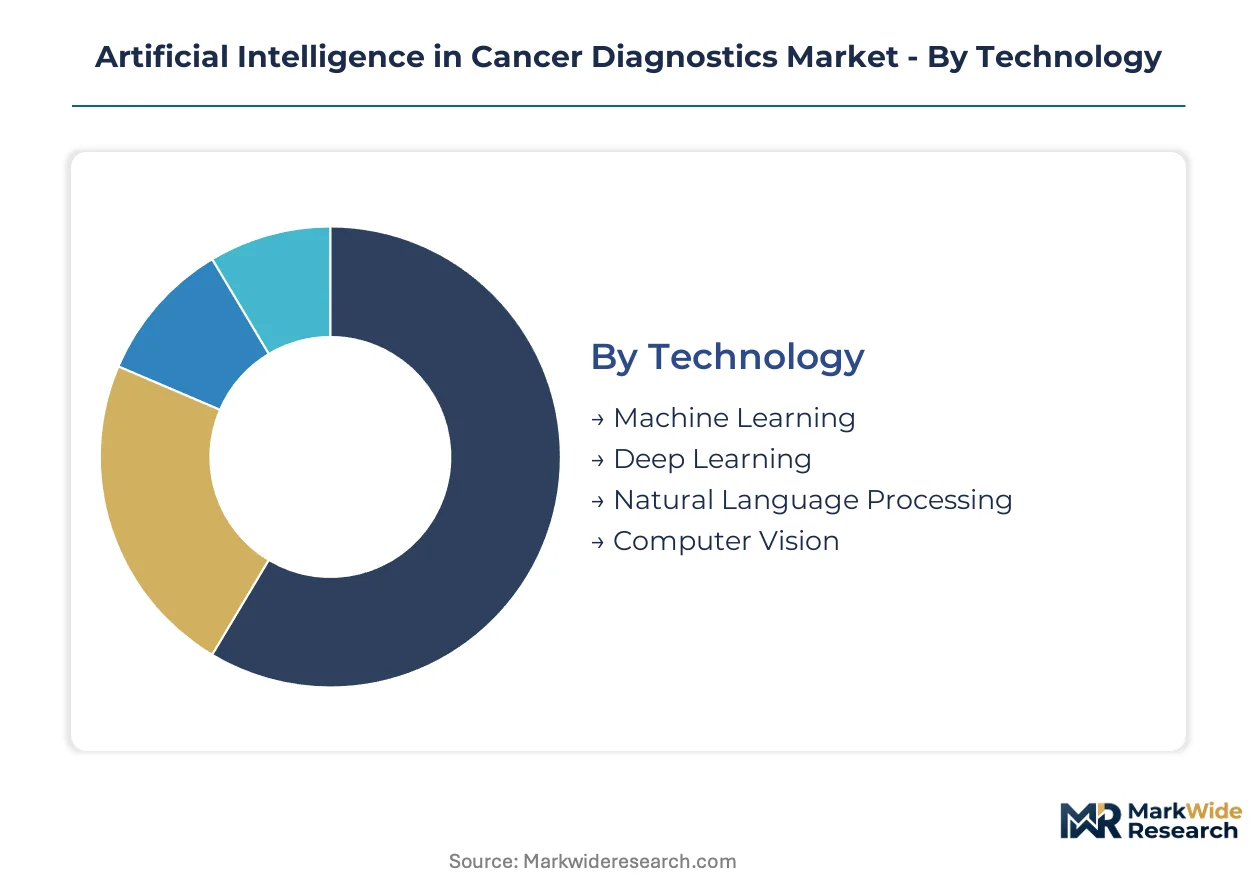
AI cancer diagnostics vendors structure their portfolios across four distinct axes that determine deployment complexity, regulatory pathway, and customer procurement behavior. Each segmentation layer reveals divergent margin profiles and technology readiness levels that shape commercial strategy.
Technology:
Computational architectures define algorithmic capability boundaries and hardware dependencies.
- Machine Learning:Traditional supervised learning models process structured clinical data for risk stratification and outcome prediction. Demand concentrates in community hospitals across the United States seeking interpretable, lower-compute diagnostic support without specialized GPU infrastructure.
- Deep Learning:Neural network architectures with multiple hidden layers extract hierarchical features from medical images and genomic sequences. Academic medical centers in Germany and Japan deploy these systems for whole-slide pathology analysis where pattern complexity exceeds human visual processing limits.
- Natural Language Processing:Text mining algorithms extract structured oncology staging data from unstructured electronic health records and clinical narratives. EHR vendors integrate these modules to automate cancer registry reporting and clinical trial matching.
- Computer Vision:Image processing pipelines localize cellular anomalies and quantify tumor microenvironment characteristics. Radiology departments embed these algorithms directly into PACS workstations for real-time lesion detection.
Deep learning leads on scale; natural language processing leads on momentum.
End User:
Procurement authority and workflow integration requirements vary sharply across institutional types.
- Hospitals:Integrated health systems with established value analysis committees negotiate enterprise-wide AI contracts spanning radiology, pathology, and oncology departments. These deployments require extensive IT security review and EHR integration.
- Diagnostic Laboratories:High-throughput reference labs prioritize batch processing efficiency and regulatory compliance for CLIA-certified operations. Cloud-based AI inference reduces capital expenditure while maintaining analytical throughput.
- Research Institutions:National cancer centers and university hospitals drive algorithm development through annotated dataset curation and clinical validation studies. Their procurement emphasizes customization flexibility over standardized workflows.
- Oncology Clinics:Community-based precision medicine programs seek point-of-care decision support with minimal infrastructure footprint. Telepathology partnerships enable these sites to access specialist-level diagnostics without on-site pathologists.
Hospitals lead on scale; oncology clinics lead on momentum.
Application:
Clinical use case determines regulatory classification and reimbursement eligibility.
- Image Analysis:Automated detection and quantification of malignant patterns in radiology and pathology images. FDA breakthrough device designations have concentrated in this segment for lung, breast, and prostate cancer screening applications.
- Biomarker Discovery:AI-driven identification of novel therapeutic targets and predictive signatures from multi-omic datasets. Pharmaceutical developers contract specialized vendors for companion diagnostic development.
- Genetic Testing:Variant interpretation algorithms classify germline and somatic mutations for hereditary cancer risk and treatment selection. Clinical laboratories deploy these tools to scale molecular pathology operations.
- Treatment Planning:Radiation oncology and surgical planning systems optimize therapeutic targeting based on tumor segmentation and organ-at-risk delineation. These applications require extensive clinical validation for safety-critical deployment.
Image analysis leads on scale; biomarker discovery leads on momentum.
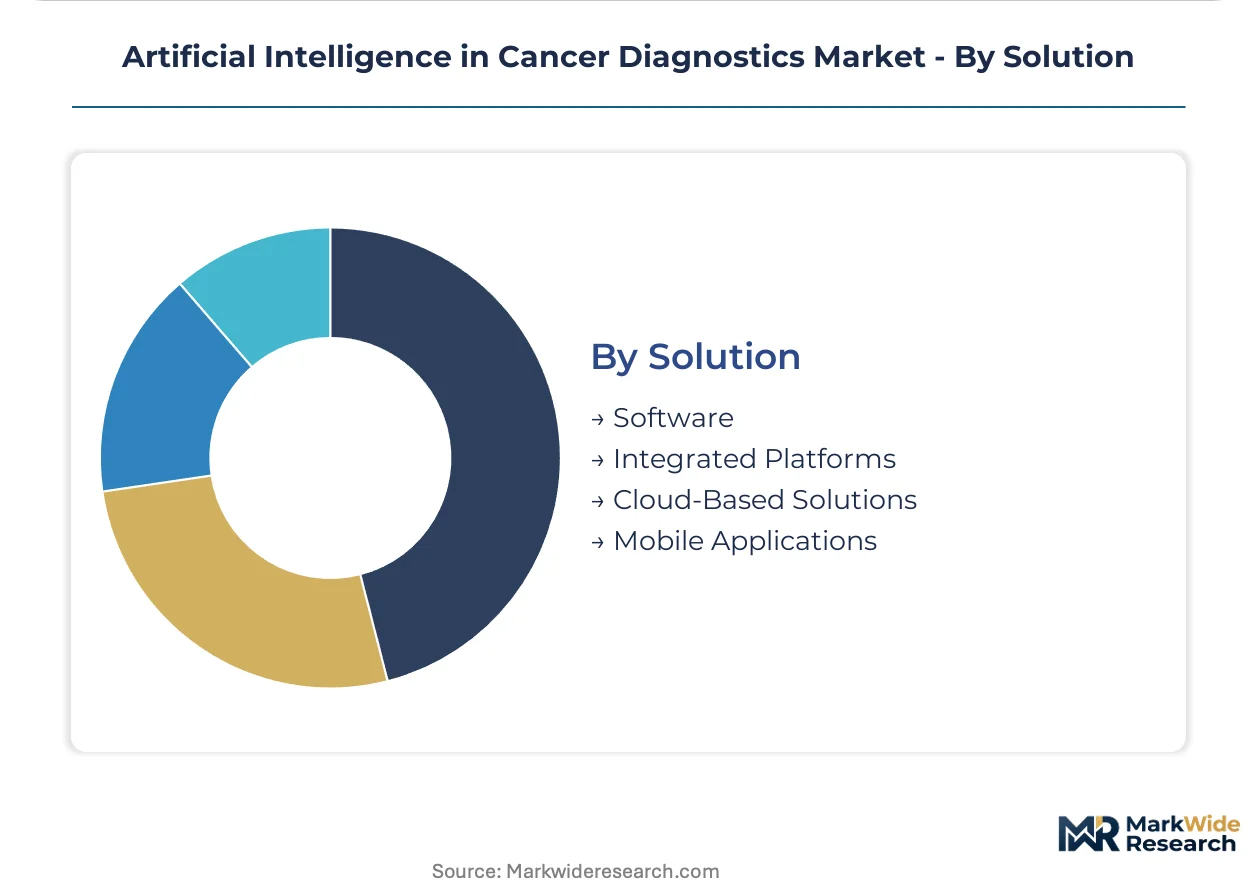
Solution:
Delivery model shapes customer total cost of ownership and vendor revenue recognition patterns.
- Software:Standalone algorithm licenses deployed on customer infrastructure or virtualized environments. Lower capital barriers accelerate adoption among budget-constrained institutions seeking targeted diagnostic capabilities.
- Integrated Platforms:Bundled hardware, software, and cloud infrastructure contracts from single vendors. Japan's university hospitals favor these arrangements to minimize multi-vendor integration complexity and establish unified support accountability.
- Cloud-Based Solutions:SaaS delivery models with consumption-based pricing and automatic algorithm updates. Diagnostic laboratories leverage these offerings to scale computational resources dynamically with screening volume fluctuations.
- Mobile Applications:Point-of-care tools for image capture and preliminary analysis in resource-limited settings. Rural oncology networks in India deploy these solutions with low-cost digital slide scanners for telepathology consultation.
Software leads on scale; cloud-based solutions lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The artificial intelligence in cancer diagnostics industry traces its commercial origins to academic medical centers in the United States and Germany, where early deep learning pathology validation studies established the clinical credibility that later attracted venture investment and regulatory engagement.
United States
FDA breakthrough device designations for AI-powered oncology algorithms have compressed commercialization timelines, while Medicare reimbursement pilots for algorithm-assisted pathology review are expanding hospital procurement budgets. The FDA's intensified scrutiny of training data diversity is reshaping vendor submission strategies. Major cancer centers in Boston and Houston are retraining screening pipelines on vision transformer architectures.
Germany
University hospitals in Bavaria and Baden-Württemberg are establishing centralized AI governance committees that pre-validate vendor submissions before procurement, responding to EU AI Act risk classification requirements. The EU MDR conformity assessment backlog is extending CE marking timelines beyond eighteen months for clinical decision-support software. Siemens Healthineers leverages its imaging installed base in Mannheim and Erlangen to integrate AI workflows directly into radiology operations.
Japan
Community hospitals in the Kanto and Kansai regions are consolidating diagnostic procurement around integrated platform contracts that bundle hardware, algorithms, and cloud infrastructure from single vendors. METI funding for precision medicine infrastructure is accelerating oncology clinic decentralization. Pathology foundation model development concentrates at national cancer centers in Tokyo and Osaka.
United Kingdom
NHS England's AI diagnostic procurement frameworks are streamlining vendor access to hospital networks, though post-Brexit regulatory divergence from EU MDR is creating dual compliance burdens for commercialization. London's academic medical centers are driving multimodal fusion research combining radiology, pathology, and genomic data streams. Manchester and Birmingham health systems are deploying cloud-based AI inference for batch processing efficiency.
India
Rural oncology networks in Maharashtra and Karnataka are penetrating underserved regions through telepathology platforms combining cloud-based AI inference with low-cost digital slide scanners. CDSCO regulatory pathways for software-as-medical-device are stabilizing as the national pharmaceutical regulator gains capacity. Hyderabad and Bangalore are emerging as contract research hubs for pharmaceutical developers seeking companion diagnostic development partnerships.
Artificial Intelligence in Cancer Diagnostics Market Competitive Landscape
Capital-heavy integrated platform vendors compete with asset-light algorithm developers for procurement contracts across hospital networks and diagnostic laboratories. The vendor base stratifies between imaging equipment incumbents with installed base advantages and specialized AI-native firms with research hospital partnerships. Three strategic archetypes dominate: imaging hardware-software bundlers, pathology-focused algorithm specialists, and multi-omic data platform operators. Competitive intensity centers on strategic partnerships with pharmaceutical developers for companion diagnostic co-development and geographic expansion through telepathology distribution networks.
Within the imaging-integrated tier, Siemens Healthineers AG and GE HealthCare exemplify capital-intensive platform strategies that embed AI analytics directly into radiology and molecular imaging hardware. Among AI-native specialists, PathAI and Paige AI Inc. occupy positions defined by digital pathology concentration and contract research partnerships with oncology drug developers. Tempus AI, Inc. anchors the multi-omic data fusion archetype, representing vendors that integrate genomic sequencing with clinical and imaging data streams for precision medicine applications.
| Leading Market Players |
|---|
| PathAI |
| Paige AI Inc. |
| Tempus AI, Inc. |
| iCAD, Inc. |
| Siemens Healthineers AG |
| GE HealthCare |
| ibex-ai |
| Lunit Inc. |
| Aidoc Medical, Ltd |
| Others |
Value Network & Pricing Analysis
Computational pathology specialists concentrated in Boston and the San Francisco Bay Area command salary premiums exceeding general software engineering roles, compressing margins for algorithm developers and forcing pricing stratification across premium, standard, and economy tiers based on vendor R&D location and talent access costs.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs AI cancer diagnostics procurement, with FDA breakthrough device designation and CE marking under EU MDR serving as tier-separating certification gates. Premium tiers bundle continuous algorithm updates and dedicated clinical support, while economy offerings target community hospitals with frozen-model licenses. Cost compression in the standard tier is intensifying because GPU compute contracts with NVIDIA H100 clusters consume disproportionate vendor operating budgets. Diagnostic laboratories exhibit highest price sensitivity due to volume-based procurement frameworks, whereas academic medical centers prioritize performance benchmarks over unit economics.
Supply Chain Analysis
Dual-sourcing requirements for GPU accelerators are becoming standard in vendor procurement policies, with NVIDIA H100 and AMD MI300X clusters both qualified for pathology foundation model training workloads. Hardware supply concentrates in Taiwan, South Korea, and the United States, while cloud infrastructure draws from hyperscaler regions in Frankfurt, Tokyo, and Northern Virginia. Single-source vulnerability in advanced semiconductor lithography creates exposure to export control adjustments. Distribution runs through direct enterprise sales teams for integrated platforms and channel partners for standalone software licenses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA breakthrough device designations and EU AI Act risk classifications are compounding regulatory validation into a demand accelerant, with reimbursement code establishment for algorithm-assisted pathology review serving as the pivotal milestone reshaping hospital procurement budgets.
For Market Incumbents: To counter foundation model commoditization from well-capitalized cloud providers, embed proprietary histopathology datasets into continuously learning architectures and secure exclusive whole-slide scanning partnerships with Germany's university hospital networks. Backward integration into low-cost digital slide scanner manufacturing secures margin protection against hardware-software unbundling. For New Entrants and Emerging Players: Begin with telepathology distribution partnerships in Maharashtra and Karnataka, where rural oncology clinic density exceeds specialist pathologist supply. White-space concentration in cloud-based AI inference for batch processing offers the most penetrable entry vector. Pursue CDSCO software-as-medical-device registration to establish regulatory credibility for subsequent geographic expansion. For Investors and Strategic Acquirers: Pharmaceutical developers seeking companion diagnostic co-development capabilities are the most active acquirer in this space, driving valuation premiums for vendors with validated multi-omic data fusion platforms. Acquisition targets should demonstrate FDA premarket review experience and at least one deployed hospital system integration. Watch for EU MDR notified body capacity expansion as the signal indicating accelerated CE marking timelines and compressed regulatory risk premiums.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerated premarket review compresses commercialization timelines for United States oncology market entry. |
| EU AI Act Conformity Assessment | Third-party auditing requirements create adjacent revenue layers for compliance service providers. |
| Hospital System Partnership | Enterprise-wide contracts spanning radiology, pathology, and oncology departments lock out point-solution competitors. |
| Pharmaceutical Companion Diagnostic Co-development | Specialized contract research partnerships with drug developers anchor long-term revenue visibility. |
| Telepathology Platform Expansion | Cloud-based AI inference combined with low-cost scanners penetrates underserved rural oncology networks. |
Research Methodology
Multiple input streams — primary interviews with hospital purchasing committees, biomedical engineers, and GPO contracts managers; secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, and hospital procurement records; and tertiary cross-checks through EMA submissions and clinical validation publications — were reconciled through bottom-up and top-down triangulation to construct market estimates.
Data-stream reconciliation across technology deployment models, end-user institution types, clinical application areas, and geographic regulatory clusters informed the analytical framework over the projection horizon. CAGRs were derived from segmented growth trajectory modeling incorporating algorithm validation timeline compression, reimbursement code expansion rates, and cloud infrastructure capacity buildouts as cancer-specific forecast inputs.
Several conditions sit outside the modeled scope, including sudden FDA enforcement shifts on continuous learning system update protocols and unanticipated EU MDR notified body capacity constraints. Forecasts reflect documented assumptions regarding reimbursement framework evolution and training data diversity standardization. Deviation in GPU semiconductor export control enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
Clinical Diagnostic Equipment Market
Clinical Diagnostics
Clinical Trial Kits Market
Clinical Diagnostics
Angiogenesis Assays Market
Clinical Diagnostics
Global Colorectal Cancer Diagnostics Market
Clinical Diagnostics
Global Electronic Clinical Outcome Assessment Solutions Market
Clinical Diagnostics
Global Clinical Chemistry Analyzers Market
Clinical Diagnostics
Herpes Marker Testing Market
Clinical Diagnostics
Chromosomal Aberration Test Market
Clinical Diagnostics
H. Pylori (Helicobacter Pylori) Test Market
Clinical Diagnostics
Kidney Function Tests Market
Clinical Diagnostics
Bacterial and Viral Specimen Collection Market
Clinical Diagnostics
Clinical Chemistry Market
Clinical Diagnostics
Colorectal Cancer Molecular Diagnostics Market
Clinical Diagnostics
Immune Response Testing Market
Clinical Diagnostics
Global Respiratory Disease Testing Market
Clinical Diagnostics
Circulating Biomarkers Market