
 Chronic Hepatitis B Virus Testing Market | 2026-2036
Chronic Hepatitis B Virus Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Chronic Hepatitis B Virus Testing Market Outlook
Premium molecular testing platforms and commodity serological assays is rebalancing as health systems prioritize viral load quantification over basic surface antigen screening. Roche dominates automated PCR workflows through integrated sample-to-answer architectures. Abbott Laboratories leverages its established immunoassay installed base to sustain recurring revenue in high-throughput hospital laboratories. Siemens Healthineers anchors its position through hybrid platforms that bridge ELISA and molecular modalities.
Chronic Hepatitis B virus testing encompasses laboratory and point-of-care diagnostic methods that detect HBV surface antigen, e-antigen, antibodies, or viral nucleic acid in human blood, serum, or plasma specimens, typically achieving PCR sensitivity thresholds of 10–20 IU/mL for molecular confirmation. These tests serve the clinical imperative of identifying active infection, guiding antiviral therapy selection, and monitoring treatment response in chronically infected patients. Molecular tests capture expanding margin pools as laboratories convert from qualitative to quantitative viral load surveillance. Diagnostic laboratories represent the fastest-growing end-user channel as centralized reference networks absorb testing volume from smaller clinics. Automated systems technology is displacing manual ELISA workflows in markets where labor costs and throughput demands converge.
The FDA's Class II device controls and the EU's In Vitro Diagnostic Regulation shape product registration pathways and post-market surveillance obligations for manufacturers seeking access to major markets. China's NMPA enforces domestic clinical trial requirements for imported nucleic acid test kits, creating asymmetric market access timelines between local and foreign suppliers. India's CDSCO has aligned hepatitis B test kit standards with WHO prequalification criteria, streamlining procurement for public health programs. Stakeholders must monitor how decentralized rapid testing protocols redefine channel economics between hospital laboratories and community-based screening programs.
Market Dynamics
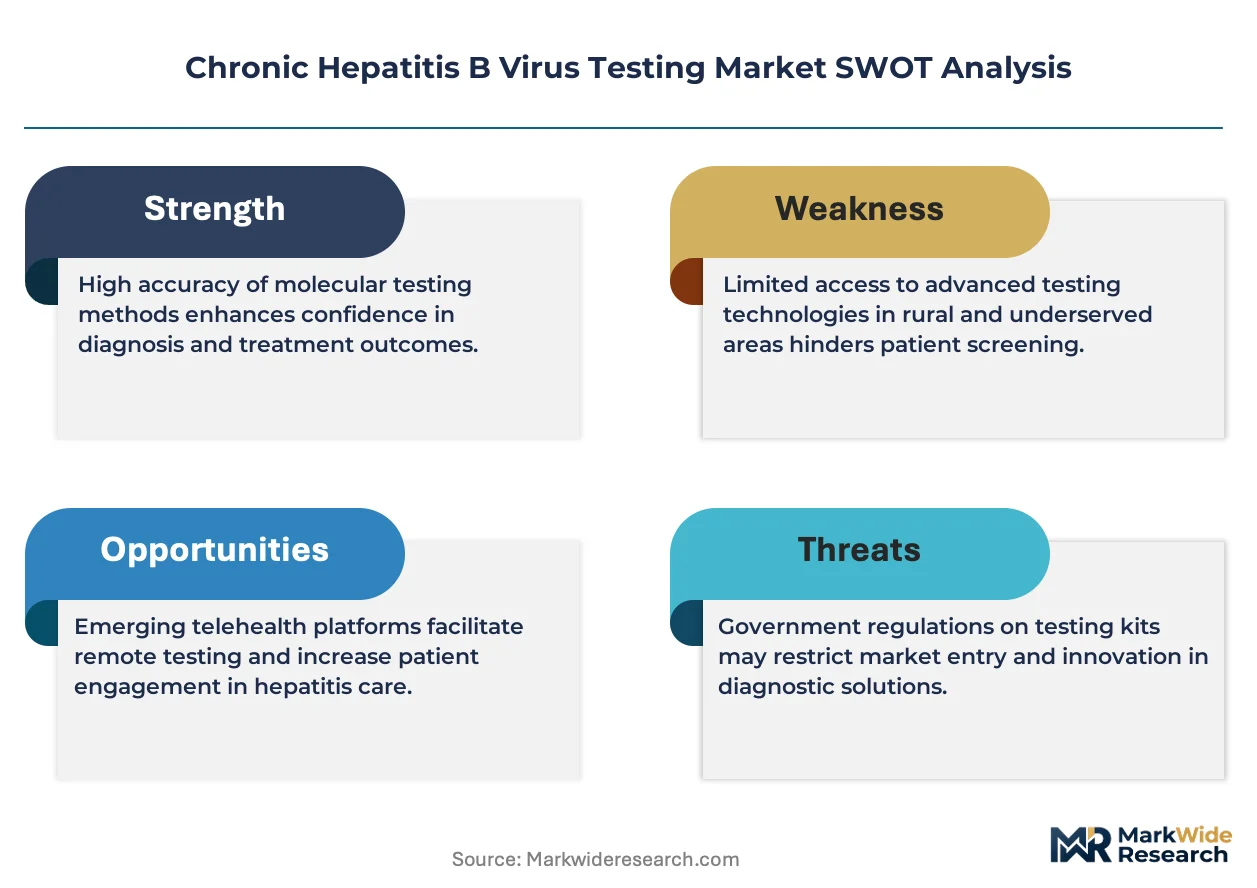
China's NMPA nucleic acid test kit registration tightening is forcing diagnostic manufacturers to rebuild clinical evidence packages, compressing market access timelines for foreign suppliers while domestic laboratories accelerate automated PCR platform procurement.
Growth Catalysts
- Automated PCR platform deployment:Diagnostic laboratories in East Asia are converting manual ELISA workflows to integrated sample-to-answer architectures, absorbing higher throughput with reduced labor inputs.
- Viral load quantification prioritization:Health systems are rebalancing test menus toward quantitative molecular surveillance over qualitative surface antigen screening, expanding reimbursement pools for nucleic acid testing.
- Centralized reference network expansion:Tier-one hospital networks in China are consolidating testing volume from smaller clinics into high-throughput diagnostic laboratories with dedicated molecular pathology capacity.
Market Restraints
- Domestic clinical trial mandates:China's NMPA requires in-country studies for imported nucleic acid test kits, creating asymmetric registration timelines that disadvantage foreign suppliers against local manufacturers.
- Reagent cost volatility:Polymerase and probe chemistries face supply concentration from specialized biochemical producers, squeezing margin structures for high-volume test kit assemblers.
- Manual ELISA infrastructure lock-in:Hospital laboratories with sunk capital in serological platforms resist full workflow conversion despite molecular sensitivity advantages.
Strategic Opportunities
- Point-of-care molecular miniaturization:Chip-based amplification technologies are penetrating community-based screening programs where centralized laboratory access remains limited.
- India's CDSCO-WHO alignment:Streamlined prequalification criteria for hepatitis B test kits accelerate public health procurement cycles, opening volume contracts for compliant suppliers.
- Hybrid platform convergence:ELISA-molecular bridge instruments enable laboratories to phase capital deployment while maintaining test menu breadth during transition periods.
Industry Challenges
- Molecular diagnostics specialist scarcity:Laboratory systems face recruitment gaps for PCR technologists and nucleic acid quality control personnel, constraining platform utilization rates.
- IVDR compliance documentation burden:European manufacturers must rebuild technical files under MDR requirements for Class C devices, extending certification timelines and legal holdback costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chronic Hepatitis B Virus Testing Market |
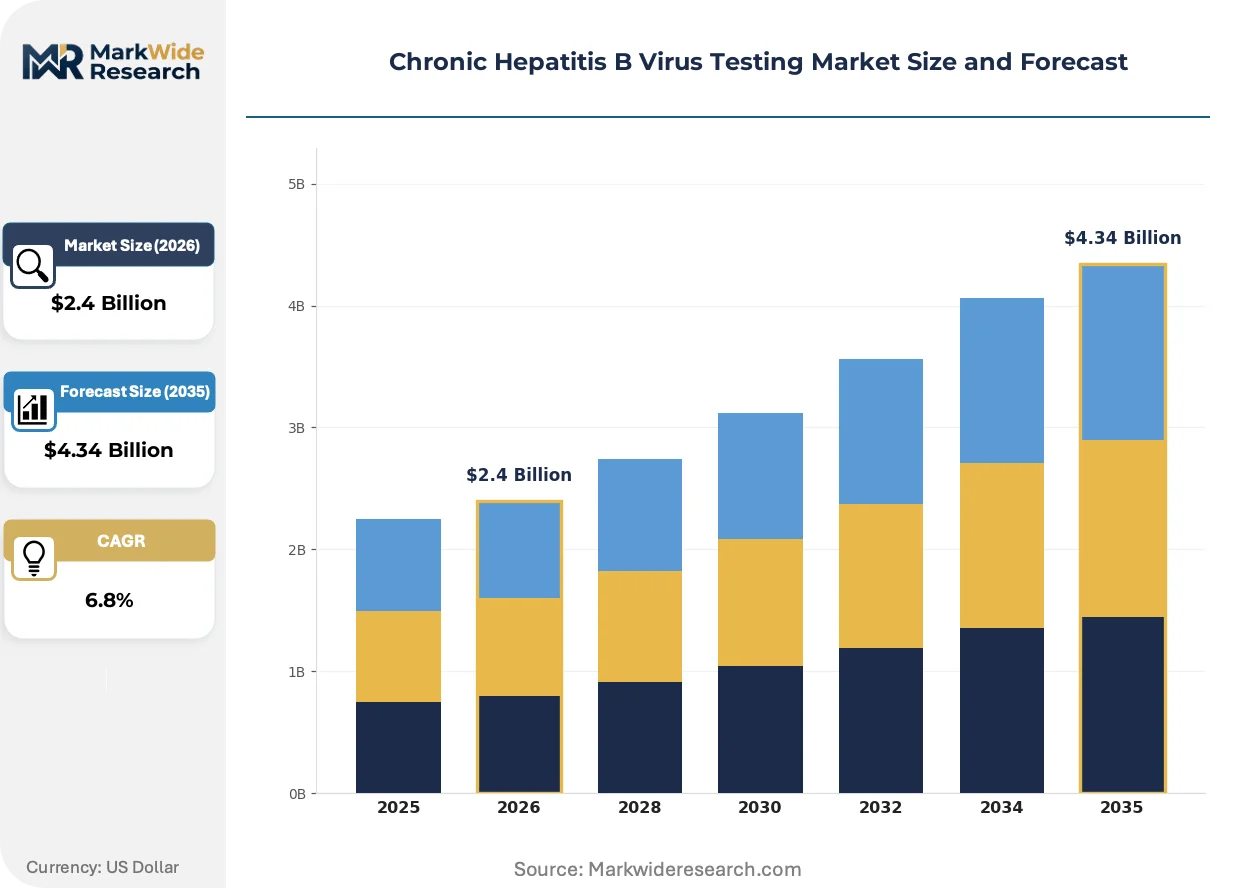
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Serological Tests, Molecular Tests, Viral Load Tests, Liver Function Tests End User: Clinics, Hospitals, Diagnostic Laboratories, Research Institutions Technology: ELISA, PCR, Rapid Testing, Automated Systems Sample Type: Blood Samples, Liver Biopsies, Serum Samples, Plasma Samples |
| Companies Covered | DiaSorin S.p.A., Siemens Healthineers AG, Roche, bioMérieux SA, Becton Dickinson and Company, Abbott Laboratories, Meridian Bioscience, Avantor, Bio-Rad Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chronic Hepatitis B Virus Testing Market Strategic Shifts
Digital PCR and isothermal amplification methods are fragmenting the molecular testing landscape, creating tiered performance segments that match sensitivity specifications to clinical use cases rather than defaulting to centralized laboratory gold standards.
Next-generation sequencing-based viral load quantification is expanding into reference laboratory workflows, enabling simultaneous resistance mutation profiling alongside titer measurement. Academic medical centers in Japan and South Korea are piloting these platforms for complex case management. The technology is expanding into reimbursement frameworks previously reserved for quantitative PCR, forcing payers to recalibrate coverage algorithms.
The EU's In Vitro Diagnostic Regulation (IVDR) is tightening post-market surveillance and performance evaluation requirements for hepatitis B nucleic acid test kits, elevating clinical evidence thresholds above prior directive standards. Manufacturers must now submit periodic safety update reports and maintain vigilance systems for Class C devices. Medium-scale European diagnostic companies are responding by narrowing product portfolios to focus resources on highest-volume assays.
Diagnostic procurement in China's tier-one hospital networks is consolidating under centralized purchasing alliances that negotiate multi-year reagent supply contracts with locked pricing tiers. Independent laboratories and smaller hospital systems are being absorbed into these purchasing cooperatives, compressing vendor negotiation leverage. This concentration is most visible in Beijing and Shanghai metropolitan clusters where provincial health commissions mandate participation in unified procurement platforms.
Chronic Hepatitis B Virus Testing Market Segmentation
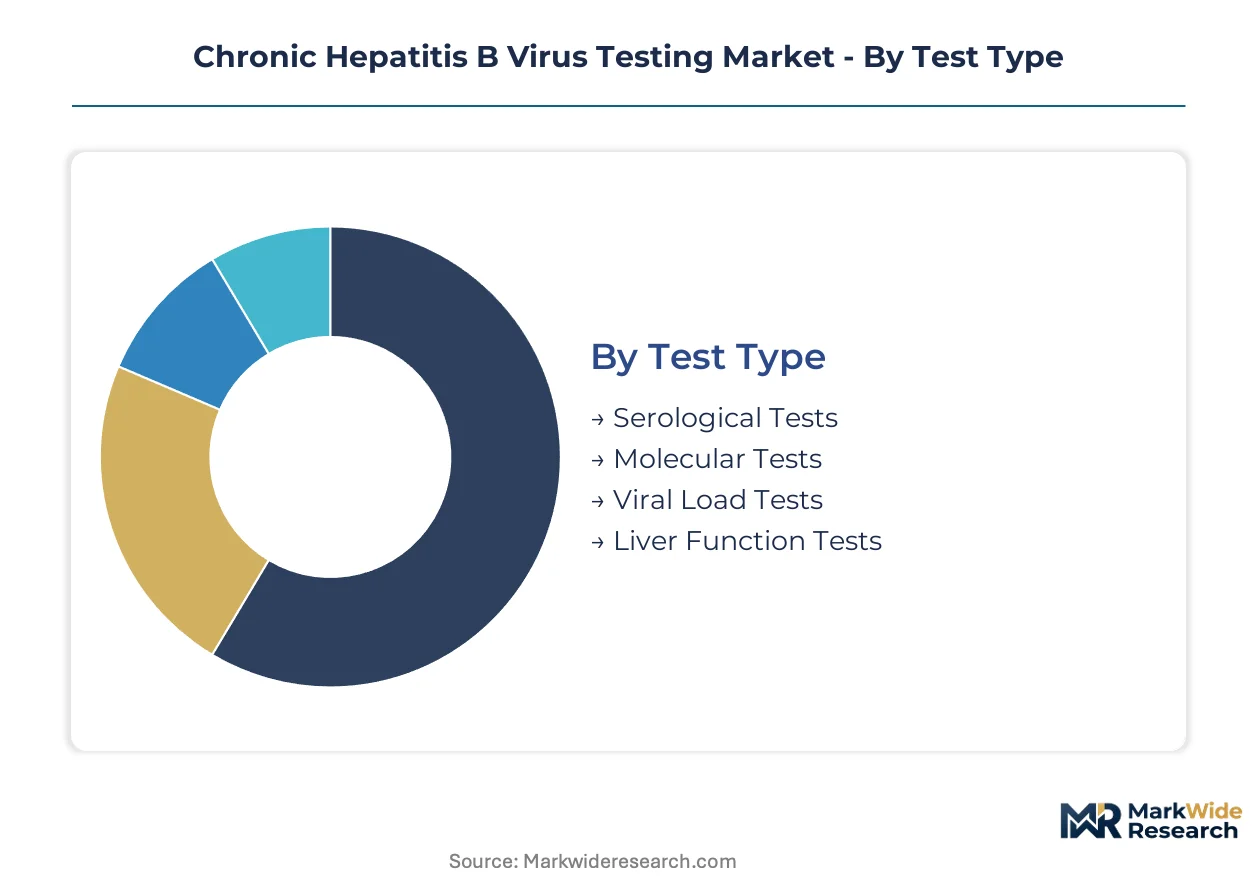
Test type and technology configurations determine whether laboratories deploy standalone instruments or integrated platforms. End-user scale and sample processing requirements further shape procurement patterns across health systems.
Test Type:
Standalone serological assays operate independently in resource-limited settings, while molecular and viral load platforms embed into automated laboratory workflows requiring specialized infrastructure.
- Serological Tests:Surface antigen and antibody detection assays run on conventional immunoassay analyzers without nucleic acid extraction steps. China's tier-one hospital networks still process high volumes for initial screening, though reimbursement pressure favors molecular confirmation.
- Molecular Tests:PCR-based nucleic acid detection achieves 10–20 IU/mL sensitivity thresholds essential for treatment monitoring. Diagnostic laboratories in Beijing and Shanghai metropolitan clusters are absorbing these volumes from smaller clinics under centralized procurement alliances.
- Viral Load Tests:Quantitative assays guide antiviral therapy selection and response assessment. Demand concentrates where hepatitis B management protocols require precise titer measurement.
- Liver Function Tests:Biochemical panels assess hepatic injury severity alongside virological markers. These integrate into broader hepatology diagnostic workups rather than standalone HBV-specific protocols.
Serological tests lead volumes today; molecular tests are gaining share fastest.
End User:
High-throughput diagnostic laboratories command premium automated systems, while clinics and smaller hospitals operate cost-optimized manual platforms with lower capital barriers.
- Clinics:Community-based screening programs rely on rapid point-of-care devices where laboratory access remains limited. India's CDSCO-WHO alignment is streamlining procurement for these settings.
- Hospitals:Inpatient and outpatient departments balance serological screening with molecular confirmation based on case complexity. Tier-one networks in China consolidate testing into dedicated molecular pathology units.
- Diagnostic Laboratories:Centralized reference networks absorb volume from smaller facilities, deploying integrated sample-to-answer architectures with reduced labor inputs. East Asian markets show the steepest expansion trajectory for this channel.
- Research Institutions:Academic medical centers pilot next-generation sequencing for resistance mutation profiling alongside viral load quantification.
Diagnostic laboratories command the steepest volume climb; hospitals retain the largest installed base.
Technology:
Manual ELISA workflows persist where capital constraints outweigh throughput demands, while PCR and automated systems capture laboratories with sufficient specimen volume to justify platform investment.
- ELISA:Enzyme-linked immunosorbent assays detect surface antigen and e-antigen through colorimetric endpoints. Sunk capital in serological infrastructure resists full conversion despite molecular sensitivity advantages.
- PCR:Polymerase chain reaction achieves quantitative viral load surveillance with superior analytical sensitivity. China's NMPA tightened registration requirements, forcing manufacturers to rebuild clinical evidence packages.
- Rapid Testing:Lateral flow and immunochromatographic devices enable point-of-care screening without laboratory infrastructure. Chip-based amplification miniaturization is penetrating community programs.
- Automated Systems:Integrated sample-to-answer platforms consolidate nucleic acid extraction, amplification, and detection. Labor cost and throughput convergence in East Asia accelerates displacement of manual workflows.
PCR anchors current revenue; automated systems show the sharpest adoption curve.
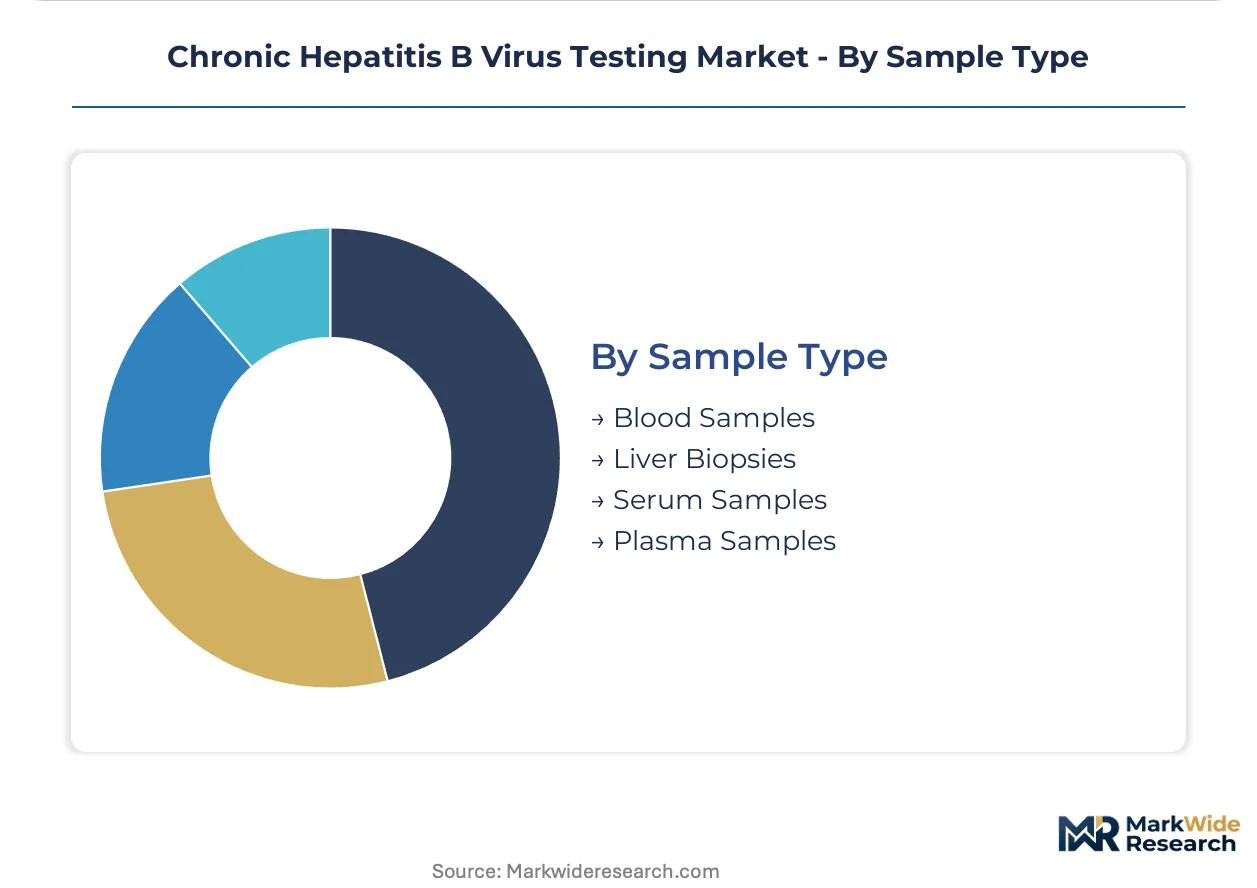
Sample Type:
Peripheral blood collection dominates routine screening, while specialized specimens serve confirmatory or research applications requiring tissue-level analysis.
- Blood Samples:Whole blood collected by venipuncture feeds both serological and molecular testing pipelines. Standardized collection protocols support high-throughput laboratory automation.
- Liver Biopsies:Tissue specimens enable histological grading of fibrosis and necroinflammatory activity. Academic medical centers in Japan deploy these for complex case management.
- Serum Samples:Clotted blood derivatives separate cellular components from circulating viral markers. Serological assays predominantly use this matrix for surface antigen detection.
- Plasma Samples:Anticoagulated blood preparations preserve nucleic acid integrity for PCR amplification. Viral load quantification protocols specify plasma to minimize degradation during processing.
Serum and plasma dominate processing volumes; liver biopsies serve niche confirmatory roles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Laboratory technologist density in East Asian metropolitan clusters anchors regional testing capacity expansion. China's tier-one hospital networks absorb molecular diagnostics volume from smaller clinics. India's CDSCO alignment with WHO prequalification criteria accelerates public health procurement cycles.
China
Beijing and Shanghai metropolitan clusters concentrate automated PCR platform deployment as provincial health commissions mandate unified procurement participation. NMPA tightened nucleic acid test kit registration requirements, forcing foreign suppliers to rebuild domestic clinical evidence packages. Tier-one hospital networks in these cities consolidate testing volume from smaller facilities into dedicated molecular pathology units.
United States
Academic medical centers pilot next-generation sequencing for resistance mutation profiling alongside viral load quantification. FDA Class II device controls shape product registration pathways and post-market surveillance obligations for manufacturers seeking market access. Laboratory networks in Boston and San Francisco absorb high-complexity testing from regional hospital systems.
India
Community-based screening programs in Maharashtra and Karnataka drive point-of-care rapid testing deployment where laboratory infrastructure remains limited. CDSCO aligned hepatitis B test kit standards with WHO prequalification criteria, streamlining procurement for national public health programs. Diagnostic laboratories in Mumbai and Bangalore expand molecular capacity through centralized reference network consolidation.
Germany
EU IVDR compliance documentation burdens extend certification timelines for Class C hepatitis B nucleic acid test kits. Medium-scale diagnostic companies respond by narrowing product portfolios to focus resources on highest-volume assays. Industrial clusters in Munich and Heidelberg host hybrid platform development bridging ELISA and molecular modalities.
Japan
Academic medical centers in Tokyo and Osaka pilot next-generation sequencing-based viral load quantification for complex case management. PMDA oversight shapes performance evaluation requirements for molecular diagnostics entering reimbursement frameworks. Kanto region laboratories displace manual ELISA workflows with integrated sample-to-answer architectures.
Chronic Hepatitis B Virus Testing Market Competitive Environment
Top-tier vendors anchor automated molecular platforms, while mid-scale specialists occupy hybrid ELISA-PCR bridge instruments. The vendor base stratifies across three functional tiers: integrated system architects, immunoassay incumbents with molecular extensions, and point-of-care miniaturization specialists. Competitive moves concentrate on automated platform procurement contracts in East Asian tier-one hospitals and IVDR technical file reconstruction for European market retention.
Among European-headquartered conglomerates, DiaSorin S.p.A., Siemens Healthineers AG, and Roche exemplify the integrated system architect archetype. Roche represents sample-to-answer automation dominance. Siemens Healthineers occupies a position bridging legacy immunoassay infrastructure with molecular modality expansion. DiaSorin S.p.A. sits within the specialty diagnostics tier focused on infectious disease assay portfolios.
| Leading Market Players |
|---|
| DiaSorin S.p.A. |
| Siemens Healthineers AG |
| Roche |
| bioMérieux SA |
| Becton Dickinson and Company |
| Abbott Laboratories |
| Meridian Bioscience |
| Avantor |
| Bio-Rad Laboratories |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap reagent specialists in Germany and Switzerland anchor polymerase supply tiers, translating concentrated biochemical production into disciplined contract pricing for test kit assemblers while tier-one hospital networks in China extract volume discounts through centralized procurement alliances.
Pricing Analysis
Bundled reagent-rental agreements dominate automated platform deployment, while unbundled per-test pricing persists in manual ELISA workflows. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared molecular assays from CE-marked alternatives and research-use-only chemistries. Pricing pressure stems from China's provincial health commissions mandating locked multi-year supply contracts with annual price step-downs. Community clinics exhibit highest price sensitivity due to capital constraints, whereas reference laboratories absorb premium instrument costs for throughput gains.
Supply Chain Analysis
Regional distribution centers in Shanghai, Singapore, and Rotterdam anchor hub-and-spoke cold-chain logistics for temperature-sensitive nucleic acid reagents. Manufacturing concentrates in China, Germany, and the United States for extraction chemistries, amplification enzymes, and detection probes respectively. Raw material dependencies center on specialized Taq polymerase formulations, fluorogenic probe syntheses, and magnetic bead separation media. Single-source vulnerability runs through Chinese suppliers of reverse transcriptase enzymes. Distribution runs through diagnostic distributor networks serving hospital systems and independent laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Chronic Hepatitis B Virus Testing Market functions as a stable compounder anchored by irreversible workflow automation in East Asian diagnostic laboratories, where labor cost convergence and throughput demands sustain replacement cycles regardless of macroeconomic volatility.
For Market Incumbents: Deepen backward integration into probe chemistry manufacturing to offset reagent cost volatility from specialized biochemical suppliers. Fortify installed base retention through extended service contracts that lock replacement timelines, countering emerging point-of-care molecular miniaturization threats from chip-based amplification specialists. For New Entrants and Emerging Players: Enter via India's CDSCO-WHO aligned procurement pathways for public health volume contracts, where streamlined prequalification accelerates market access against entrenched hospital laboratory incumbents. Target Maharashtra and Karnataka community screening programs with rapid point-of-care devices, leveraging distributor partnerships with state medical supply corporations. For Investors and Strategic Acquirers: Valuations sit cheapest among European mid-scale diagnostic companies narrowing portfolios to focus IVDR compliance resources on highest-volume hepatitis B assays. Five-to-ten year viability hinges on automated platform procurement contract renewal rates in Beijing and Shanghai metropolitan clusters. The signal to watch is NMPA registration timeline compression for domestic versus foreign nucleic acid test kit applicants.| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Technical File Reconstruction | European manufacturers must rebuild Class C device documentation under MDR requirements, extending certification timelines. |
| Automated Platform Procurement Contracts | East Asian tier-one hospital networks consolidate multi-year reagent supply agreements with locked pricing tiers. |
| Point-of-Care Molecular Miniaturization | Chip-based amplification technologies penetrate community-based screening programs with limited laboratory access. |
| CDSCO-WHO Prequalification Alignment | Streamlined procurement criteria accelerate public health volume contracts for compliant hepatitis B test kit suppliers. |
| Hybrid ELISA-Molecular Platform Development | Bridge instruments enable phased capital deployment while maintaining test menu breadth during workflow transitions. |
Study Parameters
Coverage spans East Asia, North America, and Europe, with primary inputs from each region combining structured interviews with diagnostic laboratory directors, hospital procurement committee members, molecular pathology unit heads, and regulatory affairs specialists at test kit manufacturers. Secondary validation draws from NMPA registration databases, FDA 510(k) filings, EU IVDR notified body documentation, and centralized hospital procurement platform disclosures. Bottom-up test volume modeling triangulates against top-down market size estimates from reagent supplier revenue disclosures.
Granularity-level framing applies country-specific regulatory pathway assumptions, end-user channel splits across tier-one hospitals versus community clinics, and technology migration curves from ELISA to PCR to automated systems. Segmentation dimensions include test type, technology platform, end-user scale, and geographic procurement cluster. CAGRs derive from installed base replacement cycles, reimbursement rate trajectories, and viral load quantification protocol adoption curves. Forecast inputs incorporate NMPA registration timeline differentials and IVDR compliance cost burdens.
The model holds under stable regulatory enforcement intensity and continued centralized procurement alliance expansion in China; deviation in NMPA registration reciprocity agreements or IVDR implementation delays would shift market access timelines. Forecasts reflect documented assumptions regarding workflow automation penetration and molecular test reimbursement expansion. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
Global Colorectal Cancer Diagnostics and Therapeutics Market
Clinical Diagnostics
Global High-Resolution Melting Analysis Market
Clinical Diagnostics
Global Minimal Residual Disease Market
Clinical Diagnostics
Serum Free Light Chain Assays (Sflc) Market
Clinical Diagnostics
Cardiology Genomic Testing Market
Clinical Diagnostics
Prenatal and New-Born Genetic Testing Market
Clinical Diagnostics
US Non-Invasive Prenatal Testing (NIPT) Market
Clinical Diagnostics
North America Liver Cancer Diagnostics Market
Clinical Diagnostics
Lactate Dehydrogenase Test Market
Clinical Diagnostics
Clinical Diagnostic Equipment Market
Clinical Diagnostics
Cytomegalovirus Assay Market
Clinical Diagnostics
Clinical Chemistry Market
Clinical Diagnostics
Osteoporosis Testing Market
Clinical Diagnostics
Global Breast Cancer Screening Test Market
Clinical Diagnostics
Antenatal Screening Market
Clinical Diagnostics
Global Cardiac Marker Testing Market