
 Perlite Market | 2026-2036
Perlite Market Size, Share, and Industry Trends Forecast 2026-2036
Perlite Market Intelligence
Green building contractors is redrawing procurement priorities across the perlite value chain as sustainability certifications reshape material specifications. Imerys leverages captive mining assets across volcanic belts to sustain vertical integration from raw extraction to micronized finished goods. Dicalite Management Group anchors North American supply through specialized filtration-grade production, while Silbrico Corporation differentiates via controlled expansion technology for high-performance insulation.
Perlite is a naturally occurring siliceous volcanic glass that expands up to twenty times its original volume when rapidly heated to approximately 871°C, creating a lightweight cellular structure prized for thermal insulation and moisture retention. Expanded perlite dominates volume flows due to its ubiquity in loose-fill insulation and soil amendment, while raw perlite concentrates margin pools with mining-controlled supply tightness. Horticulture applications are gaining structural momentum as soilless cultivation expands, though construction remains the mature revenue base with predictable replacement cycles.
EPA construction material standards and OSHA workplace exposure limits shape product handling protocols and site deployment requirements across the United States. ECHA REACH registrations govern chemical safety documentation for European perlite imports, while ISO 9001 quality management certifications increasingly gate distributor relationships in premium channels. Stakeholders must weigh raw ore reserve depletion against expanded capacity lead times when committing capital to vertical integration strategies.
Market Dynamics
Energy-efficiency mandates in building codes are compressing specification cycles for thermal insulation materials, forcing rapid qualification of lightweight aggregates against stricter R-value targets and fire-resistance ratings.
Growth Catalysts
- EU Green Deal renovation wave:Deep retrofit mandates across member states are accelerating demand for blown perlite cavity fill in existing building stock upgrades.
- Controlled-environment agriculture:Vertical farming operators in the Netherlands and Singapore are specifying engineered perlite substrates for precision hydroponic systems.
- Volcanic ore concentration:Greek Aegean deposits provide low-cost, high-purity feedstock anchoring Mediterranean expanded perlite supply chains.
Market Restraints
- Natural gas price volatility:Expansion furnaces consume substantial thermal energy, exposing margins to input cost swings in European manufacturing.
- Single-source ore dependency:Premium filtration grades rely on specific volcanic glass chemistries concentrated in limited geographic formations.
- Mineral wool substitution:Stone wool and glass wool producers are matching thermal performance at comparable installed cost in commercial roofing.
Strategic Opportunities
- India's PLI scheme for construction materials:Domestic manufacturing incentives could localize expanded perlite production for South Asian infrastructure buildout.
- Carbon capture substrate applications:Engineered expanded perlite is emerging as a structured packing material for direct air capture contactors.
- Biochar-perlite composite media:Converging soil amendment technologies are creating premium horticultural blends for regenerative agriculture.
Industry Challenges
- Furnace operator skill scarcity:Controlled expansion requires precise temperature profiling that experienced technicians execute; training pipelines lag capacity expansion.
- ECHA REACH dossier maintenance:Chemical safety documentation updates demand dedicated regulatory affairs capacity that mid-scale processors struggle to resource.
- Legacy silo integration:Batch expansion plants face retrofit complexity when linking to automated bulk handling systems for continuous downstream processing.
Report Scope
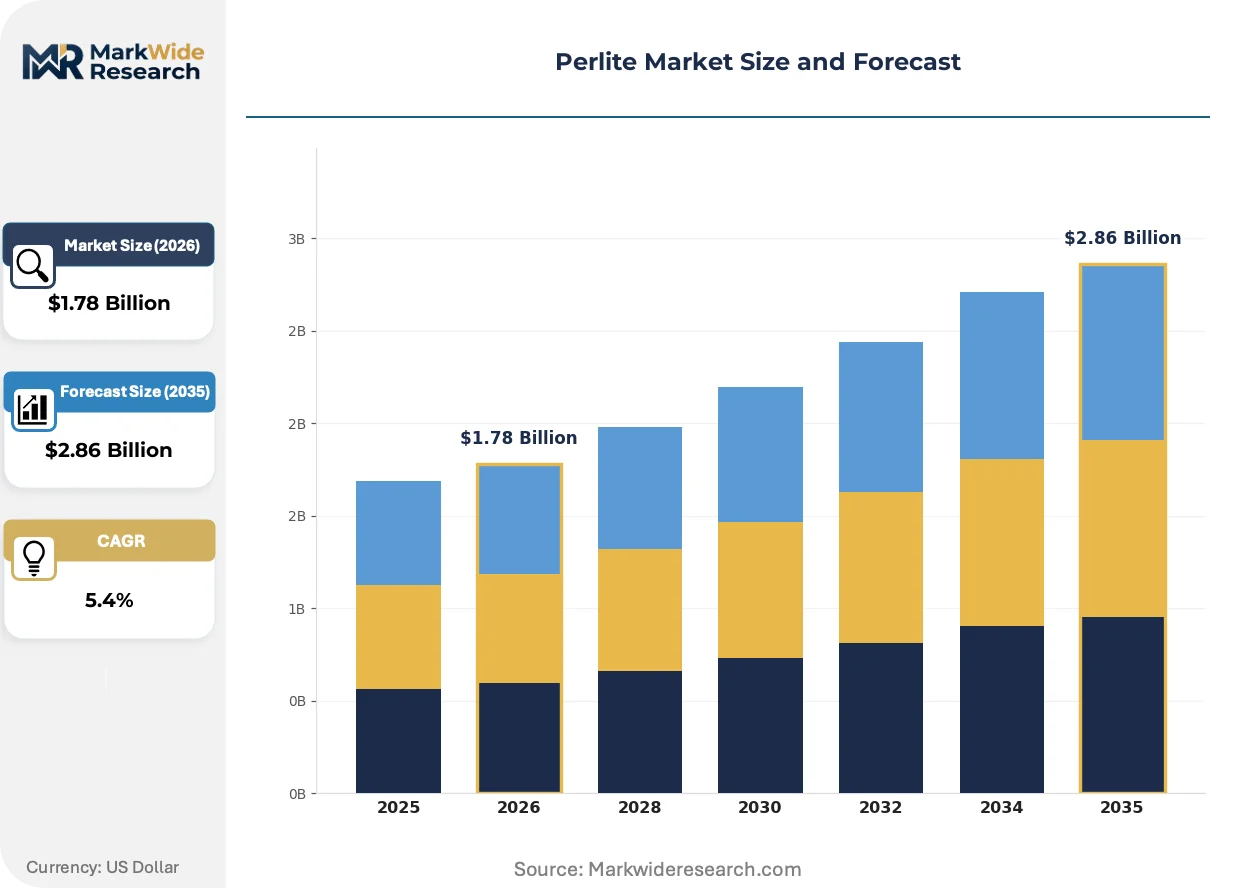
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Perlite Market |
| Market Size in 2026 | $1.78 Billion |
| Market Size in 2035 | $2.86 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Expanded Perlite, Raw Perlite, Micronized Perlite, Perlite Aggregate Application: Construction, Horticulture, Filtration, Insulation End User: Agriculture, Building Materials, Food & Beverage, Chemical Manufacturing Distribution Channel: Online, Direct Sales, Distributors, Retail |
| Companies Covered | Imerys, Dicalite Management Group, Silbrico Corporation, Hess Perlite, Genper, IPM Industries, Aegean Perlites, Perlite Hellas, Supreme Perlite Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Perlite Market Strategic Shifts & Innovations
Process intensification and sustainability certification are reshaping competitive advantage, separating capital-efficient operators from legacy batch processors unable to meet traceability requirements.
Micronization technology for perlite is bifurcating the filtration segment. Pharmaceutical and beverage clarifiers are adopting sub-50-micron grades for precision separation. This capability compression is squeezing commodity-grade suppliers while rewarding specialized processors with pharmaceutical-grade certifications.
EPA construction material standards are tightening volatile organic compound thresholds for site-applied insulation. Manufacturers are reformulating binders and coatings to maintain compliance. Commercial contractors in California and New York are pre-qualifying suppliers based on third-party emissions testing documentation.
Buyers are consolidating vendor relationships around certified cradle-to-gate carbon footprint data. Large greenhouse operators and construction firms are reducing approved supplier lists from twelve to four qualified sources. This concentration is most visible in Northern European markets where CSRD reporting requirements extend scope three emissions tracking to material inputs.
Perlite Market Segmentation
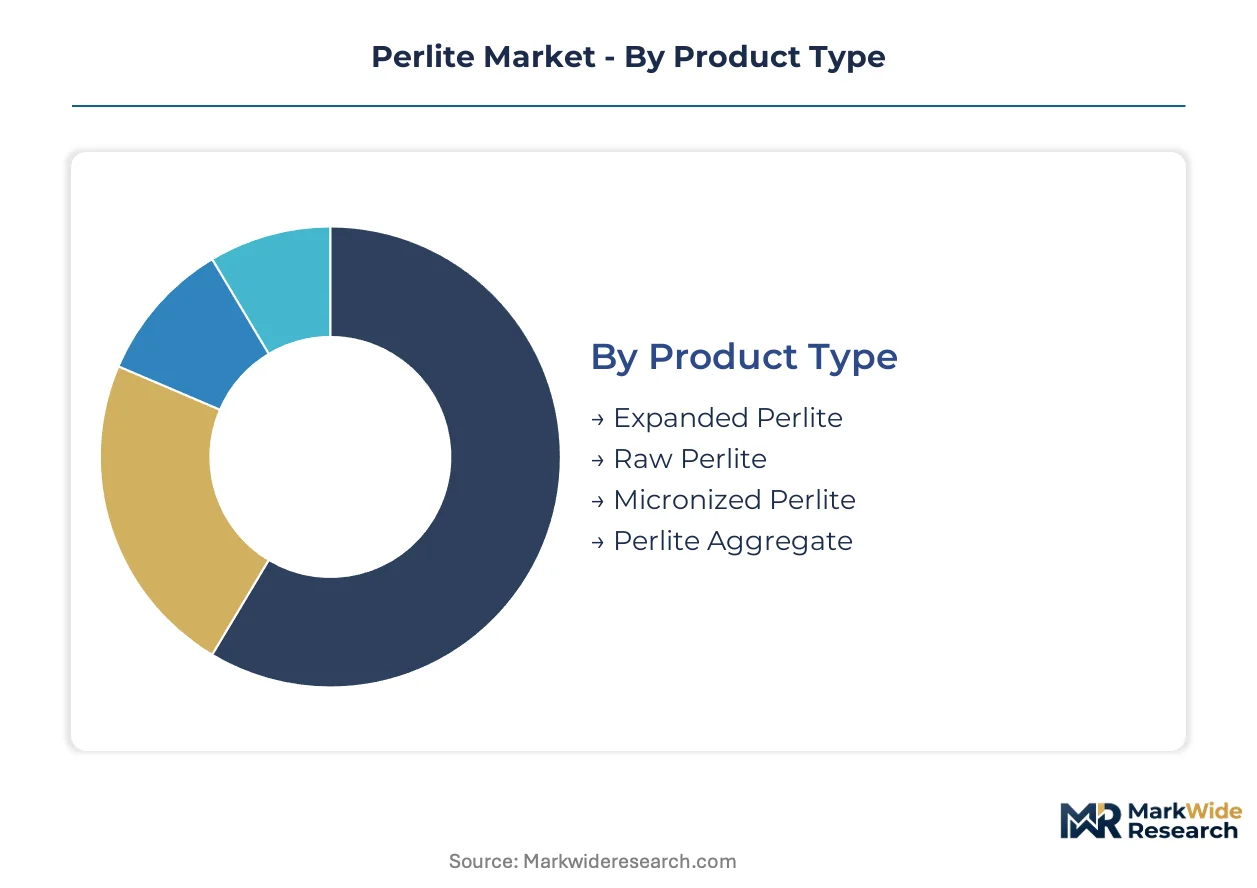
Perlite's physical transformation states and end-use specifications create distinct margin pools and channel requirements. Product form determines furnace investment intensity, while application verticals impose divergent purity and certification standards.
Product Type:
Channel mix splits sharply between bulk commodity flows and precision-grade specialty channels. Expanded perlite moves through construction distributors and agricultural supply houses in high-volume loose-fill formats. Micronized grades route through direct technical sales to filtration and pharmaceutical processors.
- Expanded Perlite:Cellular lightweight aggregate produced by rapid thermal expansion of raw ore, yielding densities from 32 to 240 kg/m³ depending on furnace temperature profiling. Construction contractors in Greece and Turkey specify blown cavity-fill grades for masonry insulation, though natural gas price volatility compresses processor margins across Mediterranean expansion facilities.
- Micronized Perlite:Precision-milled sub-50-micron powder engineered for pharmaceutical clarification and beverage filtration. German and Swiss beverage processors are consolidating supplier relationships around ISO-certified processors with documented cradle-to-gate carbon footprints.
- Raw Perlite:Unexpanded volcanic glass ore traded in bulk for captive expansion or specialized industrial applications. Aegean mining operations in Greece anchor supply concentration for premium filtration-grade feedstock.
- Perlite Aggregate:Crushed and sized raw ore for concrete lightweighting and specialized construction blends. Indian infrastructure projects are absorbing rising volumes under PLI scheme localization incentives.
Expanded perlite dominates installed base. Micronized perlite is where expansion concentrates.
Application:
Cost tier segmentation separates mature replacement-cycle businesses from emerging precision-agriculture deployments. Construction and insulation command volume scale with price-sensitive procurement. Horticulture and filtration support premium pricing through performance guarantees.
- Construction:Lightweight concrete aggregate, plaster aggregate, and masonry insulation across commercial and residential building envelopes. Dutch deep retrofit contractors under EU Green Deal mandates are specifying blown perlite for existing cavity wall upgrades.
- Horticulture:Soilless cultivation substrate for hydroponic and precision agriculture systems. Singapore vertical farming operators are engineering proprietary perlite-coco coir blends for controlled-environment production.
- Filtration:Clarification aid for beer, wine, edible oils, and pharmaceutical processing. ECHA REACH dossier maintenance requirements are gating mid-scale European processors from premium beverage-grade supply.
- Insulation:Loose-fill and formed insulation for cryogenic and ambient temperature applications. OSHA workplace exposure limits shape handling protocols for US mechanical contractors.
Construction anchors volume throughput. Horticulture is climbing the fastest.
End User:
Customer type determines specification intensity and contract structure. Food and chemical processors demand batch traceability and pharmaceutical-grade certifications. Agricultural buyers prioritize volume pricing and logistics reliability.
- Agriculture:Field crop soil amendment and greenhouse substrate applications. Large-scale Spanish and Italian greenhouse operators are reducing approved supplier lists from twelve to four qualified sources.
- Building Materials:Precast concrete, plasterboard, and specialty insulation manufacturers. EPA construction material standards are tightening volatile organic compound thresholds for site-applied insulation systems.
- Food & Beverage:Brewery, winery, and edible oil clarification processes. Swiss and German processors are mandating third-party emissions testing documentation from perlite suppliers.
- Chemical Manufacturing:Catalyst support media and specialty chemical filtration. Specific volcanic glass chemistries concentrated in limited Aegean formations create single-source ore dependency for premium grades.
Building materials commands raw tonnage. Food and beverage is where margin expansion concentrates.
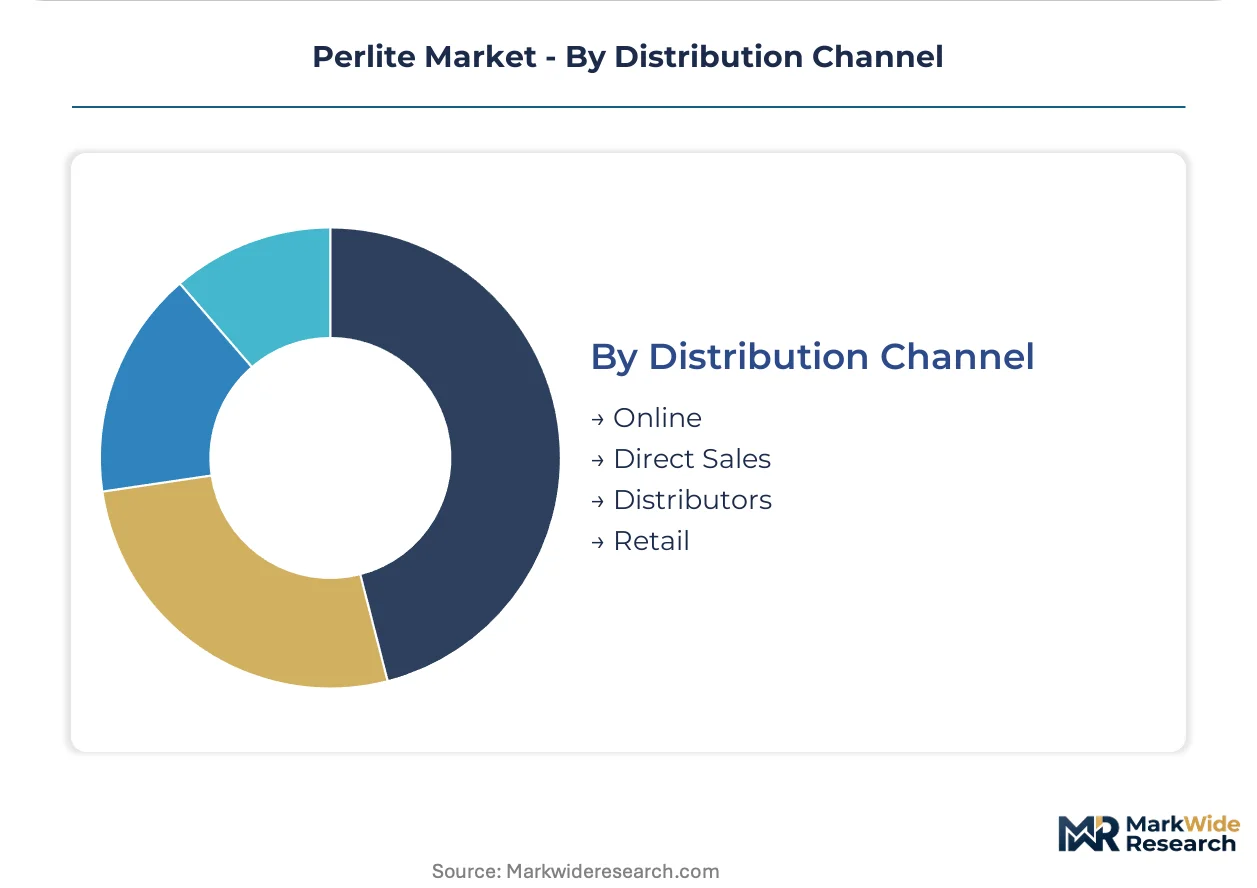
Distribution Channel:
Volume maturity separates established bulk logistics networks from emerging digital procurement platforms. Direct sales and distributors handle specification-heavy flows. Online channels are penetrating standardized agricultural grades.
- Direct Sales:Technical specification and long-term supply agreements for micronized and filtration grades. Imerys and Dicalite Management Group maintain captive sales forces for pharmaceutical and beverage processor accounts.
- Distributors:Regional construction supply and agricultural input wholesalers carrying expanded perlite in bulk and bagged formats. Northern European distributors are integrating CSRD scope three emissions tracking into supplier qualification.
- Online:E-commerce platforms for standardized horticultural grades and small-volume construction supplies. Greenhouse operators in the Netherlands are piloting digital procurement for recurring substrate orders.
- Retail:Garden center and home improvement channels for consumer-packaged soil amendments. California and New York commercial contractors are pre-qualifying retail suppliers based on emissions documentation.
Distributors dominate installed base. Online is where channel experimentation concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greek Aegean deposits feed expansion furnaces across Mediterranean processing hubs, with finished grades shipping to German construction distributors and Dutch agricultural operators under EU Green Deal procurement mandates.
Greece
Milos and Yali island mines supply premium volcanic glass feedstock for European filtration and horticultural grades. ECHA REACH dossier requirements govern chemical safety documentation for exported expanded perlite. Thessaloniki processing clusters handle bulk expansion for Italian and Spanish building material distributors.
Germany
Beverage processors in Bavaria and Baden-Württemberg specify micronized grades for beer and wine clarification systems. CSRD scope three emissions tracking extends to perlite substrate inputs for greenhouse operators. Hamburg distributors integrate carbon footprint data into supplier qualification protocols for construction insulation contracts.
United States
Western volcanic deposits in New Mexico and Oregon anchor domestic raw ore supply for filtration and construction grades. OSHA workplace exposure limits shape mechanical contractor handling protocols for loose-fill insulation deployment. EPA construction material standards tighten volatile organic compound thresholds for site-applied envelope systems in California and New York.
India
PLI scheme incentives for construction materials localize expanded perlite production for South Asian infrastructure buildout. BIS quality standards govern lightweight aggregate specifications for precast concrete manufacturers. Gujarat and Maharashtra industrial corridors absorb rising volumes of perlite aggregate for commercial building lightweighting projects.
Netherlands
Vertical farming operators in Westland and Noord-Brabant engineer proprietary perlite-coco coir blends for precision hydroponic cultivation. EU Green Deal deep retrofit mandates accelerate blown perlite demand for existing cavity wall upgrades. Rotterdam distributors pilot digital procurement platforms for recurring horticultural substrate orders.
Perlite Market Key Industry Players
Listed leaders compete with private specialists across mining-controlled supply chains and furnace technology tiers. The vendor base splits between integrated miners with captive ore reserves and regional processors dependent on third-party feedstock. Strategic archetypes include Aegean-based mining operators, North American filtration specialists, and Mediterranean expansion processors. Dominant competitive moves center on backward integration into ore reserves and certification investments for pharmaceutical-grade micronization.
Within the integrated mining tier, Imerys occupies a position exemplifying vertical control from volcanic extraction to finished goods. Among North American specialists, Dicalite Management Group and Silbrico Corporation represent contrasting approaches to filtration-grade production and controlled expansion technology respectively. These three anchors illustrate how geographic ore access and processing specialization stratify competitive positioning across construction, horticulture, and precision filtration end uses.
| Leading Market Players |
|---|
| Imerys |
| Dicalite Management Group |
| Silbrico Corporation |
| Hess Perlite |
| Genper |
| IPM Industries |
| Aegean Perlites |
| Perlite Hellas |
| Supreme Perlite Company |
| Others |
Cost & Logistics Intelligence
ECHA REACH dossier requirements gate both supply qualification and price differentiation simultaneously, forcing processors to absorb documentation costs that stratify micronized grades from commodity expanded products. Buyers in Northern Europe now demand cradle-to-gate carbon footprints as a condition of vendor approval, compressing margins for uncertified Mediterranean suppliers while rewarding integrated Aegean operators with pricing power in pharmaceutical channels.
Pricing Analysis
Legacy batch expansion technology commands economy-tier pricing against next-generation continuous furnace systems that capture premium spreads through energy efficiency and traceability certification. Three-tier pricing structure across pharmaceutical-grade micronized, construction-grade expanded, and raw ore feedstock segments reflects divergent purity standards and documentation burdens. Cost compression in expanded perlite intensifies because natural gas price volatility erodes processor margins across Mediterranean facilities. Agricultural buyers exhibit highest price sensitivity due to volume procurement and logistics-driven total cost optimization, while beverage and pharmaceutical processors accept premium positioning for documented batch traceability.
Supply Chain Analysis
Aegean ore deposits concentrated on Milos and Yali islands constitute a geographic chokepoint that concentrates premium filtration-grade feedstock supply. Greek mining operations, Turkish expansion processors, and German beverage manufacturers form the core triangle, with Indian PLI scheme localization emerging as a secondary node. Raw material flows draw from volcanic glass chemistry specificity, natural gas thermal input, and specialized furnace refractory components. Single-source ore dependency for pharmaceutical grades creates structural vulnerability to regulatory restriction or extraction disruption. Distribution runs through direct technical sales for micronized grades and regional construction distributors for bulk expanded products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Perlite market value creation increasingly attaches to substrate formulation services and carbon accounting documentation that expand faster than raw ore extraction economics. Recurring technical support contracts for controlled-environment agriculture operators and emissions verification services for CSRD compliance represent the fastest-growing revenue layers.
For Market Incumbents: Compound defensive positioning through backward integration into Aegean ore reserves and pharmaceutical-grade certification investments that mineral wool substitution threatens to erode. Prioritize captive supply of premium volcanic glass chemistries while building dedicated regulatory affairs capacity for ECHA dossier maintenance that mid-scale competitors cannot replicate. For New Entrants and Emerging Players: Anchor in India's PLI scheme localization incentives for construction-grade expansion capacity serving South Asian infrastructure buildout. Target underpenetrated carbon capture substrate applications for direct air capture contactors, leveraging engineered expanded perlite as structured packing material with technical sales to emerging climate technology developers. For Investors and Strategic Acquirers: EU Green Deal renovation wave mandates reshape the acquisition landscape toward processors with proven blown-cavity retrofit deployment capabilities and Dutch-German distribution relationships. Long-term viability centers on integrated miners with captive reserves rather than toll processors exposed to feedstock cost volatility. Watch furnace operator skill scarcity as the inflection signal—training pipeline gaps will constrain capacity expansion regardless of capital availability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aegean Ore Reserves | Imerys and Genper secure captive supply of premium volcanic glass chemistries for filtration grades. |
| Pharmaceutical-Grade Micronization Certification | ISO 9001 and ECHA REACH compliance gates access to Bavarian beverage processor accounts. |
| Continuous Furnace Technology Upgrade | Silbrico Corporation's controlled expansion systems reduce natural gas intensity per ton output. |
| Carbon Footprint Verification Service Launch | CSRD scope three tracking requirements extend to perlite substrate inputs for Dutch greenhouse operators. |
| PLI Scheme Manufacturing Localization | Gujarat and Maharashtra industrial corridors absorb expanded perlite for Indian precast concrete lightweighting. |
Research Approach
A standing panel of expansion furnace operators, horticultural substrate formulators, beverage filtration procurement managers, and construction materials distributors provided ongoing calibration against secondary validation from trade customs data, SEC processor filings, and ECHA registration databases. Primary interviews with Aegean mining engineers and Dutch vertical farming technical directors combined with bottom-up volume triangulation against top-down construction spend allocation models.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window, with segmentation modeling spanning product transformation state, application vertical, end-user industry, and regional regulatory cluster. CAGRs derived from historical expansion capacity utilization rates and forward-looking natural gas price scenarios, incorporating EU Green Deal renovation wave procurement timelines and India's PLI scheme localization incentives as industry-specific forecast inputs.
Underlying assumptions cover sustained EU energy-efficiency mandate enforcement and ECHA REACH dossier maintenance requirements, with deviation risk concentrated in natural gas price volatility and furnace operator skill scarcity constraining capacity expansion. Practitioners should keep alternative scenarios live as carbon capture substrate adoption rates and biochar-perlite composite media development evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Minerals
Barite Mining Market
Industrial Minerals
Mineral Wool Material Market
Industrial Minerals
Global and US Inorganic Salt Market
Industrial Minerals
Unexpanded Perlite Market
Industrial Minerals
Slate Market
Industrial Minerals
Strategic Mineral Materials Market
Industrial Minerals
Caustic Calcined Magnesite Market
Industrial Minerals
Potash Ores Market
Industrial Minerals
Seaweed Derived Minerals Market
Industrial Minerals
Nepheline Market
Industrial Minerals
Potassium Schoenite Market
Industrial Minerals
Limestone Mill Market
Industrial Minerals
Europe Feed Minerals Market
Industrial Minerals
Diatomite Mining Market
Industrial Minerals
Anhydrite Market
Industrial Minerals
Global Epsom Salt Market