
 Mineral Sand Market | 2026-2036
Mineral Sand Market Size, Share, and Industry Trends Forecast 2026-2036
Mineral Sand Market Intelligence
Buyer concentration in the titanium dioxide pigment sector is shifting as Chinese coatings producers consolidate procurement while Indian ceramics manufacturers fragment demand across smaller batch orders. Iluka Resources Limited anchors heavy mineral sand supply from its Western Australian operations. Kenmare Resources plc leverages its Moma titanium minerals mine in Mozambique to sustain ilmenite output for chloride-route pigment plants. Tronox Holdings plc controls integrated pigment manufacturing that competes on feedstock security rather than spot market exposure.
Mineral sands comprise titanium-bearing ores such as ilmenite, rutile, and leucoxene alongside zircon and sillimanite, typically recovered through wet gravity concentration and magnetic separation of heavy mineral concentrates from ancient beach or dune deposits; these materials serve primarily as feedstocks for titanium dioxide pigment production, titanium metal smelting, and high-temperature ceramics. Rutile commands premium pricing due to its elevated titanium dioxide content exceeding ninety percent, while zircon grade concentrates serve foundry and refractory applications where thermal shock resistance determines value. Ilmenite dominates volume flows into sulfate-route pigment plants, though leucoxene competes for chloride-process slots where higher TiO2 feedstock purity reduces waste acid generation.
EPA regulations in the United States govern dredge mining permits and wetland restoration requirements, while Australia's state-level environmental protection agencies enforce progressive rehabilitation bonds for mineral sand extraction sites. REACH compliance in the European Union shapes zirconium chemical purity standards for ceramics and dental applications. Stakeholders must monitor how China's dual carbon goals redirect titanium sponge demand toward aerospace versus civilian industrial end uses.
Market Dynamics
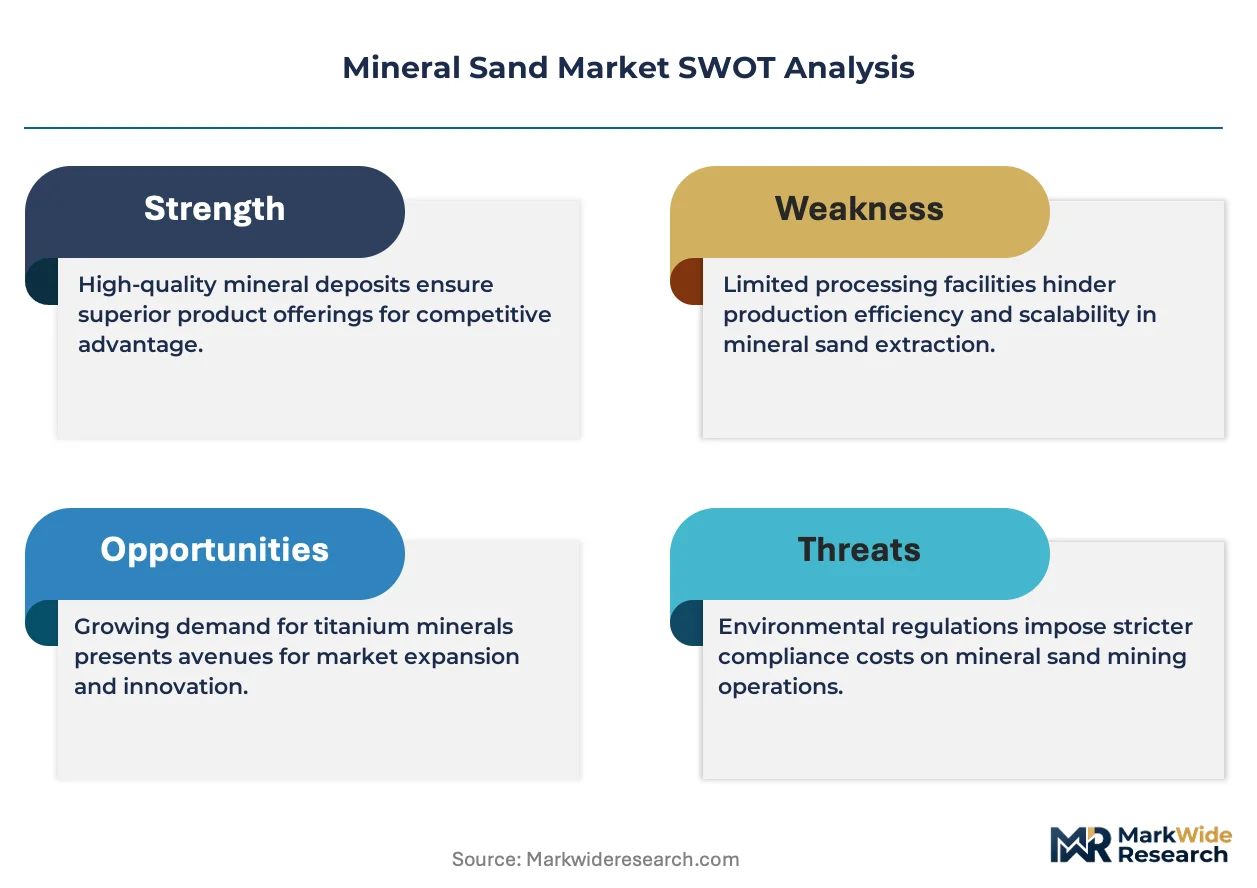
Aerospace manufacturers are accelerating titanium sponge procurement for airframe structures, tightening feedstock availability for pigment producers and forcing chloride-route plants to compete for rutile and synthetic rutile concentrates.
Growth Catalysts
- China's dual carbon goals:Beijing's emissions reduction mandates redirect titanium metal demand toward aerospace and away from civilian industrial casting, concentrating high-grade feedstock purchases.
- Ilmenite beneficiation technology:Advanced roasting and reduction processes upgrade lower-grade concentrates to synthetic rutile, expanding chloride-process feedstock pools.
- Coastal ceramics clusters:Zircon demand concentrates in China's Shandong and Guangdong provinces where sanitaryware and tile manufacturers scale output.
Market Restraints
- Australian environmental bonds:Western Australia's EPA mandates progressive rehabilitation deposits that tie up capital and delay greenfield project approvals.
- Energy cost volatility:Titanium slag smelting requires metallurgical-grade coke and electricity inputs vulnerable to spot price swings.
- Substitute ceramic media:Alumina and silicon carbide refractories displace zircon in certain foundry applications where thermal shock requirements moderate.
Strategic Opportunities
- Mozambique coastal deposits:Heavy mineral sand reserves along the Nampula province coastline remain underdeveloped relative to Australian and South African basins.
- Additive manufacturing feedstock:Plasma-atomized titanium powder specifications create premium pricing tiers for high-purity rutile-derived sponge.
- EU Green Deal industrial policy:Carbon border adjustment mechanisms favor low-carbon titanium dioxide pigment imports, advantaging chloride-route producers with renewable energy access.
Industry Challenges
- Geotechnical survey expertise:Ancient beach deposit delineation requires specialized heavy mineral assemblage modeling skills concentrated among retiring cohorts.
- Dredge fleet reconfiguration:Wet gravity concentration circuits demand capital replacement cycles that strain mid-tier operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mineral Sand Market |
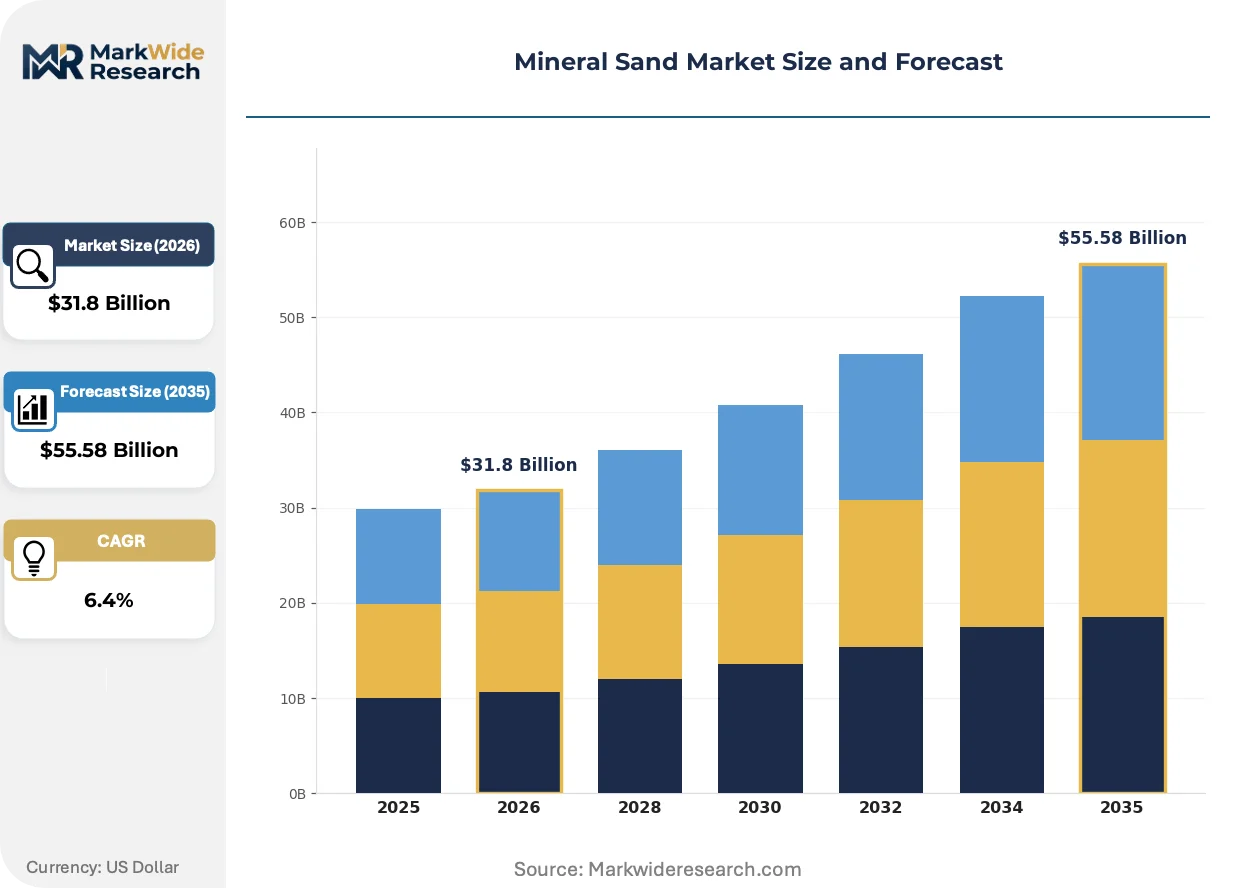
| Market Size in 2026 | $31.8 Billion |
| Market Size in 2035 | $55.58 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ilmenite, Rutile, Zircon, Leucoxene, Sillimanite Grade: Feed Grade, Rutile Grade, Zircon Grade, Refractory Grade, Chemical Grade Application: Paints & Coatings, Welding Electrodes, Ceramics Manufacturing, Foundry Sands, Abrasives End User Industry: Chemical Manufacturing, Construction Materials, Welding Units, Automotive Components, Glass Production |
| Companies Covered | Kenmare Resources plc, TiZir Limited, Iluka Resources Limited, Cristal Global, The Chemours Company, Rio Tinto Group, Base Resources Limited, QIT Madagascar Minerals, Tronox Holdings plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mineral Sand Market Strategic Shifts & Innovations
Processing technology advances and regulatory carbon accounting are compressing the cost gap between sulfate and chloride pigment routes while reshaping feedstock sourcing patterns.
High-temperature fluidized bed chlorination is decentralizing titanium slag production away from traditional smelter complexes. Pigment producers in Saudi Arabia and the United Arab Emirates adopt this technology to process imported ilmenite concentrates on-site. The shift erodes the historical advantage of vertically integrated miners with captive slag capacity.
REACH authorization requirements for zirconium compounds in dental and medical ceramics are tightening purity certification protocols. European manufacturers must demonstrate sub-50 ppm uranium and thorium content in zircon sand feedstocks. The regulation redirects procurement toward Australian and South African suppliers with established radiological screening infrastructure.
Coatings formulators in India are consolidating mineral sand procurement through toll-processing arrangements rather than direct concentrate purchases. Large paint manufacturers negotiate fixed-volume contracts with processors who manage magnetic separation and blending logistics. The model concentrates bargaining power among Mumbai and Ahmedabad-based coatings producers while fragmenting spot market liquidity.
Mineral Sand Market Segmentation
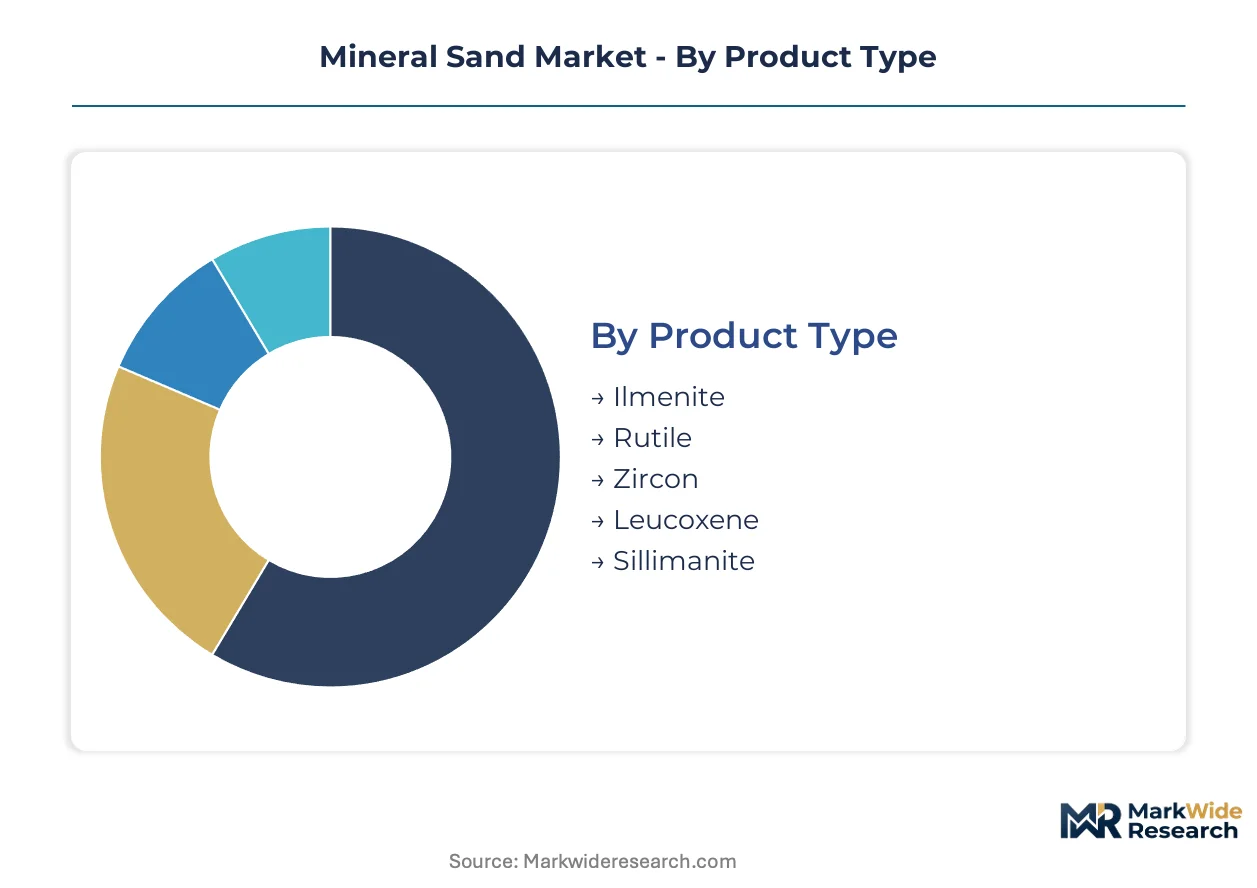
Mineral sand segmentation reveals distinct capital requirements across product categories, with chloride-route feedstock preparation demanding substantially higher upfront investment than sulfate-route beneficiation. Grade purity thresholds and end-use certification standards further stratify equipment and processing expenditure across the value chain.
Product Type:
Capital intensity peaks with synthetic rutile production circuits, while bulk ilmenite operations run on comparatively modest dredge and wet gravity infrastructure.
- Ilmenite:Titanium-iron oxide concentrate with TiO2 content ranging from 35% to 65% depending on deposit geology and beneficiation depth. China's Shandong pigment clusters absorb the majority of seaborne ilmenite flows, though chloride-route conversion requirements are tightening quality specifications.
- Rutile:Naturally occurring titanium dioxide mineral exceeding 90% TiO2 purity, commanding premium positioning for aerospace sponge and chloride pigment feedstock. Australian dredge miners concentrate rutile output for export to Saudi Arabia and UAE chlorination facilities.
- Zircon:Zirconium silicate mineral valued for thermal shock resistance in foundry and ceramic applications.
- Leucoxene:Altered ilmenite with elevated TiO2 content bridging ilmenite and rutile specifications.
- Sillimanite:Aluminosilicate mineral serving high-alumina refractory formulations.
Ilmenite absorbs the bulk of installed capacity; rutile is expanding most quickly.
Grade:
Grade stratification determines processing intensity, with chemical and refractory grades requiring radiological screening and magnetic separation circuits that multiply capital outlays.
- Feed Grade:Unbeneficiated or minimally processed concentrate suitable for sulfate-route pigment plants or titanium slag smelters. Indian toll-processors increasingly manage feed grade procurement for domestic coatings manufacturers.
- Rutile Grade:High-TiO2 concentrate meeting chloride-process purity thresholds with controlled calcium and magnesium levels. Mozambique coastal deposits are expanding rutile grade output as Australian environmental bonds constrain greenfield development.
- Zircon Grade:Concentrate meeting foundry and ceramic specifications, typically 65% ZrO2 minimum.
- Refractory Grade:Sillimanite and high-purity zircon concentrates for steel ladle and glass furnace applications.
- Chemical Grade:Sub-50 ppm uranium and thorium zircon sand certified for EU REACH dental and medical ceramics compliance.
Feed grade commands the widest production base; chemical grade is climbing the fastest as REACH authorization tightens.
Application:
Application mix shifts with coatings formulation consolidation in India and ceramics clustering in China's Guangdong province.
- Paints & Coatings:Titanium dioxide pigment consumption dominates mineral sand offtake, with sulfate and chloride routes competing on feedstock flexibility. Mumbai-based manufacturers are consolidating procurement through toll-processing contracts.
- Welding Electrodes:Rutile and ilmenite flux coatings for arc welding consumables, with demand tied to shipbuilding and infrastructure steel fabrication.
- Ceramics Manufacturing:Zircon opacifiers and refractory linings for sanitaryware, tile, and tableware production.
- Foundry Sands:Zircon sand mold facing for steel and superalloy casting where metal penetration resistance matters.
- Abrasives:Sillimanite and garnet substitutes in blasting and grinding applications.
Paints and coatings anchor volume offtake; ceramics manufacturing is gaining share fastest.
End User Industry:
End user concentration varies by titanium metal versus pigment demand, with aerospace procurement tightening sponge availability.
- Chemical Manufacturing:Titanium dioxide pigment plants and zirconium chemical processors constitute the primary demand sink, with chloride-route facilities in Saudi Arabia and UAE expanding.
- Construction Materials:Ceramic tile, sanitaryware, and glass production clusters in China's coastal provinces.
- Welding Units:Electrode manufacturers sourcing rutile and ilmenite flux materials.
- Automotive Components:Titanium forgings and castings for powertrain and chassis applications.
- Glass Production:Zircon refractories for furnace crown and regenerator applications.
Chemical manufacturing holds the deepest demand base; automotive components is expanding most quickly as aerospace titanium procurement tightens feedstock markets.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ancient beach deposits in Western Australia anchor titanium feedstock supply chains, while Mozambique's Nampula coastline and China's Shandong pigment clusters concentrate downstream demand. Environmental permitting constraints in mature mining jurisdictions are redirecting capital toward East African basins and Middle Eastern chlorination facilities.
Australia
Western Australian dredge miners supply rutile and synthetic rutile concentrates to chloride-route pigment plants in Saudi Arabia and the UAE. The state's Environmental Protection Agency mandates progressive rehabilitation bonds that tie up capital for greenfield developments. Perth-based operators concentrate heavy mineral assemblage output for export to Asian aerospace titanium sponge smelters.
China
Shandong and Guangdong province ceramics clusters absorb seaborne zircon sand for sanitaryware and tile manufacturing expansion. Beijing's dual carbon goals redirect titanium metal procurement toward aerospace applications under MIIT industrial policy guidance. Qingdao pigment processors consolidate ilmenite offtake through toll-processing arrangements with coastal coatings manufacturers.
Mozambique
Nampula province coastal deposits expand rutile grade output as Australian environmental constraints delay competing projects. The Moma titanium minerals mine anchors ilmenite supply for Indian and European chloride-route facilities. Pemba port infrastructure concentrates heavy mineral concentrate export logistics for southern African feedstock flows.
India
Mumbai and Ahmedabad-based coatings manufacturers fragment mineral sand procurement across toll-processing contracts rather than direct concentrate purchases. BIS quality standards govern zircon opacifier specifications for domestic ceramics production. Gujarat refractory clusters source chemical-grade zircon for foundry sand applications serving automotive component casting.
Saudi Arabia
Yanbu and Jubail industrial cities host fluidized bed chlorination facilities processing imported ilmenite concentrates on-site. SFDA oversight shapes zirconium chemical purity requirements for dental ceramics export to European markets. The kingdom's renewable energy access positions chloride-route pigment production for EU carbon border adjustment mechanism compliance.
Mineral Sand Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue East African coastal deposits and Middle Eastern chlorination partnerships. The market structure concentrates around integrated miners with captive dredge capacity and pigment manufacturers securing feedstock through long-term offtake agreements. Two archetypes dominate: vertically integrated heavy mineral sand miners controlling beneficiation infrastructure, and chloride-route pigment specialists competing on titanium slag conversion efficiency. Capacity expansion and strategic offtake contracting represent the dominant competitive moves as environmental permitting delays in Australia tighten feedstock availability.
Among Australian- and African-based miners, Iluka Resources Limited, Kenmare Resources plc, and Tronox Holdings plc exemplify the integrated archetype. Iluka Resources Limited occupies a position representing Western Australian dredge mining concentration. Kenmare Resources plc exemplifies East African coastal deposit development. Tronox Holdings plc anchors the pigment-integrated tier with captive feedstock security positioning.
| Leading Market Players |
|---|
| Kenmare Resources plc |
| TiZir Limited |
| Iluka Resources Limited |
| Cristal Global |
| The Chemours Company |
| Rio Tinto Group |
| Base Resources Limited |
| QIT Madagascar Minerals |
| Tronox Holdings plc |
| Others |
Cost & Logistics Intelligence
Rutile concentrate spot indices cascading from Australian dredge operations stratify procurement costs across chloride-route pigment plants in Saudi Arabia and the UAE, with synthetic rutile upgrade premiums widening spreads between sulfate and chloride feedstock tiers.
Pricing Analysis
Long-term offtake contracts with embedded assay-adjustment clauses dominate titanium feedstock procurement, with price differentiation hinging on TiO2 purity thresholds and radiological certification for EU REACH compliance. Cost compression in standard-grade ilmenite intensifies as Indian toll-processors consolidate bargaining power through volume aggregation. Mid-tier coatings manufacturers exhibit acute price sensitivity to concentrate assay variability, while aerospace sponge smelters absorb premium rutile pricing without volume elasticity.
Supply Chain Analysis
Direct-to-smelter channels handle aerospace-grade rutile demand from Western Australian miners, while toll-processing intermediaries manage fragmented Indian coatings procurement. Geographic supply concentrates in Australia, Mozambique, and South Africa for heavy mineral sand extraction, with beneficiation equipment and dredge fleet maintenance feeding from specialized engineering hubs in Perth and Johannesburg. Single-source vulnerability runs through Pemba port infrastructure for East African export flows. Distribution runs through long-term offtake agreements rather than spot market liquidity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fluidized bed chlorination technology is displacing traditional titanium slag smelting, compressing the historical advantage of vertically integrated miners with captive reduction capacity and redirecting value capture toward on-site processing specialists.
For Market Incumbents: Extend synthetic rutile beneficiation capabilities to capture chloride-route feedstock premiums as Australian environmental bonds constrain greenfield competitor entry. Deepen upstream control over Mozambique coastal deposits before Nampula province infrastructure matures. Counter alumina and silicon carbide refractory substitution threats in foundry applications through zircon grade purity certification investment. For New Entrants and Emerging Players: E-procurement platforms for toll-processing services offer entry points into India's fragmented coatings supply chain without capital-intensive dredge fleet investment. Target chemical-grade zircon segment penetration where REACH authorization tightens radiological screening requirements and incumbent certification infrastructure gaps persist. Pursue additive manufacturing feedstock specifications as plasma-atomized titanium powder demand outpaces established sponge supplier capacity. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier mineral sand processors with established assay laboratories in Western Australia facing rehabilitation bond liquidity pressure. Long-term viability centers on feedstock security positioning as aerospace procurement tightens rutile availability. Monitor chloride-route pigment plant announcements in Middle Eastern industrial cities as inflection indicators for synthetic rutile demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Beneficiation | Captive synthetic rutile production secures chloride-route feedstock supply for Saudi Arabian pigment plants. |
| Long-term Supply Agreement | Fixed-volume offtake contracts with Mumbai coatings manufacturers stabilize ilmenite revenue visibility. |
| Green Manufacturing Transition | Renewable energy-powered chlorination positions UAE facilities for EU carbon border adjustment compliance. |
| Joint Venture | Mozambique coastal development partnerships share dredge fleet capital burden across mid-tier operators. |
| Capacity Expansion | Nampula province rutile grade output growth fills supply gaps from delayed Australian greenfield approvals. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving dredge operations managers, pigment plant procurement directors, ceramics manufacturing technical leads, and heavy mineral sand assay laboratory supervisors. Bottom-up volume modeling triangulated against top-down macroeconomic demand indicators from chemical manufacturing and aerospace sector tracking.
Segment-level granularity applied across product type, grade tier, end-use industry, and regional production hub dimensions throughout the forecast period. CAGRs derived from elasticity-adjusted demand projections incorporating titanium sponge consumption patterns and pigment plant capacity announcements. Industry-specific inputs included chloride-route conversion yield assumptions and zircon radiological screening compliance cost curves.
The model holds under stable environmental permitting timelines in Australia and continued dual carbon policy enforcement in China; deviation in rehabilitation bond requirements or MIIT industrial guidance shifts would revise supply-side constraints. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Minerals
Snowflake Salt Market
Industrial Minerals
Talc Market
Industrial Minerals
Dolomite Mining Market
Industrial Minerals
Dolomite Powder Market
Industrial Minerals
Mineral Adsorbent Market
Industrial Minerals
Mineral Salt Ingredients Market
Industrial Minerals
United States Feed Minerals Market
Industrial Minerals
Aluminium Potassium Sulphate Market
Industrial Minerals
Micronized Salt Market
Industrial Minerals
Olivine Sand Market
Industrial Minerals
Mediterranean Sea Salt Micro-Mineral Complexes Market
Industrial Minerals
Middle East Feed Minerals Market
Industrial Minerals
Perlite Market
Industrial Minerals
Industrial Garnet Market
Industrial Minerals
Industrial Sodium Chloride Market
Industrial Minerals
Bentonite Market