
 Boron Minerals and Chemicals Market | 2026-2036
Boron Minerals and Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Boron Minerals and Chemicals Market Analysis
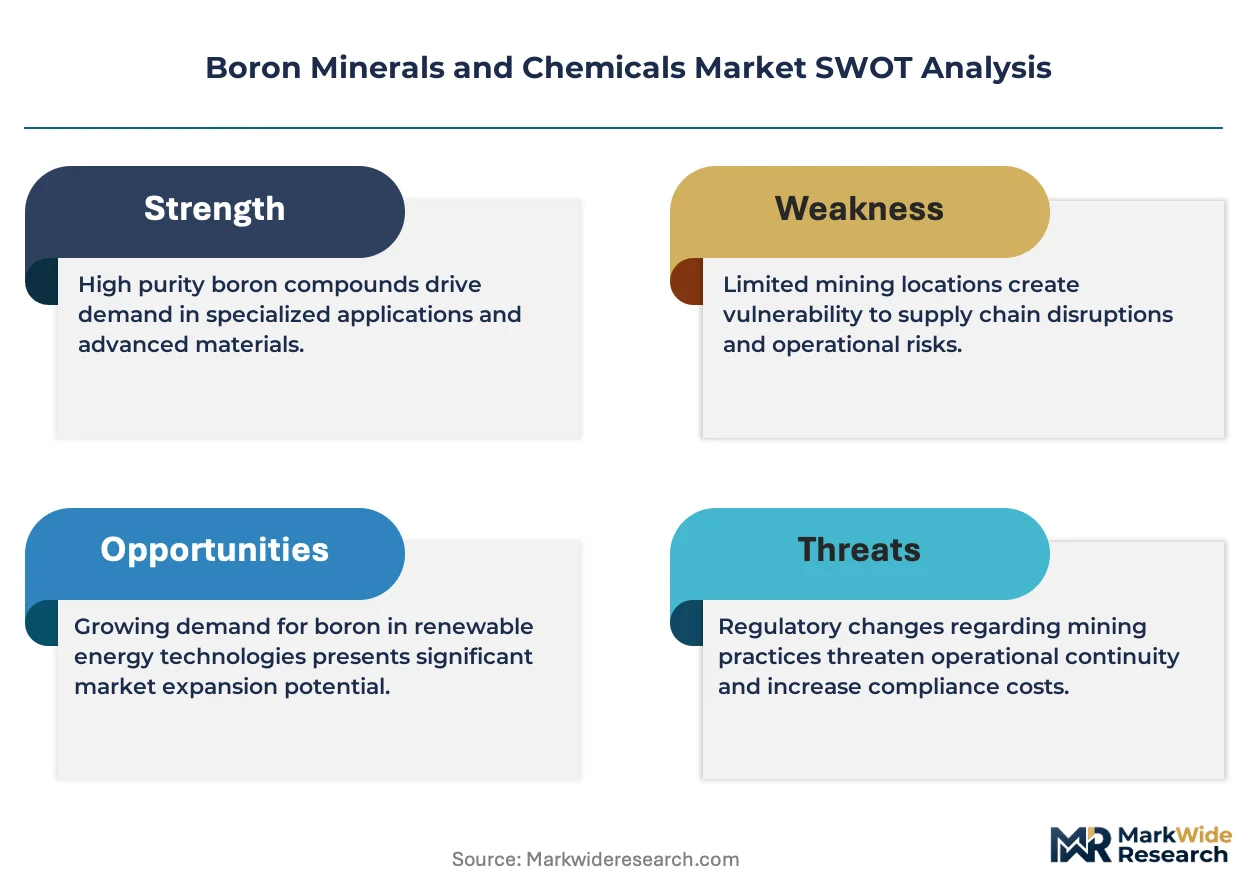
Project finance tied to lithium-boron co-extraction projects is reshaping capital deployment across the sector, allowing mid-tier miners to fund capacity without full balance-sheet commitment. Rio Tinto leverages its integrated borates-to-chemicals pipeline in California to sustain cost advantages in refined boric acid. ETI Maden anchors European supply through captive colemanite reserves in western Anatolia. Qinghai Zhongtian Boron Lithium Mining Co. Ltd competes on proximity to China's glass manufacturing belt, reducing inland logistics burdens for borax decahydrate buyers.
Boron minerals and chemicals comprise extracted borates and their processed derivatives, primarily sodium tetraborate decahydrate and orthoboric acid, which function as essential fluxing agents lowering glass melting temperatures and as cross-linking precursors in borosilicate formulations. Industrial-grade borax dominates volume flows into detergents and fiberglass, where margin pools remain thin but contractually stable, while pharmaceutical-grade boric acid commands premium pricing driven by antiseptic and ophthalmic formulation standards. Flame retardants represent the fastest-growing application segment as halogen-free polymer additives gain regulatory traction across electronics manufacturing supply chains.
EPA mining waste standards and REACH boron substance evaluations constrain permissible extraction methods and downstream chemical classifications, respectively, forcing producers to document ecotoxicological profiles for market access. Turkey's General Directorate of Mining Affairs and China's Ministry of Ecology and Environment administer overlapping but divergent permitting regimes that fragment compliance costs across supply nodes. Stakeholders must monitor evolving fertilizer-grade specifications in major agricultural import markets, where tightening purity thresholds threaten to disqualify legacy refining assets from contract eligibility.
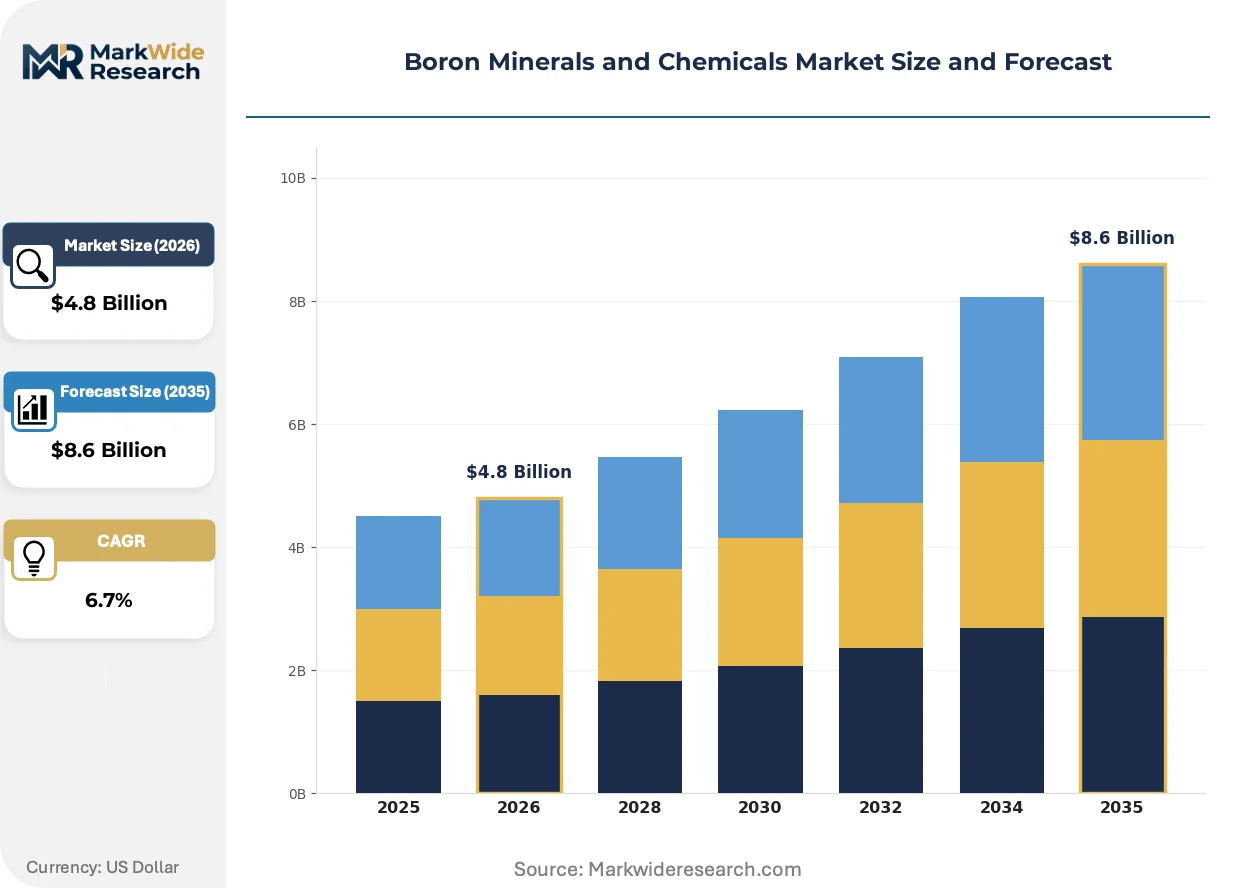
Market Dynamics
Project finance structures tied to lithium-boron co-extraction are compressing capital deployment timelines and allowing mid-tier miners to fund capacity without full balance-sheet commitment, fundamentally altering how production capacity enters the market.
Growth Catalysts
- EU Green Deal industrial policy:Binding decarbonization mandates in glass and ceramics manufacturing are elevating boron-enriched frit demand for energy-efficient solar panel production across German and Italian manufacturing corridors.
- Halogen-free flame retardant chemistry:Electronics manufacturers in South Korea and Taiwan are substituting brominated additives with boron-based polymer stabilizers to meet REACH substance restrictions and EPEAT certification requirements.
- Anatolia's colemanite belt concentration:Turkey's state-controlled mining concessions provide ETI Maden with extraction cost advantages that sustain refined boric acid competitiveness in European detergent and fiberglass supply chains.
Market Restraints
- Energy input cost volatility:Natural gas price fluctuations directly impact borax refining economics in California's Mojave operations, compressing margin pools for industrial-grade sodium tetraborate decahydrate.
- Single-source supply concentration:Western Anatolia's colemanite dominance creates geopolitical exposure for European chemical processors dependent on Turkish export quotas and concession renewals.
- Phosphate fertilizer substitution threat:Agricultural buyers in Brazil and Argentina are partially displacing boron micronutrient applications with compound fertilizers containing integrated trace elements, pressuring bulk borax pricing.
Strategic Opportunities
- India's underpenetrated glass ceramics corridor:Gujarat and Rajasthan manufacturing clusters lack proximate refined boric acid supply, creating logistics arbitrage potential for Middle Eastern chemical traders with Red Sea port access.
- US Inflation Reduction Act clean energy manufacturing credits:Domestic content bonuses for solar panel production are incentivizing borosilicate glass capacity expansion in Ohio and Georgia, pulling borax demand toward North American supply nodes.
- Boron nitride nanotube convergence with thermal interface materials:Semiconductor packaging specialists in Japan are piloting hexagonal boron nitride formulations for 3D chip stacking applications, opening premium pricing tiers beyond commodity borate chemistry.
Industry Challenges
- Process engineer scarcity in brine-lithium-boron co-extraction:The specialized skill set spanning hydrometallurgy and selective precipitation chemistry commands premium compensation, constraining project execution timelines in Argentina's Salta province.
- EPA mining waste characterization delays:New extraction projects in California's Kramer District face extended permitting cycles as operators document ecotoxicological profiles for selenium and arsenic co-occurrence in borate ore bodies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Boron Minerals and Chemicals Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boric Acid, Borax Decahydrate, Anhydrous Borax, Colemanite, Boron Carbide Grade: Industrial Grade, Pharmaceutical Grade, Agricultural Grade, Food Grade, Technical Grade Application: Glass Manufacturing, Detergents Production, Agriculture Fertilizers, Metallurgy, Flame Retardants End User Industry: Electronics Manufacturing, Agriculture Sector, Construction Sector, Chemical Industry |
| Companies Covered | Allkem Limited, American Borate Company, ETI Maden, Inkabor, Minera Santa Rita, Rio Tinto, Quiborax, Qinghai Zhongtian Boron Lithium Mining Co. Ltd, Searles Valley Minerals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Boron Minerals and Chemicals Market Emerging Trajectories
Digital process control systems and closed-loop brine management technologies are compressing extraction yields and regulatory compliance costs simultaneously, while downstream formulation science opens specialty chemical tiers beyond commodity borate trading.
Advanced sensor networks coupled with machine learning process optimization are virtualizing traditional assay-dependent extraction workflows. Rio Tinto's Boron operations deploy real-time ore grade prediction to adjust crushing and leaching parameters without laboratory lag. This capability is compressing working capital cycles and enabling just-in-time refined acid production against volatile construction fiberglass orders.
REACH boron substance evaluations are forcing downstream chemical reclassification across European supply chains. ECHA's ongoing assessment of reproductive toxicity endpoints threatens to restrict boric acid concentrations in consumer detergent formulations. German and Dutch formulators are responding by accelerating sodium perborate substitution trials and reformulating toward encapsulated boron release systems that limit dermal exposure.
Glass manufacturers in China's Hebei and Shandong provinces are consolidating procurement through direct long-term offtake contracts with Qinghai and Liaoning refiners, bypassing traditional Shanghai chemical trading houses. This disintermediation compresses price discovery transparency but locks in volume commitments that fund refinery modernization. The pattern is most visible in solar panel cover glass supply chains where boron-enriched frit specifications tighten quarterly.
Boron Minerals and Chemicals Market Segmentation
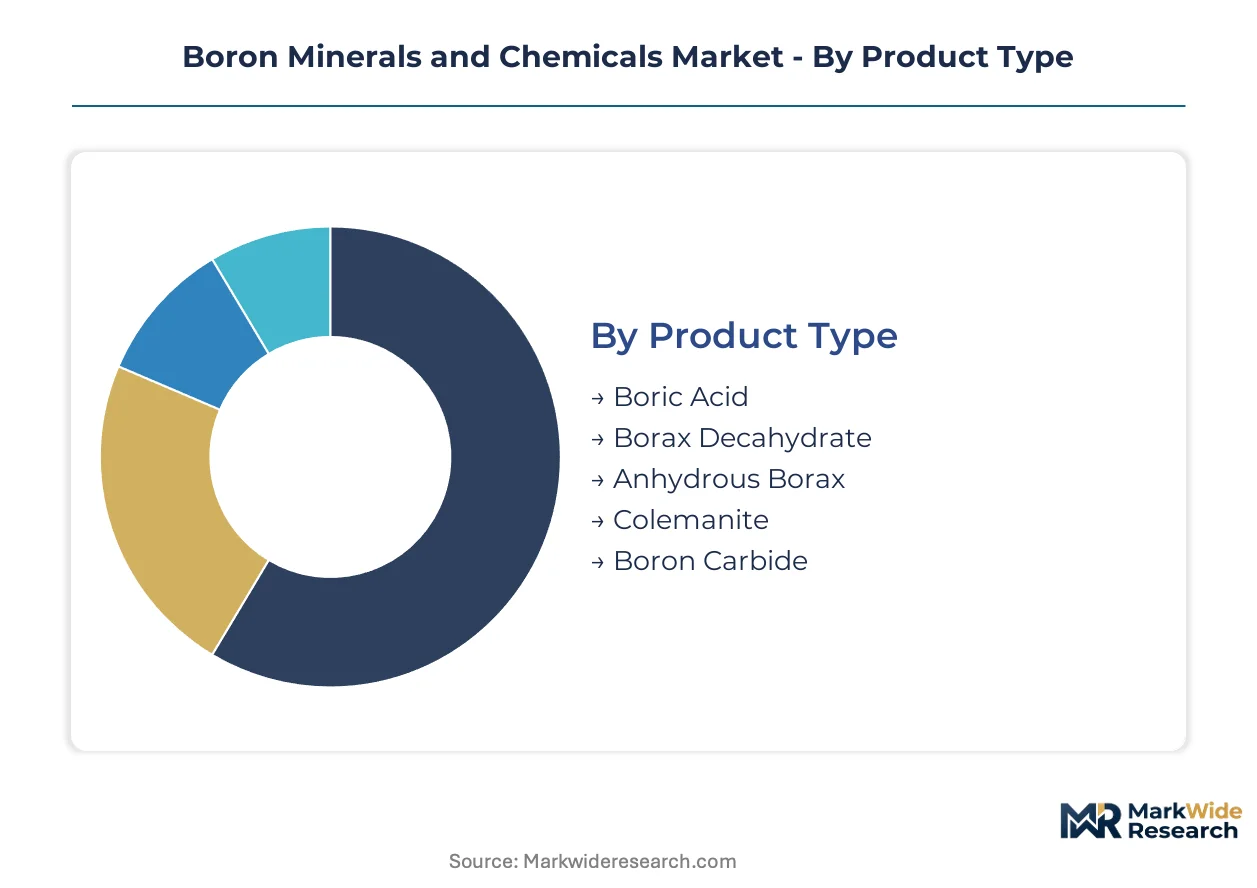
Boron minerals and chemicals fragment across technical specifications that determine pricing power and contract stability. Grade purity thresholds and end-use certification requirements create divergent margin profiles that reshape procurement strategies across glass, agriculture, and electronics supply chains.
Product Type:
Inventory velocities diverge sharply across this category, with refined derivatives turning over weekly against raw mineral stocks that sit for months awaiting processing slots.
- Boric Acid:Orthoboric acid (H3BO3) serves as the primary feedstock for borosilicate glass and flame retardant polymer additives. Demand concentrates in China's Hebei glass corridor, where solar panel cover glass manufacturers enforce sub-50ppm sulfate specifications that strain refining economics.
- Borax Decahydrate:Sodium tetraborate decahydrate (Na2B4O7·10H2O) functions as the workhorse flux in fiberglass insulation and detergent formulations. Construction sector procurement in Germany and Italy drives volume, though natural gas price volatility at California's Mojave refining complex compresses margin pools.
- Anhydrous Borax:Dehydrated sodium tetraborate eliminates water content for metallurgical flux applications where moisture introduces casting defects. Steel producers in Japan's Chiba and Kobe clusters specify this grade for continuous casting powders.
- Colemanite:Calcium borate mineral (2CaO·3B2O3·5H2O) extracted from Turkey's western Anatolia belt feeds European ceramic frit production. ETI Maden's captive reserves sustain cost advantages against refined alternatives.
- Boron Carbide:Extreme hardness ceramic (B4C) serves nuclear shielding and abrasive applications. Specialized defense and aerospace buyers in the US and France dominate offtake with multi-year qualification cycles.
Borax decahydrate anchors the volume base while boron carbide gains share at the steepest rate.
Grade:
Purity tiers stratify pricing by an order of magnitude, with certification costs determining which refiners can access pharmaceutical and food contract pools.
- Industrial Grade:Standard purity borate derivatives serve fiberglass, detergents, and bulk metallurgy where specifications tolerate 99% purity thresholds. Chinese refiners in Qinghai and Liaoning dominate this tier through scale economies.
- Pharmaceutical Grade:USP-grade boric acid meets antiseptic and ophthalmic formulation standards under FDA monograph requirements. Reproductive toxicity endpoint documentation under REACH constrains European supplier eligibility.
- Agricultural Grade:Micronutrient boron formulations for fertilizer blending carry solubility specifications that vary by crop type. Brazilian soybean growers and Argentine corn producers drive seasonal procurement patterns.
- Food Grade:FCC-certified borax serves as a food preservative and pH buffer in select applications. Stringent heavy metal limits restrict qualified refiner pools primarily to US and European producers.
- Technical Grade:Intermediate purity tier targets specialty ceramics and laboratory reagents where consistency matters more than absolute purity. Japanese and South Korean electronics chemical distributors specialize in this segment.
Industrial grade commands absolute volume leadership while pharmaceutical grade climbs the fastest on pricing power expansion.
Application:
Process intensity varies dramatically, with glass manufacturing requiring continuous furnace feeds against agriculture's seasonal batch procurement.
- Glass Manufacturing:Boron-enriched frits lower melting temperatures in solar panel cover glass and borosilicate laboratoryware. German Schott AG and Chinese Xinyi Glass enforce tightening boron oxide specifications that favor high-purity colemanite sources.
- Detergents Production:Sodium perborate and borax builders serve as bleach activators and water softeners. REACH substance evaluations threaten to restrict boric acid concentrations in European consumer formulations.
- Agriculture Fertilizers:Soluble borate granules correct micronutrient deficiencies in oilseed and legume cultivation. Indian Punjab and Haryana state extension services are expanding soil testing programs that identify boron-deficient plots.
- Metallurgy:Boron additives enhance hardenability in specialty steels and serve as nodulizing agents in cast iron. Japanese automotive steel mills in Hiroshima and Kitakyushu specify precise boron ranges for gear and shaft applications.
- Flame Retardants:Halogen-free boron-based polymer stabilizers substitute brominated additives in electronics housings. South Korean Samsung and LG Electronics suppliers are accelerating qualification under EPEAT certification requirements.
Glass manufacturing anchors the volume base while flame retardants gain share at the steepest rate.
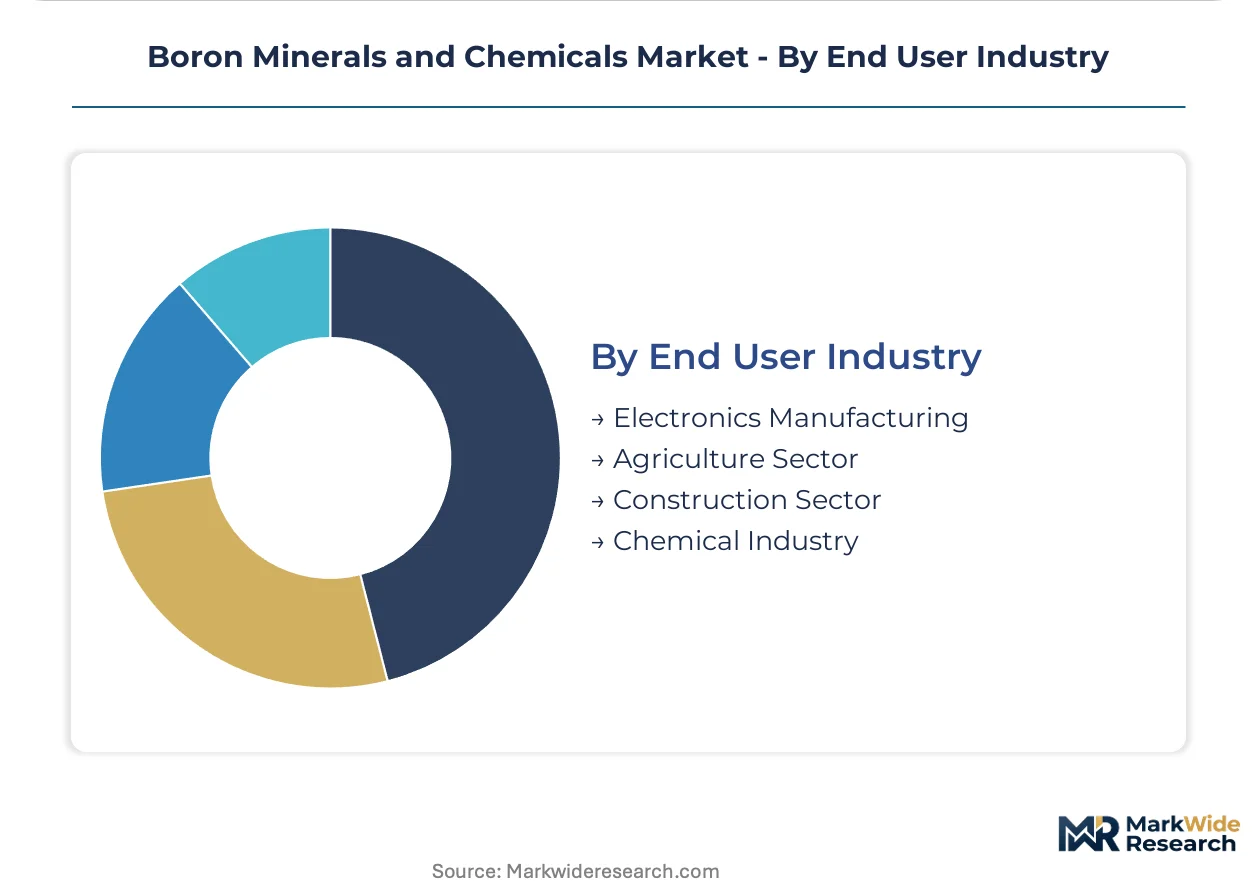
End User Industry:
Contract structures diverge by capital intensity, with electronics manufacturers demanding just-in-time delivery against agriculture's forward-priced seasonal commitments.
- Electronics Manufacturing:Semiconductor packaging and printed circuit board producers specify ultra-low sodium boron compounds for dielectric applications. Taiwan's TSMC supply chain enforces particulate contamination limits below 100ppm.
- Agriculture Sector:Fertilizer blenders and specialty nutrient formulators procure bulk borax for micronutrient enrichment. Brazilian cooperative purchasing through Paraná and Mato Grosso distribution hubs concentrates seasonal demand.
- Construction Sector:Fiberglass insulation and borosilicate glazing manufacturers drive steady industrial-grade consumption. US Inflation Reduction Act domestic content bonuses are pulling demand toward Ohio and Georgia manufacturing clusters.
- Chemical Industry:Downstream boron derivative producers—boron nitrides, metal borides, and organic boron reagents—source refined feedstocks for specialty synthesis. Japanese Showa Denko and German Evonik operate integrated boron-to-specialty pipelines.
Construction sector demand anchors the volume base while electronics manufacturing gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US Inflation Reduction Act domestic content bonuses are redirecting borax demand toward Ohio and Georgia solar glass clusters. German and Italian manufacturers face REACH substance reclassification pressures. Turkey's state mining concessions anchor European refined acid supply.
United States
Construction fiberglass and solar panel cover glass manufacturers in Ohio and Georgia are expanding borosilicate capacity to capture IRA manufacturing credits. EPA mining waste characterization delays extend permitting cycles for California's Kramer District projects. Rio Tinto's integrated Boron operations sustain cost advantages in refined boric acid through captive Mojave feedstock.
Turkey
ETI Maden's colemanite extraction from western Anatolia supplies European ceramic frit and detergent manufacturers at cost-advantaged positions. The General Directorate of Mining Affairs administers concession renewals that shape export quota availability. Izmir port infrastructure handles bulk shipments to Italian glass corridors and German chemical processors.
China
Hebei and Shandong glass manufacturers consolidate procurement through direct offtake contracts with Qinghai and Liaoning refiners, bypassing Shanghai trading houses. The Ministry of Ecology and Environment enforces dual carbon goals that elevate energy-efficient boron-enriched frit specifications. Xinyi Glass and solar panel cover producers tighten boron oxide purity thresholds quarterly.
Germany
Schott AG's borosilicate laboratoryware and solar glass operations drive pharmaceutical-grade boric acid demand under tightening USP specifications. ECHA's ongoing reproductive toxicity assessment threatens to restrict boric acid concentrations in consumer detergent formulations. Bavarian and North Rhine-Westphalia chemical processors accelerate sodium perborate substitution trials.
Argentina
Lithium-boron co-extraction projects in Salta province attract project finance structures that compress capital deployment timelines. The national mining secretary coordinates provincial permitting with federal environmental standards. Process engineer scarcity spanning hydrometallurgy and selective precipitation chemistry constrains project execution velocity.
Boron Minerals and Chemicals Market Vendor Landscape
Channel-controlling players compete with product-specialist players across divergent margin pools. State-backed mining enterprises with captive ore reserves face off against integrated chemical processors with refined acid pipelines. Two archetypes dominate: concession-holding national champions with extraction cost advantages, and integrated multinationals with downstream formulation capabilities. Capacity expansion and strategic partnerships represent the primary competitive moves, with co-extraction project finance emerging as a funding alternative to full balance-sheet commitment.
Among state-backed national champions, ETI Maden exemplifies the concession-anchored archetype through its Anatolian colemanite dominance. Rio Tinto occupies a position representing integrated multinational capabilities spanning extraction through refined acid production. Qinghai Zhongtian Boron Lithium Mining Co. Ltd sits within the proximity-advantaged tier, leveraging Qinghai location to serve China's interior glass manufacturing belt with reduced logistics burdens.
| Leading Market Players |
|---|
| Allkem Limited |
| American Borate Company |
| ETI Maden |
| Inkabor |
| Minera Santa Rita |
| Rio Tinto |
| Quiborax |
| Qinghai Zhongtian Boron Lithium Mining Co. Ltd |
| Searles Valley Minerals |
| Others |
Supply Flow & Price Mechanics
Western Anatolia's colemanite belt concentration under ETI Maden's state concessions anchors refined boric acid pricing power across European detergent and ceramic frit supply chains, with margin pools accumulating downstream at pharmaceutical-grade certification tiers rather than bulk industrial segments.
Pricing Analysis
Certification level under REACH and USP standards creates the primary spread between industrial-grade borax and pharmaceutical-grade boric acid, with reproductive toxicity documentation costs restricting European supplier eligibility. Three-tier pricing structure across premium, standard, and economy levels stratifies by purity threshold, volume commitment, and geographic delivery cost. Cost compression in industrial-grade sodium tetraborate decahydrate is intensifying because natural gas volatility at California's Mojave refining complex squeezes margin pools. Construction fiberglass buyers exhibit highest price sensitivity against semiconductor packaging specialists who absorb premiums for ultra-low sodium specifications.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Turkish state-backed mining concessions allow ETI Maden to fund extraction without full balance-sheet commitment, compressing capital deployment timelines for mid-tier competitors. Production gravity centers on Turkey, China, and the United States, with raw material dependencies on colemanite ore, natural gas for refining energy, and sulfuric acid for leaching chemistry. Single-source vulnerability from western Anatolia's dominance creates geopolitical exposure for European chemical processors dependent on export quotas. Distribution runs through direct long-term offtake contracts that bypass traditional chemical trading houses, particularly visible in Hebei and Shandong glass manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The boron minerals and chemicals market functions as a regulatory-entrenchment defensive moat, where REACH substance evaluations and EPA mining waste standards create certification barriers that protect incumbent positions while constraining new entrant viability.
For Market Incumbents: Build captive reserve positions through concession renewal negotiations and selective joint ventures in Argentina's lithium-boron co-extraction belt. ETI Maden should deepen upstream control over Anatolian colemanite logistics while Rio Tinto accelerates pharmaceutical-grade boric acid capacity to capture REACH-driven supplier disqualification. Defensive consolidation through acquisition of brine-lithium-boron co-extraction specialists addresses process engineer scarcity constraining Salta province project timelines.
For New Entrants and Emerging Players: India's underpenetrated glass ceramics corridor in Gujarat and Rajasthan represents the most penetrable entry point, lacking proximate refined boric acid supply and creating logistics arbitrage potential for Middle Eastern traders with Red Sea port access. Agricultural micronutrient formulations for Indian Punjab and Haryana extension services offer second white-space target, with soil testing program expansion identifying boron-deficient plots. Go-to-market through direct technical sales to solar panel cover glass manufacturers bypasses entrenched Shanghai trading house relationships.
For Investors and Strategic Acquirers: Capital is best deployed toward integrated borates-to-chemicals processors with captive ore reserves and downstream formulation capabilities, as these archetypes sustain margin capture across volatility cycles. Long-term viability over the coming decade rests on regulatory entrenchment deepening through ECHA reproductive toxicity assessments and EPA ecotoxicological profiling requirements. The signal to watch is lithium-boron co-extraction project finance availability, which indicates capital market appetite for mid-tier miner capacity expansion without full balance-sheet commitment.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Ore Reserves | ETI Maden's Anatolian colemanite dominance sustains European refined acid cost competitiveness against Chinese scale. |
| Long-term Supply Agreement with Solar Glass Manufacturers | Direct offtake contracts with Hebei and Shandong producers bypass Shanghai trading houses and lock volume commitments. |
| Joint Venture in Lithium-Boron Co-Extraction | Salta province project finance structures compress capital deployment timelines without full balance-sheet exposure. |
| Green Manufacturing Transition to Closed-Loop Brine Management | Rio Tinto's Boron operations deploy real-time ore grade prediction to compress working capital cycles. |
| Capacity Expansion in Pharmaceutical-Grade Boric Acid | REACH reproductive toxicity documentation requirements restrict European supplier eligibility and protect premium pricing tiers. |
Methodological Framework
Operator-level perspectives from plant managers at refining complexes, procurement leads at fiberglass and solar glass manufacturers, distribution channel partners in chemical trading houses, and technical R&D directors in flame retardant formulation anchored the qualitative base. Secondary validation drew from Turkish General Directorate of Mining Affairs concession records, Chinese Ministry of Ecology and Environment permitting databases, ECHA substance evaluation dossiers, and SEC filings from integrated chemical processors. Bottom-up capacity modeling across extraction sites and top-down demand triangulation from end-use industries were cross-referenced for convergence.
Scenario-bracketing around regulatory stringency variations and energy input cost volatility informed the analytical framework across the projection horizon. Segmentation dimensions modeled include grade tier, end-use industry, and regional production hub, with CAGRs derived from elasticity-adjusted volume trajectories and value-per-ton expansion patterns. Boron-enriched frit specification tightening in solar panel cover glass and halogen-free flame retardant qualification timelines in South Korean electronics supply chains served as industry-specific forecast inputs.
Practitioners should monitor ECHA reproductive toxicity endpoint conclusions, Turkish concession renewal schedules, and lithium-boron co-extraction project finance availability for early signals of forecast revision triggers. Forecasts reflect assumptions regarding regulatory continuity, energy cost normalization, and co-extraction technology maturation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Minerals
Potash Ores Market
Industrial Minerals
Limestone Market
Industrial Minerals
Middle East Feed Minerals Market
Industrial Minerals
Limestone Mill Market
Industrial Minerals
Industrial Garnet Market
Industrial Minerals
Caustic Calcined Magnesite Market
Industrial Minerals
Industrial Sodium Chloride Market
Industrial Minerals
Slate Market
Industrial Minerals
United States Feed Minerals Market
Industrial Minerals
India Feed Minerals Market
Industrial Minerals
China Feed Minerals Market
Industrial Minerals
Oman Industrial Salts Market
Industrial Minerals
Chelated Minerals Market
Industrial Minerals
North America Limestone Market
Industrial Minerals
Mineral Sand Market
Industrial Minerals
Europe Feed Minerals Market