
 Talc Market | 2026-2036
Talc Market Size, Share, and Industry Trends Forecast 2026-2036
Talc Market Intelligence
A shift from single-source dependency toward multi-source procurement for high-purity talc is restructuring supply chain relationships. Major suppliers like Imerys leverage their global mining footprint and processing capabilities to offer consistent quality across regions. Sibelco specializes in high-aspect-ratio talcs for advanced polymer reinforcement applications. Minerals Technologies Inc. competes through its focus on specialized grades for the North American paper and personal care industries.
Talc is a naturally occurring mineral composed of hydrated magnesium silicate, with the chemical formula Mg3Si4O10(OH)2. Its characteristic softness, with a Mohs hardness of 1, and lamellar structure make it an effective functional filler and processing aid. The plastics grade and paper grade segments represent mature, high-volume applications where cost is a primary factor. In contrast, pharmaceutical grade and cosmetic grade talc command higher margins due to stringent purity requirements and complex processing.
Regulatory scrutiny over asbestos contamination is a defining market force, with the US Food and Drug Administration (FDA) and the European Chemicals Agency (ECHA) setting rigorous testing protocols. In China, the National Medical Products Administration (NMPA) governs the use of talc in cosmetics and pharmaceuticals, aligning with international standards. Ensuring a verifiably asbestos-free supply chain through advanced testing and traceability remains the central strategic challenge for all participants.
Market Dynamics
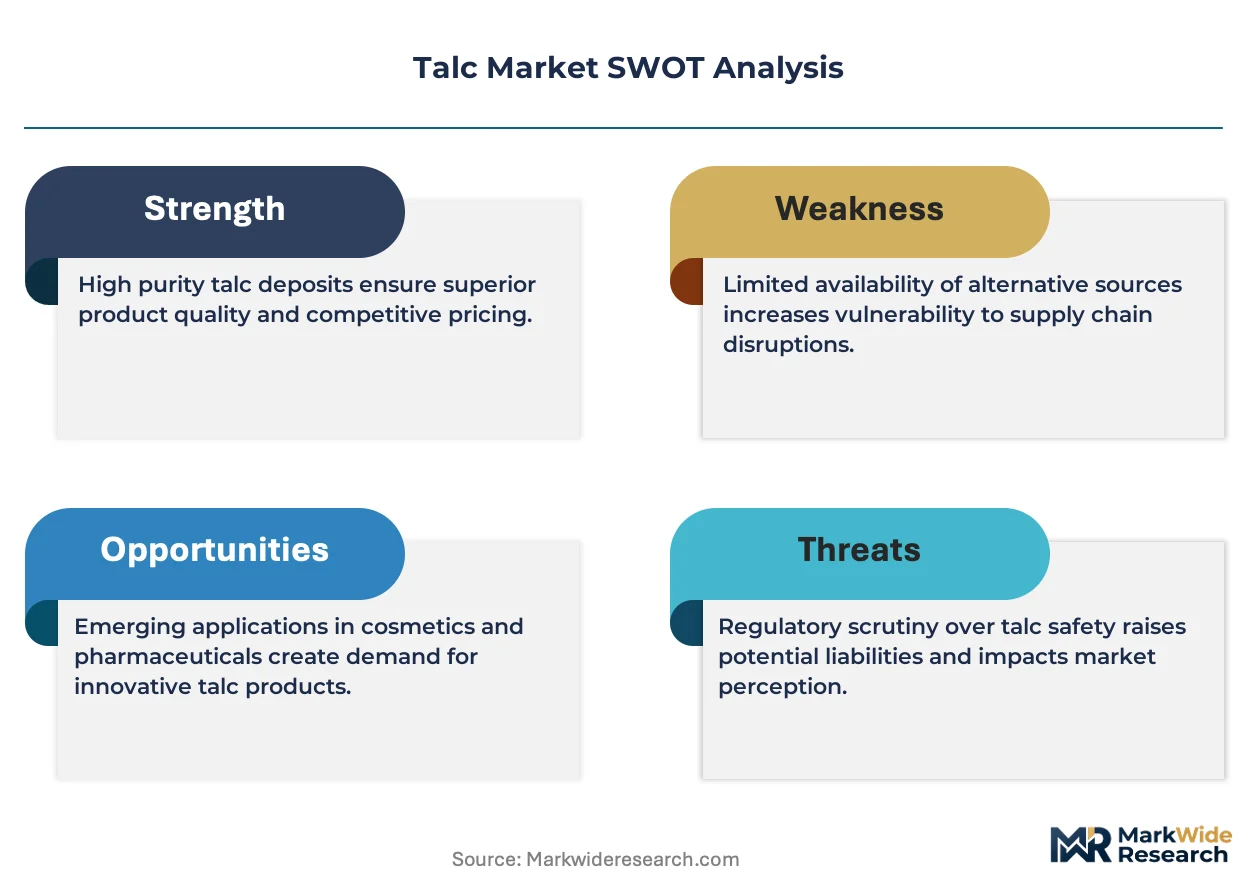
Regulatory pressure for verifiably asbestos-free talc is the central force shaping market dynamics. This scrutiny, led by agencies in the US and EU, compels investment in advanced testing and transparent sourcing, redefining cost structures and competitive positioning across the industry.
Growth Catalysts
- Automotive Lightweighting:Demand from automotive OEMs for talc as a reinforcing filler in polypropylene compounds reduces vehicle weight and improves fuel efficiency.
- Purity Standards in Cosmetics:Stringent purity requirements for cosmetic grade talc, governed by bodies like the NMPA in China, create a high-margin segment for certified asbestos-free products.
- Industrialization in Asia:China's continued industrial consumption, particularly in ceramics and plastics manufacturing, anchors global volume demand for industrial grade talc.
Market Restraints
- Asbestos Contamination Scrutiny:Persistent public health concerns and litigation risks associated with asbestos contamination create significant regulatory burdens and reputational challenges for producers.
- Threat from Chemical Substitutes:In applications like coatings and paper, talc faces competition from functional substitutes such as calcium carbonate and kaolin, which can offer cost advantages.
- Geopolitical Supply Risks:The concentration of high-quality talc deposits in a limited number of countries exposes the supply chain to potential disruptions from regional instability or trade policy shifts.
Strategic Opportunities
- High-Aspect-Ratio Grades:Developing specialized high-aspect-ratio talcs for advanced polymer composites offers a pathway into high-performance applications in electronics and aerospace.
- Bioplastic Formulations:The expansion of the bioplastics market presents an opportunity for talc as a functional additive to improve the mechanical properties and processing of materials like PLA.
- Emerging Market Penetration:Industrial growth in regions like Southeast Asia and Latin America provides new geographic markets for talc in plastics, ceramics, and paint manufacturing.
Industry Challenges
- Certification and Traceability Costs:Implementing and maintaining the rigorous testing protocols, like TEM analysis, and traceability systems needed to guarantee an asbestos-free supply chain is capital-intensive.
- Modernization of Processing Facilities:Significant capital expenditure is required to upgrade or build new milling and purification plants capable of meeting the stringent particle size and purity demands of premium grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Talc Market |
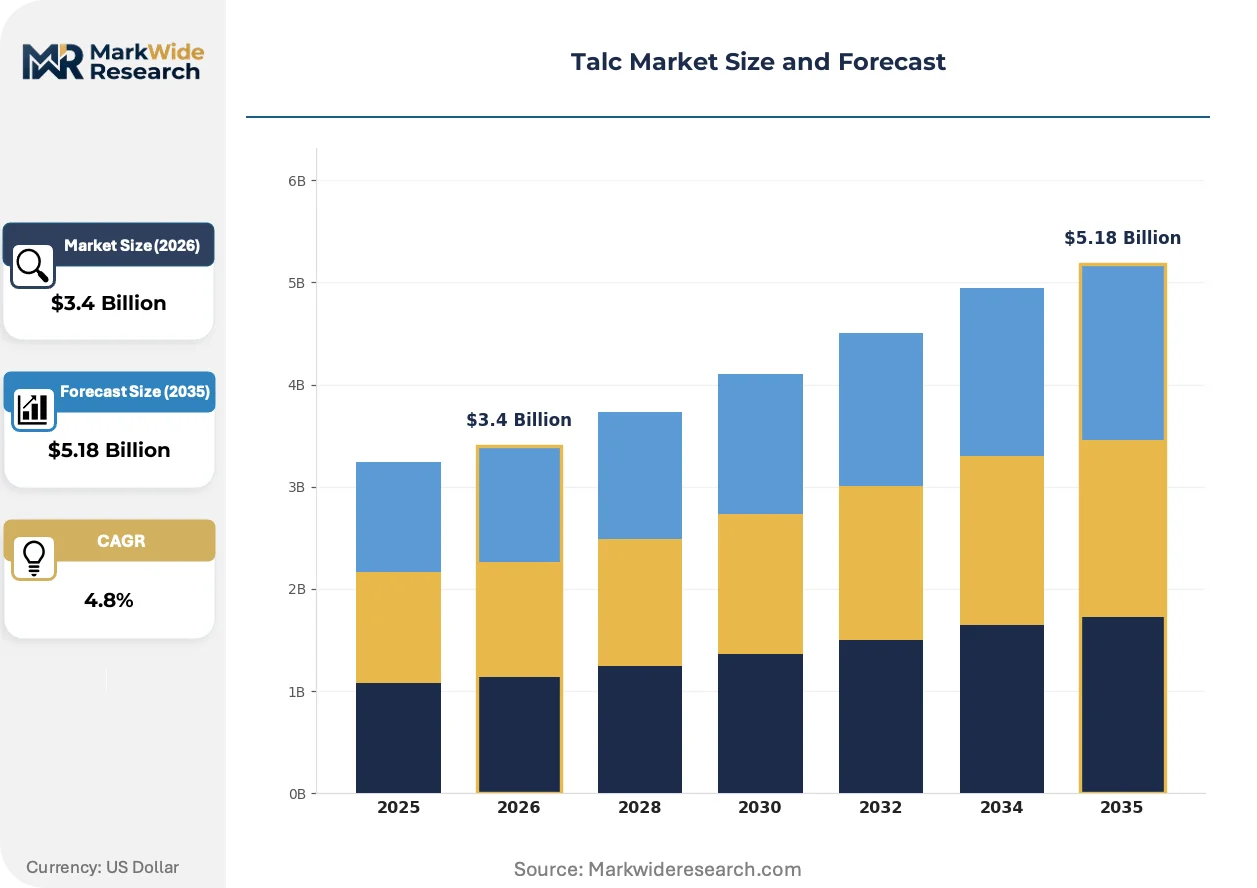
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $5.18 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cosmetic Grade, Pharmaceutical Grade, Plastics Grade, Paint Grade, Paper Grade Application: Paper Coating, Paint Fillers, Rubber Reinforcement, Ceramic Glaze, Food Additive Form: Powder, Granules, Flakes, Lump, Micronized End User Industry: Automotive OEMs, Personal Care Manufacturers, Ceramic Producers, Packaging Suppliers, Pharmaceutical Companies |
| Companies Covered | Minerals Technologies Inc., Magris Performance Materials, Imerys, Anand Talc, Nippon Talc Co., Ltd., Golcha Group, Sibelco, Guangxi Longsheng Huamei Talc Development Co. Ltd, IMI Fabi SpA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Talc Market Strategic Shifts & Innovations
Innovation in the talc market is driven by a dual mandate for higher performance in industrial applications and absolute purity for consumer-facing products. This creates distinct development pathways for functional additives versus highly regulated cosmetic and pharmaceutical grades.
Surface modification technology enhances the dispersion and hydrophobic properties of talc particles within polymer matrices. Plastics compounders serving the automotive and electronics industries are adopting these treated grades at an accelerated pace. This functionalization technology is converging with the development of high-performance thermoplastics, enabling the creation of advanced composites with superior mechanical and thermal properties.
Heightened regulatory standards for asbestos detection, including those from the US FDA and under EU REACH, are becoming stricter. This industrial consequence necessitates the use of more sensitive analytical methods like Transmission Electron Microscopy. The cosmetic and pharmaceutical talc segments are most impacted, compelling suppliers to adopt rigorous lot-by-lot testing and full supply chain traceability.
A clear behavioral change involves end-users moving from single-source dependency to a multi-source qualification strategy for high-purity talc. This trend disrupts exclusive regional supply contracts, creating openings for global miners with certified operations in multiple geographies. This sourcing evolution is most pronounced among multinational pharmaceutical and cosmetics firms aiming to mitigate geological and regulatory supply risks.
Talc Market Segmentation
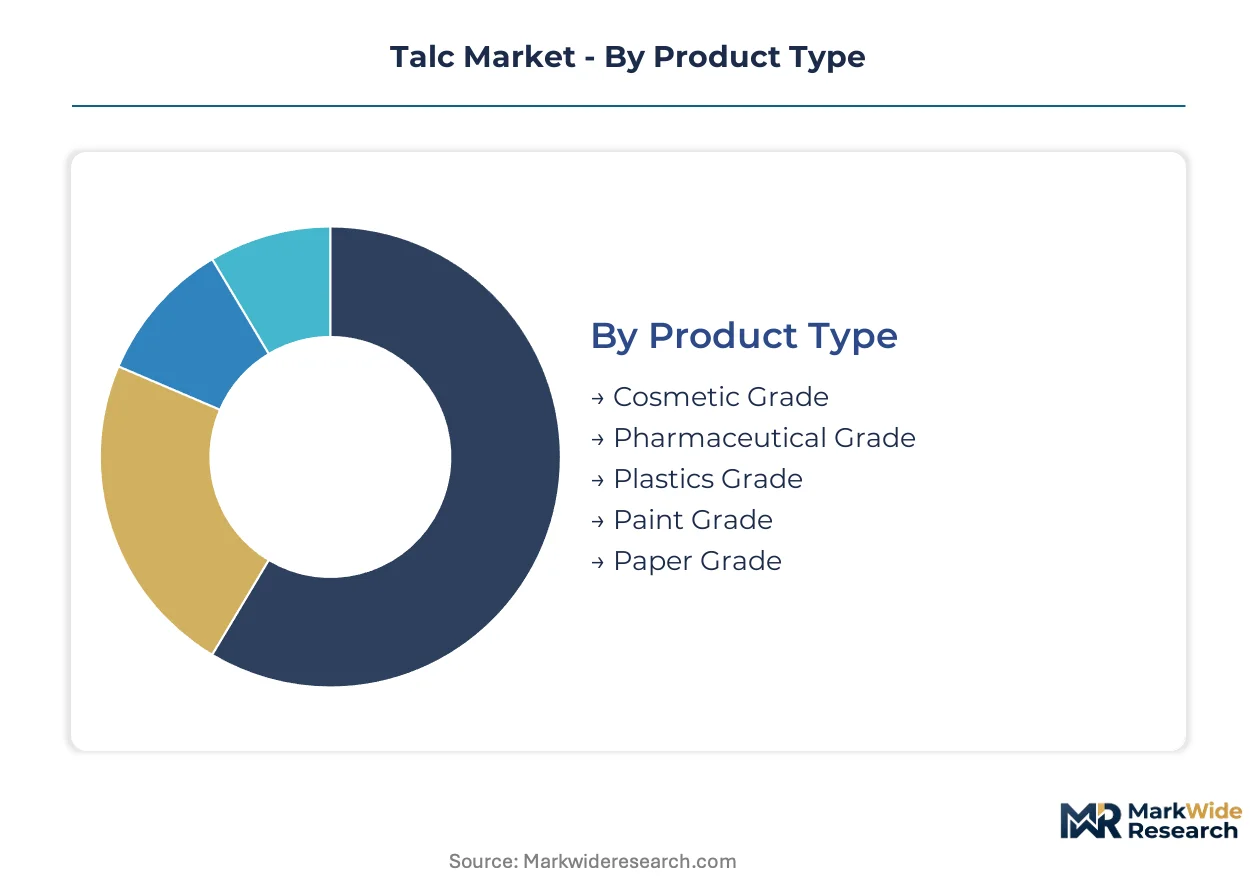
The talc market exhibits diverse segmentation driven by application-specific demands and stringent purity requirements. Understanding these distinct categories provides clarity on value creation, cost structures, and competitive dynamics across the industry. Each segment presents unique technical specifications and regulatory hurdles.
Product Type:
The product type segmentation highlights the critical specifications and processing required for different end-uses.
- Cosmetic Grade:Requires extremely high purity, verified asbestos-free status, and fine particle size for smooth application. Demand from multinational personal care manufacturers in France and Japan drives strict quality control.
- Pharmaceutical Grade:Demands the highest purity and regulatory compliance, adhering to pharmacopoeial standards like USP and EP. Pharmaceutical companies in the US and Germany require lot-by-lot testing for safety.
- Plastics Grade:Used as a reinforcing filler in polymer compounds, improving stiffness and heat distortion temperature.
- Paint Grade:Provides opacity, whiteness, and improves suspension properties in various paint formulations.
- Paper Grade:Enhances paper brightness, smoothness, and printability while reducing manufacturing costs.
Plastics Grade leads on scale; Pharmaceutical Grade leads on momentum.
Application:
The application segment illustrates where talc's functional properties deliver value across various industrial and consumer products.
- Paper Coating:Talc acts as a functional filler and coating pigment, improving surface properties and reducing ink absorption. Global paper mills, especially in Finland and Canada, use it for cost-effective production.
- Ceramic Glaze:Imparts whiteness, improves thermal shock resistance, and reduces firing temperatures in ceramic production. Chinese ceramic producers are major consumers for tiles and sanitary ware.
- Paint Fillers:Contributes to improved opacity, scrub resistance, and rheology control in architectural and industrial paints.
- Rubber Reinforcement:Enhances the stiffness, tensile strength, and abrasion resistance of various rubber products.
- Food Additive:Used as an anti-caking agent and lubricant in certain food processing applications.
Paper Coating applications command the largest market share, while Ceramic Glaze applications show significant expansion in Asia.
Form:
This category delineates talc by its physical state and processing level, influencing its suitability for diverse manufacturing processes.
- Powder:The most common form, characterized by fine particle size and high surface area, crucial for dispersion in liquid and polymer systems. Its versatility makes it essential across plastics and paint industries.
- Micronized:Ultra-fine particle talc, produced through advanced milling, offering superior dispersion and reinforcement in high-performance composites. Automotive OEMs in Germany and South Korea utilize it for lightweighting.
- Granules:Larger particle size talc, often used in applications where dust reduction or specific processing characteristics are desired.
- Flakes:Characterized by a lamellar structure, providing barrier properties and reinforcing effects in certain polymer applications.
- Lump:Raw, unprocessed talc as extracted from mines, primarily traded between mining operations and processing facilities.
Powder forms dominate volume, while Micronized forms offer higher value due to specialized processing.
End User Industry:
This segment categorizes demand based on the primary industry consuming talc, reflecting varying regulatory and performance requirements.
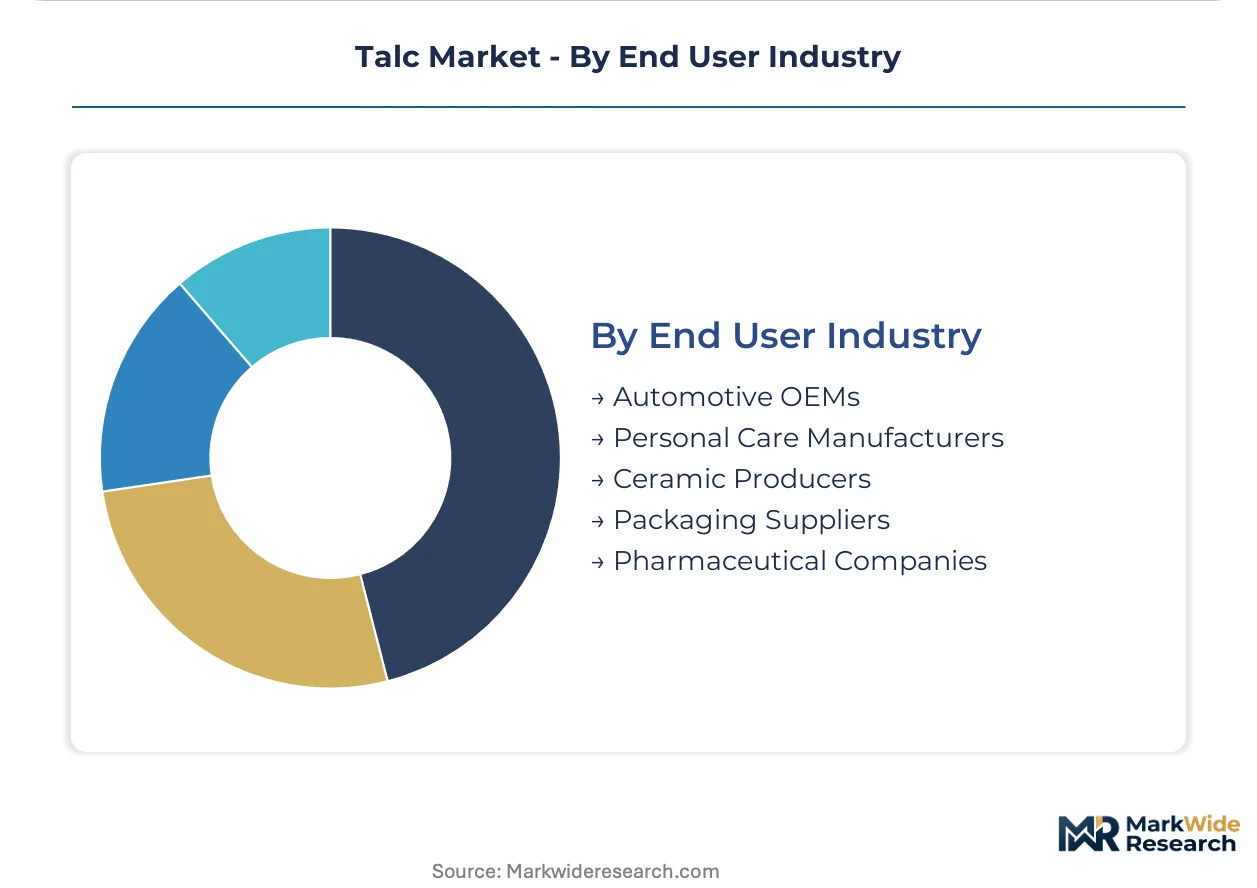
- Automotive OEMs:Utilize talc in polypropylene compounds to reduce vehicle weight, improve fuel efficiency, and enhance mechanical properties. Major car manufacturers in Germany and the US integrate talc-filled plastics.
- Pharmaceutical Companies:Rely on high-purity, asbestos-free talc as an excipient, glidant, and lubricant in tablet formulations. Strict regulatory bodies like the US FDA and EMA govern its use.
- Personal Care Manufacturers:Incorporate certified asbestos-free talc into cosmetics and personal hygiene products for its absorbent and textural properties.
- Ceramic Producers:Employ talc to improve the firing characteristics and mechanical strength of ceramic bodies and glazes.
- Packaging Suppliers:Use talc as a filler in plastic films and containers to enhance stiffness and anti-block properties.
Automotive OEMs represent a significant growth driver, while Pharmaceutical Companies face the most stringent regulatory oversight.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta industrial hub drives significant talc demand for plastics and ceramics manufacturing. This global market sees varied regional dynamics influenced by industrialization patterns and stringent purity requirements. Regulatory frameworks across major economies shape sourcing and processing strategies for talc producers.
China
China's robust ceramics and plastics manufacturing sectors generate substantial demand for industrial-grade talc. The National Medical Products Administration (NMPA) sets stringent standards for talc use in cosmetics and pharmaceuticals. Shandong Peninsula's industrial base actively consumes talc as a functional filler in diverse material production.
United States
United States automotive OEMs require talc for lightweighting applications in vehicle production. The US Food and Drug Administration (FDA) maintains rigorous purity standards, especially for pharmaceutical and cosmetic grade talc. Detroit's automotive manufacturing centers increasingly adopt talc-reinforced plastics to enhance fuel efficiency.
Germany
German automotive and pharmaceutical industries demand high-purity talc for advanced applications. European Chemicals Agency (ECHA) REACH regulations impose strict compliance requirements on chemical suppliers. Bavaria's industrial heartland leverages talc in sophisticated material science for automotive and electronics components.
Japan
Japanese personal care manufacturers seek high-purity talc for cosmetic formulations and advanced polymer applications. The Ministry of Economy, Trade and Industry (METI) guides industrial chemical safety and product quality. Tokyo's consumer goods and electronics sectors drive demand for specialized talc grades.
Finland
Finnish paper mills extensively use talc for coating and filler applications in paper production. European Union environmental directives influence sustainable sourcing and processing within the pulp and paper sector. Kymenlaakso's integrated forest industry operations rely on talc to enhance product quality and cost efficiency.
Talc Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue specialized, high-purity talc grades for niche applications. The market structure exhibits a tiered competitive landscape, with a few large global players alongside numerous regional and specialized suppliers. Strategic archetypes include integrated miners with extensive processing capabilities and specialized formulators focusing on advanced material properties. Companies primarily engage in capacity expansion for premium grades and strategic partnerships to secure asbestos-free supply chains.
Within the integrated mining archetype, Imerys, a French Société Anonyme, represents a global footprint with diverse processing capabilities and consistent quality across regions. Sibelco, a Belgian limited company, exemplifies specialization in high-aspect-ratio talcs, catering specifically to advanced polymer reinforcement applications requiring superior mechanical properties. Minerals Technologies Inc., an American corporation, sits within the category of focused suppliers catering to specific industrial sectors, including the North American paper and personal care industries, where specialized grades command higher margins.
| Leading Market Players |
|---|
| Minerals Technologies Inc. |
| Magris Performance Materials |
| Imerys |
| Anand Talc |
| Nippon Talc Co., Ltd. |
| Golcha Group |
| Sibelco |
| Guangxi Longsheng Huamei Talc Development Co. Ltd |
| IMI Fabi SpA |
Cost & Logistics Intelligence
Modernization of processing facilities and advanced testing protocols simultaneously reshapes cost economics and supply concentration in the talc market. These investments create higher barriers to entry for new suppliers and consolidate premium-grade production among established players.
Pricing Analysis
Rising input costs for energy and advanced testing are passed through, influencing talc pricing across all grades. A contract-based long-term offtake model dominates for industrial volumes, while pharmaceutical and cosmetic grades utilize a value-based pricing approach. Price differentiation stems from certified asbestos-free status and specialized particle size distribution for high-performance applications. Pricing softness affects industrial-grade talc due to competition from substitutes like calcium carbonate. Pharmaceutical and cosmetic manufacturers exhibit the lowest price sensitivity, prioritizing purity and regulatory compliance.
Supply Chain Analysis
Rigorous asbestos-free certification and qualification gating define entry into high-purity talc supply chains. Geographic supply concentrates in China for industrial grades, while high-purity sources draw from limited deposits globally. Raw talc ore and specialized milling equipment represent key raw material dependencies. Geopolitical supply risks, stemming from concentration in a few countries, pose a structural vulnerability. Distribution runs through a mix of direct sales to large industrial consumers and specialized distributors for niche, high-value grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The talc market presents a geographic-arbitrage play, with lower industrial production costs in China contrasting with stringent regulatory demands and high-purity requirements in the US and Europe.
For Market Incumbents: Hedge against evolving regulatory landscapes by investing proactively in advanced asbestos testing capabilities, such as Transmission Electron Microscopy. Diversify high-purity talc sourcing across multiple certified mining operations to mitigate single-source geopolitical risks. Expand premium-grade capacity in regions with strong demand for advanced polymer reinforcement, leveraging R&D in surface modification technology.
For New Entrants and Emerging Players: A significant price-point gap exists between high-margin pharmaceutical/cosmetic talc and volume-driven industrial grades. Target specialized, high-aspect-ratio talcs for advanced polymer composites in electronics and aerospace, which command premium pricing. Penetrate emerging markets in Southeast Asia with industrial-grade talc for ceramics and plastics manufacturing. A go-to-market angle focusing on transparent, verifiably asbestos-free supply chains offers a competitive advantage.
For Investors and Strategic Acquirers: Valuations sit cheapest among integrated miners lacking advanced processing capabilities for premium grades. Long-term viability hinges on the essential functional properties of talc and increasing regulatory barriers for purity. Acquire specialized processing facilities with proven asbestos-free certification technologies. A signal to watch is the further tightening of international regulatory standards for asbestos detection, which will increase barriers to entry and consolidate market share.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Premium Grades | Supports automotive lightweighting and advanced polymer applications, securing market share with high-value products. |
| Advanced Asbestos Testing Protocol Implementation | Ensures regulatory compliance and consumer safety, critical for pharmaceutical and cosmetic market access. |
| R&D in Bioplastic Formulations | Unlocks new growth pathways by improving mechanical properties and processing of sustainable materials. |
| Strategic Partnerships for Multi-Source Procurement | Mitigates geopolitical supply risks and ensures consistent quality for global manufacturers. |
| Geographic Expansion into Emerging Industrial Hubs | Captures new volume demand from industrialization in regions like Southeast Asia and Latin America. |
Research Approach
Bottom-up end-use modeling for automotive lightweighting and cosmetic formulation reconciled against top-down supply-side tracking of talc mining and processing forms the analytical core. Primary interviews with talc producers, automotive OEM engineers, cosmetics R&D leads, and regulatory compliance officers informed market dynamics. Secondary validation drew from geological surveys, trade publications, company annual reports, and regulatory agency reports from the US FDA and ECHA.
Historical trendline analysis established foundational growth patterns across the analysis window. The forecast framework modeled market evolution across product type, application, form, end-user industry, and purity grade. Compound annual growth rates (CAGRs) were derived through regression analysis and assessment of market share shifts. Vehicle production forecasts and regulatory updates on asbestos served as key industry-specific forecast inputs.
The model assumes a particular technology adoption path for advanced surface modification in polymers; alternative pathways for Transmission Electron Microscopy adoption would alter the outlook. Forecasts reflect assumptions regarding regulatory stability and geopolitical conditions. Deviation in global industrial output or new asbestos litigation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Minerals
Europe Diatomite Market
Industrial Minerals
Micronized Salt Market
Industrial Minerals
Global Feed Minerals Market
Industrial Minerals
Potassium Schoenite Market
Industrial Minerals
United States Feed Minerals Market
Industrial Minerals
Anhydrite Market
Industrial Minerals
Unexpanded Perlite Market
Industrial Minerals
Fluorspar Market
Industrial Minerals
Global Epsom Salt Market
Industrial Minerals
Mineral Enrichment Ingredients Market
Industrial Minerals
Industrial Salts Market
Industrial Minerals
Industrial Sodium Chloride Market
Industrial Minerals
Global Cristobalite Market
Industrial Minerals
Inorganic Salts Market
Industrial Minerals
Europe Feed Minerals Market
Industrial Minerals
Olivine Sand Market