
 Gluconate Mineral Market | 2026-2036
Gluconate Mineral Market Size, Share, and Industry Trends Forecast 2026-2036
Gluconate Mineral Market Analytics
Sodium chloride in conventional mineral supplements is hardening demand for bioavailable gluconate alternatives across clinical nutrition. Jungbunzlauer AG leverages captive fermentation capacity in Europe to sustain supply security for pharmaceutical-grade calcium gluconate. Corbion N.V. anchors its position through backward integration into glucose feedstock and purification technology. FUSO Chemical dominates Asian supply chains for magnesium gluconate with dedicated bioreactor infrastructure.
Gluconate minerals are metal salts of gluconic acid produced through microbial fermentation of glucose, typically yielding chelated forms with 8-12% elemental mineral content and high water solubility for rapid physiological absorption. These compounds serve primarily as therapeutic agents for electrolyte correction and as fortified ingredients in functional foods. Zinc gluconate leads the product type category due to established use in immune-support formulations and dermatological applications. The nutraceuticals end-user segment represents the fastest-growing demand pool as consumers shift from synthetic mineral oxides toward organic salt forms with superior bioavailability. Powder formulations remain the dominant form for industrial buyers seeking blending flexibility in food fortification and animal nutrition premixes.
FDA regulations for pharmaceutical-grade mineral salts enforce USP monograph compliance and injectable purity standards, while EMA's MDR framework tightens traceability for mineral active substances in medical devices and combination products. China's NMPA requires registration of gluconate minerals as drug substances with documented fermentation source and residual solvent profiles. India's CDSCO mandates BIS certification for imported mineral salts used in tablet and liquid dosage forms. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and ChP standards to avoid dual-testing burdens and registration delays.
Market Dynamics
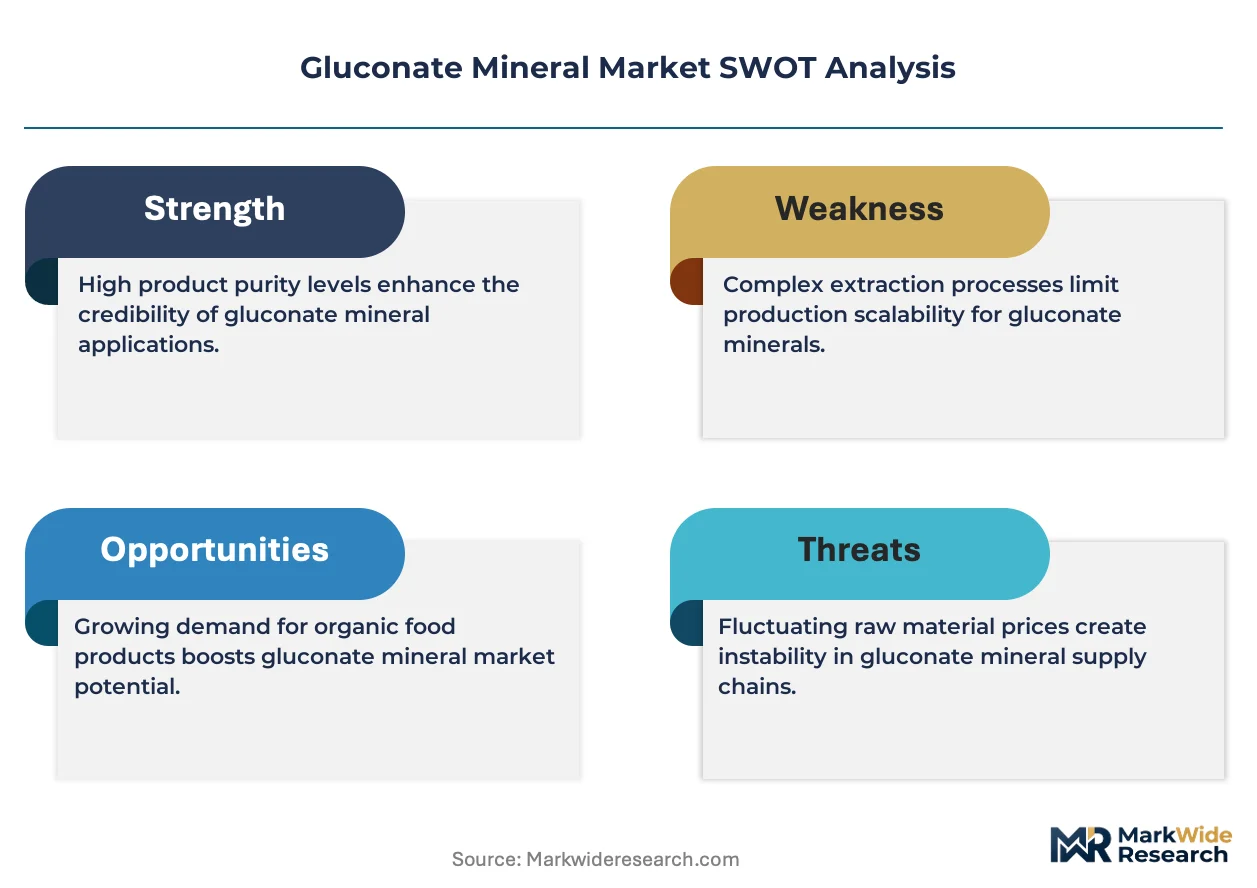
Fermentation capacity concentration in China is compressing regional cost structures and forcing Western suppliers to defend position through pharmaceutical-grade certification premiums rather than volume competition.
Growth Catalysts
- REACH Purity Benchmarks:Tightening ECHA requirements for mineral salts in human applications are disqualifying commodity-grade suppliers and expanding addressable market for certified producers.
- Clinical Nutrition Formulation:Parenteral nutrition solution manufacturers are expanding gluconate mineral use to replace sodium chloride in electrolyte correction protocols.
- Fermentation Scale Economics:China's bioreactor infrastructure concentration is driving unit cost reductions that accelerate nutraceutical adoption across Southeast Asian markets.
Market Restraints
- Glucose Feedstock Volatility:Corn and wheat-derived glucose price swings directly compress fermentation margins for European and North American producers lacking backward integration.
- Single-Geography Supply Risk:Magnesium gluconate production concentrates in Japanese and Chinese bioreactor clusters, creating vulnerability to regional energy or environmental policy disruptions.
- Mineral Oxide Substitution:Cheaper synthetic zinc oxide and magnesium oxide formulations retain cost advantage in animal feed premixes where bioavailability requirements remain permissive.
Strategic Opportunities
- Indian CDSCO Registration Pathway:BIS certification requirements for imported mineral salts create first-mover advantage for suppliers establishing local analytical partnerships and documentation capabilities.
- Medical Device Combination Products:EMA's MDR traceability mandates for mineral active substances in combination devices open premium pricing tiers for documented fermentation-source materials.
- Direct-to-Consumer Channel:E-commerce platforms specializing in practitioner-grade supplements are compressing traditional distributor margins and enabling brand building for certified organic salt forms.
Industry Challenges
- Pharmacopeial Harmonization Delays:Divergent USP, EP, and ChP residual solvent testing protocols force dual or triple analytical burdens, extending registration timelines and inflating quality assurance headcount.
- Bioreactor Contamination Control:Pharmaceutical-grade fermentation requires validated cleanroom infrastructure and specialized microbial strain management expertise that concentrates in limited talent pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gluconate Mineral Market |
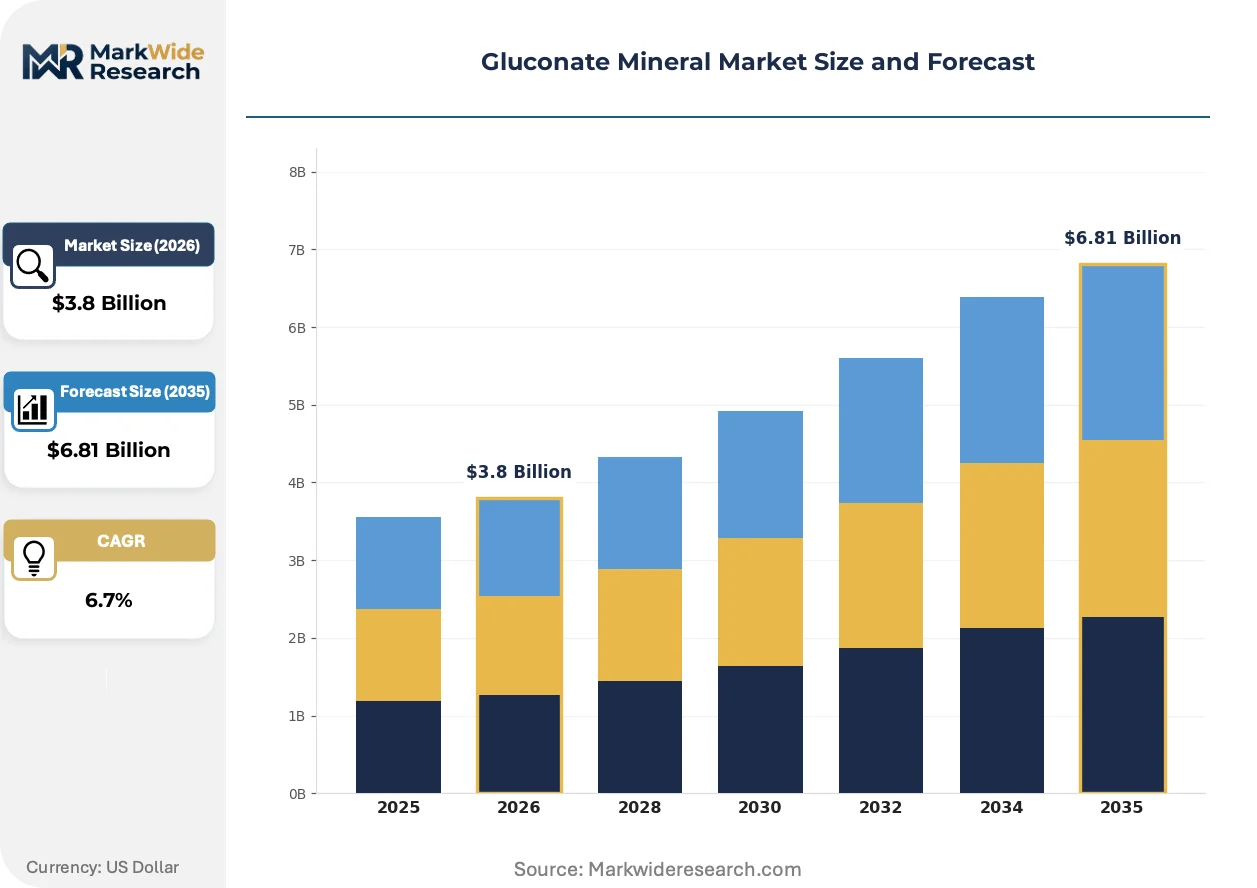
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calcium Gluconate, Magnesium Gluconate, Zinc Gluconate, Iron Gluconate End User: Food Industry, Pharmaceuticals, Nutraceuticals, Animal Feed Application: Deficiency Treatment, Nutritional Supplement, Food Fortification, Animal Nutrition Form: Powder, Granules, Tablets, Liquid |
| Companies Covered | Jungbunzlauer AG, Corbion N.V., Taizhou Yojoy Chemical Co., Ltd., FUSO Chemical, Ltd., Henan Kingsun Chemical Co., Ltd., Shandong Fuyang Bio-Tech Co., Ltd., Spectrum Chemical Manufacturing Corp., Dong Xiao Biotechnology Co., Ltd., Tomita Pharmaceutical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gluconate Mineral Market Evolving Landscape
Continuous processing technology and digital quality systems are compressing batch-to-batch variability and enabling real-time release testing for injectable-grade mineral salts.
Continuous fermentation monitoring with inline spectroscopy is integrating process analytical technology into gluconic acid production lines. Pharmaceutical contract manufacturers in Switzerland and Germany are adopting these systems to reduce offline testing delays. The technology is integrating quality assurance directly into production workflow, collapsing traditional batch release cycles from weeks to hours.
EMA's MDR framework is tightening traceability requirements for mineral active substances used in medical devices and combination products. Manufacturers must now document fermentation source, residual solvent profiles, and supply chain intermediaries for each lot. European orthopedic and wound care device producers are responding by consolidating supplier bases to those with validated documentation systems.
Practitioner-channel buyers are consolidating purchasing around suppliers offering combined mineral premix customization and regulatory documentation packages. Traditional ingredient distributors with limited technical service capabilities are losing share to vertically integrated formulators. This pattern concentrates in North American and Australian functional food markets where brand owners face accelerated product launch cycles.
Gluconate Mineral Market Segmentation
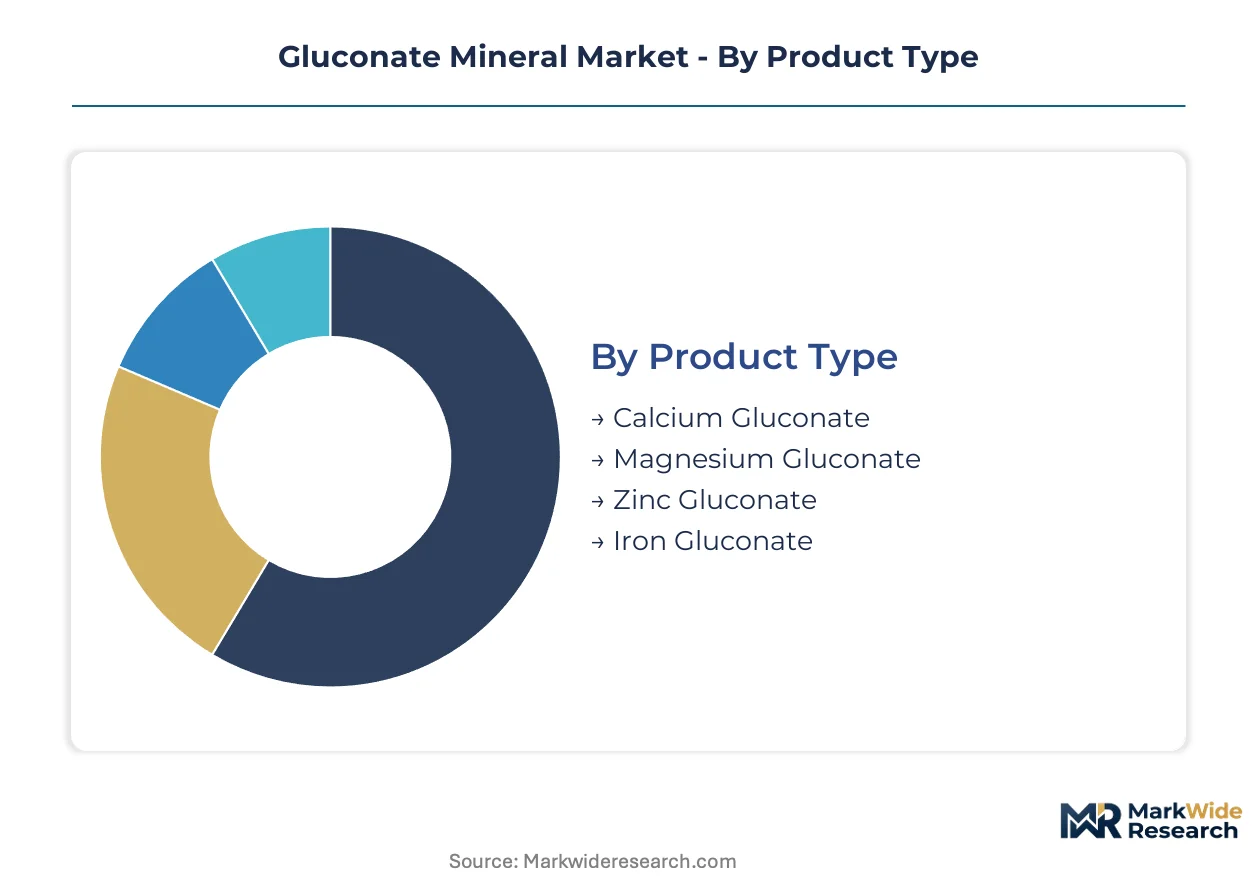
Gluconate mineral formulators prioritize segment-specific certification pathways and formulation requirements when allocating R&D investment. Each segmentation dimension carries distinct regulatory burdens and margin profiles that reshape supplier positioning.
Product Type:
Upgrade cycles in pharmaceutical-grade mineral salts are accelerating as parenteral nutrition protocols displace conventional electrolyte correction methods.
- Zinc Gluconate:Chelated zinc salt with 14% elemental content serves immune-support formulations and dermatological applications. Demand concentrates in practitioner-channel nutraceuticals across Germany and Switzerland, driven by consumer rejection of synthetic zinc oxide absorption rates.
- Calcium Gluconate:9% elemental calcium compound produced through validated fermentation delivers injectable-grade purity for clinical nutrition. Hospital procurement in France and Italy is expanding volumes for electrolyte correction protocols replacing sodium chloride.
- Magnesium Gluconate:5.5% elemental magnesium bioavailable salt targets functional food fortification.
- Iron Gluconate:Lower-concentration ferrous salt addresses deficiency treatment in pediatric and geriatric populations.
Volume placements concentrate in Calcium Gluconate; the faster expansion belongs to Zinc Gluconate.
End User:
Cost-tier stratification separates commodity animal feed buyers from premium pharmaceutical purchasers with divergent purity requirements.
- Nutraceuticals:Practitioner-grade supplement manufacturers specify organic salt forms with documented fermentation sources and residual solvent profiles. E-commerce direct-to-consumer channels in Australia and Canada are compressing traditional distributor margins for certified products.
- Pharmaceuticals:Parenteral solution and tablet formulators enforce USP monograph compliance and injectable purity standards. FDA and EMA traceability mandates for mineral active substances are consolidating supplier bases to documented fermentation-source producers.
- Food Industry:Functional food fortification buyers seek blending-flexible powder forms for beverage and bakery applications.
- Animal Feed:Premix compounders tolerate lower bioavailability requirements where synthetic mineral oxides retain cost advantage.
Pharmaceuticals commands the highest unit pricing tier; nutraceuticals is climbing the fastest.
Application:
Customer-type differentiation separates clinical protocol buyers from consumer self-directed purchasers with distinct documentation expectations.
- Deficiency Treatment:Therapeutic protocols for electrolyte correction and anemia management require pharmaceutical-grade certification and batch-level traceability. Hospital formularies in Spain and the Netherlands are standardizing on gluconate salts for reduced gastrointestinal irritation versus inorganic alternatives.
- Nutritional Supplement:Daily-use mineral supplementation in capsule and tablet formats prioritizes consumer-perceived bioavailability and clean-label positioning.
- Food Fortification:Industrial-scale blending into flour, dairy, and beverage matrices demands water-soluble powder with consistent particle size distribution.
- Animal Nutrition:Livestock and aquaculture premixes emphasize cost-per-unit-elemental-mineral over absorption efficiency metrics.
Food fortification maintains the largest shipment volumes; nutritional supplement is expanding most quickly.
Form:
Supply concentration in fermentation-derived powder creates downstream processing economics that favor granule and tablet conversion near end-use markets.
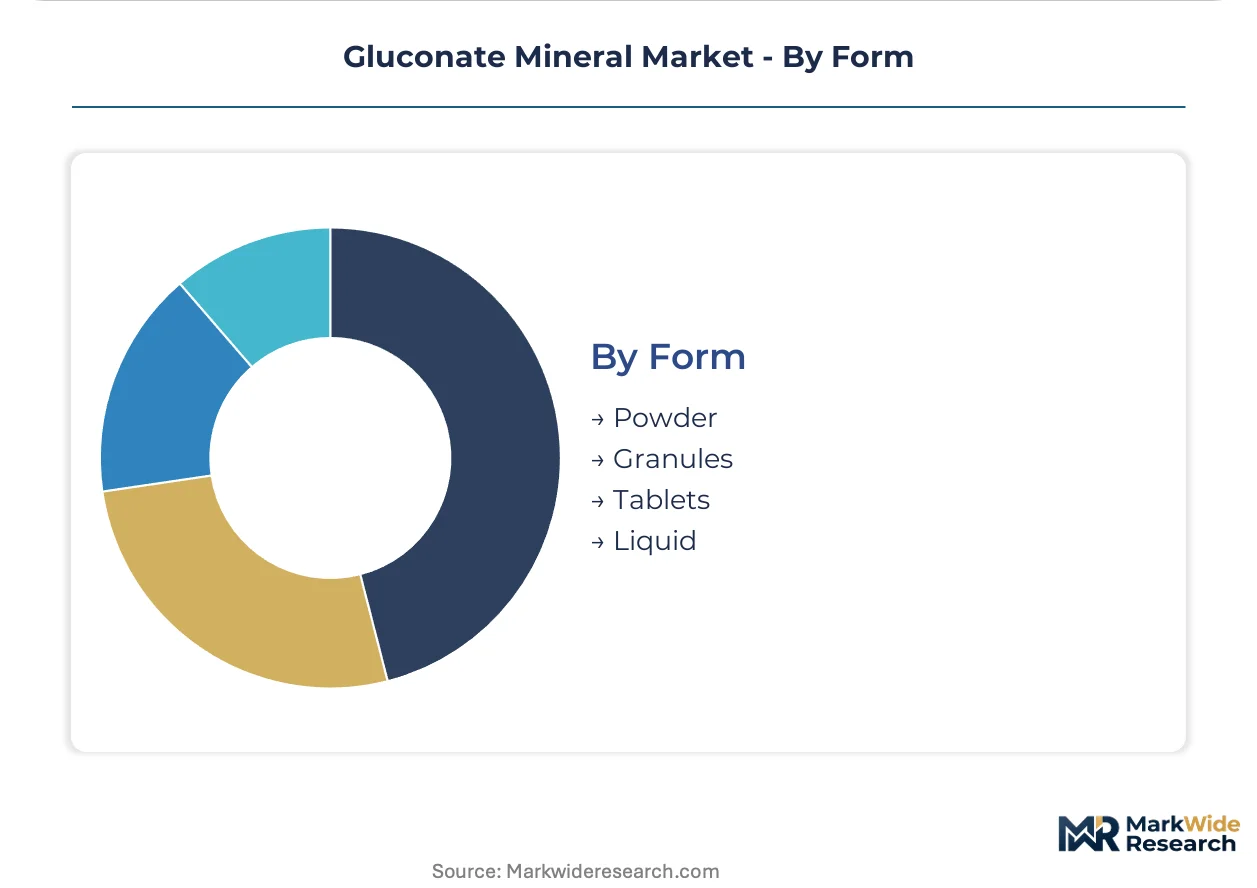
- Powder:Spray-dried crystalline product with 95%+ purity serves industrial buyers seeking blending flexibility in food fortification and premix manufacturing. China's fermentation infrastructure concentration is compressing export pricing for commodity-grade powder.
- Liquid:Aqueous solutions with stabilized pH enable direct incorporation into parenteral nutrition bags and ready-to-drink functional beverages. Swiss and German contract manufacturers are adopting continuous processing technology with inline spectroscopy for real-time release testing.
- Granules:Agglomerated powder improves flowability for high-speed tablet compression operations.
- Tablets:Finished dosage forms require excipient compatibility testing and dissolution profile validation.
Powder captures the dominant production share; liquid is gaining share fastest in pharmaceutical applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates fermentation-based production infrastructure, while pharmaceutical-grade demand clusters in Western Europe and North American clinical nutrition markets. Regulatory divergence between USP, EP, and ChP standards shapes supplier qualification requirements across jurisdictions.
China
NMPA registration mandates documented fermentation sources and residual solvent profiles for drug-grade mineral salts. Bioreactor infrastructure in Jiangsu and Shandong provinces drives unit cost compression for commodity-grade gluconate powders. Taizhou and Zhengzhou chemical clusters anchor Asian supply chains with dedicated glucose feedstock integration.
United States
FDA enforces USP monograph compliance and injectable purity standards for parenteral nutrition applications. Hospital procurement expansion in California and Texas accelerates electrolyte correction protocol updates. New Jersey and Pennsylvania pharmaceutical corridors concentrate formulation expertise for clinical-grade mineral salts.
Germany
EMA's MDR framework tightens traceability mandates for mineral active substances in medical devices. REACH compliance requirements under ECHA disqualify commodity-grade suppliers from human applications. Bavarian and North Rhine-Westphalian chemical clusters specialize in continuous processing technology with inline spectroscopy.
India
CDSCO mandates BIS certification for imported mineral salts in tablet and liquid dosage forms. Nutraceutical channel expansion in Maharashtra and Gujarat creates first-mover opportunities for documented suppliers. Mumbai-Pune pharmaceutical belt concentrates formulation demand for pediatric and geriatric deficiency treatments.
Japan
PMDA oversight of pharmaceutical-grade mineral salts aligns with ICH quality guidelines for fermentation-derived materials. Magnesium gluconate production concentrates in Osaka-Kobe industrial zones with specialized bioreactor infrastructure. Tokyo-based contract manufacturers adopt real-time release testing for injectable-grade specifications.
Gluconate Mineral Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with fermentation-scale players dominating commodity powder supply and pharmaceutical-certification holders capturing premium-tier pricing. The vendor base organizes around three archetypes: captive-fermentation multinationals, regional glucose-integrated producers, and pharmaceutical-grade contract manufacturers. Capacity expansion and backward integration into glucose feedstock represent the dominant competitive vectors.
Within the captive-fermentation tier, Jungbunzlauer AG and Corbion N.V. exemplify European suppliers defending position through pharmaceutical-grade certification premiums rather than volume competition. FUSO Chemical occupies a position among Asian bioreactor specialists with dedicated infrastructure for magnesium gluconate. These three anchors illustrate how geographic concentration in fermentation capacity compresses regional cost structures while creating qualification barriers for Western market entry.
| Leading Market Players |
|---|
| Jungbunzlauer AG |
| Corbion N.V. |
| Taizhou Yojoy Chemical Co., Ltd. |
| FUSO Chemical, Ltd. |
| Henan Kingsun Chemical Co., Ltd. |
| Shandong Fuyang Bio-Tech Co., Ltd. |
| Spectrum Chemical Manufacturing Corp. |
| Dong Xiao Biotechnology Co., Ltd. |
| Tomita Pharmaceutical Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Validated cleanroom fermentation specialists in Bavaria and North Rhine-Westphalia command wage premiums that widen spreads between pharmaceutical-grade and commodity-grade mineral salt pricing tiers. Labor-cost differentials between European certified producers and Asian bioreactor clusters compound with glucose feedstock integration advantages to stratify market access economics.
Pricing Analysis
Volume placements concentrate in commodity-grade powder exports from Chinese fermentation clusters, while margin capture belongs to injectable-grade certification holders in Switzerland and Germany. Three-tier pricing structure across pharmaceutical, food-grade, and feed-grade certification levels separates buyers by purity documentation requirements. Pricing pressure stems from corn and wheat-derived glucose volatility compressing European producer margins lacking backward integration into feedstock supply. Animal feed premix compounders exhibit highest price sensitivity, whereas parenteral nutrition formulators prioritize batch traceability over unit cost.
Supply Chain Analysis
Pharmaceutical-grade qualification gating through USP, EP, and ChP residual solvent protocols restricts supplier eligibility to documented fermentation-source producers. Supply concentrates in Chinese bioreactor infrastructure across Jiangsu and Shandong provinces, with Japanese Osaka-Kobe clusters anchoring magnesium gluconate specialization. Raw material dependencies center on corn-derived glucose, pharmaceutical-grade calcium carbonate, and specialized microbial strains for fermentation initiation. Single-geography concentration in Asian bioreactor capacity creates vulnerability to regional energy policy or environmental compliance disruptions. Distribution runs through pharmaceutical contract manufacturers in Switzerland and Germany for premium tiers, with commodity powder flowing through bulk chemical traders serving food and feed compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical-grade fermentation capacity scarcity props pricing premiums, as validated cleanroom infrastructure and microbial strain management expertise concentrate in limited European and Japanese talent pools. Supply constraints in certified production create durable margin protection for incumbent qualification holders.
For Market Incumbents: Anticipate REACH compliance tightening and EMA MDR traceability mandates by consolidating documentation systems and deepening captive glucose feedstock integration. Defensive moves should center on real-time release testing adoption to collapse batch validation cycles, while capacity addition in Swiss and German pharmaceutical corridors reinforces proximity to parenteral nutrition formulators. Mineral oxide substitution in animal feed premixes represents a persistent volume threat requiring tiered customer segmentation. For New Entrants and Emerging Players: E-commerce practitioner-channel platforms offer the most penetrable route for certified organic salt forms, as traditional distributor margins compress in Australian and Canadian direct-to-consumer markets. White-space targets include Indian CDSCO registration pathways for BIS-certified imports and medical device combination product documentation for European orthopedic device producers. A go-to-market angle anchored in combined mineral premix customization with regulatory documentation packages addresses brand owner acceleration demands. For Investors and Strategic Acquirers: The window for entry favors fermentation-scale players with existing glucose backward integration and pharmaceutical-grade certification infrastructure. Long-term viability hinges on pharmacopeial harmonization convergence reducing dual-testing burdens for multinational suppliers. Acquisition target archetypes include regional glucose-integrated producers with latent pharmaceutical-certification potential. The signal to watch is CDSCO registration completion rates for imported mineral salts, indicating first-mover documentation capability establishment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Glucose Feedstock | Captive corn-derived glucose supply insulates Jungbunzlauer and Corbion from commodity volatility compressing European fermentation margins. |
| Pharmaceutical-Grade Certification Investment | USP monograph compliance and injectable purity standards unlock parenteral nutrition procurement in California and Texas hospital systems. |
| Continuous Processing Technology Adoption | Inline spectroscopy integration at Swiss and German contract manufacturers collapses batch release cycles from weeks to hours. |
| Indian CDSCO Registration Pathway | BIS certification for imported mineral salts creates first-mover advantage in Maharashtra and Gujarat nutraceutical channel expansion. |
| Medical Device Combination Product Documentation | EMA MDR traceability mandates for mineral active substances open premium pricing tiers in European orthopedic and wound care device supply. |
Research Methodology
Trade flow databases, pharmacopeial monograph repositories, and fermentation industry technical literature formed the secondary backbone for supply-side capacity mapping. Primary interviews with pharmaceutical formulation executives, nutraceutical brand managers, CDSCO regulatory consultants, and hospital procurement directors in France, Italy, and the Netherlands validated demand-side assumptions. Bottom-up and top-down triangulation reconciled bioreactor capacity estimates with end-user volume placements across parenteral nutrition and functional food channels.
Bottom-up modeling anchored volume projections in segment-specific adoption curves, while top-down cross-checks validated aggregate market sizing against glucose feedstock consumption patterns. Segmentation dimensions spanned product type, end-user industry, application protocol, and geographic regulatory cluster. CAGRs were derived from fitted growth curves applied to validated base-year estimates, with industry-specific inputs including REACH compliance timelines, NMPA registration processing rates, and parenteral nutrition protocol update frequencies across European hospital formularies.
The model holds under stable pharmacopeial harmonization progress and continued glucose feedstock availability; deviation in fermentation input costs or regulatory registration delays would shift volume and value trajectories. Forecasts reflect documented assumptions regarding certification pathway durations and bioreactor capacity expansion schedules. A model refresh is warranted upon material change in EMA MDR enforcement intensity or Chinese environmental policy affecting Jiangsu and Shandong province production permits.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Minerals
Industrial Salts Market
Industrial Minerals
Mineral Adsorbent Market
Industrial Minerals
Aluminium Potassium Sulphate Market
Industrial Minerals
Chelated Minerals Market
Industrial Minerals
Strategic Mineral Materials Market
Industrial Minerals
Industrial Garnet Market
Industrial Minerals
Pyrophyllite Market
Industrial Minerals
Boron Minerals and Chemicals Market
Industrial Minerals
Mineral Wool Material Market
Industrial Minerals
Nepheline Market
Industrial Minerals
Global Carbonate Minerals Market
Industrial Minerals
Calcined Anthracite Market
Industrial Minerals
Barite Mining Market
Industrial Minerals
Industrial Diamond Market
Industrial Minerals
Global Cristobalite Market
Industrial Minerals
Mineral Sand Market