
 Micronized Salt Market | 2026-2036
Micronized Salt Market Size, Share, and Industry Trends Forecast 2026-2036
Micronized Salt Market Outlook
North American solar evaporation capacity is consolidating as producers rationalize harvesting operations across the Great Salt Lake and San Francisco Bay corridors. Cargill, Incorporated leverages its integrated logistics network to supply food manufacturers with consistent particle-size micronized salt. K+S Aktiengesellschaft anchors European pharmaceutical-grade output through controlled crystallization assets in Germany. Compass Minerals dominates seasonal de-icing demand but extends its micronized capabilities into water treatment applications through Utah-based processing infrastructure.
Micronized salt consists of sodium chloride particles typically milled to sub-100-micron diameters, achieving rapid dissolution and homogeneous distribution in formulations where standard granular salt creates texture defects or uneven flavor delivery. The milling process employs roller mills, air classification, or crystallization control to achieve tight particle-size distributions with minimal insoluble residue. Sea Salt and Rock Salt product categories lead volume, though pharmaceutical-grade micronized salt commands the strongest margin pool due to USP and EP compliance burdens. Food Processing applications absorb the largest share of tonnage, while Water Treatment represents the fastest-growing demand channel as municipalities adopt advanced softening and disinfection protocols requiring precise salt dosing.
FDA food additive regulations and USP monographs govern purity thresholds and heavy-metal limits for micronized salt entering pharmaceutical and food channels, while the EPA Safe Drinking Water Act shapes specifications for municipal water treatment applications. ISO 22000 and HACCP frameworks further constrain processor operations, raising compliance costs for smaller mills and favoring scaled producers with dedicated quality laboratories. Stakeholders must monitor evolving pharmaceutical excipient standards and regional water infrastructure investment cycles to align capacity with specification-intensive segments.
Market Dynamics
Food-grade purity mandates from FDA and FSSAI are compressing supplier margins while concentrating procurement among scaled mills with captive laboratory infrastructure.
Growth Catalysts
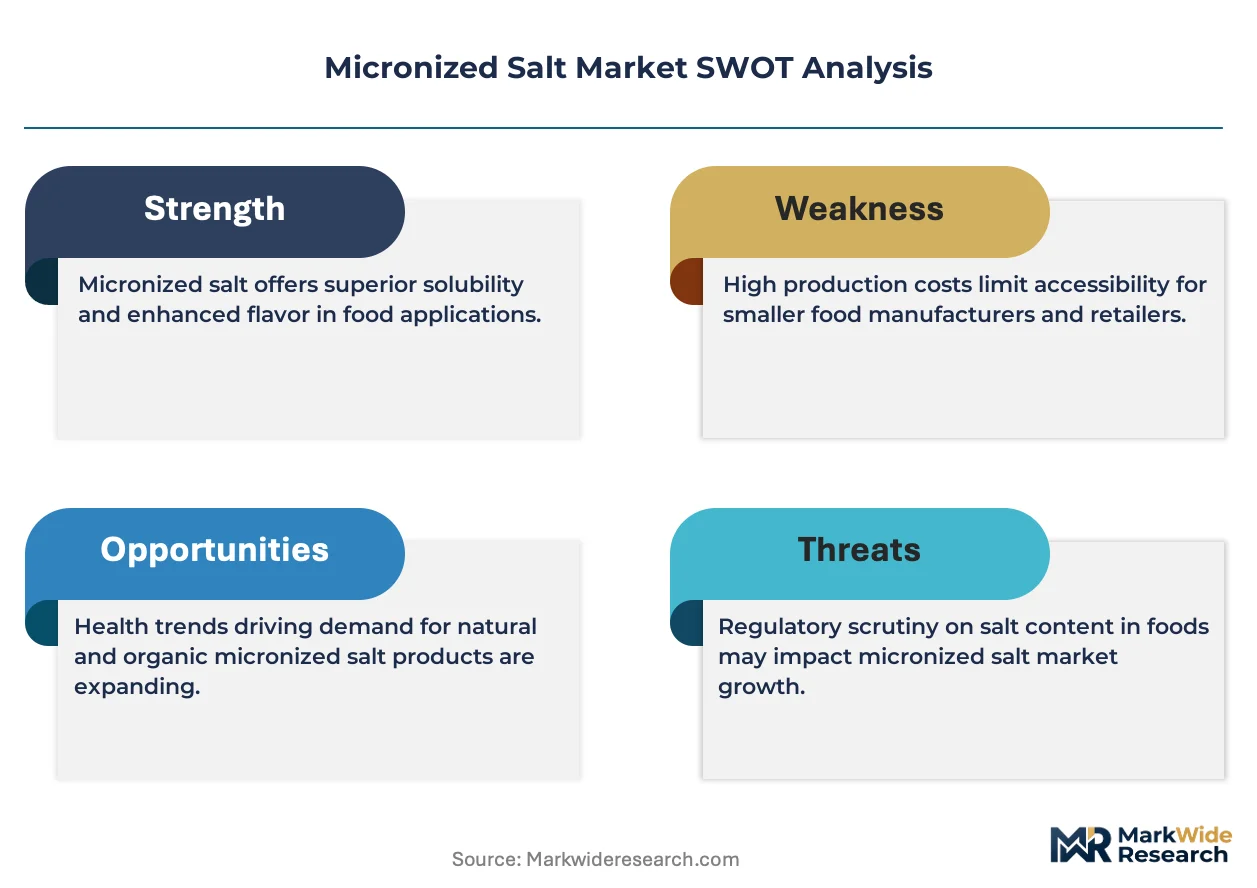
- Particle engineering advances:Air classification systems now achieve sub-50-micron distributions with minimal insoluble residue, opening formulation flexibility for pharmaceutical excipients.
- Water infrastructure mandates:EPA Safe Drinking Water Act amendments drive municipal adoption of precision-dosed softening salts across Midwestern and Southeastern treatment facilities.
- India:PLI scheme incentives for pharmaceutical manufacturing are pulling micronized sodium chloride demand toward domestic processors serving CDSCO-regulated facilities.
Market Restraints
- Energy cost volatility:Thermal evaporation and milling operations expose processors to natural gas price swings, particularly affecting Great Salt Lake corridor harvesters.
- Supply concentration:Solar evaporation capacity consolidation across Utah and California creates single-source vulnerability for North American food manufacturers.
- Substitution pressure:Potassium chloride blends and yeast extracts are displacing sodium chloride in reduced-sodium processed food formulations.
Strategic Opportunities
- Pharmaceutical-grade expansion:USP and EP compliance capabilities command 40-60% margin premiums over food-grade output, rewarding dedicated crystallization assets.
- Direct-to-formulator channels:E-commerce platforms and technical service partnerships are shortening procurement cycles for mid-sized specialty chemical buyers.
- Water treatment protocols:Advanced disinfection byproduct control regulations in Germany and France are creating specification-intensive demand for ultra-pure micronized salt.
Industry Challenges
- Certification timeline compression:ISO 22000 and HACCP audit backlogs are extending qualification periods for new supplier entry into pharmaceutical channels.
- Crystallization expertise scarcity:Process engineers capable of controlling nucleation kinetics for tight particle-size distributions command premium compensation, constraining capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Micronized Salt Market |
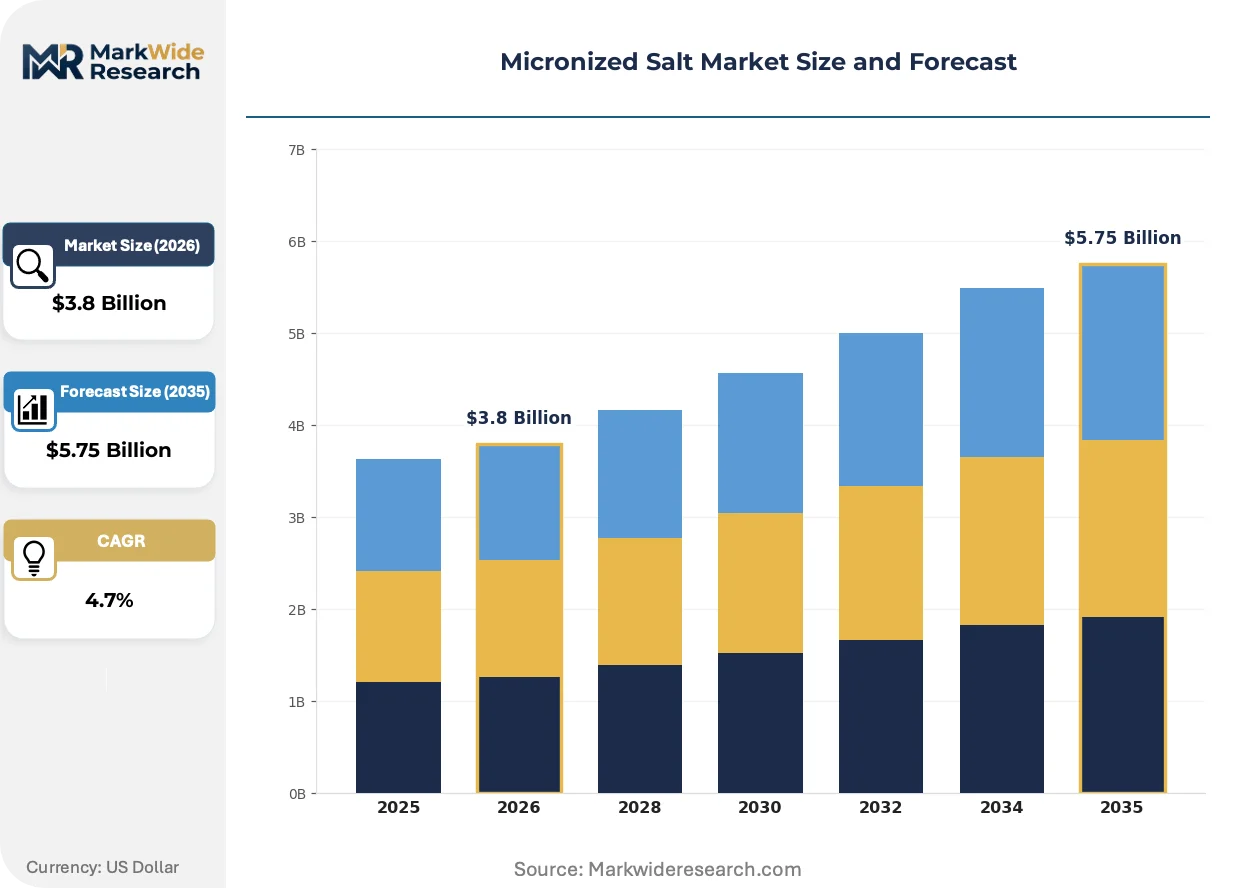
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sea Salt, Table Salt, Rock Salt, Flavored Salt Application: Food Processing, Pharmaceuticals, Cosmetics, Water Treatment Packaging Type: Bags, Boxes, Bulk Containers, Pouches End User: Household, Restaurants, Industrial, Food Manufacturers |
| Companies Covered | Cargill, Incorporated, K+S Aktiengesellschaft, Tata Chemicals Ltd., Morton Salt, Inc., Compass Minerals, Akzo Nobel N.V., INEOS AG, Dominion Salt Limited, Israel Chemicals Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Micronized Salt Market Strategic Shifts
Precision milling and real-time particle characterization are collapsing the gap between commodity salt production and specialty chemical specifications.
Continuous crystallization with inline laser diffraction monitoring is decentralizing quality control from centralized laboratories to production lines. Pharmaceutical formulators in Switzerland and Germany are adopting these systems to compress batch release timelines. The technology is decentralizing supply chain power toward integrated manufacturers capable of certificate-of-analysis automation.
REACH Annex XVII restrictions on heavy-metal contaminants are tightening impurity thresholds for salt entering EU cosmetic and pharmaceutical channels. German processors are retrofitting crystallization assets with membrane filtration to meet ECHA-mandated cadmium and lead limits. The regulation is compressing viable supplier pools to scaled operators with dedicated purification infrastructure.
Formulator technical service integration is replacing transactional spot purchasing in North American food processing. Procurement teams at mid-sized bakeries and seasoning blenders are contracting directly with salt mills for customized granulation and joint formulation development. The shift is most visible in California and Illinois, where processor consolidation has reduced qualified supplier counts.
Micronized Salt Market Segmentation
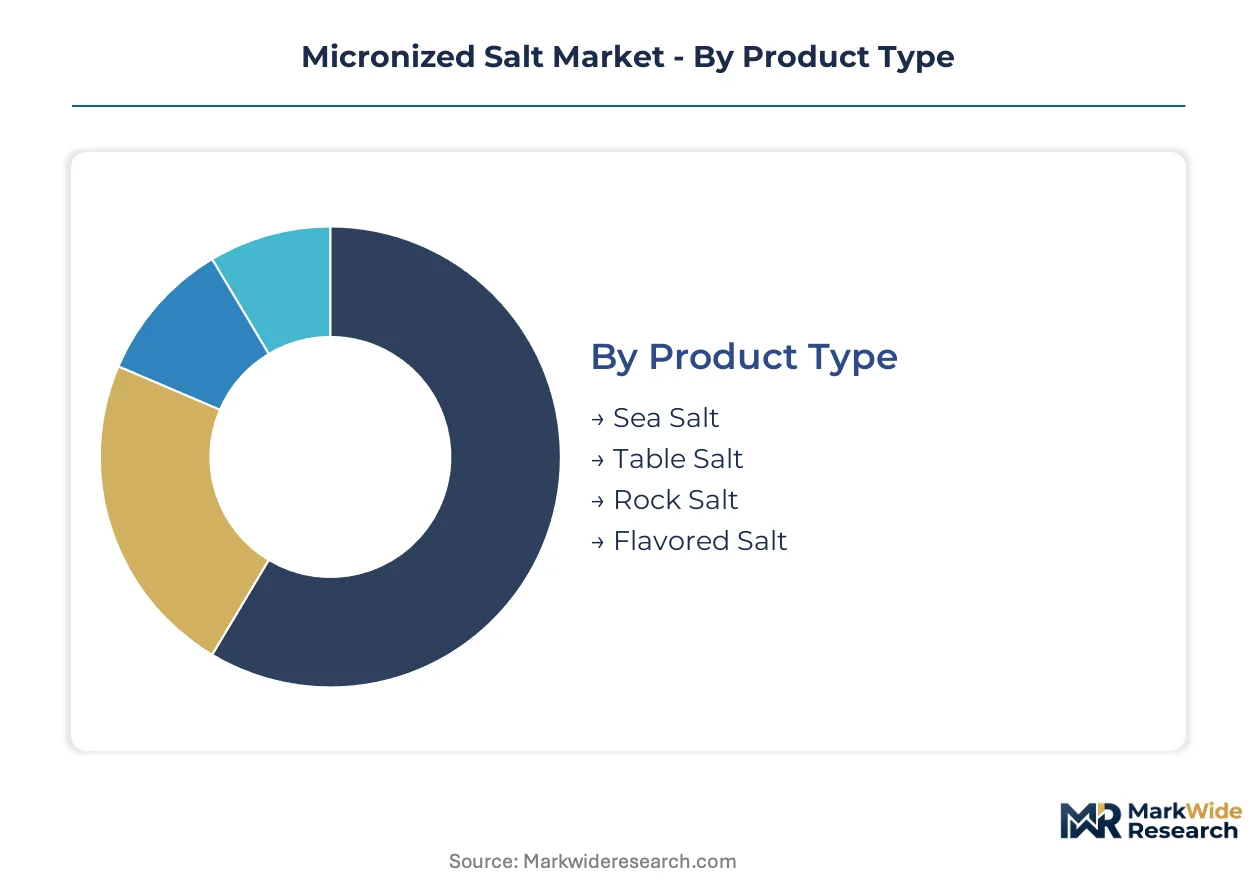
Segmentation in the micronized salt market determines specification intensity, regulatory burden, and margin capture. Product origin dictates dissolution kinetics and impurity profiles, while application channels impose divergent certification requirements.
Product Type:
Customization intensity ranges from commodity milling to crystallization-controlled pharmaceutical grades, with purity thresholds and particle engineering depth separating tiers.
- Sea Salt:Solar-evaporated sodium chloride retains trace minerals and magnesium compounds that accelerate dissolution in beverage formulations. Food manufacturers in coastal processing corridors specify sea salt for clean-label positioning, though harvest variability complicates particle-size consistency.
- Rock Salt:Underground-mined halite undergoes mechanical milling to sub-100-micron specifications without thermal processing, preserving crystalline structure for controlled-release pharmaceutical tablets. Mined deposits in Germany and Pakistan supply CDSCO-regulated facilities with low-bromide feedstock.
- Table Salt:Vacuum-evaporated refined salt achieves highest purity for household iodization programs.
- Flavored Salt:Micronized carriers infused with yeast extracts or herb compounds serve reduced-sodium seasoning blends.
Most installed capacity flows through Rock Salt. Expansion is steepest in Sea Salt.
Application:
Volume concentration versus margin intensity defines this split, with tonnage-heavy food channels diverging from specification-intensive pharmaceutical and water treatment segments.
- Food Processing:Uniform particle distribution prevents clumping in seasoning blends and ensures rapid dissolution in instant soup matrices. Bakeries and snack manufacturers in Illinois and California contract directly with mills for customized granulation.
- Water Treatment:Municipal softening and disinfection protocols demand precise dosing of ultra-pure sodium chloride to control disinfection byproduct formation. EPA Safe Drinking Water Act amendments are pulling demand toward specification-intensive grades across Midwestern treatment facilities.
- Pharmaceuticals:USP and EP compliance requirements govern excipient-grade output for tablet diluents and dialysis solutions.
- Cosmetics:REACH Annex XVII heavy-metal limits constrain salt entering exfoliant and bath formulations.
Food Processing absorbs the largest volume share. Pharmaceuticals command the steepest margin expansion trajectory.
Packaging Type:
Supply chain configuration spans bulk industrial logistics through retail-ready formats, with contamination risk and handling automation driving format selection.
- Bulk Containers:Food-grade lined totes and silo deliveries serve high-volume seasoning blenders with automated pneumatic conveying. Industrial bakeries in the Midwest specify bulk to minimize handling contamination.
- Bags:Multi-wall paper and woven polypropylene formats balance moisture protection with palletization efficiency for mid-tier food manufacturers.
- Boxes:Retail-facing cartons with pour spouts target household and restaurant segments.
- Pouches:Flexible packaging with resealable closures serves single-serve and sample applications.
Food Manufacturers drive Bulk Container procurement. Pouches are gaining share fastest in specialty and direct-to-consumer channels.
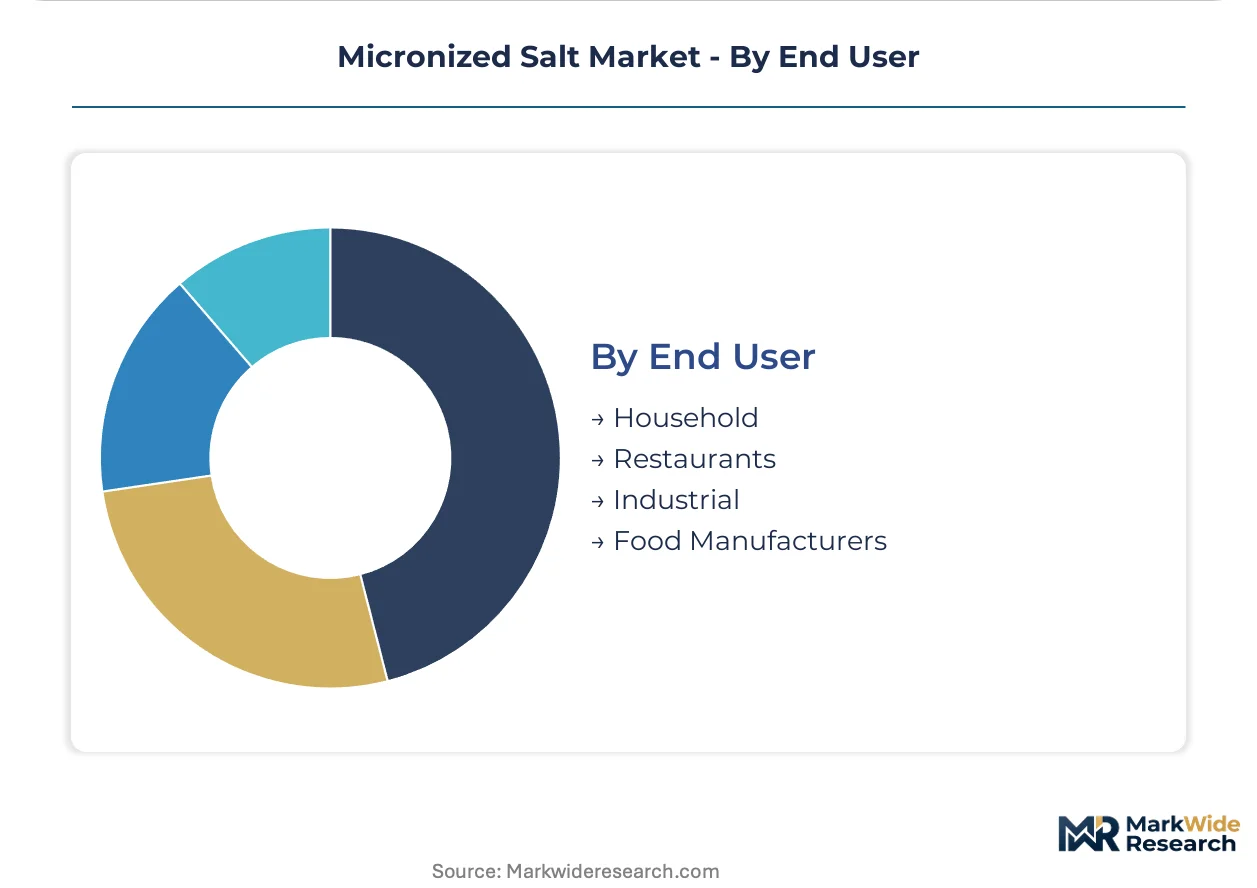
End User:
Procurement sophistication separates price-sensitive household buyers from technically demanding industrial accounts with captive laboratory requirements.
- Food Manufacturers:Scaled processors specify tight particle-size distributions and certificate-of-analysis automation to compress batch release timelines. Direct mill partnerships are replacing distributor intermediation for mid-sized accounts.
- Industrial:Water treatment utilities and chemical processors require USP or technical-grade documentation with each delivery. Municipal procurement cycles in Germany and France are tightening specification windows for softening salt.
- Restaurants:Foodservice distributors supply finished seasoning and finishing salt blends.
- Household:Retail channels deliver iodized table salt for consumer pantry replenishment.
Industrial accounts command the most intensive technical service relationships. Food Manufacturers represent the steepest volume expansion path.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting micronized salt production toward jurisdictions with lower compliance-cost burdens, even as end-use demand concentrates in specification-intensive markets. Producers balance FDA and ECHA purity mandates against energy and labor arbitrage in solar evaporation zones.
United States
Food manufacturers in Illinois and California drive specification-intensive procurement for uniform dissolution in processed foods. EPA Safe Drinking Water Act amendments pull municipal utilities toward precision-dosed softening salts across Midwestern treatment facilities. Great Salt Lake corridor harvesters consolidate operations as solar evaporation capacity rationalizes.
Germany
Pharmaceutical formulators in Switzerland and Germany adopt continuous crystallization with inline laser diffraction monitoring to compress batch release timelines. REACH Annex XVII restrictions on heavy-metal contaminants tighten impurity thresholds for salt entering cosmetic and pharmaceutical channels. German processors retrofit crystallization assets with membrane filtration to meet ECHA-mandated cadmium and lead limits.
India
PLI scheme incentives for pharmaceutical manufacturing pull micronized sodium chloride demand toward domestic processors serving CDSCO-regulated facilities. FSSAI food-grade purity requirements tighten specifications for particle size distribution and contaminant thresholds. Tata Chemicals and domestic processors in Gujarat and Maharashtra serve pharmaceutical and food processing customers with customized granulation.
China
Dual carbon goals and energy efficiency mandates reshape thermal evaporation economics for vacuum-refined salt output. NMPA pharmaceutical excipient standards align with USP and EP compliance frameworks for export-oriented producers. Yangtze River Delta processors invest in air classification systems for sub-50-micron distributions.
France
Advanced disinfection byproduct control regulations create specification-intensive demand for ultra-pure micronized salt in municipal water treatment. ANSM pharmaceutical standards govern excipient-grade output for tablet diluents. Processors in the Hauts-de-France region supply water treatment utilities with certificate-of-analysis automation.
Micronized Salt Market Competitive Environment
North American producers anchor the scale-driven tier; European specialists hold the specification-intensive premium segment. The vendor base splits between consolidated solar evaporation operators with captive logistics networks and regional mills serving technical-grade niches. Three archetypes dominate: integrated agribusiness conglomerates with salt-as-commodity positioning, dedicated minerals processors with crystallization expertise, and regional specialists with customized granulation capabilities. Competitive moves center on M&A-driven consolidation of harvesting assets and direct-to-formulator channel expansion bypassing distributor intermediation.
Among integrated agribusiness conglomerates, Cargill, Incorporated exemplifies the scale-driven archetype with captive logistics infrastructure. K+S Aktiengesellschaft occupies a position within the European pharmaceutical-grade tier, while Tata Chemicals Ltd. anchors the India-centric customized granulation segment. These three entities represent divergent strategic postures: continental supply security, specification-intensive premium positioning, and emerging-market technical service integration.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| K+S Aktiengesellschaft |
| Tata Chemicals Ltd. |
| Morton Salt, Inc. |
| Compass Minerals |
| Akzo Nobel N.V. |
| INEOS AG |
| Dominion Salt Limited |
| Israel Chemicals Ltd. |
| Others |
Value Chain & Pricing Dynamics
Process engineers capable of controlling nucleation kinetics for tight particle-size distributions concentrate in Germany's chemical processing corridor, and their premium compensation requirements widen spreads between pharmaceutical-grade and commodity food-grade pricing tiers.
Pricing Analysis
Distributor margin compression in North American food channels is accelerating direct mill relationships. Three-tier pricing structure across USP-certified pharmaceutical, food-grade standard, and bulk industrial economy levels separates margin pools by certification burden. Pricing pressure stems from energy cost volatility affecting Great Salt Lake solar evaporation operations. Mid-sized seasoning blenders exhibit highest price sensitivity; pharmaceutical formulators accept premium positioning for batch release automation.
Supply Chain Analysis
Reverse-logistics flows for bulk container returns and tote refurbishment concentrate value recovery in Midwestern industrial bakery clusters. Primary supply draws from the United States, Germany, and India for crystallization-controlled output. Raw material dependencies center on halite deposits, natural gas for thermal processing, and iodine premix for fortification. Single-source vulnerability runs through Utah and California solar evaporation corridors. Distribution runs through direct mill partnerships bypassing traditional chemical distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical-grade margin expansion justifies crystallization asset investment as energy efficiency mandates compress commodity tier economics.
For Market Incumbents: To counter potassium chloride substitution in reduced-sodium formulations, backward integration into captive iodine premix supply secures fortification economics, while membrane filtration retrofitting captures REACH Annex XVII compliance premiums in EU cosmetic channels. For New Entrants and Emerging Players: Regional water treatment utilities in France and Germany present the most penetrable white-space target, with municipal procurement cycles tightening specification windows for ultra-pure softening salt. Technical service partnerships with mid-sized formulators compress qualification timelines versus scaled incumbent channels. For Investors and Strategic Acquirers: Dedicated minerals processors with crystallization expertise are the most active acquirer in this space, consolidating harvesting assets to anchor supply security. Long-term viability frames around water infrastructure investment cycles and pharmaceutical excipient standard harmonization. The signal to watch is EPA Safe Drinking Water Act amendment pacing across Midwestern treatment facilities.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Crystallization Deployment | Inline laser diffraction monitoring compresses pharmaceutical batch release timelines in Switzerland and Germany. |
| Membrane Filtration Retrofit | ECHA-mandated cadmium and lead limits in REACH Annex XVII tighten viable supplier pools to scaled operators. |
| Direct-to-Formulator Channel Expansion | California and Illinois processor consolidation reduces qualified supplier counts, shortening procurement cycles. |
| PLI Scheme Alignment | CDSCO-regulated pharmaceutical manufacturing in Gujarat and Maharashtra pulls demand toward domestic processors. |
| Water Treatment Protocol Certification | Advanced disinfection byproduct control regulations in France and Germany create specification-intensive demand. |
Study Parameters
Bottom-up food processing and pharmaceutical formulation modeling reconciled against top-down solar evaporation and mining capacity tracking forms the analytical core. Primary interviews with plant managers at Midwestern industrial bakeries, procurement leads at seasoning blenders, technical R&D directors at crystallization facilities, and regulatory affairs specialists at CDSCO-regulated sites combined with secondary validation from FDA food additive regulations, USP monograph databases, ECHA REACH filings, and FSSAI purity standards. Triangulation across these sources anchors volume and value estimates.
Historical trendline analysis of particle engineering adoption, certification timeline compression, and channel structure evolution informs the projection framework. Segmentation dimensions span product origin type, application channel, packaging format, and end-user procurement sophistication. CAGRs derive from regression against water infrastructure investment cycles, pharmaceutical manufacturing incentive schemes, and energy cost trajectory assumptions. Industry-specific inputs include municipal softening salt specification tightening and continuous crystallization technology diffusion curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to natural gas price volatility, regulatory harmonization pacing between USP and EP standards, and substitution technology advancement in reduced-sodium formulations. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Minerals
Aluminium Potassium Sulphate Market
Industrial Minerals
Limestone Mill Market
Industrial Minerals
Global Feed Minerals Market
Industrial Minerals
Industrial Sodium Chloride Market
Industrial Minerals
Industrial Diamond Market
Industrial Minerals
Europe Frac Sand Market
Industrial Minerals
Asia Pacific Bentonite Market
Industrial Minerals
Nepheline Market
Industrial Minerals
Middle East Feed Minerals Market
Industrial Minerals
Oman Industrial Salts Market
Industrial Minerals
Bentonite Market
Industrial Minerals
United States Feed Minerals Market
Industrial Minerals
Talc Market
Industrial Minerals
Mineral Wool Material Market
Industrial Minerals
Industrial Garnet Market
Industrial Minerals
Mediterranean Sea Salt Micro-Mineral Complexes Market