
 Chelated Minerals Market | 2026-2036
Chelated Minerals Market Size, Share, and Industry Trends Forecast 2026-2036
Chelated Minerals Market Analysis
The capital-intensity gap between integrated multinationals and regional blenders is collapsing as automated chelation reactor technology becomes commoditized. Kemin Industries leverages its captive lysine and methionine platforms to bundle amino acid chelates with vitamin premixes. BASF SE anchors European supply through backward integration into ethylenediaminetetraacetic acid intermediates. Zinpro Corporation specializes in performance trace mineral programs, dominating the dairy nutrition channel with research-backed absorption claims.
Chelated minerals are metal ions bound to organic ligands such as amino acids or hydroxycarboxylic acids, forming stable ring structures that resist antagonistic interactions in the gastrointestinal tract and improve cellular uptake efficiency. The chelation process typically employs glycine or methionine at defined metal-to-ligand ratios under controlled pH and temperature conditions to ensure consistent stability constants. Zinc chelates lead the product type landscape due to their established role in immune function and reproductive performance validation across species. Liquid formulations are gaining fastest in the application dimension as integrated poultry operations adopt automated drinking water medication systems, while powder grades retain margin concentration in the dietary supplements channel where tablet compression demands flowability specifications.
The FDA regulates chelated mineral claims in animal feed through the Association of American Feed Control Officials model bill and Center for Veterinary Medicine oversight of new dietary ingredient notifications. In Europe, EFSA evaluates health claim substantiation for human applications under the Nutrition and Health Claims Regulation, while REACH governs the environmental release profiles of synthetic chelating agents. Stakeholders must monitor the evolving interface between organic certification standards and synthetic chelation chemistry, as regenerative agriculture protocols create divergence in acceptable input categories across premium supply chains.
Market Dynamics
The collapse of capital-intensity barriers between integrated multinationals and regional blenders is compressing competitive hierarchies as automated chelation reactor technology becomes commoditized. This structural force is redistributing manufacturing capacity downstream and eroding the historical moat of backward-integrated suppliers.
Growth Catalysts
- Animal Feed Bioavailability Mandates:Livestock producers across intensive pork and poultry operations are displacing inorganic mineral salts with amino acid chelates to improve absorption efficiency and reduce environmental excretion.
- REACH Compliance Architecture:The European Union's F-Gas Regulation and environmental release standards are forcing reformulation of synthetic chelating agents toward biodegradable ligand systems.
- Aquaculture Expansion:China's shrimp and finfish farming sectors are consuming mineral premixes at accelerating rates as pond density intensifies and micronutrient deficiency management becomes critical.
Market Restraints
- Ethylenediaminetetraacetic Acid Price Volatility:Intermediate supply concentration in Chinese petrochemical corridors creates input cost instability for European and North American formulators.
- Organic Certification Friction:Regenerative agriculture protocols in premium supply chains are diverging on acceptable synthetic chelation chemistry, fragmenting addressable market definitions.
- Protein Hydrolysate Substitution:Fermentation-derived mineral complexes from biotechnology suppliers are encroaching on traditional chelate applications in dietary supplements.
Strategic Opportunities
- Automated Drinking Water Systems:Integrated poultry operations in Brazil and Thailand are adopting liquid chelate formulations for precision medication delivery through in-line dosing equipment.
- Carbon Border Adjustment Mechanism:The EU's CBAM is creating compliance-service revenue streams for chelate suppliers documenting lifecycle emissions of metal-ligand production.
- Precision Livestock Convergence:Sensor-enabled feeding systems are integrating real-time mineral supplementation algorithms that favor stable, bioavailable chelate inputs over inorganic salts.
Industry Challenges
- Chelate Stability Validation:Analytical chemistry talent scarcity is extending new product qualification timelines as EFSA and FDA demand expanded stability-constant documentation under varying pH and temperature matrices.
- Legacy Premix Integration:Feed mills running decade-old batching software face protocol incompatibility with liquid chelate dosing systems, requiring parallel infrastructure investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chelated Minerals Market |
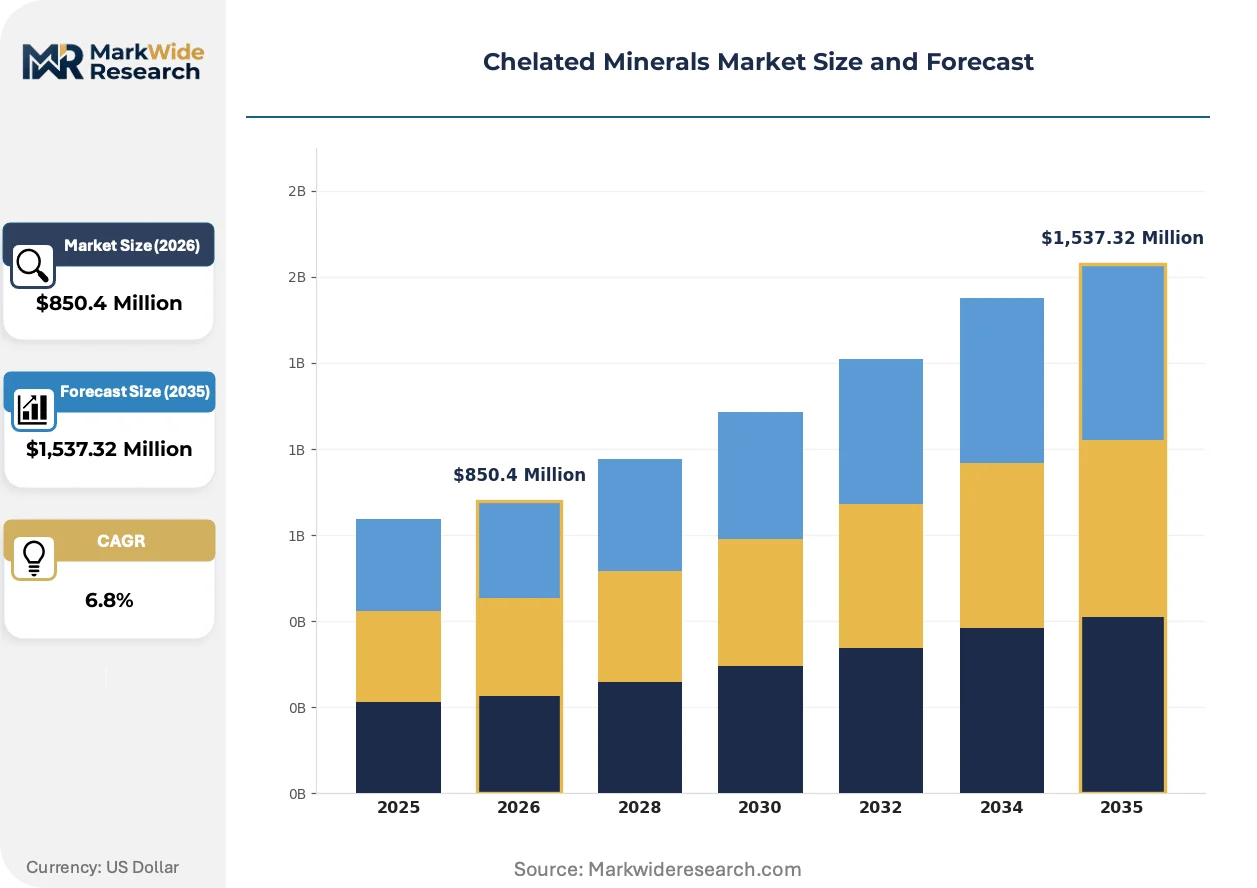
| Market Size in 2026 | $850.4 Million |
| Market Size in 2035 | $1,537.32 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Iron Chelates, Magnesium Chelates, Zinc Chelates, Calcium Chelates Application: Agriculture, Animal Feed, Dietary Supplements, Food Fortification End User: Agronomists, Nutritionists, Manufacturers, Farmers Form: Powder, Liquid, Granular, Tablet |
| Companies Covered | Nutreco N.V., Kemin Industries Inc., Archer Daniels Midland Company, Cargill Incorporated, Alltech Inc., Koninklijke DSM N.V., BASF SE, Zinpro Corporation, Balchem Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chelated Minerals Market Emerging Trajectories
Reactor miniaturization and continuous-flow chemistry are decomposing the scale economics that historically protected large-format manufacturers. These process innovations are enabling distributed production footprints closer to raw material sources and end-use concentrations.
Continuous-flow chelation reactors using microchannel mixing technology are decomposing batch-process dominance in glycinate and methioninate production. Mid-scale feed compounders in Poland and Vietnam are adopting skid-mounted systems that slash capital requirements by half. This diffusion is compressing regional price premiums and forcing integrated suppliers to defend position through captive amino acid supply.
EFSA's updated guidance on health claim substantiation for human mineral applications is tightening evidentiary standards for absorption enhancement claims. The regulation now demands crossover bioavailability studies against reference inorganic forms, elevating R&D costs for new entrants. Dietary supplement brands targeting German and French retail channels are consolidating supplier relationships to share clinical validation burdens.
Integrated poultry and swine operations are consolidating procurement authority at the enterprise level, displacing decentralized mill-level mineral purchasing. This buyer concentration is forcing chelate suppliers to adopt volume-tiered contracting and technical service bundling. The shift is most visible in Brazil's Mato Grosso soybean-poultry corridor, where three protein processors now control 60 percent of regional mineral premix specification authority.
Chelated Minerals Market Segmentation
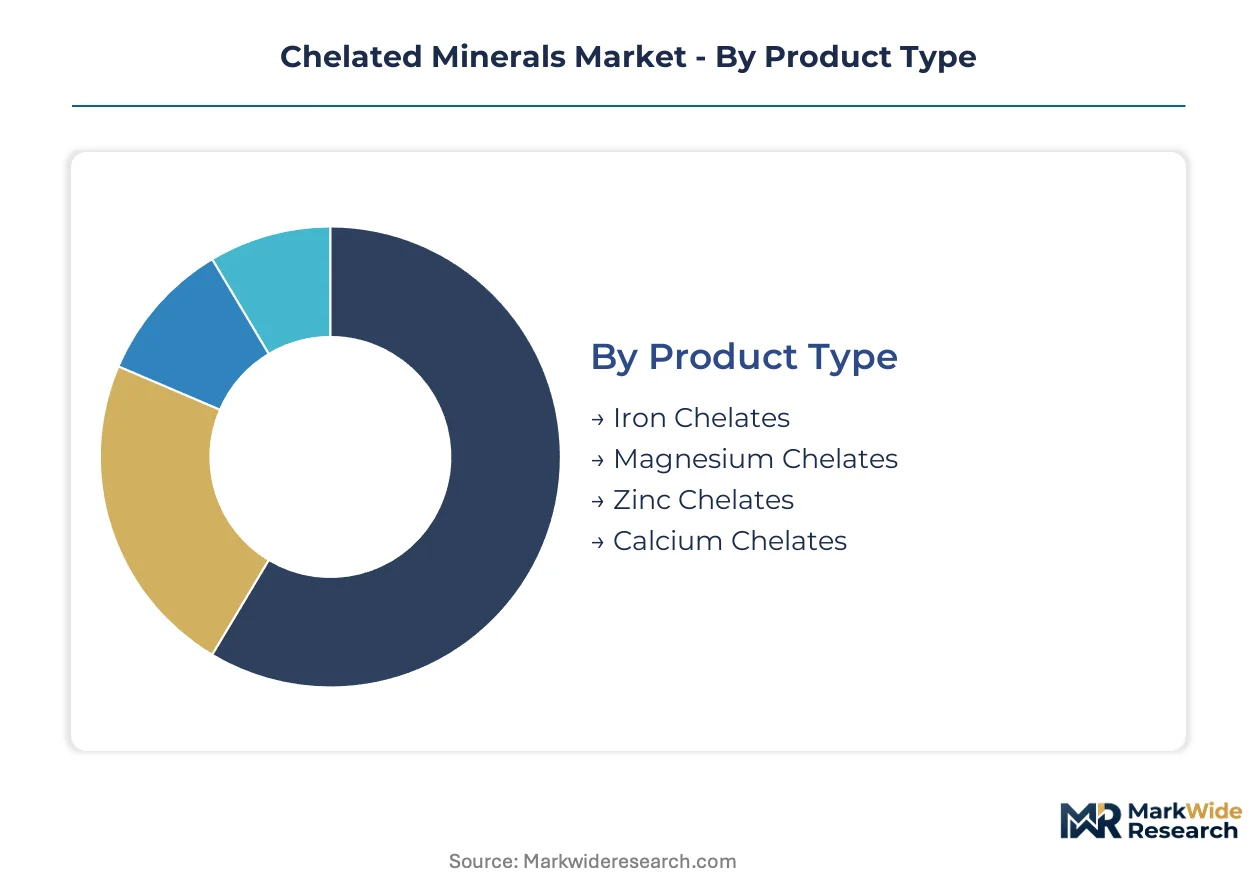
Chelated mineral suppliers must align production assets with divergent technical specifications across feed, food, and agricultural channels. Each segment imposes distinct stability requirements, regulatory pathways, and customer procurement behaviors that reshape competitive positioning.
Product Type:
Zinc and iron chelates face intensifying substitution pressure from protein hydrolysate mineral complexes in human nutrition applications, while calcium and magnesium variants defend entrenched positions in crop foliar feeds.
- Zinc Chelates:Glycine and methionine complexes dominate ruminant and swine premix formulations due to validated immune function and reproductive performance data. China's intensive pork operations and Brazil's integrated poultry processors drive concentrated procurement of high-stability zinc methionine.
- Iron Chelates:Amino acid-bound ferrous complexes serve anemia prevention protocols in aquaculture and human dietary supplements. EFSA's tightened absorption-evidence requirements are elevating qualification costs for new ferrous bisglycinate entrants targeting European retail.
- Magnesium Chelates:Magnesium glycinate supplies stress-mitigation applications in high-performance dairy herds and human sleep-support formulations.
- Calcium Chelates:Calcium amino acid complexes address blossom-end rot prevention in greenhouse tomato operations and tablet compression in supplement manufacturing.
Zinc chelates retain volume leadership; iron chelates hold the steepest expansion curve.
Application:
Cost tier stratification separates premium-grade human nutrition from commodity animal feed, with agricultural intermediates occupying a contested middle band vulnerable to inorganic salt price competition.
- Animal Feed:Amino acid chelates displace inorganic sulfates and oxides in intensive livestock operations seeking reduced environmental excretion and improved feed conversion ratios. Automated dosing systems in Thailand and Poland's poultry corridors favor liquid glycinate formulations.
- Dietary Supplements:Tablet-grade mineral chelates demand exacting flowability and compressibility specifications, with German and French retailers requiring EFSA-compliant absorption claims.
- Agriculture:Foliar-applied iron and zinc chelates address micronutrient deficiencies in high-value horticulture across Spain's Almería greenhouse cluster.
- Food Fortification:Cereal and beverage fortification employs encapsulated chelates to mask metallic off-notes and ensure shelf-stable bioavailability.
Animal feed commands the dominant revenue share; dietary supplements deliver the highest margin per kilogram.
End User:
Procurement authority is concentrating at the enterprise level among integrated protein processors, displacing decentralized purchasing by individual nutritionists and agronomists.
- Manufacturers:Premix compounders and finished feed producers specify chelate grades based on compatibility with legacy batching infrastructure and customer certification requirements.
- Farmers:Large-scale operations in Mato Grosso and Shandong province negotiate direct supply agreements, bypassing traditional distribution.
- Nutritionists:Independent consultants influence chelate selection in smaller swine and dairy operations lacking in-house technical staff.
- Agronomists:Crop advisors recommend foliar chelate programs for high-value fruit and vegetable producers.
Manufacturers control specification authority; farmers are gaining direct procurement leverage fastest.
Form:
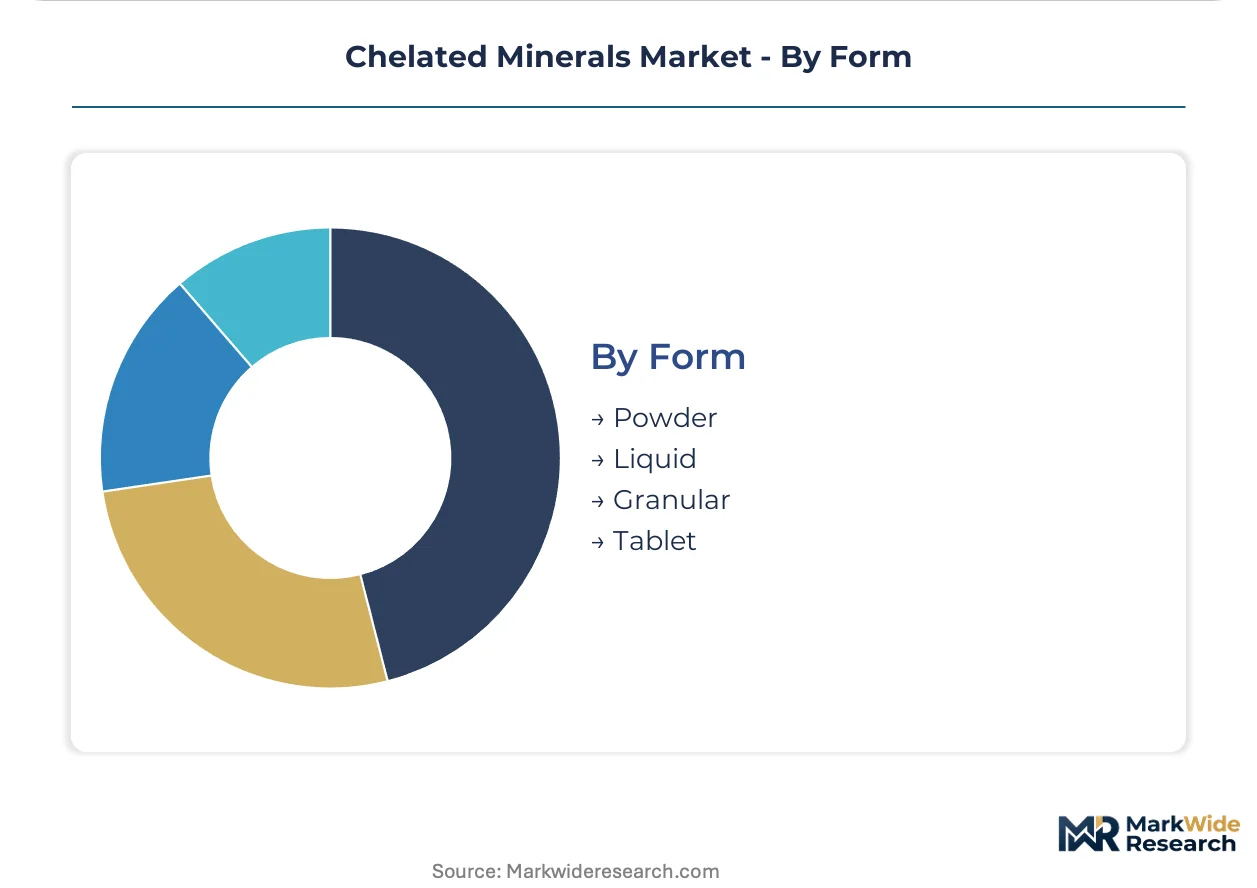
Volume scale favors powder grades, while liquid formats capture share through precision livestock farming integration.
- Powder:Spray-dried chelates serve premix blending and tablet compression, with flowability specifications critical for high-speed manufacturing lines.
- Liquid:In-line dosing compatibility drives adoption across Brazil and Thailand's automated poultry drinking water systems.
- Granular:Dust-free handling properties suit bulk feed mill operations and agricultural broadcast applications.
- Tablet:Direct-compression grades target human supplement manufacturing with disintegration-time and hardness requirements.
Powder retains manufacturing volume dominance; liquid forms are penetrating fastest in automated livestock operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's aquaculture and pork sectors show the lowest price elasticity as micronutrient deficiency management becomes critical, while European compounders face acute cost sensitivity under REACH compliance burdens. Brazil's integrated poultry processors occupy a middle ground, trading margin for bioavailability gains in automated systems.
China
Shandong province's intensive pork operations and Guangdong's shrimp farming belts drive concentrated mineral premix consumption. The Ministry of Ecology and Environment enforces dual carbon goals that favor reduced-excretion chelate formulations over inorganic salts. Yangtze River Delta feed compounders are consolidating procurement authority at the enterprise level, bypassing traditional distributor networks.
United States
Midwest dairy herds and Southeast broiler operations anchor amino acid chelate demand for reproductive performance and immune function. The FDA's Center for Veterinary Medicine oversees new dietary ingredient notifications through AAFCO model bill alignment. Iowa and North Carolina feed mills face legacy batching software incompatibility with liquid chelate dosing systems, forcing parallel infrastructure investment.
Brazil
Mato Grosso's soybean-poultry corridor concentrates specification authority among three protein processors controlling sixty percent of regional mineral premix decisions. ANVISA regulates human dietary supplement claims while MAPA governs animal feed additive registration. São Paulo state's integrated operations are adopting liquid glycinate formulations for automated drinking water medication systems.
Germany
Bavaria's dairy nutritionists specify zinc methionine for high-performance herds, while North Rhine-Westphalia premix compounders serve Benelux export markets. ECHA's REACH enforcement and the F-Gas Regulation drive reformulation toward biodegradable ligand systems. Lower Saxony's feed technology cluster is deploying continuous-flow microchannel reactors that halve capital requirements for mid-scale glycinate production.
India
Maharashtra's poultry integrators and Gujarat's dairy cooperatives are displacing inorganic sulfates with glycine chelates in intensive operations. FSSAI regulates human supplement mineral claims while BIS standards govern feed-grade specifications. Haryana's feed mill corridor faces analytical chemistry talent scarcity extending new product qualification timelines under tightened stability-constant documentation requirements.
Chelated Minerals Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with backward-integrated multinationals commanding ligand chemistry expertise while regional blenders exploit commoditized reactor technology. The competitive structure is compressing as automated chelation equipment collapses capital-intensity barriers. Three archetypes dominate: captive amino acid suppliers bundling chelates with vitamin premixes, performance trace mineral specialists defending dairy channels with absorption claims, and petrochemical-integrated intermediates producers anchoring European supply security. Dominant competitive moves include strategic partnerships with precision livestock farming platforms and geographic expansion through distributed micro-reactor footprints.
Among European-based chemical conglomerates, BASF SE exemplifies the petrochemical-integrated archetype through upstream control over ethylenediaminetetraacetic acid intermediates. Kemin Industries represents the captive amino acid supplier model, leveraging in-house lysine and methionine platforms. Zinpro Corporation occupies a position within the performance trace mineral specialist tier, anchoring dairy nutrition channel relationships. These three illustrate the divergent strategic positions required to defend margin under collapsing scale economics.
| Leading Market Players |
|---|
| Nutreco N.V. |
| Kemin Industries Inc. |
| Archer Daniels Midland Company |
| Cargill Incorporated |
| Alltech Inc. |
| Koninklijke DSM N.V. |
| BASF SE |
| Zinpro Corporation |
| Balchem Inc. |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between zinc methionine suppliers and Brazil's integrated poultry processors lock in supply access while capping price volatility exposure across multi-year procurement cycles. These arrangements tether volume commitments to glycine and methionine feedstock indices, transferring ligand chemistry cost fluctuations upstream while stabilizing downstream premix formulation budgets.
Pricing Analysis
Technical service bundling drives lifetime value for chelate suppliers defending dairy nutrition relationships against inorganic salt competitors. Three-tier pricing structure across pharmaceutical-grade, feed-grade, and agricultural-grade specifications separates EFSA-validated absorption claims from commodity premix inputs. Cost compression in standard-grade zinc glycinate intensifies as Chinese reactor miniaturization floods regional markets with fungible supply. Small-scale dairy cooperatives in India exhibit acute price sensitivity, while European compounders under REACH compliance burdens absorb premium differentials for biodegradable ligand systems.
Supply Chain Analysis
Strategic stockpiling of ethylenediaminetetraacetic acid intermediates characterizes European formulator behavior given Chinese petrochemical corridor concentration and maritime logistics vulnerability. Supply draws from Shandong province chelation reactor clusters, Rotterdam bulk chemical terminals, and São Paulo state distribution hubs. Raw material dependencies center on petrochemical-derived glycine, methionine from captive amino acid platforms, and pharmaceutical-grade metal oxides. Single-source vulnerability in Chinese EDTA intermediate production exposes margin compression risk during Yangtze River shipping disruptions. Distribution runs through premix compounder networks in Poland and Vietnam, bypassing traditional distributor layers as enterprise procurement authority concentrates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
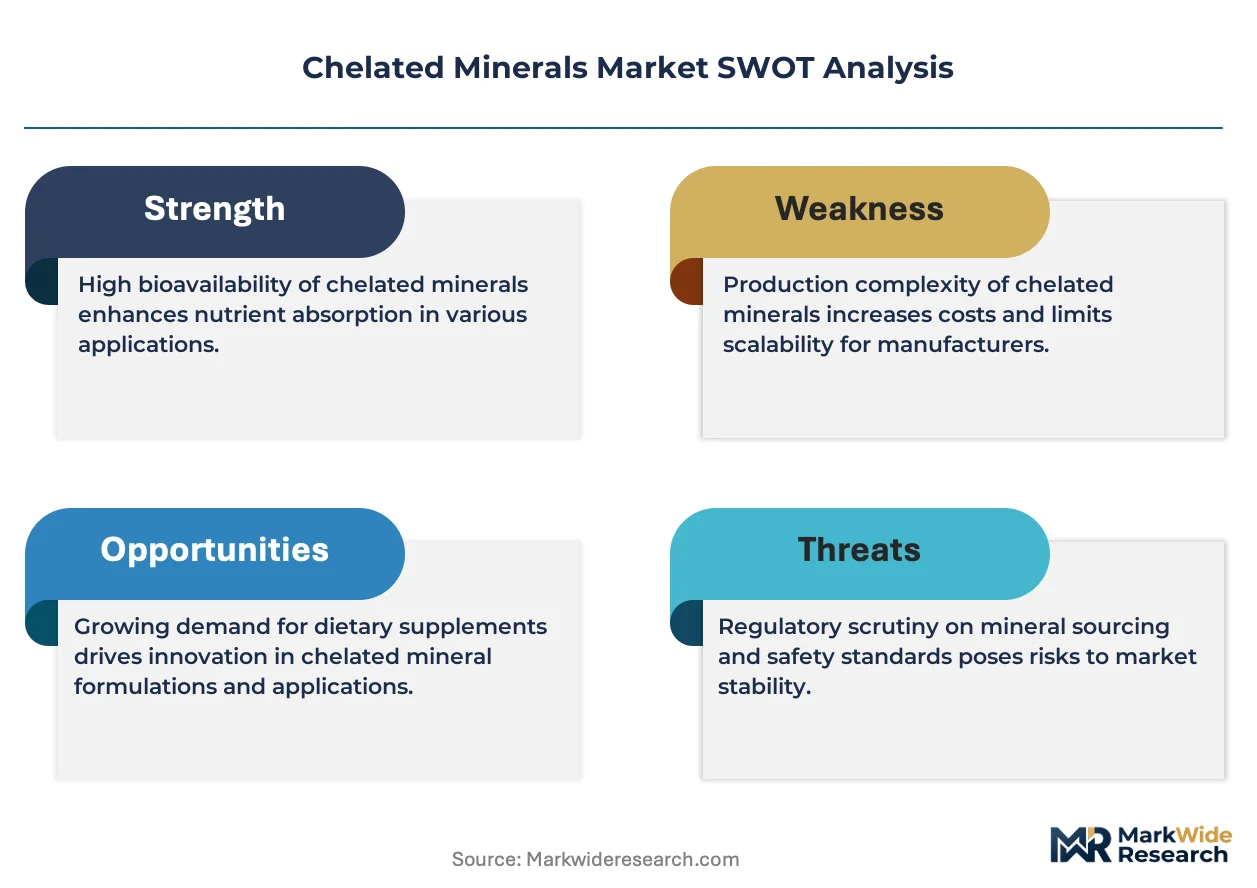
Incumbent chelate suppliers face substitution defense imperatives as fermentation-derived protein hydrolysate mineral complexes encroach on dietary supplement applications with comparable bioavailability claims at lower production complexity.
For Market Incumbents: Fortify dairy nutrition channel relationships through expanded technical service teams validating absorption performance against inorganic salt benchmarks. Deepen backward integration into methionine and glycine supply through strategic partnerships with amino acid platforms, neutralizing the captive supply advantage of bundled premix competitors. This defensive posture addresses encroachment by biotechnology-derived mineral complexes in human nutrition segments.
For New Entrants and Emerging Players: Differentiate on continuous-flow microchannel reactor deployment enabling distributed production footprints adjacent to Southeast Asian aquaculture clusters. Target Thailand's automated poultry drinking water system integrators with liquid glycinate formulations bypassing legacy powder-grade infrastructure requirements. White-space penetration concentrates in precision livestock farming platform partnerships where real-time mineral supplementation algorithms favor stable chelate inputs.
For Investors and Strategic Acquirers: Regional blenders with automated reactor technology and established premix compounder relationships represent the most attractive acquisition archetype for consolidating fragmented mid-scale production capacity. Long-term viability hinges on carbon border adjustment mechanism compliance service capabilities documenting lifecycle emissions for EU-bound supply. Watch for inflection when REACH enforcement tightens biodegradable ligand mandates, disqualifying legacy EDTA-dependent producers from premium European channels.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous-Flow Reactor Deployment | Microchannel technology halves capital requirements for mid-scale glycinate producers in Poland and Vietnam. |
| Backward Integration into Amino Acids | Captive lysine and methionine supply neutralizes bundled premix competition from Kemin Industries. |
| Biodegradable Ligand Reformulation | REACH and F-Gas Regulation compliance opens premium European channels while disqualifying EDTA-dependent rivals. |
| Precision Livestock Platform Partnership | Sensor-enabled feeding algorithm integration locks in stable chelate demand against inorganic salt substitution. |
| Carbon Border Adjustment Documentation | Lifecycle emissions verification creates compliance-service revenue streams for EU-bound mineral premix supply. |
Methodological Framework
Cross-validation between regulatory filing analysis and trade flow data anchors the qualitative findings on REACH and FDA compliance pathway evolution. Primary interviews with premix compounder procurement directors, dairy nutrition consultants, aquaculture farm managers, and chelation reactor technology suppliers combined with secondary validation against EFSA health claim guidance, customs export records, and SEC filings from publicly traded amino acid producers. Bottom-up capacity assessments and top-down consumption estimates triangulate volume figures across the analysis window.
Sensitivity analysis on glycine feedstock price volatility and EDTA intermediate supply disruption scenarios shapes the forecast framework. Segmentation dimensions modeled include mineral type, application channel, end-user procurement authority tier, and regional regulatory cluster. CAGRs derive from historical consumption trajectory analysis adjusted for bioavailability mandate adoption curves and automated dosing system penetration rates. Industry-specific inputs incorporate shrimp farming density intensification in Guangdong and pork operation consolidation in Shandong province.
Material uncertainties — regulatory enforcement timing on biodegradable ligand mandates, biotechnology substitution acceleration in human supplements, and carbon border adjustment mechanism implementation scope — sit outside the modeled envelope. Forecasts reflect assumptions on enterprise procurement authority concentration and continuous-flow reactor technology diffusion rates. Revision becomes warranted when protein hydrolysate mineral complex bioavailability claims achieve EFSA crossover study validation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Minerals
Bentonite Market
Industrial Minerals
Aluminium Potassium Sulphate Market
Industrial Minerals
Talc Market
Industrial Minerals
Gluconate Mineral Market
Industrial Minerals
Global Carbonate Minerals Market
Industrial Minerals
Seaweed Derived Minerals Market
Industrial Minerals
Slate Market
Industrial Minerals
Industrial Salts Market
Industrial Minerals
Nepheline Syenite Market
Industrial Minerals
Fluorspar Market
Industrial Minerals
Mineral Wool Material Market
Industrial Minerals
Feldspathic Minerals Market
Industrial Minerals
Snowflake Salt Market
Industrial Minerals
Anhydrite Market
Industrial Minerals
Pyrites Market
Industrial Minerals
Dolomite Mining Market