
 Global Commercial Perlite Market | 2026-2036
Global Commercial Perlite Market Size, Share, and Industry Trends Forecast 2026-2036
Global Commercial Perlite Market Foresight
Modular packaging configurations in bulk-to-bag formats is rebalancing procurement economics for mid-scale buyers. Imerys leverages its European kiln network to sustain expanded perlite supply across construction channels. Genper Group anchors Aegean sourcing through captive quarry positions in western Turkey. Hess Perlite differentiates via specialized horticultural grades distributed through North American nursery cooperatives.
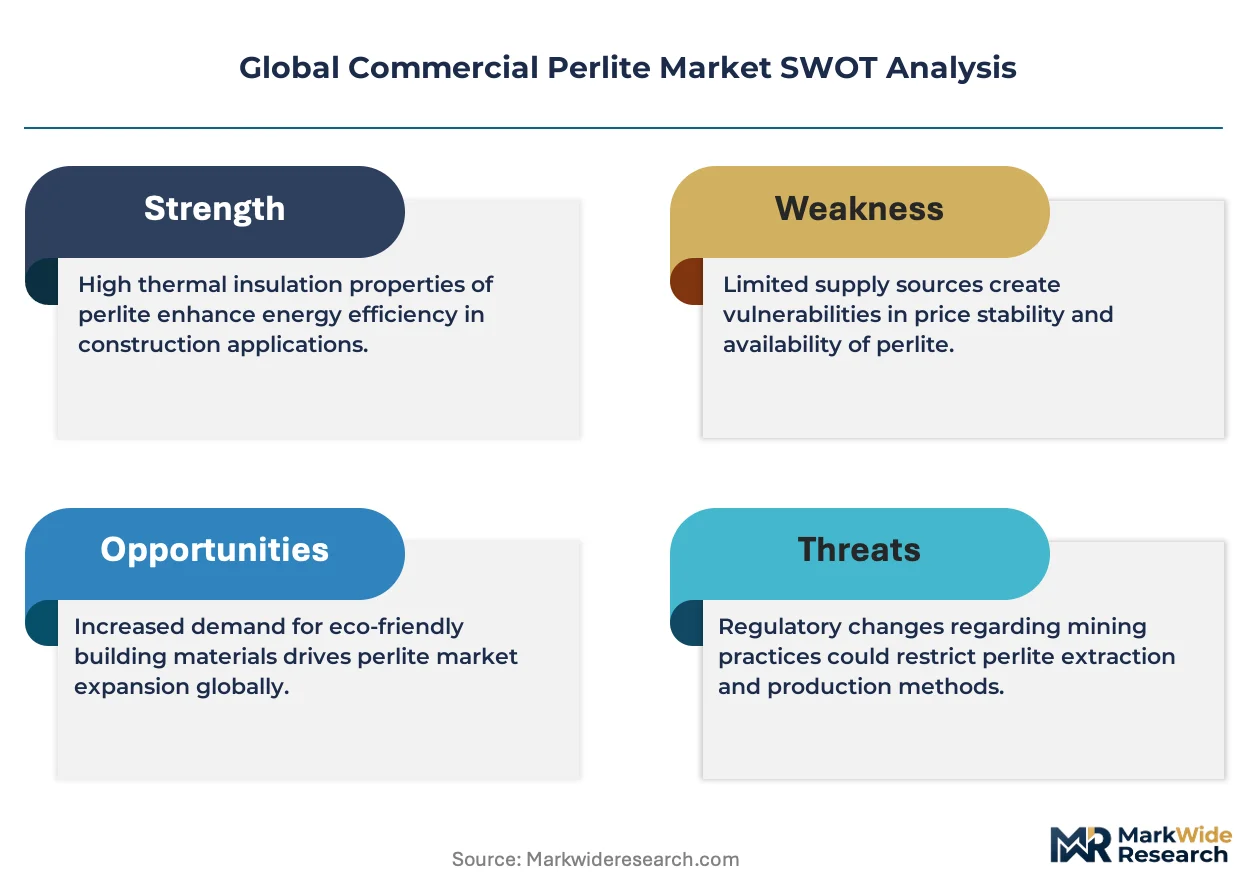
Commercial perlite is a naturally occurring siliceous volcanic glass that expands up to twenty times its original volume when heated above 870°C, creating a lightweight, porous aggregate with low thermal conductivity and high water retention capacity. Industrial buyers specify it for lightweight concrete aggregate, cryogenic insulation, and soil amendment substrates where density reduction and moisture control prove critical. Expanded perlite captures the dominant value share in construction and filtration applications where thermal performance and chemical inertness command premium specification. Filter aid perlite occupies a mature, high-margin niche serving pharmaceutical and food processing clarifier systems with stringent purity requirements. Raw perlite competes primarily on quarry proximity and freight economics rather than processed performance attributes.
EPA standards under the Toxic Substances Control Act and OSHA workplace exposure limits shape perlite processing compliance costs in the United States, while REACH registration requirements in Europe enforce crystalline silica disclosure thresholds that filter into supply chain qualification protocols. India's BIS certification for construction aggregates and China's GB standards for thermal insulation materials create divergent product testing obligations for exporters serving multiple jurisdictions. Stakeholders must monitor regulatory divergence between silica classification regimes and emerging low-carbon building codes that could reposition perlite against competing lightweight aggregates.
Market Dynamics
Construction procurement across Asia-Pacific infrastructure corridors is concentrating demand for lightweight perlite aggregate, while REACH and EPA crystalline silica thresholds are forcing kiln operators to reconfigure expansion furnace exhaust systems and product certification protocols.
Growth Catalysts
- GB standards for thermal insulation:China's building energy efficiency mandates specify perlite-based cavity wall insulation, pulling expanded aggregate through state-backed housing retrofits in tier-two cities.
- Soilless cultivation substrates:Controlled-environment agriculture in the Netherlands and Spain specifies coarse perlite grades for hydroponic tomato and pepper propagation, displacing rockwool in glasshouse expansions.
- REACH registration thresholds:ECHA crystalline silica disclosure rules favor perlite over diatomaceous earth in food-grade filtration, redirecting clarifier procurement toward verified low-crystalline supply chains.
Market Restraints
- Natural gas price volatility:Expansion kiln operations in Turkey and Greece face feedstock cost pressure, compressing margins for unhedged mid-scale processors serving Mediterranean construction markets.
- Quarry concentration in Aegean belt:Western Turkey holds dominant raw perlite reserves, creating single-source dependency risk for European expanders without captive mining positions.
- Substitute lightweight aggregates:Expanded clay and foamed glass capture specification share in Scandinavian passive house construction where lambda-value performance trumps perlite's cost advantage.
Strategic Opportunities
- India BIS certification pipeline:Bureau of Indian Standards aggregate testing for lightweight concrete creates first-mover advantage for exporters establishing in-country blending facilities ahead of infrastructure spending acceleration.
- Cryogenic LNG insulation:Perlite's super-insulating properties at sub-zero temperatures align with liquefaction terminal construction in Qatar and Australia, opening maritime specification channels outside construction saturation.
- Direct-to-grower distribution:North American horticultural perlite bypasses cooperative aggregators through e-commerce platforms serving urban rooftop farming and home greenhouse segments.
Industry Challenges
- Furnace emissions compliance:EPA Title V permitting timelines for expansion kiln upgrades extend 18-24 months, delaying capacity additions needed for construction season demand peaks.
- Cross-jurisdiction certification fragmentation:Separate BIS, GB, and ASTM testing requirements for the same perlite grade force redundant laboratory expenditure on multi-destination export batches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Commercial Perlite Market |
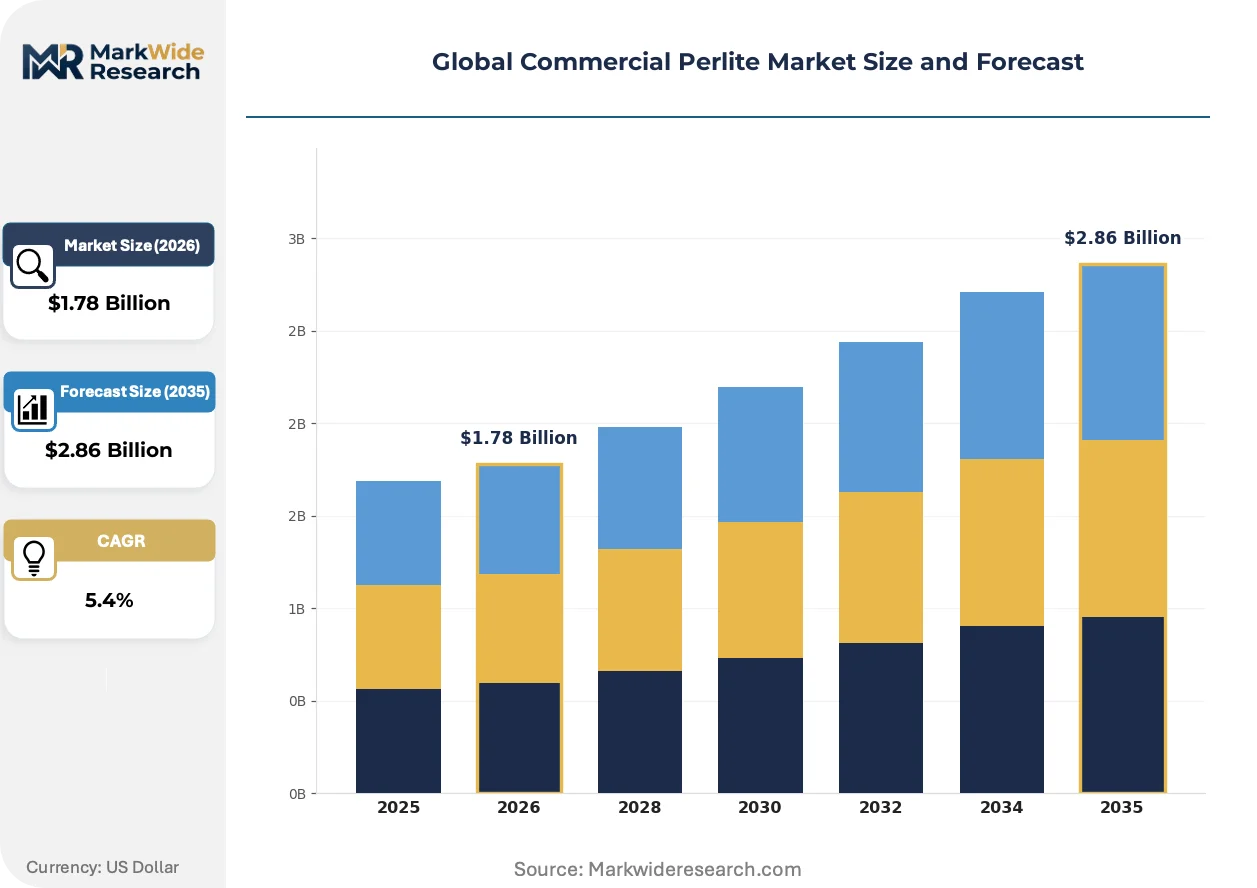
| Market Size in 2026 | $1.78 Billion |
| Market Size in 2035 | $2.86 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Expanded Perlite, Raw Perlite, Pulverized Perlite, Agricultural Perlite, Filter Aid Perlite Application: Construction, Horticulture, Filtration, Thermal Insulation, Abrasives, Pharmaceuticals End User Industry: Building Contractors, Plant Nurseries, Water Treatment Plants, Chemical Production, Food Processing, Pharmaceutical Manufacturing Packaging Type: Bags, Bulk, Boxes, Containers, Sacks |
| Companies Covered | Supreme Perlite Company, Genper Group, Imerys, The Schundler Company, Omya International AG, Dicalite Management Group, Aegean Perlites SA, Hess Perlite, Silbrico Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Commercial Perlite Market Shifts & Advancements
Mobile expansion units and distributed processing networks are compressing the traditional quarry-to-plant supply radius, while regulatory silica thresholds and procurement digitization reshape competitive differentiation beyond raw material access.
Portable expansion kiln technology is decentralizing perlite processing economics. Containerized furnace systems now operate at 40-foot scale near construction sites in Australia and Saudi Arabia, eliminating bulk shipping costs for infrastructure projects. Contractors in remote mining camps and island developments specify on-site expanded aggregate, compressing the traditional quarry-kiln-distributor value chain into single-source procurement.
ECHA's 2023 crystalline silica classification update is tightening filter aid purity documentation. Food and pharmaceutical clarifier buyers now require third-party crystalline silica testing below 0.1% threshold, forcing perlite processors to segregate quarry benches and document expansion temperature profiles. European filtration distributors are consolidating supply relationships around processors with in-house XRD testing capability.
Buyer specification behavior is fragmenting across performance tiers. Large infrastructure contractors in India and Indonesia negotiate long-term offtake contracts with volume-indexed pricing, while specialty horticultural buyers in Japan and South Korea procure certified organic perlite through agricultural cooperatives with batch-traceability requirements. Channel specialization is hardening, with construction-grade and horticultural-grade supply chains diverging on logistics, certification, and technical service bundling.
Global Commercial Perlite Market Segmentation
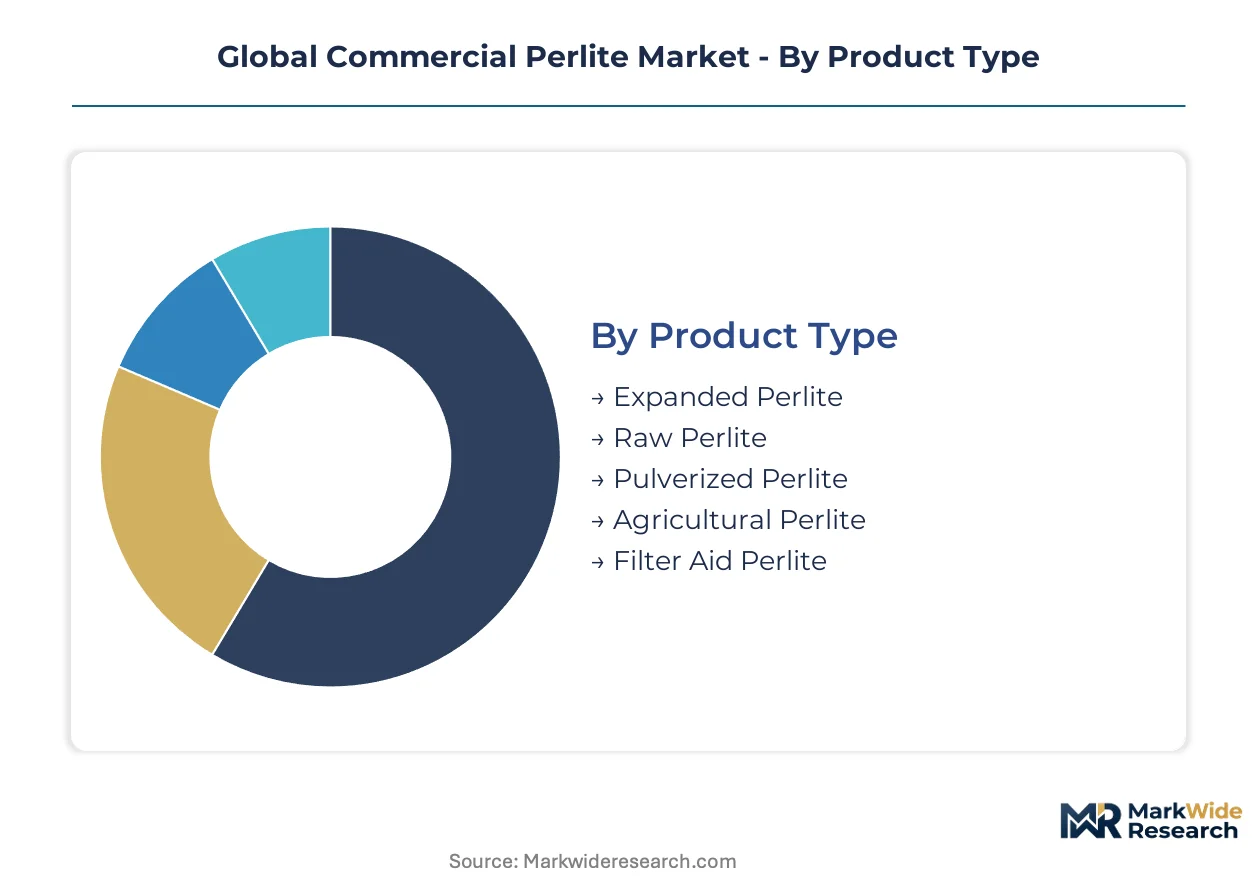
Commercial perlite's value chain fragments across processing intensity and end-use performance requirements. Each segment tier carries distinct certification burdens, logistics configurations, and margin structures that reshape procurement patterns.
Product Type:
Expanded perlite dominates standalone applications where thermal performance commands specification, while raw and pulverized grades embed into downstream manufacturing systems.
- Expanded Perlite:Heat-treated volcanic glass expanded to 15-20 times original volume creates lightweight aggregate with closed-cell porosity. Construction procurement in India and China pulls this grade through state-backed housing retrofits and infrastructure corridors where density reduction proves critical.
- Raw Perlite:Unprocessed quarry material competes primarily on freight economics and quarry proximity rather than performance attributes. Mediterranean kiln operators in Turkey and Greece source captive Aegean reserves to secure feedstock supply.
- Pulverized Perlite:Finely ground material serves specialized industrial applications requiring precise particle size distribution.
- Agricultural Perlite:Coarse grades optimize soil aeration and drainage in controlled-environment agriculture.
- Filter Aid Perlite:High-purity grades processed under documented temperature profiles serve pharmaceutical and food clarifier systems with ECHA crystalline silica thresholds below 0.1%.
Volume placements concentrate in expanded perlite; the faster expansion belongs to filter aid perlite.
Application:
Construction absorbs the heaviest tonnage flows, while horticulture and filtration extract premium pricing through certification-intensive supply chains.
- Construction:Lightweight concrete aggregate and cavity wall insulation dominate procurement volumes across Asia-Pacific infrastructure corridors. China's GB standards for thermal efficiency mandate perlite-based insulation in tier-two city retrofits.
- Horticulture:Soilless cultivation substrates in Dutch and Spanish glasshouses displace rockwool for hydroponic tomato and pepper propagation. Batch-traceability requirements through agricultural cooperatives in Japan and South Korea enforce supply chain segregation.
- Filtration:Pharmaceutical and food-grade clarifier systems demand verified low-crystalline documentation under ECHA disclosure rules.
- Thermal Insulation:Cryogenic LNG terminal construction in Qatar and Australia exploits perlite's super-insulating properties at sub-zero temperatures.
- Abrasives:Specialized surface preparation applications leverage perlite's controlled hardness and low free-silica content.
- Pharmaceuticals:Purity-critical applications require segregated quarry bench sourcing and XRD testing capability.
Construction channels capture the largest absolute tonnage; horticulture is climbing the fastest on per-kilogram value extraction.
End User Industry:
Building contractors negotiate volume-indexed offtake contracts, while pharmaceutical and food processors impose batch-traceability protocols that fragment procurement relationships.
- Building Contractors:Large infrastructure developers in India and Indonesia secure long-term supply agreements with price escalation clauses tied to natural gas indices.
- Plant Nurseries:North American nursery cooperatives distribute specialized horticultural grades, though direct-to-grower e-commerce platforms now bypass traditional aggregators for urban rooftop farming segments.
- Water Treatment Plants:Municipal filtration procurement favors established suppliers with in-house testing laboratories.
- Chemical Production:Process industry buyers specify perlite for catalyst support and filtration media.
- Food Processing:EFSA-aligned clarifier buyers require third-party crystalline silica documentation and expansion temperature profile records.
- Pharmaceutical Manufacturing:GMP-compliant facilities enforce the most stringent purity protocols, consolidating supply around processors with captive quarry positions and integrated testing.
Building contractors dominate volume placements; pharmaceutical manufacturing is gaining share fastest on specification premium capture.
Packaging Type:
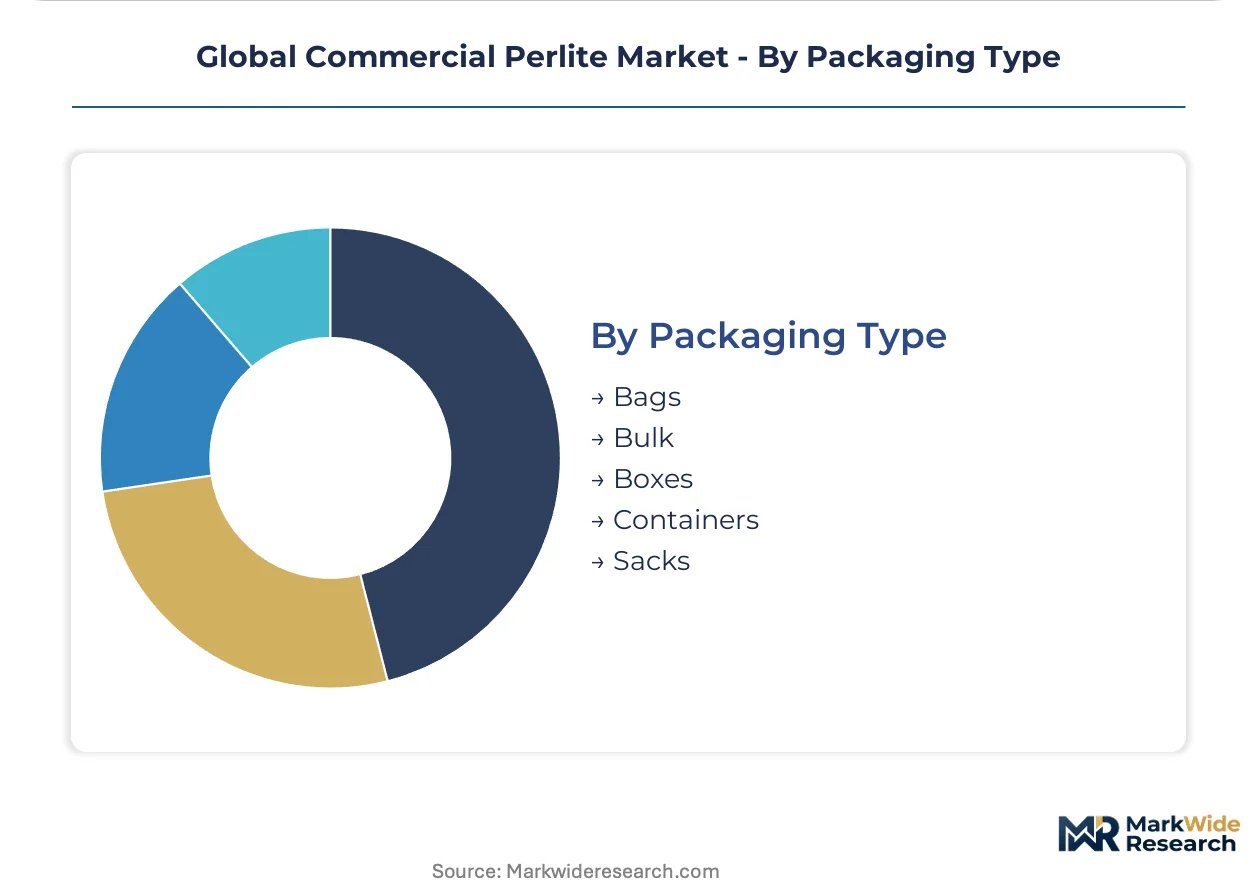
Logistics configuration splits between bulk flows to kiln-adjacent construction sites and precision-packaged units for specialty end-users.
- Bags:Standardized 50-100 pound units serve mid-scale horticultural and construction buyers through distributor networks.
- Bulk:Unpackaged aggregate moves via pneumatic trailer to large contractors with on-site storage, eliminating packaging cost for volume purchasers.
- Boxes:Retail-format packaging supports home greenhouse and urban farming segments through e-commerce channels.
- Containers:Maritime shipping units serve export markets and cryogenic insulation projects requiring contamination-controlled transport.
- Sacks:Woven polypropylene units predominate in Mediterranean construction markets with established handling infrastructure.
Bulk shipments concentrate the heaviest tonnage; containerized formats are expanding most quickly on maritime specification growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in western Turkey concentrate captive perlite quarrying and expansion kiln operations, creating a tax-advantaged hub that feeds Mediterranean construction corridors and European filtration markets.
United States
Natural gas-fired expansion kilns in the Mountain West serve lightweight concrete demand from Denver to Phoenix infrastructure projects. EPA Title V permitting under the Clean Air Act shapes furnace upgrade timelines for domestic processors. Hess Perlite anchors North American horticultural supply through distributor networks spanning the Pacific Northwest and Midwest nursery cooperatives.
China
State-backed housing retrofits in tier-two cities pull expanded perlite through GB standards-mandated cavity wall insulation programs. MIIT building energy efficiency directives enforce thermal performance benchmarks that specify perlite-based materials. Yangtze River Delta construction clusters in Jiangsu and Zhejiang provinces concentrate procurement volumes for high-speed rail and urban transit concrete applications.
India
National infrastructure corridors drive lightweight aggregate specification for highway bridges and metro rail systems across Maharashtra and Gujarat. BIS certification requirements for construction aggregates create testing obligations for imported perlite grades. Mumbai-Pune industrial belt contractors negotiate volume-indexed offtake contracts with Middle Eastern kiln operators ahead of anticipated capacity shortages.
Germany
Passive house construction standards in Bavaria and Baden-Württemberg specify perlite for thermal bridge remediation in retrofit markets. ECHA REACH crystalline silica disclosure thresholds filter into supply chain qualification protocols for filtration-grade material. Rhine-Main logistics hubs consolidate bulk perlite flows from Aegean sources for redistribution across Benelux and Scandinavian markets.
Australia
Liquefied natural gas terminal construction in Queensland and Western Australia exploits perlite's cryogenic insulation properties at sub-zero temperatures. Containerized mobile expansion units now operate at Pilbara mining camps and island developments, eliminating maritime shipping costs. Perth-based contractors specify on-site expanded aggregate for remote infrastructure projects compressing traditional supply chains.
Global Commercial Perlite Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the commercial perlite value chain, creating a tiered structure where scale-driven processors and niche horticultural suppliers coexist. Market concentration varies sharply by segment: expanded aggregate for construction flows through kiln-adjacent operators with captive quarry positions, while filtration-grade material consolidates around processors with in-house XRD testing capability. Two dominant competitive moves define current positioning: backward integration into Aegean quarry assets to secure feedstock supply, and distributed processing networks using containerized furnace systems to compress logistics radii.
Within the diversified industrial materials tier, Imerys represents European kiln network consolidation, while Genper Group exemplifies captive Aegean sourcing through western Turkey quarry positions. Among North American specialists, Hess Perlite occupies a position in horticultural-grade distribution channels. These archetypes illustrate how competitive positioning diverges between scale-driven construction aggregate suppliers and certification-intensive filtration-grade processors.
| Leading Market Players |
|---|
| Supreme Perlite Company |
| Genper Group |
| Imerys |
| The Schundler Company |
| Omya International AG |
| Dicalite Management Group |
| Aegean Perlites SA |
| Hess Perlite |
| Silbrico Corporation |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between filter aid and construction perlite manifests in divergent pricing architectures and supply chain configurations. Filter aid processors command premium positioning through ECHA-mandated crystalline silica documentation below 0.1%, while construction-grade material competes on Aegean quarry proximity and natural gas hedging.
Pricing Analysis
Short lead-time premiums separate spot procurement from contract-indexed construction volumes. Three-tier pricing structure across premium, standard, and economy levels stratifies by crystalline silica certification and expansion temperature documentation. Pricing pressure stems from natural gas volatility in Turkish and Greek kiln operations. Large infrastructure contractors in India exhibit lowest price sensitivity due to volume-indexed offtake structures, while mid-scale horticultural buyers in North America face highest elasticity.
Supply Chain Analysis
Raw perlite supply rests on western Turkey's Aegean belt quarries, with secondary draws from Greece and limited US Mountain West deposits. Expansion kiln operations hinge on natural gas feedstock, containerized furnace mobility, and maritime bulk shipping capacity. Single-source vulnerability concentrates in Turkish quarry concentration without captive mining positions. Distribution runs through kiln-adjacent bulk pneumatic trailers for construction contractors and cooperative networks for horticultural grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as ECHA silica disclosure thresholds and EPA Title V permitting timelines force sub-scale processors toward exit or acquisition.
For Market Incumbents: Hedge against Aegean supply concentration through backward integration into captive quarry positions or long-term offtake agreements with Genper Group-tier operators. Accelerate in-house XRD testing capability to capture filtration-grade premium migration as ECHA documentation requirements tighten. For New Entrants and Emerging Players: Begin with containerized mobile expansion units serving remote mining camps and island developments in Australia and Saudi Arabia, bypassing established kiln networks. Target cryogenic LNG insulation specification in Qatar and Western Australia where maritime construction channels remain underpenetrated by incumbent construction-grade suppliers. For Investors and Strategic Acquirers: Re-rating potential sits with filtration-grade specialists given EFSA-aligned crystalline silica threshold enforcement across European food and pharmaceutical clarifier procurement. Five-to-ten-year viability favors processors with integrated quarry-to-testing capabilities. Watch EPA Title V permitting backlog duration as inflection indicator for domestic US capacity shortage timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Quarries | Secures Aegean feedstock supply against single-source concentration risk in western Turkey. |
| In-House XRD Testing Capability | Captures filtration-grade premium through ECHA-mandated crystalline silica documentation below 0.1%. |
| Containerized Mobile Expansion Deployment | Compresses logistics radii for remote infrastructure projects in Pilbara and Saudi Arabia. |
| BIS Certification Pipeline Investment | Creates first-mover advantage for India infrastructure corridor lightweight concrete specification. |
| Cryogenic LNG Insulation Specialization | Opens maritime specification channels in Qatar and Australia outside construction saturation. |
Research Methodology
Multi-period observation of kiln capacity utilization, natural gas input costs, and ECHA regulatory filing patterns anchored the trend analysis, supplemented by interviews with expansion kiln operators, construction procurement managers at Indian infrastructure developers, filtration-grade distributors, and horticultural cooperative buyers. Secondary validation drew from customs trade data, BIS certification registries, SEC filings of diversified industrial materials conglomerates, and EPA Title V permitting databases. Bottom-up volume modeling triangulated against top-down construction spending forecasts across Asia-Pacific corridors.
Segment-weighting applied differential growth assumptions across expanded perlite, filter aid, and raw material tiers, with additional stratification by crystalline silica certification level and packaging format. CAGRs derived from regression against construction spending indices, natural gas price trajectories, and regulatory compliance cost curves throughout the forecast period. Industry-specific inputs included GB standards adoption rates for Chinese thermal insulation mandates and BIS testing pipeline throughput for Indian aggregate certification.
Natural gas price shocks, EPA permitting timeline extensions, and ECHA silica classification updates are the dominant revision risks to volume and value projections. Forecasts embed assumptions regarding regulatory enforcement consistency and infrastructure spending continuity across the analysis window. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Minerals
Global Epsom Salt Market
Industrial Minerals
Mineral Enrichment Ingredients Market
Industrial Minerals
Industrial Garnet Market
Industrial Minerals
Gluconate Mineral Market
Industrial Minerals
Global Cristobalite Market
Industrial Minerals
Feldspar Mining Market
Industrial Minerals
Olivine Sand Market
Industrial Minerals
Chelated Minerals Market
Industrial Minerals
Mineral Sand Market
Industrial Minerals
United States Feed Minerals Market
Industrial Minerals
Solar Salt Market
Industrial Minerals
Potassium Schoenite Market
Industrial Minerals
Anhydrite Market
Industrial Minerals
Global Graphite Market
Industrial Minerals
Bentonite Market
Industrial Minerals
Dolomite Mining Market