
 Global Capacitor Bank Controllers Market | 2026-2036
Global Capacitor Bank Controllers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Capacitor Bank Controllers Market Analysis
Data center power quality requirements are expanding faster than traditional industrial demand, pulling capacitor bank controllers into hyperscale facility designs across multiple continents. Eaton leverages its electrical infrastructure portfolio to anchor utility-scale deployments in North America. ABB sustains technology leadership through its digital control platforms for high-voltage substations. Schneider Electric competes on integrated energy management systems that bundle capacitor control with broader power factor correction.
Capacitor bank controllers are electromechanical or solid-state devices that regulate reactive power compensation by switching capacitor stages in response to load fluctuations, typically operating within voltage ranges of 480V to 38kV and response times under one cycle. Their primary purpose is maintaining power factor near unity to reduce utility penalties and stabilize grid voltage. Static controllers occupy the largest installed base due to simplicity and cost, while digital control technology captures the fastest growth as utilities demand remote monitoring and predictive diagnostics. Microcontroller-based systems concentrate margin pools in premium industrial segments where harmonic mitigation requirements are strictest.
FERC Order 2222 in the United States enables distributed energy resource aggregation that elevates capacitor bank controllers into grid-interactive assets, while IEC 61954 and IEEE 1531 standards enforce switching endurance and harmonic performance benchmarks that filter non-compliant suppliers from tender processes. The EU Green Deal's network modernization funding and China's GB/T 15576 power factor standards create parallel compliance ladders across three continents. Stakeholders must monitor how grid code harmonization between regions affects product platform standardization versus localization trade-offs.
Market Dynamics
Digital control platforms are compressing response times from electromechanical cycles to sub-cycle switching, forcing incumbent suppliers to re-architect product portfolios around predictive diagnostics and remote telemetry capabilities.
Growth Catalysts
- Utility-scale solar integration:Grid operators in India and China deploy capacitor bank controllers to manage reactive power swings from photovoltaic arrays. FERC Order 2222 in the United States enables distributed energy resource aggregation that elevates controllers into grid-interactive assets.
- Data center power quality mandates:Hyperscale facility operators require precise power factor correction to avoid utility penalties and protect sensitive server loads. IEC 61954 switching standards enforce endurance benchmarks that filter non-compliant suppliers from tender processes.
- Transmission infrastructure modernization:Germany's network operators accelerate replacement of aging electromechanical switchgear with solid-state controllers. China's GB/T 15576 power factor standards create compliance-driven replacement cycles across provincial grids.
Market Restraints
- Semiconductor supply concentration:IGBT and thyristor sourcing concentrates among East Asian foundries, exposing controller manufacturers to input volatility and extended lead times.
- Copper and aluminum price volatility:Busbar and winding materials constitute substantial bill-of-materials costs, compressing margins when commodity markets fluctuate.
- Technical limitation in harmonic environments:Standard controllers struggle with severe harmonic distortion common in variable frequency drive installations, limiting addressable market in heavy industrial segments.
Strategic Opportunities
- Underpenetrated African utilities:Power distribution networks across Nigeria and Kenya lack automated reactive power compensation, creating first-mover advantages for digital controller suppliers.
- EU Green Deal network funding:The European Union's modernization financing creates tender pipelines for integrated energy management systems bundling capacitor control with broader grid automation.
- Edge computing convergence:Controller-embedded analytics platforms merging local power quality processing with cloud-based fleet management are capturing premium positioning in industrial microgrids.
Industry Challenges
- Embedded firmware engineering scarcity:Controller development requires specialized expertise in real-time power electronics control algorithms, constraining product roadmap velocity.
- Multi-standard certification timelines:Simultaneous compliance with IEC 61954, IEEE 1531, and GB/T 15576 extends validation cycles and delays market entry.
- Legacy substation integration friction:Retrofitting digital controllers into electromechanical switchgear architectures demands custom engineering and field commissioning resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Capacitor Bank Controllers Market |
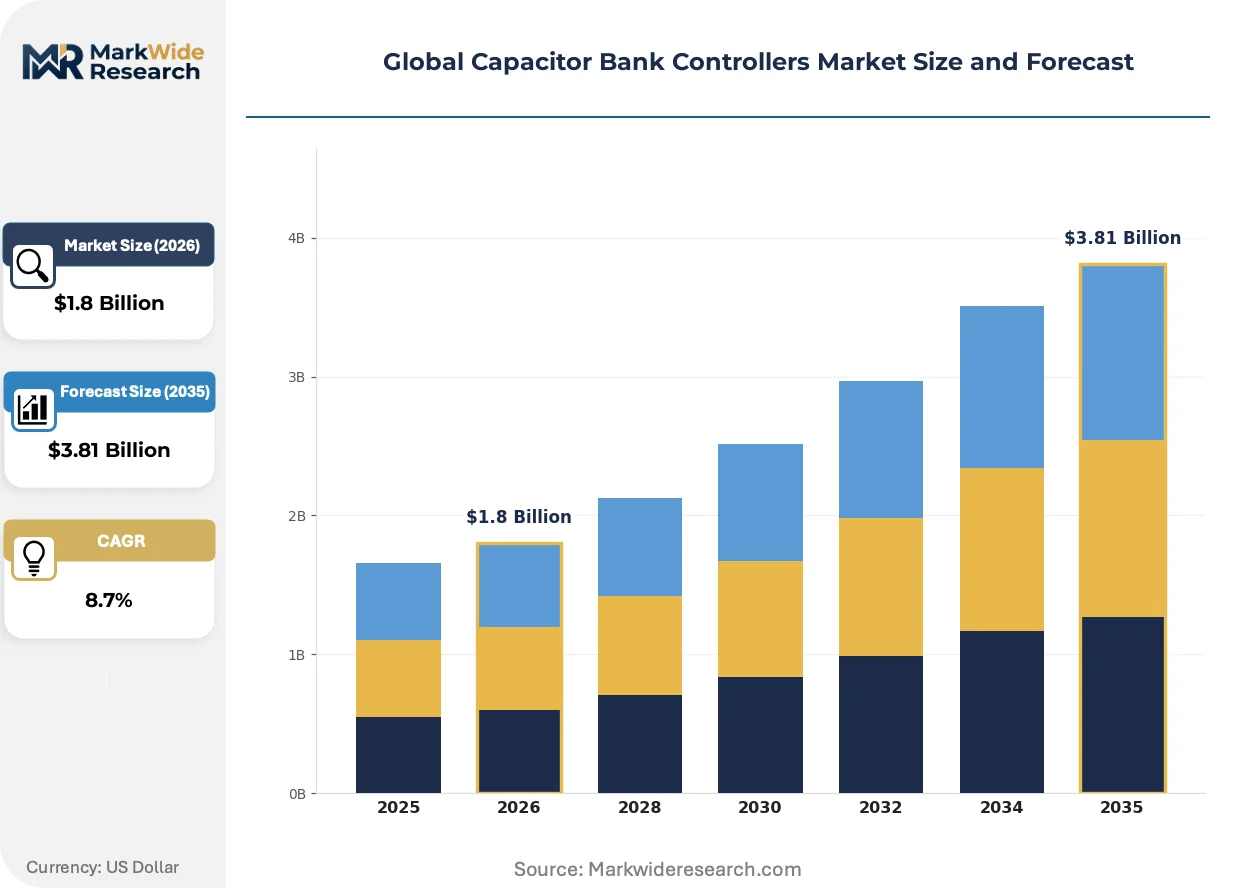
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Static, Dynamic, Hybrid, Automatic Technology: Microcontroller-Based, Programmable Logic Controller, Analog Control, Digital Control End User: Industrial, Commercial, Residential, Utilities Installation: On-site, Off-site, Integrated, Standalone |
| Companies Covered | Eaton, ABB, GE Grid Solutions, Schneider Electric, Mitsubishi Electric Corporation, S&C Electric Company, Schweitzer Engineering Laboratories, Beckwith Electric, Alstom SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Capacitor Bank Controllers Market Emerging Trajectories
Silicon carbide power semiconductors and edge-native control firmware are compressing controller response architectures from cycle-based to sub-cycle operation, reshaping competitive differentiation around thermal performance and switching precision.
Silicon carbide MOSFETs are consolidating the high-voltage controller segment by enabling faster switching frequencies with reduced thermal losses compared to silicon IGBTs. Grid operators in Germany and Japan prioritize SiC-based designs for 38kV substation applications where switching endurance exceeds 100,000 operations annually. This semiconductor transition is consolidating supplier margins toward vertically integrated power module manufacturers while pressuring discrete component assemblers.
The EU Green Deal's network modernization funding is mandating predictive maintenance capabilities in all publicly tendered grid infrastructure. Controller suppliers must embed vibration sensing, contact wear algorithms, and remote diagnostic APIs to qualify for German, French, and Italian transmission operator contracts. Medium-voltage substation projects across Northern Europe now specify IEC 61850 communication protocols as baseline requirements, excluding legacy electromechanical alternatives.
Hyperscale data center operators are unbundling capacitor bank controller procurement from traditional electrical contractor channels. Amazon Web Services, Microsoft, and Google now source controllers directly through qualified manufacturer lists, bypassing distribution intermediaries. This disintermediation concentrates in North American and Northern European markets where data center construction volumes exceed utility-scale industrial deployment.
Global Capacitor Bank Controllers Market Segmentation
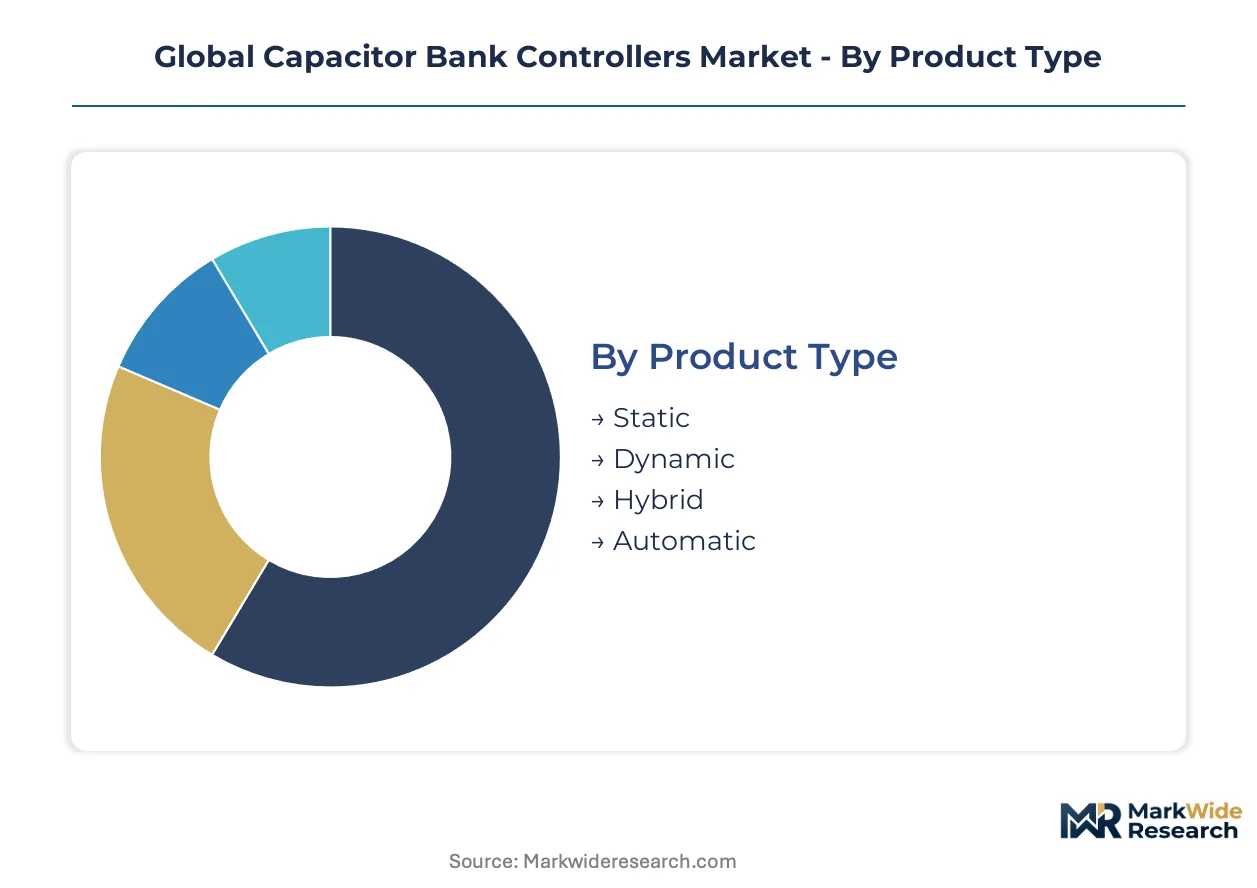
Capacitor bank controllers serve distinct operational profiles across power infrastructure, with each segment demanding tailored switching speeds, communication protocols, and harmonic tolerance specifications. Procurement patterns diverge sharply between utility-scale deployments requiring predictive maintenance integration and industrial installations prioritizing cost-effective static compensation.
Product Type:
Replacement cycles accelerate as aging electromechanical systems fail to meet modern grid code requirements for sub-cycle response and remote telemetry.
- Static:Electromechanical contactor-based designs dominate legacy installations with switching times of 5-10 cycles and minimal firmware complexity. Demand concentrates in India's state electricity boards where budget constraints favor proven reliability over digital features, though harmonic sensitivity limits deployment near variable frequency drives.
- Dynamic:Thyristor-switched capacitor banks achieve response times under one cycle through zero-voltage switching algorithms. German transmission operators specify dynamic controllers for 38kV substations managing photovoltaic ramp events, with switching endurance exceeding 100,000 operations annually driving premium pricing.
- Hybrid:Combines static stages for steady-state compensation with dynamic stages for transient response.
- Automatic:Self-optimizing controllers with embedded power factor algorithms requiring minimal operator intervention.
Volume placements concentrate in Static; the faster expansion belongs to Dynamic.
Technology:
Cost tiers separate legacy analog architectures from premium digital platforms commanding 3-4x unit pricing through predictive diagnostics capabilities.
- Microcontroller-Based:Embedded ARM or RISC-V processors execute real-time reactive power algorithms with harmonic analysis and event logging. China's GB/T 15576 compliance mandates concentrate demand in Jiangsu and Guangdong provinces where provincial grids require localized power factor correction with data retention.
- Digital Control:FPGA-accelerated architectures enable sub-millisecond switching decisions with IEC 61850 protocol integration. FERC Order 2222 aggregation requirements in Texas and California pull digital controllers into distributed energy resource management systems.
- Programmable Logic Controller:Industrial automation platforms adapted for capacitor switching through modular I/O expansion.
- Analog Control:Discrete component designs with potentiometer-adjusted setpoints and electromechanical relays.
Legacy Analog Control retains volume in cost-sensitive retrofit markets; Digital Control climbs the fastest as utilities mandate fleet-wide telemetry.
End User:
Application requirements range from residential single-phase correction to utility three-phase substation automation with synchronized phasor measurement.
- Utilities:Transmission and distribution operators deploy pole-mounted and substation-grade controllers with SCADA integration and cyber-hardened firmware. India's Power Grid Corporation and Germany's 50Hertz specify controllers with IEC 61850-9-2LE sampled value interfaces for process bus architectures.
- Industrial:Heavy manufacturing facilities require harmonic-filtering controllers capable of operating in 15-20% THD environments common with arc furnaces and rolling mills.
- Commercial:Shopping complexes and office buildings prioritize compact panel-mounted designs with simple power factor setpoint adjustment.
- Residential:Single-phase automatic capacitor controllers for distribution transformer secondary compensation.
Industrial procurement generates the highest unit volumes; Utilities demonstrate the steepest expansion trajectory through network modernization tenders.
Installation:
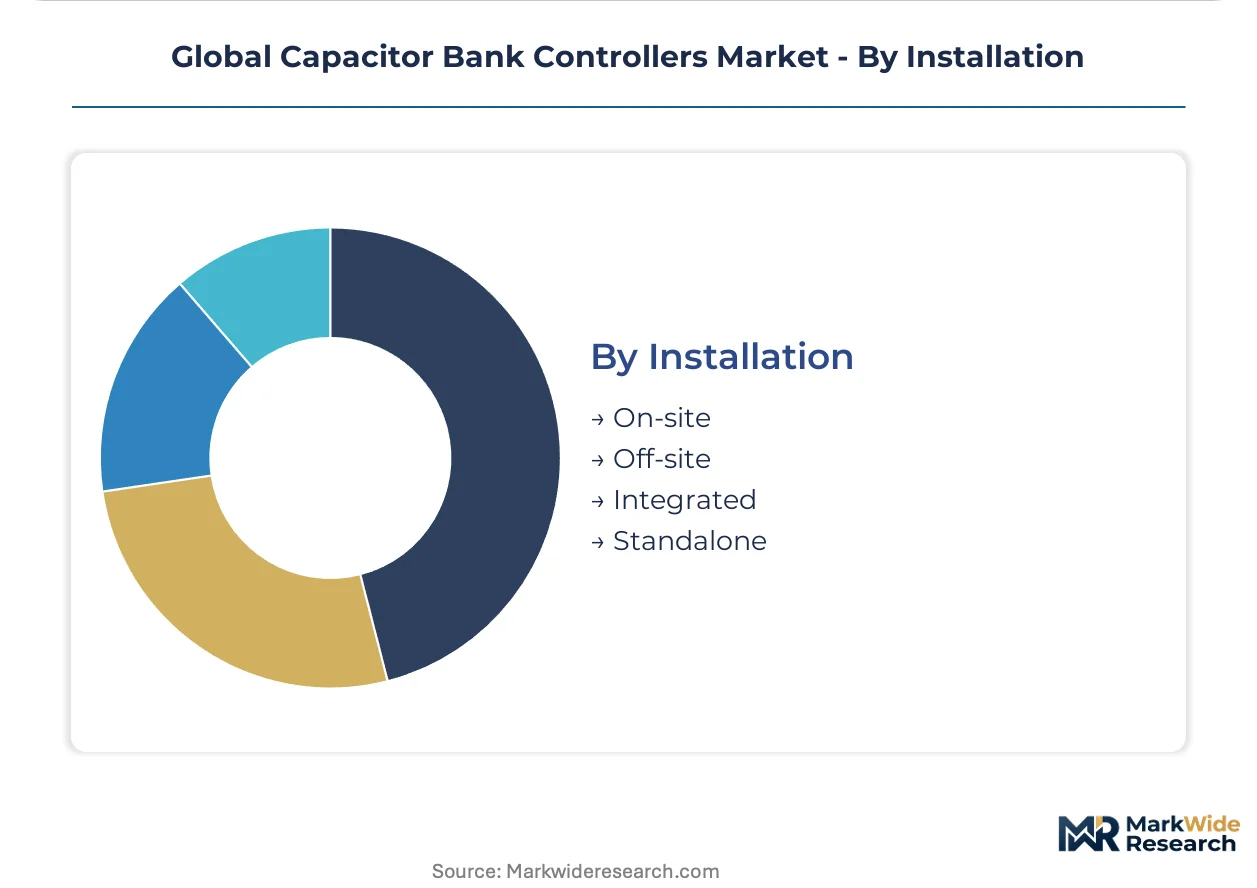
Supply chain configuration favors integrated solutions reducing field commissioning complexity versus standalone controllers requiring custom enclosure engineering.
- Integrated:Factory-assembled capacitor banks with pre-wired controllers, contactors, and protection relays in IP54-rated enclosures. Schneider Electric and ABB deliver integrated systems to French and Italian distribution operators under EU Green Deal network funding.
- Standalone:Controller-only procurement allowing retrofit of existing capacitor stages with new control logic.
- On-site:Field-programmed controllers commissioned after mechanical installation.
- Off-site:Pre-configured and tested systems shipped with parameter sets matching specific substation load profiles.
Integrated solutions capture volume through turnkey procurement; Standalone controllers gain share fastest in retrofit markets seeking to extend electromechanical asset life.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Special Economic Zones for power equipment manufacturing concentrate controller assembly in Gujarat and Maharashtra, drawing component suppliers into tax-advantaged corridors that reduce landed costs for provincial grid tenders.
China
Jiangsu and Guangdong provinces drive procurement through GB/T 15576 compliance mandates requiring localized power factor correction with data retention. The National Energy Administration enforces dual carbon goals that accelerate replacement of aging electromechanical switchgear. Yangtze River Delta manufacturing clusters supply solid-state controllers to State Grid Corporation tenders.
United States
Texas and California utilities deploy digital controllers for FERC Order 2222 distributed energy resource aggregation requirements. The Federal Energy Regulatory Commission enables grid-interactive asset status for capacitor banks participating in wholesale markets. ERCOT and CAISO control areas specify sub-cycle switching for photovoltaic ramp event management.
Germany
Transmission operators 50Hertz and TenneT specify IEC 61850-9-2LE sampled value interfaces for process bus architectures in 38kV substations. EU Green Deal network modernization funding mandates predictive maintenance capabilities in publicly tendered infrastructure. Northern European projects now require cyber-hardened firmware as baseline specifications.
India
State electricity boards in Maharashtra and Tamil Nadu favor static electromechanical designs where budget constraints outweigh digital feature requirements. The Central Electricity Authority enforces harmonic performance benchmarks that filter non-compliant suppliers from tender processes. Power Grid Corporation specifications pull IEC 61850 protocol integration into greenfield substation projects.
Global Capacitor Bank Controllers Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated solution providers capturing utility-scale tenders while standalone controller vendors penetrate retrofit industrial markets. The vendor base concentrates around three strategic archetypes: multinational electrical infrastructure conglomerates with substation automation portfolios, regional power electronics specialists with deep firmware capabilities, and captive manufacturers serving single national utilities. M&A activity targets predictive diagnostics software assets, while capacity expansion concentrates in East Asian semiconductor packaging corridors to secure IGBT and thyristor supply.
Among diversified electrical infrastructure groups, Eaton, ABB, and Schneider Electric exemplify the integrated-systems archetype that bundles capacitor control with broader power factor correction and energy management platforms. These Switzerland-based and France-based entities occupy positions where factory-assembled banks with pre-wired controllers qualify for EU Green Deal network funding in French and Italian distribution operator tenders. Their scale enables simultaneous compliance with IEC 61954, IEEE 1531, and GB/T 15576 across three continental regulatory regimes.
| Leading Market Players |
|---|
| Eaton |
| ABB |
| GE Grid Solutions |
| Schneider Electric |
| Mitsubishi Electric Corporation |
| S&C Electric Company |
| Schweitzer Engineering Laboratories |
| Beckwith Electric |
| Alstom SA |
| Others |
Supply Flow & Price Mechanics
Embedded firmware engineering scarcity in Germany's Baden-Württemberg region widens labor-cost differentials between digital controller specialists and commodity static controller assemblers, translating into three-tier pricing spreads across premium predictive-diagnostic platforms, mid-tier microcontroller systems, and economy-grade electromechanical units.
Pricing Analysis
Premium pricing attaches to sub-8-week lead-time guarantees for SiC-based dynamic controllers serving German transmission operators, while spot inventory of legacy static designs trades at 15-25% discounts in India's state electricity board tenders. Project-based contracting dominates utility-scale procurement with IEC 61850 protocol integration and predictive maintenance bundling as primary price differentiation drivers. Cost compression in economy tiers intensifies as Chinese provincial grids consolidate volume awards around GB/T 15576-compliant domestic suppliers. Industrial retrofit buyers exhibit highest price sensitivity, while data center operators demonstrate lowest sensitivity given power quality penalty avoidance.
Supply Chain Analysis
IGBT and thyristor supply rests on East Asian foundry concentration in China, South Korea, and Japan, with Yangtze River Delta packaging corridors capturing 60-70% of power semiconductor module assembly for controller integration. Critical dependencies span silicon carbide substrates from Japanese producers, copper busbar from Chilean-Chinese smelter partnerships, and ARM-core microcontrollers from Taiwanese foundries. Single-source vulnerability concentrates in 1700V+ SiC MOSFET supply where Wolfspeed and Infineon control qualified die production. Distribution runs through integrated solution providers for utility tenders and electrical distributors for industrial retrofit channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
IEC 61954 switching endurance certification creates a cost-of-compliance moat that filters non-compliant suppliers from German, French, and Italian transmission operator tenders, consolidating margin pools among pre-certified incumbents.
For Market Incumbents: Deploy predictive diagnostics software acquisitions to differentiate against emerging Asian challengers entering European markets through price-aggressive static controller offerings. Capture stranded value in Africa's underpenetrated distribution networks before Chinese suppliers establish local assembly partnerships. Reinforce certification investment in simultaneous IEEE 1531 and GB/T 15576 compliance to maintain cross-regional tender eligibility. For New Entrants and Emerging Players: Begin with Kenya and Nigeria's state distribution utilities where automated reactive power compensation remains below 15% penetration and incumbent relationships are weakest. Target standalone controller retrofits in India's aging electromechanical installed base as the most penetrable volume segment. Pursue direct engagement with hyperscale data center operators in Northern Europe bypassing traditional electrical contractor channels. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated power module manufacturers given SiC semiconductor transition catalysts consolidating controller margins toward upstream component suppliers. Long-term viability favors suppliers with captive firmware development capabilities and multi-standard certification portfolios. Watch FERC Order 2222 implementation velocity across Texas and California ISOs as inflection indicator for grid-interactive controller demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Diagnostics Software Acquisition | Embeds vibration sensing and contact wear algorithms qualifying for EU Green Deal network modernization tenders. |
| Backward Integration into SiC Power Modules | Captures margin compression from semiconductor transition while securing supply for 38kV substation applications. |
| IEC 61850 Protocol Certification Investment | Enables process bus architecture integration required by 50Hertz and TenneT transmission specifications. |
| African Distribution Network Partnership | Establishes first-mover positioning in Kenya and Nigeria before Chinese suppliers localize assembly operations. |
| Data Center Direct Procurement Channel | Bypasses electrical contractor intermediaries serving AWS, Microsoft, and Google qualified manufacturer lists. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with utility planning officers, substation automation engineers, EPC contractors, and power electronics procurement leads at transmission operators. FERC Order 2222 dockets, IEC 61954 certification registries, and State Grid Corporation tender databases provided compliance and volume validation. Bottom-up unit economics triangulated against top-down grid investment forecasts across the analysis window.
Segment-level modeling deployed product type, technology architecture, end-user application, and installation configuration as core dimensions, with regional regulatory framework and grid code harmonization status as cross-cutting variables. CAGRs derived from installed base replacement cycles, renewable integration mandates, and data center construction pipelines. Forecast inputs incorporated photovoltaic ramp event frequency, harmonic distortion tolerance thresholds, and semiconductor packaging capacity expansion.
Underlying measurement precision varies by segment; utility-scale and data center deployments carry tighter precision given disclosed tender values and operator capex guidance, while industrial retrofit estimates reflect sampling uncertainty. Forecasts reflect assumptions around IEC 61954 enforcement consistency, SiC substrate supply elasticity, and copper price trajectory. Supply chain disruption, grid code acceleration, and hyperscale data center demand volatility warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Terminal Block Market
Electrical Equipment
Vacuum Circuit Breaker Market
Electrical Equipment
Electrical Enclosures Market
Electrical Equipment
Central Vacuum Receivers Market
Electrical Equipment
Wire Splicing Kits Market
Electrical Equipment
Electric Enclosure Market
Electrical Equipment
Global Busbar Market
Electrical Equipment
Slip Ring Market
Electrical Equipment
Copper and Aluminum Terminal Blocks Market
Electrical Equipment
Europe High Voltage Switchgear Market
Electrical Equipment
Air Circuit Breaker Market
Electrical Equipment
High Voltage Porcelain Bushing Market
Electrical Equipment
Global Copper Clad Steel (CCS) Wire Market
Electrical Equipment
High Voltage Insulator Market
Electrical Equipment
Asia-Pacific Vacuum Circuit Breakers Market
Electrical Equipment
Europe Electrical Bushing Market