
 Contactor-based Transfer Switch Market | 2026-2036
Contactor-based Transfer Switch Market Size, Share, and Industry Trends Forecast 2026-2036
Contactor-based Transfer Switch Market Insights
The NFPA 110 standard for emergency and standby power systems is pivoting the cost-of-entry calculus for transfer switch manufacturers, requiring enhanced testing protocols and documentation that favor established suppliers. ABB leverages its integrated power distribution portfolio to anchor premium positioning in data center applications. Schneider Electric sustains technology leadership through its digital energy management platforms embedded in automatic transfer switch designs. Siemens competes on manufacturing scale across medium voltage and high voltage product lines.
A contactor-based transfer switch is an electromechanical device that uses electrically operated switches to transfer load connections between primary and alternate power sources, typically rated for operation at 50-60 Hz with interrupting capacities up to 200 kA depending on voltage class. Its primary industrial purpose is ensuring uninterrupted power supply to critical loads during utility failure or maintenance events. Automatic transfer switches command the largest revenue pool among type segments due to their essential role in data center uptime architectures. Medium voltage ratings are capturing accelerated interest from industrial plant operators modernizing captive power infrastructure. The utilities end-user segment occupies the deepest margin pools where long-term service contracts attach to initial equipment sales.
The US National Electrical Code, administered by the National Fire Protection Association, shapes product design requirements and installation practices for transfer switches in commercial and industrial buildings. China's GB standards and MIIT technical specifications govern telecommunications facility power switching equipment, while India's Central Electricity Authority mandates reliability benchmarks for grid-connected backup systems. Stakeholders must monitor evolving harmonics between national electrical codes and sector-specific uptime standards as data center load densities continue rising.
Market Dynamics
Utility grid instability across South Asia and tightening uptime mandates from data center operators are forcing accelerated replacement cycles for electromechanical switching equipment. Procurement teams now prioritize interrupting capacity ratings and digital monitoring capabilities over initial capital cost.
Growth Catalysts
- NFPA 110 compliance mandates:US data center operators must install automatic transfer switches with enhanced testing documentation, creating specification lock-in for certified suppliers.
- Telecommunications infrastructure expansion:China's MIIT is tightening power reliability standards for 5G base stations, requiring redundant switching architectures in rural and urban deployments.
- Captive power modernization:Industrial plant operators in India are retrofitting medium voltage transfer switches to integrate solar-diesel hybrid systems.
Market Restraints
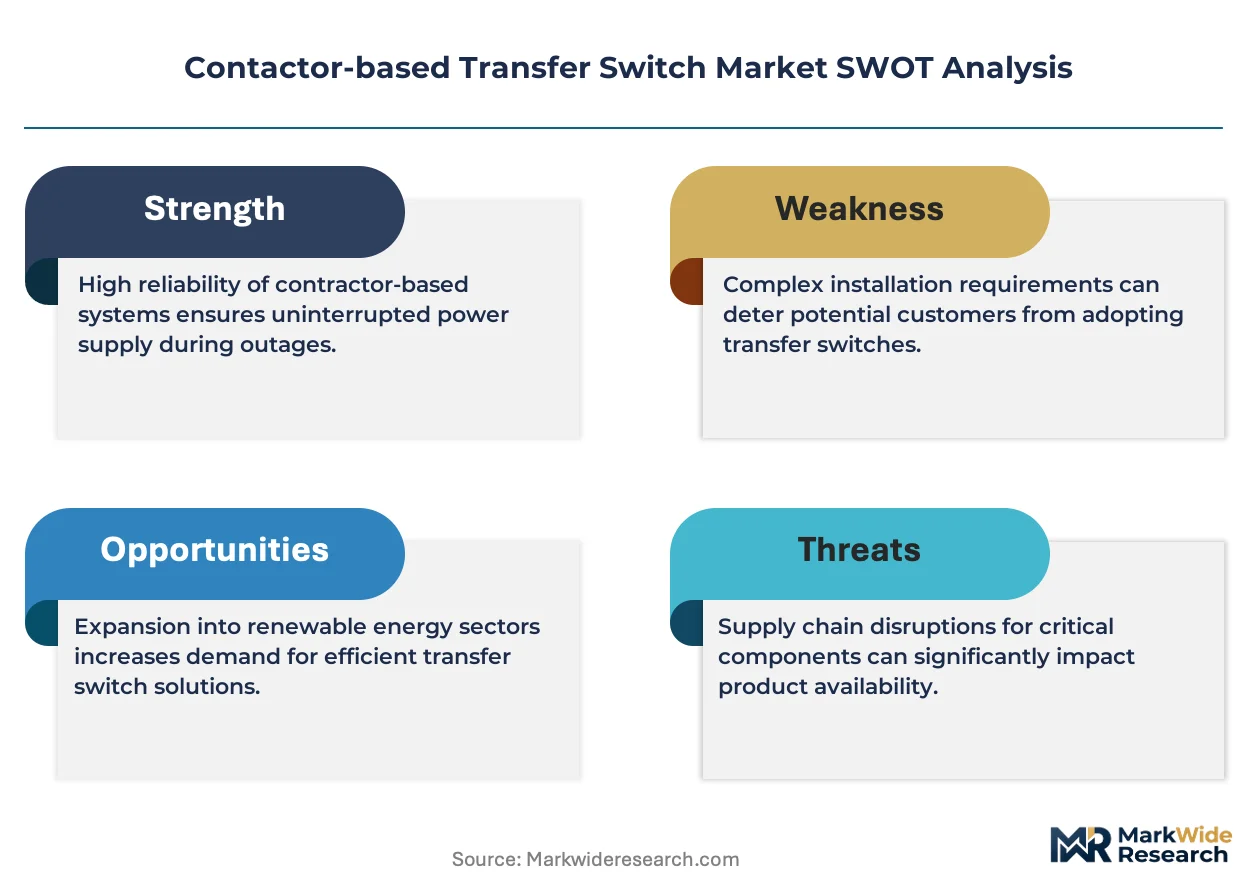
- Copper and silver contact volatility:Raw material price swings compress margin predictability for manufacturers dependent on electromechanical contactor assemblies.
- Technical limitation in arc quenching:Contactor-based designs face interrupting capacity ceilings near 200 kA that constrain adoption in ultra-high fault current environments.
- Substitution from solid-state switches:Silicon-controlled rectifier and insulated-gate bipolar transistor alternatives are capturing sub-100 kA applications with faster transfer speeds.
Strategic Opportunities
- Underpenetrated industrial clusters:Vietnam's manufacturing zones lack standardized backup power switching, creating first-mover advantage for automatic transfer switch suppliers.
- Technology convergence:Integration of contactor-based switches with IEC 61850 digital substation protocols enables predictive maintenance and remote diagnostics.
- Distribution innovation:Direct procurement from original equipment manufacturers is displacing traditional electrical distributor channels in large data center contracts.
Industry Challenges
- Skill gap in medium voltage commissioning:Qualified field engineers for 15 kV and above installations remain scarce in Southeast Asian markets.
- Certification timeline compression:UL 1008 and IEC 60947-6-1 testing cycles now exceed 18 months, delaying product launches.
- Legacy system integration friction:New automatic transfer switches must interface with decades-old generator control panels without full infrastructure replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Contactor-based Transfer Switch Market |
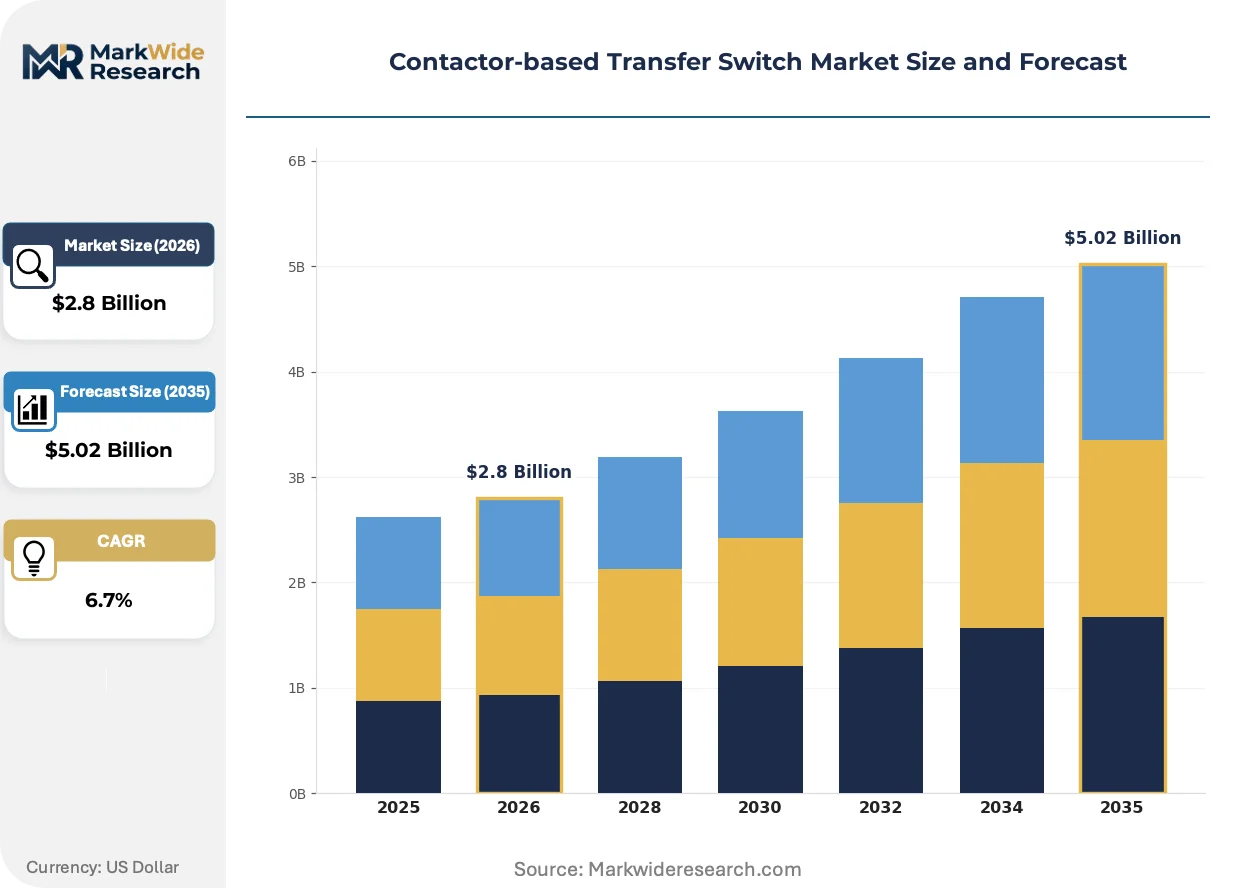
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Automatic, Manual, Motorized, Electronic, Pneumatic Voltage Rating: Low Voltage, Medium Voltage, High Voltage, Ultra High Voltage Application: Data Centers, Commercial Complexes, Industrial Plants, Telecommunications Facilities, Government Buildings End User: Utilities, Manufacturing Facilities, Construction Sites, Educational Institutions, Hospitality Sector |
| Companies Covered | ABB, Schneider Electric, Eaton, Siemens, Cummins, Caterpillar, Generac Power Systems, Kohler, Vertiv, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Contactor-based Transfer Switch Market Trends and Innovations
Digitalization of power distribution is embedding intelligence into traditionally electromechanical devices. Manufacturers are racing to differentiate through embedded analytics and predictive capabilities rather than hardware specifications alone.
Smart contactor-based transfer switches are integrating microprocessor-based controllers with real-time load monitoring and self-diagnostic algorithms. Data center operators in the United States are specifying these units for Tier III and Tier IV facilities requiring sub-100 millisecond transfer times. This integration is compressing the traditional separation between switching hardware and building management systems.
The US National Electrical Code's latest cycle introduced stricter arc flash labeling and coordination study requirements for transfer switch installations. Electrical contractors must now document selective coordination with upstream overcurrent protective devices. Commercial building projects in California and Texas are experiencing permitting delays as jurisdictions adapt inspection protocols.
Buyers are unbundling after-sales service contracts from initial equipment purchases, forcing manufacturers to compete on lifecycle cost transparency. Large industrial accounts in India now procure maintenance separately through third-party electrical contractors. This disintermediation is most visible in Maharashtra and Gujarat, where captive power users negotiate multi-year service agreements independent of capital equipment tenders.
Contactor-based Transfer Switch Market Segmentation
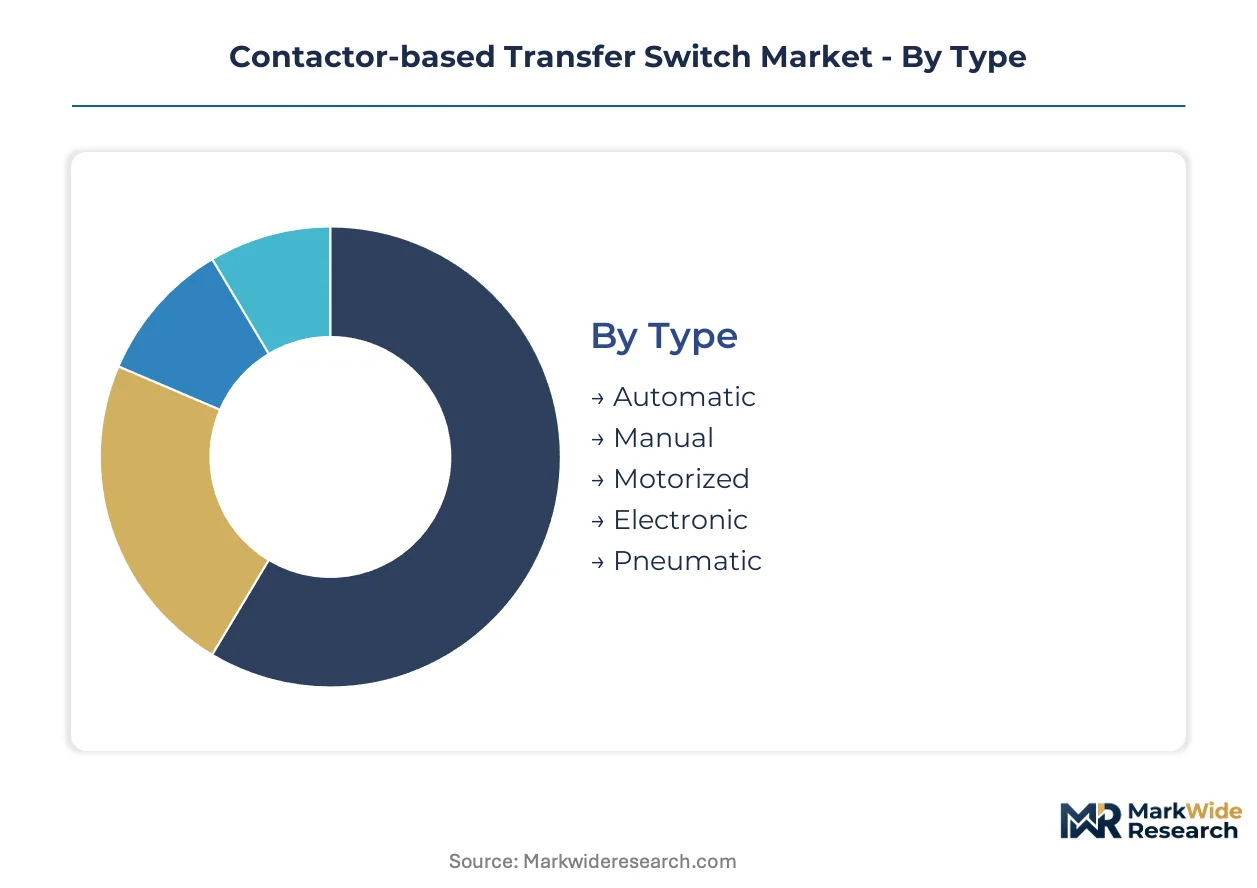
Segmentation in the contactor-based transfer switch market reflects divergent technical requirements across power reliability tiers. Buyers prioritize interrupting capacity, transfer speed, and integration complexity based on load criticality and voltage class.
Type:
Buyers in this category differentiate by automation level and response time requirements for critical load protection.
- Automatic:Microprocessor-controlled units execute source transfers without operator intervention, typically achieving sub-100 millisecond switching. Data center operators in the United States specify these for Tier III and Tier IV facilities under NFPA 110 uptime mandates.
- Manual:Operator-actuated designs rely on physical switching mechanisms for load transfer decisions. Small commercial installations in India deploy these where capital constraints outweigh automation benefits and grid instability is managed through human oversight.
- Motorized:Electric motor drives enable remote operation with mechanical simplicity exceeding electronic alternatives. Industrial plant operators favor these for medium voltage applications requiring robust arc handling without solid-state complexity.
- Electronic:Solid-state hybrid architectures combine contactor durability with silicon-controlled rectifier speed for specialized sub-100 kA environments. Telecommunications facilities in China integrate these for 5G base station redundancy under MIIT reliability standards.
- Pneumatic:Compressed air actuation delivers high-force switching for extreme fault current conditions. Heavy manufacturing environments with explosive atmospheres specify these where electrical actuation poses ignition risks.
Volume sits with Automatic; growth tilts toward Electronic.
Voltage Rating:
Procurement patterns in this dimension track infrastructure modernization cycles and captive power integration trends.
- Low Voltage:Rated below 1 kV, these units dominate commercial building and small industrial installations. Construction activity in Vietnam's manufacturing zones is absorbing capacity for standardized backup power architectures.
- Medium Voltage:Covering 1 kV to 52 kV, this class is capturing accelerated interest from industrial operators retrofitting solar-diesel hybrid systems. India's captive power users in Maharashtra and Gujarat are modernizing aging switchgear with these ratings.
- High Voltage:Above 52 kV ratings serve transmission-level switching and large industrial substations. Utility procurement in the United States attaches long-term service contracts to these capital-intensive installations.
- Ultra High Voltage:Exceeding 245 kV, these specialized designs address grid interconnection and bulk power transfer. National transmission operators specify these for strategic infrastructure with decade-long replacement cycles.
Revenue concentrates in Medium Voltage; expansion is steepest in Low Voltage.
Application:
End-use differentiation centers on uptime tier requirements and regulatory compliance intensity.
- Data Centers:Hyperscale and colocation facilities demand automatic transfer switches with embedded monitoring and sub-100 millisecond performance. NFPA 110 compliance in the United States is forcing specification upgrades across Tier III and Tier IV builds.
- Commercial Complexes:Office buildings and retail centers balance first cost against code-minimum reliability. California and Texas jurisdictions are experiencing permitting delays as NEC arc flash labeling requirements reshape installation protocols.
- Industrial Plants:Process manufacturing and heavy industry prioritize interrupting capacity and selective coordination with generator controls. Legacy system integration friction complicates upgrades in decades-old captive power installations.
- Telecommunications Facilities:5G base stations and central offices require redundant switching architectures for continuous service. China's MIIT is tightening power reliability standards that mandate automatic transfer capability in rural and urban deployments.
- Government Buildings:Critical infrastructure protection drives hardened specifications for emergency operations centers. Procurement cycles extend through federal budgeting processes with multi-year lead times.
Specification intensity peaks in Data Centers; contract velocity runs highest in Telecommunications Facilities.
End User:
Customer type determines pricing leverage, service attachment rates, and channel structure.
- Utilities:Grid operators and generation companies procure through multi-year frameworks with lifecycle service bundling. These accounts occupy the deepest margin pools where maintenance contracts extend across 15-20 year equipment lifespans.
- Manufacturing Facilities:Discrete and process industries are unbundling service from equipment purchases, forcing transparency in total cost of ownership. Large accounts in India now negotiate maintenance separately through third-party electrical contractors.
- Construction Sites:Temporary power applications demand rapid deployment with minimal commissioning complexity. Rental equipment channels dominate with standardized low voltage units.
- Educational Institutions:University and K-12 campuses balance budget constraints against code compliance for emergency systems. State procurement vehicles aggregate demand across multiple facilities.
- Hospitality Sector:Hotels and resorts prioritize guest safety systems with automatic transfer for life safety loads. Brand standards from major chains drive specification consistency across properties.
Service revenue concentrates with Utilities; price pressure intensifies in Manufacturing Facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates demand growth for contactor-based transfer switches as utility grid instability forces commercial and industrial investment in backup power infrastructure. The United States shapes premium specifications through NFPA 110 compliance mandates for data center uptime. China drives telecommunications infrastructure procurement under tightening MIIT reliability standards.
United States
Data center operators in Northern Virginia and Dallas-Fort Worth are expanding automatic transfer switch procurement to meet Tier III and Tier IV uptime requirements. NFPA 110 mandates enhanced testing protocols and documentation that favor established suppliers with certification depth. California and Texas jurisdictions are experiencing permitting delays as NEC arc flash labeling requirements reshape inspection protocols for commercial installations.
China
MIIT is tightening power reliability standards for 5G base stations, requiring redundant switching architectures in rural and urban deployments. GB standards and MIIT technical specifications govern telecommunications facility power switching equipment with escalating fault tolerance requirements. Yangtze River Delta manufacturing clusters are absorbing capacity for standardized backup power architectures serving expanding digital infrastructure.
India
Utility grid instability across Maharashtra and Gujarat drives commercial and industrial investment in backup power switching equipment. Central Electricity Authority mandates reliability benchmarks for grid-connected backup systems that accelerate replacement cycles. Captive power users in these western states are retrofitting medium voltage transfer switches to integrate solar-diesel hybrid systems.
Germany
Industrial plant operators in North Rhine-Westphalia and Bavaria are modernizing captive power infrastructure with medium voltage transfer switches. CE marking and IEC 60947-6-1 certification requirements shape product design for European market access. Automotive manufacturing clusters around Stuttgart and Munich specify automatic transfer switches with embedded monitoring for production line continuity.
Vietnam
Manufacturing zones in Ho Chi Minh City and Hanoi lack standardized backup power switching, creating first-mover advantage for automatic transfer switch suppliers. Foreign direct investment in electronics assembly is driving demand for reliable power infrastructure. Industrial parks in Binh Duong and Bac Ninh provinces are specifying low voltage units for rapid deployment in new facility construction.
Contactor-based Transfer Switch Market Competitive Landscape
European and North American producers anchor the premium tier; Asian specialists hold volume positions in standardized segments. The market structures around three tiers: integrated electrical conglomerates with full power distribution portfolios, dedicated power generation equipment manufacturers with captive switching lines, and regional fabricators serving price-sensitive procurement. Strategic archetypes include specification leaders competing on certification depth, scale players optimizing manufacturing across voltage classes, and niche specialists targeting telecommunications or data center verticals. Dominant competitive moves include portfolio diversification into digital energy management platforms and geographic expansion into underpenetrated industrial clusters.
Among the integrated electrical conglomerates, ABB leverages its power distribution breadth to anchor premium positioning in data center applications. Schneider Electric exemplifies the digital convergence archetype through embedded energy management platforms. Siemens occupies a scale-driven position across medium voltage and high voltage product lines. These three represent contrasting strategic postures: ABB emphasizes integrated system sales, Schneider Electric prioritizes software-enabled differentiation, and Siemens competes on manufacturing scope and voltage range coverage.
| Leading Market Players |
|---|
| ABB |
| Schneider Electric |
| Eaton |
| Siemens |
| Cummins |
| Caterpillar |
| Generac Power Systems |
| Kohler |
| Vertiv |
| Others |
Pricing and Supply Chain Analysis
Copper and silver contact price volatility cascades through electromechanical switch manufacturing into tiered pricing structures that separate UL 1008-certified premium suppliers from uncertified regional fabricators serving price-sensitive Indian captive power users.
Pricing Analysis
Volume concentrates in standardized low voltage automatic units where manufacturing scale anchors competitive pricing, while margin pools deepen in medium voltage and high voltage classes where IEC 60947-6-1 certification creates specification lock-in. Three-tier pricing structure across premium certified, standard compliant, and economy unbranded levels reflects divergent testing documentation depth and after-sales service bundling. Cost compression in economy tiers is intensifying because raw material swings compress margin predictability for contactor assembly-dependent producers. Manufacturing facilities in India exhibit highest price sensitivity, whereas US data center operators prioritize interrupting capacity and digital monitoring capabilities over capital cost.
Supply Chain Analysis
Dual-sourcing requirements from US data center operators and European industrial accounts mandate multi-supplier qualification for copper contact forgings, insulating materials, and microprocessor controllers. Manufacturing concentrates in China for contactor subassemblies, Germany for precision switching mechanisms, and India for standardized low voltage enclosures. Raw material dependencies center on copper cathodes from Chilean and Peruvian mining operations, silver for contact plating, and epoxy resin systems for insulation. Single-source vulnerability in semiconductor-based controller chips creates bottleneck exposure. Distribution runs through electrical distributors for small commercial accounts, while direct OEM procurement dominates large data center and utility contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NFPA 110 compliance mandates erect a cost-of-compliance barrier that protects certified incumbents while forcing uncertified competitors into uneconomical testing investments or market exit.
For Market Incumbents: To counter solid-state switch substitution in sub-100 kA applications, deepen certification moats through accelerated UL 1008 and IEC 60947-6-1 testing cycle completion, and anchor premium positioning via backward integration into copper contact manufacturing to insulate margin from commodity volatility. For New Entrants and Emerging Players: Direct procurement channels from hyperscale data center developers offer the most penetrable route around established distributor relationships, targeting Vietnamese manufacturing zones lacking standardized backup power switching infrastructure with rapid-deployment low voltage units and unbundled third-party maintenance partnerships. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap specialists with stranded IEC 61850 digital protocol development assets in Germany and India, where captive power modernization and telecommunications infrastructure expansion create acquisition platform potential; watch for copper price stabilization as inflection signal for margin recovery in electromechanical assembly-dependent producers.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Acceleration Investment | Compressing UL 1008 testing cycles below 18 months captures specification lock-in from NFPA 110-mandated data center builds. |
| IEC 61850 Protocol Integration | Embedding digital substation compatibility enables predictive maintenance contracts with European utility accounts. |
| Copper Contact Backward Integration | In-house forging capacity insulates margin from London Metal Exchange price swings in contactor assemblies. |
| Vietnam Distribution Partnership | First-mover positioning in Binh Duong and Bac Ninh industrial parks captures foreign direct investment-driven demand. |
| Unbundled Service Model Launch | Separating maintenance contracts from capital equipment tenders aligns with Indian manufacturing facility procurement shifts. |
Research Methodology
Trade association filings, customs import records, and electrical equipment certification databases formed the secondary backbone, cross-referenced against primary interviews with data center engineering directors, utility substation planners, industrial plant maintenance managers, and electrical distributor procurement heads. Bottom-up unit shipment estimates triangulated against top-down voltage class revenue analysis.
Historical trendline analysis of replacement cycle compression and regulatory mandate timing informed projection modeling across the forecast period. Segmentation dimensions included automation level, voltage rating tier, end-use application, and regional regulatory cluster. CAGRs derived from fitted growth curves adjusted for copper price elasticity and certification timeline constraints. Forecast inputs incorporated MIIT telecommunications reliability standard evolution and Indian Central Electricity Authority mandate enforcement patterns.
The model holds under stable copper pricing and current NFPA 110 testing documentation requirements; deviation in raw material volatility spikes or UL certification timeline compression would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
DC Circuit Breaker Market
Switches
Smart Dimmer Switch Market
Switches
KVM Switch Market
Switches
South America Low Voltage Switchgear Market
Switches
UK Reed Sensors Switches Market
Switches
Electric Switch Market
Switches
United States X by Wire Systems Market
Switches
Pressure Switch Market
Switches
United States Switchgear Market
Switches
Europe Push Buttons and Signaling Devices Market
Switches
Optical Cross Connect (OXC) Switches Market
Switches
Electromechanical Microwave Switch Market
Switches
Japan Reed Sensors Switches Market
Switches
Micro Switch Market
Switches
Matrix Switches Market
Switches
Disconnect Switch Market