
 Wire Splicing Kits Market | 2026-2036
Wire Splicing Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Wire Splicing Kits Market Insights
Electrical distributor networks is rewriting how wire splicing kits reach end users, with bulk procurement platforms and direct contractor portals displacing traditional hardware retail. 3M Company leverages its adhesive and electrical tape heritage to anchor premium kit positioning across North American industrial channels. TE Connectivity competes through deep connector integration, bundling splicing hardware with its sensor and terminal portfolios. Panduit dominates structured cabling adjacencies, extending its data-center footprint into power splicing applications for integrated infrastructure builds.
Wire splicing kits are assemblies of connectors, insulation sleeves, crimping tools, and sealing compounds designed to join, terminate, or repair electrical conductors while restoring dielectric integrity and mechanical tensile strength. These kits typically accommodate conductor gauges from 22 AWG to 4/0 AWG and must pass voltage-withstand testing per IEC 61215-1 for photovoltaic splices or UL 486D for underground applications. Specialty kits lead margin pools where heat-shrink environmental sealing and gel-filled underground configurations command price premiums over commodity manual sets. Heavy-duty kits sustain growth in utility and renewable energy installations where aluminum-to-copper transitions and submersible splices require engineered solutions beyond standard crimp barrels.
UL standards in the United States and IEC frameworks in Europe shape product design by mandating temperature cycling, corrosion resistance, and pull-out force thresholds that determine market access. The EU Green Deal and national electrical codes in Germany through KBA-influenced automotive harness standards and France through ANSM-tracked industrial safety protocols are elevating material traceability and recyclability requirements for splicing components. Stakeholders must monitor how RoHS substance restrictions and emerging PFAS regulations in the European Union and individual US states will alter insulation compound formulations and supplier qualification timelines.
Market Dynamics
Electrical contractor procurement consolidation is compressing distribution layers and forcing kit manufacturers to bypass traditional hardware retail through direct digital portals and bulk purchasing platforms.
Growth Catalysts
- EV Charging Infrastructure Mandates:Federal and state-level EV charging rollout requirements in the United States are accelerating underground and weather-resistant splicing kit deployment for grid interconnection work.
- RoHS and PFAS Compliance Deadlines:The European Union's tightening substance restrictions are phasing out legacy insulation compounds, creating replacement demand for reformulated gel-filled and heat-shrink configurations.
- Aluminum-to-Copper Transition Engineering:Renewable energy installations and utility grid modernization projects require specialized transition splices that accommodate dissimilar metal joining with corrosion-resistant metallurgy.
Market Restraints
- Copper and Aluminum Price Volatility:Raw material cost swings for conductor metals and petroleum-derived insulation compounds compress kit margins and complicate long-term contract pricing.
- East Asian Connector Concentration:Crimp barrel and terminal manufacturing clusters in China and Taiwan create supply vulnerability for North American and European kit assemblers.
- Pre-Insulated Push-In Substitution:Tool-free push-in connector technology threatens manual crimp kit volumes in residential and light commercial wiring segments.
Strategic Opportunities
- India Grid Modernization:The country's rural electrification expansion and smart metering programs present untapped demand for weatherproof splicing hardware in tropical climate conditions.
- Photovoltaic DC Splicing Specialization:IEC 61215-1 certified kits for solar string wiring represent a high-margin niche as utility-scale solar accelerates across multiple continents.
- Direct Contractor E-Commerce:Bulk procurement platforms and mobile-optimized ordering systems are capturing electrical contractor spend previously flowing through distributor counter sales.
Industry Challenges
- Certified Installer Shortage:UL 486D and IEC qualification requirements for underground and photovoltaic applications outpace the supply of trained field technicians.
- Multi-Standard Compliance Burden:Kit manufacturers must simultaneously satisfy divergent UL, IEC, and emerging national standards, extending product development cycles and testing costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wire Splicing Kits Market |
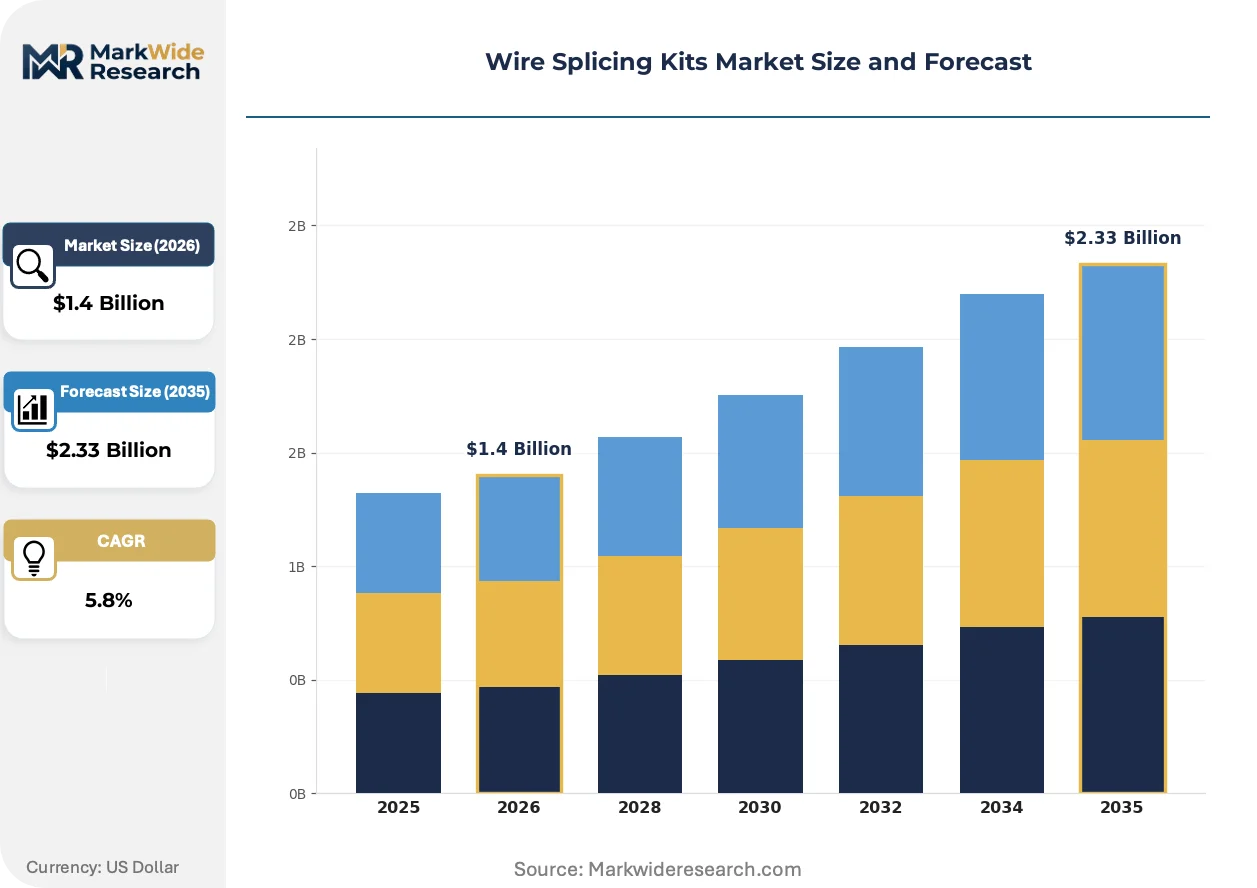
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.33 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Kits, Manual Kits, Specialty Kits, Heavy-Duty Kits Application: Automotive, Electrical, Consumer Electronics, Industrial Equipment End User: Technicians, DIY Enthusiasts, Electrical Contractors, Manufacturers Material: Copper, Aluminum, Plastic, Rubber |
| Companies Covered | 3M Company, Molex, Panduit, HellermannTyton, Ideal Industries, ABB, TE Connectivity, Phoenix Contact, Gardner Bender, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wire Splicing Kits Market Trends and Innovations
Digital integration across kit specification, procurement, and field installation is compressing traditional supply chain intermediaries and enabling real-time compliance verification.
Smart crimping tools with embedded force sensors and Bluetooth connectivity are digitizing quality assurance in field installations. Electrical contractors deploying these systems transmit crimp compression data directly to project management platforms. The technology is digitizing documentation workflows that previously relied on manual torque logs and paper certificates.
The EU Green Deal's material traceability requirements are mandating digital product passports for electrical components entering European markets. Manufacturers must now embed recyclability data and substance declarations into kit packaging and online portals. Industrial buyers in Germany and France are screening suppliers based on PFAS-free certifications and circular economy compliance scores.
Electrical distributors are unbundling after-sales technical support from product sales, offering subscription-based installation training and code-compliance consulting. Contractor purchasing departments are negotiating these service contracts separately from hardware procurement. The shift is most pronounced in the United States, where master electrician licensing requirements vary by state and drive demand for jurisdiction-specific code guidance.
Wire Splicing Kits Market Segmentation
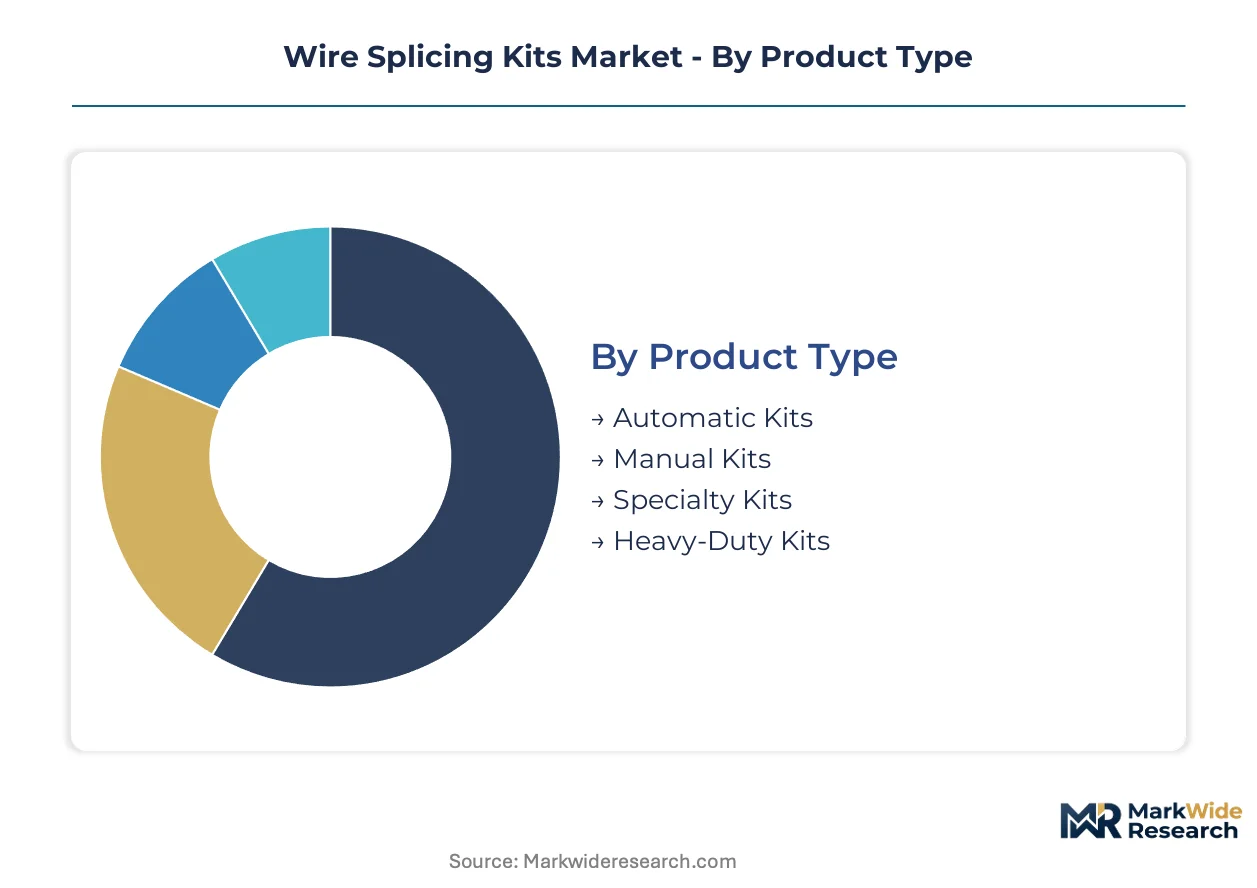
Wire splicing kit manufacturers face divergent service intensity requirements across product tiers, with heavy-duty and specialty configurations demanding field engineering support while manual kits move through self-service channels. Segmentation strategy must align technical assistance investment with margin profiles and procurement consolidation patterns.
Product Type:
After-sales service intensity varies sharply across product tiers, with engineered solutions requiring certified installer networks and commodity kits functioning through minimal-touch distribution.
- Automatic Kits:These systems integrate pneumatic or battery-powered crimping mechanisms with die sets calibrated for specific conductor gauges. Demand concentrates in Germany and Japan where automotive harness manufacturers specify tool-plus-consumable bundles to reduce operator error rates. OEM service contracts dominate procurement, bundling calibration maintenance with consumable replenishment.
- Manual Kits:Hand-operated crimp tools with interchangeable dies remain the volume staple for residential electrical contractors across the United States. Price compression from direct-to-contractor e-commerce platforms is eroding distributor margins while expanding addressable reach into rural markets previously served by hardware retail.
- Specialty Kits:Gel-filled underground and heat-shrink environmental sealing configurations command technical specification support from utility procurement departments.
- Heavy-Duty Kits:Aluminum-to-copper transition splices and submersible configurations require metallurgical engineering consultation during project design phases.
By volume, Manual Kits leads. By growth pace, Specialty Kits is ahead.
Application:
Application segmentation tracks voltage environment and regulatory exposure, with industrial and automotive applications imposing the strictest certification burdens.
- Automotive:Wire splicing kits for vehicle harnesses must satisfy KBA-influenced vibration and thermal cycling standards in Germany plus NHTSA electrical safety protocols in the United States. EV battery pack and charging infrastructure wiring is expanding kit specifications toward high-amperage copper compression splices.
- Electrical:Grid interconnection and building wiring applications span residential service upgrades to commercial EV charging installations. NEC compliance variations across US states create fragmented specification requirements that favor kit manufacturers with jurisdiction-specific code expertise.
- Consumer Electronics:Miniaturized crimp and IDC connectors for appliance internal wiring prioritize cost minimization over field serviceability.
- Industrial Equipment:Motor termination and control panel applications in France and Italy require ANSM-tracked industrial safety documentation.
Electrical applications generate the highest absolute volume. Automotive applications are climbing the fastest.
End User:
End user segmentation reveals procurement authority concentration, with electrical contractors consolidating spend while DIY channels fragment.
- Electrical Contractors:Master electricians and journeyman crews in the United States now procure through bulk digital platforms that displace traditional distributor relationships. These buyers prioritize UL-listed configurations with jurisdiction-specific code compliance documentation.
- Technicians:Factory maintenance and field service personnel in Germany and Japan specify kits integrated with employer-mandated tool calibration programs. Demand concentrates in automotive and industrial equipment maintenance where traceable crimp quality records reduce liability exposure.
- DIY Enthusiasts:Residential consumers purchasing through home improvement retail and online marketplaces drive manual kit volumes with minimal technical support requirements.
- Manufacturers:OEM harness builders in China and Mexico integrate kit components into production line termination stations.
Electrical Contractors command the largest share of value. Technicians are gaining share fastest.
Material:
Material selection determines corrosion compatibility, conductivity requirements, and regulatory compliance pathways across installation environments.
- Copper:Oxygen-free copper conductors dominate electrical and industrial applications where conductivity standards are non-negotiable. RoHS substance restrictions in the European Union are tightening traceability requirements for copper sourcing and alloy composition declarations.
- Aluminum:Lightweight conductors with specialized transition metallurgy serve utility and renewable energy installations where conductor weight reduction justifies joint engineering complexity. PFAS-free insulation compound development is altering aluminum splice sealing specifications.
- Plastic:Nylon and polypropylene housing materials for connector bodies face recyclability scoring under EU Green Deal digital product passport requirements.
- Rubber:EPDM and silicone sealing gaskets in underground and submersible kits must satisfy REACH substance restrictions while maintaining dielectric performance.
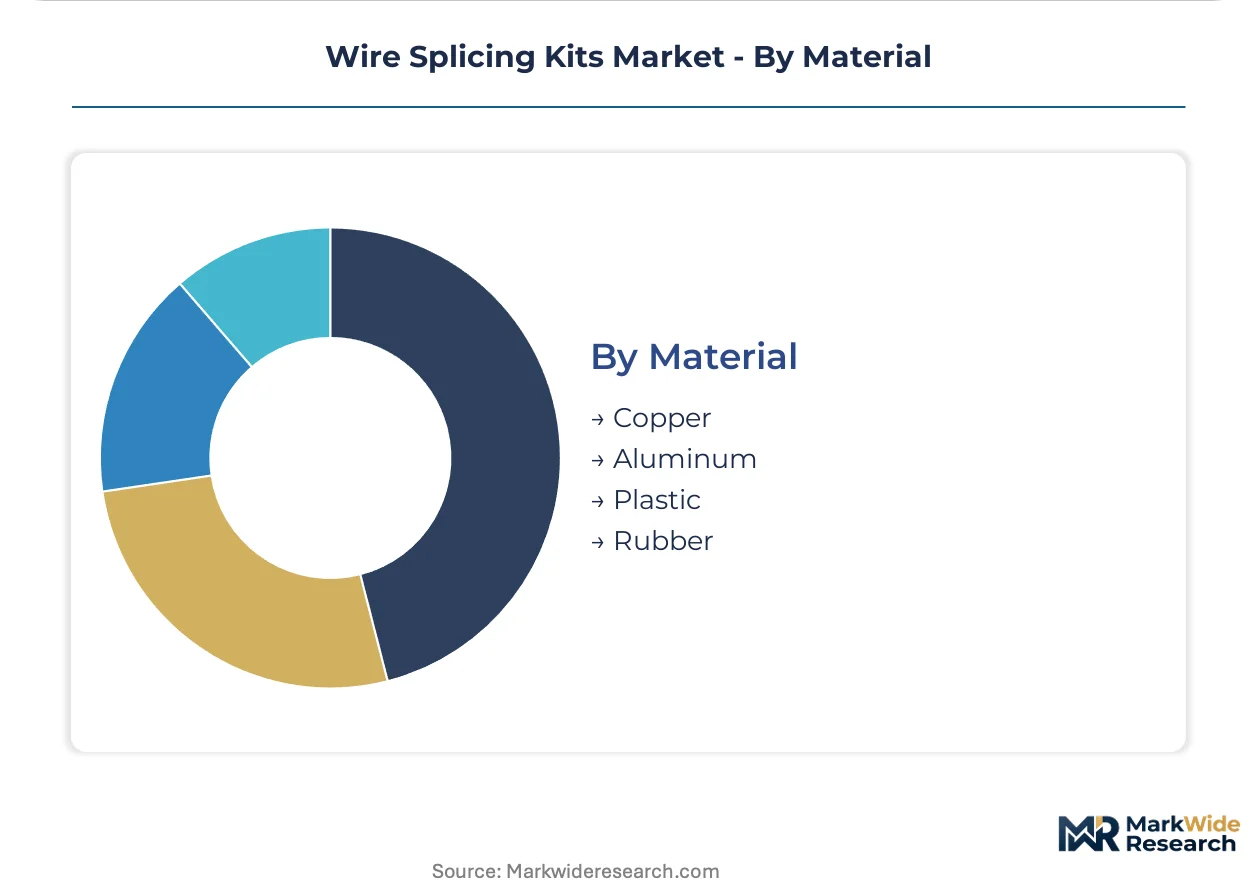
Copper leads by installed value. Aluminum is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
UL standards in the United States anchor the regulatory framework that shapes product design and market access for wire splicing kit manufacturers worldwide. Country-specific procurement patterns and certification requirements create distinct competitive environments across major demand centers.
United States
Federal EV charging infrastructure mandates and aging grid modernization drive kit deployment across underground and weather-resistant applications. NEC compliance variations by state fragment specification requirements and favor manufacturers with jurisdiction-specific code expertise. Texas and California electrical contractor networks concentrate procurement through bulk digital platforms that displace traditional distributor relationships.
Germany
Automotive harness manufacturers specify tool-plus-consumable bundles to reduce operator error rates in production environments. KBA-influenced vibration and thermal cycling standards elevate certification thresholds for vehicle wiring applications. Bavaria-based industrial buyers screen suppliers based on PFAS-free certifications and circular economy compliance scores under EU Green Deal requirements.
China
Utility-scale solar acceleration and rural grid expansion generate demand for IEC 61215-1 certified photovoltaic splicing hardware. GB standards and MIIT industrial policies shape domestic product specifications while dual carbon goals drive aluminum conductor adoption in renewable installations. Yangtze River Delta connector manufacturing clusters supply crimp barrel components to North American and European kit assemblers.
India
Rural electrification expansion and smart metering programs create untapped demand for weatherproof splicing hardware in tropical climate conditions. CEA grid interconnection standards and PLI scheme incentives for domestic manufacturing reshape procurement patterns. Maharashtra and Gujarat electrical infrastructure projects concentrate kit deployment for distribution network upgrades.
Japan
Automotive OEM harness builders integrate kit components into production line termination stations with METI-mandated quality traceability. JIS standards for industrial equipment maintenance drive demand for tool calibration programs among factory service personnel. Kansai and Chubu manufacturing corridors concentrate procurement authority for high-reliability connector systems.
Wire Splicing Kits Market Competitive Landscape
Diversified industrial conglomerates and specialized electrical component manufacturers split the market between integrated portfolio breadth and focused application expertise. The vendor base organizes into three strategic archetypes: adhesive and insulation heritage players leveraging material science capabilities, connector engineering specialists bundling hardware with sensor portfolios, and structured cabling incumbents extending data-center footprints into power applications. Dominant competitive moves include direct-to-contractor e-commerce platform development and certified installer network expansion to capture specification authority at the project level.
Within the diversified industrial tier, 3M Company and TE Connectivity occupy positions that exemplify divergent strategic paths—one anchored in adhesive and electrical tape heritage across North American channels, the other competing through deep connector integration with terminal and sensor portfolios. Panduit represents the structured cabling extension archetype, leveraging data-center infrastructure relationships into adjacent power splicing applications.
| Leading Market Players |
|---|
| 3M Company |
| Molex |
| Panduit |
| HellermannTyton |
| Ideal Industries |
| ABB |
| TE Connectivity |
| Phoenix Contact |
| Gardner Bender |
| Others |
Pricing and Supply Chain Analysis
Connector manufacturing clusters in China's Yangtze River Delta and Taiwan's precision metalworking corridors concentrate upstream supply, anchoring margin pools in gel-filled underground and heat-shrink environmental sealing configurations where metallurgical engineering commands specification authority.
Pricing Analysis
North American electrical contractors pay 15-25% premiums over European counterparts for UL 486D-certified underground kits due to jurisdiction-specific code documentation requirements. Three-tier pricing structure across premium, standard, and economy levels separates OEM service-bundled automatic systems from direct-to-contractor manual kits and commodity retail configurations. Price differentiation hinges on certification grade and after-sales service intensity, with specialty heavy-duty kits resisting compression while manual kit margins erode from bulk e-commerce procurement. Cost compression in residential-grade manual kits is intensifying because direct contractor portals displace distributor markups, though utility procurement departments show limited price sensitivity for aluminum-to-copper transition engineering.
Supply Chain Analysis
Export-control scrutiny on advanced crimping tool electronics and force-sensor components limits technology flows from Japan and Germany to Chinese kit assemblers, fragmenting equipment sourcing. Crimp barrel production concentrates in China, Taiwan, and South Korea, while oxygen-free copper drawing and EPDM compound formulation centers on U.S. Gulf Coast and German chemical corridors. Raw material dependencies rest on petroleum-derived insulation compounds, rare-earth magnet materials for battery-powered tools, and specialized aluminum-lithium alloys for transition splices. Single-source vulnerability runs through Yangtze River Delta connector clusters where regional disruptions cascade to North American and European kit assemblers. Distribution runs through electrical distributor networks unbundling technical support from hardware sales, with bulk procurement platforms capturing contractor spend previously flowing through counter sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wire splicing kit procurement consolidation across electrical contractor networks fragments specification authority, creating niches for specialized metallurgical engineering and certified installer training services that bypass traditional distribution layers.
For Market Incumbents: Harden specification authority in aluminum-to-copper transition engineering and submersible splice configurations where UL 486D and IEC 61215-1 certification barriers exclude commodity competitors. Deepen backward integration into gel-filled compound formulation and heat-shrink polymer production to defend margin pools against raw material volatility. Expand certified installer networks in Texas and California electrical contractor markets where jurisdiction-specific NEC compliance documentation determines procurement decisions. For New Entrants and Emerging Players: Establish a beachhead in India's rural electrification and smart metering programs where CEA grid interconnection standards create demand for tropical-grade weatherproof hardware with minimal incumbent saturation. Target photovoltaic DC splicing specialization for utility-scale solar deployments across multiple continents, leveraging IEC 61215-1 certification as a qualification wedge. Pursue direct contractor e-commerce platforms with mobile-optimized ordering systems that capture electrical contractor spend migrating from distributor counter relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across manual kit assembly as direct-to-contractor digital platforms displace working-capital-heavy distributor inventory positions, favoring asset-light specialist acquisitions. Long-term viability centers on specialty and heavy-duty kit manufacturers with captive metallurgical engineering capabilities and recurring OEM service contract revenue. Monitor PFAS-free certification adoption curves in Bavaria and France as signals for insulation compound reformulation investment requirements and supplier qualification timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Installer Network Expansion | Captures specification authority at project level where UL 486D and IEC qualifications determine procurement decisions. |
| Direct Contractor E-Commerce Platform | Displaces traditional distributor relationships in Texas and California electrical contractor markets. |
| PFAS-Free Compound Reformulation | Aligns with EU Green Deal digital product passport requirements and ANSM-tracked industrial safety protocols. |
| Aluminum-to-Copper Transition Engineering | Addresses renewable energy and utility grid modernization demand for corrosion-resistant metallurgy. |
| Photovoltaic DC Splicing Specialization | Targets IEC 61215-1 certified kits for utility-scale solar acceleration across multiple continents. |
Research Methodology
Cross-validation between primary interviews with electrical contractor procurement managers, utility specification engineers, and automotive harness manufacturing directors and secondary sources including UL certification databases, IEC standards documentation, and CEA grid interconnection filings anchors the qualitative findings. Bottom-up triangulation aggregates product-level shipment data across manual, automatic, specialty, and heavy-duty kit configurations, while top-down calibration incorporates macroeconomic indicators for copper and aluminum price trajectories. Trade flow analysis from customs records and distributor inventory disclosures validates regional demand concentration patterns.
Calibration against historical certification adoption curves and raw material cost pass-through elasticities shapes the analytical framework across the analysis window. Segmentation dimensions modeled include product type, application voltage environment, end-user procurement authority, and conductor material composition. CAGRs derive from regression analysis of installed base replacement cycles and new infrastructure deployment pipelines, with EV charging infrastructure mandates and renewable energy interconnection backlogs serving as primary demand-side forecast inputs.
Sensitivities concentrate around copper and aluminum price volatility, PFAS regulatory timeline acceleration, and East Asian supply chain disruption scenarios. Forecasts reflect assumptions on certification harmonization progress and contractor digital procurement adoption rates. Material shifts in RoHS substance restriction enforcement or REACH compound disclosure requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Asia-Pacific Electrical Bushing Market
Electrical Equipment
Electrical Fuses Market
Electrical Equipment
Earth Leakage Circuit Breakers Market
Electrical Equipment
Europe Circuit Breakers Market
Electrical Equipment
Contactors Market
Electrical Equipment
Circuit Breaker and Fuses Market
Electrical Equipment
Lighting Contactor Market
Electrical Equipment
India Electrical Enclosures Market
Electrical Equipment
High Voltage Circuit Breaker Market
Electrical Equipment
High Voltage Electric Insulators Market
Electrical Equipment
Transient Protection Device Market
Electrical Equipment
Rotary and RF Rotary Joints Market
Electrical Equipment
China DC Motor Market
Electrical Equipment
Axial Fans Market
Electrical Equipment
Global Electrical Steel Market
Electrical Equipment
Passover Humidifiers Market