
 Slip Ring Market | 2026-2036
Slip Ring Market Size, Share, and Industry Trends Forecast 2026-2036
Slip Ring Market Outlook
Renewable energy is rebalancing the end-use mix away from traditional industrial automation customers. Moog Inc. anchors aerospace and defense contracts with high-reliability capsule designs. Schleifring GmbH dominates European medical imaging installations through localized service networks. MERSEN competes in heavy-current industrial segments with carbon brush expertise.
A slip ring is an electromechanical device that transmits electrical power and signals between stationary and rotating structures using conductive rings and sliding contacts, typically rated for rotational speeds from zero to thousands of RPM and operating temperatures spanning -40°C to +80°C depending on material selection. Its primary purpose is to eliminate cable twisting in continuously rotating machinery across defense, energy, and factory automation systems. Fiber optic slip rings now lead in bandwidth-intensive defense and broadcast applications where electromagnetic immunity is non-negotiable. Hybrid electrical-optical configurations represent the fastest-growing architecture as wind turbine nacelles consolidate power, data, and Ethernet onto single rotating joints. Mercury-wetted variants retain niche positions in radar and satellite ground stations where contact resistance stability outweighs environmental handling constraints.
FDA electrical safety standards for rotating components in CT and MRI systems shape medical-grade product development cycles in the United States. REACH substance restrictions and RoHS compliance in Europe constrain mercury contact formulations and drive material substitution programs. China's GB standards and NMPA device regulations enforce localized testing protocols for imported slip rings in domestic medical equipment. Stakeholders must monitor how wireless power transfer standards from IEC working groups displace contact-based architectures in next-generation robotics and drone applications.
Market Dynamics
Hybrid electrical-optical slip ring architectures are compressing procurement cycles as wind turbine OEMs consolidate multiple rotating interfaces into single-joint assemblies, forcing legacy electrical-only suppliers to requalify designs under tighter bandwidth specifications.
Growth Catalysts
- Offshore wind installation hubs:China's coastal provinces and Germany's North Sea ports are scaling nacelle assembly lines requiring fiber-capable rotating joints rated for 20+ year service intervals.
- FDA 510(k) electrical safety pathways:Tightened rotating component standards for CT and MRI systems in the United States are filtering out uncertified suppliers and concentrating procurement among qualified vendors.
- Carbon brush substitution programs:REACH substance restrictions on mercury formulations are accelerating material transitions toward precious-metal and fiber optic contact systems in European industrial automation.
Market Restraints
- Precious metal input volatility:Gold and palladium price swings in commodity markets compress margin buffers for capsule slip ring manufacturers serving aerospace and defense contracts.
- Mercury-wetted supply concentration:Environmental handling constraints and limited qualified suppliers constrain availability for radar and satellite ground station applications requiring contact resistance stability.
- Wireless power transfer substitution:IEC working group standards for contactless rotating power transmission threaten to displace traditional contact-based architectures in next-generation robotics and drone joints.
Strategic Opportunities
- India's medical device PLI scheme:Domestic imaging equipment manufacturing incentives are creating localized demand for certified rotating interfaces previously served entirely by imports.
- 5G broadcast infrastructure:Fiber optic slip rings capable of handling 100Gbps+ throughput are penetrating live sports and news production rigs where electromagnetic immunity eliminates coaxial alternatives.
- Direct OEM channel consolidation:Wind turbine manufacturers are bypassing distributor networks to negotiate multi-year frame contracts with engineering support bundled into hardware pricing.
Industry Challenges
- Cross-disciplinary engineering talent scarcity:Hybrid optical-electrical designs require expertise spanning fiber splicing, precision machining, and RF shielding that concentrates in Germany's industrial corridor and China's eastern seaboard.
- NMPA and FDA dual certification timelines:Medical device manufacturers face 18-24 month approval cycles for rotating interfaces in imaging systems, locking working capital in inventory before revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Slip Ring Market |
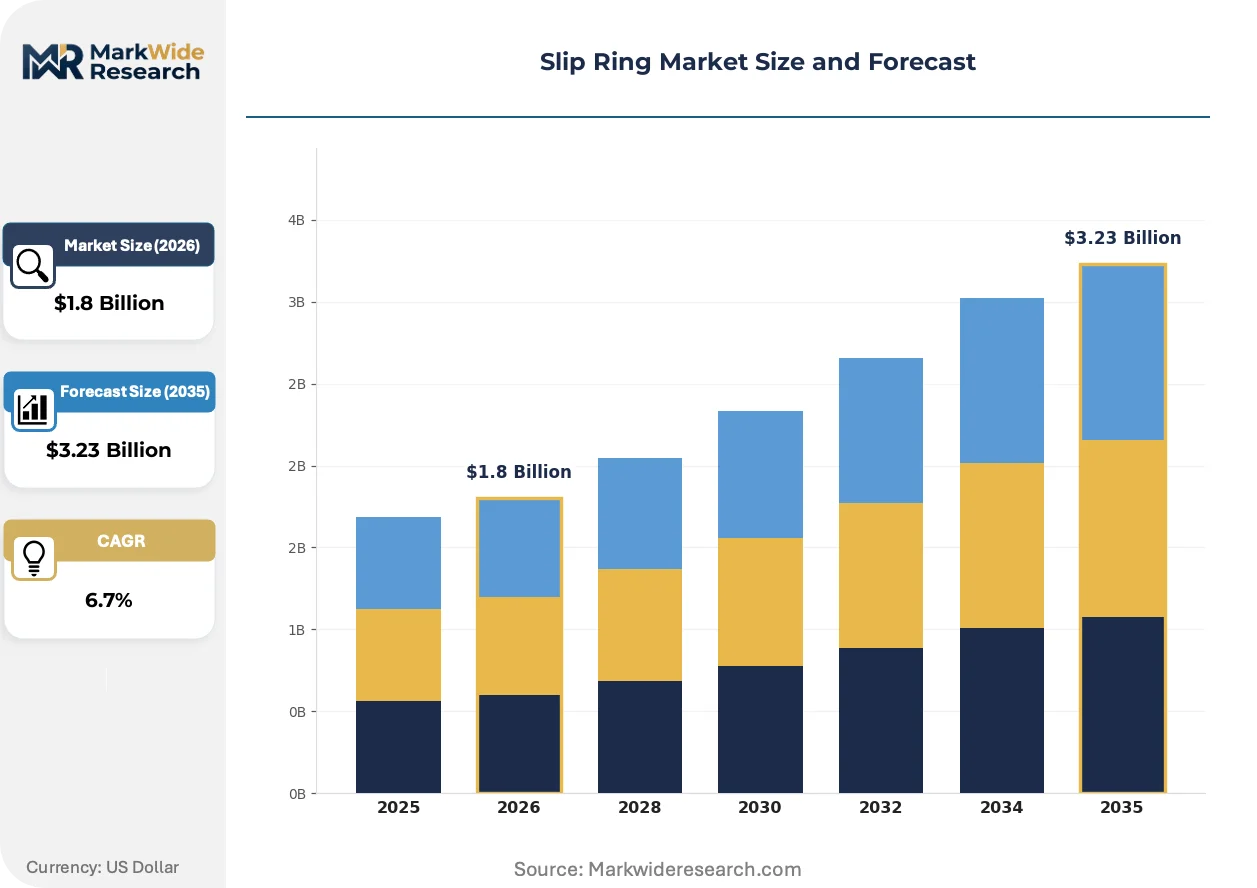
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mercury, Fiber Optic, Conductive, Capacitive End User: Aerospace, Industrial Automation, Renewable Energy, Marine Application: Robotics, Wind Turbines, Medical Equipment, CCTV Systems Technology: Electrical, Optical, Hybrid, Wireless |
| Companies Covered | Moog Inc., Schleifring GmbH, MERSEN, Conductix-Wampfler, Moflon Technology, Rotac Co., Ltd., Cobham Plc, STEMMANN-TECHNIK, Jinpat Electronics Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Slip Ring Market Strategic Shifts
Slip ring technology is bifurcating between commodity electrical designs facing margin compression and specialized hybrid-fiber configurations capturing premium positioning in bandwidth-intensive applications.
Fiber optic rotary joints are absorbing Ethernet and sensor data traffic previously carried through copper bundles in wind turbine nacelles. Vestas and Goldwind are specifying these variants for new offshore platforms where electromagnetic interference from power electronics degrades signal integrity. This absorption is collapsing the traditional separation between power transmission and data networking hardware procurement.
REACH substance restrictions and RoHS compliance frameworks in Europe are constraining mercury contact formulations and forcing material substitution programs across industrial automation. Manufacturers serving heavy-current segments must requalify carbon brush alternatives under accelerated wear testing protocols. German and French industrial OEMs are responding by consolidating supplier audits to verify full material disclosure documentation.
Buyer concentration among wind turbine OEMs is compressing distributor margins and shifting contract terms toward performance-based acceptance criteria. Tier-1 nacelle assemblers in Denmark and China now require 10-year minimum mean-time-between-failure guarantees with penalty clauses. This concentration is visible in procurement patterns where direct engineering engagement replaces catalog-based purchasing for installations above 5MW rated capacity.
Slip Ring Market Segmentation
Slip ring procurement decisions hinge on certification requirements that vary sharply across end-use environments. Medical imaging demands FDA 510(k) or NMPA clearance, while offshore wind specifications prioritize IEC corrosion ratings and 20-year service guarantees. These divergent approval pathways fragment supplier qualifications and create distinct competitive arenas.
Product Type:
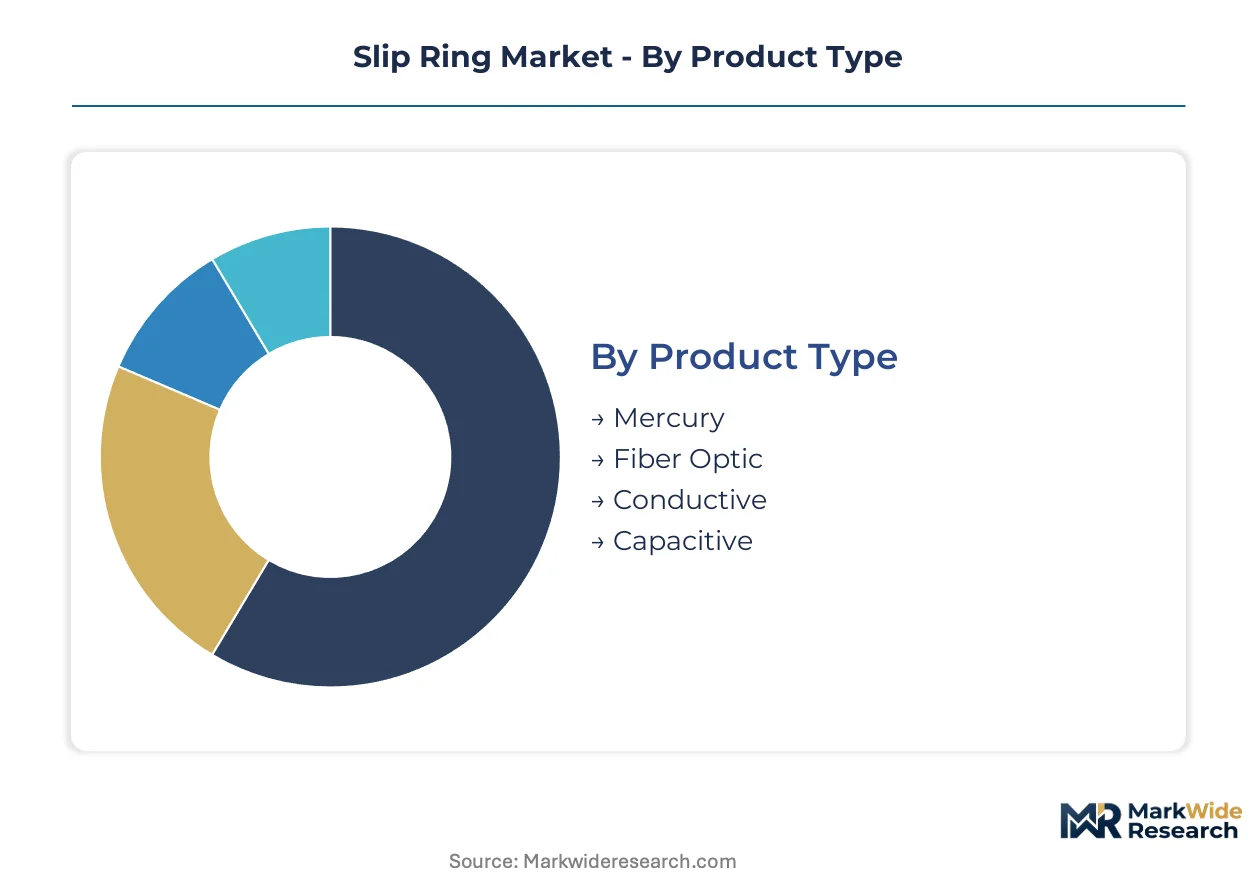
FDA electrical safety standards and REACH substance restrictions impose divergent material constraints across product categories, with mercury formulations facing phase-out pressure while fiber variants gain bandwidth-driven preference.
- Mercury:Liquid-metal contact interfaces deliver sub-milliohm resistance stability for radar pedestal and satellite ground station applications. Availability concentrates among qualified suppliers serving defense contractors in the United States and European ground tracking networks, constrained by environmental handling regulations under EPA and ECHA frameworks.
- Fiber Optic:Photonic rotary joints transmit 100Gbps+ data streams through silica waveguides immune to electromagnetic interference. Demand clusters in China's offshore wind nacelles and Germany's broadcast production rigs where power electronics generate severe EMI fields that degrade copper signal integrity.
- Conductive:Precious-metal brush-and-ring assemblies dominate industrial automation with proven cost-performance ratios across millions of rotation cycles.
- Capacitive:Contactless power transfer through rotating plate capacitors serves sealed medical equipment and food processing machinery where contamination exclusion is paramount.
Fiber Optic sits at the top of the volume ranking, with Hybrid configurations climbing the fastest as turbine OEMs consolidate electrical and optical channels.
End User:
Customer procurement scale varies from single-unit medical device qualification programs to thousand-unit wind farm frame contracts, reshaping supplier engagement models and engineering resource allocation.
- Aerospace:Capsule slip rings rated for -55°C to +125°C thermal excursions and 50,000-foot altitude pressure cycles anchor flight control and in-flight entertainment systems. Contracts bundle 25-year spares availability with MIL-STD-810G environmental qualification, concentrating procurement among vendors with AS9100D certification and FAA PMA approvals.
- Industrial Automation:Modular slip ring assemblies integrate into robotic arms, packaging lines, and rotary indexing tables across Germany's automotive manufacturing belt and China's eastern seaboard factory clusters. REACH compliance documentation and CE marking dominate supplier audit protocols in European installations.
- Renewable Energy:Nacelle-mounted rotating joints must survive salt spray, vibration, and temperature cycling across 20-year design lives. China's coastal provinces and Germany's North Sea ports drive specification development for 5MW+ turbine platforms.
- Marine:Submersible-rated slip rings with IP68 sealing serve winch systems, sonar turrets, and dynamic positioning equipment on offshore vessels.
Industrial Automation commands the largest installed base, with Renewable Energy expanding most quickly as offshore wind installation accelerates.
Application:
Performance specifications diverge between continuous rotation environments and intermittent indexing motions, with medical and broadcast applications imposing the tightest signal integrity requirements.
- Robotics:Compact slip rings with integrated Ethernet and power channels serve collaborative robot joints and automated guided vehicle steering assemblies. Multi-axis architectures in Japanese automotive plants and German logistics centers demand hybrid electrical-data configurations with 10 million-cycle minimum life ratings.
- Wind Turbines:Pitch control and yaw drive systems require high-current power transmission alongside blade sensor data and SCADA networking. Offshore platforms in China's Jiangsu and Guangdong provinces specify fiber-capable joints to isolate turbine control networks from generator harmonic interference.
- Medical Equipment:CT gantry and MRI patient table slip rings must satisfy FDA 510(k) electrical isolation requirements and NMPA device registration in China. Isolation ratings, leakage current limits, and biocompatibility documentation extend qualification timelines to 18-24 months.
- CCTV Systems:Pan-tilt-zoom camera installations in municipal surveillance and critical infrastructure deploy compact capsule designs with video, power, and control signal integration.
Wind Turbines leads absolute shipment volume, with Medical Equipment posting the steepest specification-driven pricing premiums.
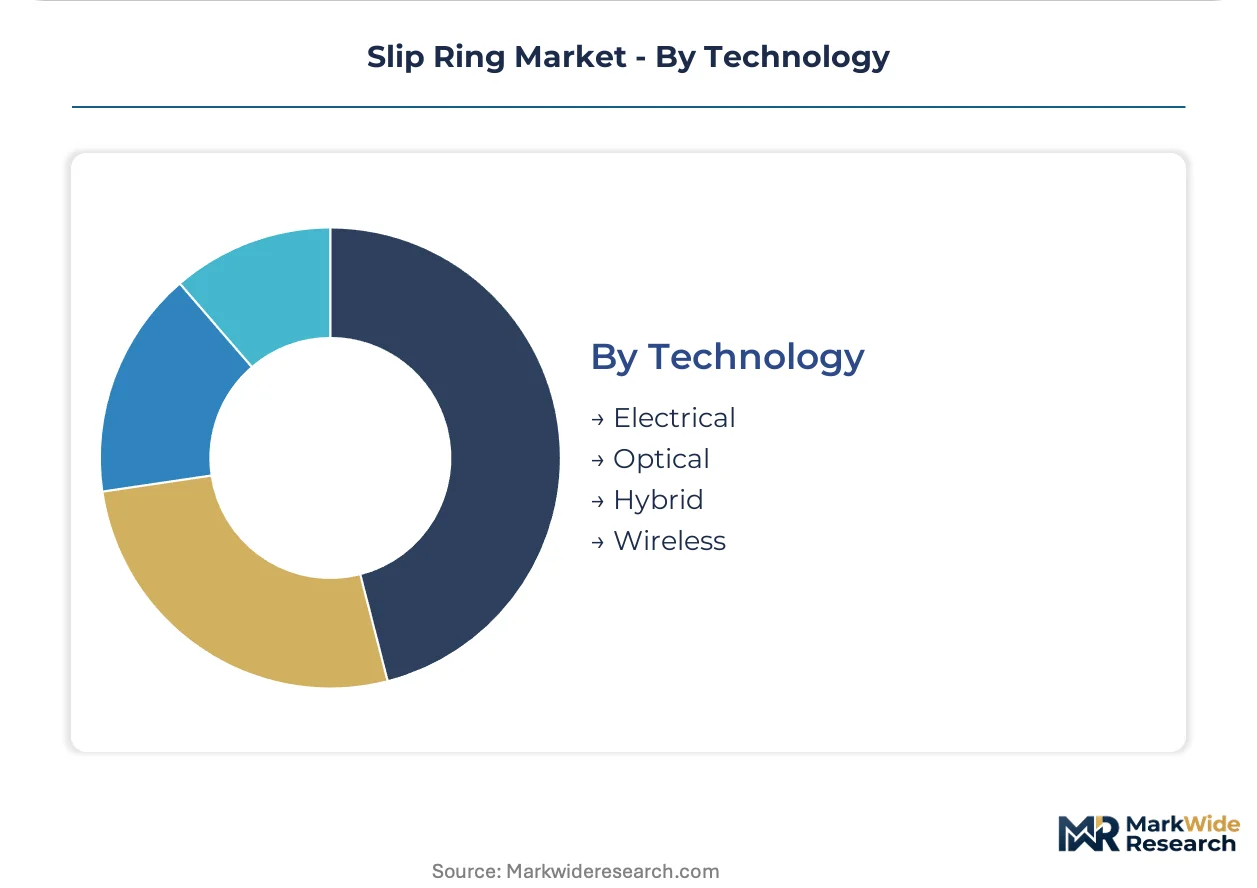
Technology:
Architecture selection determines whether procurement flows through electrical component distributors or specialized optical communications vendors, with hybrid designs forcing channel consolidation.
- Electrical:Traditional brush-and-ring architectures with copper-graphite or precious-metal contacts persist in cost-sensitive industrial applications. Margin pressure from commodity pricing and wireless substitution threats concentrate volume in high-volume, low-customization segments.
- Optical:Fiber rotary joints using expanded-beam or physical contact ferrule designs achieve insertion losses below 1dB across rotation. Broadcast sports production and defense satellite communications specify these variants where coaxial cable shielding proves inadequate.
- Hybrid:Integrated electrical power and optical data channels within single housing assemblies capture premium positioning in wind turbine nacelles. Vestas and Goldwind procurement specifications now mandate these configurations for offshore platforms above 5MW rated capacity.
- Wireless:Inductive power transfer and capacitive coupling architectures eliminate mechanical wear entirely. IEC working group standards development threatens displacement of contact-based designs in next-generation drone and collaborative robot joints.
Electrical technology retains the broadest installed base, with Hybrid architectures gaining share fastest as bandwidth and power consolidation reshape turbine procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting slip ring production toward jurisdictions with streamlined certification pathways for hybrid electrical-optical designs, compressing lead times for wind turbine and medical imaging OEMs.
China
Offshore wind installation in Jiangsu and Guangdong provinces drives fiber-capable rotating joint procurement for 5MW+ nacelles. NMPA medical device regulations enforce localized testing protocols for imported slip rings in domestic CT and MRI systems. Qingdao and Shanghai manufacturing clusters are scaling hybrid assembly lines to serve Goldwind and Vestas frame contracts.
Germany
Industrial automation demand concentrates in Baden-Württemberg and Bavaria, where automotive OEMs specify REACH-compliant precious-metal brush systems. ECHA substance restrictions on mercury formulations accelerate carbon brush substitution programs. Hamburg and Bremerhaven ports anchor North Sea wind turbine nacelle assembly requiring 20-year service interval guarantees.
United States
FDA 510(k) electrical safety pathways for rotating components in imaging systems filter procurement toward qualified vendors with established biocompatibility documentation. EPA environmental handling constraints constrain mercury-wetted supply for radar pedestal applications. Connecticut and California defense contractors anchor aerospace capsule slip ring demand with MIL-STD-810G qualification requirements.
India
CDSCO medical device regulations and the PLI scheme for domestic imaging equipment manufacturing create localized demand for certified rotating interfaces. Maharashtra and Karnataka industrial corridors are absorbing technology transfer partnerships for hybrid optical-electrical assembly. Mumbai and Bangalore clusters are emerging as qualification hubs for NMPA-FDA dual-certified component sourcing.
Japan
METI industrial standards and PMDA device regulations shape precision rotating joint specifications for robotic and medical applications. Kanto and Kansai manufacturing belts demand compact capsule designs with integrated Ethernet for multi-axis automation. Nagoya-area automotive plants are consolidating supplier audits for 10 million-cycle minimum life ratings.
Slip Ring Market Competitive Environment
Portfolio diversification dominates the current landscape as established electrical-only suppliers requalify designs under tighter bandwidth specifications to capture hybrid architecture contracts. The vendor base organizes around three archetypes: aerospace-defense specialists with AS9100D certification, industrial automation incumbents with localized service networks, and emerging optical-communications entrants. M&A activity and capacity expansion in fiber splicing capabilities represent the primary competitive vectors as turbine OEMs consolidate procurement channels.
Among Germany-based precision manufacturers, Schleifring GmbH exemplifies the medical-imaging service-network archetype, while Moog Inc. anchors the aerospace-defense capsule segment with FAA PMA positioning. MERSEN occupies a position within heavy-current industrial applications, reflecting carbon brush heritage. Chinese fabricators including Moflon Technology and Jinpat Electronics Co., Ltd. represent scale-driven hybrid assembly expansion, with Zhengzhou and Shenzhen production clusters capturing direct OEM frame contracts through bundled engineering support.
| Leading Market Players |
|---|
| Moog Inc. |
| Schleifring GmbH |
| MERSEN |
| Conductix-Wampfler |
| Moflon Technology |
| Rotac Co., Ltd. |
| Cobham Plc |
| STEMMANN-TECHNIK |
| Jinpat Electronics Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Captive fiber splicing capacity in Qingdao and Shenzhen anchors supplier pricing power for hybrid electrical-optical assemblies, compressing distributor margins while elevating direct-to-OEM contract premiums. This integration pattern concentrates cost control among turbine manufacturers consolidating multi-year frame agreements with bundled engineering support.
Pricing Analysis
Distributor margin compression now defines channel economics as Goldwind and Vestas negotiate direct procurement terms bypassing catalog-based purchasing. Three-tier pricing structure across premium hybrid configurations, standard conductive assemblies, and economy capsule designs differentiates by certification grade and volume scale. Cost compression in standard conductive tiers intensifies because REACH-compliant precious-metal substitution raises input costs. Industrial automation buyers in Germany's automotive belt exhibit highest price sensitivity, while aerospace contractors absorbing MIL-STD-810G qualification premiums show lowest.
Supply Chain Analysis
Precious-metal brush supply rests on South African platinum-group mining and Chinese rare-earth processing clusters for magnetic components in capsule designs. Fiber optic ferrule fabrication draws from Japanese precision ceramic manufacturers and German optical coating specialists. Single-source vulnerability concentrates in mercury-wetted contact formulations where EPA and ECHA restrictions constrain qualified suppliers to defense contractors in Connecticut and satellite ground stations in Bavaria. Distribution runs through direct OEM engineering engagement for installations above 5MW, with distributor networks serving replacement parts in industrial automation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory-arbitrage dynamics favor hybrid assembly expansion in India's PLI scheme corridors, where CDSCO medical device regulations and domestic imaging incentives compress qualification timelines versus NMPA-FDA dual certification burdens.
For Market Incumbents: Anchor aerospace capsule positions through AS9100D certification maintenance and FAA PMA pathway investment against wireless power transfer substitution threats from IEC working group standards. Deepen backward integration into fiber splicing capabilities in Zhengzhou production clusters to capture Goldwind direct frame contracts. Prioritize REACH-compliant material disclosure documentation to defend automotive automation supplier status in Baden-Württemberg. For New Entrants and Emerging Players: India's PLI scheme for domestic medical imaging equipment opens a window for CDSCO-certified rotating interface supply previously served entirely by imports. Target Maharashtra and Karnataka industrial corridors for technology transfer partnerships in hybrid optical-electrical assembly. Penetrate 5G broadcast infrastructure through fiber optic rotary joints handling 100Gbps+ throughput in live sports production rigs where electromagnetic immunity eliminates coaxial alternatives. For Investors and Strategic Acquirers: Consolidation pressure builds where cross-disciplinary engineering talent scarcity concentrates hybrid design expertise in Germany's industrial corridor and China's eastern seaboard. Long-term viability frames around captive fiber splicing capacity and dual-certification asset bases serving medical imaging OEMs. Watch NMPA-FDA approval timeline convergence as inflection indicator for working capital efficiency in rotating interface suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Architecture Qualification | Captures Vestas and Goldwind offshore platform procurement consolidating electrical and optical channels. |
| Dual Certification Investment | Unlocks NMPA-FDA parallel approval pathways for CT and MRI rotating interfaces in domestic Chinese manufacturing. |
| Fiber Splicing Capacity Expansion | Secures captive supply of expanded-beam ferrule assemblies for 100Gbps+ broadcast and defense applications. |
| Direct OEM Channel Development | Bypasses distributor margin compression through engineering-integrated frame contracts with 10-year MTBF guarantees. |
| REACH-Compliant Material Transition | Satisfies ECHA substance restrictions eliminating mercury formulations from European industrial automation supply. |
Study Parameters
Direct dialogue with wind turbine procurement directors, medical device regulatory affairs leads, fiber optic component engineers, and industrial automation maintenance directors grounded qualitative findings in operational realities. Secondary validation drew from FDA 510(k) filings, NMPA device registration databases, ECHA REACH compliance disclosures, and IEC working group standards documentation. Bottom-up unit shipment estimates triangulated against top-down OEM capex allocation patterns across the analysis window.
Segment-level outputs across product type, end user, application, and technology dimensions fed into analytical framework calculations over the projection horizon. CAGRs derived from fitted growth curves applied to base-year market sizing, with wind turbine installation forecasts and medical imaging equipment shipment projections serving as primary demand-side inputs.
Revisions become necessary when IEC wireless power transfer standards accelerate contactless architecture adoption, or when NMPA-FDA dual certification timelines diverge sharply. Forecasts reflect documented assumptions on precious-metal price stability and offshore wind installation pacing. A small set of named triggers—regulatory pathway convergence, fiber input cost volatility, and wireless substitution thresholds—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Copper and Aluminum Terminal Blocks Market
Electrical Equipment
Global Dehydrating Breather Market
Electrical Equipment
Soft Starter Market
Electrical Equipment
Global Circuit Breakers Market
Electrical Equipment
Electrical Resistor Market
Electrical Equipment
Medium Voltage Transformer Market
Electrical Equipment
High Voltage Circuit Breaker Market
Electrical Equipment
Motor Protection Devices Market
Electrical Equipment
Global Cooling Fan Market
Electrical Equipment
Europe High Voltage Switchgear Market
Electrical Equipment
Busbar Systems Market
Electrical Equipment
Global General Purpose Contactor Market
Electrical Equipment
Circuit Breaker and Fuses Market
Electrical Equipment
Central Vacuum Receivers Market
Electrical Equipment
High Voltage PTC Heater Market
Electrical Equipment
High Voltage Insulator Market