
 Terminal Block Market | 2026-2036
Terminal Block Market Size, Share, and Industry Trends Forecast 2026-2036
Terminal Block Market Outlook
Industrial distribution channels is reconfiguring as electrical component procurement migrates toward digital platforms and direct manufacturer engagement. WAGO Kontakttechnik GmbH & Co. KG leverages its spring-cage technology leadership to anchor premium positioning in DIN rail applications. TE Connectivity sustains broad portfolio breadth across automotive and industrial verticals, while Phoenix Contact dominates European project engineering channels through specification-grade product depth.
A terminal block is an insulated modular device with conductive metal strips and clamping mechanisms designed to join electrical wires securely, typically rated for voltages from 250V to 1000V and currents up to 125A depending on configuration. DIN rail terminal blocks lead volume demand due to universal mounting compatibility across control panels and switchgear assemblies. PCB mount variants represent the fastest-growing type as miniaturization pressures intensify in telecommunications and embedded controller designs. Plastic material formulations command the largest share by volume, though composite housings are gaining traction where halogen-free flame retardancy meets IEC 60695 glow-wire test requirements.
FCC electromagnetic compatibility rules shape signal integrity specifications for telecommunications terminal blocks sold into US infrastructure projects. EMA's alignment with IEC 60947-7-x standards governs European market access, while China's SAMR enforces GB 14048 compliance for imported electrical connection devices. Stakeholders must monitor evolving dual carbon goals in China and the EU Green Deal's embodied carbon tracking requirements, as these frameworks will increasingly filter supplier qualification criteria and material disclosure obligations without explicit mandate overlap.
Market Dynamics
Industrial automation OEMs are expanding terminal block procurement for smart factory retrofits, compressing specification cycles and forcing suppliers to align with IEC 60947-7-1 creepage and clearance requirements.
Growth Catalysts
- Smart factory retrofits:Industrial automation OEMs in Germany's Ruhr cluster are accelerating terminal block replacement programs to meet IEC 60947-7-1 safety standards for reduced creepage distances.
- GB 14048 compliance:China's SAMR enforcement for imported electrical connection devices is creating specification-grade demand for halogen-free terminal blocks in control panel assemblies.
- PCB miniaturization:Telecommunications equipment manufacturers are adopting compact terminal block variants as embedded controller designs shrink footprint requirements.
Market Restraints
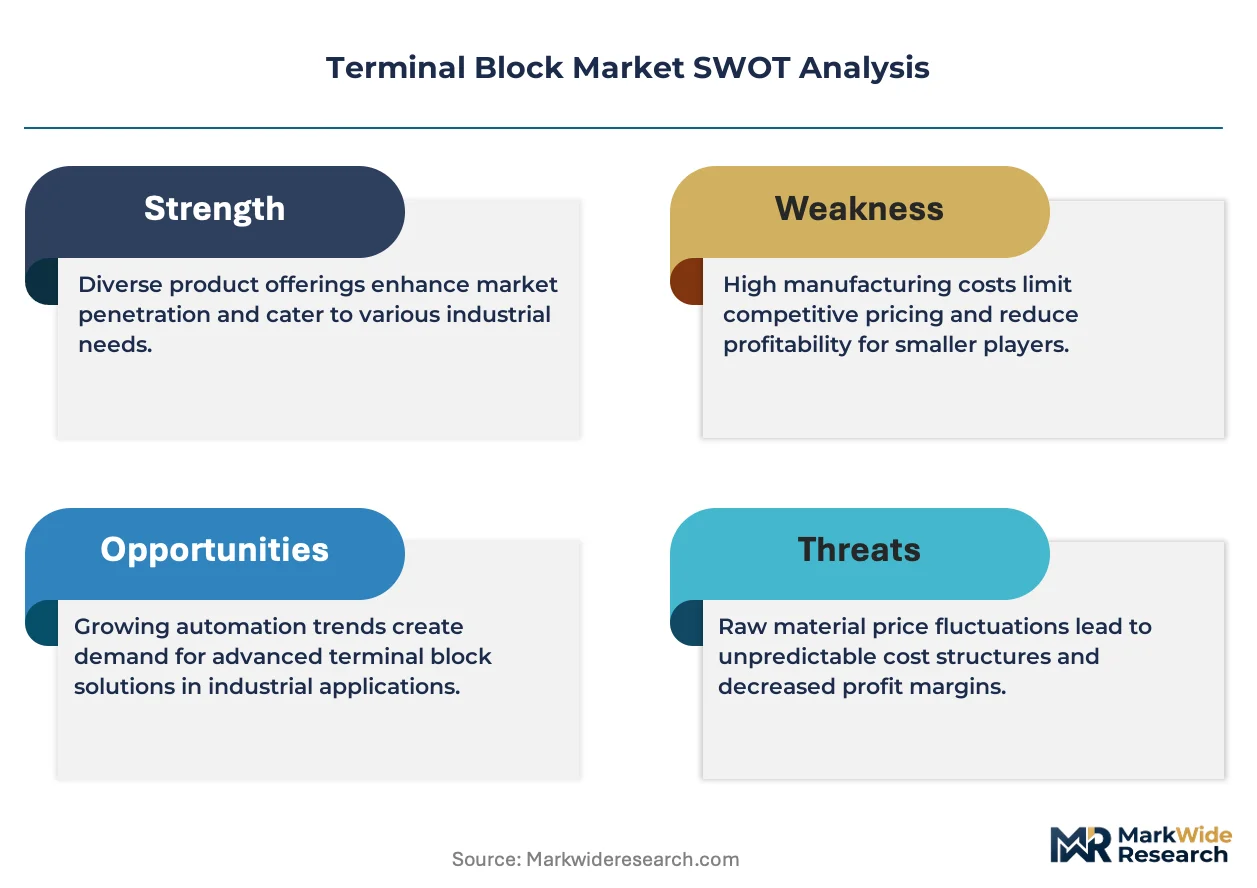
- Copper price volatility:Conductive metal strip costs fluctuate with LME copper futures, compressing margin visibility for DIN rail terminal block producers.
- Supply concentration:Premium spring-cage technology remains concentrated among German specialists, creating procurement bottlenecks for tier-two automation integrators.
- Technical limitation:Legacy screw-clamp designs face displacement pressure from push-in alternatives, stranding existing inventory and tooling investments.
Strategic Opportunities
- EU Green Deal alignment:Embodied carbon tracking requirements will filter supplier qualification criteria, rewarding early adopters of lifecycle disclosure protocols.
- India manufacturing expansion:PLI scheme incentives for industrial automation are creating specification entry points for terminal block vendors in Gujarat and Tamil Nadu industrial corridors.
- Channel disintermediation:Direct manufacturer engagement platforms are capturing procurement volume previously flowing through electrical distribution intermediaries.
Industry Challenges
- IEC 60695-2 glow-wire testing:Certification timelines extend 8-14 weeks for composite housing formulations, delaying product launches for halogen-free variants.
- Legacy system integration:Retrofit projects require backward-compatible terminal block geometries, constraining design freedom for next-generation spring-cage architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Terminal Block Market |
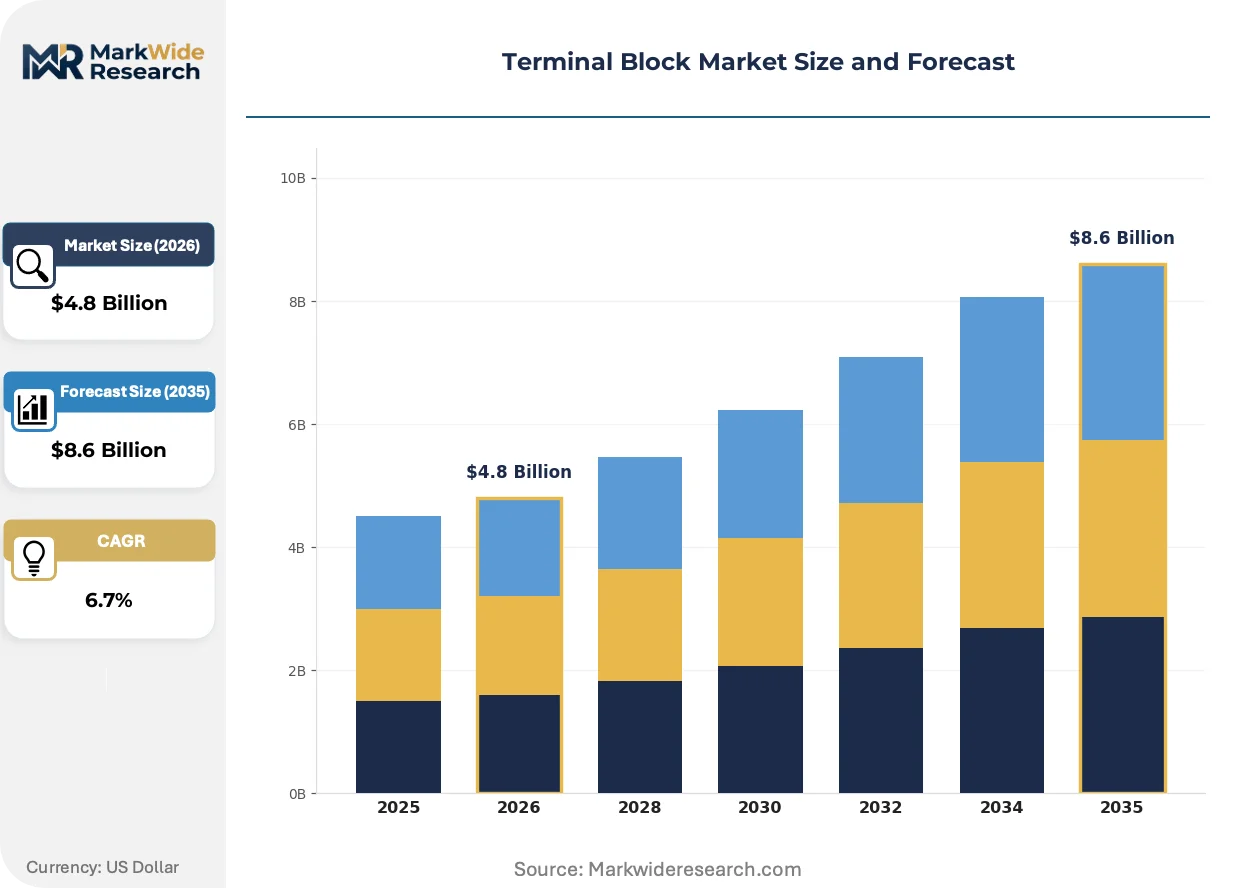
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Barrier, Plug-in, PCB Mount, Din Rail Material: Plastic, Metal, Composite, Silicone Application: Automotive, Industrial Automation, Renewable Energy, Telecommunications End User: Manufacturers, Distributors, Contractors, Service Providers |
| Companies Covered | WAGO Kontakttechnik GmbH & Co. KG, TE Connectivity, Weidmüller Interface GmbH & Co. KG, Phoenix Contact, Molex, Amphenol, Omron Corporation, Legrand Electric Ltd., Eaton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Terminal Block Market Strategic Shifts
Terminal block architecture is hybridizing across mounting technologies and material formulations as end-users demand unified solutions spanning DIN rail, PCB, and chassis-mount applications.
Spring-cage termination technology is hybridizing with traditional screw-clamp designs in modular housing formats. Railway signaling and renewable energy inverter manufacturers are specifying these hybrid configurations for vibration-resistant installations. The convergence is compressing pure-play screw-clamp market positions while elevating premium pricing for captive spring-force engineering.
REACH substance restrictions and RoHS recast directives are tightening phthalate and halogenated flame retardant limits for electrical connection devices sold into EU infrastructure. Manufacturers are reformulating PA66 and PBT housing compounds to satisfy ECHA SVHC screening thresholds. German control panel builders are now requiring full material disclosure documentation as a standard procurement qualifier.
Specification-grade buyers are consolidating vendor relationships around integrated connection technology portfolios rather than commodity terminal block transactions. Project engineering channels in European automation markets are favoring suppliers offering bundled terminal blocks, relays, and power supplies. This consolidation pressure is most visible in German automotive production line retrofits, where single-source qualification reduces compliance documentation burden.
Terminal Block Market Segmentation
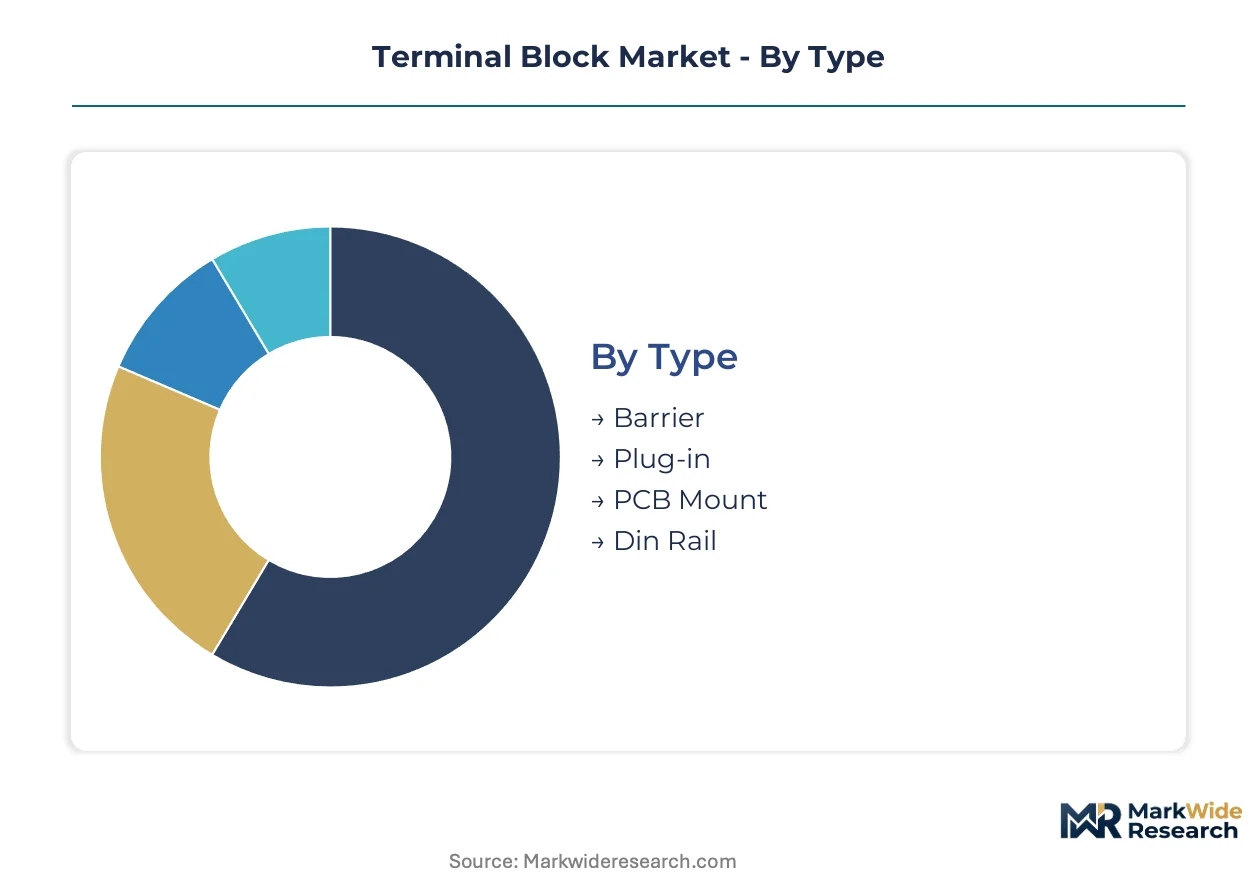
Terminal block procurement patterns diverge sharply across mounting technologies, material formulations, and end-use specifications. Understanding these segment boundaries clarifies where specification-grade premiums concentrate versus commodity price competition.
Type:
Mounting configuration dictates installation labor, panel density, and maintenance accessibility across control system architectures.
- DIN Rail:Universal 35mm top-hat mounting compatibility dominates industrial control panel assemblies. Germany's Ruhr cluster OEMs specify these for IEC 60947-7-1 compliant retrofits requiring tool-free wiring changes.
- PCB Mount:Surface-mount and through-hole variants shrink footprint for embedded controllers. Telecommunications equipment manufacturers in Shenzhen and Seoul drive demand as 5G base station designs compress interconnection density.
- Barrier:Elevated partition designs separate high-voltage circuits in power distribution units.
- Plug-in:Modular mating interfaces enable rapid field replacement without rewiring entire assemblies.
The dominant share belongs to DIN Rail, while PCB Mount is closing the gap fastest.
Material:
Flammability ratings and halogen content now filter supplier qualification before price negotiation begins.
- Plastic:PA66 and PBT formulations command volume leadership through cost efficiency and moldability. ECHA SVHC screening thresholds are forcing compound reformulations across EU-bound production.
- Composite:Glass-reinforced thermoplastics satisfy IEC 60695-2 glow-wire test requirements without halogenated additives. Certification timelines of 8-14 weeks constrain launch velocity for these variants.
- Metal:Aluminum and steel housings serve high-temperature industrial environments.
- Silicone:Flexible formulations seal connections in moisture-exposed outdoor installations.
Plastic retains the largest installed base, though composite formulations are expanding most quickly as REACH restrictions tighten.
Application:
Voltage ratings, vibration tolerance, and environmental sealing requirements fragment demand across vertical markets.
- Industrial Automation:Smart factory retrofits in Germany's automotive production lines specify spring-cage termination for vibration resistance. IEC 60947-7-1 creepage and clearance compliance is non-negotiable for these installations.
- Renewable Energy:Solar inverters and wind turbine power electronics demand wide-temperature-range operation. Railway signaling manufacturers specify hybrid spring-screw configurations for vibration-critical installations.
- Automotive:Electric vehicle battery management systems require compact high-current interconnection.
- Telecommunications:FCC electromagnetic compatibility rules shape signal integrity specifications for US infrastructure projects.
Industrial Automation captures the dominant procurement volume, while Renewable Energy is climbing the fastest as inverter installations multiply.
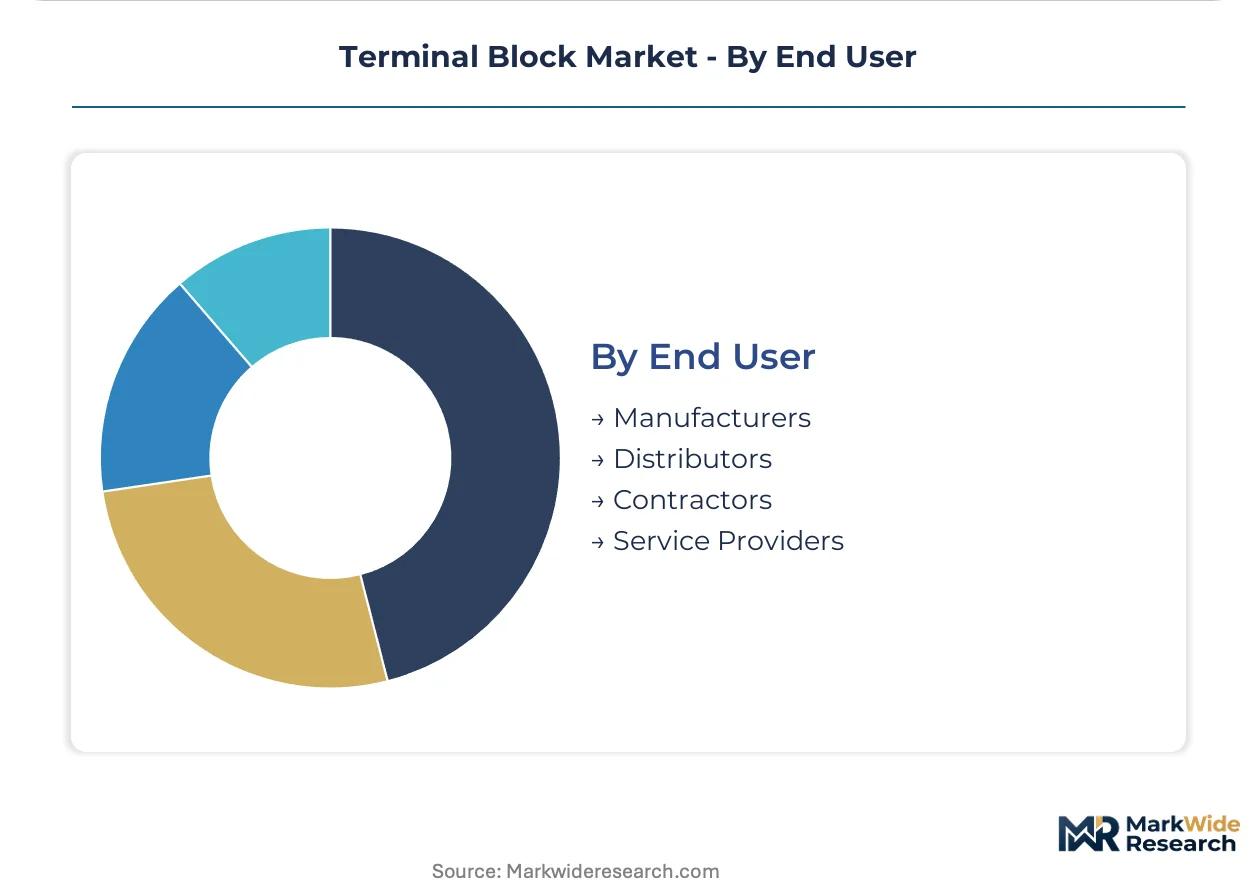
End User:
Procurement authority and technical specification involvement vary dramatically across the value chain.
- Manufacturers:OEMs and control panel builders exercise direct specification authority. German automotive line builders now consolidate vendor relationships around integrated connection portfolios rather than commodity transactions.
- Distributors:Electrical supply intermediaries face disintermediation pressure as direct manufacturer platforms capture volume. Channel reconfiguration is most visible in digital procurement migration.
- Contractors:Installation firms prioritize inventory availability and familiar termination tools.
- Service Providers:Maintenance organizations value backward-compatible geometries for retrofit accessibility.
Manufacturers hold specification control, though Distributors are losing share fastest to direct engagement platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Ruhr industrial cluster anchors European terminal block procurement through dense control panel fabrication and automotive production line retrofits. The Port of Rotterdam's electrical component transshipment volumes shape continental distribution patterns for DIN rail assemblies.
Germany
Smart factory retrofits in automotive production lines drive specification-grade demand for spring-cage termination technology. IEC 60947-7-1 creepage and clearance requirements filter supplier qualification across the Ruhr industrial cluster. WAGO Kontakttechnik and Phoenix Contact anchor premium positioning through project engineering channels in North Rhine-Westphalia.
China
5G base station deployments and embedded controller miniaturization accelerate PCB mount terminal block adoption in Shenzhen and Seoul supply chains. SAMR enforcement of GB 14048 compliance creates specification barriers for imported electrical connection devices. Yangtze River Delta control panel builders consolidate procurement around halogen-free composite housings.
United States
FCC electromagnetic compatibility rules shape signal integrity specifications for telecommunications infrastructure projects. Industrial automation OEMs in the Midwest manufacturing belt specify DIN rail assemblies for smart factory retrofits. Chicago and Detroit electrical distributors face disintermediation pressure from direct manufacturer engagement platforms.
India
PLI scheme incentives for industrial automation create specification entry points in Gujarat and Tamil Nadu industrial corridors. BIS certification requirements for electrical connection devices filter import qualification criteria. Mumbai and Chennai control panel builders expand procurement of spring-cage terminal blocks for vibration-resistant installations.
Japan
METI industrial efficiency standards accelerate terminal block replacement programs in precision manufacturing facilities. JIS-compliant creepage specifications govern procurement for railway signaling and renewable energy inverter applications. Osaka and Nagoya electrical component distributors consolidate vendor relationships around integrated connection portfolios.
Terminal Block Market Competitive Environment
On the supply side, the industry is consolidating around specification-grade portfolios rather than commodity transactions. German specialists dominate premium spring-cage technology through captive engineering capabilities. Three archetypes define competitive positioning: integrated connection technology portfolios, pure-play termination specialists, and scale-driven component fabricators. M&A activity targets complementary relay and power supply capabilities, while direct digital platforms disintermediate traditional electrical distribution channels.
Among German-based engineering specialists, WAGO Kontakttechnik GmbH & Co. KG and Phoenix Contact exemplify premium-tier positioning through specification-grade product depth and project engineering channel control. TE Connectivity occupies a position spanning automotive and industrial verticals through portfolio breadth. Weidmüller Interface GmbH & Co. KG represents the integrated archetype combining termination technology with power supply and relay offerings for consolidated procurement.
| Leading Market Players |
|---|
| WAGO Kontakttechnik GmbH & Co. KG |
| TE Connectivity |
| Weidmüller Interface GmbH & Co. KG |
| Phoenix Contact |
| Molex |
| Amphenol |
| Omron Corporation |
| Legrand Electric Ltd. |
| Eaton |
| Others |
Value Chain & Pricing Dynamics
German spring-cage technology specialists anchor upstream supply concentration, channeling margin pools toward specification-grade project engineering channels and away from commodity DIN rail transactions. Copper conductive strip costs and captive termination engineering capabilities dictate where pricing power accrues across the terminal block value chain.
Pricing Analysis
Volume-discount tiering separates specification-grade spring-cage architectures from standard screw-clamp and economy push-in alternatives. Price differentiation rests on IEC 60947-7-1 certification grade and spring-force engineering precision, with German automotive line builders paying premiums for material disclosure documentation. Cost compression in standard-tier DIN rail assemblies is intensifying because push-in termination technology displaces legacy screw-clamp inventory. Tier-two automation integrators exhibit highest price sensitivity, while railway signaling and renewable energy inverter manufacturers demonstrate lowest sensitivity for vibration-resistant hybrid configurations.
Supply Chain Analysis
Contract manufacturing capacity for precision spring-cage components concentrates with German EMS specialists and select Czech fabrication facilities serving the Ruhr industrial cluster. Geographic supply concentration centers on Germany, China, and India, with raw material dependencies spanning LME copper futures, PA66/PBT engineering plastics, and glass-reinforced thermoplastic compounds. Single-source vulnerability in premium spring-force engineering creates procurement bottlenecks for tier-two integrators. Distribution runs through direct manufacturer engagement platforms disintermediating traditional electrical supply intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Terminal block market fragmentation creates entry niches as specification-grade buyers consolidate around integrated connection portfolios rather than commodity transactions. Smart factory retrofit demand splinters procurement authority across OEMs, control panel builders, and direct digital platforms.
For Market Incumbents: Entrench specification-grade positioning by deepening captive spring-cage engineering capabilities and securing IEC 60695-2 glow-wire certification ahead of REACH substance restriction deadlines. Channel control through project engineering relationships in North Rhine-Westphalia defends against disintermediation from direct manufacturer platforms. For New Entrants and Emerging Players: Build out halogen-free composite housing capabilities targeting Yangtze River Delta control panel builders facing SAMR GB 14048 compliance requirements. India's Gujarat and Tamil Nadu industrial corridors offer the most penetrable geography given PLI scheme automation incentives. Lead with lifecycle carbon disclosure protocols to qualify for EU Green Deal supplier criteria. For Investors and Strategic Acquirers: Capital is best deployed toward integrated connection technology portfolios combining terminal blocks, relays, and power supplies rather than pure-play termination specialists. Long-term viability favors vendors with backward integration into precision metal stamping and captive polymer compounding. Watch for inflection when railway signaling and renewable energy inverter specifications mandate hybrid spring-screw configurations as default architecture.| Strategic Initiative | Industry Significance |
|---|---|
| Spring-Cage Technology Licensing | Transfers vibration-resistant termination IP to tier-two automation integrators in India's industrial corridors. |
| Halogen-Free Material Reformulation | Positions composite housing suppliers ahead of ECHA SVHC screening threshold tightening across EU infrastructure. |
| Direct Digital Platform Launch | Captures procurement volume migrating from Chicago and Detroit electrical distribution intermediaries. |
| GB 14048 Certification Investment | Unlocks specification entry points with Yangtze River Delta control panel builders under SAMR enforcement. |
| Integrated Portfolio Acquisition | Consolidates terminal block, relay, and power supply offerings for German automotive line builder single-source qualification. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs trade data, IEC certification registries, and SEC filings from electrical component manufacturers. Primary interviews engaged control panel builders, OEM procurement teams, railway signaling engineers, and aftermarket service heads across Germany, China, and the United States. Secondary validation drew from ECHA substance restriction databases, SAMR compliance bulletins, and EU Green Deal embodied carbon tracking protocols. Bottom-up terminal block shipment analysis triangulates against top-down industrial automation capex estimates.
Forecast inputs include mounting technology adoption curves, material formulation substitution rates, and end-use vertical expansion patterns across the projection horizon. Segmentation dimensions span DIN rail versus PCB mount configurations, plastic versus composite material grades, and industrial automation versus renewable energy application splits. CAGRs derive from installed base replacement cycles, smart factory retrofit program announcements, and 5G base station deployment trajectories. Copper price volatility assumptions and REACH regulatory timeline scenarios inform sensitivity bands.
Stress conditions across LME copper futures, IEC certification backlog durations, and PLI scheme incentive continuity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding spring-cage technology displacement rates and direct platform procurement migration velocity. Quarterly review of ECHA SVHC list updates, SAMR enforcement patterns, and EU Green Deal supplier qualification criteria is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Copper and Aluminum Terminal Blocks Market
Electrical Equipment
Saudi Arabia Industrial Electrical Components Market
Electrical Equipment
High-Speed Busbar Transfer Devices Market
Electrical Equipment
Electric Wall Heaters Market
Electrical Equipment
Europe Electric Drives Market
Electrical Equipment
Soft Starter Market
Electrical Equipment
Surface Mounting Distribution Panel Market
Electrical Equipment
High Voltage Electric Insulators Market
Electrical Equipment
Europe Electric Insulator Market
Electrical Equipment
Global Copper Clad Steel (CCS) Wire Market
Electrical Equipment
United States Busbar Market
Electrical Equipment
Capacitor Bank Market
Electrical Equipment
Global Medium Voltage Surge Arresters Market
Electrical Equipment
Asia-Pacific Electrical Bushing Market
Electrical Equipment
Central Vacuum Receivers Market
Electrical Equipment
Alligator Clips Market