
 High Voltage Porcelain Bushing Market | 2026-2036
High Voltage Porcelain Bushing Market Size, Share, and Industry Trends Forecast 2026-2036
High Voltage Porcelain Bushing Market Insights
Aftermarket service revenue for field-aged porcelain bushings is rewriting profit pools across the high-voltage supply chain. Siemens Energy leverages its transformer service footprint to capture refurbishment cycles in European grids. ABB anchors large-contract utility relationships through integrated bushing-switchgear packages. Hitachi Energy differentiates via R&D intensity in seismic-resistant porcelain formulations for earthquake-prone installations.
High voltage porcelain bushings are cylindrical ceramic insulators, typically alumina-based with silica and feldspar additives, fired above 1,200°C to achieve dielectric strength exceeding 20 kV/mm and mechanical load ratings above 50 kN; they conduct high-potential conductors through grounded enclosures while preventing flashover in outdoor substations. The transformer application segment commands the largest revenue share due to replacement cycles in aging OECD grid infrastructure, while the renewable installations application category posts the fastest growth trajectory as offshore wind farms demand salt-fog-resistant bushing designs. Isostatic pressing technology leads on dimensional precision for ultra-high-voltage ratings above 550 kV, whereas dry pressing dominates volume production for standard distribution-class units where cost efficiency outweighs performance premiums.
The US Department of Energy and FERC shape demand through grid reliability mandates and interconnection queue reforms that accelerate transformer procurement timelines. China's GB standards and MIIT industrial policy enforce localization ratios that redirect supply chains toward domestic porcelain manufacturers. India's CEA technical standards and BIS certification requirements for seismic and pollution performance tiers filter market access and elevate product qualification barriers. Stakeholders must monitor how divergent national testing protocols fragment procurement specifications and force parallel product line investments.
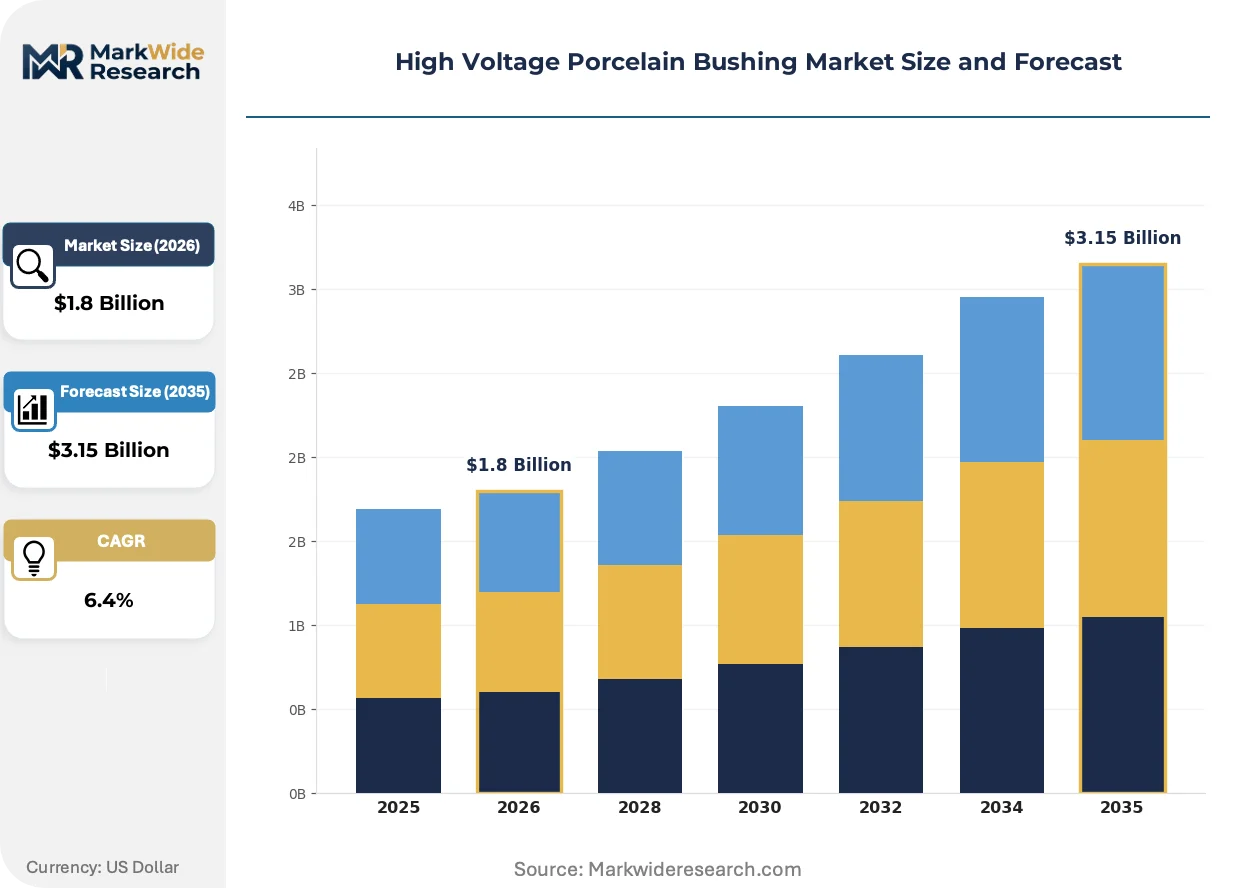
Market Dynamics
Utility-scale transformer replacement cycles across aging OECD grids are compressing procurement timelines and forcing bushing manufacturers to pre-qualify products against divergent national testing protocols before contract award.
Growth Catalysts
- China's dual carbon goals:Provincial grid buildouts under MIIT industrial policy mandate localized porcelain content, redirecting supply chains toward domestic ceramic insulator production above 72.5 kV ratings.
- India's transmission strengthening programs:CEA technical standards and BIS certification requirements for seismic performance tiers are elevating product qualification barriers and filtering import competition.
- Isostatic pressing technology:Dimensional precision gains for ultra-high-voltage bushings above 550 kV enable manufacturers to capture premium contracts in offshore wind interconnection projects.
Market Restraints
- Alumina price volatility:Raw material cost swings in high-purity ceramic feedstocks compress margin structures for dry-pressed distribution-class units where cost efficiency dominates purchasing criteria.
- Supply concentration in Shandong province:China's porcelain manufacturing clusters face disruption risks from environmental compliance inspections and energy rationing under MEE enforcement protocols.
- Composite insulator substitution:Polymer-housing alternatives with lighter weight profiles are displacing porcelain in 72.5-145 kV distribution applications where seismic load requirements remain moderate.
Strategic Opportunities
- Aftermarket refurbishment services:Field-aged bushing replacement cycles in European grids create recurring revenue streams for service-integrated transformer OEMs with established utility relationships.
- Salt-fog-resistant formulations:Offshore wind farm interconnections in the North Sea and Baltic markets demand specialized glaze chemistries that resist marine pollution accumulation.
- India's PLI scheme for power equipment:Production-linked incentives for domestic manufacturing are accelerating ceramic insulator localization and creating captive supply partnerships with state transmission utilities.
Industry Challenges
- Seismic qualification testing:Japan's METI standards and California's CPUC requirements demand divergent shake-table protocols, forcing parallel product line investments and extended certification timelines.
- High-voltage test bay capacity:Capex intensity for 800 kV+ impulse testing infrastructure limits mid-tier manufacturers from entering ultra-high-voltage contract competitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Voltage Porcelain Bushing Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transformers, Switchgear, Circuit Breakers, Capacitors, Surge Arresters Technology: Centrifugal Casting, Dry Pressing, Isostatic Pressing, Slip Casting Application: Power Transmission, Grid Infrastructure, Renewable Installations, Rail Electrification, Substation Equipment End User: Electric Utilities, Equipment Manufacturers, Industrial Plants, Telecom Providers, Rail Operators |
| Companies Covered | ABB, Siemens Energy, Hitachi Energy, GE Vernova, Trench Group, PFISTERER Holding SE, Hubbell, Toshiba, CG Power and Industrial Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Voltage Porcelain Bushing Market Trends and Innovations
Digital twin technology is virtualizing condition monitoring of porcelain bushings, enabling predictive maintenance models that compress replacement cycle uncertainty and reshape aftermarket service economics.
Isostatic pressing is virtualizing quality control for ultra-high-voltage bushings by enabling real-time density mapping during green-body formation. European grid operators specify these units for 550 kV+ transformer interconnections where dimensional tolerances below 0.1% prevent partial discharge initiation. The technology is compressing rejection rates and shortening qualification timelines for seismic-resistant formulations.
China's GB standards enforcement through MIIT certification audits is fragmenting procurement specifications across provincial grid companies. Domestic manufacturers must maintain parallel testing documentation for State Grid and Southern Power Grid technical requirements. The policy is elevating compliance costs for import-dependent suppliers and reinforcing localization ratios in 220 kV and above ratings.
Buyer consolidation among national transmission utilities is compressing supplier bases and unbundling after-sales service contracts from hardware procurement. European TSOs now tender bushing replacement as standalone maintenance agreements rather than bundled transformer purchases. The shift is visible in German and French grid modernization programs where service capability weights technical scoring above unit price.
High Voltage Porcelain Bushing Market Segmentation
Porcelain bushing procurement specifications fragment sharply across voltage classes and installation environments. Manufacturers must maintain parallel product lines to serve transformer OEMs, grid operators, and industrial end-users with divergent qualification protocols.
Product Type:
Application voltage and mechanical load requirements determine which product category commands procurement priority in utility tenders.
- Transformers:Cylindrical alumina-silica insulators rated above 72.5 kV conduct high-potential windings through grounded transformer tanks. Aging OECD grid infrastructure compresses replacement cycles in Germany, Japan, and the United States.
- Switchgear:Compact bushing designs integrate with gas-insulated switchgear enclosures where space constraints demand reduced external creep distances. Chinese provincial grid buildouts under MIIT localization mandates concentrate procurement volume.
- Circuit Breakers:High mechanical load ratings above 50 kN withstand switching impulse forces in live-tank configurations.
- Capacitors:Specialized glaze chemistries prevent surface tracking in high-humidity environments.
- Surge Arresters:Coordinated insulation levels protect against lightning impulse overvoltages in exposed substation layouts.
Transformers hold installed capacity. Switchgear is rotating up the share rankings.
Technology:
Dimensional precision requirements scale with voltage rating, separating premium manufacturing methods from volume production.
- Isostatic Pressing:Uniform hydrostatic pressure during green-body formation achieves density tolerances below 0.1% for ultra-high-voltage ratings above 550 kV. Offshore wind interconnection projects in the North Sea specify these units for salt-fog-resistant installations.
- Dry Pressing:Automated die compaction dominates distribution-class production where cost efficiency outweighs performance premiums. India's PLI scheme for power equipment accelerates localization of dry-pressed capacity for 72.5-145 kV ratings.
- Centrifugal Casting:Rotational molding produces hollow cylindrical bodies with consistent wall thickness.
- Slip Casting:Liquid clay deposition suits complex external profiles with deep ribs or sheds.
Isostatic pressing captures premium contract value. Dry pressing is expanding most quickly in emerging market manufacturing.
Application:
Environmental exposure severity and pollution classification dictate material formulation and glaze specification.
- Power Transmission:Ultra-high-voltage bushings above 550 kV interconnect national grid backbones with dielectric strength exceeding 20 kV/mm. China's State Grid and Southern Power Grid procurement specifications enforce GB standards compliance.
- Renewable Installations:Offshore wind farms demand marine-grade glaze chemistries resisting salt-fog accumulation in Baltic and North Sea conditions. This segment is gaining share fastest as interconnection queues accelerate.
- Grid Infrastructure:Utility-scale replacement programs in the United States follow FERC reliability mandates.
- Rail Electrification:Vibration-resistant mountings withstand dynamic loads in 25 kV AC overhead systems.
- Substation Equipment:Compact substation designs integrate multi-function bushing assemblies.
Power Transmission anchors utility procurement volumes. Renewable Installations is climbing the fastest in new order intake.
End User:
Procurement authority and technical specification control vary sharply across customer categories.
- Electric Utilities:National transmission utilities consolidate supplier bases through framework agreements covering 220 kV and above ratings. India's CEA technical standards and BIS certification requirements filter qualified vendors for state transmission company tenders.
- Equipment Manufacturers:Transformer OEMs pre-qualify bushing suppliers against customer-specific test protocols before contract award. Siemens Energy and ABB integrate bushing procurement into transformer platform standardization.
- Industrial Plants:Captive power facilities specify medium-voltage bushings for in-house substations.
- Telecom Providers:Power supply bushings support rectifier stations in remote tower installations.
- Rail Operators:National railway electrification agencies procure through infrastructure concession frameworks.
Electric Utilities control specification authority. Equipment Manufacturers is tightening vertical coordination with certified suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility buyers in India and China prioritize cost efficiency in distribution-class procurement, while European transmission system operators absorb premium pricing for seismic-qualified ultra-high-voltage units above 550 kV.
China
Provincial grid buildouts under State Grid and Southern Power Grid drive procurement of porcelain bushings rated above 220 kV. MIIT industrial policy enforces localization ratios that redirect supply chains toward domestic ceramic insulator manufacturers. Shandong province manufacturing clusters face environmental compliance inspections under MEE enforcement protocols that periodically constrain production capacity.
India
CEA-mandated transmission strengthening programs accelerate replacement of aging transformer bushings across state transmission utilities. The PLI scheme for power equipment production-linked incentives tightens local content rules for equipment above 72.5 kV. Gujarat and Maharashtra industrial corridors host emerging ceramic insulator fabrication capacity serving domestic procurement.
Germany
Offshore wind interconnection projects in the North Sea demand salt-fog-resistant glaze chemistries for 550 kV+ transformer installations. EU Green Deal grid modernization funding compresses procurement timelines for utility-scale transformer replacements. Bavaria-based transformer OEMs pre-qualify bushing suppliers against customer-specific seismic test protocols before contract award.
United States
FERC interconnection queue reforms accelerate transformer procurement timelines across independent system operators. Grid reliability mandates from the Department of Energy elevate technical qualification barriers for ultra-high-voltage ratings above 345 kV. Texas and California transmission development corridors concentrate demand for pollution-resistant bushing designs in coastal and desert installations.
Japan
METI seismic qualification standards demand shake-table testing protocols that extend certification timelines for porcelain formulations. Utility transformer replacement cycles in the Tokyo and Osaka metropolitan areas drive aftermarket refurbishment demand. Chubu and Kansai industrial regions maintain specialized testing infrastructure for earthquake-resistant ultra-high-voltage bushings.
High Voltage Porcelain Bushing Market Competitive Landscape
Capability concentration sits with transformer-integrated OEMs possessing captive testing infrastructure; scale advantage sits with specialized ceramic insulator houses serving multiple equipment categories. The market structure organizes into three tiers: integrated energy technology conglomerates with full transformer platforms, dedicated bushing specialists with qualification depth in narrow voltage bands, and regional ceramic fabricators competing on dry-pressed distribution-class volume. Dominant competitive moves include backward integration into alumina feedstock processing and strategic partnerships with national transmission utilities for framework supply agreements.
Among Switzerland-based and Germany-based energy technology groups, ABB and Siemens Energy exemplify the integrated OEM archetype, anchoring large-contract utility relationships through combined hardware and service offerings. Hitachi Energy occupies a position representing the seismic-specialization vector, with R&D intensity in porcelain formulations for earthquake-prone installations. These three entities illustrate how qualification depth in divergent national testing protocols shapes competitive positioning across regional procurement markets.
| Leading Market Players |
|---|
| ABB |
| Siemens Energy |
| Hitachi Energy |
| GE Vernova |
| Trench Group |
| PFISTERER Holding SE |
| Hubbell |
| Toshiba |
| CG Power and Industrial Solutions |
| Others |
Pricing and Supply Chain Analysis
Shandong province's alumina processing clusters anchor cost structures for high-purity ceramic feedstocks, concentrating margin capture with integrated manufacturers possessing captive refining capacity while compressing spreads for import-dependent dry-pressed distribution-class producers.
Pricing Analysis
Aftermarket refurbishment services drive lifetime value capture for transformer-integrated OEMs with established utility relationships. Three-tier pricing structure across premium seismic-qualified, standard grid-compliant, and economy distribution-class levels separates contracts by certification intensity and testing protocol burden. Cost compression in dry-pressed 72.5-145 kV ratings intensifies as polymer composite alternatives displace porcelain in weight-sensitive installations. State transmission utilities in India and China exhibit highest price sensitivity, while European TSOs absorb premiums for offshore wind interconnection specifications.
Supply Chain Analysis
High-purity alumina feedstock draws from Australian bauxite refining, Chinese domestic calcination capacity, and Indian emerging ceramic processing corridors. Critical dependencies include feldspar from Turkish deposits, silica sand from domestic Chinese sources, and specialized glaze chemistries from German and Japanese formulation houses. Single-source vulnerability concentrates in Shandong province environmental compliance inspections under MEE enforcement protocols. Distribution runs through transformer OEM platform standardization and direct framework agreements with national transmission utilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Composite insulator substitution threatens porcelain bushing incumbents across 72.5-145 kV distribution applications, forcing defensive repositioning around qualification depth and service integration.
For Market Incumbents: Insulate core utility relationships through backward integration into alumina feedstock processing and captive seismic testing infrastructure. Deepen certification holdings against divergent national protocols—Japan's METI shake-table standards and California's CPUC requirements—to raise rival qualification barriers. Anchor large-contract positions via bundled hardware-service offerings that composite alternatives cannot replicate.
For New Entrants and Emerging Players: Build out dry-pressed capacity serving India's PLI scheme production-linked incentives for 72.5-220 kV ratings, where local content rules filter import competition. Target state transmission utility framework agreements in Gujarat and Maharashtra industrial corridors with certified BIS seismic performance tiers. Enter through aftermarket refurbishment partnerships with European transformer service networks lacking captive bushing supply.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed ceramic insulator specialists possessing narrow voltage-band qualification depth but lacking transformer platform integration. Five-to-ten year viability hinges on offshore wind interconnection buildouts and grid reliability mandate enforcement. Watch FERC interconnection queue processing speeds as inflection indicator for North American procurement velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alumina Feedstock | Captive refining capacity insulates margin structures against Shandong province supply disruptions. |
| Seismic Qualification Infrastructure Investment | Shake-table testing bays at 800 kV+ ratings unlock Japanese METI and California CPUC contract access. |
| Aftermarket Service Network Expansion | Field-aged bushing replacement cycles in European grids generate recurring revenue streams. |
| Salt-Fog-Resistant Formulation Development | Marine-grade glaze chemistries capture North Sea and Baltic offshore wind interconnection premiums. |
| PLI Scheme Localization Partnerships | Domestic manufacturing accreditation under India's CEA standards filters import competition. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC 10-K filings, and State Grid procurement disclosures. Primary interviews engaged transformer OEM procurement directors, utility planning officers at national transmission companies, ceramic insulator plant managers, and aftermarket service heads. Secondary validation drew from CEA technical standards documentation, MIIT industrial policy circulars, and FERC interconnection queue reports. Bottom-up unit economics triangulate against top-down grid investment forecasts.
Forecast inputs span voltage class segmentation, technology method adoption curves, application exposure severity, and end-user procurement authority concentration across the projection horizon. Modeled dimensions include product type, manufacturing technology, installation environment, and customer category. CAGRs derive from utility-scale transformer replacement cycle timing, renewable interconnection queue velocities, and localization policy enforcement intensity. Alumina price volatility bands and environmental compliance inspection frequency stress-test baseline assumptions.
Stress conditions across raw material cost swings, MEE enforcement stringency, and composite substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about grid modernization funding continuity and national testing protocol harmonization. Cross-checking against IEA grid investment benchmarks and IEC standard revision timelines is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Electrical Bushings Market
Electrical Equipment
Electrical Sub Panels Market
Electrical Equipment
Terminal Block Market
Electrical Equipment
High Efficiency Low Voltage Aluminum Motors Market
Electrical Equipment
Surface Mounting Distribution Panel Market
Electrical Equipment
Ultra High Voltage (UHV) Appliances Market
Electrical Equipment
India Electrical Enclosures Market
Electrical Equipment
Rotary and RF Rotary Joints Market
Electrical Equipment
Insulator Market
Electrical Equipment
Slip Ring Market
Electrical Equipment
North America Electrical Bushing Market
Electrical Equipment
Electric Control Panel Market
Electrical Equipment
High-Speed Busbar Transfer Devices Market
Electrical Equipment
Global Medium Voltage Electric Drives Market
Electrical Equipment
Voltage Transformer Market
Electrical Equipment
Cable Distribution Cabinets Market