
 Camera Technology Market | 2026-2036
Camera Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Camera Technology Market Outlook
Sensor engineering talent is collapsing across Japanese and European optics hubs, forcing incumbents to restructure hiring pipelines. Sony Corporation leverages captive CMOS foundry capacity to dominate image sensor supply for smartphone OEMs. Canon Inc. sustains professional DSLR and mirrorless R&D through vertical control over lens mount ecosystems. STMicroelectronics N.V. competes in automotive-grade time-of-flight modules for cabin monitoring and exterior ADAS arrays.
Camera technology encompasses optoelectronic systems that capture electromagnetic radiation—primarily visible light—through lens assemblies focused onto photosensitive arrays measured in megapixels and dynamic range in stops. These systems convert optical signals into digital data for storage, transmission, or real-time processing across consumer, industrial, and security applications. Mirrorless systems now lead professional photography due to compact flange distances enabling faster autofocus pipelines. Smartphone integration anchors volume demand as CMOS wafer output shifts toward sub-micron pixel architectures. Surveillance applications concentrate margin pools in edge-AI cameras with on-device analytics, reducing cloud dependency for facial recognition and anomaly detection.
FDA oversees medical imaging camera standards for endoscopic and diagnostic equipment sold into US healthcare networks. EMA and MDR govern clinical-grade camera systems deployed in EU surgical suites, demanding biocompatibility and sterilization resilience. FCC certification rules constrain wireless-enabled camera modules for IoT and drone platforms operating in unlicensed spectrum bands. Stakeholders must weigh regulatory fragmentation against the cost of maintaining parallel compliance tracks for consumer, automotive, and medical certification tiers.
Market Dynamics
The Camera Technology Market is being fundamentally restructured by the migration of computational imaging pipelines from cloud infrastructure to edge-AI silicon, compressing latency requirements and rewiring supplier relationships across automotive, medical, and security verticals.
Growth Catalysts
- EU AI Act compliance mandates:Surveillance system operators across Germany, France, and Italy must deploy on-device facial recognition, accelerating demand for cameras with embedded neural processing units.
- Automotive ADAS camera integration:Tier-1 suppliers in China are scaling time-of-flight and thermal modules for Level 2+ autonomous driving programs.
- Sub-micron pixel architectures:Smartphone OEMs in Shenzhen and Seoul are driving 0.56-micron pixel mass production, forcing foundry capacity reallocation toward mobile CMOS wafers.
Market Restraints
- Specialized sensor engineering talent scarcity:Optics hubs in Japan and Germany face collapsing graduate pipeline output, extending R&D timelines for next-generation stacked CMOS designs.
- Concentrated foundry capacity:Taiwan-based advanced node fabrication for image sensors creates single-source vulnerability for automotive-grade time-of-flight modules.
- Gallium arsenide substrate cost volatility:Infrared sensor manufacturers face input price swings from restricted rare earth processing capacity.
Strategic Opportunities
- India PLI scheme for electronics manufacturing:Camera module assembly incentives are attracting smartphone supply chain relocation from coastal China.
- Surgical robotics vision systems:FDA-cleared 4K endoscopic cameras represent underpenetrated demand in US hospital networks.
- Drone-mounted thermal imaging:FAA Part 107 regulatory clarity is opening commercial inspection applications for agricultural and infrastructure monitoring.
Industry Challenges
- Multi-jurisdiction certification parallelism:Medical camera OEMs must maintain separate FDA 510(k), EMA MDR, and PMDA approval tracks, fragmenting quality management systems.
- Legacy automotive Tier-1 integration complexity:Established ADAS suppliers resist architecture shifts to centralized compute with distributed smart cameras.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Camera Technology Market |
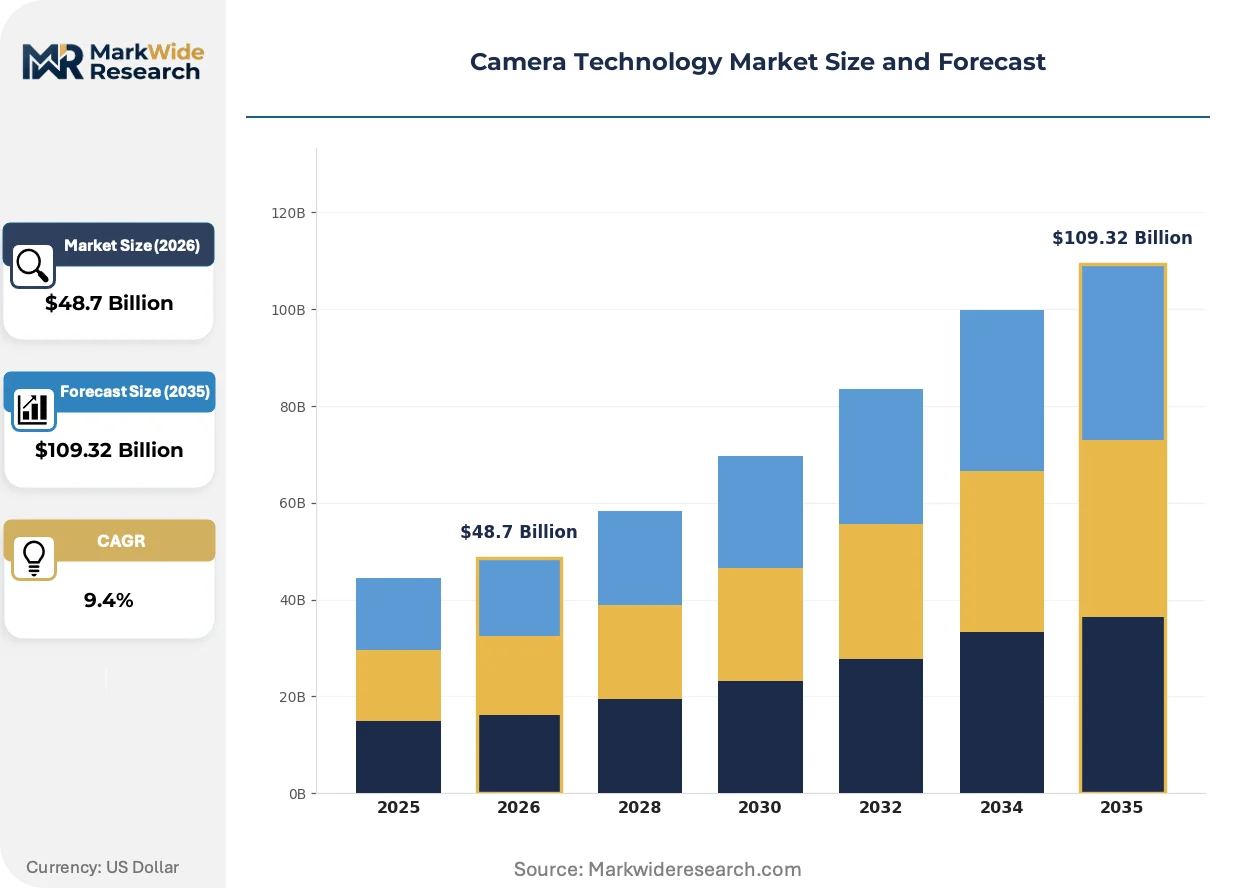
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $109.32 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DSLR, Mirrorless, Point-and-Shoot, Smartphone Technology: CMOS, CCD, Foveon, Multi-layer Application: Photography, Videography, Surveillance, Broadcasting End User: Consumers, Professionals, Enterprises, Hobbyists |
| Companies Covered | Sony Corporation, Canon Inc., Nikon Corporation, Sunny Optical Technology Group Co. Ltd., Foxconn Technology Co. Ltd., STMicroelectronics N.V., FUJIFILM Holdings Corporation, Panasonic Corporation, Apple Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Camera Technology Market Strategic Shifts
Computational photography is migrating from software post-processing to silicon-integrated pipelines, rewiring competitive advantage toward semiconductor design capability and away from traditional optics engineering.
Stacked CMOS image sensors with pixel-level analog-to-digital conversion are miniaturizing die footprints while preserving dynamic range. Automotive Tier-1s in Stuttgart and Detroit are adopting these architectures for cabin monitoring and exterior perception arrays. The technology is compressing module size requirements, enabling windshield-integrated camera placement previously impossible with discrete component designs.
EMA's Medical Device Regulation (MDR) is tightening biocompatibility and sterilization resilience standards for surgical camera systems. European OEMs must redesign cable assemblies and housing materials to meet new cytotoxicity testing protocols. Endoscopic equipment manufacturers in Germany and Switzerland are responding by vertically integrating polymer compound development to control certification timelines.
Enterprise security buyers are unbundling hardware acquisition from video-analytics subscriptions, compressing vendor switching cycles. Large facility operators in Texas and Singapore now procure cameras on open-platform specifications, displacing proprietary ecosystem lock-in. This pattern is most visible in critical infrastructure verticals where cybersecurity audit requirements favor hardware-software decoupling.
Camera Technology Market Segmentation
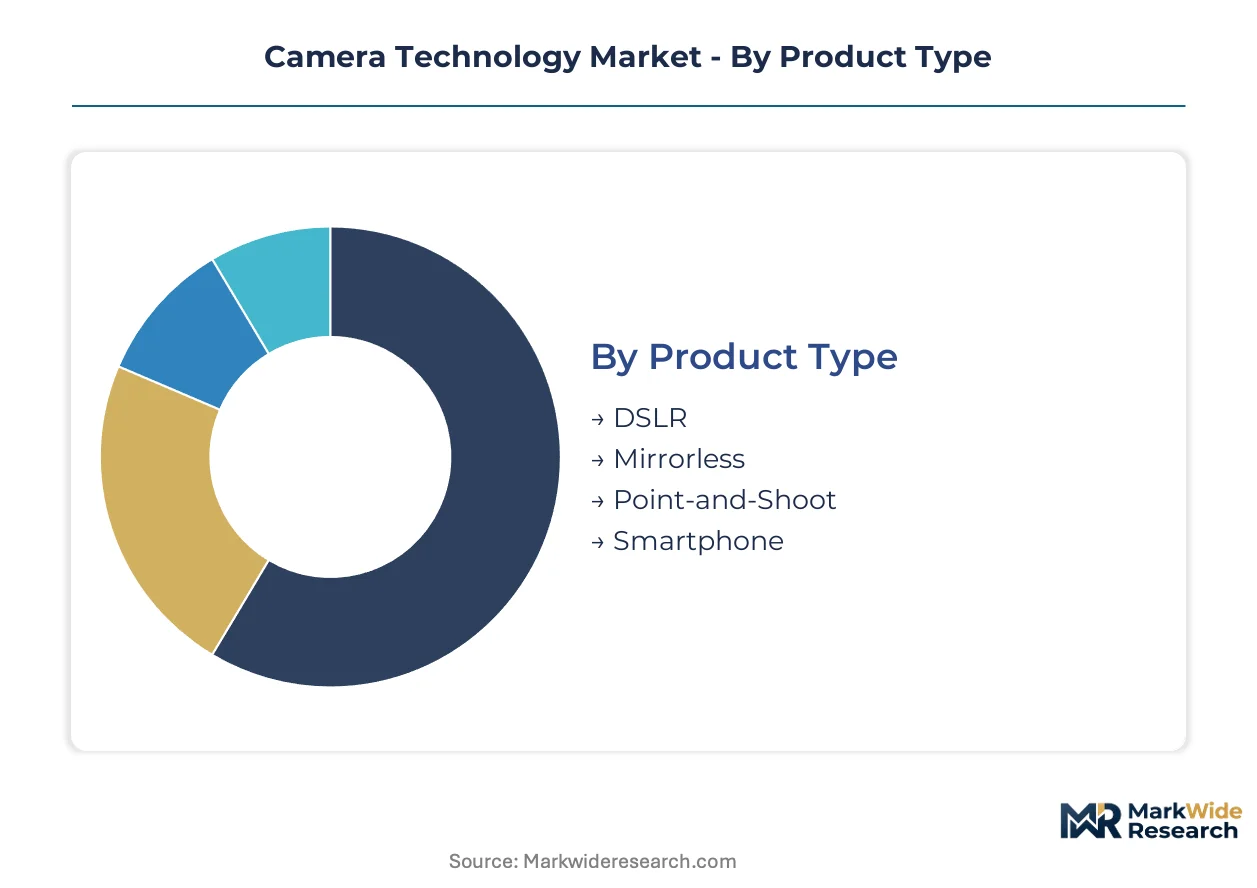
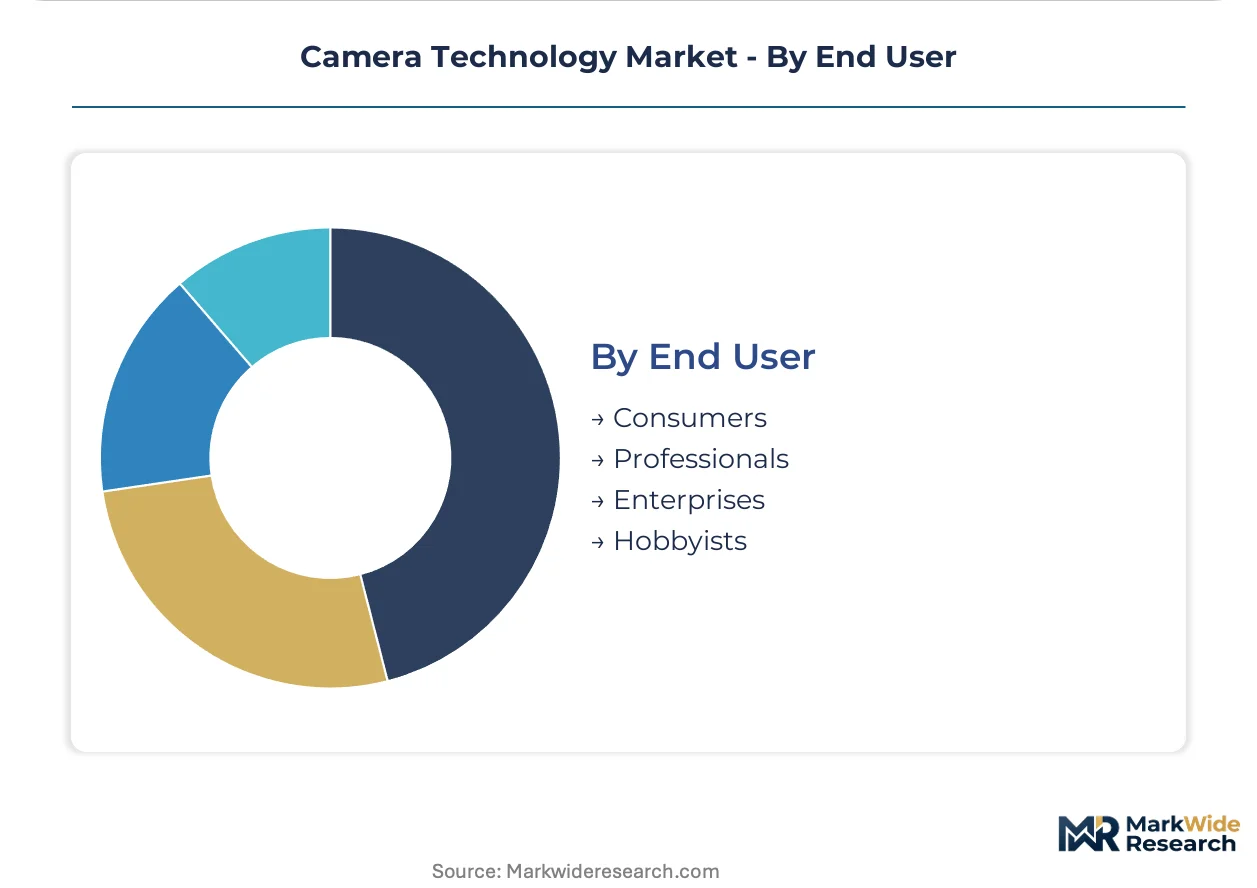
Camera technology segmentation reveals how regulatory compliance, performance tiering, and supply chain concentration fragment procurement decisions across consumer, automotive, and medical verticals. Understanding these divides enables suppliers to align certification investments with margin pools.
Product Type:
Regulatory differentiation separates professional-grade equipment subject to FCC and CE electromagnetic compliance from consumer devices facing lighter conformity assessment.
- DSLR:Optical viewfinder systems with dedicated phase-detection autofocus modules and large battery enclosures. Demand concentrates among wedding and sports photographers in the US and Germany who require all-day shooting endurance; thermal design constraints from EU energy efficiency directives extend product refresh cycles.
- Mirrorless:Electronic viewfinder architectures with short flange distances enabling high-speed readout pipelines. Shenzhen and Seoul OEMs are driving sensor stack integration for hybrid photo-video capture; compact form factors accelerate adoption among documentary filmmakers facing airline carry-on restrictions.
- Point-and-Shoot:Fixed-lens compact cameras with integrated zoom optics and simplified user interfaces. Travel retail channels in Dubai and Singapore sustain residual volume.
- Smartphone:Miniaturized camera modules with computational photography pipelines and multi-array fusion. Domestic EV integration programs in China and sub-micron pixel foundry output anchor global wafer demand.
Smartphone handles the majority of throughput; mirrorless is the fastest mover on share.
Technology:
Cost tiering separates mass-market CMOS wafers from specialized architectures commanding premium pricing in scientific and aerospace applications.
- CMOS:Complementary metal-oxide-semiconductor sensors with per-pixel amplification and low-voltage operation. Automotive ADAS programs in Stuttgart and Detroit require AEC-Q100 qualified variants; stacked architectures with Cu-Cu bonding reduce module height for windshield integration.
- CCD:Charge-coupled device sensors with uniform noise characteristics and high fill factors. Scientific instrumentation in Japan and Switzerland maintains demand for cooled astronomical imaging; legacy supply chains face obsolescence risk from foundry capacity reallocation.
- Foveon:Vertical color separation sensors exploiting silicon absorption depth without Bayer demosaicing. Niche studio applications in California and Italy value per-pixel color accuracy.
- Multi-layer:Stacked photodiode architectures with separate near-infrared and visible light channels. Security system operators in France and Germany deploy these for EU AI Act-compliant facial recognition under varying illumination.
CMOS dominates manufacturing scale; multi-layer is expanding most quickly on surveillance demand.
Application:
Volume concentration varies sharply between saturated consumer photography and surveillance verticals undergoing edge-AI hardware refresh cycles.
- Photography:Static image capture with emphasis on dynamic range, color science, and lens ecosystem depth. Professional workflows in New York and London sustain medium-format and full-frame investment; social platform compression algorithms reduce perceived hardware differentiation.
- Videography:Motion capture with sustained high-bitrate recording and thermal management requirements. Content creators in Los Angeles and Mumbai drive demand for 6K-8K internal recording; CFexpress media standardization reduces proprietary lock-in.
- Surveillance:Continuous monitoring with edge analytics and encrypted transmission protocols. Critical infrastructure operators in Texas and Singapore favor ONVIF-compliant hardware decoupled from analytics subscriptions.
- Broadcasting:Studio and field production with genlock synchronization and 12G-SDI output. Sports leagues in the UK and Brazil require HDR and high-frame-rate capture for live distribution.
Photography retains installed base depth; surveillance is climbing the fastest on compliance-driven refresh spending.
End User:
Customer type determines procurement channel, with enterprises negotiating multi-year service agreements against consumer impulse purchasing.
- Consumers:Price-sensitive purchasers prioritizing ease of use and ecosystem integration. Smartphone upgrade cycles in China and India compress standalone camera consideration.
- Professionals:Revenue-dependent users requiring durability, service network density, and lens compatibility. Wedding photographers in Italy and Australia demand dual-card redundancy and weather sealing.
- Enterprises:Organizational procurement with cybersecurity audit requirements and centralized fleet management. Corporate security departments in Germany and the Netherlands specify NDAA-compliant supply chains.
- Hobbyists:Enthusiast purchasers balancing capability aspiration with budget constraints. Secondhand market liquidity in Japan and the UK extends product lifecycles.
Consumers generate absolute unit volume; enterprises are gaining share fastest on security infrastructure investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAMR governs camera module quality standards in China, where domestic EV integration programs and smartphone manufacturing clusters concentrate procurement volume. Regulatory fragmentation across FDA, EMA, and PMDA approval tracks shapes competitive positioning in medical imaging verticals.
China
Domestic EV camera integration programs and sub-micron pixel foundry output anchor regional demand. MIIT enforces GB standards for automotive-grade imaging modules deployed in Level 2+ autonomous driving systems. Shenzhen and Dongguan manufacturing clusters supply smartphone OEMs with stacked CMOS architectures for multi-array fusion.
United States
FDA-cleared 4K endoscopic cameras drive surgical robotics vision system procurement in hospital networks. FCC certification rules constrain wireless-enabled camera modules for IoT and drone platforms operating in unlicensed spectrum bands. Texas critical infrastructure operators favor ONVIF-compliant hardware decoupled from proprietary analytics subscriptions.
Germany
Automotive Tier-1s in Stuttgart adopt stacked CMOS architectures with Cu-Cu bonding for windshield-integrated ADAS placement. EU AI Act compliance mandates accelerate demand for cameras with embedded neural processing units in surveillance applications. Bavarian endoscopic equipment manufacturers vertically integrate polymer compound development to control EMA MDR certification timelines.
Japan
Specialized sensor engineering talent scarcity extends R&D timelines for next-generation stacked CMOS designs in optics hubs. METI oversees industrial policy supporting domestic CMOS foundry capacity retention against Taiwan-based competition. Tokyo and Osaka maintain demand for cooled CCD sensors in scientific instrumentation despite legacy supply chain obsolescence risk.
India
PLI scheme incentives for electronics manufacturing attract camera module assembly relocation from coastal China. BIS standards govern import quality certification for security system hardware deployed in smart city infrastructure. Tamil Nadu and Karnataka industrial corridors host emerging smartphone supply chain clusters serving domestic and export markets.
Camera Technology Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with captive foundry capacity and lens mount ecosystem control separating the upper tier from component suppliers. The middle layer comprises automotive-grade module specialists and time-of-flight fabricators serving Tier-1 integration programs. Two strategic archetypes dominate: semiconductor-integrated imaging platform vendors and optics-pure-play manufacturers with vertical control over lens ecosystems. Competitive moves concentrate on foundry capacity expansion for automotive qualification and strategic partnerships to secure rare earth processing for infrared sensor substrates.
Within the integrated platform tier, Sony Corporation exemplifies captive CMOS foundry dominance for smartphone OEM supply chains, while Canon Inc. occupies a position defined by lens mount ecosystem control in professional imaging. STMicroelectronics N.V. sits within the automotive-grade specialist tier, representing the time-of-flight module fabricators supplying cabin monitoring and exterior perception arrays to Stuttgart and Detroit Tier-1s.
| Leading Market Players |
|---|
| Sony Corporation |
| Canon Inc. |
| Nikon Corporation |
| Sunny Optical Technology Group Co. Ltd. |
| Foxconn Technology Co. Ltd. |
| STMicroelectronics N.V. |
| FUJIFILM Holdings Corporation |
| Panasonic Corporation |
| Apple Inc. |
| Others |
Value Chain & Pricing Dynamics
Fourteen-week lead times for automotive-grade time-of-flight modules concentrate pricing power with Taiwan-based foundries serving Stuttgart and Detroit Tier-1s, while smartphone CMOS wafer allocation tightens procurement leverage for Shenzhen OEMs. This inventory compression cascades into spot-market premiums for gallium arsenide substrates and forces dual-sourcing investments among infrared sensor manufacturers facing rare earth processing bottlenecks.
Pricing Analysis
Geographic price spreads between German automotive ADAS modules and Chinese smartphone camera assemblies exceed three-to-one ratios driven by AEC-Q100 certification premiums against commodity CMOS tiers. Three-tier pricing structure across automotive-grade, professional imaging, and consumer electronics levels separates FDA-cleared surgical vision systems from FCC-certified IoT modules. Cost compression in smartphone sub-micron pixel production is intensifying because foundry capacity reallocations favor mobile wafer output. Enterprise security buyers in Texas and Singapore exhibit lowest price sensitivity due to cybersecurity audit requirements, while hobbyist segments in Japan and the UK face liquidity constraints from secondhand market depth.
Supply Chain Analysis
Taiwan Strait transit vulnerabilities expose single-source dependencies for stacked CMOS image sensors serving Level 2+ autonomous driving programs. Manufacturing concentrates in Taiwan, China, and South Korea for advanced node fabrication, with Japan retaining legacy CCD capacity for scientific instrumentation. Raw material flows draw from gallium arsenide substrate processors, rare earth refineries, and polymer compound developers for MDR-compliant cable assemblies. Tariff exposure runs through US-China technology trade restrictions on semiconductor manufacturing equipment. Distribution runs through Tier-1 automotive suppliers in Stuttgart and Detroit, smartphone OEM assembly clusters in Shenzhen and Dongguan, and hospital network procurement committees for FDA-cleared endoscopic systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smartphone computational photography pipelines threaten standalone camera module incumbents by compressing hardware differentiation into software algorithms, forcing optical specialists to defend against silicon-integrated substitution.
For Market Incumbents: Secure captive foundry capacity for automotive-grade time-of-flight qualification before Taiwan-based allocation tightens further. Lock lens mount ecosystem control through backward integration into polymer compound development for EMA MDR biocompatibility compliance, defending against modular open-platform competitors displacing proprietary hardware-software bundles. For New Entrants and Emerging Players: Anchor in India PLI scheme incentives for camera module assembly serving domestic smartphone OEMs and export markets. Target surgical robotics vision systems as the most penetrable vertical, where FDA 510(k) pathway clarity and underdeveloped domestic supply chains create white-space for 4K endoscopic camera entrants with sterilization resilience credentials. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because automotive ADAS camera integration programs and EU AI Act compliance mandates concentrate procurement volume with scale-qualified suppliers. Acquisition candidates with AEC-Q100 certification and Cu-Cu bonding stacked CMOS expertise offer defensive positioning. Watch FAA Part 107 regulatory clarity on drone-mounted thermal imaging as the inflection signal for agricultural inspection demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Automotive Qualification Investment | AEC-Q100 certification unlocks Stuttgart and Detroit Tier-1 procurement pipelines for ADAS modules. |
| Edge-AI Silicon Integration | Embedded neural processing units satisfy EU AI Act facial recognition mandates for German surveillance operators. |
| Foundry Capacity Expansion | Domestic CMOS fabrication retention counters Taiwan-based single-source vulnerability for Japanese optics hubs. |
| MDR Compliance Verticalization | In-house polymer compound development accelerates EMA biocompatibility timelines for Bavarian endoscopic manufacturers. |
| Open-Platform Specification Adoption | ONVIF compliance attracts Texas critical infrastructure buyers decoupling hardware from analytics subscriptions. |
Study Parameters
Initial hypotheses were tested against primary input from automotive Tier-1 procurement officers, smartphone OEM supply chain managers, hospital biomedical engineers, and surveillance system integrators and refined through secondary validation against SEC filings of sensor manufacturers, MIIT GB standard publications, FDA 510(k) clearance databases, and EMA MDR technical documentation. Bottom-up module shipment aggregation across consumer, automotive, and medical verticals was triangulated against top-down wafer foundry capacity allocation estimates.
Variance decomposition across product type, technology architecture, application vertical, and end-user procurement channel structured the analytical framework over the projection horizon. CAGRs were derived from segment-level volume trajectories and value-per-unit evolution across certification tiers. Forecast inputs incorporated automotive ADAS camera penetration curves, sub-micron pixel foundry yield improvements, and EU AI Act implementation timelines for on-device analytics mandates.
Underlying assumptions cover sustained rare earth processing capacity for infrared substrates and Taiwan-based advanced node fabrication continuity, with deviation risk concentrated in US-China technology trade restrictions and automotive semiconductor qualification backlog extensions. Practitioners should keep alternative scenarios live as EU AI Act enforcement intensity and India PLI scheme participation rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Compact Camera Module Market
Imaging
Visualiser Market
Imaging
Machine Vision Market
Imaging
CMOS Smartphone Camera Lens Market
Imaging
Hyper Spectral Imaging System Market
Imaging
North America Image Sensors Market
Imaging
Gige Camera Market
Imaging
Semiconductor Microscopes Market
Imaging
Global Image Processing Systems Market
Imaging
Chemical Imaging Systems Market
Imaging
Semiconductor CD-SEM Systems Market
Imaging
Pocket Video Camera Market
Imaging
Handheld Imaging Systems Market
Imaging
US Near Infrared Imaging Market
Imaging
Photoacoustic Microscope Market
Imaging
Light Field Market