
 Webcam Market | 2026-2036
Webcam Market Size, Share, and Industry Trends Forecast 2026-2036
Webcam Market Intelligence
4K resolution tiering is reorganizing the webcam value chain as enterprise buyers replace legacy 720p fleets. Logitech leverages its channel control across commercial distributors to sustain volume leadership. Insta360 anchors the premium creative segment with specialized imaging hardware. Razer competes in the gaming and streamer niche through RGB-integrated industrial design.
A webcam is a digital video capture device combining a CMOS or CCD image sensor, fixed or varifocal lens assembly, and USB or wireless controller chipset, engineered for real-time audiovisual transmission across conferencing platforms, surveillance systems, and content creation workflows. External webcams dominate corporate procurement budgets as IT departments standardize on detachable, upgradeable peripherals over integrated laptop cameras. Streamer-oriented 4K units with built-in microphone arrays command the fastest expansion in feature-tier revenue pools.
FCC Part 15 emissions compliance and CE marking under EU Radio Equipment Directive shape hardware certification timelines and market access eligibility for manufacturers. USB Implementers Forum certification and Thunderbolt interoperability testing further constrain which chipset architectures gain enterprise approval. Stakeholders must monitor regulatory convergence between data privacy frameworks and hardware authentication standards to anticipate procurement specification shifts.
Market Dynamics
Hybrid work permanence is compressing enterprise refresh cycles from five-year intervals to eighteen-month rotations, forcing IT procurement departments to standardize on detachable peripherals with unified firmware management capabilities.
Growth Catalysts
- USB Video Class certification:FCC Part 15 emissions compliance and CE marking under EU Radio Equipment Directive are elevating baseline performance thresholds, disqualifying uncertified suppliers from enterprise tenders.
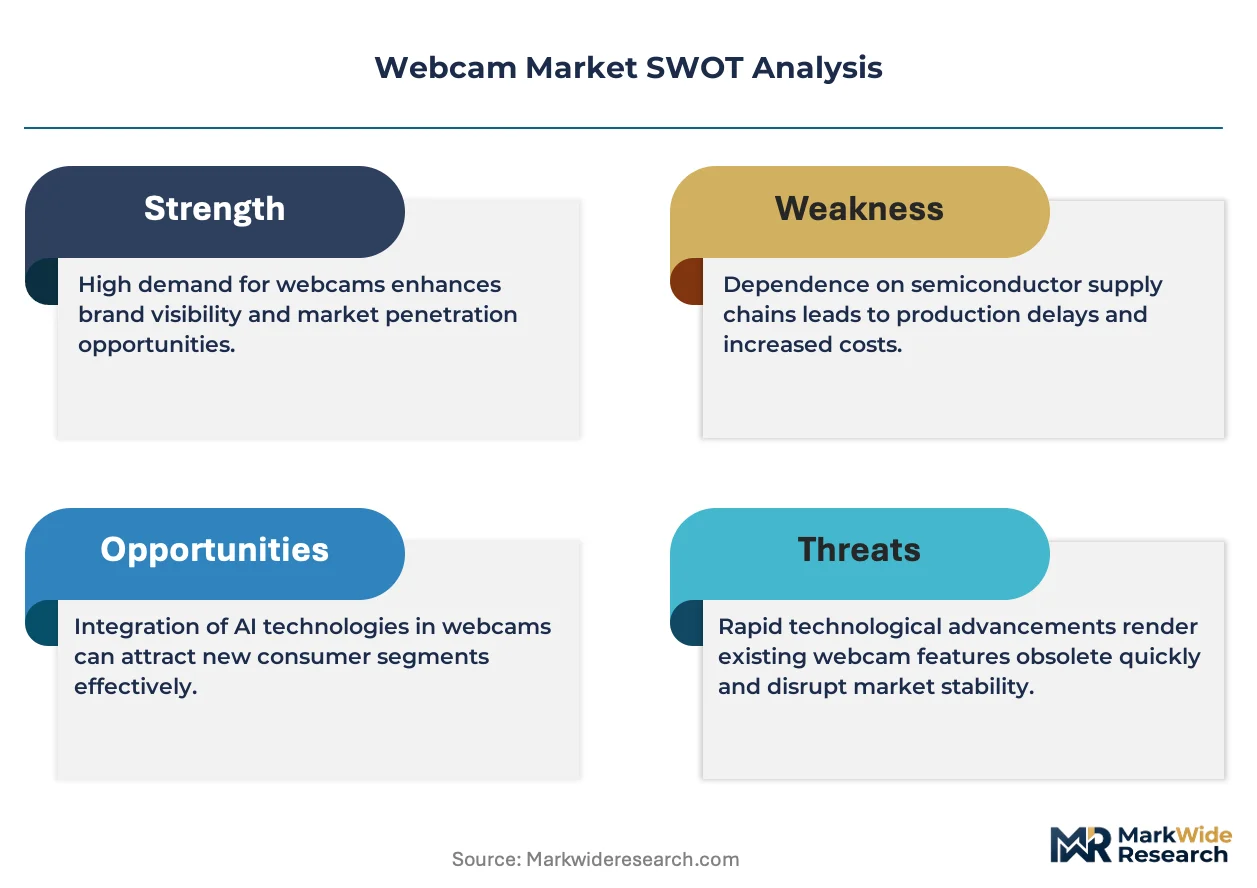
- CMOS sensor advancement:Backside-illuminated stacked architectures are collapsing low-light noise floors, enabling 4K capture at price points previously occupied by 1080p units.
- Japan enterprise endpoint programs:METI-backed workplace digitization subsidies are accelerating camera replacements in financial services and precision manufacturing headquarters clusters.
Market Restraints
- Image sensor supply concentration:Advanced CMOS fabrication capacity concentrates in Taiwan and South Korea foundries, exposing procurement timelines to geopolitical friction and capacity allocation disputes.
- Thunderbolt interoperability testing:USB Implementers Forum certification timelines extend six to nine months, freezing product launches for manufacturers lacking pre-certified controller architectures.
- Integrated laptop camera substitution:Notebook OEMs are narrowing the quality gap with AI-enhanced ISP tuning, reducing the attach rate for external units in cost-sensitive segments.
Strategic Opportunities
- India BIS certification pathway:Mandatory Bureau of Indian Standards registration for electronics imports is creating first-mover advantage for manufacturers establishing local testing partnerships ahead of enforcement deadlines.
- AI-driven framing and background segmentation:Neural processing unit offload from host CPUs is enabling intelligent auto-tracking without dedicated hardware, opening premium feature tiers at mid-market pricing.
- Healthcare telemedicine workflows:HIPAA-compliant peripheral authentication requirements in US hospital systems are mandating hardware-level encryption, favoring suppliers with pre-validated security architectures.
Industry Challenges
- Firmware engineering talent scarcity:Real-time video pipeline optimization for heterogeneous conferencing platforms requires specialized embedded systems expertise concentrated in Shenzhen and Taipei talent pools.
- CE marking documentation burden:EU Radio Equipment Directive technical file compilation demands electromagnetic compatibility testing across multiple notified bodies, extending time-to-revenue for new product families.
- Legacy UC platform integration:Backward compatibility with aging Microsoft Teams and Zoom client versions requires maintaining multiple firmware branches, fragmenting engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Webcam Market |
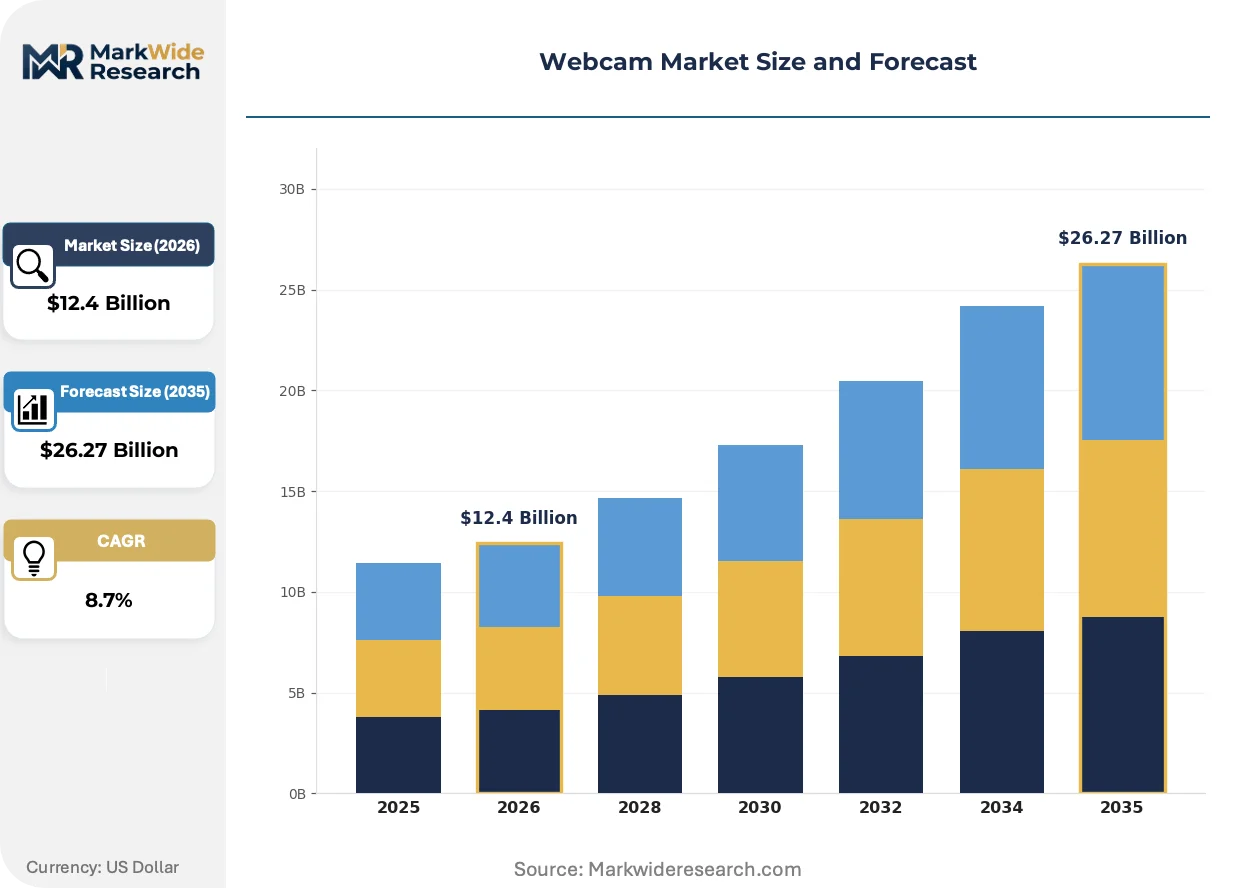
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $26.27 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: External Webcam, Integrated Webcam, HD Webcam, 4K Webcam End User: Corporate, Educational, Creative Professionals, Streamers Technology: USB, Wireless, Bluetooth, Thunderbolt Feature: Auto-Focus, Low-Light Correction, Wide-Angle, Built-In Microphone |
| Companies Covered | Anker, Insta360, Logitech, Yololiv, Dell, Elgato, OBSBOT, Corsair, Razer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Webcam Market Strategic Shifts & Innovations
Computational imaging is redistributing value from optical hardware to signal processing software, compressing the traditional lens-sensor assembly cost structure while elevating firmware and AI model training as competitive differentiators.
Computational photography stacks are decomposing the traditional imaging pipeline into discrete software modules. Enterprise procurement teams are prioritizing units with field-upgradable neural processing capabilities over fixed-function hardware. This architecture is decomposing the premium tier's historical reliance on large-format sensors and precision glass.
EU AI Act risk classification frameworks are mandating transparency documentation for biometric identification systems including facial recognition in conferencing peripherals. Hardware vendors must now maintain algorithmic audit trails and human oversight protocols for intelligent framing features. German automotive and pharmaceutical headquarters clusters are demanding pre-certified compliance packages ahead of enforcement timelines.
Enterprise buying committees are consolidating peripheral procurement under managed service contracts rather than discrete hardware purchases. Value-added distributors are absorbing inventory risk and providing unified endpoint management dashboards. This pattern is most pronounced in United States financial services and professional services verticals where IT standardization programs mandate single-supplier relationships for audiovisual endpoints.
Webcam Market Segmentation
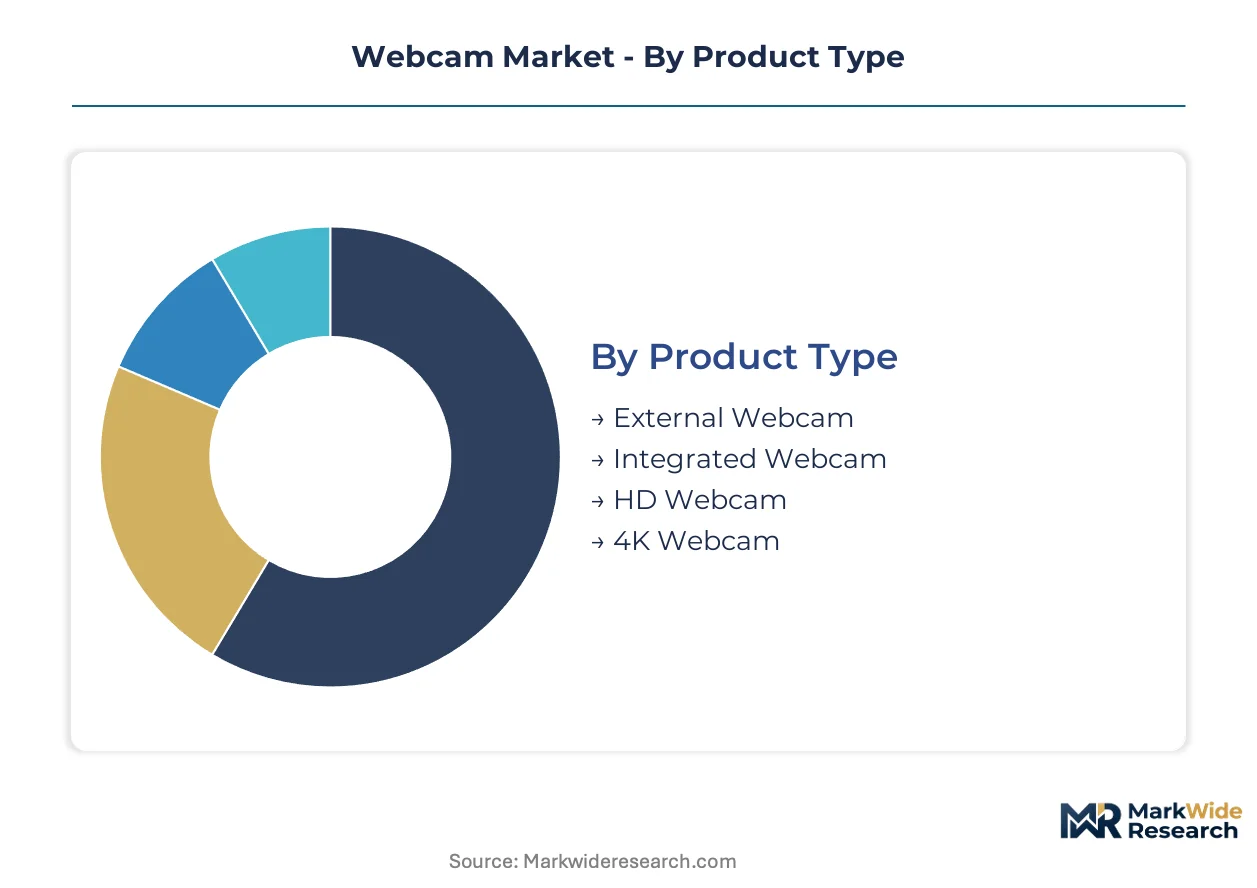
Webcam segmentation reflects divergent substitution pressures across hardware tiers. Integrated laptop cameras are narrowing quality gaps with AI-enhanced ISP tuning, forcing external peripheral vendors to differentiate through detachable flexibility and enterprise manageability.
Product Type:
External units face the strongest substitution pressure from integrated alternatives, while resolution tiers stratify procurement budgets across enterprise refresh cycles.
- External Webcam:Detachable USB or wireless peripherals with dedicated image sensors and lens assemblies. Corporate IT departments in the United States and Germany are standardizing on upgradeable external units with unified firmware management to escape laptop vendor lock-in.
- 4K Webcam:Ultra-high-definition capture devices leveraging backside-illuminated CMOS architectures. Streamer and creative professional demand in Japan and the United States is compressing price premiums as sensor costs decline.
- HD Webcam:1080p resolution devices occupying mid-market procurement tiers. Educational institutions favor these units for cost-sensitive classroom deployments.
- Integrated Webcam:Embedded camera modules in notebook displays and all-in-one systems. Notebook OEMs are narrowing the quality gap with AI-enhanced ISP tuning.
External Webcam anchors the volume base while 4K Webcam gains share at the steepest rate.
End User:
Procurement authority concentration varies sharply across these segments, with managed service contracts consolidating purchasing power in corporate verticals.
- Corporate:Enterprise IT departments procuring standardized fleets for hybrid work endpoints. United States financial services and professional services verticals are mandating single-supplier relationships for audiovisual peripherals under managed service contracts.
- Streamers:Individual content creators and gaming broadcasters demanding broadcast-quality capture. RGB-integrated industrial design and AI-driven background segmentation command premium positioning in this segment.
- Educational:K-12 and higher institutions deploying cameras for remote instruction. Budget constraints favor HD resolution tiers with bulk purchasing agreements.
- Creative Professionals:Video producers and photographers requiring color-accurate capture. Specialized imaging hardware with manual exposure controls addresses this niche.
Corporate procurement dominates absolute volume while Streamer-oriented feature tiers expand most quickly.
Technology:
Certification timelines and interoperability testing create divergent time-to-revenue constraints across connectivity standards.
- USB:Universal Serial Bus Video Class devices with plug-and-play compatibility. FCC Part 15 emissions compliance and CE marking under EU Radio Equipment Directive elevate baseline performance thresholds for USB certification.
- Thunderbolt:High-bandwidth connectivity enabling uncompressed 4K video streams. USB Implementers Forum certification timelines extend six to nine months, freezing product launches for manufacturers lacking pre-certified controller architectures.
- Wireless:Wi-Fi or proprietary radio-based transmission protocols. Latency sensitivity limits adoption in real-time conferencing applications.
- Bluetooth:Short-range wireless protocol primarily for audio synchronization. Insufficient bandwidth for video transmission constrains this technology to peripheral pairing functions.
USB connectivity anchors installed base volumes while Thunderbolt interfaces climb the fastest among premium-tier deployments.
Feature:
Computational imaging is redistributing value from optical hardware to signal processing software, compressing traditional lens-sensor cost structures.
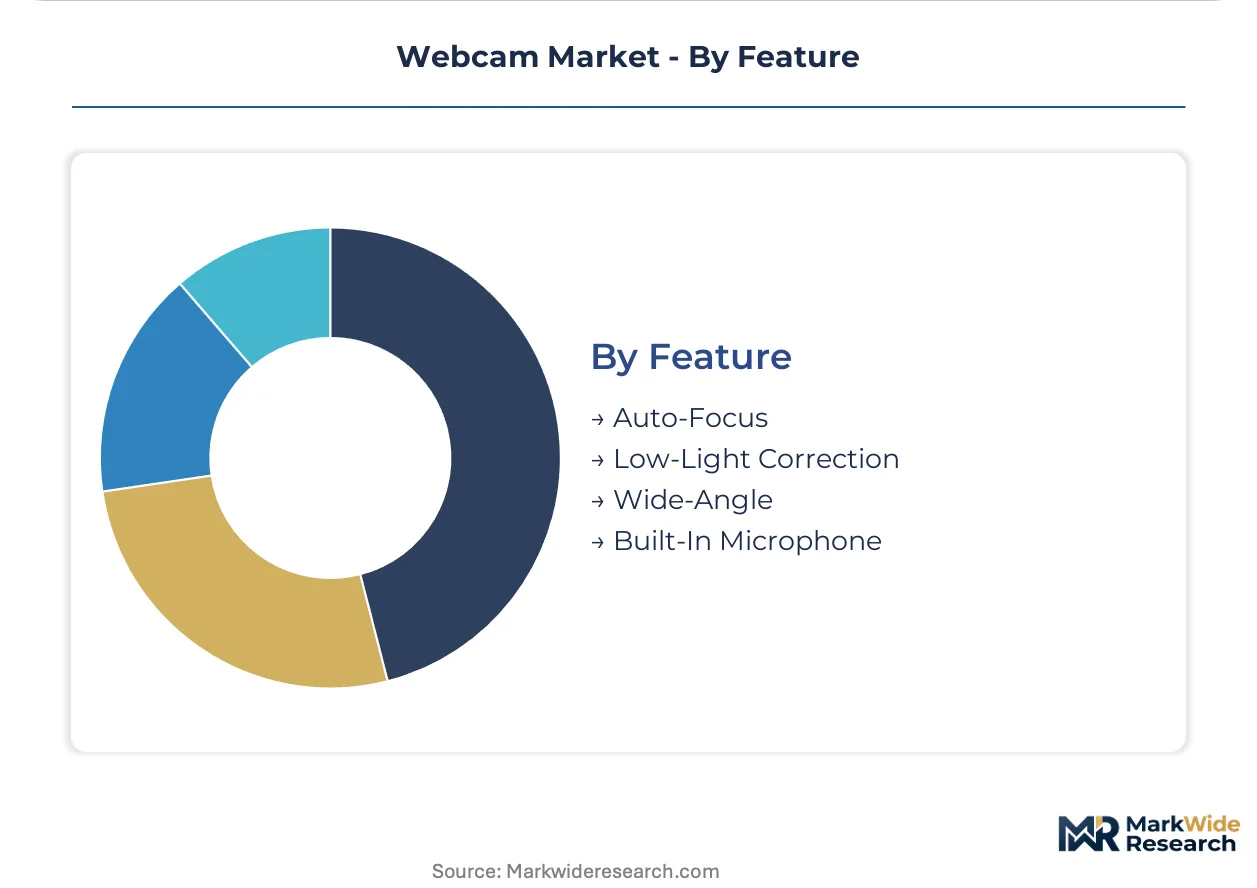
- Auto-Focus:Contrast-detection or phase-detection systems maintaining subject sharpness. Enterprise procurement teams prioritize field-upgradable neural processing capabilities over fixed-function hardware implementations.
- Built-In Microphone:Integrated microphone arrays with noise cancellation algorithms. Streamer-oriented 4K units with beamforming arrays command fastest expansion in feature-tier revenue pools.
- Low-Light Correction:Backside-illuminated sensor architectures and multi-frame noise reduction. Stacked CMOS designs are collapsing noise floors at price points previously occupied by standard sensors.
- Wide-Angle:Short focal length lenses capturing expanded field of view. Huddle room deployments in corporate settings drive specification requirements for 120-degree coverage.
Built-In Microphone anchors attach-rate expectations while Auto-Focus capabilities gain share fastest through AI-driven neural processing offload.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CMOS sensor fabrication concentrates in Taiwan and South Korea foundries, creating geographic exposure for procurement timelines. Enterprise endpoint upgrade programs in financial services and precision manufacturing headquarters clusters are compressing refresh cycles across major economies.
United States
Financial services and professional services verticals are mandating single-supplier relationships for audiovisual peripherals under managed service contracts. HIPAA-compliant peripheral authentication requirements in hospital systems mandate hardware-level encryption. Corporate headquarters clusters in New York Metro and Greater Boston are accelerating camera replacements as hybrid work permanence resets IT procurement standards.
Germany
Automotive and pharmaceutical headquarters clusters are demanding pre-certified compliance packages ahead of EU AI Act enforcement timelines. CE marking under EU Radio Equipment Directive shapes hardware certification timelines and market access eligibility. Industrial concentrations in Bavaria and Baden-Württemberg are standardizing on detachable peripherals with unified firmware management capabilities.
Japan
METI-backed workplace digitization subsidies are accelerating camera replacements in financial services and precision manufacturing headquarters clusters. JIS standards and technical compliance frameworks elevate baseline performance thresholds for enterprise tenders. Tokyo and Osaka metropolitan areas anchor demand for 4K resolution tiers as enterprise buyers replace legacy 720p fleets.
India
Mandatory Bureau of Indian Standards registration for electronics imports is creating first-mover advantage for manufacturers establishing local testing partnerships. CDSCO and central bank frameworks shape procurement specifications in healthcare and financial verticals. Maharashtra and Karnataka technology corridors are concentrating demand for mid-market HD units in educational and corporate deployments.
South Korea
Advanced CMOS fabrication capacity anchors sensor supply for global webcam manufacturers, exposing procurement timelines to capacity allocation disputes. MFDS and central bank regulations shape enterprise procurement in healthcare and financial sectors. Seoul Capital Area and Busan-Ulsan industrial clusters are driving demand for premium 4K units with AI-driven background segmentation capabilities.
Webcam Market Key Industry Players
Concentration sits with diversified peripherals specialists and imaging hardware innovators. The vendor base spans three distinct tiers: volume leaders controlling commercial distribution channels, premium specialists commanding creative professional segments, and gaming-focused designers targeting streamer niches. Strategic moves center on channel control consolidation and computational imaging capability acquisition. Portfolio diversification and firmware management platform development represent dominant competitive vectors.
Within the volume leadership tier, Logitech exemplifies channel control across commercial distributors. Insta360 and Razer occupy differentiated positions at the premium and gaming-specialist ends respectively. Logitech represents scale-driven procurement standardization. Insta360 anchors specialized imaging hardware for creative workflows. Razer exemplifies RGB-integrated industrial design targeting content creator niches. These three fabricators illustrate how competitive positioning fragments across enterprise manageability, creative professional features, and gaming aesthetic differentiation.
| Leading Market Players |
|---|
| Anker |
| Insta360 |
| Logitech |
| Yololiv |
| Dell |
| Elgato |
| OBSBOT |
| Corsair |
| Razer |
| Others |
Cost & Logistics Intelligence
FCC Part 15 emissions compliance and CE marking under EU Radio Equipment Directive gate both supply qualification and price differentiation simultaneously, forcing uncertified manufacturers into economy tiers while pre-certified suppliers command procurement premiums across United States and German enterprise tenders.
Pricing Analysis
USB Video Class certification dictates the pricing tier structure across the webcam market. Three-tier pricing structure across premium, standard, and economy levels separates streamer-oriented 4K units with AI-driven features from HD corporate fleets and uncertified entry-level devices. Price differentiation rests on certification grade and volume scale, with enterprise managed-service contracts compressing per-unit margins. Cost compression in the HD tier intensifies because notebook OEMs narrow quality gaps with AI-enhanced ISP tuning. Educational institutions represent the most price-sensitive buyer segment, while healthcare systems purchasing HIPAA-compliant peripherals show the least sensitivity due to mandatory hardware-level encryption requirements.
Supply Chain Analysis
Strategic stockpiling of CMOS sensors dominates inventory strategy as manufacturers buffer against Taiwan and South Korea foundry allocation disputes. Advanced CMOS fabrication concentrates in Taiwan and South Korea, with Japan contributing precision lens assemblies. Raw material dependencies include silicon wafers, rare-earth optical coatings, and USB controller chipsets. Single-source vulnerability in backside-illuminated sensor supply exposes procurement timelines to geopolitical friction. Distribution runs through commercial IT distributors and value-added resellers serving corporate procurement departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-economics inflection centers on USB Video Class certification becoming the interoperability layer that determines hardware market access, with Microsoft Teams and Zoom client ecosystems driving consolidation toward pre-certified suppliers.
For Market Incumbents: Consolidate channel control through exclusive distributor relationships and captive firmware management platforms to defend against integrated laptop camera substitution. Backward integration into CMOS sensor supply agreements with Taiwan foundries secures allocation priority. Certification investment in BIS pre-registration for India creates first-mover advantage ahead of enforcement deadlines. For New Entrants and Emerging Players: Lead with AI-driven framing and background segmentation capabilities targeting mid-market pricing gaps between premium streamer units and standard corporate fleets. Healthcare telemedicine workflows present the most penetrable segment due to HIPAA-compliant peripheral authentication requirements mandating hardware-level encryption. Direct-to-enterprise sales bypassing distributor markups offers the strongest go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified electronics conglomerates with dormant webcam peripheral divisions lacking USB-IF certification infrastructure. Long-term viability hinges on computational imaging capability ownership shifting value from optical hardware to signal processing software. Watch for EU AI Act enforcement timelines crossing thresholds that trigger German automotive and pharmaceutical procurement specification shifts.| Strategic Initiative | Industry Significance |
|---|---|
| USB-IF Certification Acceleration | Pre-certified controller architectures from Taiwan suppliers compress six-to-nine month launch timelines. |
| Computational Imaging Acquisition | Neural processing unit offload capabilities open premium feature tiers at mid-market pricing points. |
| India BIS Partnership Establishment | Local testing relationships ahead of mandatory electronics import registration create first-mover advantage. |
| Healthcare Security Architecture Validation | HIPAA-compliant peripheral authentication pre-qualification secures hospital system procurement mandates. |
| Managed Service Contract Consolidation | Single-supplier relationships for audiovisual endpoints capture United States financial services verticals. |
Research Approach
The analysis maps external webcam hardware tiers, integrated camera substitution pressures, and resolution-based segmentation clusters, each validated through IT procurement officers, channel distribution managers, and firmware engineering directors. Primary interviews with enterprise endpoint standardization leads, commercial distributor category heads, and embedded systems specialists combine with secondary validation from USB Implementers Forum certification databases, FCC equipment authorization filings, and EU notified body CE marking registries. Bottom-up sensor shipment tracking and top-down enterprise IT spend analysis enable triangulation across data sources.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. The analytical framework models resolution tiers, connectivity standards, end-user verticals, and regional certification requirements throughout the forecast period. CAGRs derive from segment-level shipment trajectories and average selling price erosion curves. Forecast inputs include hybrid work permanence indicators, CMOS sensor cost decline slopes, and regulatory enforcement timeline acceleration in the EU and India.
The analysis sits within stated boundaries; outcomes outside sustained enterprise refresh cycle compression or stable Taiwan-South Korea foundry capacity would require recalibration. Forecasts reflect assumptions around USB Video Class certification remaining the dominant interoperability standard. Revision becomes warranted when geopolitical friction in East Asian semiconductor supply crosses thresholds that trigger allocation rationing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
CCD Image Sensors Market
Imaging
CMOS Smartphone Camera Lens Market
Imaging
Chemiluminescence Imaging Market
Imaging
Video Processing Solutions Market
Imaging
Uncooled Infrared Imaging Market
Imaging
Whole Slide Imaging Systems Market
Imaging
Frame Grabber Market
Imaging
Sub-Micrometer Computed Tomography Market
Imaging
Borescope Market
Imaging
Machine Vision Camera Market
Imaging
X-Ray Systems Market
Imaging
Machine Vision System Market
Imaging
Mobile Camera Module Market
Imaging
Smart Camera Market
Imaging
SDI Camera Market
Imaging
Semiconductor Microscopes Market