
 Chemiluminescence Imaging Market | 2026-2036
Chemiluminescence Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Chemiluminescence Imaging Market Analysis
Academic research laboratories are collapsing into the dominant buyer archetype for chemiluminescence imaging systems as pharmaceutical R&D budgets flatten. LI-COR Biosciences leverages its Odyssey platform's near-infrared detection to dominate the high-end research segment. Thermo Fisher Scientific sustains broad channel control across clinical and research markets through its installed base of western blot workflows. Azure Biosystems competes on compact footprint designs tailored to space-constrained university core facilities.
Chemiluminescence imaging detects light emission from chemical reactions, typically employing cooled CCD cameras with quantum efficiency exceeding 80% in the 400–700 nm range for quantitative protein and nucleic acid visualization. The technique serves as the backbone of Western blot documentation, enzyme-linked immunosorbent assay readouts, and reporter gene assays in molecular biology laboratories. Reagents and immunoassay kits capture recurring revenue streams with higher margin stability than instrument sales, while advanced imaging systems with automated exposure algorithms command premium pricing in high-throughput screening environments. Research applications anchor volume demand, though clinical diagnostics segments are deepening penetration as point-of-care immunoassay platforms mature.
FDA 510(k) clearance requirements for in vitro diagnostic imaging readers shape product development timelines and clinical market access pathways. ISO 13485 quality management standards govern manufacturing protocols for systems destined for regulated diagnostic environments. The EPA's analytical method validation frameworks influence environmental monitoring applications where chemiluminescence detection quantifies pollutant biomarkers. Stakeholders must weigh instrument platform standardization against modular upgrade flexibility as assay multiplexing demands intensify.
Market Dynamics
Academic procurement consolidation is compressing vendor margins as universities consolidate core imaging facilities and demand multi-user platform licenses over single-lab instrument sales. NIH funding volatility creates cyclical replacement windows that synchronize demand spikes across Boston, San Diego, and Research Triangle Park clusters.
Growth Catalysts
- Companion diagnostic validation:FDA 510(k) pathway expansion for imaging-based IVDs is pulling high-sensitivity systems into clinical development pipelines.
- Western blot standardization:CCD quantum efficiency improvements above 80% in the 400–700 nm range are displacing film-based documentation in proteomics core facilities.
- Near-infrared multiplexing:Dual-channel detection protocols are expanding quantitative applications beyond single-analyte chemiluminescence.
Market Restraints
- Cooled sensor supply concentration:Sony and ON Semiconductor dominate sCMOS and CCD sensor fabrication, creating single-source vulnerability for high-quantum-efficiency detectors.
- Reagent cost volatility:Horseradish peroxidase substrate prices fluctuate with agricultural commodity cycles, compressing recurring revenue margins.
- Fluorescence substitution:Alexa Fluor and IRDye detection systems are capturing multiplexing applications that chemiluminescence cannot address spectrally.
Strategic Opportunities
- Point-of-care immunoassay integration:Miniaturized CMOS photodiode arrays are enabling handheld chemiluminescence readers for decentralized diagnostics.
- India research infrastructure:DBT and DST funding for molecular biology core facilities is creating first-time instrument procurement outside established US and EU markets.
- ISO 13485 certification acceleration:Streamlined quality management pathways are shortening clinical market entry timelines for research-platform vendors.
Industry Challenges
- Cross-disciplinary technician training:Facilities managers now require simultaneous expertise in optics, molecular biology, and IT integration, narrowing qualified hiring pools.
- Legacy gel documentation displacement:UV transilluminator replacement cycles are colliding with chemiluminescence upgrade budgets, forcing capital prioritization decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chemiluminescence Imaging Market |
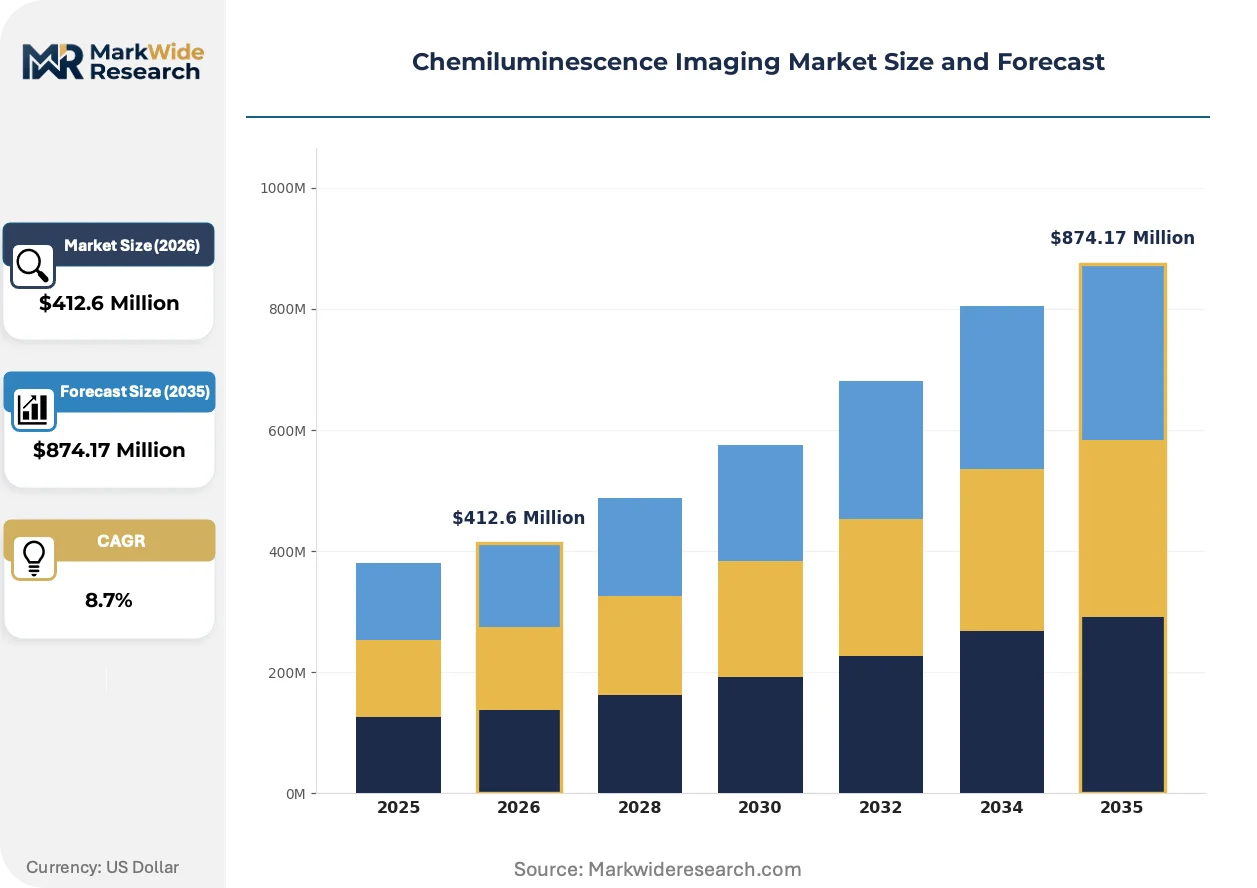
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $874.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Immunoassay Kits, Equipment, Software Application: Clinical Diagnostics, Environmental Monitoring, Drug Testing, Research End User: Hospitals, Diagnostic Laboratories, Research Institutions, Pharmaceuticals Technology: Conventional Methods, Advanced Imaging Systems, Analytical Techniques, Automation |
| Companies Covered | LI-COR Biosciences, Analytik Jena US, Thermo Fisher Scientific, Agilent Technologies, Bio-Techne Corporation, GE Healthcare, Azure Biosystems, Syngene, PerkinElmer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chemiluminescence Imaging Market Emerging Trajectories
Computational exposure algorithms and solid-state photon counting are converging to compress acquisition times while expanding dynamic range. These shifts are redefining instrument architecture away from hardware-centric toward software-differentiated platforms.
CMOS photodiode arrays with integrated analog-to-digital conversion are decomposing the traditional cooled CCD camera stack. Proteomics core facilities at Johns Hopkins and ETH Zurich are piloting these compact detectors for high-throughput screening. The technology is decomposing the premium pricing tier that thermal management and vacuum-sealed sensors previously sustained.
EPA analytical method validation frameworks for pollutant biomarker quantification are tightening detection limit documentation requirements. Environmental monitoring laboratories must now demonstrate picogram-level sensitivity with traceable calibration chains. Western blot workflows in toxicology applications are responding by adopting automated exposure bracketing to satisfy audit trails.
Core facility directors are unbundling service contracts from instrument purchases and negotiating regional multi-site maintenance agreements. Thermo Fisher and Azure Biosystems distributors in the United States are losing captive service revenue to third-party biomedical equipment servicers. This pattern concentrates in California and Massachusetts where university procurement consortia command volume leverage.
Chemiluminescence Imaging Market Segmentation
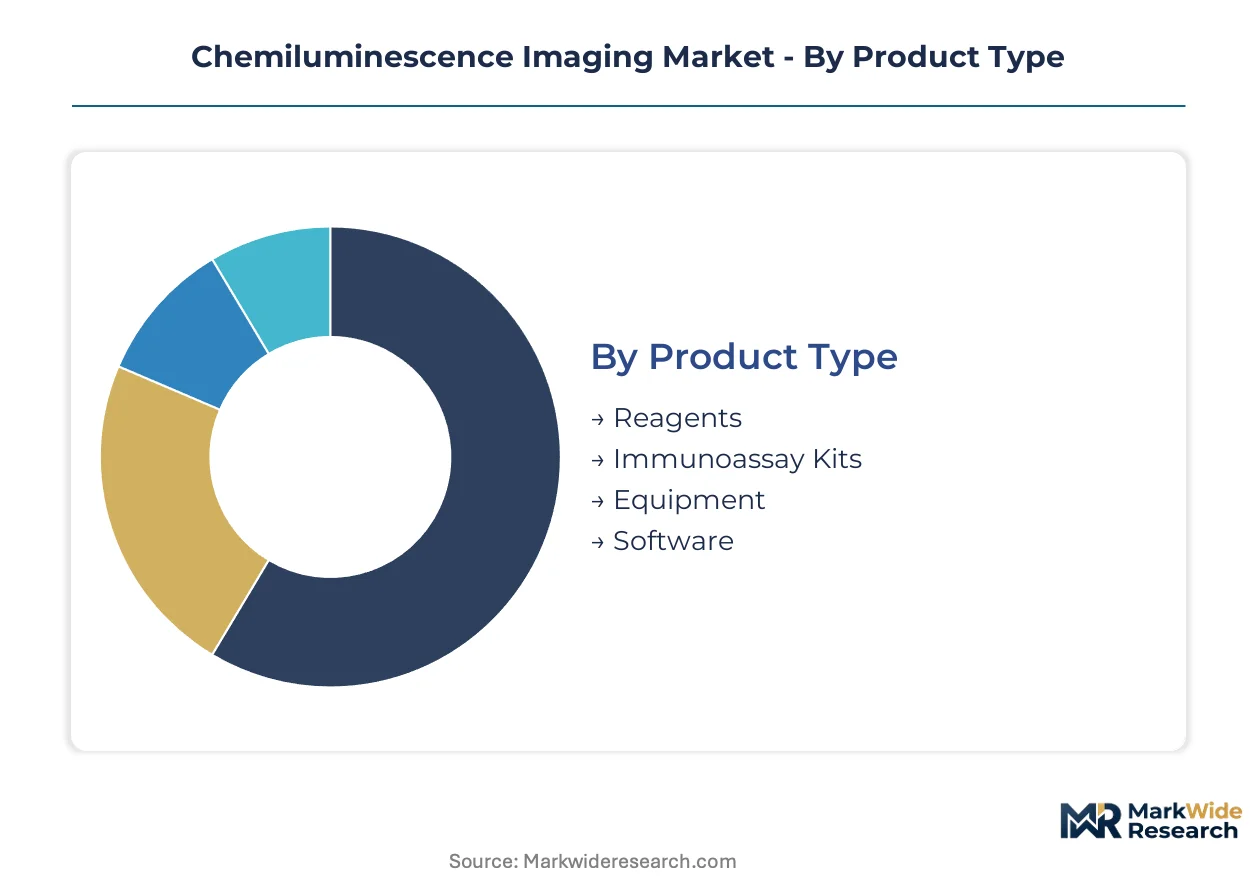
Chemiluminescence imaging market segmentation reveals where substitution pressures and margin concentration diverge across product tiers. Understanding these fault lines enables targeted positioning against fluorescence and digital PCR alternatives.
Product Type:
Reagent segments face acute substitution pressure from fluorescent probe chemistries, while equipment tiers defend position through sensor integration complexity. Cost tier analysis shows consumables competing on per-test economics against instrument platforms competing on capital efficiency.
- Reagents:Horseradish peroxidase and alkaline phosphatase substrates dominate Western blot workflows. Academic core facilities in Boston and San Diego drive volume through standardized ELISA protocols despite peroxidase price volatility tied to agricultural commodity cycles.
- Immunoassay Kits:Pre-validated antibody-substrate combinations reduce assay development time for clinical laboratories. FDA 510(k) clearance requirements for companion diagnostics tighten kit performance documentation, favoring vendors with regulatory affairs infrastructure.
- Equipment:Cooled CCD and sCMOS camera systems anchor instrument revenue with quantum efficiency specifications exceeding 80% in the 400–700 nm range.
- Software:Automated exposure algorithms and quantitative analysis modules differentiate premium platforms from basic image capture systems.
Reagents anchor the volume base while advanced imaging systems gain share at the steepest rate.
Application:
Application segmentation tracks diverging regulatory maturity—clinical endpoints demand ISO 13485 certification while research workflows prioritize throughput flexibility. Customer type rotation shows academic buyers consolidating procurement against pharmaceutical R&D budget compression.
- Clinical Diagnostics:Point-of-care immunoassay platforms require miniaturized photon detection with traceable calibration chains. FDA clearance pathways for imaging-based IVDs pull high-sensitivity systems into hospital laboratory networks.
- Research:Western blot standardization in proteomics core facilities displaces film-based documentation. NIH funding cycles synchronize replacement windows across Research Triangle Park and San Diego clusters.
- Environmental Monitoring:EPA analytical method validation frameworks mandate picogram-level sensitivity for pollutant biomarker quantification.
- Drug Testing:High-throughput screening environments demand automated exposure bracketing to satisfy toxicology audit trails.
Research applications command the installed base while clinical diagnostics climbs the fastest toward regulatory-validated revenue.
End User:
End user segmentation exposes procurement consolidation dynamics—university core facilities negotiate multi-site licenses while diagnostic laboratories prioritize service contract unbundling. Geography rotation concentrates demand in United States biotech corridors with NIH funding exposure.
- Research Institutions:Space-constrained university core facilities favor compact footprint designs with multi-user platform licenses. Procurement consortia in California and Massachusetts command volume leverage against distributor service revenue.
- Diagnostic Laboratories:Hospital networks demand ISO 13485-certified systems with streamlined quality management pathways for clinical market entry.
- Pharmaceuticals:Flattening R&D budgets compress instrument replacement cycles while companion diagnostic pipelines sustain high-sensitivity imaging demand.
- Hospitals:Point-of-care integration requirements favor handheld CMOS photodiode arrays for decentralized immunoassay readouts.
Research institutions anchor the volume base while diagnostic laboratories gain share at the steepest rate.
Technology:
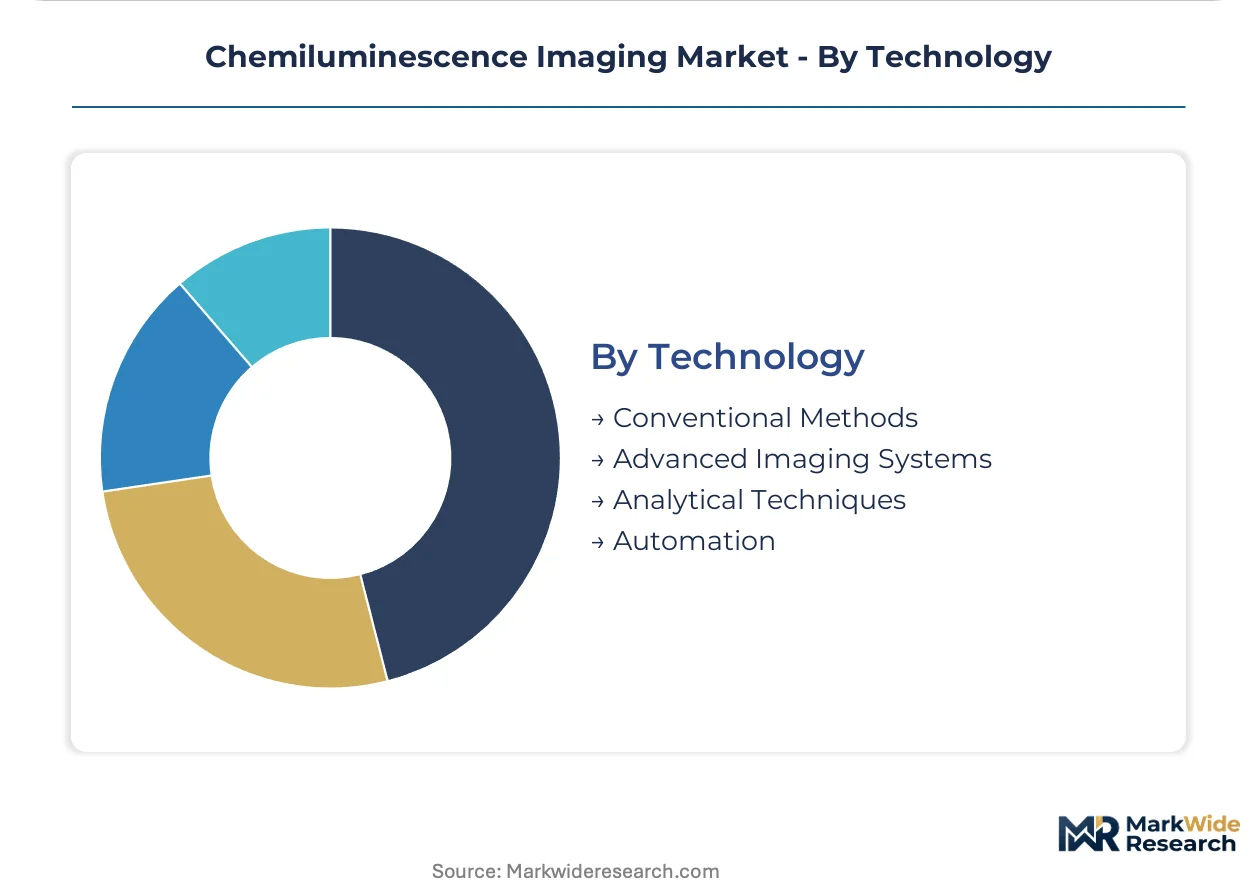
Technology segmentation tracks hardware-to-software value migration—solid-state photon counting decomposes premium pricing tiers previously sustained by thermal management complexity. Maturity rotation shows conventional methods defending installed base against automated platform displacement.
- Advanced Imaging Systems:Computational exposure algorithms and integrated analog-to-digital conversion compress acquisition times while expanding dynamic range. Johns Hopkins and ETH Zurich pilot compact detectors for high-throughput proteomics screening.
- Automation:Robotic sample handling and automated exposure bracketing address cross-disciplinary technician training gaps in facilities management hiring pools.
- Conventional Methods:Film-based documentation persists in budget-constrained laboratories despite CCD quantum efficiency advantages.
- Analytical Techniques:Method validation protocols for traceable calibration chains satisfy EPA and FDA documentation requirements.
Conventional methods anchor the volume base while automation gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Swiss precision instrumentation exports flow into United States academic core facilities and diagnostic laboratory networks, establishing transatlantic trade corridors that synchronize replacement cycles across Boston and San Diego clusters.
United States
NIH funding volatility concentrates instrument procurement windows in Research Triangle Park and Greater Boston biotech corridors. FDA 510(k) clearance requirements for companion diagnostic imaging readers tighten validation protocols for clinical market entry. Thermo Fisher Scientific's installed base across western blot workflows sustains channel control in San Diego and Massachusetts research clusters.
Germany
Analytik Jena US leverages German precision engineering heritage to supply cooled CCD systems into European proteomics facilities. EMA regulatory frameworks for in vitro diagnostic imaging influence quality management standards across manufacturing operations. Baden-Württemberg instrumentation clusters export high-quantum-efficiency detectors to academic buyers in Switzerland and Austria.
China
NMPA medical device registration pathways extend product development timelines for clinical diagnostic imaging systems. MIIT industrial policy supports domestic CMOS photodiode array fabrication for miniaturized immunoassay readers. Yangtze River Delta biotech parks in Shanghai and Suzhou pilot compact chemiluminescence platforms for decentralized diagnostics.
India
DBT and DST funding for molecular biology core facilities creates first-time instrument procurement outside established US and EU markets. CDSCO medical device regulations shape quality documentation requirements for imported imaging systems. Karnataka and Telangana research infrastructure in Bangalore and Hyderabad attracts western blot workflow standardization projects.
United Kingdom
Syngene maintains imaging system development operations serving European academic consortia and pharmaceutical R&D networks. MHRA post-Brexit regulatory divergence from EMA frameworks complicates cross-border diagnostic device approvals. Cambridge and Oxford research clusters sustain demand for high-sensitivity Western blot documentation systems.
Chemiluminescence Imaging Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity and regulatory affairs capabilities. Thermo Fisher Scientific and Agilent Technologies leverage public market access to fund diagnostic platform acquisitions, while LI-COR Biosciences and Azure Biosystems operate with private capital flexibility. Three archetypes dominate: diversified life science conglomerates with installed base advantages, specialized imaging platform developers with sensor integration expertise, and compact system innovators targeting space-constrained core facilities. Competitive moves concentrate on ISO 13485 certification acceleration for clinical market entry and service contract unbundling to defend margin position against third-party biomedical equipment servicers.
Within the diversified conglomerate tier, Thermo Fisher Scientific and Agilent Technologies occupy positions spanning research and clinical market channels. LI-COR Biosciences exemplifies the specialized platform archetype through its near-infrared detection focus. Azure Biosystems represents compact footprint innovation targeting university procurement consortia in California and Massachusetts. These three anchors demonstrate how sensor integration complexity and regulatory infrastructure separate sustainable competitive position from commodity imaging hardware.
| Leading Market Players |
|---|
| LI-COR Biosciences |
| Analytik Jena US |
| Thermo Fisher Scientific |
| Agilent Technologies |
| Bio-Techne Corporation |
| GE Healthcare |
| Azure Biosystems |
| Syngene |
| PerkinElmer |
| Others |
Supply Flow & Price Mechanics
ISO 13485 certification gates both supplier qualification and price differentiation in clinical diagnostic imaging systems, compressing margins for uncertified vendors while enabling premium positioning for quality-validated platforms. Academic procurement consortia exploit this bifurcation to negotiate volume discounts on research-grade equipment, forcing manufacturers to absorb certification costs or surrender clinical market access.
Pricing Analysis
Next-generation CMOS photodiode arrays command three-tier pricing structure across premium, standard, and economy levels, with cooled CCD systems defending mid-tier positioning against solid-state displacement. Price differentiation hinges on quantum efficiency specifications and ISO 13485 certification tier, with FDA-cleared clinical systems capturing 40-60% premiums over research-only configurations. Pricing pressure stems from academic budget consolidation in California and Massachusetts, where multi-site licensing negotiations erode per-unit margins. Research institutions exhibit highest price sensitivity due to NIH funding volatility, while diagnostic laboratories prioritize total cost of ownership over capital expenditure.
Supply Chain Analysis
Sony and ON Semiconductor fabrication capacity in Japan and the United States constitutes a critical chokepoint for high-quantum-efficiency sCMOS and CCD sensors, constraining instrument production timelines across all vendor tiers. The supply chain draws from German precision optics, Japanese sensor fabrication, and Chinese CMOS assembly for miniaturized photodiode arrays. Single-source vulnerability in cooled sensor manufacturing amplifies tariff exposure from US-Japan trade frameworks. Distribution runs through authorized distributors serving academic core facilities and direct sales teams penetrating hospital laboratory networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a switching-cost fortress, where Western blot workflow entrenchment and FDA validation timelines create formidable barriers against fluorescence substitution and emerging detection modalities.
For Market Incumbents: Fortify installed base stickiness through backward integration into reagent supply chains, capturing recurring revenue streams that offset instrument margin compression. Accelerate ISO 13485 certification for research-platform derivatives to preempt clinical market entry by compact system innovators. Defend against CMOS photodiode displacement by emphasizing thermal management advantages in high-sensitivity applications. For New Entrants and Emerging Players: Anchor in India's DBT-funded molecular biology core facilities, where first-time instrument procurement lacks incumbent workflow entrenchment. Target space-constrained university consortia in California and Massachusetts with compact footprint designs unburdened by legacy service contract obligations. Pursue white-label partnerships with third-party biomedical equipment servicers to bypass distributor channel control. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across CMOS photodiode array manufacturing, compressing returns for hardware-centric business models while expanding software-differentiated platform economics. Favor acquisition targets with regulatory affairs infrastructure spanning FDA 510(k) and EMA quality management pathways. Monitor NIH appropriations cycles as the critical inflection signal for replacement demand synchronization.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Acceleration | Shortens clinical market entry timelines for research-platform vendors competing against Thermo Fisher's regulatory infrastructure. |
| Reagent Supply Integration | Captures horseradish peroxidase substrate revenue streams with higher margin stability than instrument sales cycles. |
| CMOS Photodiode Platform Development | Decomposes premium pricing tiers previously sustained by thermal management complexity in cooled CCD systems. |
| Multi-Site Service Contract Unbundling | Erodes distributor captive revenue in California and Massachusetts where university procurement consortia command volume leverage. |
| India Research Infrastructure Partnership | Positions first-mover advantage in Bangalore and Hyderabad core facilities outside established US and EU replacement cycles. |
Methodological Framework
Operator-level perspectives from proteomics core facility directors, biomedical equipment servicers, regulatory affairs specialists at imaging system vendors, and hospital laboratory purchasing committees anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through FDA 510(k) clearance databases, NIH RePORTER funding records, EPA analytical method validation frameworks, and ISO 13485 certification registries. Bottom-up instrument shipment analysis triangulated against top-down reagent consumption estimates across academic and clinical end-use segments.
Sensitivity analysis tested demand elasticity against NIH appropriations volatility, sensor supply disruption scenarios, and fluorescence substitution penetration rates across the projection horizon. The analytical framework modeled segmentation across product type, application, end user, and technology maturity tiers, with additional dimensioning by regional regulatory cluster and funding agency exposure. CAGRs derived from replacement cycle analysis synchronized to NIH funding windows and clinical diagnostic validation timelines, incorporating Western blot standardization adoption curves and point-of-care miniaturization trajectories.
Decision-makers should treat outputs as directional under sustained NIH funding levels and stable sensor supply availability; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as EPA detection limit requirements and FDA companion diagnostic pathways evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Virtual Reality Camera Market
Imaging
Visualiser Market
Imaging
Ultraviolet Transilluminator Imaging Systems Market
Imaging
X-Ray Microscopes Market
Imaging
Hyperspectral Imaging Camera Market
Imaging
Uncooled Thermal Imaging Market
Imaging
Global Pathology Imaging Systems Market
Imaging
India CCTV Camera Market
Imaging
Global Trail Camera Market
Imaging
Europe CT Market
Imaging
Global Digital Photography Market
Imaging
Global Thermal Imager Market
Imaging
Camcorder Market
Imaging
In Vivo Imaging Systems Market
Imaging
Europe IP Camera Market
Imaging
Global Broadcast Cameras Market