
 Semiconductor Cartridge Heaters Market | 2026-2036
Semiconductor Cartridge Heaters Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Cartridge Heaters Market Insights
Semiconductor fabrication equipment is pivoting toward higher thermal uniformity requirements as advanced node processes multiply heating zones per chamber. Watlow leverages its North American manufacturing base to supply OEMs with application-engineered cartridge configurations. Chromalox sustains competitive pressure through R&D intensity in high-purity sheath materials for cleanroom environments. Tempco Electric Heater Corporation anchors its position via specialized geometries for etch and deposition tools.
A semiconductor cartridge heater is a cylindrical resistance heating element, typically constructed from a nickel-chromium coil embedded in magnesium oxide insulation within a stainless steel or Incoloy sheath, designed to deliver localized, high-watt-density thermal energy in precision process equipment. The device converts electrical current to heat through Joule heating, with sheath temperatures reaching levels required for wafer processing, gas line heating, and chamber wall temperature management in semiconductor manufacturing environments. Silicon carbide and molybdenum disilicide variants command premium positioning due to extreme temperature tolerance in epitaxy and diffusion applications, while Kanthal-based products occupy mature, cost-sensitive maintenance and replacement segments. Electronics manufacturing end users generate the dominant demand pool, though automotive components and aerospace qualification programs are expanding as non-traditional buyers.
Regulatory frameworks from the EPA, OSHA, and REACH constrain material selection and workplace exposure limits for heater sheath alloys and ceramic insulators, directly elevating compliance costs for suppliers serving multinational OEMs. The EU F-Gas Regulation and analogous state-level rules in California and New York further tighten process emissions standards, indirectly amplifying demand for precision thermal control that reduces purge gas consumption. Stakeholders must monitor evolving semiconductor subsidy eligibility rules across jurisdictions, as local content thresholds increasingly determine qualification for public procurement and tariff relief programs.
Market Dynamics
Advanced node migration below 7nm is fragmenting thermal management architectures, multiplying discrete heating zones per process chamber from dozens to hundreds and forcing cartridge heater suppliers to engineer sub-millimeter precision at wafer-scale uniformity.
Growth Catalysts
- CHIPS Act capital deployment:US-based megafab construction is accelerating qualification timelines for domestic heater suppliers seeking foundry equipment integration slots.
- Silicon carbide epitaxy expansion:Power semiconductor fabrication for electric vehicle inverters is pulling ultra-high-temperature cartridge variants into 1,400°C process environments.
- Gas line heating density:Advanced deposition chemistries require distributed heater arrays along precursor delivery systems, expanding unit counts per tool.
Market Restraints
- Nickel-chromium alloy supply concentration:Specialty wire production clusters in Germany and Japan create single-source vulnerability for high-purity resistance elements.
- REACH substance restrictions:ECHA candidate list expansions for nickel compounds are forcing sheath material reformulations with unproven field longevity.
- Induction heating substitution:Non-contact thermal systems are capturing select annealing applications above 800°C where cartridge maintenance cycles burden throughput.
Strategic Opportunities
- India semiconductor ecosystem:Gujarat and Tamil Nadu fab incentives under the PLI scheme are creating greenfield procurement channels without incumbent supplier lock-in.
- Predictive maintenance integration:Embedding resistance drift sensors into heater cartridges enables condition-based replacement contracts with OEM service divisions.
- Hydrogen process compatibility:Reducing atmosphere annealing for advanced memory nodes requires hydrogen-rated sheath alloys with premium positioning potential.
Industry Challenges
- Cleanroom-certified technician scarcity:Installation and replacement protocols for Class 1 environments require specialized training pipelines that regional labor markets cannot fill.
- Multi-vendor chamber integration:Thermal uniformity validation across heterogeneous heater populations from different suppliers extends tool qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Cartridge Heaters Market |
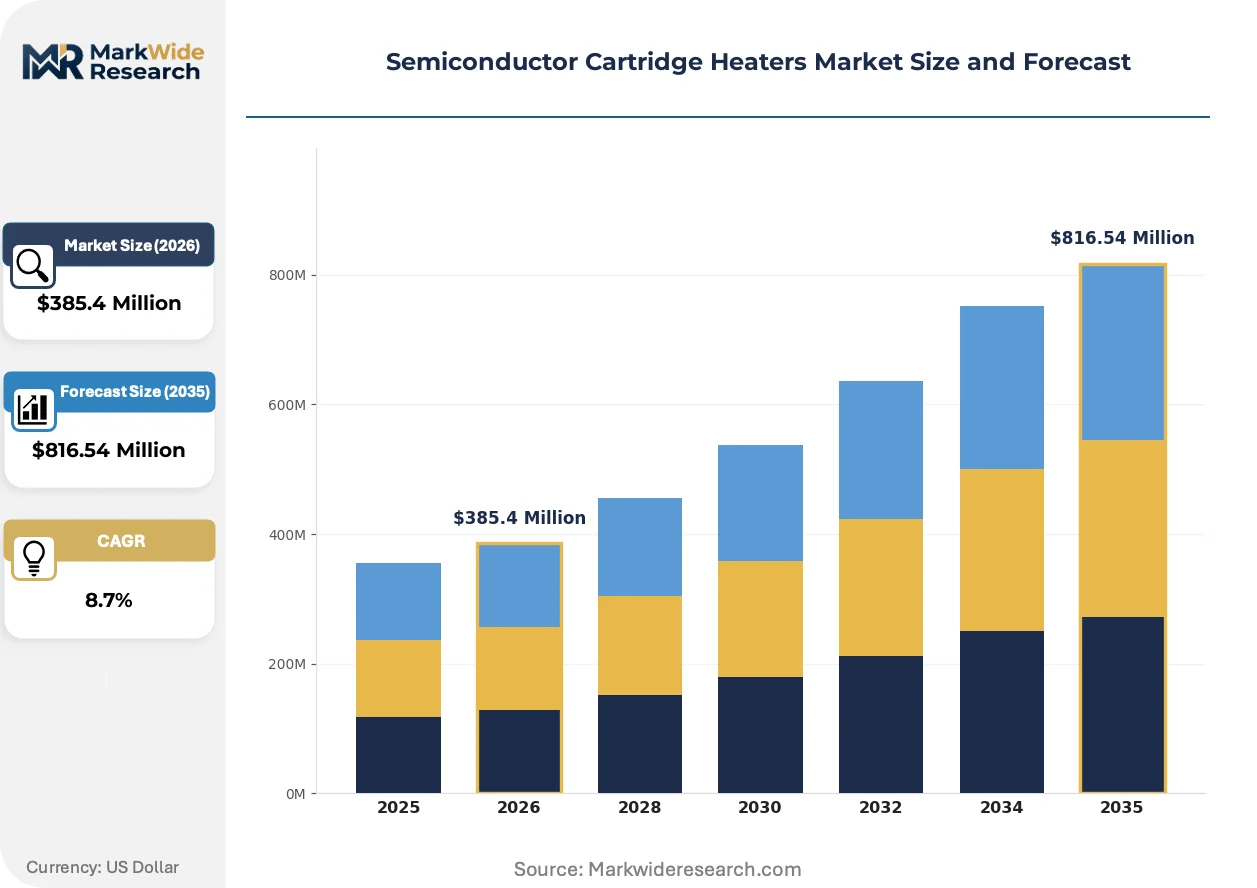
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $816.54 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicon Carbide, Molybdenum Disilicide, Kanthal, Others End User: Electronics Manufacturing, Aerospace, Automotive Components, Industrial Equipment Power Rating: Low Power, Medium Power, High Power, Ultra High Power Installation Type: On-Site, Modular, Integrated, Standalone |
| Companies Covered | Watlow, Chromalox, Tempco Electric Heater Corporation, Zoppas Industries, NIBE Industrier AB, Backer Group, Hotset, Sino-Japan Electric Heater, Headway Electric Heat Components, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Cartridge Heaters Market Trends and Innovations
Precision thermal engineering is converging with semiconductor process control architectures, embedding distributed sensing and adaptive power modulation directly into heating elements rather than treating them as passive components.
Zone-level cartridge control is decentralizing thermal management from centralized PID systems to edge-computing heater modules. Foundry equipment OEMs in Taiwan and South Korea are piloting addressable heater arrays that adjust watt density in real-time based on chamber gas flow patterns. This architecture compresses thermal gradient tolerances from ±5°C to ±1.5°C while reducing purge gas consumption.
EPA emissions standards for perfluorinated compounds are tightening process gas abatement requirements. Semiconductor manufacturers in Oregon and Arizona must now demonstrate thermal destruction efficiency above 99% for effluent streams, elevating specification priority for high-temperature heater reliability. Equipment suppliers are responding with redundant heating configurations and continuous resistance monitoring.
Aftermarket service unbundling is fragmenting traditional OEM captive supply relationships. Independent semiconductor maintenance contractors in Singapore and Dresden are qualifying third-party cartridge heaters for non-warranty tool support, compressing replacement part margins while expanding addressable volume. This channel shift is most pronounced in mature node facilities where process risk tolerance exceeds leading-edge constraints.
Semiconductor Cartridge Heaters Market Segmentation
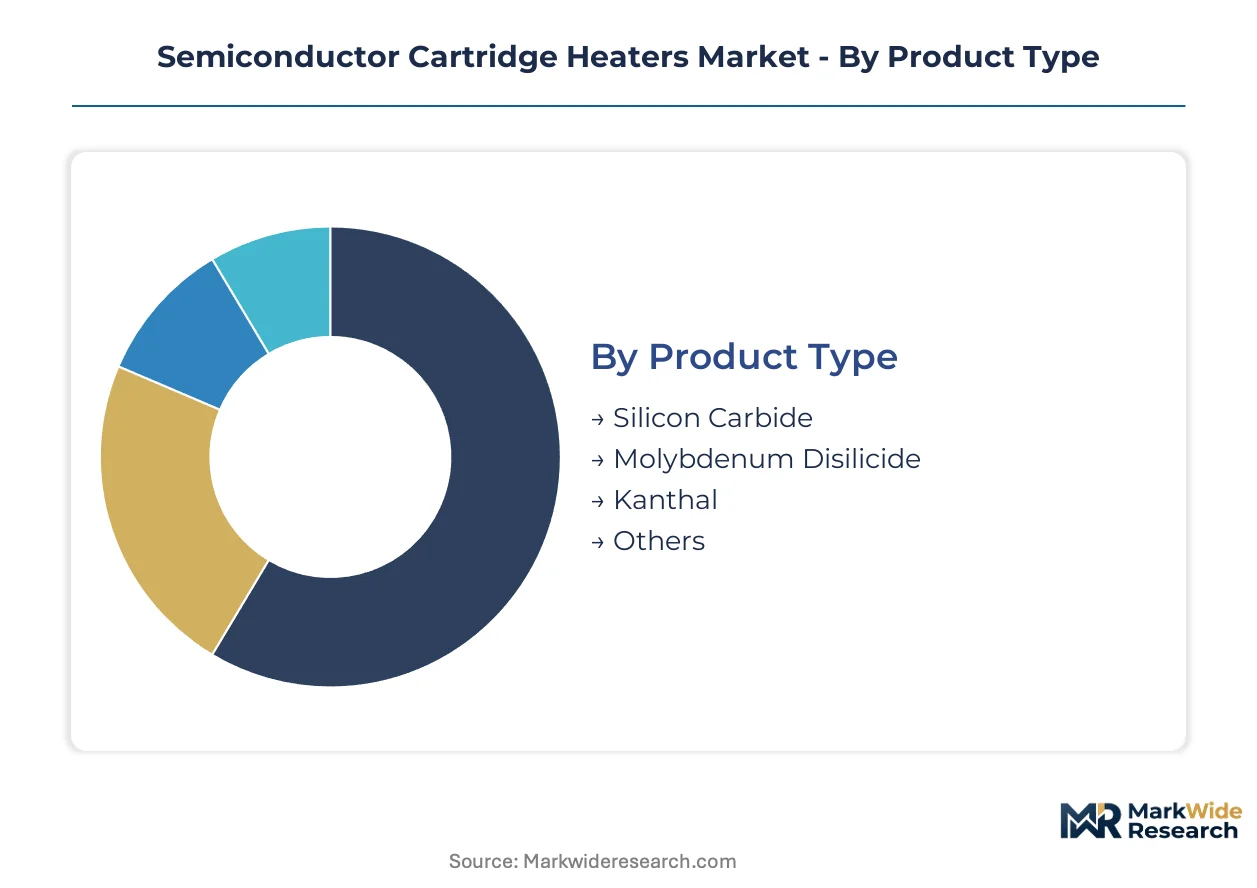
Segmentation in semiconductor cartridge heaters reveals how thermal engineering specifications fragment across process requirements. Equipment OEMs configure heater portfolios by material tolerance, power density, and integration architecture rather than treating cartridges as interchangeable commodities.
Product Type:
Customization intensity peaks at the material science layer, where sheath alloys and resistance elements determine temperature ceilings and chemical compatibility.
- Silicon Carbide:Ceramic composite construction withstands sustained operation above 1,400°C in epitaxy and diffusion furnaces. Power semiconductor foundries in Taiwan and Germany are expanding procurement for silicon carbide wafer processing as electric vehicle inverter demand accelerates.
- Molybdenum Disilicide:Refractory silicide heating elements deliver rapid thermal ramp rates in oxidation and annealing chambers. Leading-edge memory fabs in South Korea specify this chemistry for atomic layer deposition tool retrofits requiring sub-minute temperature transitions.
- Kanthal:Iron-chromium-aluminum alloys serve mature node maintenance and replacement cycles where cost sensitivity outweighs extreme temperature requirements.
- Others:Nickel-chromium and specialized superalloy variants occupy niche applications in hydrogen-rated process environments.
Leading the category by volume: Kanthal. Expanding most quickly: Silicon Carbide.
End User:
Application risk profiles separate customers by chamber classification tolerance and qualification burden.
- Electronics Manufacturing:Dominant demand pool spanning logic, memory, and analog foundries with Class 1 cleanroom protocols. Taiwanese equipment OEMs specify cartridge heaters for etch, deposition, and thermal processing tools across 300mm wafer lines.
- Automotive Components:Power module packaging and sensor fabrication pull medium-temperature cartridges into non-leading-edge semiconductor applications. German tier-one suppliers are qualifying domestic heater sources for silicon carbide device assembly lines.
- Aerospace:Radiation-hardened and high-reliability chip programs impose extended burn-in and qualification cycles on thermal component suppliers.
- Industrial Equipment:Process control and automation semiconductor applications tolerate broader thermal tolerances with compressed procurement lead times.
Highest qualification barriers: Electronics Manufacturing. Fastest volume acceleration: Automotive Components.
Power Rating:
Watt density configurations align with chamber zone count and thermal uniformity specifications.
- Ultra High Power:Concentrated heat output above 100 W/cm² serves single-zone rapid thermal processing and susceptor heating in compound semiconductor epitaxy. Arizona-based megafabs are specifying these cartridges for gallium nitride RF device fabrication.
- High Power:Distributed arrays in CVD and PVD chambers balance watt density against sheath longevity. Japanese equipment OEMs favor this rating for multi-zone ALD tools.
- Medium Power:Gas line heating and chamber wall temperature management dominate this segment with moderate thermal gradient requirements.
- Low Power:Precursor bottle warming and ancillary thermal control occupy this specification tier with minimal technical differentiation.
Widest deployment: High Power. Steepest specification climb: Ultra High Power.
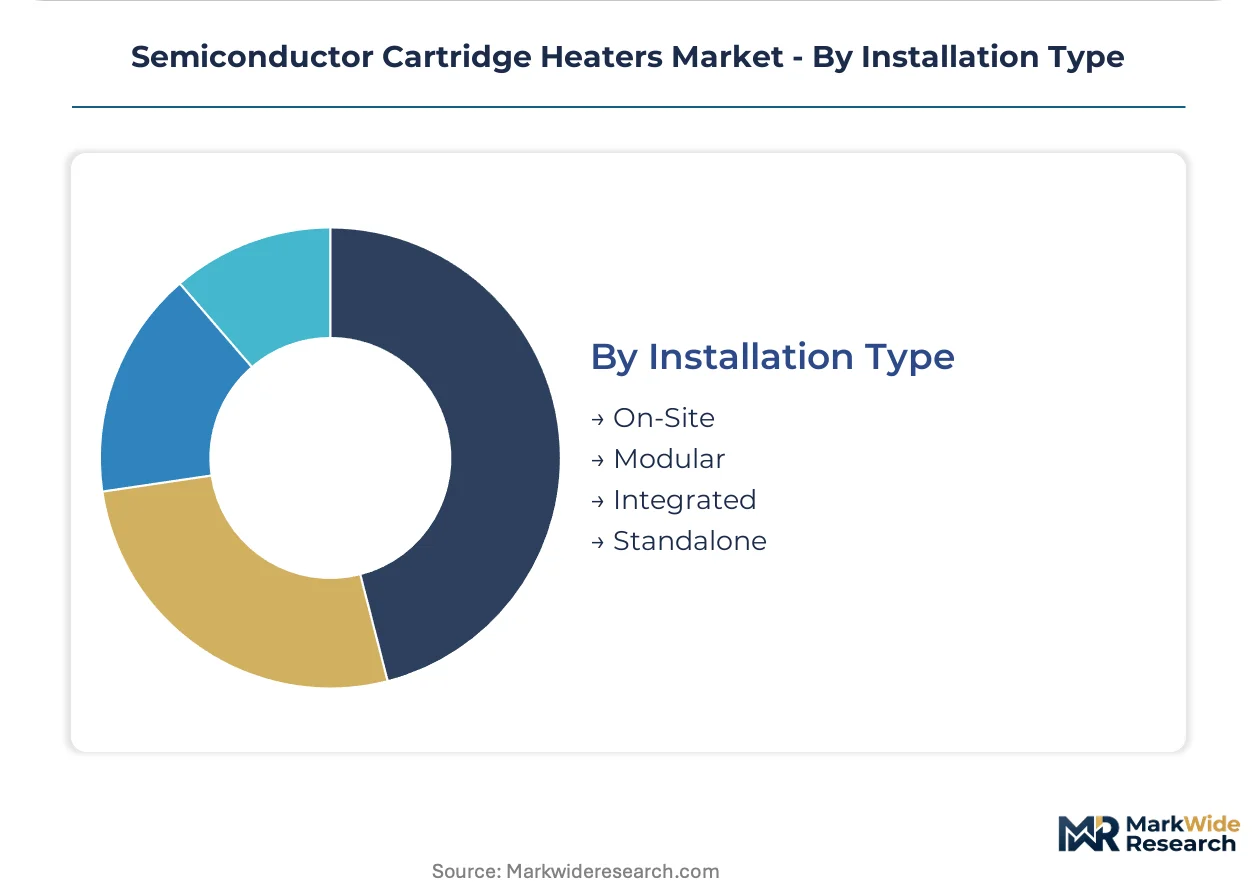
Installation Type:
Integration architecture determines field service protocols and supplier-OEM relationship depth.
- Integrated:Cartridges factory-installed within chamber assemblies require OEM-level qualification and captive supply relationships. Dutch lithography equipment suppliers mandate this architecture for thermal uniformity warranty coverage.
- Modular:Swappable heater subassemblies enable independent replacement without full chamber recalibration. Singapore maintenance contractors are building inventory positions around this configuration for mature node facilities.
- On-Site:Custom-fit installations accommodate legacy tool retrofits and non-standard chamber geometries with extended field engineering support.
- Standalone:Self-contained heating units for ancillary process equipment operate outside critical thermal uniformity specifications.
Deepest OEM integration: Integrated. Fastest channel shift: Modular.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Phoenix's CHIPS Act megafab zone concentrates capital deployment for precision thermal components. Dresden's subsidy corridor and Gujarat's PLI scheme are accelerating greenfield procurement channels. Hsinchu Science Park anchors East Asian foundry equipment demand.
United States
Intel and TSMC megafabs in Arizona drive cartridge heater procurement for 300mm wafer processing equipment. EPA emissions standards for perfluorinated compounds elevate thermal destruction efficiency specifications above 99%. Oregon semiconductor manufacturers face tightened abatement requirements that amplify high-temperature heater reliability demands.
Germany
Silicon carbide device fabrication for automotive inverters pulls ultra-high-temperature cartridge variants into 1,400°C process environments. ECHA candidate list expansions for nickel compounds force sheath material reformulations with unproven field longevity. Saxony's Dresden cluster hosts Bosch and GlobalFoundries expansion with specialized thermal component qualification timelines.
Taiwan
TSMC's advanced node migration below 7nm multiplies discrete heating zones per process chamber from dozens to hundreds. METI-equivalent industrial standards govern precision thermal component integration in foundry equipment. Hsinchu Science Park equipment OEMs pilot addressable heater arrays adjusting watt density in real-time based on chamber gas flow patterns.
South Korea
Samsung and SK Hynix memory fabs specify molybdenum disilicide chemistry for atomic layer deposition tool retrofits requiring sub-minute temperature transitions. MFDS workplace exposure limits constrain nickel-chromium alloy handling protocols in cleanroom environments. Pyeongtaek semiconductor complex drives zone-level cartridge control adoption for thermal gradient compression from ±5°C to ±1.5°C.
India
Gujarat and Tamil Nadu fab incentives under the PLI scheme create greenfield procurement channels without incumbent supplier lock-in. BIS certification requirements for industrial heating equipment extend qualification timelines for imported thermal components. Dholera Special Investment Region and Chennai's electronics manufacturing clusters attract first-mover heater suppliers seeking OEM integration slots.
Semiconductor Cartridge Heaters Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with captive OEM relationships dominating integrated architectures and third-party channels capturing modular replacement demand. The vendor base concentrates around three strategic archetypes: application-engineered specialists with foundry equipment integration depth, high-purity material science leaders serving cleanroom protocols, and scale-driven fabricators optimizing cost-sensitive maintenance cycles. M&A activity targets predictive maintenance technology assets, while capacity expansion concentrates in CHIPS Act beneficiary zones and Indian PLI corridors.
Among North American application-engineered specialists, Watlow anchors the premium-tier vector through OEM captive supply relationships. Chromalox exemplifies the high-purity material science archetype with R&D intensity in sheath formulations for Class 1 environments. Tempco Electric Heater Corporation occupies a position within the specialized geometry segment for etch and deposition tool configurations. These three represent distinct competitive positioning vectors rather than interchangeable commodity supply.
| Leading Market Players |
|---|
| Watlow |
| Chromalox |
| Tempco Electric Heater Corporation |
| Zoppas Industries |
| NIBE Industrier AB |
| Backer Group |
| Hotset |
| Sino-Japan Electric Heater |
| Headway Electric Heat Components |
| Others |
Pricing and Supply Chain Analysis
EPA emissions standards for perfluorinated compounds gate qualified supply access and premium-tier pricing power, as semiconductor manufacturers in Oregon and Arizona must demonstrate thermal destruction efficiency above 99% for effluent streams. Only suppliers with certified high-temperature heater reliability and redundant heating configurations can command pricing premiums, while uncertified competitors face exclusion from foundry equipment integration slots.
Pricing Analysis
Short lead-time premiums dominate transactional pricing, with Arizona megafabs paying markups for expedited delivery of application-engineered cartridge configurations while spot inventory of Kanthal-based maintenance cartridges trades at discounts. Three-tier pricing structure across premium, standard, and economy levels separates silicon carbide epitaxy variants from high-power CVD arrays and mature-node replacement units. Price differentiation hinges on cleanroom certification grade and OEM captive supply status. Cost compression in the Kanthal tier is intensifying because independent maintenance contractors in Singapore and Dresden are qualifying third-party sources for non-warranty tool support. Mature node facilities exhibit highest price sensitivity; leading-edge memory fabs show least sensitivity due to thermal uniformity warranty requirements.
Supply Chain Analysis
Refurbishment flows from mature-node decommissioning in Japan and South Korea feed secondary channels for Kanthal cartridge recovery, reducing raw material draw for cost-sensitive replacement segments. Manufacturing concentration clusters in Germany, Japan, and the United States, with specialty wire production for nickel-chromium resistance elements anchored in German and Japanese facilities. Raw material dependencies span high-purity magnesium oxide insulation, nickel-chromium alloy wire, and ceramic sheath composites. Single-source vulnerability for specialty wire creates structural risk exposure. Distribution runs through OEM captive channels for integrated architectures and independent maintenance contractors for modular replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
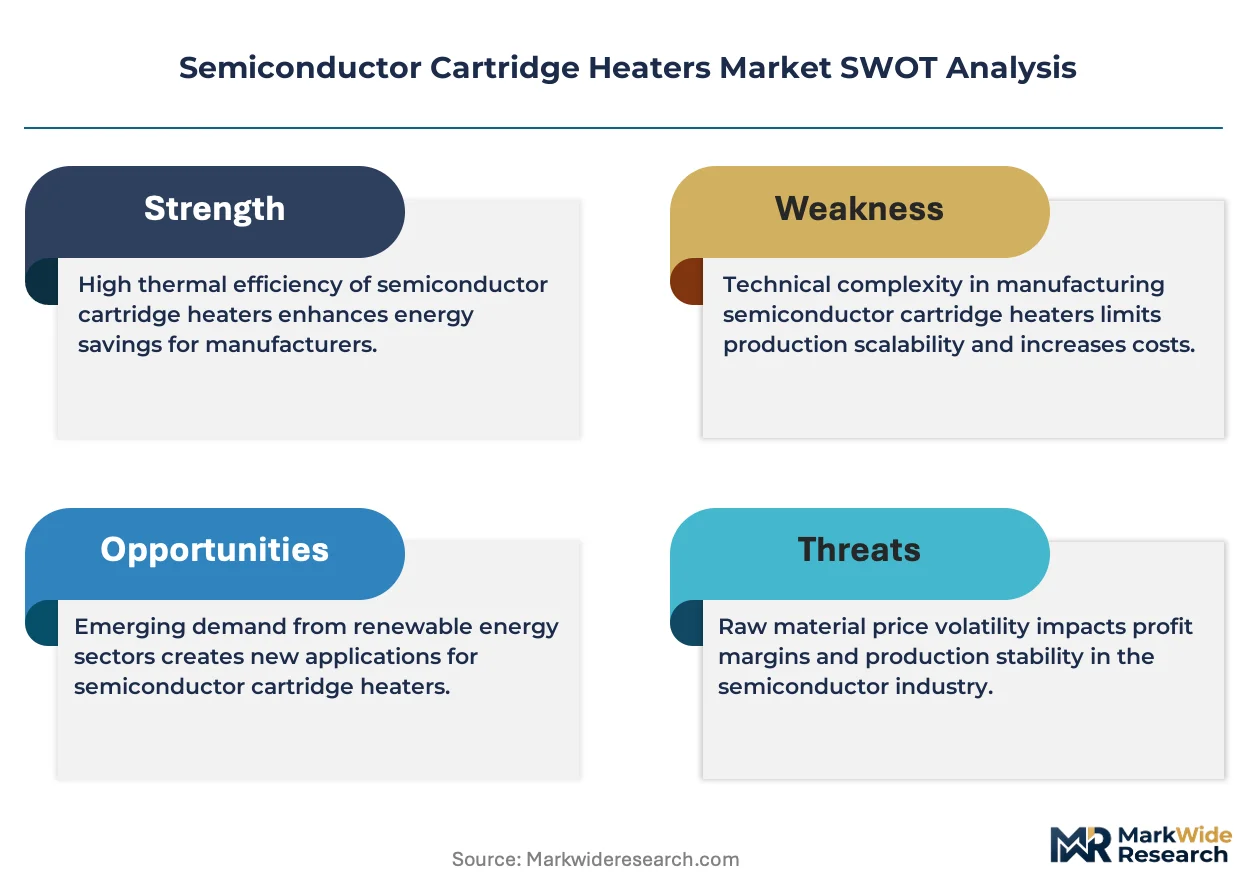
REACH substance restrictions for nickel compounds create a compliance moat that elevates qualification costs and consolidates share among sheath material science leaders with proven field longevity. This cost-of-compliance story favors incumbents with established ECHA regulatory affairs capabilities.
For Market Incumbents: Anchor market position through backward integration into high-purity magnesium oxide supply and capacity expansion in CHIPS Act beneficiary zones. Induction heating substitution in annealing applications above 800°C threatens cartridge maintenance cycle economics; defend by embedding predictive maintenance sensors that enable condition-based replacement contracts with OEM service divisions.
For New Entrants and Emerging Players: Begin with Gujarat and Tamil Nadu fab incentives under India's PLI scheme, where greenfield procurement channels lack incumbent supplier lock-in. Target modular installation configurations for mature node facilities in Singapore and Dresden, where independent maintenance contractors are unbundling traditional OEM captive relationships. Pursue qualification partnerships with European automotive tier-one suppliers for silicon carbide device assembly lines.
For Investors and Strategic Acquirers: TSMC's advanced node migration below 7nm is the leading indicator that zone-level cartridge control adoption is accelerating thermal gradient compression requirements. Long-term viability rests on predictive maintenance technology assets and hydrogen-rated sheath alloy capabilities. Target acquisition candidates with embedded sensor integration and reducing atmosphere annealing expertise. Monitor CHIPS Act capital deployment timelines for early signals of domestic supplier qualification acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen-Rated Sheath Development | Enables reducing atmosphere annealing for advanced memory nodes with premium positioning potential. |
| Predictive Maintenance Sensor Integration | Creates condition-based replacement contracts with OEM service divisions like Watlow and Chromalox. |
| India PLI Corridor Capacity Buildout | Captures greenfield procurement channels in Gujarat and Tamil Nadu without incumbent lock-in. |
| High-Purity Material Science R&D | Satisfies ECHA REACH compliance for nickel compound restrictions in German automotive supply chains. |
| Zone-Level Control Architecture Partnership | Aligns with TSMC and Samsung real-time watt density adjustment pilots in Hsinchu and Pyeongtaek. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, while primary interviews with foundry equipment OEM procurement directors, thermal component R&D leads, cleanroom maintenance contractors, and semiconductor fab engineering heads provided operational validation. SEC 10-K disclosures from equipment manufacturers, EPA emissions compliance databases, ECHA REACH candidate list updates, and BIS certification registries supplied quantitative foundations. Bottom-up unit economics from cartridge specifications and top-down capital expenditure patterns from CHIPS Act and EU subsidy programs were reconciled through iterative triangulation.
Data-stream reconciliation across shipment volumes, qualification timelines, and replacement cycle frequencies informed the analytical framework over the projection horizon. Segmentation dimensions modeled include sheath material chemistry, power density rating, installation architecture, end-use application risk profile, and regional regulatory cluster. CAGRs were derived from equipment capital expenditure trajectories and heating zone multiplication factors in advanced node migration. Forecast inputs incorporated silicon carbide epitaxy expansion rates for electric vehicle inverters and zone-level control adoption curves in Taiwanese and South Korean foundries.
Underlying measurement precision varies by segment; silicon carbide and molybdenum disilicide product categories carry tighter precision than Kanthal maintenance replacement estimates due to concentrated supplier disclosure. Forecasts reflect assumptions about subsidy program continuity, REACH substance restriction implementation timelines, and induction heating substitution rates. Practitioners should monitor EPA perfluorinated compound enforcement actions, ECHA nickel compound list expansions, and India PLI scheme disbursement schedules for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
TIG Torch Market
Industrial Equipment
Chemical Storage Tank and Bottle for Semiconductor Market
Industrial Equipment
Europe Fusion Splicer Market
Industrial Equipment
Vibration Isolation Tables Market
Industrial Equipment
Dust Extraction System Market
Industrial Equipment
Global Industrial Dispensing System and Equipment Market
Industrial Equipment
UV Conveyor Systems Market
Industrial Equipment
Magnetizing Equipment Market
Industrial Equipment
Global DC Drives Market
Industrial Equipment
Magnetorheological Finishing (MRF) Machine Market
Industrial Equipment
High-Speed Electric Spindle Market
Industrial Equipment
Global Linear Bearings Market
Industrial Equipment
United States Ball Bearing Market
Industrial Equipment
Rotary Scroll Air Compressor Market
Industrial Equipment
Linear Shaft Motor Market
Industrial Equipment
Refrigeration Coolers Market