
 Global Broadcast Cameras Market | 2026-2036
Global Broadcast Cameras Market Size, Share, and Industry Trends Forecast 2026-2036
Global Broadcast Cameras Market Analysis
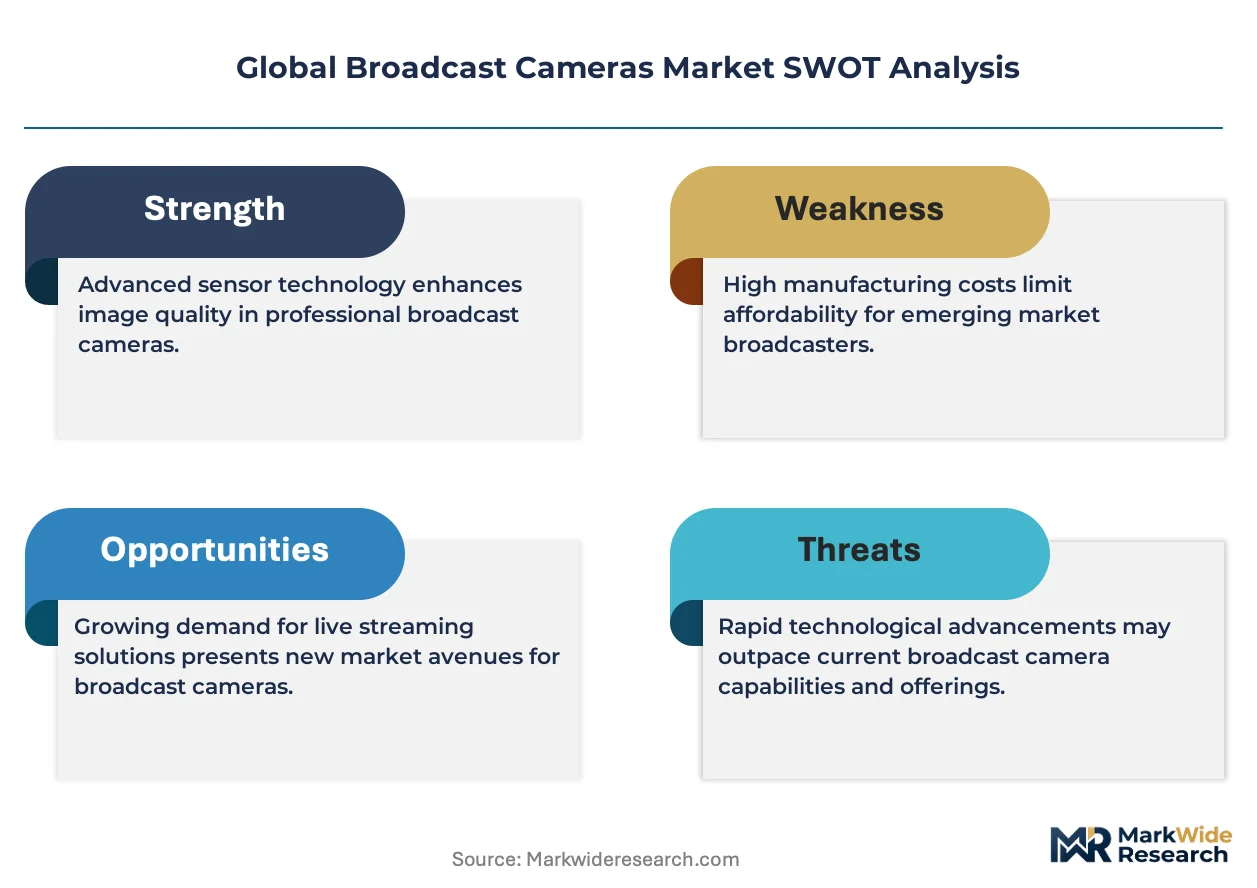
Multi-source component procurement is rebalancing toward vertically integrated supply chains among broadcast camera manufacturers. Sony Corporation leverages in-house image sensor fabrication to control cost and performance trajectories. ARRI AG anchors its position through precision mechanical engineering and color science specialization. Blackmagic Design Pty Ltd competes aggressively on price-performance ratios in the prosumer-to-professional crossover tier.
Broadcast cameras are professional video acquisition systems engineered around large-format image sensors, broadcast-grade lens mounts, and real-time signal processing chains delivering uncompressed or lightly compressed output for live transmission and recorded production. These systems typically integrate 2/3-inch or larger sensors with 14+ stops of dynamic range and genlock synchronization for multi-camera environments. PTZ cameras and IP-based technology segments attract disproportionate investment as remote production workflows reduce on-site crew requirements. Mirrorless cameras gain share in cinematography applications where shallow depth-of-field aesthetics and compact form factors displace traditional cinema camera configurations. Fixed installation and studio-based setups retain stable replacement cycles while mobile and outdoor configurations expand with event-driven content demand.
FCC spectrum management in the United States, ETSI standards through CE marking in Europe, and MIIT equipment certification in China each shape product compliance requirements and market access conditions for manufacturers. ISO 9001 quality frameworks and SMPTE technical standards further define interoperability benchmarks that influence purchasing decisions among broadcast network engineers. Stakeholders must monitor IP protocol standardization battles between proprietary and open-standards camps as this technical choice locks in infrastructure investments for decade-long depreciation cycles.
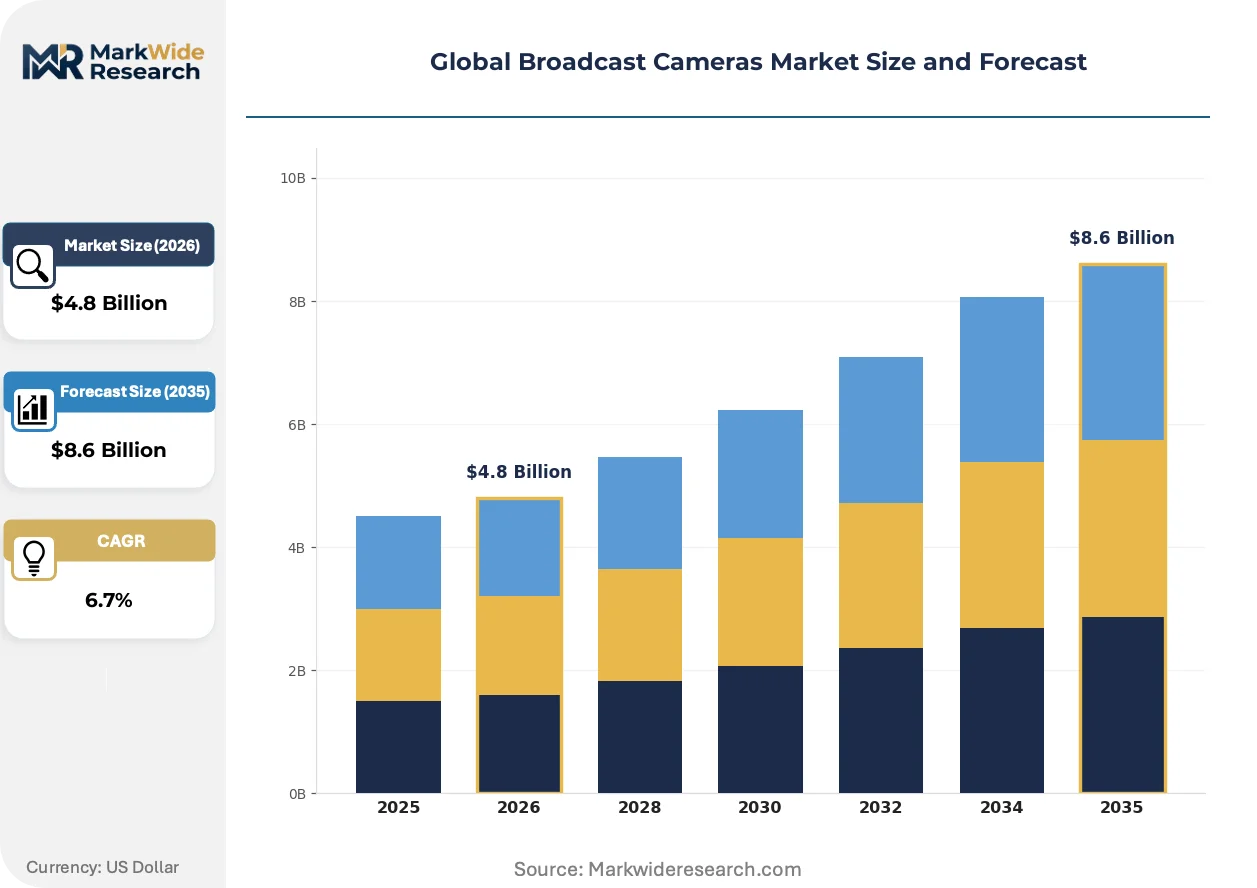
Market Dynamics
IP-based SMPTE ST 2110 workflows are compressing capital deployment timelines and forcing infrastructure reinvestment across broadcast networks, while live sports production volumes sustain replacement cycles despite broader media budget pressures.
Growth Catalysts
- Live Sports Production:Multi-camera event coverage demands synchronized acquisition systems with genlock capability, driving studio and venue installations in the United States, China, and Germany.
- ETSI CE Marking Pathways:European standardization reduces certification friction for IP-enabled broadcast equipment, accelerating product launches across EU member states.
- PTZ Camera Adoption:Remote production workflows reduce on-site crew requirements, with broadcasters deploying pan-tilt-zoom systems for cost-efficient multi-angle coverage.
Market Restraints
- Image Sensor Supply Concentration:Advanced CMOS fabrication capacity clusters in East Asian foundries, creating single-source vulnerability for large-format sensor procurement.
- FCC Spectrum Repacking:Wireless microphone and camera link frequency reallocations force equipment obsolescence and unplanned replacement spending.
- Mirrorless Substitution:Compact full-frame cinematography cameras displace traditional broadcast configurations in scripted content production, compressing addressable volume for dedicated broadcast systems.
Strategic Opportunities
- India Content Production:Streaming platform investment in regional language programming creates demand for broadcast-grade acquisition systems outside traditional Western hubs.
- Cloud-Native Production:Remote editing and distributed workflows enable camera-to-cloud architectures, reducing physical infrastructure requirements for emerging broadcasters.
- EU Green Deal Procurement Mandates:Energy efficiency criteria in public sector purchasing favor next-generation camera systems with reduced power consumption profiles.
Industry Challenges
- SMPTE 2110 Integration Complexity:Legacy SDI infrastructure and IP-based signal chains require hybrid workflow engineering expertise scarce among broadcast technical staff.
- MIIT Certification Timelines:Chinese equipment approval processes extend product launch windows, delaying revenue recognition for manufacturers targeting domestic broadcasters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Broadcast Cameras Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PTZ Cameras, Action Cameras, DSLR Cameras, Mirrorless Cameras Technology: 4K, 8K, HD, IP-Based End User: Broadcast Media, Sports Organizations, Cinematography, Education Institutions Installation Type: Fixed Installation, Mobile Setup, Studio-Based, Outdoor Setup |
| Companies Covered | Sony Corporation, Canon Inc., Panasonic Corporation, ARRI AG, Blackmagic Design Pty Ltd, JVCKENWOOD Corporation, Grass Valley, RED Digital Cinema, Ikegami Tsushinki Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Broadcast Cameras Market Emerging Trajectories
Three distinct vectors are compressing product lifecycles and redistributing value capture across the broadcast camera value chain: signal processing architecture, regulatory compliance frameworks, and procurement model evolution.
Large-format global shutter sensors are rewriting performance benchmarks for motion acquisition in live environments. Sports broadcasters in North America and Western Europe are adopting these sensors to eliminate rolling shutter artifacts during high-speed action capture. The technology is rewriting competitive positioning between established cinema camera suppliers and traditional broadcast equipment manufacturers as image quality thresholds converge.
GDPR-mandated data handling protocols are reshaping cloud-connected camera deployments across European production facilities. The regulation requires encrypted metadata transmission and localized storage architectures, increasing system integration complexity. Documentary and reality production segments are most affected, with producers retrofitting acquisition workflows to satisfy data protection audit requirements.
Subscription-based hardware access is disrupting capital-intensive procurement patterns among mid-tier content studios. Rental and managed service models are replacing outright purchase for 4K and 8K camera systems, particularly in episodic television production. This shift is most visible in the United Kingdom and Nordic markets, where production financing structures favor operational expenditure classification over depreciable assets.
Global Broadcast Cameras Market Segmentation
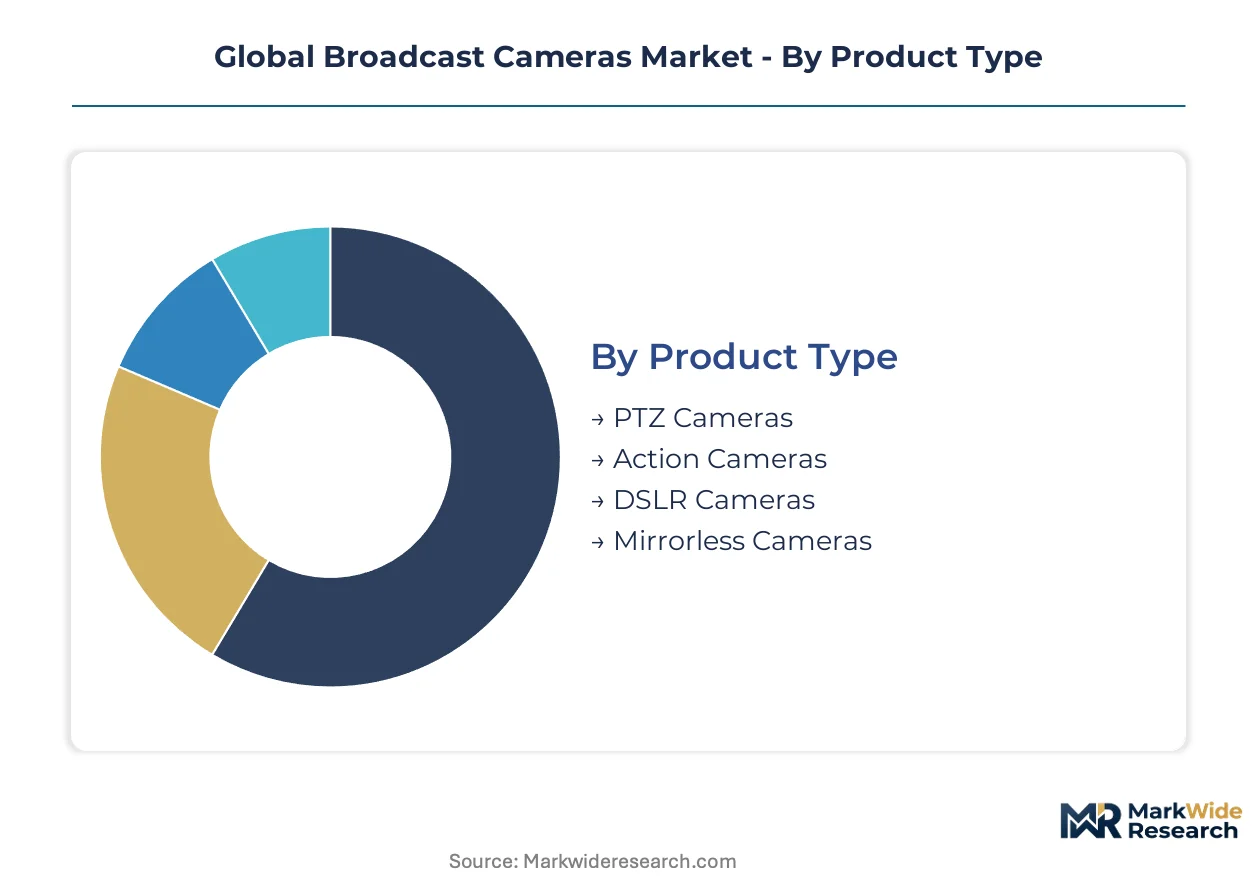
Broadcast camera procurement patterns diverge sharply across technical specifications, deployment contexts, and buyer sophistication levels. Understanding these fault lines reveals where infrastructure investment concentrates and where replacement cycles accelerate.
Product Type:
Sensor format and optical architecture distinguish professional acquisition tiers from crossover equipment.
- PTZ Cameras:Remote-controllable pan-tilt-zoom systems integrate broadcast-grade genlock synchronization with robotic positioning for unmanned venue coverage. Demand clusters in sports organizations across Germany and the United States as venue operators reduce on-site crew density for multi-angle live production.
- Mirrorless Cameras:Compact full-frame systems with shallow depth-of-field optics and high-ISO performance displace traditional cinema configurations in scripted content workflows. Cinematography applications in China and the United Kingdom drive volume as production houses prioritize mobility and lens interchangeability.
- DSLR Cameras:Optical viewfinder systems retain niche deployment in documentary and news gathering where battery endurance and mechanical reliability outweigh electronic feature sets.
- Action Cameras:Ruggedized miniature acquisition units with extreme environmental sealing serve specialized POV and stunt capture requirements in sports and reality production.
Mature deployment sits with DSLR Cameras. Newer deployment is concentrated in Mirrorless Cameras.
Technology:
Resolution and signal transport protocols determine infrastructure compatibility and depreciation timelines.
- IP-Based:SMPTE ST 2110 uncompressed IP workflows enable flexible routing and distributed production architectures. Broadcast media networks in the United States and Germany lead migration as legacy SDI infrastructure reaches end-of-life, though hybrid engineering expertise remains scarce.
- 4K:Ultra-high-definition acquisition at 3840×2160 resolution has become baseline for premium content production. Sports organizations across China and the United Kingdom drive replacement cycles as transmission standards mandate higher spatial resolution.
- 8K:7680×4320 resolution systems serve experimental and archival capture where future-proofing justifies premium hardware expenditure. NHK broadcasting trials in Japan and select Olympic production deployments anchor current volume.
- HD:1920×1080 resolution systems persist in regional broadcast, corporate communication, and education institutions where bandwidth constraints and budget limitations delay upgrade cycles.
Volume leadership rests with 4K. Steepest expansion trajectory belongs to IP-Based.
End User:
Content monetization models and production scale dictate equipment specification thresholds.
- Broadcast Media:National and regional television networks operate multi-camera studios and live transmission chains requiring genlock synchronization and redundant signal paths. FCC spectrum management and ETSI CE marking compliance shape procurement specifications in the United States and European Union respectively.
- Sports Organizations:League operators and venue owners deploy camera systems for live event coverage and instant replay infrastructure. Stadium installations in Germany, China, and the United States concentrate demand for weather-sealed, high-frame-rate acquisition.
- Cinematography:Feature film and episodic television production prioritizes dynamic range, color science, and shallow depth-of-field aesthetics over live transmission capability.
- Education Institutions:Universities and technical colleges equip broadcast journalism and media production programs with cost-optimized systems that balance pedagogical feature sets against capital constraints.
Equipment refresh cycles are longest in Education Institutions. Compressed replacement timelines characterize Broadcast Media.
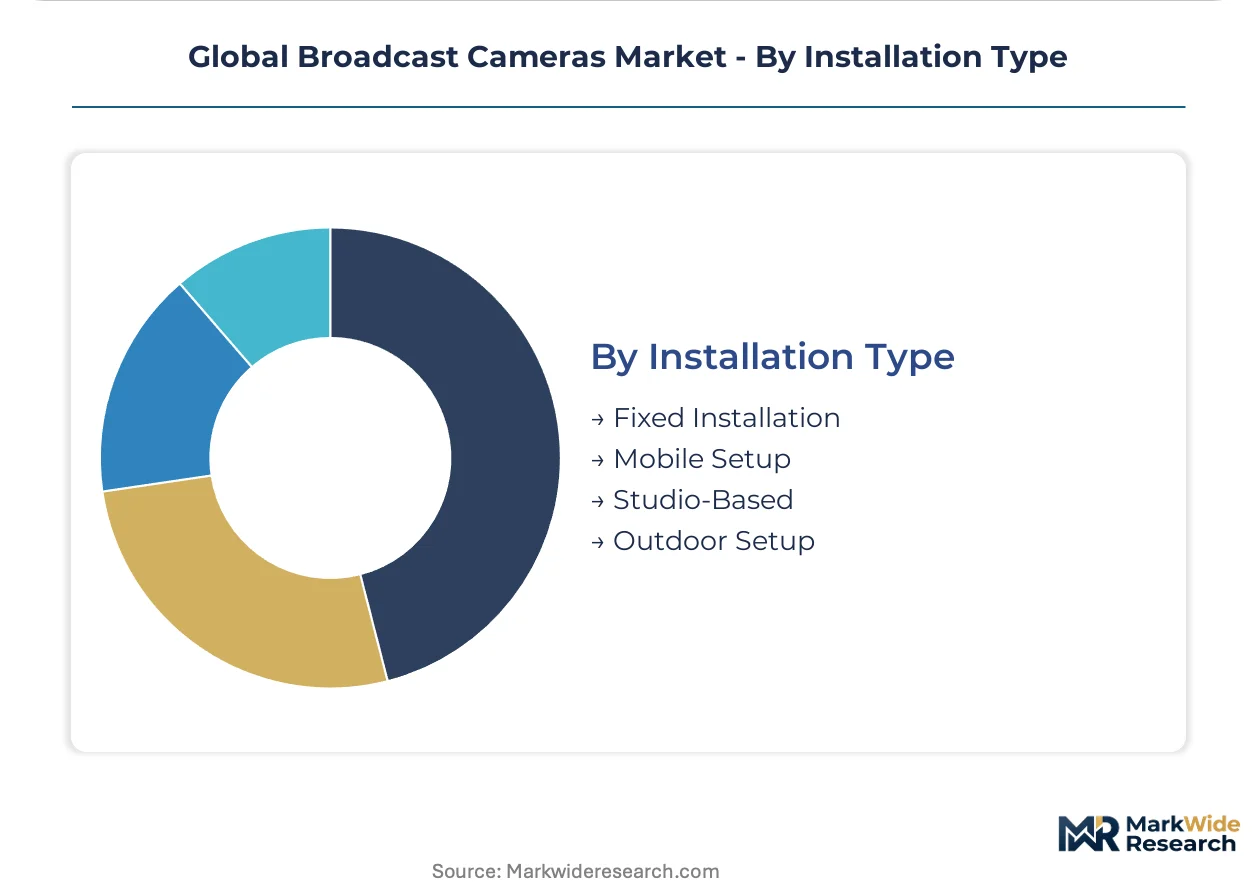
Installation Type:
Physical deployment context determines environmental hardening, connectivity architecture, and mobility requirements.
- Studio-Based:Climate-controlled permanent installations integrate with lighting grids, cable infrastructure, and control rooms. Broadcast media facilities in the United States, Germany, and China anchor replacement demand as IP workflow migration forces infrastructure reinvestment.
- Mobile Setup:Vehicle-mounted or flypack configurations enable rapid deployment for live event coverage. Sports organizations across the United Kingdom and Germany favor these systems for touring productions and temporary venue installations.
- Fixed Installation:Permanent venue deployments in arenas, houses of worship, and corporate auditoriums prioritize reliability and remote operability over transportability.
- Outdoor Setup:Weather-hardened configurations with extended temperature tolerances and moisture sealing serve open-air sports, news gathering, and natural history production.
Capital intensity peaks with Studio-Based. Operational expenditure classification favors Mobile Setup.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon wafer fabrication clusters in Japan and South Korea anchor image sensor supply chains for broadcast camera manufacturers worldwide. Content production hubs in the United States, Germany, and China concentrate equipment procurement. Regulatory divergence across FCC, ETSI, and MIIT jurisdictions fragments certification pathways.
United States
National sports leagues and broadcast networks drive multi-camera studio installations with genlock synchronization requirements. FCC spectrum repacking mandates force wireless equipment replacement cycles. Los Angeles and New York production clusters anchor demand for IP-based SMPTE ST 2110 workflow migration.
Germany
Regional public broadcasters and commercial sports networks sustain venue camera deployments across Bundesliga stadiums. ETSI CE marking pathways accelerate IP-enabled equipment launches. Munich and Cologne production hubs concentrate technical engineering talent for hybrid SDI-IP infrastructure integration.
China
State media expansion and streaming platform investment in regional language programming compress replacement timelines. MIIT equipment certification extends product launch windows for foreign manufacturers. Beijing and Shanghai broadcast clusters lead 4K and 8K transmission standard adoption.
Japan
Broadcast technology export orientation and NHK 8K trial deployments sustain premium equipment development. METI industrial policy supports domestic image sensor fabrication capacity. Tokyo and Osaka electronics clusters integrate broadcast camera design with semiconductor foundry partnerships.
United Kingdom
Subscription streaming production and episodic television financing favor operational expenditure classification for camera access. GDPR-mandated data handling protocols reshape cloud-connected deployment architectures. London post-production facilities anchor remote editing workflow integration with distributed acquisition systems.
Global Broadcast Cameras Market Vendor Landscape
Global majors compete with regional champions across image sensor fabrication and precision mechanical engineering dimensions. Market structure consolidates around vertically integrated sensor manufacturers and specialized optical engineering houses. Three archetypes dominate: in-house semiconductor fabricators, precision mechanics specialists, and price-performance disruptors. Competitive moves concentrate on backward integration into sensor supply and portfolio diversification across resolution tiers.
Within the in-house fabrication tier, Sony Corporation exemplifies captive image sensor production. ARRI AG anchors precision mechanical engineering specialization. Blackmagic Design Pty Ltd occupies the aggressive price-performance position in prosumer-to-professional crossover segments.
| Leading Market Players |
|---|
| Sony Corporation |
| Canon Inc. |
| Panasonic Corporation |
| ARRI AG |
| Blackmagic Design Pty Ltd |
| JVCKENWOOD Corporation |
| Grass Valley |
| RED Digital Cinema |
| Ikegami Tsushinki Co. Ltd |
| Others |
Supply Flow & Price Mechanics
Family-owned precision mechanics specialists in Germany and Japan anchor premium-tier pricing discipline through captive optical engineering and multi-decade service relationships. Their ownership structures resist quarterly margin pressure, sustaining investment in long-horizon R&D while pricing subscription-bundled hardware access to capture recurring revenue from streaming-era broadcasters.
Pricing Analysis
Extended warranty and field-service bundling separates premium-tier manufacturers from unbundled equipment vendors competing on capital-expenditure minimization. Three-tier pricing structure across premium, standard, and economy levels reflects sensor format differentiation, with genlock-enabled large-format systems commanding brand premiums against prosumer crossover alternatives. Cost compression in the mid-tier intensifies because Blackmagic Design and similar disruptors force price-performance recalibration. Education institutions exhibit highest price sensitivity, while national broadcast networks prioritize total-cost-of-ownership metrics over unit acquisition cost.
Supply Chain Analysis
Refurbishment and remanufacturing flows for broadcast lenses and camera bodies concentrate in Japan and Germany, extending asset lifecycles for rental houses and public broadcasters. Image sensor fabrication draws from Taiwan, South Korea, and Japan, with advanced CMOS processes tethered to East Asian foundry capacity. Single-source vulnerability in large-format sensor procurement threatens equipment availability during foundry allocation shifts. Distribution runs through authorized dealer networks and direct-to-broadcaster contracts, with rental-managed service models gaining share in episodic production.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Broadcast camera procurement sits in a technology-transition phase as SMPTE ST 2110 IP workflows displace legacy SDI infrastructure, forcing decade-long depreciation cycles to compress and hybrid engineering capability to become the scarce competitive resource.
For Market Incumbents: Lock in hybrid workflow engineering talent through targeted acquisition of IP integration specialists and structured training partnerships with SMPTE standards bodies. Deepen backward integration into image sensor supply through foundry partnerships in Japan and South Korea to mitigate single-source concentration risk. Defensive consolidation around color science IP and precision mechanics manufacturing protects margin position against prosumer crossover entrants. For New Entrants and Emerging Players: Begin with cloud-native camera-to-cloud architectures serving mid-tier content studios in India and Southeast Asia where legacy infrastructure constraints are weakest. Regional language streaming production represents the most penetrable segment, with procurement officers prioritizing operational-expenditure classification over capital-intensive equipment ownership. Go-to-market execution should emphasize subscription-based hardware access and remote technical support to reduce customer switching costs. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision mechanics specialists with established ETSI CE marking pathways and existing relationships with European public broadcasters. Long-term viability over a five-to-ten year window rests on hybrid SDI-IP engineering capability and sensor supply security rather than pure-play IP-native positioning. Monitor FCC spectrum repacking announcements and MIIT certification timeline shifts as early signals of equipment replacement cycle acceleration or delay.| Strategic Initiative | Industry Significance |
|---|---|
| IP Workflow Migration | SMPTE ST 2110 adoption forces infrastructure reinvestment across United States and German broadcast networks. |
| Sensor Supply Securement | Foundry partnerships in Japan and South Korea reduce single-source vulnerability for large-format CMOS procurement. |
| Subscription Service Launch | Hardware-as-a-service models capture recurring revenue from United Kingdom streaming production financing structures. |
| Regional Certification Investment | MIIT approval acceleration unlocks revenue recognition from Chinese state media expansion programs. |
| Hybrid Engineering Talent Acquisition | SDI-IP integration expertise scarcity creates competitive moat for broadcast equipment vendors. |
Methodological Framework
Document review covered regulatory filings with FCC, ETSI, and MIIT, complemented by interviews with broadcast network engineering directors, rental house operations managers, and post-production facility technical leads. Secondary validation drew from SMPTE technical standards documentation, hyperscaler content production capex disclosures, and customs trade data for broadcast equipment imports. Bottom-up equipment shipment analysis triangulated against top-down content production spend estimates across the analysis window.
Cross-referencing historical replacement cycle patterns with panel input from broadcast procurement officers shaped the analytical framework. Segmentation dimensions modeled include product type, resolution tier, signal transport protocol, end-user category, and installation context. CAGRs were derived through regression analysis of equipment shipment trajectories and content production investment correlations, with particular weighting applied to live sports production volume trends and IP infrastructure deployment timelines.
Underlying measurement precision varies by segment; PTZ camera and IP-based technology categories carry tighter precision than emerging 8K experimental deployments. Forecasts reflect assumptions about streaming platform investment continuity, regulatory certification timeline stability, and semiconductor foundry allocation patterns. Practitioners should monitor FCC spectrum auction outcomes, ETSI standards revision schedules, and MIIT equipment approval queue lengths for early signals of forecast revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Middle East and Africa Image Sensors Market
Imaging
Computational Photography Market
Imaging
Pan-Tilt-Zoom (PTZ) Camera Market
Imaging
Digital Camera Market
Imaging
In Vivo Imaging Systems Market
Imaging
Hyperspectral Imaging Camera Market
Imaging
Embedded Smart Cameras Market
Imaging
Digital Movie Cameras Market
Imaging
Global Automotive Imaging Market
Imaging
Image Intensifier Market
Imaging
3D Time-Of-Flight Image Sensor Market
Imaging
Global 4K Camera Market
Imaging
Concrete Rebar Corrosion and Delamination Imaging Systems Market
Imaging
Machine Vision Market
Imaging
Handheld Retinal Scanners Market
Imaging
Global AI in Computer Vision Market