
 Microscope Digital Cameras Market | 2026-2036
Microscope Digital Cameras Market Size, Share, and Industry Trends Forecast 2026-2036
Microscope Digital Cameras Market Outlook
MDR compliance in Europe is broadening the cost-of-entry calculus for clinical-grade microscope digital cameras, forcing manufacturers to validate software pipelines and optical subsystems under stricter traceability protocols. Carl Zeiss AG leverages its Jena-based vertical manufacturing footprint to sustain end-to-end quality certification across CMOS and CCD product lines. Danaher Corporation anchors its position through the Leica Microsystems subsidiary, which dominates premium pathology imaging workflows in North American hospital networks. Nikon Corporation differentiates through proprietary image-processing algorithms that compete directly with Hamamatsu Photonics K.K. in high-speed fluorescence applications.
Microscope digital cameras are electro-optical devices that convert photonic signals from microscope objectives into digital image files, typically employing sensors with pixel pitches below 3.5 micrometers and quantum efficiency ratings exceeding 80% in the visible spectrum for scientific-grade units; their primary purpose is to enable quantitative documentation, computational analysis, and remote collaboration in research and diagnostic settings. CMOS sensors now lead unit shipments due to lower per-pixel manufacturing costs and faster readout speeds, while CCD architectures retain margin concentration in low-light scientific applications where read noise specifications remain critical. Real-time imaging technology is expanding fastest in surgical pathology workflows, whereas 3D imaging commands premium positioning in material science defect analysis.
FDA 21 CFR Part 11, EU MDR, and ISO 13485 collectively shape product standards by mandating electronic record integrity, biocompatibility documentation, and quality management system certification for devices entering clinical environments. These frameworks create asymmetric compliance burdens that favor established manufacturers with dedicated regulatory affairs teams over emerging entrants. Stakeholders must monitor evolving cybersecurity requirements for wireless-connected camera systems as healthcare networks harden attack surfaces against ransomware threats to diagnostic infrastructure.
Market Dynamics
Live-cell imaging workflows in academic and clinical settings are forcing sensor manufacturers to reconcile quantum efficiency demands with real-time data throughput requirements, reshaping R&D allocation across CMOS and CCD architectures.
Growth Catalysts
- EU MDR traceability mandates:Clinical diagnostic laboratories across Germany, France, and Italy now require end-to-end optical subsystem validation, expanding replacement cycles for certified camera systems.
- Fluorescence microscopy throughput:High-speed sCMOS sensors enable multi-position time-lapse experiments that legacy CCD arrays cannot execute, pulling demand from neuroscience and developmental biology departments.
- Jena-Oberkochen manufacturing cluster:Concentrated optical engineering talent and captive glass-to-sensor supply chains reduce procurement lead times for European research institutions.
Market Restraints
- Specialized sensor wafer costs:Scientific-grade back-illuminated CMOS fabrication relies on 300mm silicon substrates with defect densities below 0.1 per cm², concentrating supply risk with Taiwanese foundries.
- FDA 21 CFR Part 11 validation overhead:Clinical camera deployments require documented software lifecycle management that extends sales cycles by 8-14 months versus research-grade equivalents.
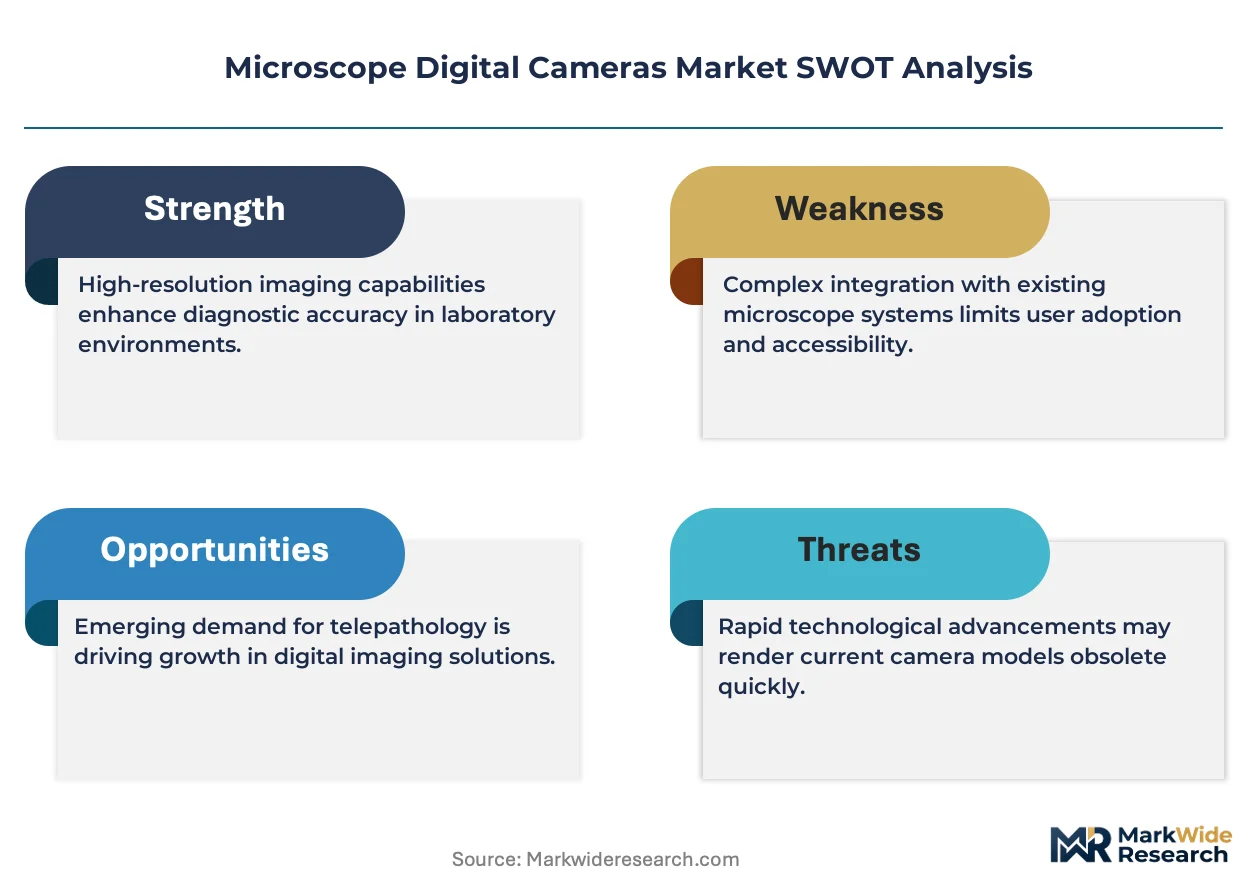
- Computational imaging substitution:AI-enhanced image reconstruction from smartphone-grade sensors threatens entry-level scientific camera segments in educational microscopy.
Strategic Opportunities
- India's PLI scheme for medical devices:Domestic manufacturing incentives for diagnostic equipment create local assembly pathways for cost-optimized camera modules serving South Asian hospital networks.
- ISO 13485 certification arbitrage:Mid-tier manufacturers in South Korea and Japan can capture share in Southeast Asian clinical markets where MDR-equivalent standards are still emerging.
- Edge computing convergence:On-camera FPGA preprocessing reduces bandwidth loads for remote pathology consultations, opening subscription-based service models for rural diagnostic networks.
Industry Challenges
- Cross-disciplinary talent scarcity:Camera system design now requires simultaneous expertise in semiconductor physics, embedded software, and clinical workflow optimization, compressing available hiring pools.
- Legacy microscope integration:Decades-old mechanical interfaces and proprietary software stacks in installed bases force costly adapter development for new sensor formats.
- Cybersecurity certification timelines:Wireless-connected cameras for telepathology face extended penetration testing protocols under hospital IT governance frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microscope Digital Cameras Market |
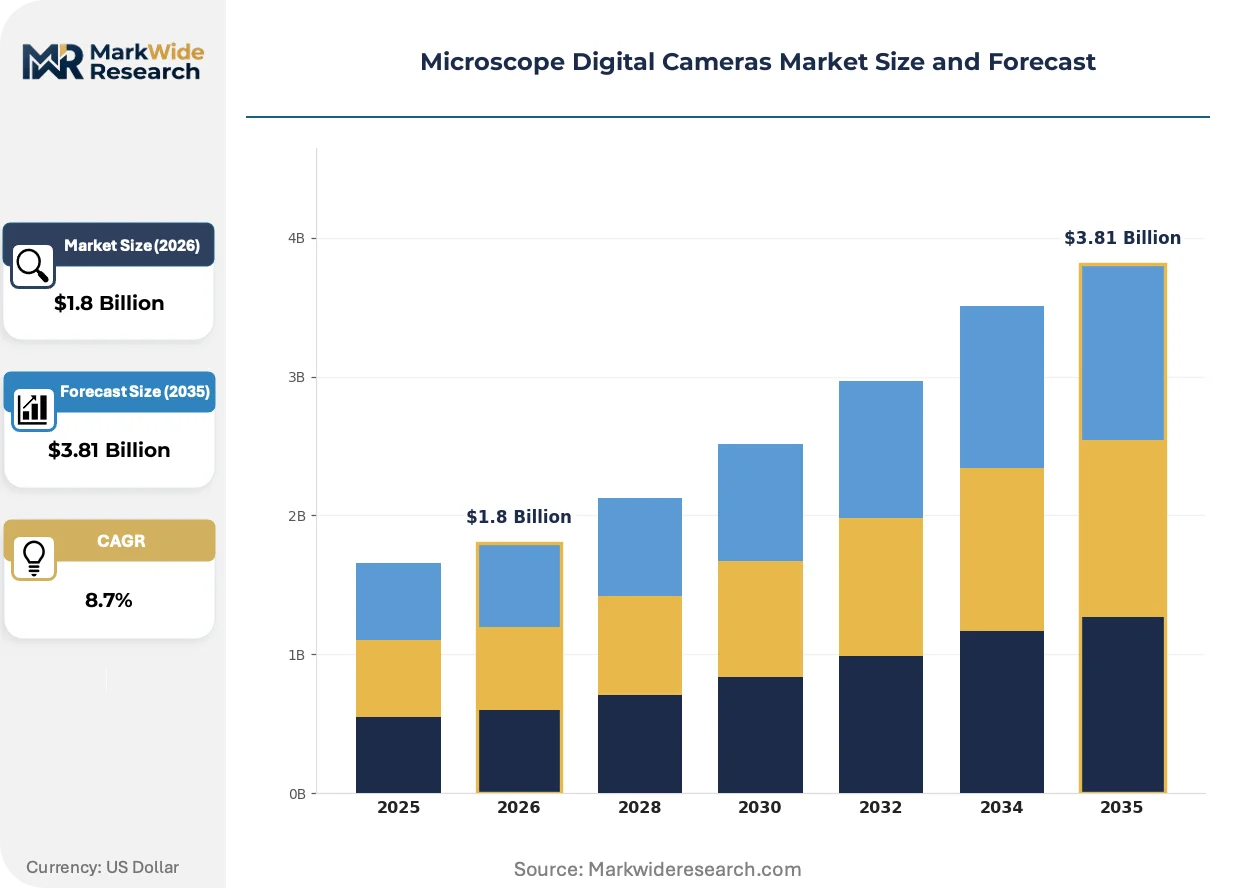
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
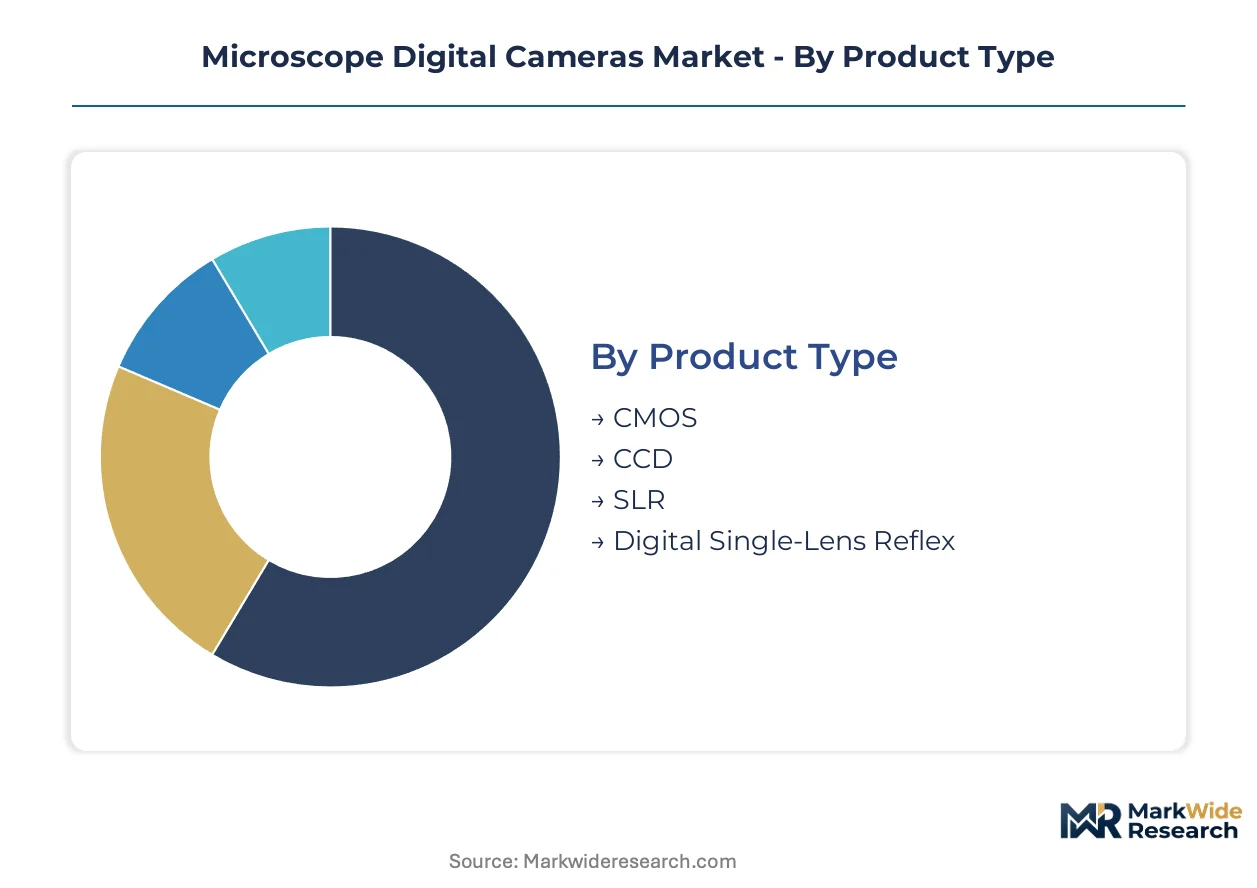
| Segmentation | Product Type: CMOS, CCD, SLR, Digital Single-Lens Reflex End User: Research Laboratories, Educational Institutions, Healthcare Facilities, Industrial Applications Technology: Image Processing, Real-Time Imaging, 3D Imaging, Wireless Connectivity Application: Pathology, Microbiology, Material Science, Forensic Analysis |
| Companies Covered | Carl Zeiss AG, Danaher Corporation, Olympus Corporation, Nikon Corporation, Hamamatsu Photonics K.K., Basler AG, Roper Technologies, Jenoptik AG, Leica Microsystems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microscope Digital Cameras Market Strategic Shifts
Computational pipelines and hardware-software co-design are displacing pure sensor specification competition, rewarding vendors who control full imaging stacks from photon capture to analysis-ready file formats.
Back-illuminated sCMOS technology is unifying the previously separate domains of high-speed live-cell imaging and low-light fluorescence microscopy. Pathology departments in US academic medical centers are adopting these sensors for whole-slide scanning workflows that previously required multiple camera types. The technology is compressing capital equipment footprints while raising performance floors for mid-tier instrument buyers.
EU MDR Article 10 technical documentation requirements now mandate clinical evidence for software algorithms that adjust contrast or stitch image tiles. German notified bodies are enforcing stricter scrutiny of artificial intelligence components in diagnostic cameras than equivalent US FDA 510(k) pathways. Manufacturers are responding by segregating EU-bound product lines with dedicated quality management system certifications.
Hospital procurement departments are consolidating imaging equipment vendors to reduce cybersecurity audit burdens, favoring suppliers with end-to-end platform coverage. Leasing and reagent-rental bundling are displacing capital purchase models in North American health systems. This concentration is most visible in integrated delivery networks across Texas and California, where standardization committees now mandate interoperable camera interfaces across pathology, hematology, and microbiology departments.
Microscope Digital Cameras Market Segmentation
Sensor architecture and regulatory certification grade determine procurement pathways across research and clinical environments. End-use workflows impose divergent specifications on frame rate, bit depth, and software validation requirements.
Product Type:
Wafer fabrication capacity concentrates scientific-grade sensor supply in East Asian foundries, with back-illumination processing creating bottlenecks for high-quantum-efficiency variants.
- CMOS:Front-illuminated and back-illuminated architectures now dominate unit economics, with sCMOS variants capturing fluorescence microscopy workflows requiring >100 fps readout. Demand clusters in German neuroscience institutes and US academic medical centers running live-cell time-lapse protocols.
- CCD:Electron-multiplying CCDs retain installed base in low-light spectroscopy and quantitative imaging where read noise below 1e- remains non-negotiable. Replacement cycles extend in European core facilities with validated legacy software pipelines.
- SLR:Adapted large-format sensors serve documentation-grade microscopy in educational settings where cost thresholds override specification intensity.
- Digital Single-Lens Reflex:Mirrorless interchangeable-lens systems increasingly displace traditional SLR adapters in field microscopy and portable diagnostic deployments.
CMOS absorbs the bulk of installed capacity; sCMOS within the CMOS category is expanding most quickly.
End User:
Procurement authority and validation burden diverge sharply between grant-funded research and hospital capital committees.
- Research Laboratories:Principal investigators drive specifications toward maximum photon collection efficiency, with NIH and NSF funding cycles synchronizing upgrade waves. Core facilities at MIT, Stanford, and Max Planck institutes standardize on sCMOS platforms to amortize training costs across user groups.
- Healthcare Facilities:Pathology departments in US integrated delivery networks and Germany's university hospital systems (Charité, Heidelberg) mandate FDA 510(k) or MDR Class IIa certification, extending sales cycles and concentrating vendor selection.
- Educational Institutions:Undergraduate microscopy labs prioritize durability and software simplicity over quantum efficiency specifications.
- Industrial Applications:Semiconductor defect inspection and quality control drive demand for high-dynamic-range sensors with automated metrology integration.
Healthcare Facilities concentrate replacement spending; Research Laboratories show the steepest expansion trajectory for high-speed imaging platforms.
Technology:
Software-hardware integration now differentiates competitive positioning more than raw sensor specifications.
- Real-Time Imaging:FPGA-accelerated preprocessing enables surgical pathology consultations without dedicated workstation infrastructure, with Texas and California health systems piloting edge-compute deployments.
- 3D Imaging:Structured illumination and light-sheet modalities require synchronized multi-camera arrays, commanding premium positioning in material science defect analysis at Fraunhofer institutes.
- Image Processing:On-camera denoising and flat-field correction reduce downstream computational loads for high-throughput screening.
- Wireless Connectivity:Wi-Fi 6E and 5G-enabled cameras face extended cybersecurity certification timelines under hospital IT governance frameworks.
Image Processing capabilities absorb the bulk of R&D allocation; Real-Time Imaging is gaining share fastest in clinical translation.
Application:
Diagnostic reimbursement pathways and research funding mechanisms create divergent demand profiles across verticals.
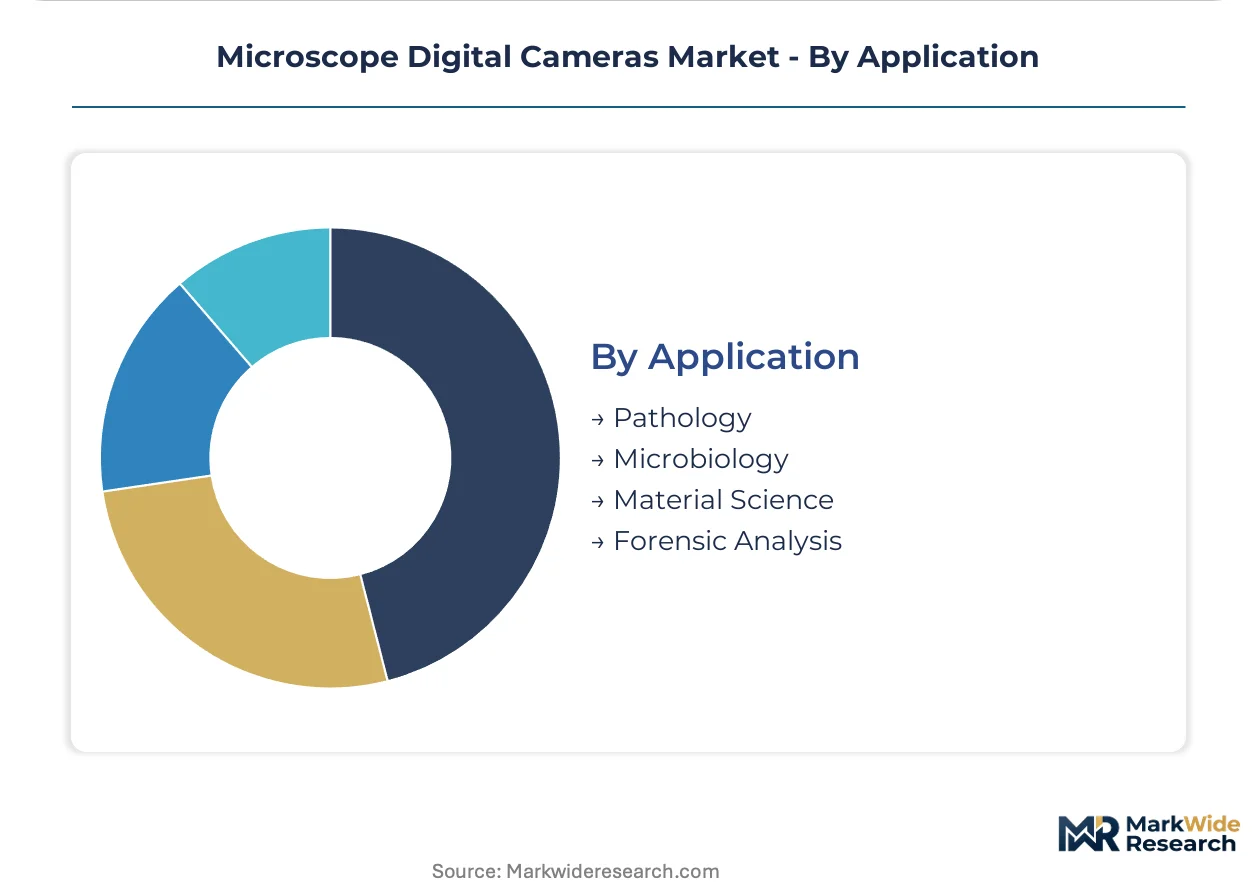
- Pathology:Whole-slide imaging workflows drive demand for large-format sensors with consistent color reproduction across tile boundaries, with CAP accreditation requirements validating camera selection.
- Microbiology:Time-lapse colony imaging and antimicrobial susceptibility testing require environmental sealing and long-term stability under incubator conditions.
- Material Science:Polarized light and differential interference contrast applications stress optical uniformity and thermal stability.
- Forensic Analysis:Chain-of-custody documentation and court-admissible image integrity impose audit-trail requirements on camera software.
Pathology commands the largest share of clinical-grade procurement; Microbiology is climbing the fastest as automated culture systems proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Jena-Oberkochen optical corridor operates as a specialized economic zone where Carl Zeiss AG and Jenoptik AG maintain captive glass-to-sensor manufacturing chains. This concentration draws procurement decisions from European research institutions seeking reduced lead times for certified imaging systems.
United States
NIH-funded neuroscience institutes and CAP-accredited pathology networks drive demand for FDA 510(k)-cleared cameras with validated software pipelines. The FDA's 21 CFR Part 11 electronic record requirements extend sales cycles by 8-14 months for clinical deployments. Texas and California integrated delivery networks now mandate interoperable camera interfaces across pathology, hematology, and microbiology departments.
Germany
University hospital systems including Charité Berlin and Heidelberg University Hospital anchor MDR Class IIa procurement for diagnostic-grade microscopy. The EU MDR Article 10 technical documentation mandates now enforce stricter scrutiny of AI-enhanced image processing than equivalent US pathways. Jena's concentrated optical engineering talent sustains end-to-end quality certification for CMOS and CCD product lines.
Japan
Hamamatsu Photonics K.K. and Nikon Corporation compete in high-speed fluorescence applications through proprietary image-processing architectures. METI's medical device quality standards align with ISO 13485 frameworks for clinical camera certification. Tokyo-Osaka manufacturing corridors retain specialized back-illuminated sensor fabrication capacity for scientific-grade units.
India
Domestic hospital networks in Maharashtra and Karnataka are expanding diagnostic infrastructure under the PLI scheme for medical devices. CDSCO's emerging regulatory framework for diagnostic equipment creates local assembly pathways for cost-optimized camera modules. South Asian pathology labs increasingly source mid-tier CMOS systems for whole-slide imaging workflows.
China
NMPA's medical device registration requirements now mandate cybersecurity documentation for wireless-connected diagnostic cameras. Yangtze River Delta semiconductor foundries supply 300mm silicon substrates for scientific-grade back-illuminated CMOS sensors. Shenzhen and Shanghai research institutes are adopting sCMOS platforms for live-cell time-lapse protocols previously served by imported systems.
Microscope Digital Cameras Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the microscope digital cameras landscape. The market structure concentrates around vertically integrated optical conglomerates and sensor-technology specialists, with mid-tier module assemblers occupying fragmented niches. Two dominant archetypes emerge: diversified life-science instrument platforms and dedicated electro-optical component suppliers. Competitive moves center on backward integration into captive sensor fabrication and M&A targeting computational imaging software stacks.
Within the diversified conglomerate tier, Danaher Corporation occupies a position through its Leica Microsystems subsidiary, while Carl Zeiss AG exemplifies vertical control from optical glass to finished camera systems. Nikon Corporation and Hamamatsu Photonics K.K. represent the specialized electro-optical archetype, competing through proprietary sensor architectures and image-processing algorithms rather than platform breadth.
| Leading Market Players |
|---|
| Carl Zeiss AG |
| Danaher Corporation |
| Olympus Corporation |
| Nikon Corporation |
| Hamamatsu Photonics K.K. |
| Basler AG |
| Roper Technologies |
| Jenoptik AG |
| Leica Microsystems |
| Others |
Value Chain & Pricing Dynamics
EU MDR Article 10 technical documentation mandates gate qualified supply access for clinical-grade microscope digital cameras, concentrating premium-tier pricing power among manufacturers with validated quality management systems and captive optical fabrication capabilities.
Pricing Analysis
Lead-time-driven pricing stratification separates expedited delivery premiums from spot-inventory discounts across the procurement landscape. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) certification grade and quantum efficiency specifications. Cost compression in economy-tier educational cameras is intensifying because AI-enhanced smartphone sensor substitution erodes specification floors. Research laboratories at Max Planck and NIH-funded institutes show least price sensitivity; undergraduate teaching labs face acute budget constraints.
Supply Chain Analysis
Single-source vulnerability sits with Taiwanese foundries supplying 300mm back-illuminated CMOS wafers with defect densities below scientific-grade thresholds. Manufacturing concentrates in Taiwan, Japan, and Germany for sensor fabrication, precision optical glass, and final assembly respectively. Raw material dependencies include high-purity silicon substrates, rare-earth doped optical glasses, and FPGA chipsets for onboard processing. Tariff exposure on semiconductor components threatens margin stability for European and North American camera assemblers. Distribution runs through authorized microscopy dealers and direct hospital procurement committees in integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR compliance costs function as a barrier-to-entry moat, privileging established manufacturers with dedicated regulatory affairs infrastructure over capital-constrained challengers seeking clinical market access.
For Market Incumbents: Deploy backward integration into captive sensor fabrication to defend margin position against foundry pricing volatility and secure supply continuity for sCMOS platforms. Consolidate software validation pipelines to streamline FDA 510(k) and MDR Class IIa submission cycles. Counter computational imaging substitution threats by bundling proprietary image-processing algorithms with hardware sales to pathology networks. For New Entrants and Emerging Players: India's PLI scheme for medical devices opens a window for cost-optimized camera module assembly serving South Asian hospital networks with emerging diagnostic infrastructure. Target educational microscopy and industrial quality control segments where certification burdens remain lighter than clinical pathology. Pursue ISO 13485 certification arbitrage in Southeast Asian markets where MDR-equivalent standards are still developing, enabling faster market entry than European or North American pathways. For Investors and Strategic Acquirers: Hospital procurement consolidation into single-vendor imaging platforms is the leading indicator that scale advantages are hardening for diversified life-science instrument conglomerates. Over the medium-term horizon, acquisition targets should emphasize computational imaging software stacks and edge-compute preprocessing capabilities rather than pure sensor hardware. Watch for CDSCO regulatory framework maturation in India as a signal that domestic manufacturing economics will shift competitive positioning in South Asia.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Fabrication | Captive wafer supply from Taiwan and Japan insulates against foundry allocation constraints. |
| Regulatory Certification Arbitrage | ISO 13485 pathways in Southeast Asia accelerate market entry versus MDR timelines. |
| Software-Hardware Co-Development | On-camera FPGA preprocessing enables subscription service models for rural telepathology networks. |
| Edge Computing Convergence | Reduced bandwidth loads position vendors for hospital IT governance frameworks hardening cybersecurity requirements. |
| Geographic Manufacturing Diversification | India PLI assembly pathways capture cost-sensitive South Asian pathology lab procurement. |
Study Parameters
Multi-period observation of NIH funding cycles, EU MDR notified body approval timelines, and foundry capacity utilization anchored the trend analysis, supplemented by interviews with biomedical engineers at Charité Berlin and Heidelberg University Hospital, GPO contracts managers at Texas integrated delivery networks, and regulatory affairs leads at Jena-Oberkochen optical manufacturers. Secondary validation drew from FDA 510(k) filings, EMA MDR technical documentation databases, hospital procurement records, and SEMI semiconductor capacity reports. Bottom-up sensor shipment estimates and top-down diagnostic equipment spending patterns were triangulated to cross-verify market sizing.
Input-output matrices modeled unit economics across sensor architecture, certification grade, and end-use workflow dimensions throughout the forecast period. Segmentation dimensions included CMOS versus CCD versus sCMOS sensor types, research versus clinical versus educational versus industrial end users, and real-time versus 3D versus wireless technology tiers. CAGRs were derived from installed base replacement cycles synchronized with funding and regulatory approval waves. Industry-specific inputs encompassed quantum efficiency improvement trajectories, MDR transition completion timelines, and computational imaging substitution elasticities.
The model assumes a particular technology adoption path; alternative pathways for AI-enhanced image reconstruction from commodity sensors would alter the outlook for entry-level scientific camera demand. Forecasts reflect assumptions regarding EU MDR enforcement consistency, foundry capacity expansion, and hospital cybersecurity standardization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
US Near Infrared Imaging Market
Imaging
Printed Image Sensors Market
Imaging
Borescope Market
Imaging
Global Microscopy Market
Imaging
North America Image Sensors Market
Imaging
Camera Lens Market
Imaging
Underwater Camera Market
Imaging
Industrial Camera Market
Imaging
Thermal Imaging Riflescope for Hunting Market
Imaging
Gel Imaging Documentation Market
Imaging
Sub-Micrometer Computed Tomography Market
Imaging
In Vivo Imaging Systems Market
Imaging
Specific Imaging Solution Market
Imaging
Medical X-Ray Detectors Market
Imaging
Weatherproof Camera Market
Imaging
TDI Camera Market