
 Handheld Imaging Devices Market | 2026-2036
Handheld Imaging Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Handheld Imaging Devices Market Analysis
Asset-light leasing models for portable ultrasound systems is reconfiguring competitive dynamics across emerging health networks. GE Healthcare leverages captive financing programs to anchor deployment scale in Latin American clinics. Butterfly Network specializes in semiconductor-based transducer architectures that compress unit costs for budget-constrained buyers. Siemens Healthineers navigates dual certification requirements across EU MDR and FDA pathways to sustain premium positioning.
Handheld imaging devices integrate compact sensor arrays, low-power signal processors, and wireless transmission modules into battery-operated form factors for bedside diagnostic capture. Optical coherence tomography units achieve axial resolutions below ten micrometers using swept-source laser interferometry, enabling retinal layer mapping outside traditional ophthalmology suites. Diagnostic imaging applications dominate volume flows across clinics and hospitals, while telemedicine-linked wireless imaging represents the fastest-expanding margin pool as reimbursement codes mature for remote interpretation. Home care endpoints remain nascent due to operator training barriers and liability frameworks.
FDA 510(k) premarket notification requirements and EU MDR technical documentation standards shape product development cadences and commercialization timelines for manufacturers targeting dual-market registration. ISO 13485 quality management certification functions as a baseline gating factor for original equipment supplier qualification across regulated jurisdictions. Stakeholders must monitor evolving AI diagnostic algorithm validation standards from notified bodies to anticipate which product architectures will secure priority market access.
Market Dynamics
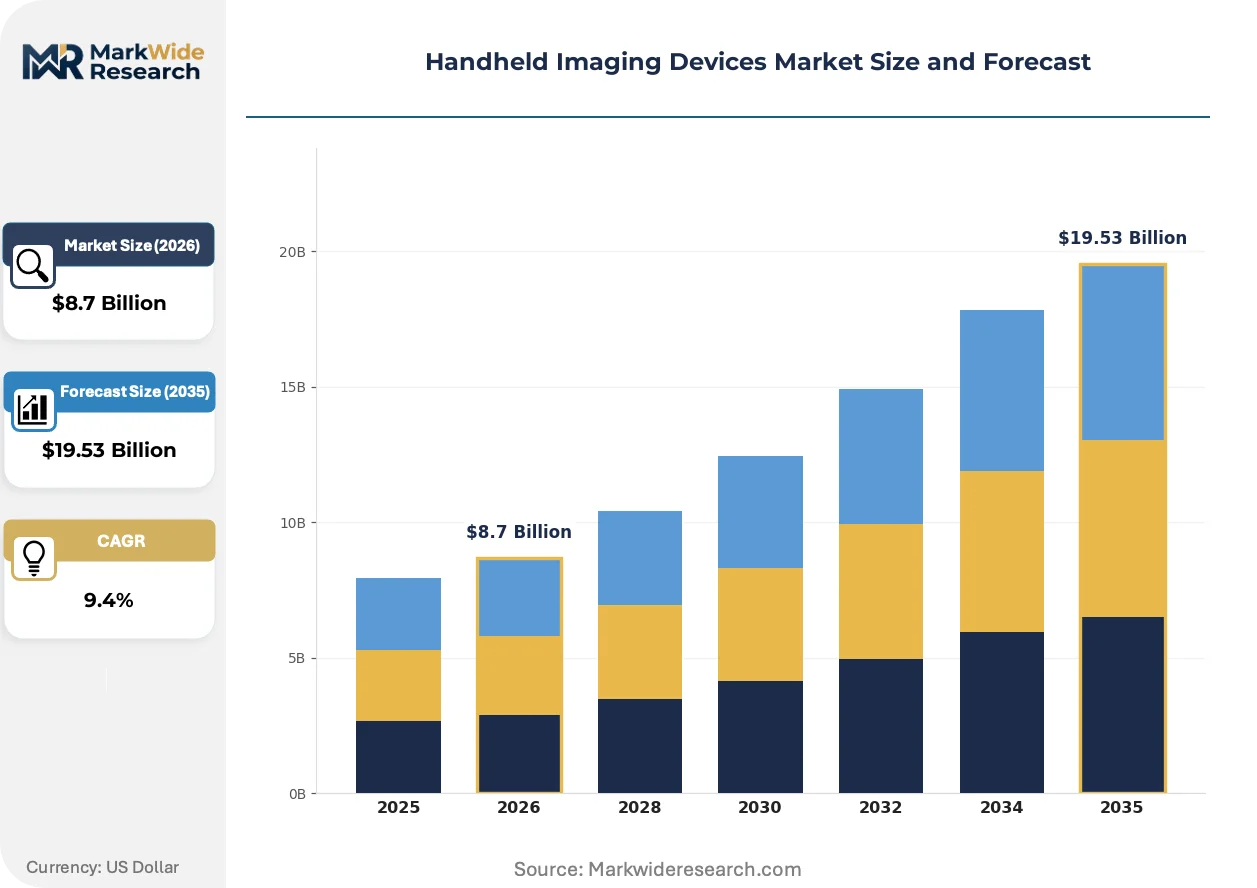
Point-of-care ultrasound adoption is compressing capital equipment replacement cycles across emergency departments and rural clinics, while FDA 510(k) clearance pathways for AI-enabled diagnostic software are accelerating product-to-market velocity for semiconductor-based transducer architectures.
Growth Catalysts
- AI Algorithm Validation Standards:FDA 510(k) premarket notification requirements for AI-enabled diagnostic software are compressing development timelines for manufacturers targeting dual-market registration across regulated jurisdictions.
- Rural Emergency Department Expansion:Point-of-care ultrasound adoption is accelerating across India's tier-two hospital networks and Brazil's rural emergency departments seeking bedside diagnostic capture capabilities.
- EU MDR Technical Documentation:The European Union's Medical Device Regulation standardization is creating baseline gating factors for original equipment supplier qualification that prioritize quality management certification.
Market Restraints
- Semiconductor Supply Concentration:Semiconductor-based transducer architectures face input cost volatility from concentrated fabrication capacity in East Asian foundries, compressing margins for budget-constrained buyers.
- Operator Training Barriers:Home care endpoints remain structurally constrained by liability frameworks and the skill gap in image interpretation outside traditional radiology departments.
- Dual Certification Friction:Manufacturers navigating simultaneous EU MDR and FDA pathways encounter extended commercialization timelines that delay revenue recognition across premium positioning strategies.
Strategic Opportunities
- Telemedicine Reimbursement Maturation:Wireless imaging linked to remote interpretation is expanding margin pools as reimbursement codes mature for diagnostic capture outside traditional hospital settings.
- Asset-Light Leasing Models:Captive financing programs are reconfiguring competitive dynamics across Latin American clinics seeking portable endoscopy systems without capital expenditure burdens.
- Optical Coherence Tomography Expansion:Swept-source laser interferometry achieving sub-ten-micrometer axial resolution is enabling retinal layer mapping outside traditional ophthalmology suites in China's tier-two networks.
Industry Challenges
- ISO 13485 Certification Timelines:Quality management certification functions as a non-negotiable baseline for supplier qualification, with documentation requirements extending product development cadences by twelve to eighteen months.
- Wireless Transmission Module Integration:Low-power signal processors and wireless transmission modules require specialized firmware development talent that concentrates in specific geographic clusters, creating recruitment bottlenecks.
- Legacy PACS Compatibility:Integration complexity with hospital picture archiving and communication systems forces additional engineering cycles for seamless data flow into existing radiology workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Handheld Imaging Devices Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasound, Endoscopy, X-Ray, Optical Coherence Tomography End User: Clinics, Hospitals, Research Institutions, Home Care Technology: Digital Imaging, Analog Imaging, Wireless Imaging, High-Resolution Imaging Application: Diagnostic Imaging, Surgical Guidance, Patient Monitoring, Telemedicine |
| Companies Covered | GE Healthcare, Teledyne FLIR, Koninklijke Philips N.V., Siemens Healthineers, Butterfly Network, Zebra Technologies, Canon Inc., Fluke Corporation, FUJIFILM Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Handheld Imaging Devices Market Emerging Trajectories
Semiconductor miniaturization and AI inference at the edge are reconfiguring the technical architecture of bedside diagnostic capture, compressing unit economics while expanding addressable clinical settings beyond traditional imaging departments.
Semiconductor-based transducer arrays are replacing piezoelectric crystal assemblies in portable ultrasound systems, delivering comparable image fidelity at one-third the manufacturing cost. Emergency departments across India's tier-two hospital networks are adopting these architectures at accelerated pace, bypassing traditional capital equipment procurement committees. The technology is virtualizing the radiology workflow by enabling real-time image interpretation at the point of care without dedicated scanner rooms or specialized technicians.
FDA 510(k) clearance pathways for AI-enabled diagnostic software are compressing product development timelines by establishing predicate device frameworks that reduce clinical validation requirements. Manufacturers targeting dual-market registration are prioritizing algorithm submissions that demonstrate substantial equivalence to cleared reference standards. Portable endoscopy systems and point-of-care ultrasound platforms are responding fastest, with development cadences now tracking six to nine months shorter than hardware-centric submissions.
Hospital procurement committees are unbundling after-sales service contracts from capital equipment purchases, shifting toward per-scan or subscription-based economic models. Latin American clinics and China's tier-two networks are leading this behavioral transition, replacing bundled maintenance agreements with third-party technical support arrangements. The shift is most visible in Brazil's rural emergency departments, where budget constraints and financing access limitations favor operational expenditure structures over capital deployment.
Handheld Imaging Devices Market Segmentation
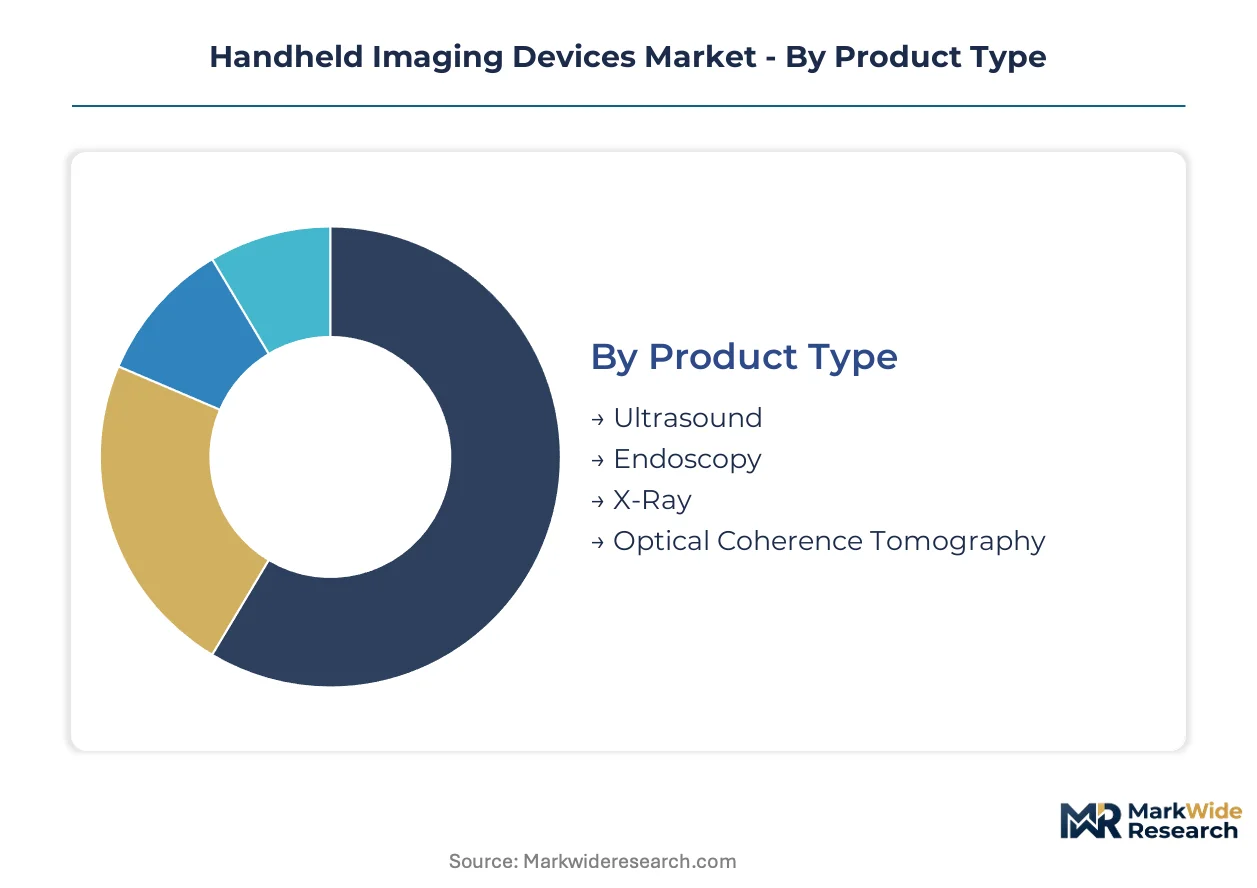
Segmentation in handheld imaging devices reveals how technical specifications, clinical settings, and connectivity architectures determine procurement patterns and margin structures across regulated healthcare markets. Understanding these divides exposes where capital concentrates and which configurations command premium positioning.
Product Type:
Mature modalities dominate installed base volumes while semiconductor-enabled architectures reshape unit economics across emerging health networks.
- Ultrasound:Semiconductor-based transducer arrays replace piezoelectric crystal assemblies, delivering comparable image fidelity at reduced manufacturing cost. India's tier-two hospital networks and Brazil's rural emergency departments are adopting these architectures fastest, bypassing traditional capital equipment procurement committees to enable bedside diagnostic capture.
- Endoscopy:Portable endoscopy systems integrate compact sensor arrays with low-power signal processors for gastrointestinal and respiratory tract visualization outside dedicated endoscopy suites. China's tier-two hospital networks are concentrating procurement here, driven by demand for point-of-care diagnostic capabilities without infrastructure investment.
- X-Ray:Miniaturized digital radiography units leverage CMOS flat-panel detectors for extremity and chest imaging in mobile clinical settings.
- Optical Coherence Tomography:Swept-source laser interferometry achieves sub-ten-micrometer axial resolution for retinal layer mapping.
Ultrasound handles the majority of throughput across installed base volumes; Optical Coherence Tomography is expanding most quickly on share as ophthalmology applications migrate outside traditional suites.
End User:
Procurement authority and reimbursement access create tiered demand patterns that separate institutional buyers from emerging home care endpoints.
- Hospitals:Emergency departments and radiology units deploy point-of-care ultrasound to compress diagnostic turnaround times and reduce scanner room bottlenecks. These buyers command volume pricing leverage and integrate devices into existing PACS infrastructure.
- Clinics:Latin American clinics and India's tier-two networks favor asset-light leasing models for portable endoscopy systems, avoiding capital expenditure burdens through operational expenditure structures.
- Research Institutions:Academic medical centers validate AI-enabled diagnostic algorithms for FDA 510(k) predicate device frameworks.
- Home Care:Operator training barriers and liability frameworks constrain penetration despite wireless transmission module maturation.
Hospitals command the largest share of current revenue; Clinics are climbing the fastest as financing innovation unlocks budget-constrained segments.
Technology:
Signal processing architectures and connectivity protocols differentiate performance tiers and determine compatibility with legacy healthcare IT systems.
- Digital Imaging:CMOS and CCD sensor arrays with onboard FPGA processing enable real-time image enhancement and AI inference at the edge. These architectures dominate new product development cadences targeting FDA 510(k) clearance pathways.
- Wireless Imaging:Low-power Bluetooth and Wi-Fi transmission modules integrate with telemedicine platforms for remote interpretation. Reimbursement code maturation for diagnostic capture outside traditional hospital settings is accelerating deployment.
- Analog Imaging:Legacy piezoelectric transducer systems persist in cost-sensitive replacement markets.
- High-Resolution Imaging:Specialized firmware development for sub-millimeter resolution concentrates in specific geographic talent clusters.
Digital Imaging anchors current technology investment; Wireless Imaging shows the steepest expansion trajectory as telemedicine reimbursement frameworks mature.
Application:
Clinical use cases separate high-volume screening workflows from specialized interventional procedures and emerging remote care models.
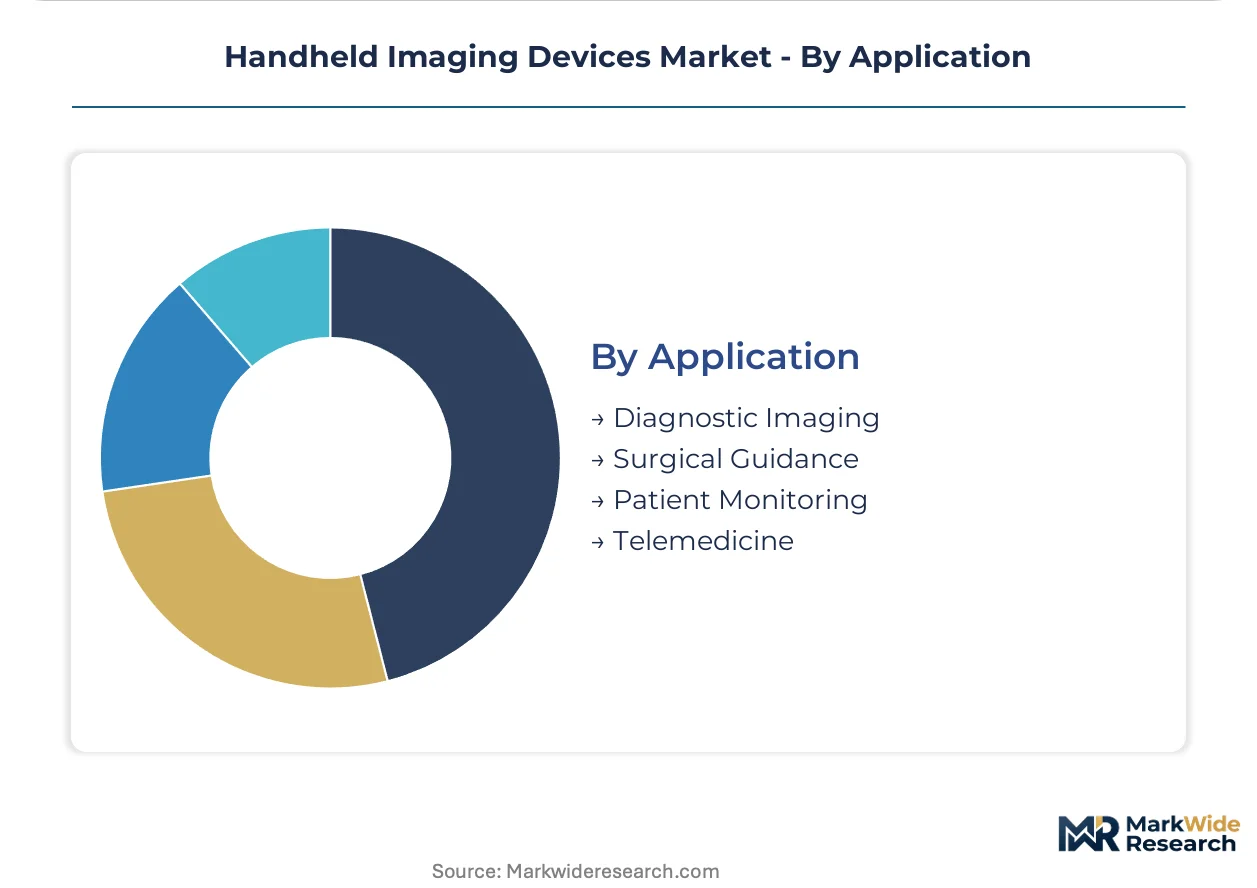
- Diagnostic Imaging:Bedside capture for cardiology, obstetrics, and abdominal assessment represents the core volume application across clinics and hospitals. This segment absorbs the majority of point-of-care ultrasound deployment.
- Telemedicine:Wireless imaging linked to remote interpretation is expanding margin pools as reimbursement codes mature for diagnostic capture outside traditional hospital settings. Brazil's rural emergency departments and India's tier-two networks are leading adoption.
- Surgical Guidance:Intraoperative ultrasound and endoscopy support real-time decision-making in operating theaters.
- Patient Monitoring:Continuous hemodynamic assessment applications remain nascent due to regulatory validation requirements.
Diagnostic Imaging handles the majority of throughput; Telemedicine is gaining share fastest as connectivity infrastructure and reimbursement alignment converge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government procurement incentives for rural healthcare infrastructure are accelerating point-of-care imaging deployment across emerging economies. Brazil's SUS program and India's Ayushman Bharat scheme directly subsidize portable ultrasound acquisition in underserved districts. China's 14th Five-Year Plan prioritizes tier-two hospital digitization, creating concentrated demand for wireless-enabled diagnostic devices.
United States
Emergency medicine residency programs at Johns Hopkins and Mayo Clinic now mandate point-of-care ultrasound certification, institutionalizing bedside imaging workflows. FDA 510(k) clearance pathways compress commercialization timelines for AI-enabled diagnostic software developers. The Research Triangle Park cluster in North Carolina concentrates semiconductor-based transducer R&D talent for next-generation portable systems.
Germany
University hospitals in Munich and Heidelberg validate optical coherence tomography protocols for outpatient retinal screening outside traditional ophthalmology suites. EU MDR technical documentation requirements enforce quality management standards that prioritize ISO 13485-certified suppliers. The Baden-Württemberg medical technology corridor hosts specialized firmware development clusters for low-power signal processing architectures.
China
Tier-two hospital networks in Sichuan and Shaanxi provinces concentrate procurement of portable endoscopy systems for gastrointestinal screening programs. NMPA regulatory harmonization with international standards accelerates dual-market registration for domestic manufacturers. The Yangtze River Delta manufacturing belt supplies compact sensor arrays and wireless transmission modules at compressed unit economics.
Brazil
Rural emergency departments in Minas Gerais and Ceará bypass capital equipment committees through ANVISA-sanctioned leasing arrangements for point-of-care ultrasound. The SUS reimbursement framework now covers telemedicine-linked diagnostic interpretation from remote radiologists. São Paulo's medical device distribution hub coordinates third-party technical support for asset-light operational expenditure models.
India
Ayushman Bharat health and wellness centers in Uttar Pradesh and Bihar deploy semiconductor-based ultrasound architectures for maternal and abdominal screening. CDSCO streamlined medical device registration reduces import clearance timelines for portable imaging equipment. The Bengaluru medical technology cluster integrates AI inference engines with edge-processing hardware for real-time image enhancement.
Handheld Imaging Devices Market Vendor Landscape
On the supply side, the industry is consolidating around three strategic archetypes: diversified conglomerates with captive financing arms, semiconductor-native specialists with compressed cost structures, and precision-optics manufacturers extending into portable modalities. Market structure tilts toward tiered competition where premium positioning requires simultaneous FDA and EU MDR certification. Dominant competitive moves include strategic partnerships with telemedicine platforms and geographic expansion through asset-light distribution networks.
Within the diversified healthcare technology tier, GE Healthcare and Siemens Healthineers exemplify archetypes combining imaging hardware with captive financing programs. Philips anchors the precision-diagnostics segment through integrated workflow solutions. Butterfly Network occupies a distinct position as a semiconductor-native specialist leveraging custom transducer architectures. These three entities represent the primary competitive anchors around which mid-scale specialists and regional assemblers organize market entry strategies.
| Leading Market Players |
|---|
| GE Healthcare |
| Teledyne FLIR |
| Koninklijke Philips N.V. |
| Siemens Healthineers |
| Butterfly Network |
| Zebra Technologies |
| Canon Inc. |
| Fluke Corporation |
| FUJIFILM Holdings Corporation |
| Others |
Supply Flow & Price Mechanics
The Yangtze River Delta manufacturing belt concentrates compact sensor array and wireless transmission module production, granting Chinese contract manufacturers outsized leverage over unit economics for portable ultrasound and endoscopy systems. This geographic concentration cascades into downstream pricing power, with tier-two hospital networks in India and Brazil facing compressed margins when negotiating procurement terms against consolidated supplier bases.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with FDA 510(k)-cleared and EU MDR-compliant devices commanding substantial premiums over CDSCO-registered equivalents. Three-tier pricing structure across premium, standard, and economy levels reflects after-sales service bundling and AI-enabled diagnostic software inclusion. Cost compression in economy tiers is intensifying because semiconductor-based transducer architectures from Butterfly Network and similar specialists displace legacy piezoelectric systems. Latin American clinics exhibit highest price sensitivity due to capital expenditure constraints, while German university hospitals show lowest sensitivity given captive financing access and reimbursement code maturity.
Supply Chain Analysis
East Asian foundries in Taiwan, South Korea, and China hold concentrated capacity for semiconductor-based transducer fabrication and CMOS flat-panel detector production. Raw material dependencies center on rare earth elements for laser interferometry components, lithium-ion battery cells for portable power architectures, and specialized optical glass for endoscope lenses. Single-source vulnerability in advanced FPGA processing units creates exposure to export control restrictions from the US Bureau of Industry and Security. Distribution runs through third-party medical device distributors in São Paulo and Bengaluru, with direct-to-hospital models gaining traction only in mature North American markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor-native imaging specialists and smartphone-connected diagnostic platforms threaten incumbent hardware margins by virtualizing the radiology workflow and eliminating dedicated scanner room infrastructure. Incumbents must defend against this substitution by anchoring proprietary value in regulatory certification moats and integrated service ecosystems.
For Market Incumbents: Build certification moats by accelerating simultaneous FDA 510(k) and EU MDR submissions to create dual-market exclusivity windows. Deepen backward integration into semiconductor transducer design to match Butterfly Network's cost structure. Prioritize captive financing program expansion across Latin American clinics to lock out asset-light leasing competitors. Anchor hospital procurement relationships through PACS integration engineering that smartphone-connected substitutes cannot replicate.
For New Entrants and Emerging Players: Build out telemedicine-linked wireless imaging platforms targeting Brazil's rural emergency departments and India's Ayushman Bharat health and wellness centers, where reimbursement code maturation outpaces incumbent coverage. Concentrate on optical coherence tomography for retinal screening outside traditional ophthalmology suites, a segment with lower regulatory density than ultrasound. Pursue ANVISA-sanctioned leasing arrangements as the primary go-to-market mechanism to bypass capital equipment committee friction.
For Investors and Strategic Acquirers: Long-term, this sits as a substitution defense play because semiconductor miniaturization and AI inference at the edge will compress hardware margins while expanding addressable clinical settings beyond radiology departments. Target acquisition profiles should emphasize firms with ISO 13485 certification infrastructure and existing FDA predicate device frameworks, as these assets accelerate product-to-market velocity. Monitor NMPA regulatory harmonization announcements as the signal indicating when Chinese domestic manufacturers will achieve dual-market registration parity, triggering competitive intensity inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | Simultaneous FDA 510(k) and EU MDR submissions compress commercialization timelines by six to nine months. |
| Telemedicine Platform Partnership | Wireless imaging integration with remote interpretation platforms expands margin pools as reimbursement codes mature. |
| Semiconductor Transducer Development | Custom CMOS architectures reduce manufacturing costs to one-third of legacy piezoelectric crystal assemblies. |
| Captive Financing Program Expansion | Asset-light leasing models in Latin American clinics bypass capital expenditure constraints and lock in procurement relationships. |
| PACS Integration Engineering | Seamless data flow into hospital picture archiving systems creates switching costs that smartphone-connected substitutes cannot overcome. |
Methodological Framework
Desk research of FDA 510(k) premarket notification databases, EU MDR technical documentation filings, and hospital procurement contract registries preceded structured interviews with emergency department clinicians, biomedical engineering directors, GPO contracts managers, and regulatory affairs specialists at notified bodies. Primary fieldwork across India's tier-two hospital networks and Brazil's rural emergency departments validated secondary estimates of point-of-care ultrasound adoption velocity. Bottom-up unit shipment modeling triangulated against top-down healthcare expenditure allocation data from national insurance schemes.
Assumptions held reimbursement code maturation for telemedicine-linked diagnostic interpretation and semiconductor fabrication capacity expansion fixed at current trajectory levels across the analysis window, while varying AI algorithm validation standards and dual certification friction scenarios. Segmentation dimensions modeled include product modality, end-user facility type, technology architecture, and clinical application. CAGRs derived from regression analysis against historical capital equipment replacement cycles and rural healthcare infrastructure investment patterns. Forecast inputs incorporated NMPA regulatory harmonization timelines and Ayushman Bharat deployment schedules.
Sensitivities concentrate around FDA AI diagnostic algorithm validation standard revisions and EU MDR notified body capacity constraints that could extend commercialization timelines. Forecasts reflect assumptions regarding continued semiconductor cost compression and wireless transmission module performance improvement. Quarterly review of CDSCO import clearance timelines and ANVISA leasing arrangement sanction rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Visualiser Market
Imaging
Microscopic Camera Market
Imaging
Pan-Tilt-Zoom (PTZ) Camera Market
Imaging
Compact Camera Module Market
Imaging
Middle East and Africa Hyperspectral Imaging Systems Market
Imaging
Weatherproof Camera Market
Imaging
Europe Multi Camera Vision Inspection Systems Market
Imaging
Industrial Machine Vision Market
Imaging
Software-Defined Camera (SDC) Market
Imaging
Middle East and Africa Image Sensors Market
Imaging
Brazil Surveillance Analog Camera Market
Imaging
Global Thermal Imager Market
Imaging
Asia Pacific Smartphone Camera Module Market
Imaging
Instant Digital Cameras Market
Imaging
US Near Infrared Imaging Market
Imaging
Cooled IR Camera Market