
 Global Brewery Filtration Market | 2026-2036
Global Brewery Filtration Market Size, Share, and Industry Trends Forecast 2026-2036
Global Brewery Filtration Market Analysis
Aftermarket service revenue for filtration system maintenance is reconfiguring margin pools away from initial equipment sales toward lifecycle contracts. Pall Corporation leverages its depth filtration portfolio to anchor replacement cartridge demand across industrial brewery networks. Alfa Laval competes through crossflow membrane specialization that sustains premium positioning in craft brewery segments. GEA Group extends its geographic footprint by controlling large-scale project engineering for greenfield brewery installations in Asia-Pacific and Latin America.
Brewery filtration encompasses mechanical separation processes that remove yeast, proteins, and particulates from beer using pore-rated media typically spanning 0.45 to 100 microns, with membrane systems operating at differential pressures below 2 bar to preserve sensory integrity. The primary purpose centers on achieving microbial stability, visual clarity, and shelf-life extension prior to packaging. Membrane filtration leads product type architecture due to its scalability from microbrewery pilot systems to industrial continuous-flow installations, while crossflow configurations capture the fastest expansion as brewers seek reduced filter aid consumption and lower waste volumes. Depth filtration retains mature share in traditional lager production where cost-per-hectoliter sensitivity dominates procurement decisions.
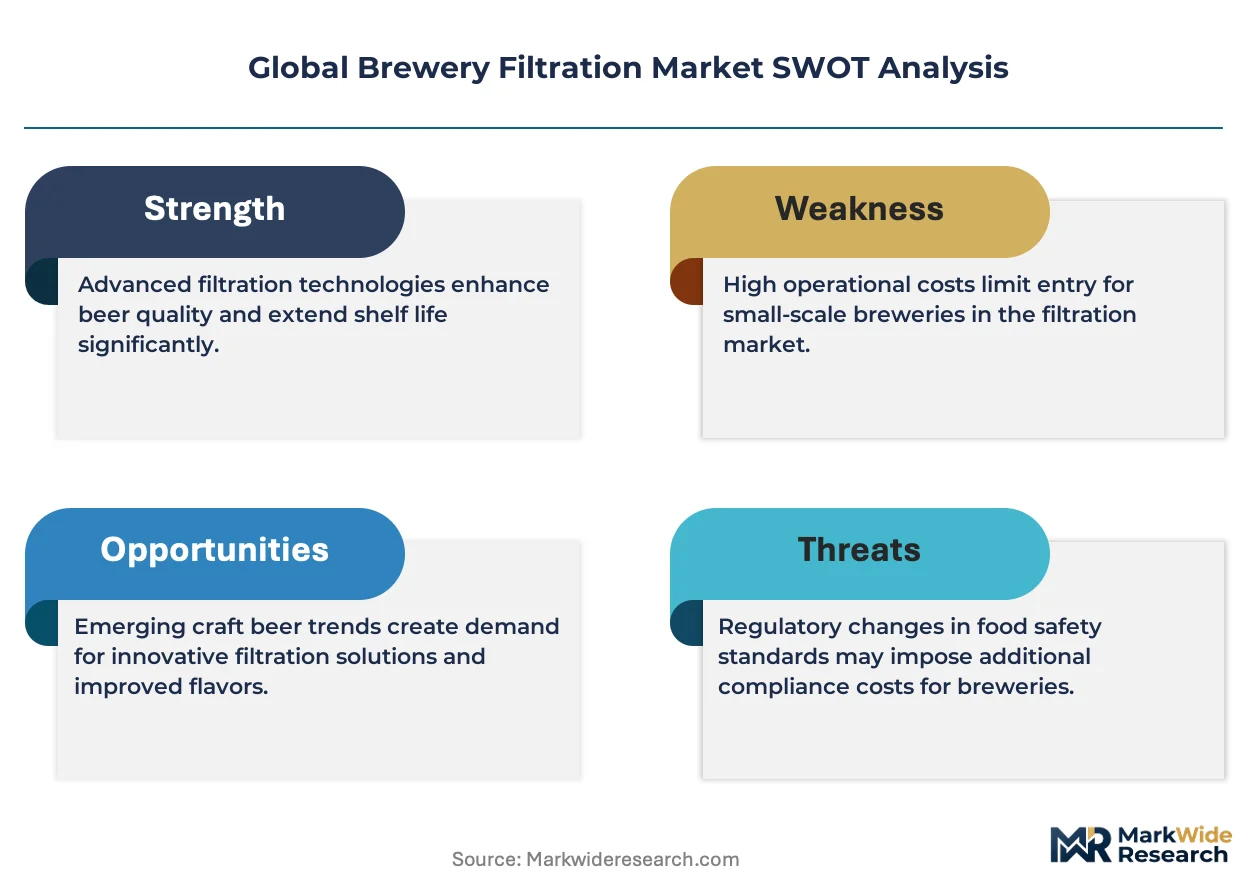
FDA food-contact substance notifications and EPA effluent guidelines shape filter media selection and backwash wastewater handling protocols for US-based equipment suppliers. REACH chemical authorization requirements and EU F-Gas Regulation compliance on refrigeration-integrated filtration systems constrain material choices and refrigerant recovery designs for European manufacturers. ISO 22000 food safety management standards govern international supply chain qualification for membrane and cartridge producers serving multinational brewery groups. Stakeholders must monitor evolving PFAS restrictions in filter membrane polymers and assess captive regeneration service capabilities as sustainability metrics penetrate brewery procurement scorecards.
Market Dynamics
Membrane filtration scalability from craft microbreweries to industrial continuous-flow installations is compressing equipment replacement cycles and redistributing vendor margin pools toward consumable cartridge streams and captive regeneration services.
Growth Catalysts
- REACH chemical authorization:European purity specifications for filter media are tightening, compelling brewers to upgrade depth and membrane systems to compliant materials.
- Crossflow membrane technology:Reduced filter aid consumption and lower waste volumes are accelerating adoption across German and US craft brewery networks seeking operational efficiency.
- China and Brazil:Greenfield brewery installations and production line modernization in these markets are driving demand for scalable filtration infrastructure.
Market Restraints
- Polymer input volatility:PFAS restrictions in membrane polymers are constraining material sourcing and elevating raw material qualification costs for filter media producers.
- Equipment supplier concentration:Large-scale project engineering capabilities for industrial installations cluster with a limited set of European and North American engineering firms.
- Refrigerant recovery design complexity:EU F-Gas Regulation compliance requirements for refrigeration-integrated filtration systems extend lead times and capex thresholds.
Strategic Opportunities
- Captive regeneration services:Sustainability metrics penetrating brewery procurement scorecards create white space for vertically integrated service models spanning membrane cleaning and reuse.
- India:Underpenetrated craft brewery infrastructure presents expansion potential for membrane system suppliers capable of modular pilot-to-production scaling.
- ISO 22000 qualification:Food safety management certification is becoming a procurement gate for multinational brewery groups, favoring certified membrane and cartridge producers.
Industry Challenges
- Backwash wastewater handling:EPA effluent guidelines in the US require specialized protocols that complicate system integration and elevate operational expertise requirements.
- Membrane-to-legacy equipment interoperability:Retrofitting crossflow systems into traditional lager production lines demands custom engineering and extends commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Brewery Filtration Market |
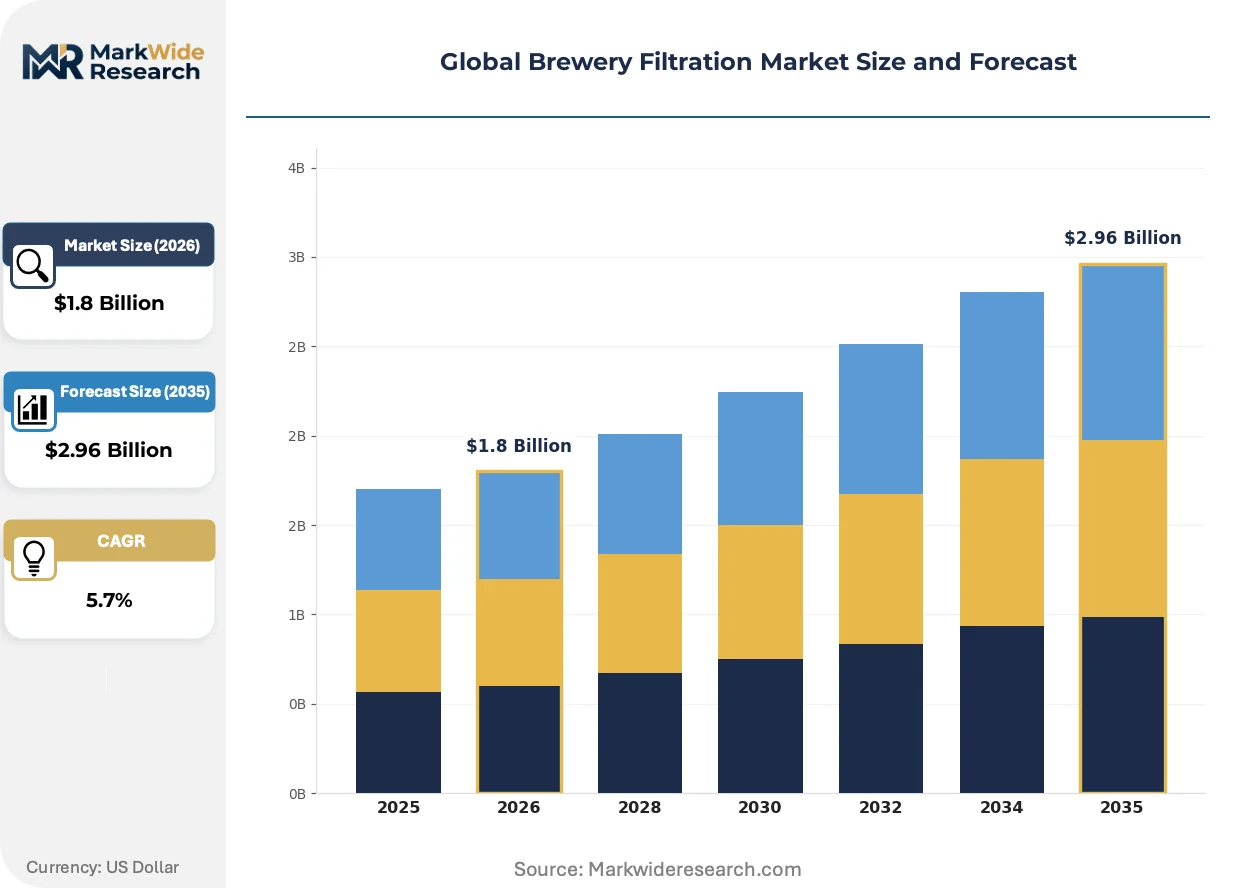
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Membrane Filtration, Cartridge Filtration, Crossflow Filtration, Depth Filtration Application: Beer Production, Wastewater Treatment, Clarification, Carbonation End User: Microbreweries, Craft Breweries, Large Enterprises, Industrial Breweries Technology: Microfiltration, Ultrafiltration, Reverse Osmosis, Filtration Equipment |
| Companies Covered | Pall Corporation (Danaher Corporation), Alfa Laval, GEA Group, Krones AG, Sartorius AG, 3M, Pentair, Ziemann International GmbH, Eaton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Brewery Filtration Market Emerging Trajectories
Filtration technology convergence with sustainability mandates and service model unbundling is reconfiguring how breweries evaluate total cost of ownership across equipment lifecycles.
Crossflow membrane configurations are collapsing the traditional trade-off between filtration precision and waste generation that constrained older dead-end systems. Craft breweries in Germany and the United States are piloting these systems at accelerating pace. The structural consequence compresses operating cost differentials between small-batch and industrial-scale production.
EU F-Gas Regulation compliance requirements are mandating refrigerant recovery designs for temperature-controlled filtration processes. Equipment suppliers must reengineer cooling-integrated systems to meet chemical authorization timelines. Breweries with extensive cold-chain packaging operations face the steepest retrofit obligations.
After-sales service unbundling from initial equipment contracts is fragmenting buyer-vendor relationships across the industry. Lifecycle maintenance agreements and replacement cartridge subscriptions are displacing upfront capital purchase models. This pattern concentrates in North American craft brewery segments where cash flow sensitivity favors operational expenditure structures.
Global Brewery Filtration Market Segmentation
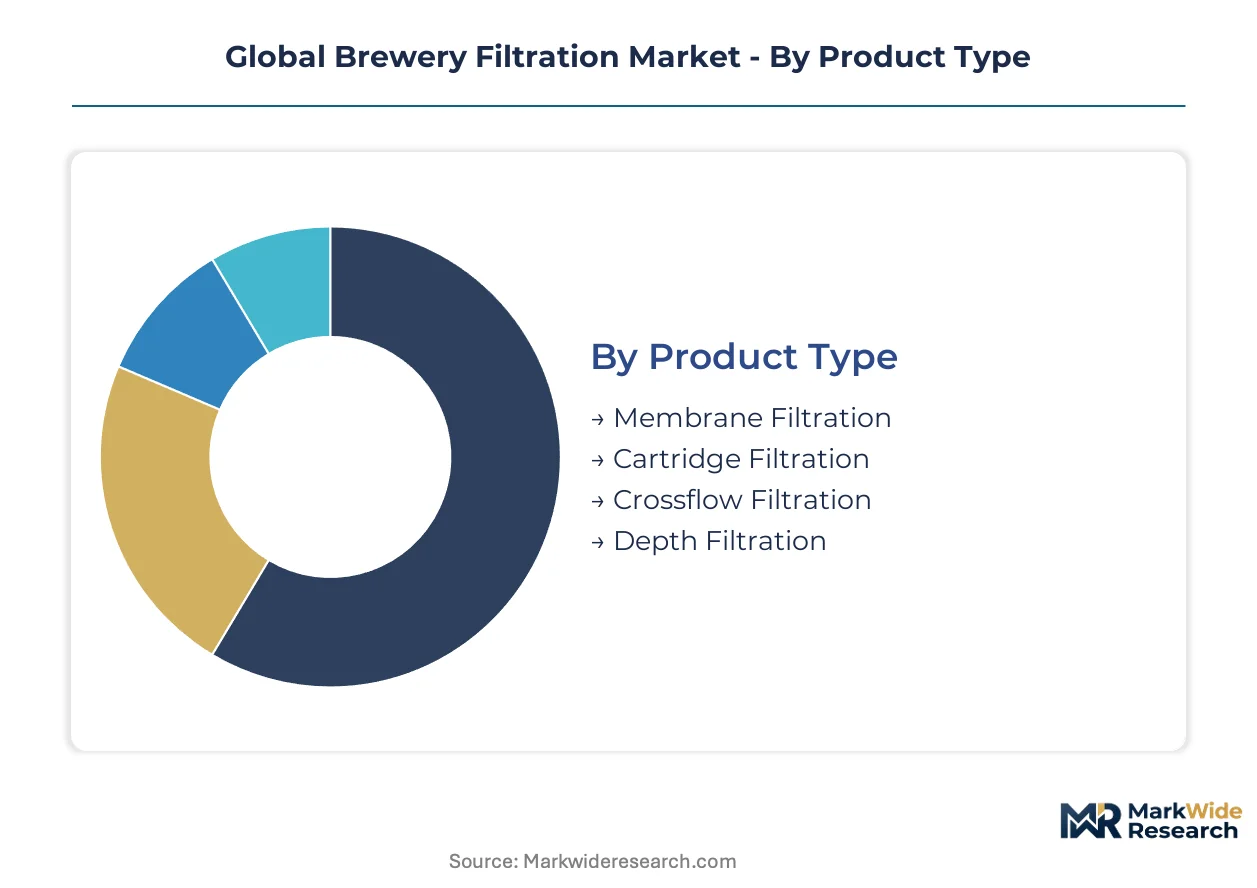
Brewery filtration procurement splits across four distinct category axes, each commanding different vendor engagement models and margin structures. Equipment replacement cycles, consumable replenishment rates, and service attachment potential vary dramatically by segment, forcing suppliers to prioritize portfolio depth over breadth.
Product Type:
Replacement cycle velocity separates these segments most sharply, with consumable cartridges turning over fastest and fixed infrastructure slowest.
- Membrane Filtration:Polymeric or ceramic pore-rated media operating at sub-2 bar differential pressures deliver microbial stability without thermal pasteurization. German craft breweries and Chinese industrial greenfield sites are standardizing on hollow-fiber configurations to meet shelf-stability specifications while preserving sensory profiles.
- Crossflow Filtration:Tangential-flow configurations recirculate feed streams parallel to membrane surfaces, slashing filter aid consumption and waste generation versus dead-end alternatives. US craft brewery networks are piloting these systems aggressively as operational efficiency penetrates procurement scorecards.
- Cartridge Filtration:Disposable depth-media elements in polypropylene or cellulose housings handle final polishing and point-of-use protection.
- Depth Filtration:Diatomaceous earth and perlite-based stacked sheet systems retain cost dominance in traditional lager production where hectoliter economics override precision demands.
Depth filtration anchors the volume base while crossflow filtration gains share at the steepest rate.
Application:
Process stage determines contamination risk tolerance and regulatory scrutiny intensity, with packaging-line applications facing the tightest purity gates.
- Beer Production:Primary and secondary clarification stages remove yeast, proteins, and polyphenols prior to packaging. Brazilian industrial breweries are modernizing legacy lines with automated membrane skids to reduce manual handling and batch-to-batch variability.
- Clarification:Polishing filtration achieves visual brilliance and colloidal stability for premium positioning. Craft breweries in Germany specify 0.45-micron absolute ratings for export-grade portfolio extensions.
- Wastewater Treatment:Backwash recovery and effluent polishing systems manage EPA and EU discharge compliance.
- Carbonation:Membrane contactors and inline gas injection filtration ensure bubble consistency and microbial security in counter-pressure filling operations.
Beer production commands the installed base while clarification applications attract the steepest technology upgrade investment.
End User:
Scale tier dictates capital availability, technical staffing depth, and service contract willingness, fragmenting vendor go-to-market architectures.
- Industrial Breweries:Continuous-flow operations exceeding one million hectoliters annually demand redundant filtration trains and predictive maintenance contracts. Chinese and Brazilian greenfield projects are specifying integrated membrane-cleaning-in-place systems to minimize downtime.
- Craft Breweries:Batch-scale operations under 100,000 hectoliters prioritize modular skids with pilot-to-production scalability. US and German craft segments are driving crossflow adoption as waste reduction targets harden.
- Microbreweries:Sub-10,000 hectoliter operations rely on cartridge-based point-of-use solutions with minimal technical support requirements.
- Large Enterprises:Multi-site brewery groups centralize procurement through corporate technical standards and approved vendor lists.
Industrial breweries anchor capital equipment demand while craft breweries expand most quickly as a consumable revenue pool.
Technology:
Performance specification and energy intensity differentiate these process technologies, with pore size selectivity determining application fit.
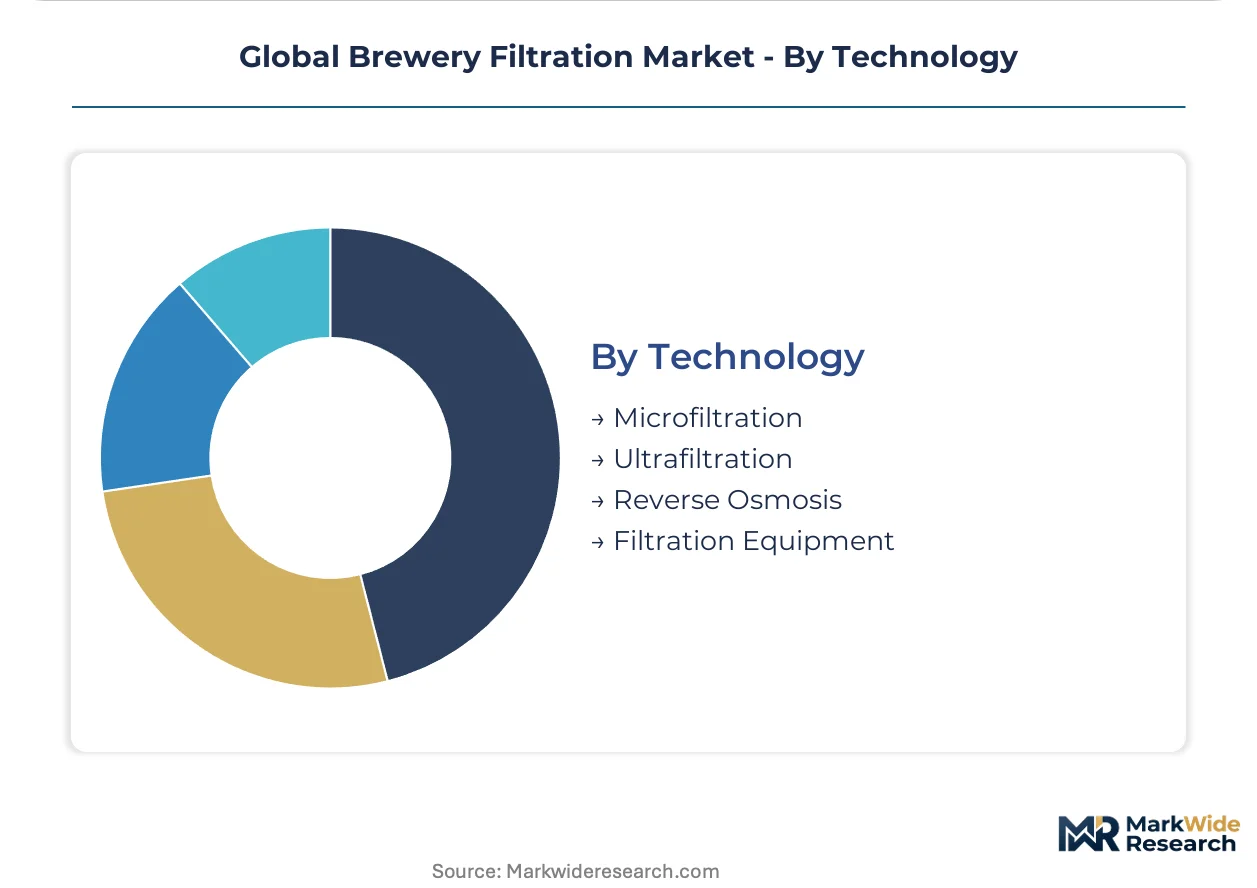
- Microfiltration:0.1 to 10 micron pore ratings retain yeast and bacteria while passing proteins and flavor compounds. This technology dominates cold sterilization applications across German lager production and US ale portfolios.
- Ultrafiltration:1 to 100 nanometer molecular weight cut-offs concentrate proteins and remove haze-forming polyphenols. Alcohol-free beer production lines in Brazil and China are adopting ultrafiltration for dealcoholization without thermal damage.
- Reverse Osmosis:Sub-nanometer rejection layers enable water demineralization and high-gravity brewing liquor adjustment.
- Filtration Equipment:Vessel housings, pump skids, and control automation form the fixed infrastructure layer.
Microfiltration holds the installed base while ultrafiltration climbs fastest on alcohol-free beer expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment fabrication and consumable manufacturing cluster heavily in Germany and the United States, while greenfield demand concentrates in China and Brazil as production capacity expands.
Germany
Bavarian craft breweries drive crossflow membrane adoption for shelf-stable export lagers. REACH chemical authorization from ECHA tightens purity specifications for polymeric filter media. Munich and Lower Bavaria host dense clusters of filtration system integrators serving both domestic brewers and Central European export markets.
United States
Craft brewery networks in Colorado and the Pacific Northwest pilot tangential-flow configurations to reduce diatomaceous earth waste. EPA effluent guidelines govern backwash wastewater handling protocols for filtration skids. Denver and Portland metropolitan areas concentrate equipment distributors and membrane cartridge regeneration service providers.
China
Industrial brewery greenfield installations in Shandong and Guangdong provinces specify automated membrane skids for continuous-flow operations. The Ministry of Ecology and Environment enforces discharge standards that elevate wastewater treatment filtration requirements. Qingdao and Zhuhai anchor manufacturing zones where local fabricators assemble filtration trains for domestic and Southeast Asian markets.
Brazil
Dealcoholization lines for alcohol-free beer portfolios drive ultrafiltration demand in São Paulo and Minas Gerais industrial zones. ANVISA pharmaceutical-grade standards for food-contact materials constrain imported membrane sourcing. Ribeirão Preto and Petrópolis house brewery technical centers where filtration upgrade decisions cascade to satellite production facilities.
India
Underpenetrated craft infrastructure in Maharashtra and Karnataka presents modular pilot-to-production scaling opportunities for membrane suppliers. FSSAI food safety notifications tighten microbial stability requirements for packaged beer. Bangalore and Pune microbrewery clusters generate early-stage demand for cartridge-based point-of-use clarification systems.
Global Brewery Filtration Market Vendor Landscape
Integrated filtration conglomerates and specialized membrane technology developers split the market into distinct capability tiers. The vendor base organizes around three strategic archetypes: diversified industrial equipment groups with brewery divisional focus, pure-play membrane technology specialists, and regional fabrication houses serving emerging market greenfield projects. Competitive maneuvering concentrates on captive regeneration service bundling and crossflow technology licensing arrangements.
Among diversified industrial equipment groups, Pall Corporation and Alfa Laval exemplify the integrated-service archetype, while GEA Group anchors the large-scale project engineering tier. These three entities represent contrasting geographic emphases and portfolio depths without overlapping strategic positioning.
| Leading Market Players |
|---|
| Pall Corporation (Danaher Corporation) |
| Alfa Laval |
| GEA Group |
| Krones AG |
| Sartorius AG |
| 3M |
| Pentair |
| Ziemann International GmbH |
| Eaton |
| Others |
Supply Flow & Price Mechanics
PFAS restrictions on membrane polymers determine both the premium-to-economy pricing spread and the geographic clustering of filter media fabrication. Regulatory chokepoints in Germany and the United States compress margins for non-compliant suppliers while elevating certified producers into premium tiers.
Pricing Analysis
REACH chemical authorization dictates the pricing tier structure across European procurement, separating FDA-cleared membrane systems from standard depth filtration on certification grade. Three-tier pricing structure across premium, standard, and economy levels stratifies by after-sales bundling intensity and regeneration service attachment. Cost compression in economy-tier cartridge replacements is intensifying because Chinese fabricators are expanding hollow-fiber capacity. Microbreweries exhibit acute price sensitivity, while industrial breweries with corporate technical standards absorb premium positioning for predictive maintenance contracts.
Supply Chain Analysis
Contract manufacturing for polymeric membrane substrates concentrates with specialized German and US chemical processors, while ceramic element fabrication clusters in Japanese and Chinese foundries. Raw material flows draw from fluoropolymer resin suppliers in the United States, diatomaceous earth miners in Denmark, and perlite processors in Greece. Single-source vulnerability runs through hollow-fiber spinning equipment held by a limited set of European engineering houses. Distribution runs through authorized system integrators in Munich, Denver, and Qingdao who bundle installation with lifecycle service agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brewery filtration demand tracks the capital expenditure cycle of greenfield brewery construction, with Chinese and Brazilian capacity additions signaling an upswing phase.
For Market Incumbents: Entrench crossflow technology leadership through captive regeneration service networks that lock in replacement cartridge demand. Pall Corporation and Alfa Laval anchor defensive positioning by controlling membrane-cleaning-in-place system specifications. Backward integration into hollow-fiber polymer extrusion mitigates PFAS sourcing risk. For New Entrants and Emerging Players: Build out modular pilot-to-production skids for Maharashtra and Karnataka craft brewery clusters where technical staffing constraints favor plug-and-play solutions. India's underpenetrated infrastructure presents the most penetrable geography. Lead with ISO 22000 qualification as a procurement gate for multinational brewery groups. For Investors and Strategic Acquirers: The market sits at a capacity-expansion phase that favors vertically integrated membrane specialists with regeneration capabilities. Long-term viability rests on sustainability metrics penetrating procurement scorecards. Acquisition targets should demonstrate captive service revenue attachment above industry norms. Monitor EPA effluent guideline enforcement intensity as an inflection signal for wastewater treatment filtration demand.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Regeneration Service Buildout | Vertically integrated membrane cleaning locks in recurring revenue streams across industrial brewery networks. |
| Crossflow Technology Licensing | Tangential-flow configurations reduce diatomaceous earth waste for German craft export lagers. |
| Greenfield Project Engineering Partnerships | Collaboration with Chinese and Brazilian EPC contractors secures automated skid specifications. |
| PFAS-Compliant Material Qualification | REACH and FDA food-contact certification opens premium procurement channels. |
| Modular Pilot-to-Production Scaling | Standardized skids address technical staffing constraints in India's emerging craft segments. |
Methodological Framework
Initial hypotheses were tested against primary input from brewery engineering directors, filtration system procurement managers, membrane cartridge regeneration service heads, and EPC project developers, and refined through secondary validation against SEC filings of diversified industrial equipment groups, customs records of filter media trade flows, EPA effluent guideline enforcement databases, and ECHA chemical authorization timelines. Bottom-up sizing of membrane and depth filtration unit demand triangulated against top-down capital expenditure patterns across greenfield brewery installations.
Demand-supply balance modeling across the projection horizon segmented by product type, application stage, end-user scale tier, and pore-size technology specification. CAGRs derived from regression analysis of historical equipment replacement cycles and consumable replenishment rates, with crossflow membrane adoption curves and alcohol-free beer production line expansion as industry-specific demand inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Chinese membrane fabricators or accelerated PFAS regulatory timelines would shift outcomes. Quarterly review of ECHA authorization schedules, EPA enforcement actions, and Chinese greenfield brewery permit approvals is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Organic Beer Market
Alcoholic Beverages
India Gin Market
Alcoholic Beverages
Germany Alcohol E-Commerce Market
Alcoholic Beverages
Low Alcohol Beverages Market
Alcoholic Beverages
Australia Alcohol E-Commerce Market
Alcoholic Beverages
Chardonnay Market
Alcoholic Beverages
North America Craft Beer Market
Alcoholic Beverages
Alcoholic Flavors Market
Alcoholic Beverages
Gin and Tonic Tea Market
Alcoholic Beverages
Automated Brewing System Market
Alcoholic Beverages
Asia-Pacific Wine Market
Alcoholic Beverages
Europe Beer Market
Alcoholic Beverages
Cannabis Drinks Market
Alcoholic Beverages
Light-Flavor Liquor Market
Alcoholic Beverages
Beer Filter System Market
Alcoholic Beverages
Canned Cocktails Market