
 Chardonnay Market | 2026-2036
Chardonnay Market Size, Share, and Industry Trends Forecast 2026-2036
Chardonnay Market Outlook
Burgundy is tilting toward precision viticulture and smaller-yield appellations to protect its premier cru positioning. Domaine Serene leverages extended lees-aging programs to sustain Oregon's reputation for mineral-driven expressions. Catena Zapata anchors high-altitude Mendoza plantings, competing on elevation-defined concentration. Bonterra differentiates through certified organic estate farming, controlling distribution through direct-to-trade channels in North American markets.
Chardonnay denotes a green-skinned grape variety yielding white wines ranging from lean, high-acid styles to rich, barrel-fermented expressions with malolactic complexity and alcohol levels typically between twelve and fifteen percent. The primary commercial purpose spans still table wine, sparkling base material, and premium bottle-aged offerings for hospitality and retail channels. Still wine occupies the largest volume pool across price tiers, while sparkling Chardonnay commands disproportionate margin concentration in super-premium and luxury segments. Oaked profiles retain dominance in mature North American markets, though unoaked and biodynamic classifications are gaining fastest in European specialist retail.
France's national wine regulator enforces Appellation d'Origine Contrôlée standards that restrict yields, grape sourcing, and winemaking methods for Chardonnay labeled by village or vineyard name. The EU Green Deal and F-Gas Regulation are tightening vineyard equipment emissions standards and refrigerant use in cellars, reshaping capital investment timelines for producers. California's state environmental quality act adds layer-specific compliance for new vineyard development in coastal zones. Stakeholders must monitor how carbon accounting rules and water allocation policies in key growing regions reshape site selection and long-term portfolio architecture.
Market Dynamics
EU Green Deal agricultural standards and California's coastal environmental quality act are forcing vineyard operators to recalibrate capital deployment timelines, site selection criteria, and long-term portfolio architecture across premium white wine segments.
Growth Catalysts
- Premium hospitality channel expansion:North American fine dining establishments are widening Chardonnay placements as wine-by-the-glass programs recover post-pandemic, driving volume through on-premise accounts.
- EU Green Deal certification pathways:Vineyard operators pursuing organic conversion timelines gain preferential access to EU distribution networks and retail shelf positioning in specialist channels.
- High-altitude Mendoza plantings:Elevation-defined concentration profiles from Argentine terroir are capturing export demand for mineral-driven expressions outside traditional Old World supply zones.
Market Restraints
- Oak barrel input cost volatility:French cooperage supply constraints and extended seasoning requirements for premium toast profiles compress margin structures for barrel-fermented production tiers.
- Water allocation policy tightening:California's State Water Resources Control Board restrictions on new agricultural groundwater use in coastal counties limit vineyard expansion in Sonoma and Central Coast sub-regions.
- Sparkling base substitution:Pinot Blanc and Aligoté plantings in Champagne and Crémant zones compete for acreage and cellar capacity as alternative white grape base materials.
Strategic Opportunities
- Biodynamic certification penetration:Demeter and Biodyvin standards command retail price premiums in German and Austrian specialist channels, creating margin expansion for compliant estate producers.
- Direct-to-trade channel development:Restaurant and hotel account relationships bypass traditional three-tier distribution economics in select US state markets, capturing value previously allocated to wholesale intermediaries.
- Extended lees-aging differentiation:Sur lie maturation programs of 18-24 months enable stylistic positioning against standard commercial releases in premium and super-premium price bands.
Industry Challenges
- Viticulture technician skill scarcity:Precision agriculture system operation and canopy management automation require cross-functional expertise combining agronomy and data analytics competencies that remain underdeveloped in traditional winegrowing labor pools.
- F-Gas Regulation compliance timelines:Cellar refrigeration equipment retrofits to meet EU fluorinated gas phase-down mandates demand capital outlays with uncertain payback periods given vintage-to-vintage volume variability.
- Appellation boundary litigation:Village-level expansion petitions in Burgundy's Côte de Beaune face multi-year administrative review and grower coalition opposition, freezing site development in contested zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chardonnay Market |
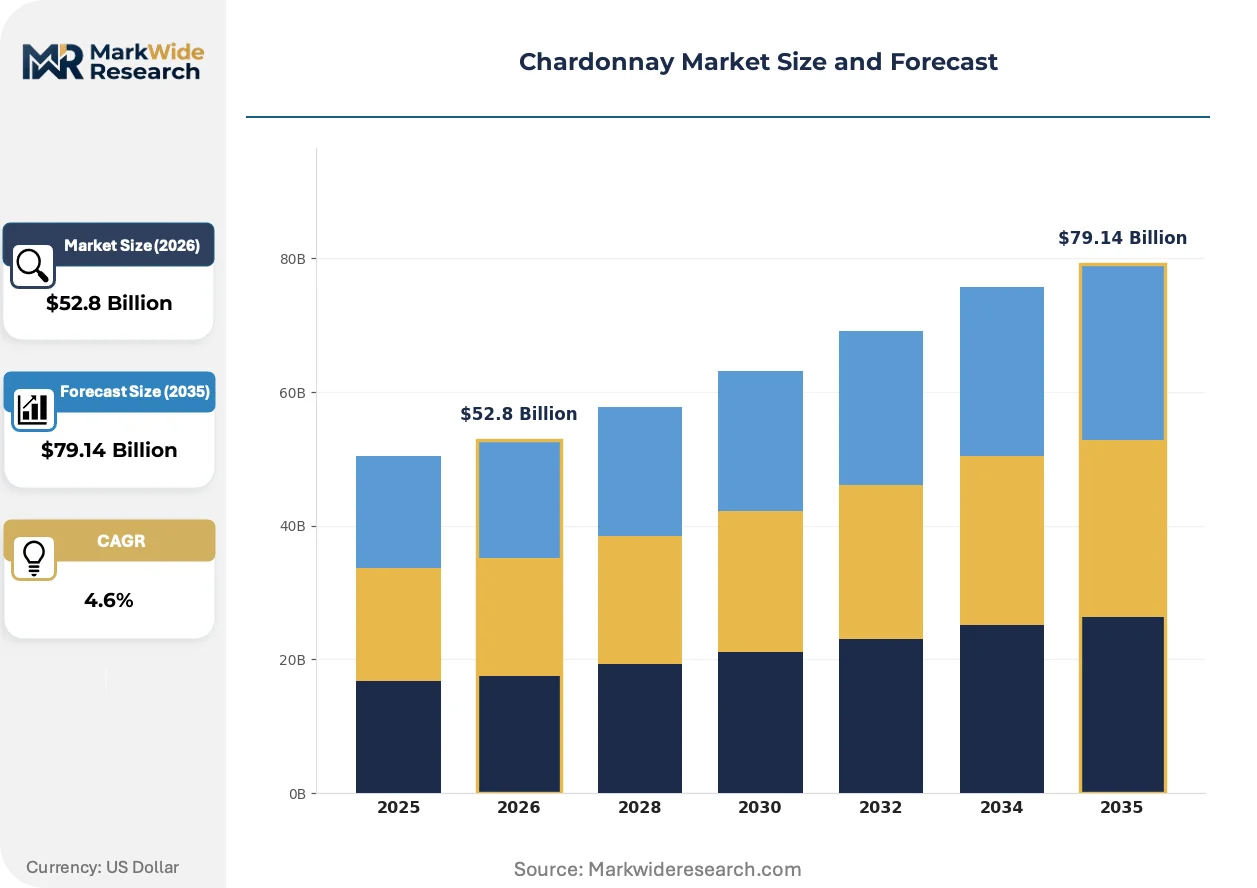
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $79.14 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sparkling, Still, Dessert, Fortified Origin: Burgundy, California, Australia, South Africa Profile: Oaked, Unoaked, Organic, Biodynamic Price Tier: Premium, Super Premium, Affordable, Luxury |
| Companies Covered | Jean-Marc Brocard, Darioush, Domaine Serene, Sidewood Estate, Bodega Chacra, Catena Zapata, Bonterra, 1276 Wines, Chateau Ste. Michelle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chardonnay Market Strategic Shifts
Precision viticulture systems and alternative vessel maturation protocols are compressing traditional winemaking timelines while enabling more granular site expression, forcing estate operators to reevaluate cellar infrastructure and labor deployment models.
Concrete egg fermentation vessels are hybridizing oak-derived texture with stainless steel purity, enabling mid-tier producers to simulate barrel complexity without cooperage capital intensity or extractive tannin load. Oregon's Willamette Valley estates have adopted these vessels at scale for premium Chardonnay lots, compressing the equipment payback window versus traditional barrique programs. The technology is hybridizing cost structures across premium price tiers while preserving stylistic differentiation.
France's national wine regulator has tightened Appellation d'Origine Contrôlée yield restrictions and mandatory grape sourcing radius rules for premier cru classifications, elevating compliance documentation burdens for négociant operations. Estate bottlers with controlled vineyard footprints gain structural advantage over blended cuvée producers in allocation negotiations with importers. Burgundy's village-level appellations face the most acute certification scrutiny, driving consolidation toward single-domaine labeling.
Specialist retail buyers in Northern European markets are unbundling traditional distributor relationships, establishing direct procurement contracts with certified organic and biodynamic estates. Copenhagen and Stockholm restaurant groups now source barrel samples through estate visits rather than portfolio tastings, displacing national importer selection authority. This channel compression is most visible in Denmark and Sweden, where alcohol retail monopolies have relaxed parallel import restrictions for on-premise licensed operators.
Chardonnay Market Segmentation
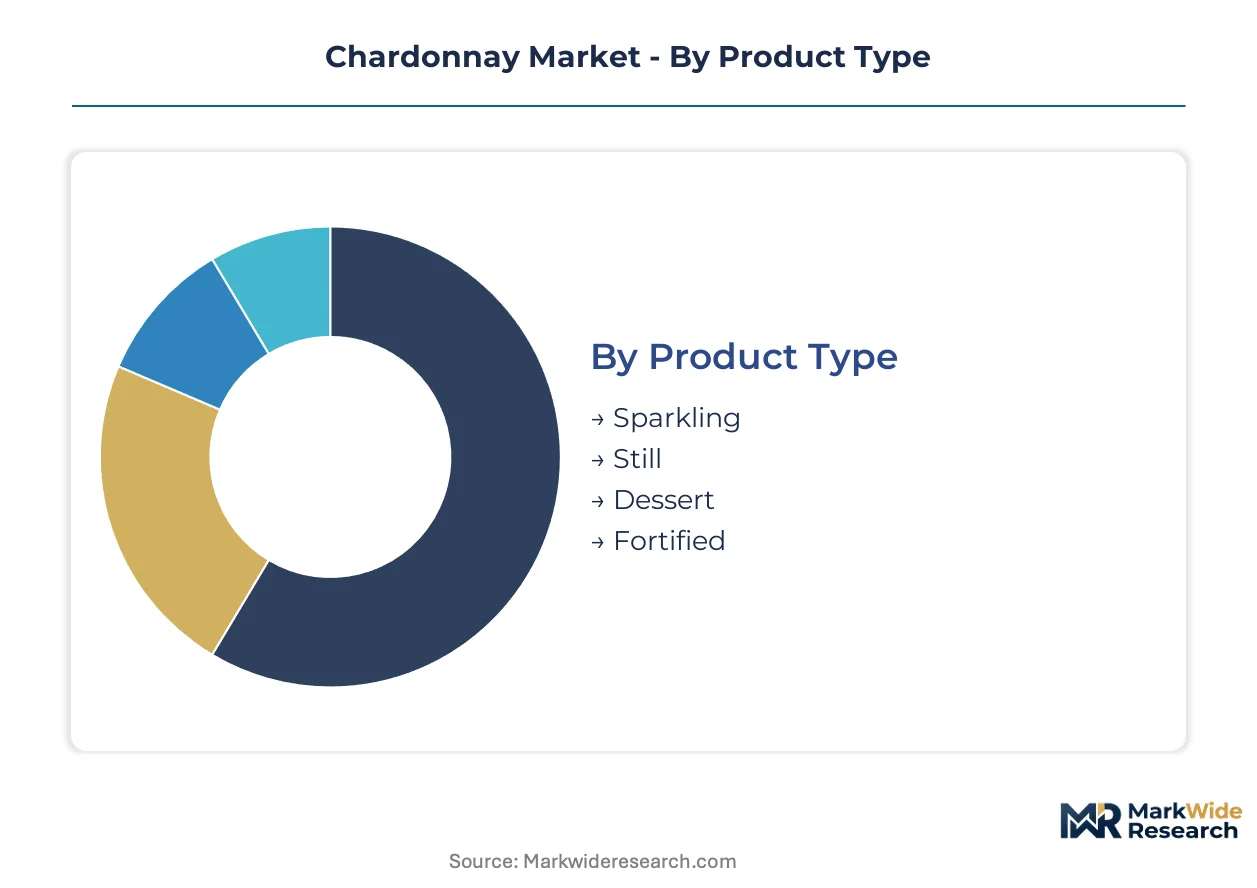
Chardonnay's stylistic versatility demands granular segmentation to capture how production methods, provenance, and price positioning align with diverging channel requirements and consumer preferences across hospitality and retail.
Product Type:
Still wine anchors commercial volume, while sparkling formats concentrate margin in prestige segments and dessert styles serve niche gastronomy channels.
- Still:Fermented to dryness without secondary carbonation, still Chardonnay spans lean stainless-steel expressions to barrel-fermented wines with malolactic softness. California's Central Coast and Sonoma County sub-regions concentrate plantings for this category, constrained by State Water Resources Control Board groundwater restrictions on new vineyard development.
- Sparkling:Base wines undergo secondary fermentation in bottle or tank, yielding pressure levels from 1-6 atmospheres depending on method. Champagne AOC regulations and Crémant appellation standards in France enforce geographic and varietal sourcing rules that limit expansion, with Pinot Blanc and Aligoté competing for acreage in traditional zones.
- Dessert:Late-harvest or botrytized expressions with elevated residual sugar target fine dining dessert pairings.
- Fortified:Spirit addition arrests fermentation, preserving sweetness at elevated alcohol levels for after-dinner service.
Established volume favors Still; emerging adoption favors Sparkling.
Origin:
Terroir expression and regulatory frameworks differentiate sourcing zones, with elevation and soil composition driving stylistic positioning in export markets.
- Burgundy:Appellation d'Origine Contrôlée standards enforce village-level yield restrictions and mandatory grape sourcing radius rules for premier cru classifications. France's national wine regulator has tightened documentation burdens, elevating structural advantage for estate bottlers with controlled vineyard footprints over négociant blenders.
- California:Coastal environmental quality act compliance adds layer-specific requirements for new vineyard development in Sonoma and Central Coast sub-regions. Water allocation policy tightening limits expansion, concentrating demand in established plantings with grandfathered groundwater rights.
- Australia:Margaret River and Yarra Valley regions concentrate cool-climate expressions with pronounced acidity profiles.
- South Africa:Walker Bay and Elgin sub-regions leverage Benguela current influence for restrained, mineral-driven styles.
Prestige positioning concentrates in Burgundy; volume scalability centers on California.
Profile:
Winemaking protocol selection determines texture, aromatic development, and certification eligibility for specialist retail channels.
- Oaked:Barrel fermentation and maturation introduce toast-derived vanilla, spice, and textural weight through lees contact and controlled oxidation. North American fine dining establishments favor this profile for wine-by-the-glass programs, though French cooperage supply constraints compress margin structures.
- Unoaked:Stainless steel or neutral vessel fermentation preserves primary fruit aromatics and crisp acidity. European specialist retail channels in Germany and Austria show steepest expansion trajectory for this category as consumers seek lighter, food-versatile expressions.
- Organic:Certified estate farming without synthetic pesticides or fertilizers qualifies for EU Green Deal preferential distribution access.
- Biodynamic:Demeter and Biodyvin standards command retail price premiums through enhanced soil vitality protocols and lunar calendar adherence.
Channel placement differentiates Oaked from Unoaked; certification premiums separate Organic from Biodynamic.
Price Tier:
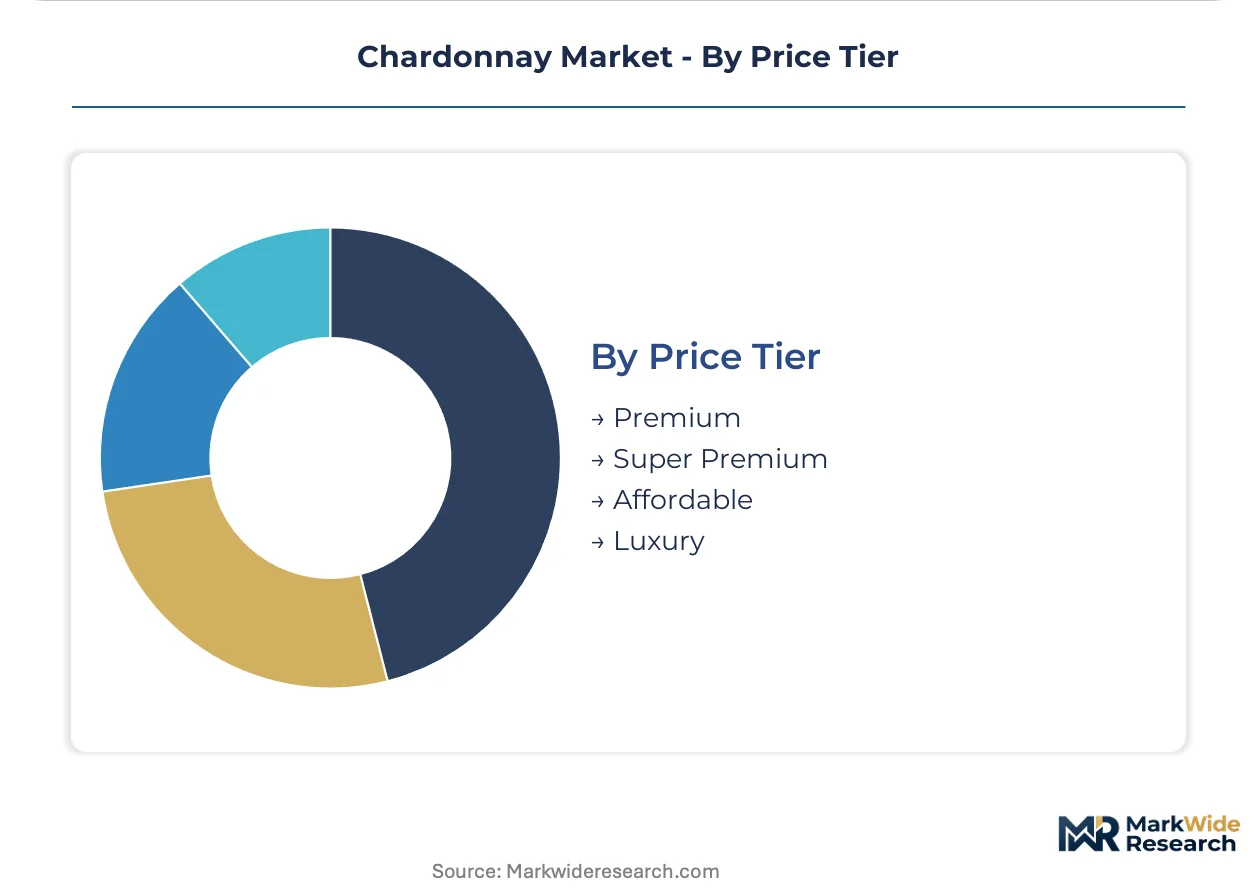
Production scale, vineyard provenance, and aging regimen stratify offerings across mass retail, on-premise, and collector markets.
- Affordable:High-volume commercial releases from warm-climate regions prioritize consistency and immediate drinkability over site expression. This tier supplies supermarket chains and casual dining accounts where turnover velocity outweighs provenance storytelling.
- Premium:Single-vineyard or regional appellation wines with controlled yields and modest oak integration target independent retail and mid-tier hospitality. Extended lees-aging programs of 18-24 months enable stylistic positioning against standard commercial releases in this band.
- Super Premium:Limited-production estate bottlings from recognized terroirs with extended maturation protocols serve specialist merchants and fine dining wine lists.
- Luxury:Grand cru Burgundy and icon-level New World expressions with provenance documentation and bottle-aging programs target auction markets and private client portfolios.
Volume concentration sits with Affordable; margin expansion concentrates in Super Premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vineyard acreage clusters in coastal valleys and continental river basins where diurnal temperature swings preserve acidity. Regulatory frameworks governing water access and chemical inputs are redrawing viable planting zones faster than climate migration alone.
France
Burgundy's premier cru vineyards command allocation premiums through Appellation d'Origine Contrôlée yield restrictions. The EU Green Deal tightens vineyard equipment emissions standards and refrigerant phase-down timelines under F-Gas Regulation. Chablis and Meursault sub-regions concentrate estate bottling operations as négociant blending faces documentation burdens.
United States
California's Central Coast and Sonoma County sub-regions drive premium hospitality channel placements as wine-by-the-glass programs expand. The State Water Resources Control Board restricts new agricultural groundwater use in coastal counties, freezing expansion for unpermitted sites. Napa Valley and Russian River Valley clusters leverage grandfathered water rights to maintain production scale.
Argentina
High-altitude Mendoza plantings at 1,400-1,600 meters elevation capture export demand for mineral-driven expressions. The national wine institute enforces geographic indication standards that block non-Mendoza labeling for elevation-designated wines. Uco Valley sub-regions concentrate new plantings as producers compete on concentration metrics defined by terroir altitude.
Australia
Margaret River and Yarra Valley cool-climate expressions penetrate Northern European specialist retail with pronounced acidity profiles. The country's national wine regulator administers export certification requirements that verify chemical residue thresholds for EU-bound shipments. Adelaide Hills and Mornington Peninsula clusters expand biodynamic conversion programs to qualify for premium channel access.
South Africa
Walker Bay and Elgin sub-regions leverage Benguela current influence for restrained, mineral-driven styles targeting UK and Scandinavian markets. The country's agricultural standards authority enforces integrated production protocols that restrict synthetic pesticide use near protected water catchments. Stellenbosch and Franschhoek valleys concentrate estate operations with controlled distribution through direct-to-trade channels.
Chardonnay Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in vineyard management and cooperage supply. The producer base stratifies between estate bottlers with controlled acreage and négociant blenders sourcing across multiple appellations. Three archetypes dominate: terroir-defined estate houses, scale-oriented regional brands, and certification-driven organic specialists. Competitive moves center on biodynamic conversion timelines and direct-to-trade channel development that bypasses traditional import tiers.
Among Old World estate producers, Jean-Marc Brocard occupies a position exemplifying Chablis precision viticulture, while Domaine Serene represents the New World elevation-defined archetype through Willamette Valley operations. Catena Zapata anchors the high-altitude concentration narrative for Argentine supply, sitting within the elevation-specialist tier that competes on altitude-derived extract metrics.
| Leading Market Players |
|---|
| Jean-Marc Brocard |
| Darioush |
| Domaine Serene |
| Sidewood Estate |
| Bodega Chacra |
| Catena Zapata |
| Bonterra |
| 1276 Wines |
| Chateau Ste. Michelle |
| Others |
Value Chain & Pricing Dynamics
French cooperage concentration in Limousin and Vosges forests anchors barrel input costs for premium Chardonnay tiers, concentrating margin pressure on producers dependent on extended lees-aging programs. This upstream bottleneck feeds downstream into pricing power stratification between estate bottlers with captive oak programs and négociant blenders exposed to spot cooperage markets.
Pricing Analysis
EU Green Deal certification dictates the pricing tier structure by mandating organic conversion documentation for shelf access in German and Austrian specialist retail. Three-tier pricing separates biodynamic estate releases from standard organic classifications from conventional commercial tiers. Price differentiation hinges on certification grade and vineyard provenance documentation. Cost compression in super-premium barrel-fermented tiers is intensifying because French oak supply constraints extend seasoning timelines. Casual dining accounts exhibit highest price sensitivity; luxury auction markets demonstrate lowest.
Supply Chain Analysis
Barrel stave feedstock draws from French, American, and Hungarian oak forests with divergent toast profile specifications. Vineyard labor pools, precision viticulture equipment, and cellar refrigeration hardware constitute critical input dependencies. Single-source vulnerability concentrates in French premier cru fruit contracts where appellation boundary litigation freezes expansion. Distribution runs through three-tier wholesale networks in US markets and direct-to-trade channels in Scandinavian alcohol monopoly jurisdictions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chardonnay incumbents face substitution defense against high-altitude Mendoza plantings and concrete egg fermentation alternatives that simulate barrel complexity without cooperage capital intensity. Pinot Blanc and Aligoté sparkling base materials compete for acreage in traditional Champagne zones.
For Market Incumbents: Entrench appellation-controlled vineyard footprints through backward integration into premier cru sites in Burgundy's Côte de Beaune. Accelerate biodynamic certification timelines to capture Demeter price premiums in Northern European specialist channels. Defend against concrete egg substitution by emphasizing extended lees-aging provenance in allocation negotiations with direct-to-trade restaurant accounts. For New Entrants and Emerging Players: Build out certified organic estate operations in California's Central Coast sub-regions where State Water Resources Control Board restrictions have frozen incumbent expansion. Target unoaked stainless-steel expressions for German and Austrian retail channels showing steepest adoption trajectory. Establish direct procurement relationships with Copenhagen and Stockholm restaurant groups bypassing traditional importer tiers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional brand aggregators seeking biodynamic conversion capex for margin expansion. Long-term viability centers on water-rights grandfathered properties in Sonoma County and elevation-designated Mendoza plantings above 1,400 meters. Watch F-Gas Regulation compliance timelines as inflection indicator for cellar refrigeration retrofit burdens.| Strategic Initiative | Industry Significance |
|---|---|
| Biodynamic Certification Program | Demeter standards unlock retail price premiums in German specialist channels. |
| Direct-to-Trade Channel Development | Restaurant account relationships bypass three-tier distribution economics in select US states. |
| Extended Lees-Aging Investment | Sur lie programs of 18-24 months differentiate against standard commercial releases. |
| High-Altitude Vineyard Acquisition | Uco Valley plantings above 1,400 meters compete on elevation-defined concentration metrics. |
| Alternative Vessel Fermentation | Concrete egg adoption compresses equipment payback versus traditional barrique programs. |
Study Parameters
The analysis maps still wine, sparkling base, and dessert style sub-sectors, each validated through winemaking directors, vineyard managers, specialist retail buyers, and hospitality procurement leads. Primary fieldwork combined with secondary validation against EU Green Deal regulatory filings, Appellation d'Origine Contrôlée documentation, and customs export certification records. Bottom-up volume triangulation against top-down value estimates anchored the sizing framework.
Assumptions held regulatory compliance timelines and water allocation policy trajectories fixed across the projection horizon while varying organic conversion adoption rates and direct-to-trade channel penetration. Segmentation dimensions modeled include product type, origin terroir, winemaking profile, and price tier positioning. CAGRs derived from vintage volume variability patterns and hospitality channel recovery trajectories. Forecast inputs incorporated groundwater restriction enforcement intensity and F-Gas Regulation retrofit compliance schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by elevation-specialist Argentine entrants or concrete egg technology adopters would shift outcomes. Cross-checking against EU distribution network allocation data and US state-by-state three-tier regulatory variations is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Balsam Bottle Market
Alcoholic Beverages
Germany Wine Coolers Market
Alcoholic Beverages
Europe Kegs Market
Alcoholic Beverages
South America Beer Market
Alcoholic Beverages
Asia-Pacific Spirits Market
Alcoholic Beverages
N-Hexyl Alcohol Market
Alcoholic Beverages
Asia-Pacific Tequila Market
Alcoholic Beverages
Canned Alcoholic Beverages Market
Alcoholic Beverages
Fruit Wine Market
Alcoholic Beverages
Japan Tequila Market
Alcoholic Beverages
Europe Wine Coolers Market
Alcoholic Beverages
Europe Craft Spirits Market
Alcoholic Beverages
Drinkware, Beverageware, and Barware Market
Alcoholic Beverages
Middle East and Africa Wine Market
Alcoholic Beverages
Beer Kegs Market
Alcoholic Beverages
Asia Pacific Beer Market