
 Canned Cocktails Market | 2026-2036
Canned Cocktails Market Size, Share, and Industry Trends Forecast 2026-2036
Canned Cocktails Market Analysis
Outdoor entertainment and at-home social occasions is consolidating as the dominant demand vector for canned cocktails, displacing traditional on-premise bar visits. Bacardi Limited leverages its Caribbean rum heritage to anchor tropical-flavored offerings in beach and festival channels. Diageo competes through spirits-backed authenticity, while The Boston Beer Company specializes in hard seltzer-cocktail hybrids that occupy the premium convenience tier.
Canned cocktails are pre-mixed alcoholic beverages sealed in single-serve containers, typically containing distilled spirits, carbonated or still mixers, and flavoring agents at 4-12% ABV, manufactured through cold-fill or tunnel-pasteurization processes to preserve volatile aromatics without preservatives. Their primary commercial purpose is delivering consistent, portable bar-quality drinking experiences outside licensed premises. Hard seltzers dominate volume due to lower calorie positioning and broader retail authorization, while spirits-based beverages command margin concentration through premium pricing and aged-liquor credibility. Sparkling wine cocktails sustain niche growth in celebratory and female-skewing segments where packaging aesthetics drive gift and occasion purchasing.
The U.S. TTB governs formula approval, labeling, and interstate commerce, creating compliance barriers that favor established distillers with regulatory infrastructure over new entrants. State-level three-tier system variations and direct-to-consumer shipping restrictions fragment market access, compelling brands to navigate distributor relationships or invest in state-by-state licensing. The EU's Food Information to Consumers Regulation and member-state alcohol marketing restrictions shape formulation transparency and promotional channels across Europe. Stakeholders must monitor evolving low- and no-alcohol tax classifications and deposit-return packaging mandates, as these policy shifts will determine which product architectures and geographic bets yield sustainable returns.
Market Dynamics
The portable beverage category is consolidating around spirits-authenticated formulations as consumers reject malt-based dilutions, forcing manufacturers to secure TTB formula approvals and cold-fill production lines that preserve volatile aromatics without chemical preservatives.
Growth Catalysts
- Direct-to-Shipper Liberalization:State-level reforms in California, New York, and Texas are dismantling three-tier system barriers, enabling craft distillers to bypass distributor markups and capture margin directly from festival and beach-channel consumers.
- Carbonation Technology:Tunnel-pasteurization systems now stabilize 8-12% ABV formulations without heat degradation, allowing authentic aged-spirit character in shelf-stable formats previously dominated by fermented malt beverages.
- Festival Economy Expansion:Outdoor entertainment venues in Florida, Nevada, and Tennessee are replacing draft beer installations with canned cocktail refrigeration, converting on-premise consumption into portable brand discovery moments.
Market Restraints
- Aluminum Tariff Volatility:Input costs for 12oz and 16oz can stock fluctuate with Section 232 trade policy adjustments, compressing margins for mid-tier brands lacking long-term smelter contracts.
- TTB Formula Backlogs:The Alcohol and Tobacco Tax and Trade Bureau's 90-180 day approval timelines for new distilled-spirit formulations delay seasonal product launches and tie up working capital in inventory.
- Hard Seltzer Substitution:Lower-calorie, broader-retail-authorized malt beverages capture convenience-store shelf space and price-sensitive trial purchases, constraining spirits-based volume in mass channels.
Strategic Opportunities
- Low-No Alcohol Tax Reclassification:Pending FDA guidance on sub-0.5% ABV distilled-spirit derivatives could unlock grocery and pharmacy distribution channels currently restricted to licensed retailers.
- Deposit-Return Packaging Mandates:Oregon, Maine, and Vermont's extended producer responsibility laws favor aluminum formats with established recycling infrastructure, penalizing glass-dependent competitors.
- Aged-Liquor Hybrid Formats:Barrel-finished expressions and cask-strength reductions are converging with RTD convenience, creating premium tier pricing previously unavailable in single-serve containers.
Industry Challenges
- Cold-Chain Logistics Fragmentation:Distributor networks built for ambient-stable beer lack refrigerated last-mile capacity, forcing brands to invest in dedicated fleet partnerships or accept quality degradation.
- Flavor Chemist Scarcity:Formulation expertise that balances TTB-compliant ingredient declarations with volatile aromatic stability commands premium compensation, constraining R&D throughput for emerging brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canned Cocktails Market |
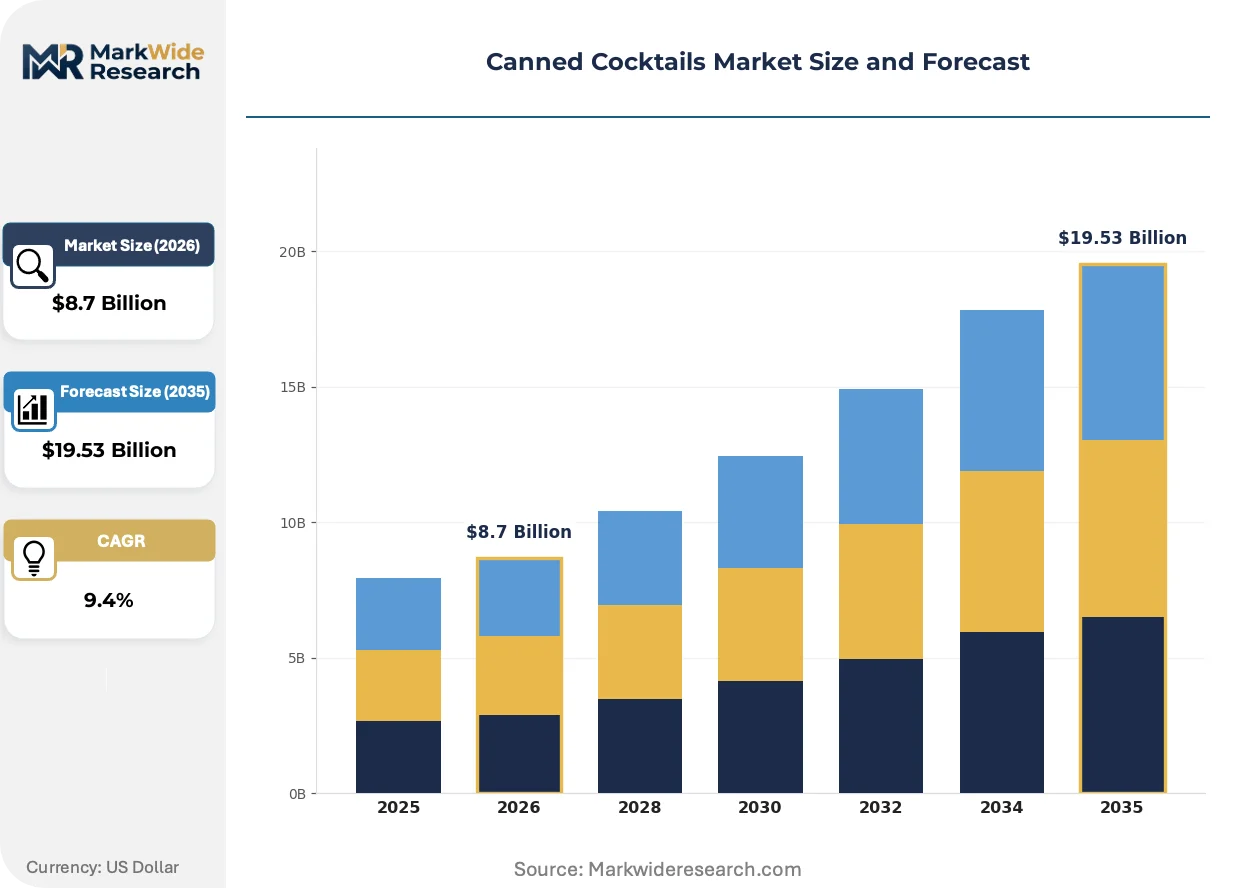
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hard Seltzers, Pre-Mixed Cocktails, Sparkling Wine Cocktails, Spirits-Based Beverages Flavor Profile: Citrus, Berry, Herbal, Spicy Packaging Type: Aluminium Cans, Glass Cans, Eco-Friendly Packaging, PET Cans Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Specialty Liquor Stores |
| Companies Covered | Pernod Ricard, Bacardi Limited, Anheuser-Busch InBev, Suntory, The Boston Beer Company, Diageo, Constellation Brands, Campari Group, Brown-Forman, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canned Cocktails Market Emerging Trajectories
Formulation science and regulatory navigation are separating viable competitors from commodity players, with three distinct vectors reshaping how bar-quality experiences translate into shelf-stable formats.
Cold-fill aseptic packaging is converging with nitrogen-dosing systems to eliminate oxygen exposure during sealing, preserving delicate botanical top notes in gin and tequila formulations that previously required on-premise fresh mixing. Premium distillers in California and Texas are retrofitting brewery assets with these hybrid lines, compressing the quality gap between canned and craft-cocktail preparation. The structural consequence is margin compression for brands still relying on tunnel-pasteurization heat treatments that flatten aromatic complexity.
The EU's Food Information to Consumers Regulation is mandating ingredient disclosure and allergen labeling for imported RTD beverages, forcing reformulation of US-origin products containing caramel colorings and artificial flavor carriers. German and Dutch customs authorities are rejecting shipments that fail updated nutritional declaration standards, diverting trade flows toward compliant domestic European production. Spirits-backed brands with clean-label architectures are capturing shelf space as retailers preempt enforcement with stricter procurement filters.
Festival organizers are unbundling beverage service from venue operators, issuing exclusive pouring rights to canned-cocktail sponsors who provide refrigerated infrastructure and staff training. This procurement model displaces open-bar arrangements and draft beer minimums at Coachella, Bonnaroo, and Austin City Limits, converting temporary permits into multi-year brand partnerships. The shift is most visible in sun-belt states where outdoor season extension maximizes sponsorship ROI against fixed compliance costs.
Canned Cocktails Market Segmentation
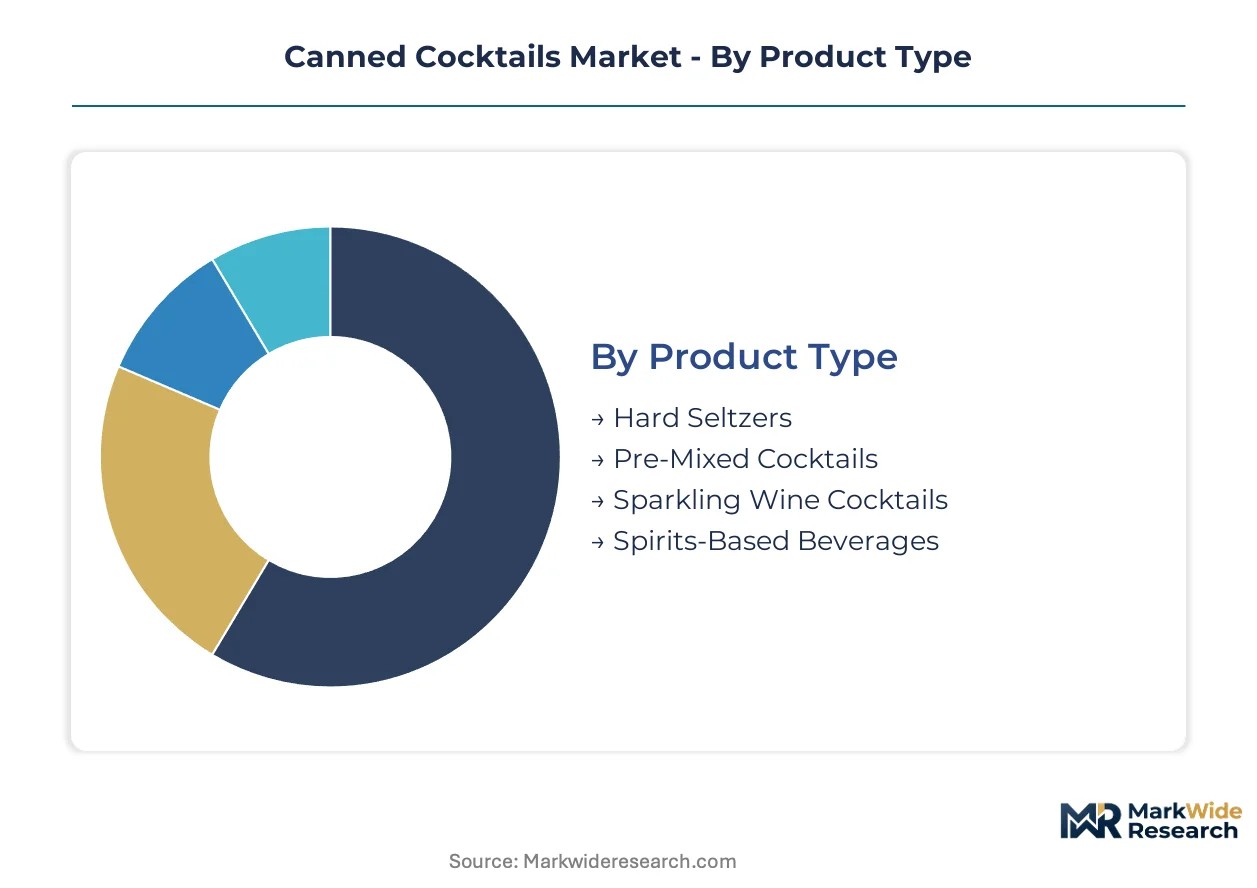
Canned cocktail manufacturers configure product architectures around four intersecting dimensions. Each dimension carries distinct regulatory, margin, and channel implications that determine which formulations reach festival coolers versus grocery shelves.
Product Type:
Supply concentration favors spirits-authenticated production lines with TTB formula approvals and cold-fill capability, marginalizing malt-based commodity players.
- Hard Seltzers:Fermented malt or sugar bases at 4-6% ABV with carbonated water and natural flavors. Demand clusters in convenience stores and beach venues where calorie-conscious trial drives volume, though margin compression from brand proliferation constrains profitability.
- Pre-Mixed Cocktails:Distilled spirits blended with verified mixers at 8-12% ABV, requiring tunnel-pasteurization or nitrogen-dosing preservation. Festival organizers in Florida and Nevada are converting exclusive pouring rights into multi-year partnerships for margarita and mule formulations.
- Spirits-Based Beverages:Authentic aged-liquor expressions with barrel-finished or cask-strength reductions.
- Sparkling Wine Cocktails:Wine-spritzer hybrids targeting celebratory and gift occasions with aesthetic packaging.
Today's leader: Hard Seltzers. Tomorrow's challenger: Pre-Mixed Cocktails.
Flavor Profile:
Cost tier separation is pronounced, with natural extract formulations commanding premium shelf placement against artificial flavor competitors.
- Citrus:Lime, grapefruit, and yuzu profiles dominate summer seasonal rotations. German and Dutch retailers are rejecting US-origin citrus formulations containing non-compliant caramel colorings under EU Food Information to Consumers Regulation mandates.
- Berry:Raspberry, blackberry, and açaí variants skew female and gift-purchasing demographics.
- Herbal:Botanical infusions requiring nitrogen-dosing systems to preserve volatile top notes.
- Spicy:Jalapeño, ginger, and tajín expressions capturing Latin flavor migration.
Premium extraction methods separate citrus and berry winners from commodity followers.
Packaging Type:
Volume throughput favors aluminum formats with established recycling infrastructure under extended producer responsibility laws.
- Aluminium Cans:Standard 12oz and 16oz formats with established smelter contracts insulating against Section 232 tariff volatility. Oregon, Maine, and Vermont deposit-return mandates penalize alternatives lacking closed-loop recycling.
- Eco-Friendly Packaging:Recycled-content aluminum and biodegradable liners meeting retailer procurement filters.
- Glass Cans:Premium aesthetic formats with higher logistics costs.
- PET Cans:Lightweight alternatives with limited spirits-category adoption.
Aluminium Cans hold current volume. Eco-Friendly Packaging is climbing the fastest.
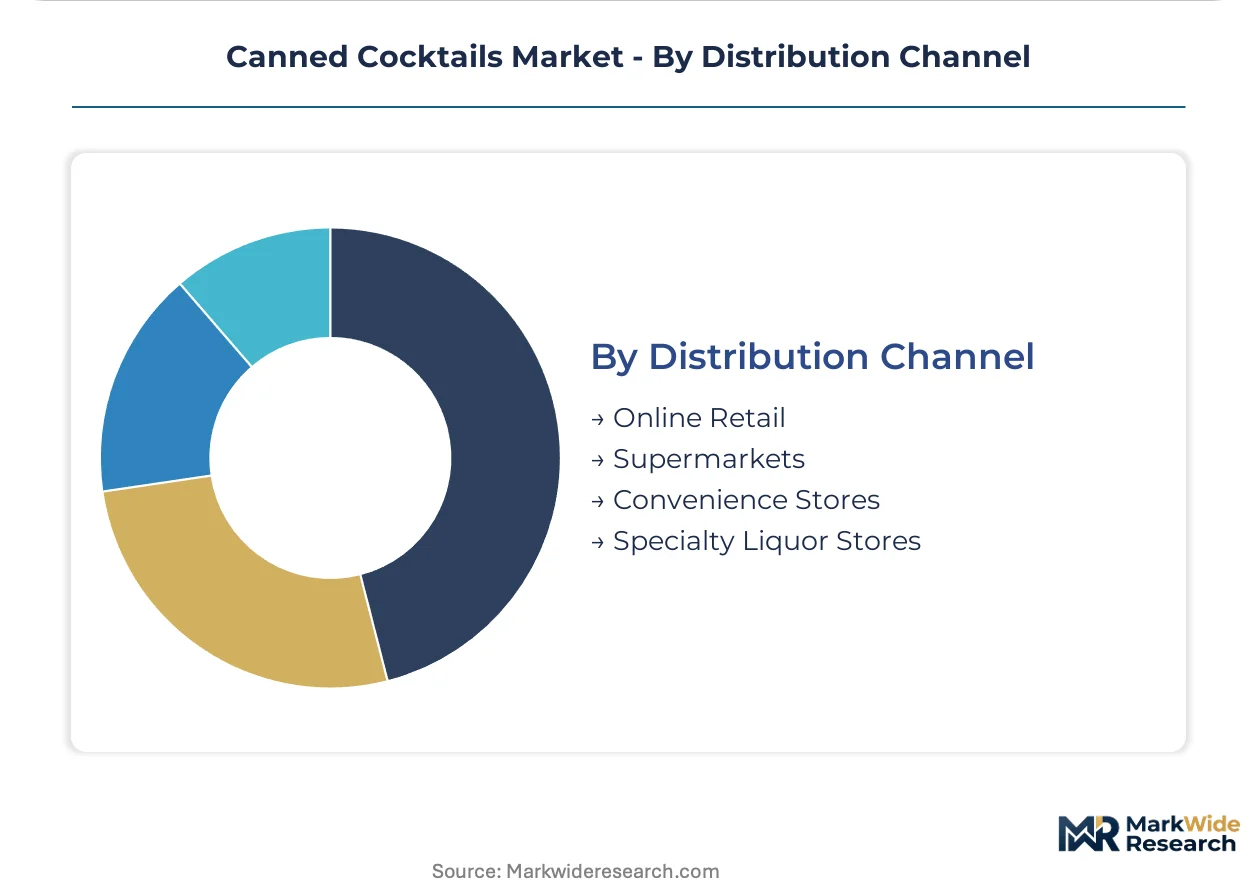
Distribution Channel:
Customer type stratification separates licensed-premise specialists from mass-channel generalists.
- Specialty Liquor Stores:Curated spirits-authenticated selections with staff training and refrigerated display. California, New York, and Texas direct-to-shipper liberalization is enabling craft distillers to bypass distributor markups here.
- Online Retail:State-by-state licensing navigation with three-tier system workarounds.
- Supermarkets:Mass-volume authorization constrained by licensed-retailer requirements in most jurisdictions.
- Convenience Stores:Hard seltzer and malt-beverage dominance with spirits-based volume restrictions.
Specialty Liquor Stores anchor premium positioning. Online Retail shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Austin-Round Rock metro anchors North American canned cocktail innovation, where festival economics and direct-to-shipper liberalization concentrate brand development infrastructure. National demand patterns diverge sharply across regulatory environments, with state-level alcohol commerce laws determining market access depth.
United States
Millennial and Gen-Z consumers at Florida beach venues and Nevada festival circuits drive spirits-authenticated demand. The TTB's 90-180 day formula approval timelines constrain seasonal product velocity. California, New York, and Texas direct-to-shipper reforms enable craft distillers to bypass distributor markups and capture margin directly from outdoor entertainment channels.
Germany
Clean-label procurement filters at Berlin and Munich retailers favor compliant formulations over US-origin imports. The EU Food Information to Consumers Regulation mandates ingredient disclosure and allergen labeling that rejects caramel-coloring formulations. Hamburg customs authorities enforce updated nutritional declaration standards, diverting trade flows toward domestic European production.
United Kingdom
Premium convenience culture in London and Manchester sustains hard seltzer and spirits-based hybrid demand. The UK Alcohol Duty Reform introduces tiered taxation based on ABV content, reshaping formulation economics. Scotland's distilling heritage clusters near Edinburgh and Glasgow are spawning RTD spinoffs from established whisky houses.
Japan
Chu-hi culture and convenience store density in Tokyo and Osaka sustain single-serve alcoholic beverage penetration. METI guidelines on low-alcohol marketing shape promotional channel access. Suntory and Kirin production facilities in the Kanto region supply nitrogen-dosing preservation technology for botanical-forward formulations.
Australia
Outdoor festival economics in New South Wales and Queensland mirror US beach-channel demand patterns. State-level liquor licensing variations create fragmented retail authorization. Melbourne's craft distilling corridor is retrofitting brewery assets with cold-fill aseptic lines to serve Asia-Pacific export markets.
Canned Cocktails Market Vendor Landscape
Strategic partnerships dominate the current landscape as established distillers and beverage conglomerates converge on festival sponsorship and co-manufacturing arrangements. The vendor base stratifies across three tiers: multinational spirits houses with TTB infrastructure, regional craft distillers leveraging direct-to-shipper liberalization, and hard seltzer specialists with mass-channel authorization. Two archetypes command disproportionate influence: heritage distillers extending aged-liquor credibility into RTD formats, and fermentation-platform companies hybridizing seltzer economics with cocktail positioning. Portfolio diversification and cold-fill capacity expansion represent the dominant competitive moves, with brands racing to secure nitrogen-dosing production lines before flavor chemist scarcity constrains R&D throughput.
Within the heritage distiller archetype, Bacardi Limited and Brown-Forman occupy positions that exemplify Caribbean rum and American whiskey lineage translation into portable formats. Diageo anchors the multinational tier with spirits-backed authenticity claims that bypass malt-based dilution skepticism. The Boston Beer Company represents the hybridization vector, where hard seltzer platform economics converge with cocktail flavor migration to capture premium convenience demand.
| Leading Market Players |
|---|
| Pernod Ricard |
| Bacardi Limited |
| Anheuser-Busch InBev |
| Suntory |
| The Boston Beer Company |
| Diageo |
| Constellation Brands |
| Campari Group |
| Brown-Forman |
| Others |
Supply Flow & Price Mechanics
Festival procurement mandates for refrigerated infrastructure and exclusive pouring rights are forcing brands to absorb fixed compliance costs upfront, compressing working capital and pushing mid-tier players toward contract manufacturing partnerships that sacrifice margin for speed-to-shelf.
Pricing Analysis
Aluminum tariff exposure from Section 232 trade policy adjustments passes directly into input costs for 12oz and 16oz can stock, with brands lacking long-term smelter contracts bearing the steepest compression. Three-tier pricing structure across premium spirits-authenticated, standard malt-based, and economy private-label levels separates winners by TTB formula approval status and cold-fill capability. Pricing pressure stems from hard seltzer substitution in convenience channels, where broader retail authorization and lower calorie positioning capture trial purchases. Mass-channel buyers exhibit highest price sensitivity, while festival organizers and specialty liquor stores prioritize provenance and aromatic stability over per-unit cost.
Supply Chain Analysis
Domestic-content mandates in Oregon, Maine, and Vermont under extended producer responsibility laws favor aluminum formats with established closed-loop recycling infrastructure, penalizing glass-dependent competitors and reshaping can sourcing toward domestic smelters. Manufacturing concentration centers on California, Texas, and Florida, where retrofit brewery assets and nitrogen-dosing production lines cluster near festival and beach-channel demand. Raw material dependencies span aluminum can stock, natural flavor extracts, and aged-spirit inventory carrying TTB bond requirements. Single-source vulnerability runs through flavor chemist expertise that balances compliant ingredient declarations with volatile aromatic stability. Distribution runs through distributor networks built for ambient-stable beer, forcing dedicated refrigerated fleet partnerships or quality degradation acceptance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns for players who navigate regulatory infrastructure as a competitive moat, with the TTB's formula approval timelines and state-level direct-to-shipper liberalization creating divergent fates for compliant versus exposed operators.
For Market Incumbents: Lock in nitrogen-dosing production capacity and TTB formula backlogs as defensive barriers against craft distiller encroachment. Secure long-term aluminum smelter contracts to neutralize Section 232 tariff volatility. Deepen backward integration into barrel-finishing and cask-strength reduction capabilities to anchor premium tier pricing against malt-based dilution. For New Entrants and Emerging Players: Cold-fill aseptic technology with nitrogen-dosing systems offers the most penetrable wedge for authentic aged-spirit character in shelf-stable formats. Target direct-to-shipper liberalization corridors in California, New York, and Texas where three-tier system bypass captures margin from festival and beach-channel consumers. Lead with clean-label architectures compliant with EU Food Information to Consumers Regulation to preempt retailer procurement filters. For Investors and Strategic Acquirers: Asymmetric upside sits with craft distillers possessing TTB infrastructure and state-by-state licensing navigation capabilities, positioned to exploit direct-to-shipper liberalization before incumbent distributor relationships reconfigure. Long-term viability hinges on regulatory compounder status rather than brand equity alone. Watch for FDA guidance on sub-0.5% ABV distilled-spirit derivatives as inflection signal for grocery and pharmacy channel expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Fill Capacity Expansion | TTB-compliant nitrogen-dosing lines preserve volatile aromatics without heat degradation, separating authentic spirits from commodity malt dilutions. |
| Direct-to-Shipper Licensing | State-by-state authorization bypasses three-tier markups in California, New York, and Texas festival corridors. |
| Clean-Label Reformulation | EU Food Information to Consumers Regulation compliance unlocks German and Dutch retail procurement filters rejecting caramel-coloring formulations. |
| Festival Sponsorship Infrastructure | Refrigerated pouring rights at Coachella, Bonnaroo, and Austin City Limits convert temporary permits into multi-year brand partnerships. |
| Aged-Liquor Hybrid Development | Barrel-finished and cask-strength reductions create premium tier pricing previously unavailable in single-serve containers. |
Methodological Framework
Coverage spans the United States, Germany, the United Kingdom, Japan, and Australia, with primary inputs from each market's regulatory and channel environment. The analysis combines structured interviews with festival procurement officers, craft distiller founders, TTB compliance consultants, flavor chemists, and aluminum can supply managers with secondary validation from TTB formula approval databases, EU Food Information to Consumers Regulation enforcement records, state-level direct-to-shipper legislative tracking, and SEC filings from publicly traded beverage conglomerates. Bottom-up volume modeling triangulates against top-down category spend estimates.
Granularity-level modeling operates at the intersection of product type, flavor profile, packaging format, and distribution channel, with additional dimensioning by ABV tier and regulatory authorization status. CAGRs derive from segment-level growth trajectory analysis across the projection horizon, incorporating TTB formula approval velocity, state-level licensing expansion rates, and festival economy sponsorship renewal patterns as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to aluminum tariff policy shifts, FDA low-alcohol tax reclassification guidance, and deposit-return packaging mandate expansion. Forecasts reflect documented assumptions about regulatory approval timelines, distributor network reconfiguration, and consumer substitution elasticity between spirits-authenticated and malt-based formats. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
France Tequila Market
Alcoholic Beverages
Fortified Wine Market
Alcoholic Beverages
Lager Market
Alcoholic Beverages
Middle East and Africa Wine Market
Alcoholic Beverages
Tanzania Spirits Market
Alcoholic Beverages
Beer Brewing Machine Market
Alcoholic Beverages
Hard Tea Market
Alcoholic Beverages
China Tequila Market
Alcoholic Beverages
Pineapple Beer Market
Alcoholic Beverages
Instant Wine Chillers and Refreshers Market
Alcoholic Beverages
Global Bars and Nightclubs Market
Alcoholic Beverages
Low-Alcohol Beer Market
Alcoholic Beverages
Vermouth Market
Alcoholic Beverages
Distilled Spirits Market
Alcoholic Beverages
Asia Pacific Beer Market
Alcoholic Beverages
Wine Filling Machine Market