
 Automated Brewing System Market | 2026-2036
Automated Brewing System Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Brewing System Market Outlook
Craft breweries and microbreweries are collapsing the historical dominance of large distilleries as the primary buyer archetype for automated brewing systems. Krones AG leverages its filling and packaging integration to anchor premium system bundling for mid-size brewers. GEA Group competes through specialized heat exchange and separation technology embedded within brewhouse automation. Siemens differentiates its portfolio with process control software that extends from mashing through fermentation monitoring.
An automated brewing system integrates vessels, pumps, heat exchangers, and programmable logic controllers to execute mashing, lautering, boiling, and whirlpool operations with minimal manual intervention, typically achieving temperature precision within 0.5 degrees Celsius to ensure batch consistency. The primary commercial purpose centers on reducing labor dependency while standardizing output quality across repeated production cycles. Fully automatic systems now lead capital deployment as brewers seek to eliminate variability in hop dosing and fermentation timing, while IoT-enabled technology represents the fastest-expanding segment because remote diagnostics and predictive maintenance reshape total cost of ownership calculations for distributed microbrewery networks. Small batch capacity remains mature in home brewer channels where price sensitivity limits automation depth.
FDA food-contact notifications and EMA guidelines on stainless-steel alloy composition for beverage equipment shape material selection and supplier qualification timelines for system manufacturers entering North American and European markets. CE marking under the EU Machinery Directive and ISO 22000 food safety management standards further constrain design architectures for export-bound equipment. Stakeholders must monitor how evolving national energy-efficiency mandates for commercial kitchens and brewhouses alter heating system specifications and retrofit economics across their installed base.
Market Dynamics
IoT-enabled predictive maintenance is compressing brewhouse downtime economics and redistributing capital deployment toward distributed microbrewery networks over centralized production facilities.
Growth Catalysts
- EMA Stainless-Steel Alloy Standards:Tightened certification requirements for food-contact surfaces in beverage equipment are accelerating replacement cycles among European craft brewers upgrading from manual kettle systems.
- Remote Diagnostics Integration:Cloud-connected PLCs enabling real-time fermentation monitoring are reducing labor dependency for microbrewery operators managing multiple production sites.
- German Craft Brewing Density:Concentrated demand from Bavarian and North Rhine-Westphalian microbreweries is sustaining order flow for mid-capacity automated brewhouses.
Market Restraints
- Specialized Fabrication Input Costs:Price volatility in food-grade stainless steel and precision heat exchanger components constrains margin flexibility for system integrators.
- CE Marking Compliance Burden:Extended EU Machinery Directive certification timelines delay market entry for non-European equipment manufacturers seeking European distribution.
- Manual Kettle Substitution Economics:Low-cost artisanal brewing setups retain cost advantage for sub-thousand-liter annual production volumes in price-sensitive home brewer segments.
Strategic Opportunities
- Chinese Microbrewery Expansion:Underpenetrated automation rates among tier-two city craft brewers create white space for standardized mid-size system deployment.
- ISO 22000 Certification Arbitrage:Food safety management standard compliance is becoming a procurement filter for contract brewing facilities seeking brand partner validation.
- AI-Driven Recipe Optimization:Convergence of machine learning with process control software enables dynamic mash temperature adjustment based on grain lot variability.
Industry Challenges
- Mechatronics Technician Scarcity:Shortage of specialists capable of servicing integrated PLC, pump, and heat exchanger systems extends service response times in distributed brewery networks.
- Legacy System Integration Complexity:Retrofitting IoT sensors and automated dosing into existing manual brewhouses requires custom engineering that fragments project economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Brewing System Market |
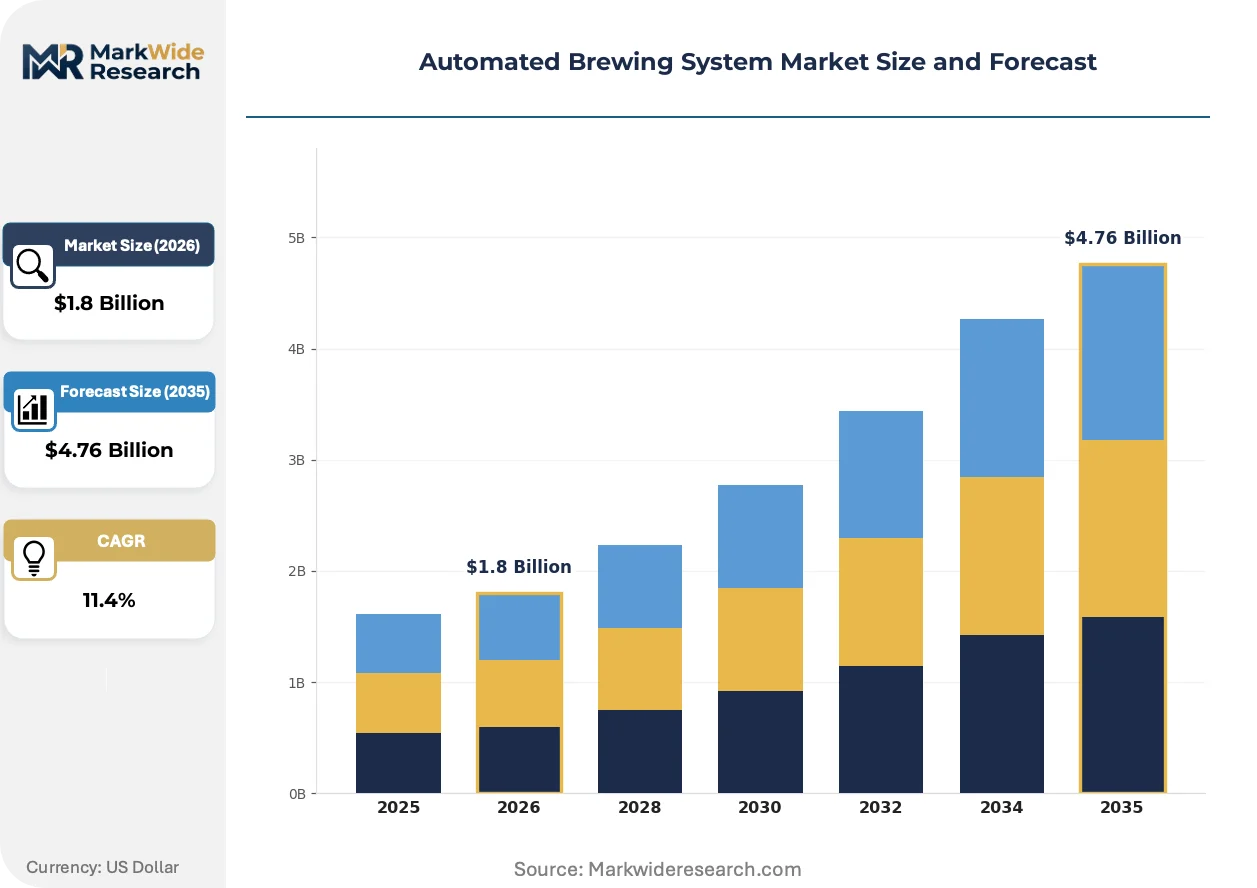
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Semi-Automatic, Fully Automatic, Hybrid, Manual End User: Home Brewers, Microbreweries, Craft Breweries, Large Distilleries Technology: IoT Enabled, Temperature Control, Mobile App Controlled, Traditional Capacity: Small Batch, Medium Batch, Large Batch, Commercial |
| Companies Covered | ProLeiT, Krones AG, Rockwell Automation, Czech Brewery System, Alfa Laval, Siemens, GEA Group, Micet Group, Yokogawa Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Brewing System Market Strategic Shifts
Edge computing architectures and modular vessel design are dismantling the traditional trade-off between production scale and operational flexibility that has governed brewhouse capital planning for decades.
Sensor fusion technology combining temperature, pressure, and turbidity readings into unified fermentation monitoring dashboards is fragmenting the historical dominance of standalone control systems. Mid-size craft breweries in the United States and Germany are adopting these integrated platforms fastest, compressing the vendor landscape from point-solution specialists toward full-stack automation providers.
FDA food-contact notification requirements for novel alloy compositions in brewing vessels are extending supplier qualification timelines. Equipment manufacturers seeking North American market access must now document migration testing for nickel and chromium leaching under revised guidance, with stainless-steel certification backlogs most acute among Asian fabricators.
After-sales service unbundling is altering how microbreweries contract for system support. Operators in China and the United States increasingly procure predictive maintenance subscriptions separate from capital equipment, with remote troubleshooting packages displacing traditional annual service agreements for multi-site brewing groups.
Automated Brewing System Market Segmentation
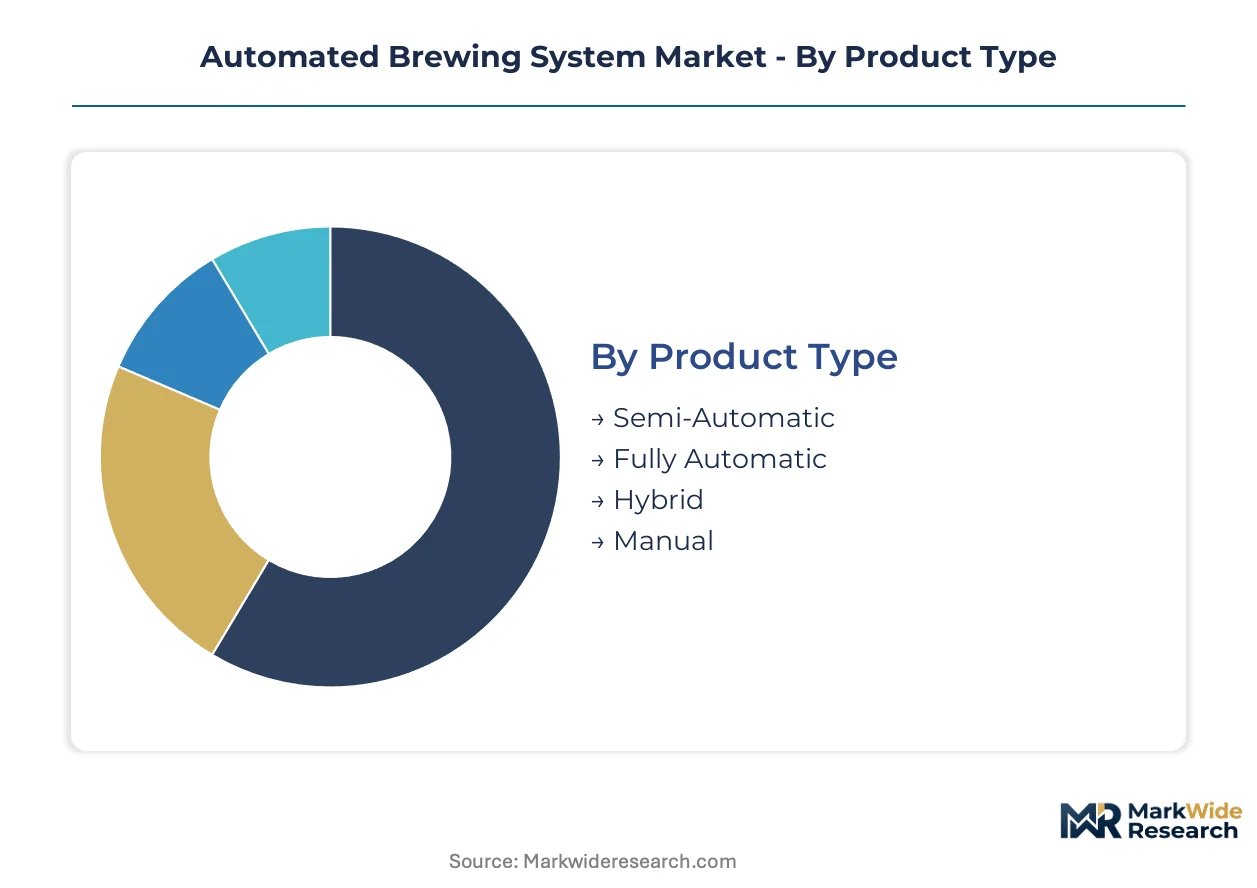
Automated brewing systems fragment across four critical dimensions that determine capital deployment patterns and vendor competitive intensity. Product type and technology choices reshape total cost of ownership calculations, while end-user scale and batch capacity dictate system architecture and service requirements.
Product Type:
Manual kettle configurations exert persistent substitution pressure on semi-automatic systems in price-sensitive entry segments.
- Fully Automatic:Systems integrate PLCs, automated hop dosing, and fermentation monitoring to eliminate manual intervention across mashing through whirlpool operations. Craft breweries in Germany and the United States concentrate procurement here as labor costs and batch consistency requirements intensify.
- Semi-Automatic:Hybrid architectures retain manual oversight for critical process steps while automating temperature control and pump sequencing. Microbreweries in China and tier-two US markets favor this tier to balance capital constraints against quality standardization needs.
- Hybrid:Modular designs allow brewers to retrofit automation components onto existing vessel infrastructure.
- Manual:Traditional kettle setups persist in home brewer channels and artisanal microbreweries prioritizing hands-on process control.
Fully automatic systems retain volume leadership; semi-automatic configurations hold the steepest expansion curve.
End User:
Cost tier stratification separates capital-intensive commercial deployments from discretionary home equipment purchases.
- Craft Breweries:Mid-size operators with annual production between 1,000 and 50,000 barrels drive premium system demand. Bavarian and North Rhine-Westphalian craft brewers anchor European order flow, while Colorado and California clusters sustain US procurement.
- Microbreweries:Smaller-scale commercial operators prioritize IoT-enabled remote monitoring to manage distributed production sites with minimal staffing. Chinese tier-two city expansions concentrate demand growth in this segment.
- Large Distilleries:Industrial-scale brewing operations integrate automated brewhouses into broader beverage production lines.
- Home Brewers:Enthusiast segments exhibit extreme price sensitivity, constraining automation depth and vendor margin.
Craft breweries retain volume leadership; microbreweries hold the steepest expansion curve.
Technology:
Application specificity determines whether remote diagnostics or precision control delivers superior value capture.
- IoT Enabled:Cloud-connected PLCs transmit real-time fermentation data to centralized dashboards, enabling predictive maintenance and multi-site coordination. Distributed microbrewery networks in the United States and China adopt fastest to compress downtime economics.
- Temperature Control:Precision heating and cooling systems achieve ±0.5°C consistency across mash and fermentation stages. German craft brewers demand this capability to meet Reinheitsgebot-adjacent quality standards.
- Mobile App Controlled:Smartphone interfaces for parameter adjustment and alert management appeal to smaller operators.
- Traditional:Hardwired control panels without network connectivity persist in legacy installations and budget-constrained deployments.
IoT enabled systems retain volume leadership; temperature control holds the steepest expansion curve.
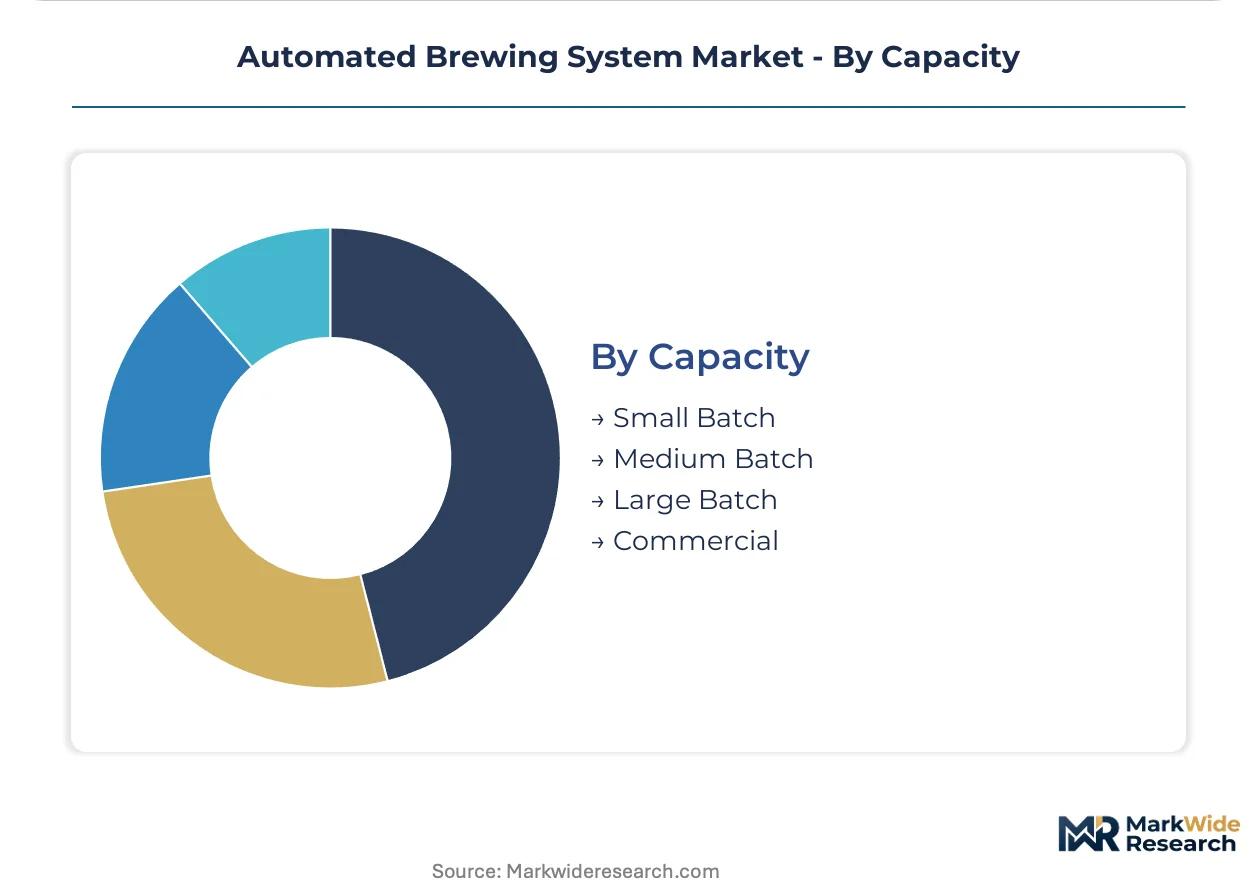
Capacity:
Volume scale dictates vessel configuration, supply chain complexity, and installation logistics.
- Medium Batch:Systems processing 500–2,000 liter batches dominate craft brewery procurement. German and US mid-size operators displace manual kettle setups with standardized configurations that balance throughput against floor space constraints.
- Commercial:Large-scale continuous production lines serve industrial brewing and contract manufacturing facilities.
- Small Batch:Pilot systems and experimental brewing setups concentrate in R&D facilities and high-end home brewer segments.
- Large Batch:Specialized configurations for regional production facilities bridge medium and commercial scales.
Medium batch systems retain volume leadership; commercial capacity holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German brewhouse fabricators export automated systems to craft breweries across the United States and China, establishing the primary trade-flow corridor for mid-capacity equipment. This bilateral equipment movement concentrates technology transfer between established European engineering centers and emerging craft brewing clusters. National regulatory frameworks and local production economics reshape procurement patterns in each destination market.
United States
Colorado and California microbrewery clusters drive demand for IoT-enabled brewhouses with remote fermentation monitoring. FDA food-contact notifications for stainless-steel alloys extend supplier qualification timelines for European equipment imports. Denver and San Diego operators are displacing manual kettle setups with medium-batch automated systems to standardize quality across multi-site networks.
Germany
Bavarian craft brewers anchor European order flow for precision temperature control systems meeting Reinheitsgebot-adjacent quality standards. EMA tightened certification requirements for food-contact surfaces accelerate replacement cycles among manual kettle operators. Munich and North Rhine-Westphalian brewing clusters sustain procurement of fully automatic brewhouses as labor costs intensify.
China
Tier-two city craft brewers in Chengdu and Qingdao create white space for standardized mid-size system deployment with underpenetrated automation rates. GB standards for food machinery safety constrain design architectures for domestic and import equipment alike. Yangtze River Delta fabricators are scaling production of semi-automatic systems for price-sensitive microbrewery entrants.
Japan
Tokyo and Osaka craft brewing clusters demand compact automated systems addressing severe floor-space constraints in urban brewing facilities. METI energy-efficiency mandates for commercial kitchens alter heating system specifications for brewhouse equipment. Kanto region operators are adopting IoT-enabled predictive maintenance to compress downtime economics in high-rent environments.
United Kingdom
London and Manchester microbreweries prioritize modular automation components enabling retrofit of existing vessel infrastructure. CE marking under the EU Machinery Directive constrains design architectures for equipment sourced from non-European manufacturers. Southeast England brewing groups are unbundling after-sales service contracts, procuring remote diagnostics subscriptions separate from capital equipment.
Automated Brewing System Market Competitive Environment
Listed leaders compete with private specialists across automation depth and integration breadth, producing a tiered competitive structure where scale-driven conglomerates face nimble regional fabricators. The vendor base concentrates around three strategic archetypes: diversified industrial automation conglomerates, specialized beverage equipment integrators, and regional brewhouse fabricators serving price-sensitive craft segments. Dominant competitive moves include strategic partnerships between control software developers and vessel manufacturers, plus geographic expansion through distributor networks into underpenetrated craft brewing clusters.
Among diversified industrial conglomerates, Siemens AG and Rockwell Automation exemplify the control-systems-first archetype, anchoring competitive positioning through process software that extends across mashing and fermentation stages. Krones AG occupies a position within the specialized beverage equipment tier, representing the filling-and-packaging integration model for mid-size brewer bundling. GEA Group sits within the heat-exchange specialization segment, illustrating how component-level engineering expertise translates into brewhouse automation market presence.
| Leading Market Players |
|---|
| ProLeiT |
| Krones AG |
| Rockwell Automation |
| Czech Brewery System |
| Alfa Laval |
| Siemens |
| GEA Group |
| Micet Group |
| Yokogawa Corporation |
| Others |
Value Chain & Pricing Dynamics
Mid-capacity vessel fabrication in Germany and China generates scale economies that compress unit costs for stainless-steel brewhouse components while anchoring regional price floors for automated system exports. These production-scale advantages concentrate supply authority among established fabricators and constrain pricing flexibility for smaller regional competitors seeking entry into craft brewery procurement channels.
Pricing Analysis
Current-generation IoT-enabled brewhouses command substantial premiums over prior-generation PLC-controlled systems and emerging next-generation AI-integrated platforms still in pilot deployment. Pricing stratifies across premium, standard, and economy tiers based on FDA food-contact certification grade and after-sales service bundling depth. Cost compression in semi-automatic configurations is intensifying because Yangtze River Delta fabricators are scaling standardized mid-size production. Home brewer segments exhibit extreme price sensitivity, while German craft breweries demonstrate lowest sensitivity due to Reinheitsgebot-adjacent quality requirements.
Supply Chain Analysis
Strategic stockpiling of food-grade stainless steel dominates inventory strategy among German brewhouse fabricators buffering against nickel and chromium price volatility, whereas Chinese producers favor just-in-time procurement to minimize working capital intensity. Supply concentrates in Germany, China, and the United States for precision heat exchangers and PLC control modules. Raw material dependencies draw from Indonesian nickel ore, South African chromium, and Taiwanese semiconductor components for sensor arrays. Single-source vulnerability in precision pump manufacturing extends lead times during demand surges. Distribution runs through specialized beverage equipment distributors and direct OEM relationships with multi-site brewing groups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of mechatronics technicians capable of servicing integrated PLC, pump, and heat exchanger systems creates a capability bottleneck that constrains service response times and fragments aftermarket economics for distributed brewery networks.
For Market Incumbents: Shield installed-base relationships by embedding predictive maintenance subscriptions that lock microbreweries into multi-year service contracts before Asian fabricators achieve CE marking compliance. Prioritize backward integration into precision heat exchanger manufacturing to defend margin position against stainless-steel input cost volatility. Accelerate FDA food-contact notification documentation to preempt certification backlogs that delay North American market entry for competitors. For New Entrants and Emerging Players: ISO 22000 certification fast-track positions contract brewing facilities as the most penetrable customer archetype, as these operators require food safety management standard compliance for brand partner validation. Target tier-two Chinese cities where underpenetrated automation rates among craft brewers create white space for standardized semi-automatic system deployment. Pursue a remote diagnostics-first go-to-market angle that unbundles after-sales service from capital equipment to compress customer acquisition costs. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among IoT-enabled system providers with predictive maintenance subscription attach rates above sixty percent, indicating superior long-term viability across a five-to-ten year holding window. Prioritize acquisition targets with established CE marking pathways and FDA food-contact notification portfolios rather than pure hardware fabricators. Watch mechatronics technician training program graduation rates as the inflection indicator for service capacity constraints easing in distributed brewery networks.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Subscription Unbundling | Recurring revenue streams from Chinese and US microbreweries displace traditional annual service agreements. |
| CE Marking Fast-Track Investment | Accelerated EU Machinery Directive compliance timelines capture European craft brewery replacement cycles. |
| Backward Integration into Heat Exchanger Manufacturing | In-house production of precision components defends margins against stainless-steel alloy price volatility. |
| ISO 22000 Certification Arbitrage | Food safety management standard compliance becomes procurement filter for contract brewing facilities. |
| AI-Driven Recipe Optimization Platform Launch | Machine learning convergence with Siemens process control software enables dynamic mash temperature adjustment. |
Study Parameters
A standing panel of brewhouse operations managers, mechatronics service technicians, craft brewery procurement directors, and food safety compliance officers provided ongoing calibration throughout the study period. Primary interviews with these stakeholders combined with secondary validation against FDA food-contact notification databases, EMA stainless-steel certification registries, EU Machinery Directive filing records, and German engineering association technical standards. Bottom-up demand modeling from microbrewery capital expenditure surveys triangulated against top-down supply-side capacity assessments from Yangtze River Delta and Bavarian fabricator production disclosures.
Consistency checks validated volume and value outputs against external benchmarks including customs trade data for brewhouse equipment imports and engineering sector order intake reports. The analytical framework segmented demand across product type, end-user scale, technology generation, and batch capacity throughout the projection horizon. CAGRs derived from fitted growth curves incorporating replacement cycle dynamics, regulatory compliance acceleration effects, and IoT adoption diffusion patterns. Industry-specific forecast inputs included EMA stainless-steel certification timeline compression and FDA food-contact notification backlog severity indices.
Decision-makers should treat outputs as directional under assumptions of sustained craft brewery capital expenditure intensity and stable food-grade stainless-steel alloy pricing; material deviation would warrant model refresh. Forecasts reflect base-case assumptions regarding mechatronics technician training pipeline expansion and CE marking compliance timeline stability. Revision becomes warranted when FDA food-contact notification processing delays or EMA certification backlogs cross thresholds that materially alter supplier qualification economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Specialty Beer Market
Alcoholic Beverages
Lager Market
Alcoholic Beverages
Global Liquor Bottles Market
Alcoholic Beverages
Chocolate Beer Market
Alcoholic Beverages
United States Beer Market
Alcoholic Beverages
Rhum Agricole Market
Alcoholic Beverages
Alcohol Gummies Market
Alcoholic Beverages
Wine Bags Market
Alcoholic Beverages
Commercial Wine Dispenser Market
Alcoholic Beverages
Global Bourbon Market
Alcoholic Beverages
Global Brewery Filtration Market
Alcoholic Beverages
Dark Spirits Market
Alcoholic Beverages
Beer Mug Market
Alcoholic Beverages
Wine Production Machinery Market
Alcoholic Beverages
Middle East and Africa Beer Market
Alcoholic Beverages
Nitro Cocktails Market