
 Cannabis Drinks Market | 2026-2036
Cannabis Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
Cannabis Drinks Market Analysis
The EU Green Deal is decoupling cannabis beverage production from conventional agricultural inputs by pressuring European bottlers toward regenerative hemp sourcing and carbon-accounted supply chains. Canopy Growth Corporation leverages its Canadian cultivation infrastructure to sustain cost advantages in THC extraction for drink formulations. Tilray Brands, Inc. anchors its European positioning through Portuguese cultivation assets that navigate divergent member-state cannabis policies. Truss Beverage Co. competes in the ready-to-drink segment through its Molson Coors distribution partnership, which controls shelf access across North American retail channels.
Cannabis drinks are non-alcoholic beverages infused with cannabinoids—primarily THC, CBD, or terpene blends—typically dosed between 2.5 mg and 10 mg per serving, manufactured through nanoemulsion technology to enhance bioavailability and onset speed, and designed for social consumption occasions or functional wellness applications. Carbonated beverages dominate current revenue due to their alignment with existing refreshment purchasing habits and cooler placement in licensed dispensaries, while concentrates in powdered delivery mode represent the fastest-expanding margin pool as on-the-go consumers seek portable, airline-friendly formats. THC ingredient formulations command premium positioning relative to CBD-only variants, reflecting the differentiated regulatory burden and psychoactive utility that shapes consumer willingness to pay.
The FDA maintains oversight of hemp-derived CBD in beverages through the Food, Drug, and Cosmetic Act, while individual U.S. state cannabis regulators—such as California's Department of Cannabis Control and Colorado's Marijuana Enforcement Division—impose separate testing and labeling mandates that fragment compliance requirements. Health Canada establishes federal standards for THC potency limits and packaging warnings that directly constrain product development cycles for cross-border suppliers. Stakeholders must monitor the convergence of state-level THC beverage allowances with federal alcohol beverage taxation frameworks, as this interface will determine channel economics and competitive positioning for emerging entrants.
Market Dynamics
Nanoemulsion technology has compressed onset times from 90 minutes to 15 minutes, fundamentally altering the competitive calculus between cannabis beverages and traditional alcohol in social consumption occasions. This bioavailability breakthrough is forcing incumbent beverage alcohol distributors to renegotiate shelf-space contracts with licensed retailers.
Growth Catalysts
- State-Level Legalization Cascades:Colorado's Marijuana Enforcement Division and California's Department of Cannabis Control have established testing protocols that neighboring states adopt verbatim, reducing compliance friction for multi-state operators.
- Wellness-Function Convergence:Gen Z consumers in licensed dispensaries purchase low-dose THC seltzers alongside CBD relaxation beverages, collapsing the historical separation between psychoactive and functional positioning.
- Nanoemulsion Manufacturing Scale:Proprietary lipid-in-water processing now achieves 50-nanometer droplet consistency, enabling clear beverage formulations that bypass the cloudy appearance that previously limited mainstream acceptance.
Market Restraints
- FDA-Cannabis Policy Asymmetry:The Food, Drug, and Cosmetic Act prohibits interstate commerce of hemp-derived CBD in beverages while permitting intrastate THC sales in legalized jurisdictions, fragmenting supply chain logic.
- THC Input Concentration:Extraction capacity clusters in California's Central Valley and Colorado's Pueblo County, creating geographic supply vulnerability for brands without captive cultivation.
- Alcohol Taxation Arbitrage:Federal alcohol excise frameworks impose per-gallon levies that cannabis beverages currently evade, yet pending legislative convergence threatens margin structures designed around this differential.
Strategic Opportunities
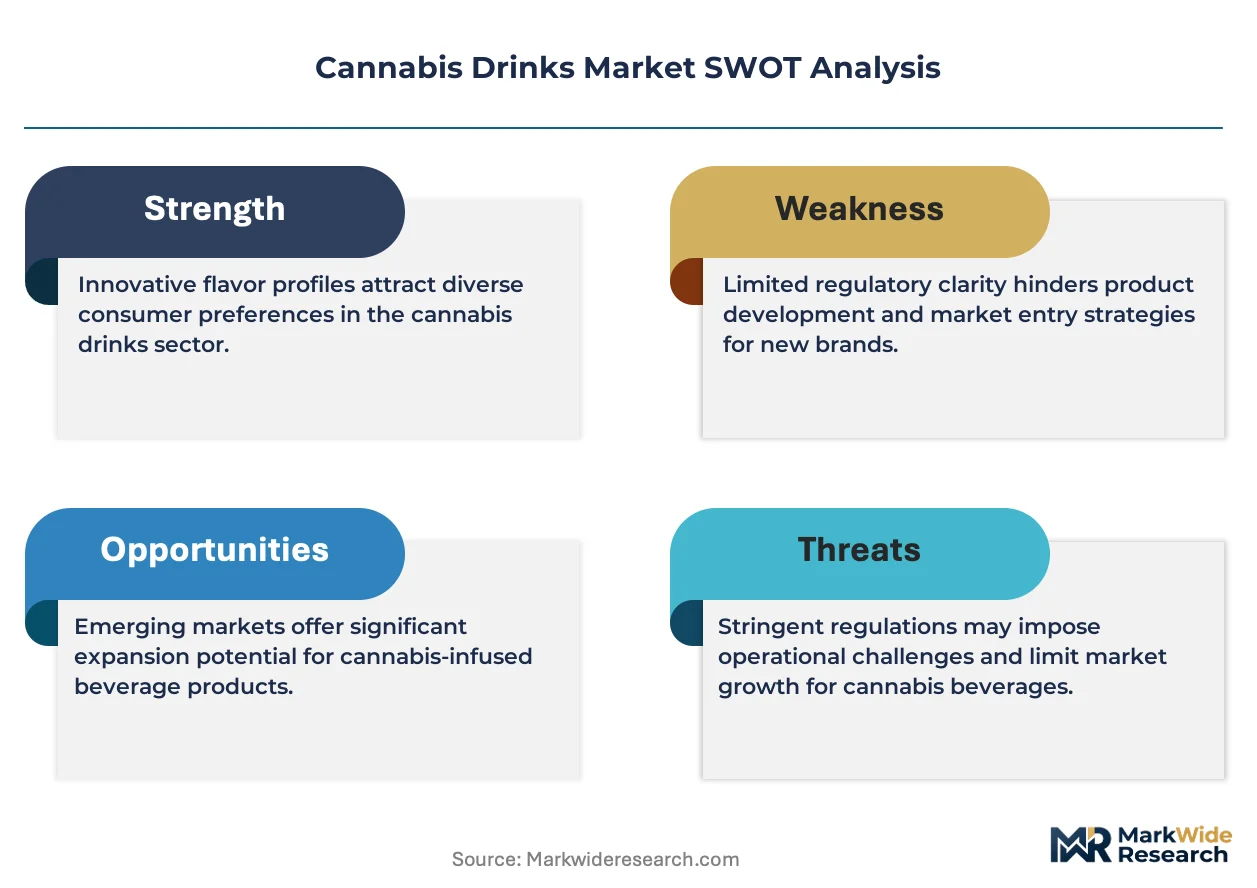
- Airline-Compatible Formats:Powdered concentrates below 3.4 fluid ounces bypass Transportation Security Administration liquid restrictions, opening duty-free and travel retail channels unavailable to carbonated alternatives.
- Regenerative Hemp Sourcing:EU Green Deal carbon-accounting requirements for imported agricultural inputs create first-mover advantage for European bottlers establishing certified regenerative supply chains.
- Terpenoid Precision Blending:Convergence of gas chromatography analytics with beverage formulation software enables strain-specific terpene replication without botanical sourcing constraints.
Industry Challenges
- Cross-Functional Talent Scarcity:Formulation chemists with simultaneous expertise in emulsion stability and cannabinoid pharmacokinetics command compensation premiums that strain mid-cap R&D budgets.
- Dual-Label Compliance Burden:Products crossing state lines require simultaneous adherence to source-state cannabis regulations and destination-state hemp rules, doubling packaging revision cycles.
- Dispensary-to-Retail Channel Integration:Legacy alcohol distributors lack relationships with licensed cannabis retailers, forcing beverage brands to maintain parallel sales organizations with incompatible incentive structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cannabis Drinks Market |
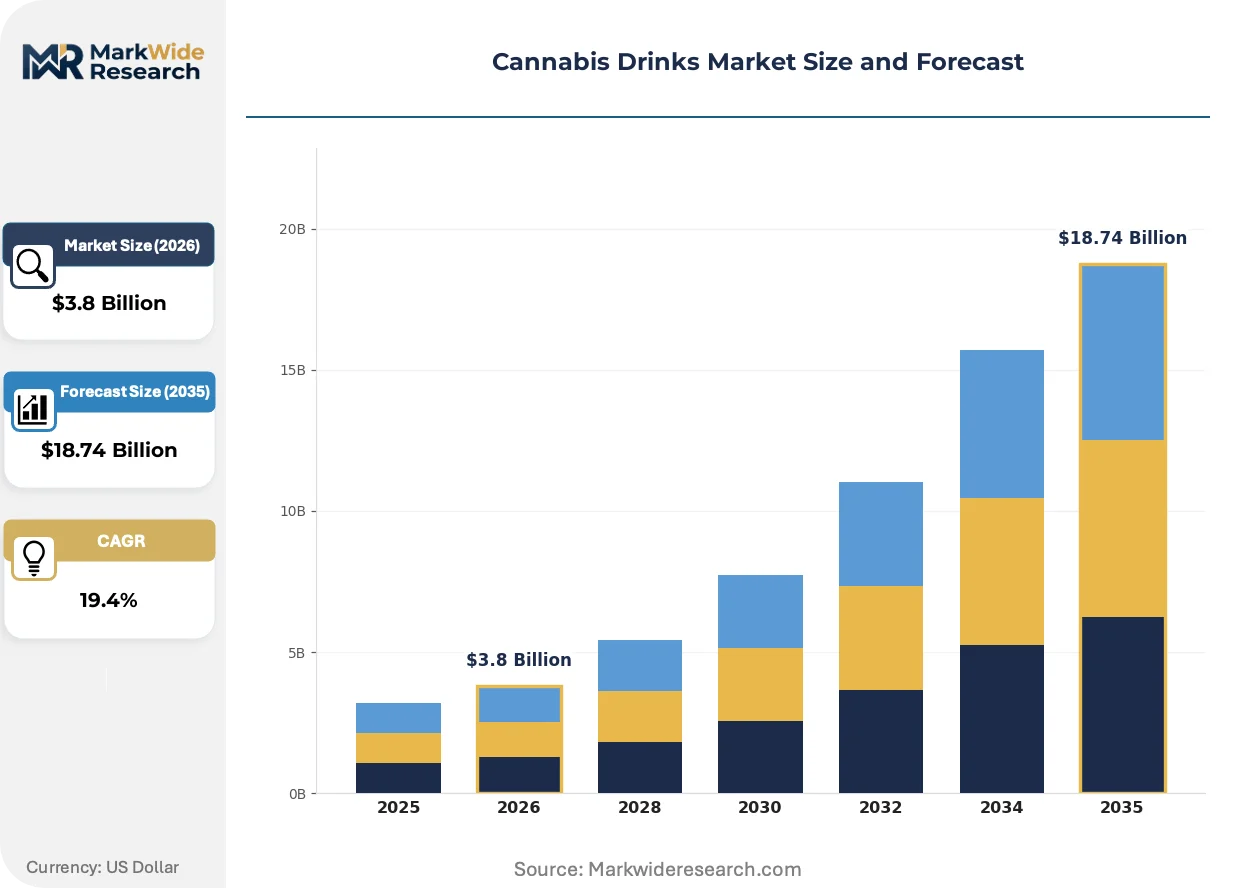
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $18.74 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbonated Beverages, Non-Carbonated Beverages, Concentrates, Enhancers Delivery Mode: Ready-to-Drink, Powdered, Infused, Tinctures Ingredient Type: THC, CBD, Terpenes, Flavoring Agents Packaging Type: Glass Bottles, Cans, Pouches, Tetra Packs |
| Companies Covered | Canopy Growth Corporation, Tilray Brands, Inc., Truss Beverage Co., Keef Brands, Uncle Arnie's, Brēz, Cronos Group Inc., Aurora Cannabis Inc., Cann Social Tonics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cannabis Drinks Market Emerging Trajectories
Formulation science is compressing the functional gap between cannabis beverages and conventional alcohol, while regulatory arbitrage between state and federal frameworks creates temporary competitive windows for agile operators.
Water-soluble nanoemulsion platforms are rewriting the onset-speed benchmark that previously confined cannabis beverages to solo consumption. Licensed dispensaries in California now stock THC seltzers with 10-15 minute activation windows alongside traditional edibles. This speed parity is enabling placement in social-occasion retail sets previously reserved for beer and wine.
Health Canada's federal potency caps and mandatory health warnings constrain product development cycles for North American suppliers seeking cross-border scale. The 10 mg THC per-package ceiling forces Canadian formulators toward multi-can packaging formats that increase per-unit production costs. Domestic brands respond by emphasizing terpene complexity and minor cannabinoid ratios as differentiation vectors within rigid quantitative limits.
Millennial and Gen Z buyers now treat dispensary purchases as ingredient sourcing for home mixing rather than finished-product acquisition. This behavior fragments volume across concentrates, tinctures, and micro-dosed beverages rather than concentrating in single-category winners. Colorado's integrated dispensary-lounge model exhibits this pattern most visibly, with consumers purchasing base spirits and cannabis modifiers separately for on-premise combination.
Cannabis Drinks Market Segmentation
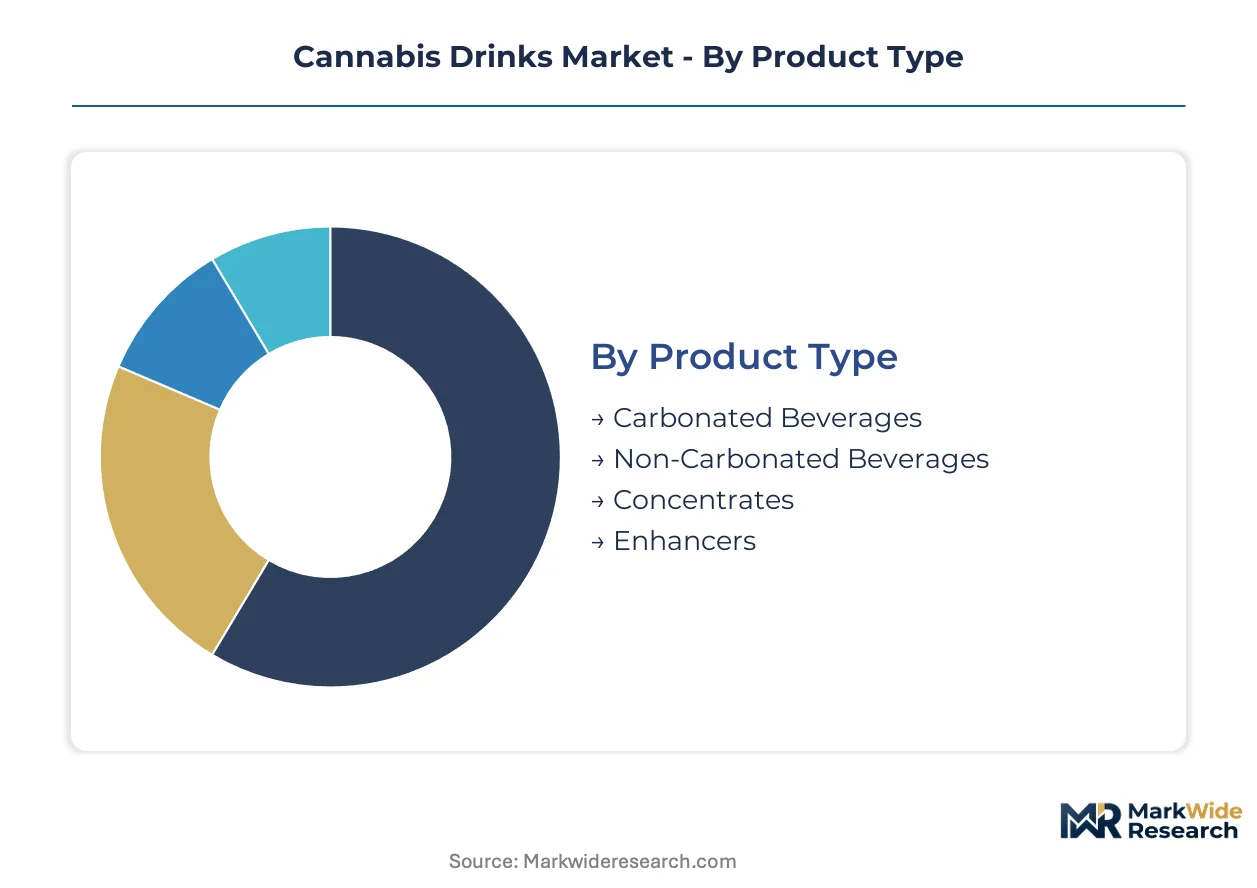
Cannabis drinks segment along four intersecting dimensions that determine formulation cost, regulatory pathway, and channel access. Product type and delivery mode shape manufacturing infrastructure requirements, while ingredient type and packaging format dictate compliance burden and consumer occasion targeting.
Product Type:
Standardization dominates carbonated formats where established beverage contract manufacturers replicate beer and seltzer production protocols, while concentrates demand bespoke emulsion engineering that fragments supplier capabilities.
- Carbonated Beverages:THC-infused seltzers and sparkling waters leverage existing carbonation lines and cold-chain distribution networks. California dispensaries and Colorado licensed retailers stock these in cooler sets adjacent to alcoholic hard seltzers, with nanoemulsion clarity standards now matching conventional beverage appearance. Onset compression to 15 minutes is displacing beer in social consumption occasions among wellness-oriented millennials.
- Concentrates:Water-soluble powders and liquid concentrates enable precise dosing flexibility and bypass liquid restrictions in travel retail. Powdered formats below 3.4 ounces comply with Transportation Security Administration carry-on limits, opening airline duty-free channels unavailable to bottled alternatives. Gaining share fastest as on-the-go consumers prioritize portability over immediate consumption.
- Non-Carbonated Beverages:Still waters, teas, and functional shots serve wellness applications where carbonation conflicts with ingredient positioning.
- Enhancers:Drop-in flavor and cannabinoid packets transform conventional beverages into cannabis-infused versions.
Leading the category by volume: Carbonated Beverages. Expanding most quickly: Concentrates.
Delivery Mode:
Volume scale clusters in ready-to-drink formats where unit economics justify dedicated production lines, while powdered and tincture modes serve niche dosing precision requirements with higher per-gram margins.
- Ready-to-Drink:Pre-formulated beverages in final packaging dominate licensed dispensary shelves and emerging retail channels. Molson Coors distribution partnerships control shelf access across North American retail networks, creating incumbent advantage in route-to-market infrastructure. Health Canada potency caps force multi-can packaging formats that increase per-unit production costs.
- Tinctures:Sublingual drops and beverage additives offer milligram-level dosing control for home mixing applications. Colorado's integrated dispensary-lounge model exhibits concentrated tincture demand, with consumers purchasing base spirits and cannabis modifiers separately for on-premise combination.
- Powdered:Single-serve sachets and bulk canisters enable airline-compatible transport and extended shelf stability without refrigeration.
- Infused:Real-time cannabinoid introduction at point of consumption preserves terpene volatility.
Dominating shelf presence: Ready-to-Drink. Steepest expansion trajectory: Tinctures.
Ingredient Type:
Regulatory burden separates THC formulations requiring state cannabis licensing from CBD variants operating under hemp-derived frameworks, with terpene blends occupying a positioning middle ground.
- THC:Psychoactive tetrahydrocannabinol formulations command premium positioning reflecting differentiated regulatory burden and utility. California's Department of Cannabis Control and Colorado's Marijuana Enforcement Division impose testing and labeling mandates that fragment compliance for multi-state operators. Extraction capacity clusters in California's Central Valley and Colorado's Pueblo County, creating geographic supply vulnerability.
- CBD:Non-psychoactive cannabidiol from hemp operates under FDA Food, Drug, and Cosmetic Act oversight that prohibits interstate beverage commerce while permitting intrastate sales. This asymmetry fragments supply chain logic and constrains brand scale.
- Terpenes:Strain-specific aromatic compounds enable functional replication without botanical sourcing constraints.
- Flavoring Agents:Natural and artificial taste modifiers mask emulsion bitterness and enable mainstream palatability.
Highest price realization: THC. Fastest regulatory evolution: CBD.
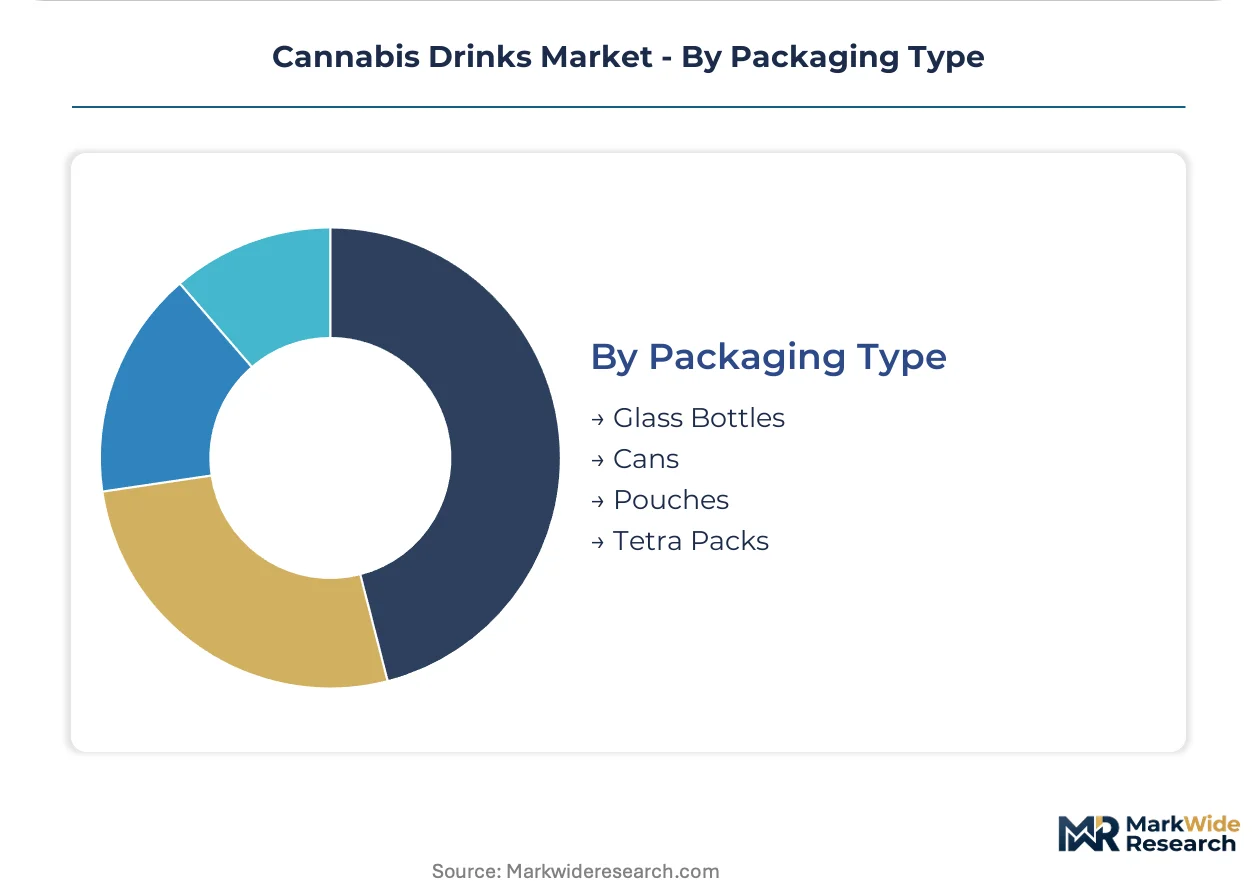
Packaging Type:
Recyclability mandates and child-resistance requirements pull packaging decisions toward aluminum cans and multi-layer pouches, while glass retains premium positioning despite weight and breakage liabilities.
- Cans:Aluminum containers dominate carbonated formats with established recycling infrastructure and lightweight logistics. EU Green Deal carbon-accounting requirements pressure European bottlers toward regenerative supply chains and recycled content thresholds.
- Pouches:Flexible multi-layer films reduce shipping cube and enable single-serve portioning with child-resistant zipper innovations.
- Glass Bottles:Premium positioning in cocktail-replacement occasions leverages conventional beverage aesthetics.
- Tetra Packs:Aseptic carton technology extends shelf life for non-carbonated functional beverages.
Highest volume throughput: Cans. Emerging fastest: Pouches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Central Valley extraction clusters and Colorado's Pueblo County cultivation corridors anchor North American supply capacity, while Portuguese greenhouse complexes and Canadian prairie processing infrastructure shape transatlantic trade flows.
United States
California's Department of Cannabis Control testing protocols and Colorado's Marijuana Enforcement Division labeling mandates create de facto national standards that neighboring states adopt verbatim. The FDA Food, Drug, and Cosmetic Act prohibits interstate hemp-derived CBD beverage commerce while permitting intrastate THC sales, fragmenting supply chain logic. Los Angeles and Denver dispensary-lounge integrations demonstrate convergent alcohol-cannabis consumption occasions.
Canada
Health Canada federal potency caps at 10 mg THC per package force multi-can packaging formats that inflate per-unit production costs. Prairie province greenhouse complexes supply extraction feedstock for cross-border formulation. Ontario and Quebec retail monopolies constrain brand access compared to fragmented U.S. state systems.
Germany
BfArM cannabis agency import quotas and pharmacy-only distribution channels limit beverage format penetration versus North American direct retail. EU Green Deal carbon-accounting requirements pressure bottlers toward regenerative hemp sourcing. Berlin and Munich urban clusters exhibit nascent CBD wellness beverage demand in specialty retail.
Netherlands
Opiumwet tolerance policy frameworks permit limited THC coffee shop sales without formal beverage manufacturing authorization. Rotterdam port logistics and Randstad distribution density position the country for hypothetical EU harmonized trade. Amsterdam pilot programs test on-premise consumption licensing for infused beverages.
Australia
TGA scheduling restrictions confine THC beverages to prescription pathways, while hemp-derived CBD operates under food standard exemptions. Sydney and Melbourne functional beverage incubators experiment with terpene-forward non-psychoactive formulations. Victorian and New South Wales agricultural departments trial industrial hemp cultivars for extract supply.
Cannabis Drinks Market Vendor Landscape
The competitive structure tilts toward licensed cannabis incumbents with captive cultivation assets and beverage alcohol distributors leveraging route-to-market infrastructure. Three archetypes dominate: vertically integrated Canadian LPs with extraction scale, U.S. multi-state operators with state-level licensing depth, and beverage alcohol partnerships accessing mainstream retail shelf space. Capacity expansion in nanoemulsion processing and strategic co-manufacturing agreements constitute the primary competitive vectors.
Within the licensed producer tier, Canopy Growth Corporation and Tilray Brands, Inc. exemplify cultivation-backed formulation scale, while Truss Beverage Co. occupies a position representing beverage alcohol distribution partnerships. These three anchors demonstrate divergent geographic emphases—Canadian federal infrastructure, European greenhouse assets, and North American retail channel access respectively—without overlapping strategic postures.
| Leading Market Players |
|---|
| Canopy Growth Corporation |
| Tilray Brands, Inc. |
| Truss Beverage Co. |
| Keef Brands |
| Uncle Arnie's |
| Brēz |
| Cronos Group Inc. |
| Aurora Cannabis Inc. |
| Cann Social Tonics |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up multi-state operators in California and Colorado anchor supply concentration through captive cultivation assets, translating upstream control into pricing discipline that resists commoditization pressure from hemp-derived CBD alternatives.
Pricing Analysis
Outcome-based pricing tied to onset speed anchors THC beverage premiums, with nanoemulsion clarity standards commanding tiered positioning across 15-minute activation and 90-minute legacy formats. Price differentiation separates state-licensed THC formulations from hemp-derived CBD variants, reflecting divergent regulatory burden and psychoactive utility. Cost compression in CBD-only tiers intensifies as FDA interstate commerce prohibitions fragment brand scale and concentrate competition in saturated intrastate markets. Dispensary buyers exhibit lowest price sensitivity for terpene-forward, strain-specific positioning, while mainstream retail channels prioritize per-milligram economy in functional wellness applications.
Supply Chain Analysis
Workforce availability constraints in California's Central Valley and Colorado's Pueblo County extraction clusters tether capacity expansion to specialized emulsion chemistry talent pools. Supply concentrates in these two states, with Canadian prairie greenhouse complexes feeding cross-border formulation demand. Raw material dependencies span nanoemulsion lipids, strain-specific biomass, and child-resistant packaging substrates. Single-source vulnerability runs through California's Department of Cannabis Control testing protocol adoption, which neighboring states replicate verbatim, creating cascade compliance risk. Distribution runs through parallel alcohol-beverage and licensed-cannabis retail infrastructures with incompatible incentive structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Nanoemulsion technology is displacing legacy lipid-infusion methods, compressing competitive windows for operators without clear-beverage formulation capabilities.
For Market Incumbents: Deploy captive cultivation leverage to secure extraction feedstock against California Central Valley supply bottlenecks. Deepen backward integration into nanoemulsion processing equipment to defend margin position from contract-manufacturing commoditization. Fortify shelf-access contracts with Molson Coors-tier distributors before federal taxation convergence erases channel arbitrage advantages. For New Entrants and Emerging Players: Airline-compatible powdered concentrates below TSA liquid limits offer the most penetrable white-space, bypassing refrigerated logistics that incumbent carbonated formats require. Target duty-free and travel retail channels unavailable to bottled alternatives through single-serve sachet positioning. Pursue direct-to-consumer subscription models in CBD-friendly jurisdictions to build brand equity ahead of federal regulatory clarity. For Investors and Strategic Acquirers: Distressed-cycle entries favor Canadian licensed producers with Health Canada-compliant packaging infrastructure and prairie cultivation assets. Long-term viability hinges on cross-border formulation scale once U.S. federal frameworks harmonize with Canadian standards. Monitor FDA hemp-derived CBD rulemaking as the critical inflection signal for capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Nanoemulsion Manufacturing Scale-Up | 50-nanometer droplet consistency enables clear beverage parity with conventional seltzers in licensed dispensary cooler placement. |
| Regenerative Hemp Supply Certification | EU Green Deal carbon-accounting compliance creates first-mover advantage for European bottlers accessing duty-free channels. |
| Airline-Compatible Format Development | Powdered concentrates below 3.4 ounces bypass TSA restrictions, unlocking travel retail previously closed to liquid alternatives. |
| Terpenoid Precision Blending Investment | Gas chromatography analytics enable strain-specific replication without botanical sourcing constraints or seasonal biomass volatility. |
| Dual-Channel Distribution Partnership | Molson Coors-tier alcohol distributor relationships bridge licensed cannabis retailers and mainstream retail shelf access. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with nanoemulsion formulation chemists, licensed dispensary buyers, California Department of Cannabis Control compliance officers, and Molson Coors distribution executives. Bottom-up volume triangulation across product type, ingredient category, and packaging format reconciled against top-down expenditure estimates from state-level cannabis tax disclosures and Health Canada production reports.
Data-stream reconciliation across the analysis window employed simultaneous modeling of carbonated beverage, concentrate, and non-carbonated delivery modes against THC, CBD, and terpene ingredient segments. CAGRs derived from segment-level volume trajectories weighted by per-unit pricing stratification across premium, standard, and economy tiers. Forecast inputs incorporated nanoemulsion technology adoption curves, state-level legalization cascade patterns, and FDA hemp-derived CBD regulatory evolution scenarios.
Several conditions sit outside the modeled scope, including federal U.S. cannabis descheduling timing, alcohol taxation parity legislation, and EU member-state harmonization beyond Germany and Netherlands pilot programs. Forecasts reflect assumptions regarding sustained state-level regulatory fragmentation and incremental FDA guidance evolution. Material deviation in federal scheduling, interstate commerce rulings, or major distributor partnership structures warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Electrolyte Beer Market
Alcoholic Beverages
Bayberry Wine Market
Alcoholic Beverages
Global Malt Market
Alcoholic Beverages
E Liquid Market
Alcoholic Beverages
Asia-Pacific Kegs Market
Alcoholic Beverages
Industrial Alcohol Market
Alcoholic Beverages
Wine Barrel Market
Alcoholic Beverages
Rotels Market
Alcoholic Beverages
Luxury Wines and Spirits Market
Alcoholic Beverages
Wine Filtering Machine Market
Alcoholic Beverages
United States Tequila Market
Alcoholic Beverages
Ready to Drink Cocktails Market
Alcoholic Beverages
Commercial Beer Tap System Market
Alcoholic Beverages
Whey Based Vodka Market
Alcoholic Beverages
South America Craft Beer Market
Alcoholic Beverages
Ethanol Market