
 North America Craft Beer Market | 2026-2036
North America Craft Beer Market Size, Share, and Industry Trends Forecast 2026-2036
North America Craft Beer Market Analytics
Independent bottle shops and specialty retailers is narrowing as consolidation pressures mount across the three-tier system. Boston Beer Company leverages its diversified beverage portfolio to maintain shelf presence beyond core beer offerings. Sierra Nevada Brewing Company anchors production scale through its North Carolina and California brewing campuses. D.G. Yuengling & Son competes on price-positioned heritage branding across mid-Atlantic and Southeastern markets.
Craft beer denotes beer produced by small, independent, and traditional brewers, typically employing malted barley as the primary fermentable sugar source with hop varieties selected for aroma, bitterness, or preservative function, yielding alcohol-by-volume concentrations generally between four and twelve percent for commercial distribution. Its primary commercial purpose centers on flavor-differentiated consumption occasions that command premium pricing over mass-market lager alternatives. Ales maintain volume leadership across product type categories due to shorter fermentation cycles and broader style versatility, while nitro brewing technique applications are gaining traction in on-premise channels for textural differentiation. E-commerce distribution channel growth reflects direct-to-consumer regulatory liberalization in select states, though wholesalers retain structural control in markets with strict franchise law protections.
The Alcohol and Tobacco Tax and Trade Bureau governs formula approval, label certification, and excise tax collection for all interstate craft beer commerce, while state alcohol beverage control agencies enforce divergent distribution tier requirements that fragment market access rules across jurisdictions. FDA Food Safety Modernization Act provisions extend to brewing ingredient suppliers, elevating traceability standards for malt and hop sourcing. Canadian Food Inspection Agency and provincial liquor board regulations add compliance layers for cross-border expansion. Stakeholders must monitor state legislative sessions for franchise law reform proposals that could unlock self-distribution pathways or tighten existing wholesaler protections.
Market Dynamics
The Alcohol and Tobacco Tax and Trade Bureau labeling requirements and state-level franchise laws are compressing market access pathways while independent brewpubs expand flavor experimentation capabilities.
Growth Catalysts
- Direct-to-Consumer Regulatory Liberalization:Select states are loosening self-distribution caps, allowing craft brewers to bypass wholesale tier controls for on-premise and e-commerce sales channels.
- Nitro Brewing Technique Diffusion:On-premise gastropubs are deploying nitrogen-infusion systems to create textural differentiation that commands premium pricing over standard carbonated pours.
- Pacific Northwest Cluster Concentration:Oregon and Washington state maintain dense supplier networks for specialty hop varieties and malt sourcing that reduce ingredient procurement lead times.
Market Restraints
- Three-Tier System Structural Lock-In:Franchise law protections in multiple states legally bind craft brewers to exclusive wholesaler relationships that limit pricing autonomy and market exit options.
- Input Cost Volatility in Specialty Hops:Climate-sensitive aroma hop varieties from Yakima Valley and Willamette Valley face yield fluctuations that compress gross margins on IPA-dominant portfolios.
- Mass-Market Lager Substitution Threat:Multinational brewers' craft-style sub-brands capture shelf space through distributor volume incentives that disadvantage independent label placements.
Strategic Opportunities
- Cross-Border Canadian Expansion:Provincial liquor board privatization trends in Alberta and Ontario create entry pathways for US craft brands seeking volume diversification beyond saturated domestic markets.
- Non-Alcohol Adjacent Portfolio Convergence:Brewers with diversified beverage capabilities can leverage existing TTB-certified production facilities for hop-water and functional seltzer line extensions.
- E-Commerce Subscription Channel Development:Regulatory carve-outs for direct shipment in states like California and Vermont enable recurring revenue models that bypass traditional wholesale margin stacking.
Industry Challenges
- Brewing Technician Skill Scarcity:Specialized fermentation science and quality control laboratory expertise commands premium wages that strain operational budgets at sub-10,000 barrel facilities.
- TTB Formula Approval Timeline Compression:Experimental ingredient submissions for fruited sours and barrel-aged releases face multi-month review queues that delay seasonal product launches.
- Legacy Equipment Integration Friction:Automated canning line upgrades require retrofitting existing brewhouse footprints with minimal production downtime tolerance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Craft Beer Market |
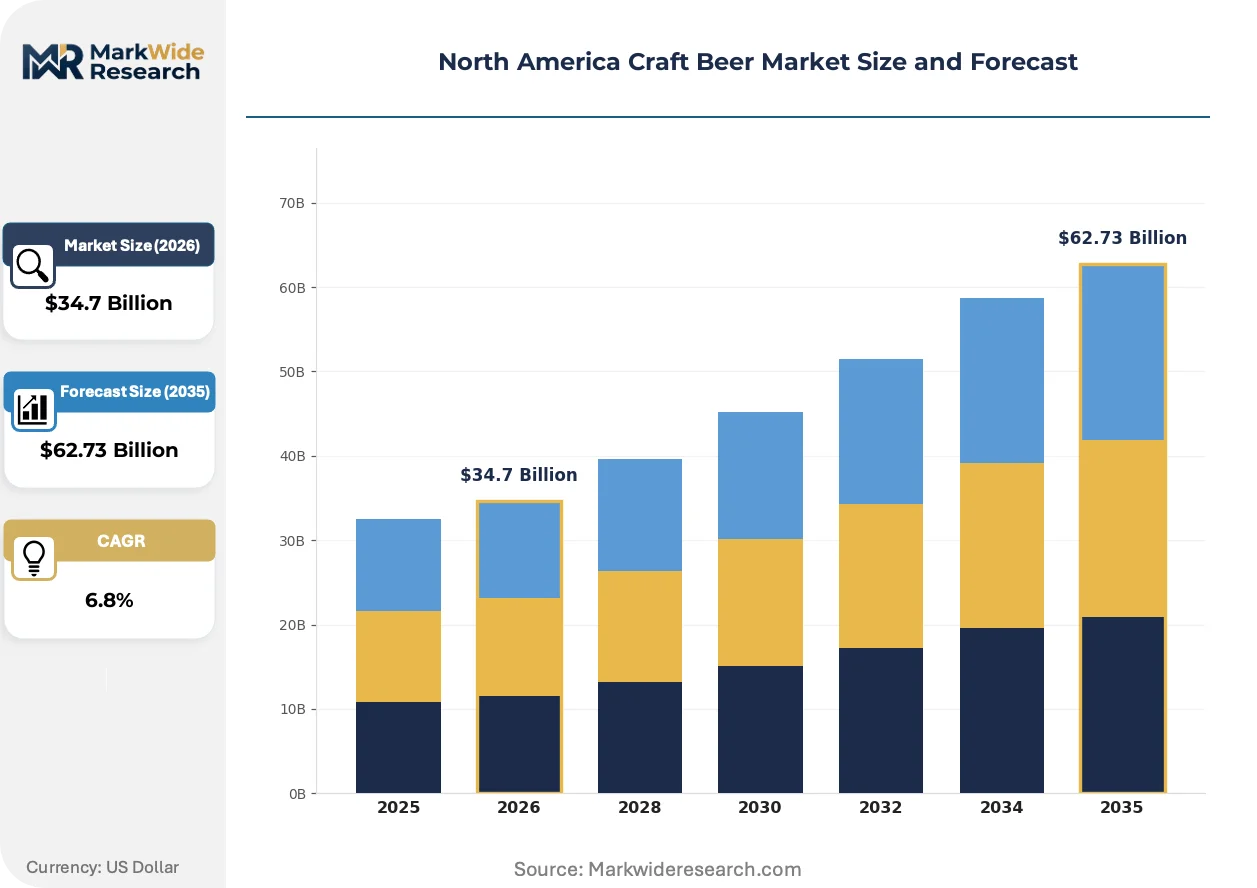
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $62.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ales, Lagers, Stouts, Porters Distribution Channel: Retail, On-Premise, E-commerce, Wholesalers Customer Type: Craft Beer Enthusiasts, Casual Drinkers, Events, Restaurants Brewing Technique: Traditional, Hybrid, Spontaneous Fermentation, Nitro |
| Companies Covered | Anheuser-Busch InBev, Boston Beer Company, D.G. Yuengling & Son, Constellation Brands, Heineken, Sierra Nevada Brewing Company, Molson Coors Beverage Company, Diageo, Duvel Moortgat USA, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Craft Beer Market Evolving Landscape
Flavor-forward experimentation and production technology upgrades are reconfiguring competitive differentiation mechanisms across the independent brewing tier.
Automated brewing control systems are migrating from large-scale regional campuses to mid-size production facilities. Brewpubs in the 5,000-15,000 barrel range are adopting sensor-driven fermentation monitoring that previously required dedicated laboratory staffing. This technology compression is enabling real-time gravity tracking and temperature modulation that reduces batch variation and ingredient waste.
The FDA Food Safety Modernization Act traceability mandates are elevating documentation standards for malt and hop suppliers. Ingredient lot tracking now extends backward through distributor tiers to farm-level harvest data. Smaller brewers without enterprise resource planning infrastructure face compliance cost burdens that favor supplier consolidation toward vertically integrated maltsters with built-in traceability systems.
Consumer preference rotation toward lower-ABV session formats is displacing high-gravity imperial stout dominance in seasonal release calendars. Taproom visitors in urban coastal markets are selecting four-percent alcohol-by-volume options at rates that alter production scheduling and tank allocation decisions. This consumption-pattern shift is most visible in Portland and San Diego metropolitan clusters where brewery density intensifies on-premise competition for visit frequency.
North America Craft Beer Market Segmentation
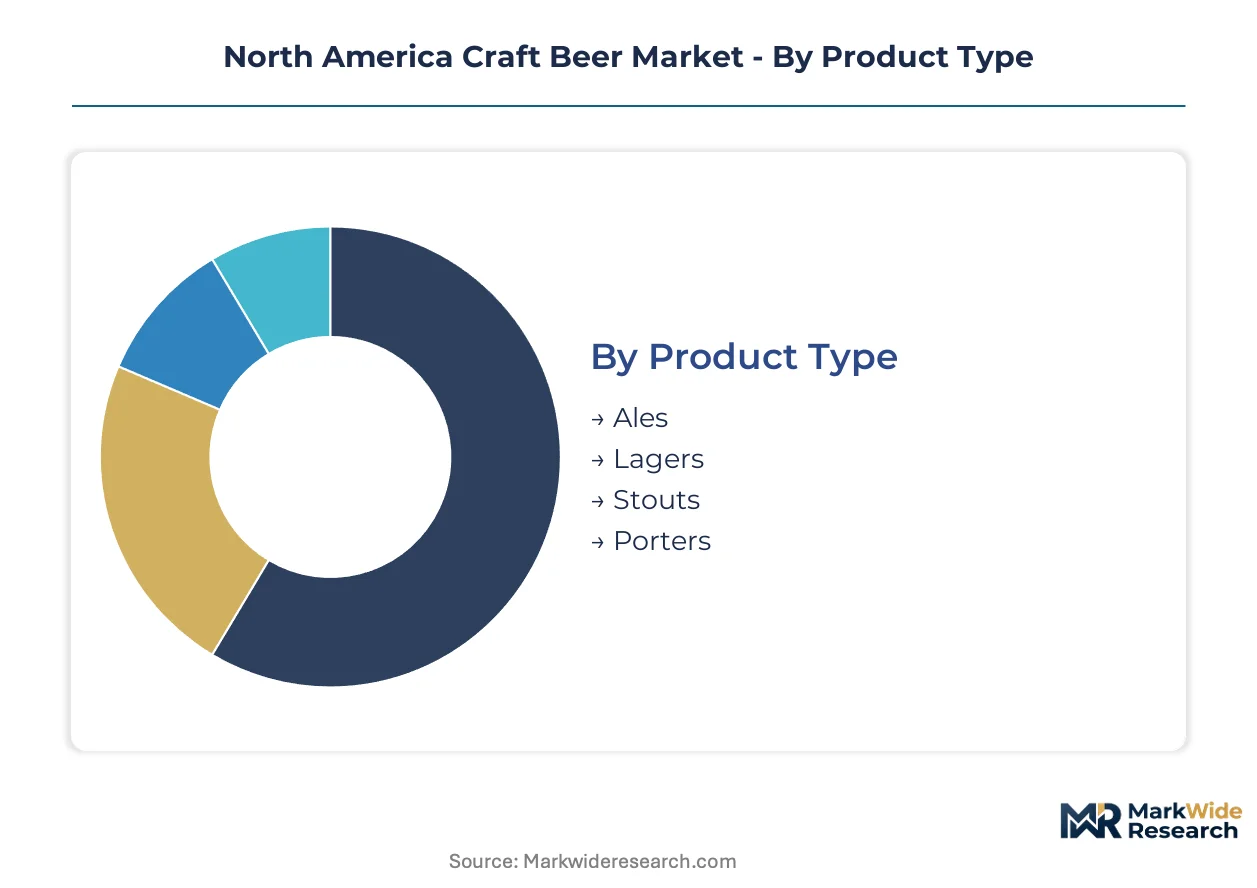
Segmentation reveals how craft beer value pools concentrate across brewing methodologies, consumption occasions, and regulatory access tiers. Understanding these divisions exposes where margin compression hits hardest and where premium pricing endures.
Product Type:
Flavor profile and fermentation biology determine production economics, with fermentation cycle length directly affecting tank turnover rates and working capital intensity.
- Ales:Top-fermenting Saccharomyces cerevisiae strains operate at warmer temperatures, enabling shorter production cycles and faster inventory rotation. Pacific Northwest brewpubs favor ales for seasonal rotation flexibility, though hop-forward IPA sub-styles face margin pressure from volatile Cascade and Centennial hop pricing.
- Lagers:Bottom-fermenting Saccharomyces pastorianus demands extended cold conditioning periods, tying up fermentation vessels for four to eight weeks versus one to two weeks for ales. Mexican-style lagers are gaining traction in Texas and California border markets as heritage-positioned alternatives to mass-market imports.
- Stouts:High-gravity dark ales utilizing roasted barley and chocolate malt additions command taproom premiums in urban Northeast markets.
- Porters:Lower-alcohol dark beer variants offer sessionable alternatives to imperial stouts in Midwest independent bottle shop channels.
Ales command the established base. The steepest expansion runs through lagers as heritage-style positioning displaces import dependency.
Distribution Channel:
Regulatory tier structure fragments access economics, with franchise law jurisdictions creating divergent margin stacking between producer and consumer price points.
- On-Premise:Brewpubs and gastropubs capture the highest per-ounce pricing through direct service labor and experience bundling. Oregon and Washington state taprooms benefit from self-distribution allowances that preserve margin on direct pours.
- E-commerce:Direct-to-consumer shipping platforms exploit regulatory carve-outs in California, Vermont, and Virginia, enabling subscription revenue models that bypass wholesale margin extraction. Compliance complexity limits participation to brewers with dedicated regulatory staff.
- Retail:Independent bottle shops and grocery chains face shelf-space competition from multinational craft-style sub-brands with distributor volume incentive backing.
- Wholesalers:Three-tier system mandates in most states legally bind small brewers to exclusive distribution agreements with limited termination rights.
On-premise channels command the established base. The steepest expansion runs through e-commerce as state-level regulatory liberalization accelerates.
Customer Type:
Consumption occasion and purchase motivation stratify pricing tolerance, with knowledge intensity determining brand loyalty versus switching behavior.
- Craft Beer Enthusiasts:High-involvement consumers pursuing style authenticity and brewery provenance drive limited-release queuing behavior and secondary market trading. This segment sustains barrel-aged program viability despite extended aging inventory costs.
- Restaurants:Food-pairing-focused accounts in metropolitan clusters prioritize local provenance claims and rotating draft handles to differentiate dining experiences.
- Casual Drinkers:Occasion-driven purchasers respond to packaging design and price-point positioning rather than style-specific education.
- Events:Festival and wedding catering demand concentrates in summer months, creating production scheduling and cold storage capacity challenges.
Craft beer enthusiasts command the established base. The steepest expansion runs through restaurants as gastropub format density climbs in urban markets.
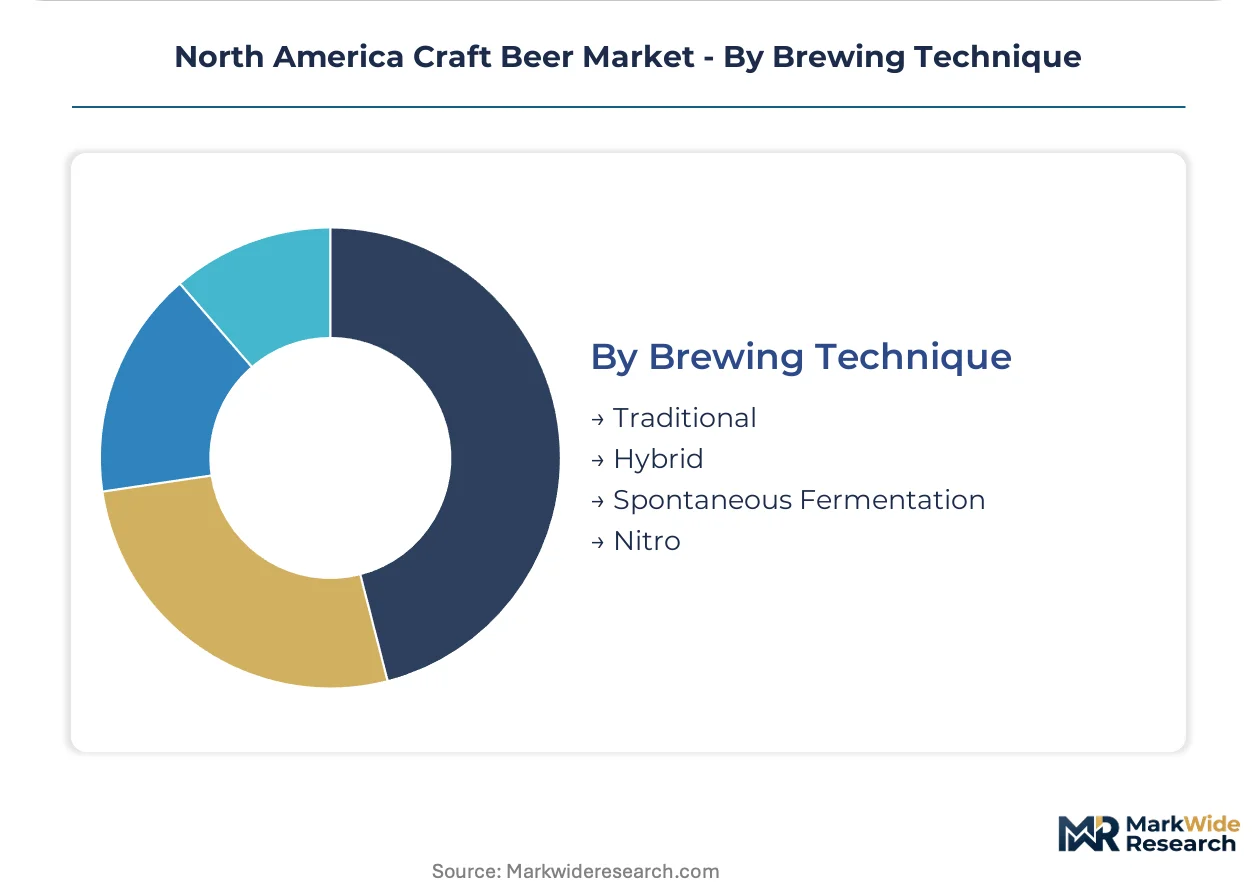
Brewing Technique:
Process innovation and equipment specialization create capability moats that separate scalable production from artisanal positioning.
- Nitro:Nitrogen-infusion systems utilizing restrictor plates produce cascading pour aesthetics and creamy mouthfeel differentiation. On-premise installation costs limit adoption to brewpubs with sufficient draft volume to amortize equipment investment.
- Traditional:Reinheitsgebot-adjacent all-malt brewing with specified hop schedules dominates regional brewery identity marketing in German-heritage Midwest markets.
- Hybrid:Cross-style fermentation protocols combining ale yeast with lager conditioning temperatures enable flavor profile experimentation.
- Spontaneous Fermentation:Coolship-opened inoculation utilizing ambient wild yeast and bacterial cultures requires dedicated barrel programs and extended aging infrastructure.
Traditional techniques command the established base. The steepest expansion runs through nitro as gastropubs deploy textural differentiation for premium pricing capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Long Beach anchors trans-Pacific malt and hop imports that supply West Coast brewing clusters, while the St. Lawrence Seaway system enables Great Lakes grain movements that sustain Midwest production corridors.
United States
Oregon and Washington state harbor dense specialty hop acreage that compresses procurement lead times for Pacific Northwest brewpubs. The Alcohol and Tobacco Tax and Trade Bureau governs interstate formula approvals and excise tax collection, creating compliance bottlenecks for experimental releases. San Diego and Portland metropolitan clusters exhibit intense brewery density that accelerates on-premise competition for visit frequency.
Canada
Alberta and Ontario provincial liquor board privatization trends unlock shelf-space access for US craft brands seeking volume diversification. The Canadian Food Inspection Agency imposes ingredient traceability mandates that elevate documentation burdens for cross-border suppliers. British Columbia's Lower Mainland concentrates craft production near Vancouver's urban consumption base.
Mexico
Baja California and Mexico City metropolitan zones absorb heritage-style lager positioning that displaces import dependency in border-adjacent markets. COFEPRIS regulates alcohol beverage labeling and health claims with divergent standards from US TTB requirements. Monterrey's industrial corridor hosts brewing equipment fabrication that shortens capital expenditure timelines for regional entrants.
North America Craft Beer Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in ingredient supply and equipment fabrication. The North American craft beer market exhibits tiered consolidation where multinational beverage conglomerates control mass distribution infrastructure while independent regional brewers occupy flavor-differentiated niches. Three strategic archetypes dominate: heritage-positioned price competitors, diversified beverage portfolio operators, and production-scale campus specialists. Competitive moves concentrate on portfolio diversification into adjacent non-alcohol categories and geographic expansion through cross-border provincial board negotiations.
Among diversified portfolio operators, Boston Beer Company exemplifies the multi-beverage platform archetype that leverages existing TTB-certified production infrastructure for line extensions. Sierra Nevada Brewing Company anchors the production-scale specialist tier through multi-campus brewing operations. D.G. Yuengling & Son occupies the heritage-positioned price competitor niche with Southeastern and mid-Atlantic market concentration.
| Leading Market Players |
|---|
| Anheuser-Busch InBev |
| Boston Beer Company |
| D.G. Yuengling & Son |
| Constellation Brands |
| Heineken |
| Sierra Nevada Brewing Company |
| Molson Coors Beverage Company |
| Diageo |
| Duvel Moortgat USA |
| Others |
Value Network & Pricing Analysis
Yakima Valley hop acreage concentration in Washington state anchors ingredient cost volatility that cascades through Pacific Northwest brewpub margins and compresses pricing autonomy for IPA-dominant portfolios downstream.
Pricing Analysis
Volume-discount tiering structures separate craft beer enthusiasts from casual drinkers and events-based purchasers. Three-tier pricing structure across premium, standard, and economy levels stratifies by brand heritage claims and taproom experience bundling. Pricing pressure stems from multinational craft-style sub-brands capturing shelf space through distributor volume incentives. Casual drinkers exhibit highest price sensitivity, while craft beer enthusiasts sustain premium tolerance for barrel-aged limited releases.
Supply Chain Analysis
Extended payment terms from maltsters with built-in traceability systems are easing working capital constraints for sub-10,000 barrel facilities. Raw material flows draw from Washington state specialty hop yards, Canadian prairie malt barley, and Mexican heritage corn for adjunct lagers. Single-source vulnerability concentrates in Cascade and Centennial aroma hop varieties from Willamette Valley. Distribution runs through wholesaler tier controls in franchise law states, though self-distribution carve-outs bypass margin stacking in Oregon and Vermont.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated gastropub chains and subscription platform operators, fragmenting pricing leverage once held by independent bottle shops and specialty retailers.
For Market Incumbents: Insulate core barrel-aged programs from margin compression by securing multi-year hop contracts with Yakima Valley growers before climate volatility escalates. Add nitrogen-infusion capacity at flagship taprooms to capture textural premium pricing. Diversify into hop-water and functional seltzer line extensions using existing TTB-certified infrastructure to offset beer volume softness.
For New Entrants and Emerging Players: Alberta and Ontario provincial liquor board privatization trends represent the most penetrable entry point for US craft brands seeking volume diversification beyond saturated domestic markets. Mid-size production facilities in Baja California can leverage Monterrey equipment fabrication proximity to compress capital expenditure timelines. Direct-to-consumer subscription models in California and Vermont offer go-to-market pathways that bypass wholesale tier margin extraction.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional brewery platforms lacking diversified beverage capabilities. Long-term viability hinges on portfolio breadth across non-alcohol adjacencies and cross-border Canadian distribution scale. Watch for state legislative franchise law reform proposals as inflection indicators for self-distribution pathway unlocking.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Channel Expansion | Regulatory carve-outs in California and Vermont enable subscription revenue models bypassing wholesale margin stacking. |
| Cross-Border Canadian Market Entry | Alberta and Ontario provincial liquor board privatization creates shelf-space access for volume diversification. |
| Non-Alcohol Portfolio Convergence | TTB-certified production facilities accommodate hop-water and functional seltzer line extensions using existing infrastructure. |
| Specialty Hop Supply Contracting | Multi-year agreements with Yakima Valley growers hedge against climate-driven Cascade and Centennial yield volatility. |
| Nitrogen-Infusion System Deployment | Gastropub textural differentiation commands premium pricing over standard carbonated pours in on-premise channels. |
Research Methodology
Cross-validation between brewmaster interviews and distributor financial disclosures anchors the qualitative findings on margin compression dynamics. Primary fieldwork engaged craft brewery owners, TTB compliance officers, wholesale tier procurement managers, and gastropub beverage directors. Secondary sources included Alcohol and Tobacco Tax and Trade Bureau formula approval databases, state alcohol beverage control agency regulatory filings, and Canadian Food Inspection Agency cross-border compliance documentation. Bottom-up production volume estimates triangulated against top-down retail audit data from independent bottle shop channels.
Calibration against historical franchise law reform episodes and direct-to-consumer regulatory liberalization patterns shaped the projection framework. Segmentation modeling spanned product type, distribution channel, customer motivation, and brewing technique dimensions across the analysis window. CAGRs derived from weighted average growth assumptions calibrated to TTB excise tax collection trajectories and provincial liquor board volume disclosures. Input variables included hop yield volatility indices and self-distribution regulatory penetration rates.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending patterns or aluminum tariff regimes would shift the trajectory. Forecasts assume continued three-tier system structural lock-in with selective carve-out expansion. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Cocktail Mixers Market
Alcoholic Beverages
Asia Pacific Wine Coolers Market
Alcoholic Beverages
Beer Dispensing Machine Market
Alcoholic Beverages
Barrel Liner Market
Alcoholic Beverages
Europe Beer Market
Alcoholic Beverages
Liquor Flavored Ice Cream Market
Alcoholic Beverages
South America Wine Market
Alcoholic Beverages
Home Beer Brewing Machine Market
Alcoholic Beverages
E-Commerce Liquor Market
Alcoholic Beverages
Rhum Agricole Market
Alcoholic Beverages
Vermouth Market
Alcoholic Beverages
Beer Kegs Market
Alcoholic Beverages
Herbal Distillates Market
Alcoholic Beverages
Cannabis Beverages Market
Alcoholic Beverages
Asia-Pacific Craft Beer Market
Alcoholic Beverages
Alcopop Market