
 Organic Beer Market | 2026-2036
Organic Beer Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Beer Market Intelligence
Direct-to-consumer sales through online platforms and taprooms is fragmenting the traditional three-tier distribution model. Large brewers like Anheuser-Busch and Heineken compete by acquiring smaller organic labels to enter the segment. In contrast, dedicated craft producers such as Hopworks Urban Brewery differentiate through a core commitment to certified organic ingredients and sustainable brewing processes from inception.
Organic beer is a beverage produced using ingredients, primarily malt, hops, yeast, and water, that are certified organic and grown without synthetic pesticides or GMOs. Production requires strict adherence to a certified supply chain, from farm to brewery, to meet regulatory standards. While ales and lagers command the largest share of product types, growth is notable in specialty stout and pilsner categories. Distribution through specialty stores and restaurants provides higher margins compared to supermarkets, with cans gaining preference over bottles for their recyclability and lower shipping weight.
Market access hinges on compliance with stringent certification bodies like the USDA's National Organic Program and the European Union's organic farming regulations. These frameworks govern everything from ingredient sourcing to labeling, forming the basis for consumer trust and premium pricing. The ability to secure a consistent and verifiable supply of organic hops and barley remains a critical factor for brewers aiming to expand production.
Market Dynamics
The central structural force shaping the organic beer market is the persistent tension between rising consumer demand for verifiable sustainability and the constrained, fragmented supply of certified organic ingredients like hops and barley, which dictates production capacity and market entry.
Growth Catalysts
- Certification Frameworks:Strict standards like the USDA National Organic Program and the EU organic logo build consumer trust and justify premium pricing, creating a clear value proposition for certified products over conventional alternatives.
- Channel Demand:Demand from specialty retail stores and environmentally conscious restaurants provides high-margin distribution channels for brewers, supporting brand positioning away from competitive supermarket shelves.
- Geographic Concentration:Strong consumer interest in established markets, including Germany, the United States, and Canada, creates dense demand clusters that allow brewers to focus marketing and distribution efforts effectively.
Market Restraints
- Input Supply Volatility:The limited global acreage dedicated to certified organic hops and barley creates a supply bottleneck, leading to price volatility and sourcing challenges that can halt production expansion for brewers.
- Cost Structure:Higher agricultural costs for organic farming, coupled with expensive certification and audit requirements, result in a premium final product price that can limit appeal among price-sensitive consumer segments.
- Regulatory Barriers:The complexity and expense of achieving and maintaining organic certification under frameworks like those from the USDA or EU regulators act as a significant barrier to entry, particularly for small or startup breweries.
Strategic Opportunities
- Product Line Extension:Brewers have an opportunity to innovate beyond common ales and lagers by developing certified organic versions of specialty styles like stouts, sours, and pilsners to attract discerning craft beer enthusiasts.
- Direct-to-Consumer Channels:The expansion of online sales platforms and brewery-owned taprooms allows producers to bypass the traditional three-tier distribution system, capture higher margins, and build direct customer relationships.
- New Market Entry:Significant white space exists in regions like parts of Asia-Pacific and Latin America, where consumer awareness of organic goods is increasing but local organic beer production remains underdeveloped.
Industry Challenges
- Supply Chain Integrity:Maintaining end-to-end traceability and segregation for certified organic ingredients from farm to brewery is an operational challenge that requires significant investment in logistics and quality assurance systems.
- Brand Differentiation:Communicating the tangible benefits of organic certification beyond the label itself is a key marketing challenge, especially in crowded markets where consumers face a wide array of craft and specialty beer choices.
- Scaling Production:Expanding brewing capacity while strictly adhering to organic production standards presents a significant operational hurdle, as rapid scaling can compromise the batch integrity and sourcing protocols required for certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Beer Market |
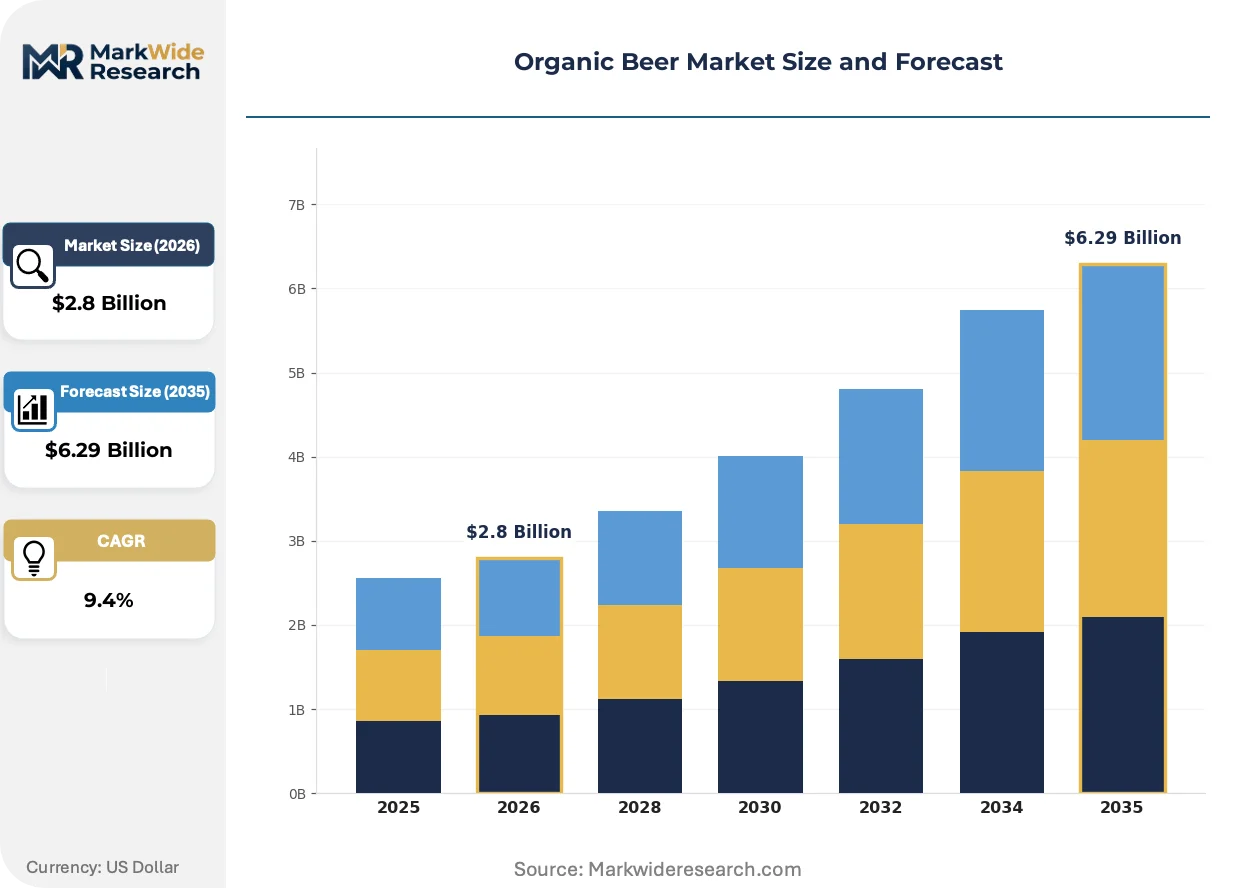
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.29 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lager, Ale, Stout, Pilsner, Wheat Beer, Amber Beer Ingredient Source: Organic Barley, Organic Hops, Organic Yeast, Organic Malt, Organic Wheat Packaging Type: Bottle, Can, Keg, Growler, Box, Plastic Flask Distribution Channel: Online Retail, Specialty Stores, Liquor Stores, Supermarkets, Bars, Restaurants |
| Companies Covered | Anheuser-Busch, Heineken, Carlsberg, Hopworks Urban Brewery, Lakefront Brewery, Eel River Brewing, Asher Brewing, Bison Brewing, Samuel Smith, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Beer Market Strategic Shifts & Innovations
A convergence of agricultural technology and sustainable packaging innovation is reshaping the production and market appeal of organic beer. These shifts address both core operational efficiencies for brewers and evolving environmental preferences among consumers, redefining competitive positioning in the sector.
Advanced water reclamation systems are becoming a key feature in sustainable brewing operations. These closed-loop technologies use membrane filtration and UV sterilization to purify and reuse process water from cleaning and cooling cycles. Environmentally conscious craft breweries are adopting these systems to drastically lower their water consumption and utility costs. This focus on resource efficiency is rendering obsolete the traditional high-volume, single-pass water usage models previously common in brewing.
The European Union's updated organic farming regulations are forcing adjustments across the supply chain. These stricter rules, part of the broader EU Green Deal, tighten controls on ingredient origins, soil management, and allowable processing aids. This is compelling brewers to invest in more localized and transparent supply chains within the EU. Lager and pilsner producers are most affected due to their reliance on specific hop and barley varieties, spurring new agricultural partnerships.
Consumer preference is decisively shifting from glass bottles toward aluminum cans, particularly in the craft and organic segments. This change is driven by the superior recyclability, lower shipping weight, and greater convenience of cans for active lifestyles. The trend is disrupting packaging lines and favoring breweries equipped with modern canning capabilities over traditional bottling infrastructure. This behavioral shift is most visible in North American markets like the United States and Canada.
Organic Beer Market Segmentation
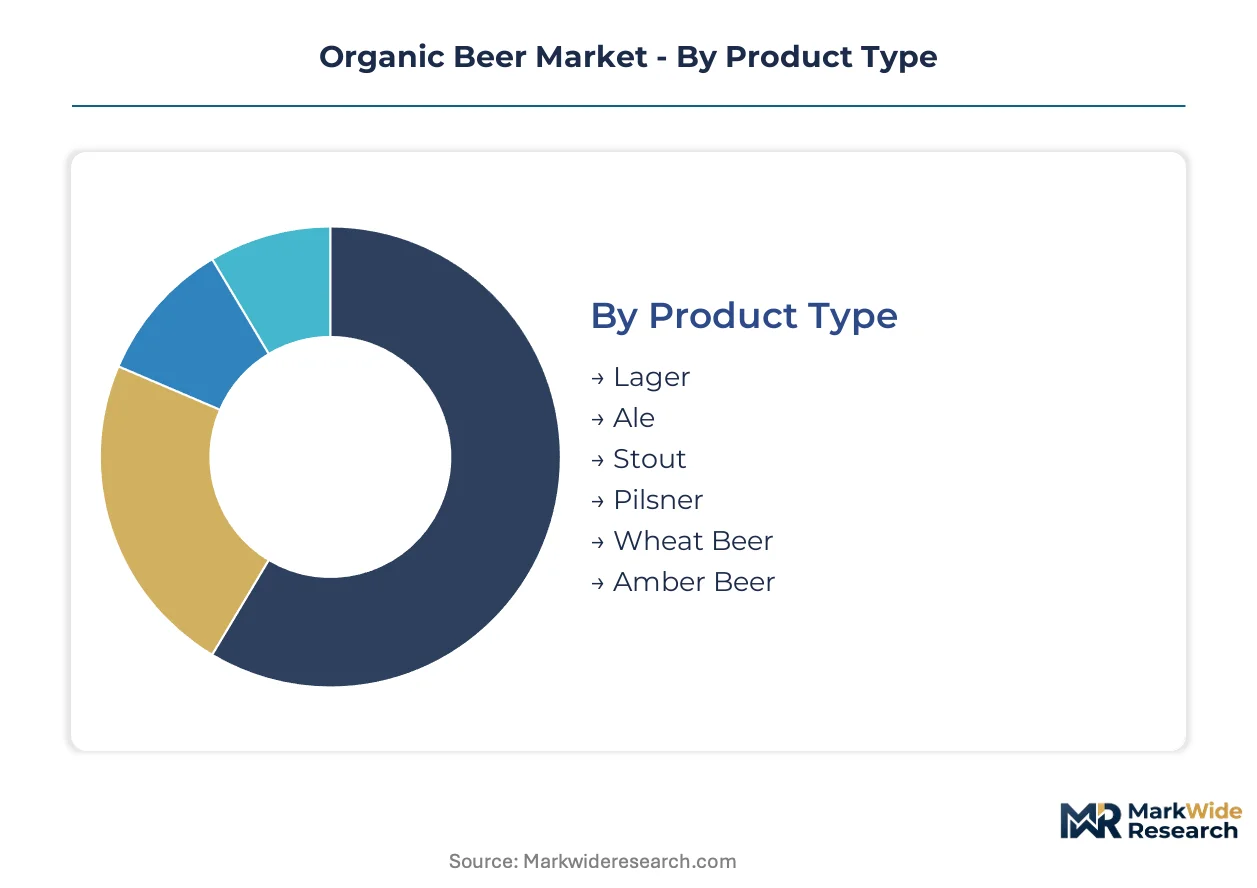
The organic beer market exhibits diverse segmentation across product types, ingredient sources, packaging, and distribution channels. Understanding these segments helps brewers tailor their offerings and market strategies to specific consumer preferences and operational realities. This granular view reveals where value accrues and competitive differentiation is most effective.
Product Type:
The after-sales service intensity for organic beer product types varies with consumer knowledge and serving requirements. Specialty styles often demand more informed consumption, impacting customer engagement.
- Ale:Ales are top-fermented beers with complex flavor profiles, brewed at warmer temperatures. Consumer demand for organic ales is strong in the United States, driven by craft products.
- Lager:Lagers are bottom-fermented beers conditioned at cooler temperatures, resulting in a crisp taste. Germany shows significant demand for organic lagers, influenced by traditional methods.
- Stout:Stouts are dark, rich beers made with roasted malt or barley, offering notes of coffee or chocolate.
- Pilsner:Pilsners are pale lagers with a distinctive hop character and golden color, originating from the Czech Republic.
- Wheat Beer:Wheat beers contain significant wheat, often presenting a cloudy appearance and fruity, spicy notes.
- Amber Beer:Amber beers are characterized by their amber color and balanced malt-hop profile, offering a medium body.
Ale holds the largest share; momentum sits with Stout and Pilsner.
Ingredient Source:
The supply concentration of organic ingredients significantly influences production capacity and market entry for brewers. Access to consistent, certified raw materials remains a critical bottleneck.
- Organic Barley:Organic barley forms the primary fermentable sugar source for most organic beers, requiring extensive certified acreage. Sourcing challenges impact production volumes in Canada.
- Organic Hops:Organic hops provide bitterness, aroma, and flavor to organic beers, demanding stringent certification. Limited global acreage creates price volatility for brewers in the United States.
- Organic Yeast:Organic yeast strains are crucial for fermentation, converting sugars into alcohol and contributing to flavor.
- Organic Malt:Organic malt is barley that has undergone malting, a controlled germination process to activate enzymes.
- Organic Wheat:Organic wheat is used in specific beer styles, contributing to body and head retention.
Ingredient sourcing for Organic Barley presents the most significant challenge, while Organic Yeast offers broader availability.
Packaging Type:
Customer type and consumption occasion heavily influence the preferred packaging format for organic beer. Convenience, portability, and environmental considerations drive choices.
- Can:Aluminum cans offer superior recyclability, protection from light, and lighter shipping weight, appealing to conscious consumers. Preference for cans is strong in North American markets.
- Bottle:Glass bottles provide a traditional aesthetic, often preferred for premium organic beers, offering a clear view. European markets, especially Germany, maintain strong preference.
- Keg:Kegs are used for bulk distribution to bars and restaurants, ensuring freshness for on-premise consumption.
- Growler:Growlers are reusable containers filled directly from a tap, popular for fresh, draft organic beer sales at breweries.
- Box:Box packaging is less common for organic beer but can be used for larger format, bulk sales.
- Plastic Flask:Plastic flasks are a niche packaging option, occasionally used for convenience or specific event consumption.
The shift towards Can packaging reflects evolving consumer preferences, with Bottle maintaining a traditional market presence.
Distribution Channel:
Margin structures and consumer access dictate the strategic importance of various distribution channels for organic beer producers. Direct consumer engagement generally yields higher profitability.
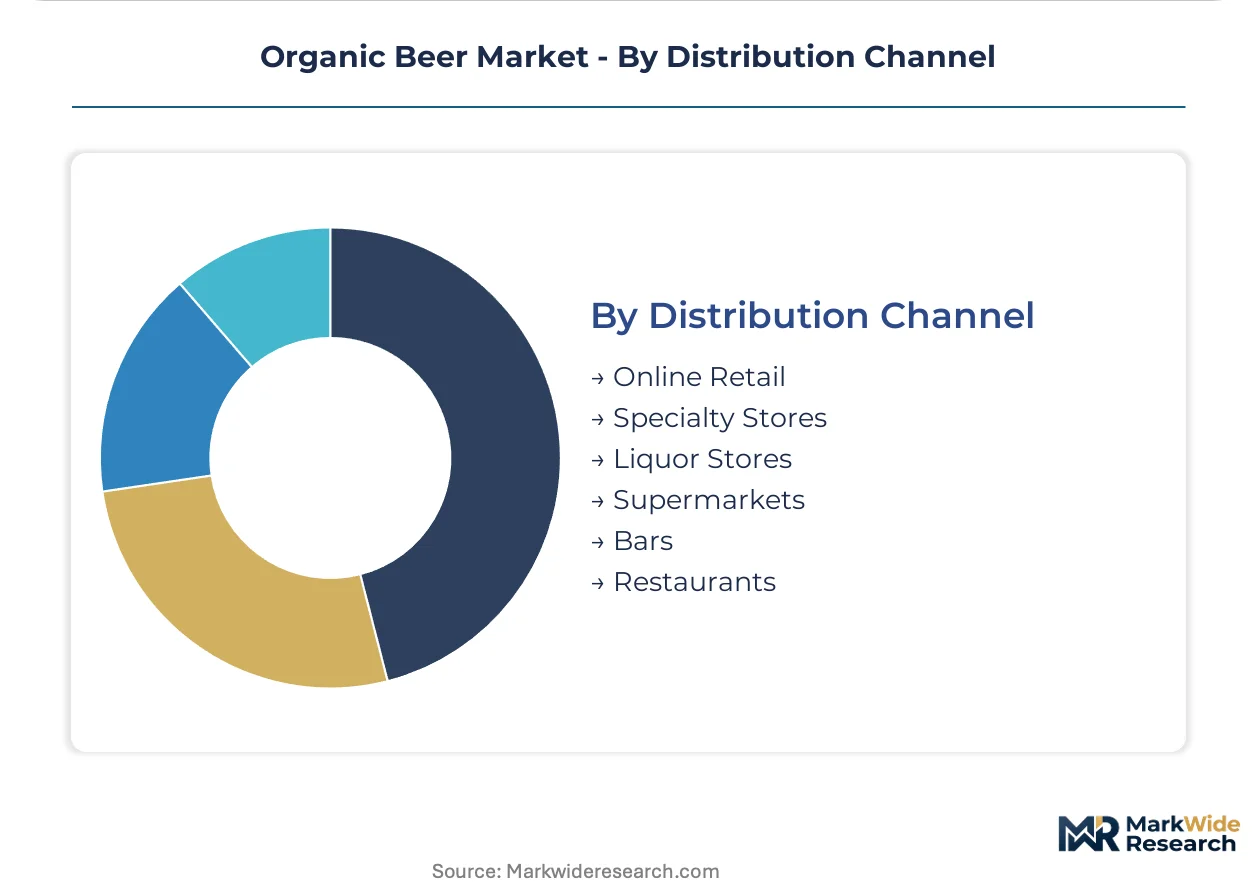
- Specialty Stores:Specialty stores offer curated selections and knowledgeable staff, providing higher margins and brand positioning for premium organic beers. Demand is strong in urban centers across the United States.
- Online Retail:Online retail platforms allow brewers to reach a broader audience directly, bypassing traditional tiers and capturing higher profit margins. This channel is expanding most quickly in Canada.
- Liquor Stores:Liquor stores provide a dedicated retail environment for alcoholic beverages, offering a focused sales channel.
- Supermarkets:Supermarkets offer high-volume sales and broad consumer reach, though often with lower margins.
- Bars:Bars serve organic beer on-premise, providing a social consumption experience and brand exposure through draft offerings.
- Restaurants:Environmentally conscious restaurants increasingly feature organic beer on their menus, aligning with sustainable sourcing.
Channels like Specialty Stores and Online Retail are critical for market penetration and brand visibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply-side concentration of certified organic ingredients significantly influences regional market development for organic beer. This dynamic drives brewers to secure consistent raw material access, impacting production capacity. Consequently, market growth often aligns with the availability of organic hops and barley.
United States
Strong consumer demand for craft organic ales drives market growth across the United States. The USDA National Organic Program provides stringent certification standards for organic beer production. California's craft brewing hubs, like San Diego, see significant organic product innovation and market penetration.
Germany
Germany's traditional beer culture fuels robust demand for organic lagers and pilsners. The EU organic farming regulations mandate strict ingredient sourcing and processing for brewers. Bavaria's numerous breweries are actively adapting to these enhanced regulatory requirements.
Canada
Canadian consumer preference for cans and online retail channels expands organic beer accessibility. Health Canada's organic standards govern product labeling and ingredient claims within the country. British Columbia's thriving craft scene embraces sustainable organic brewing practices.
United Kingdom
Growing interest in sustainable products boosts organic stout and specialty beer consumption across the United Kingdom. UK organic certification bodies ensure product integrity and consumer trust. London's independent breweries increasingly offer certified organic options to meet this demand.
Australia
Rising health consciousness supports organic beer sales, particularly in Australia's urban centers. Australian Certified Organic (ACO) standards regulate organic ingredient supply and production processes. Melbourne's vibrant food and drink scene features an expanding organic beer selection.
Organic Beer Market Key Industry Players
Large multinational conglomerates and dedicated craft producers split the organic beer market, reflecting divergent strategic priorities. Major players pursue segment entry through strategic acquisitions of smaller organic labels, expanding their portfolio presence. Dedicated craft breweries emphasize differentiation through a core commitment to certified organic ingredients and sustainable brewing processes from inception. Market participants engage in portfolio diversification and geographic expansion to capture evolving consumer interest.
Within the dedicated craft producer archetype, Hopworks Urban Brewery exemplifies a core commitment to certified organic ingredients and sustainable brewing processes from inception. This approach often involves direct-to-consumer sales and strong local community ties. Multinational entities like Anheuser-Busch and Heineken represent the strategy of acquiring smaller organic labels to enter this specialized segment, leveraging their extensive distribution networks for broader reach. These companies anchor different ends of the market spectrum, reflecting diverse approaches to organic beer production, market penetration, and brand building across various consumer tiers.
| Leading Market Players |
|---|
| Anheuser-Busch |
| Heineken |
| Carlsberg |
| Hopworks Urban Brewery |
| Lakefront Brewery |
| Eel River Brewing |
| Asher Brewing |
| Bison Brewing |
| Samuel Smith |
| Others |
Cost & Logistics Intelligence
European rail networks' cost dynamics directly influence organic beer ingredient supply concentration, ultimately shaping downstream price differentiation for certified products. This logistical dependency creates distinct regional pricing tiers.
Pricing Analysis
EU organic farming regulations dictate the pricing tier structure for organic beer, establishing a clear premium over conventional alternatives. Price differentiation stems from the specific certification level and established brand premium. Cost compression in the standard organic tier intensifies due to supermarket competition. Price-sensitive consumers in mass retail channels contrast with less sensitive buyers in specialty stores.
Supply Chain Analysis
European Union's updated organic farming regulations, by tightening controls on ingredient origins, effectively limit the flow of certified organic barley and hops. Geographic supply concentrates in regions like Germany and parts of the United States for these critical inputs. Commodity price volatility for organic hops creates a significant supply chain risk. Distribution largely functions through a traditional three-tier system, increasingly complemented by direct-to-consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The organic beer market requires a strong substitution defense, as incumbents must navigate the threat posed by conventional craft beer's broad appeal and lower price point. Maintaining certified organic integrity against this substitute requires focused strategy.
For Market Incumbents: Insulate core organic beer offerings by acquiring smaller, certified organic labels to expand portfolio breadth and market share. Invest in localized organic barley and hop supply chains within key markets like Germany to mitigate input volatility and ensure consistent quality. This strategy defends against the pervasive threat of conventional craft beer market saturation. Controlling direct-to-consumer channels also strengthens brand loyalty.
For New Entrants and Emerging Players: Specialty stout and pilsner categories, alongside regions like Asia-Pacific and Latin America, represent the most penetrable entry points for new organic beer brands. These white spaces show rising consumer awareness for organic goods but lack established local production. A direct-to-consumer go-to-market strategy, leveraging online platforms, allows for efficient market entry and higher margin capture. Focus on unique flavor profiles and sustainable packaging.
For Investors and Strategic Acquirers: Dedicated craft producers with strong organic certification and established direct-to-consumer channels offer compelling acquisition targets. Long-term viability is underpinned by sustained consumer demand for verifiable sustainable products over the next decade. These smaller breweries often possess authentic brand stories and localized supply networks. The consistent growth in certified organic ingredient acreage is the signal to watch for broader market expansion potential.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Line Diversification | Attracts discerning craft beer enthusiasts with certified organic versions of specialty styles like sours. |
| Direct-to-Consumer Channel Expansion | Bypasses traditional distribution, capturing higher margins and fostering direct customer relationships. |
| Localized Organic Ingredient Sourcing | Mitigates supply chain volatility and ensures consistent access to certified raw materials. |
| Advanced Water Reclamation Systems | Significantly lowers water consumption and operational costs, enhancing environmental credentials. |
| Sustainable Packaging Shift (Cans) | Aligns with consumer preference for recyclability and reduces shipping weight, improving logistics. |
Research Approach
A standing panel of brewery owners, organic ingredient suppliers, specialty retail buyers, and sustainability consultants provided ongoing calibration for market estimates. Primary interviews with these industry stakeholders were rigorously validated against secondary data. Secondary sources included USDA National Organic Program reports, EU Green Deal documents, trade association publications, and consumer preference surveys. This approach facilitated robust bottom-up and top-down triangulation.
Scenario-bracketing defined the analytical framework, projecting market trajectories across the analysis window. Segmentation dimensions modeled included product type, ingredient source, packaging type, distribution channel, and regional regulatory compliance. Compound Annual Growth Rates were derived from historical data and projected market drivers. Key forecast inputs included organic acreage expansion rates and evolving craft beer consumption trends.
Macroeconomic conditions sit as an overlay; deviation in global consumer spending or agricultural policy would shift the trajectory. Forecasts reflect assumptions regarding market dynamics and technological adoption. Material shifts in unforeseen regulatory changes or severe climate events impacting organic harvests would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
West Africa Alcoholic Beverages Market
Alcoholic Beverages
Germany Tequila Market
Alcoholic Beverages
Global Distillation System Market
Alcoholic Beverages
Tonic Wine Market
Alcoholic Beverages
Beer Bottle Market
Alcoholic Beverages
RTD Bottled Cocktails Market
Alcoholic Beverages
Global Liquor Bottles Market
Alcoholic Beverages
Commercial Wine Dispenser Market
Alcoholic Beverages
US Wine Cooler Market
Alcoholic Beverages
Coconut Alcohol Market
Alcoholic Beverages
Built-In Wine Coolers Market
Alcoholic Beverages
Whiskey Market
Alcoholic Beverages
Whey Based Vodka Market
Alcoholic Beverages
Moscato Wine Market
Alcoholic Beverages
Premixed Margarita Market
Alcoholic Beverages
Barware Market