
 US Bubble Tea Market | 2026-2036
US Bubble Tea Market Size, Share, and Industry Trends Forecast 2026-2036
US Bubble Tea Market Outlook
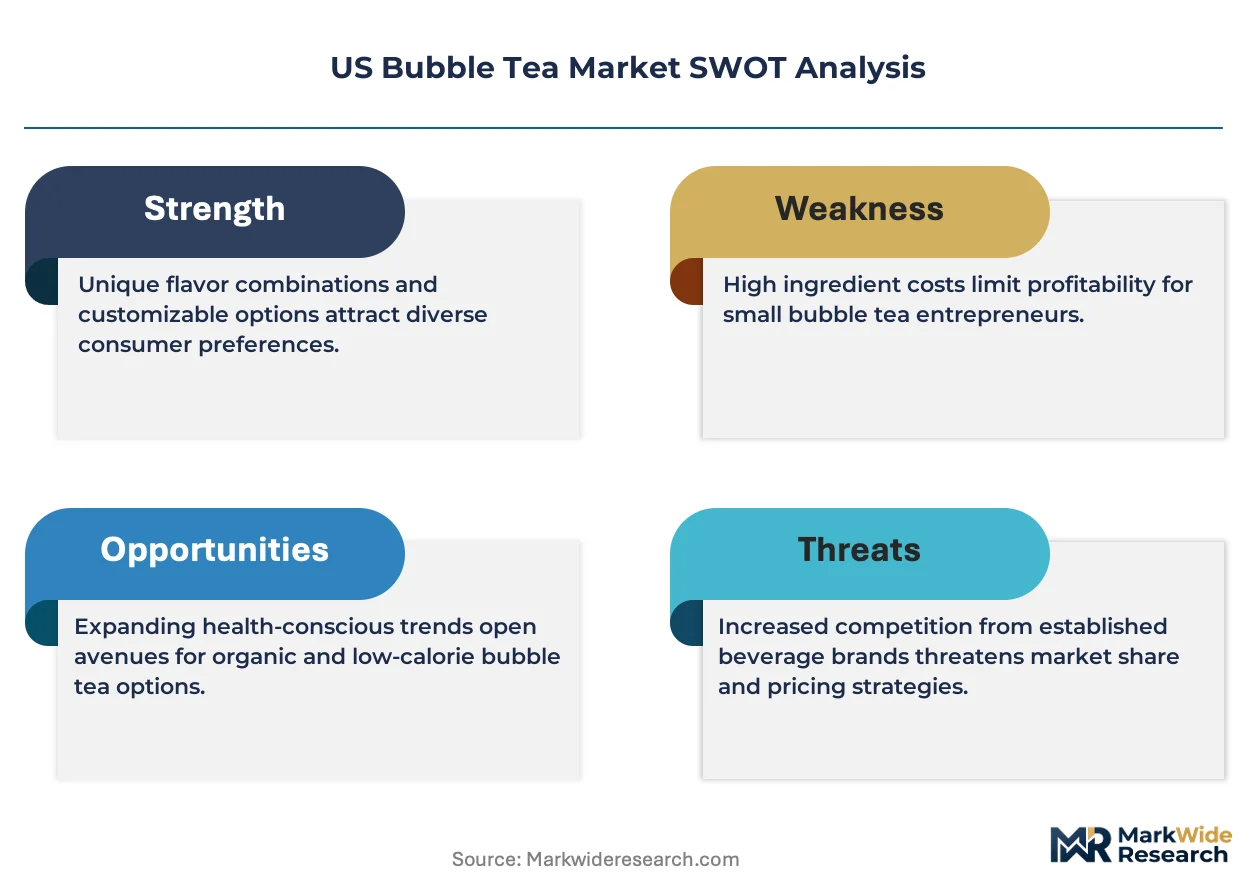
Multi-source procurement of tapioca pearls and flavor syrups is broadening as chains reduce dependence on single Asian suppliers. Kung Fu Tea leverages captive relationships with Taiwanese starch processors to secure consistent pearl quality. Gong Cha sustains its position through direct sourcing agreements that bypass intermediary distributors. The Boba Guys differentiates via vertically controlled in-house syrup production at its California commissary.
Bubble tea comprises brewed tea base combined with milk or fruit puree, sweetener, and chewy tapioca starch pearls typically measuring 8-10 millimeters in diameter, served cold with a wide-bore straw engineered to accommodate the textured inclusions. The beverage functions as a refreshment product positioned between coffee shop culture and dessert occasion consumption. Milk tea occupies the dominant revenue position within product type segmentation due to its flavor familiarity and repeat purchase rates. Popping boba represents the fastest-expanding ingredient category, displacing traditional tapioca among younger consumer segments seeking novel texture experiences. Food trucks and mobile units capture disproportionate trial volume among teens and young adults, though cafe channels retain higher per-transaction averages.
FDA import alert protocols for tapioca starch and the Food Safety Modernization Act's foreign supplier verification program shape ingredient sourcing compliance costs for US operators. State-level health department grading systems in California and New York directly influence storefront location viability and consumer traffic patterns. Stakeholders must monitor evolving FDA guidance on novel food ingredients as popping boba and alternative base formulations test existing additive approval frameworks.
Market Dynamics
Gen Z and millennial consumers in US college towns and urban centers are accelerating visit frequency to specialty beverage shops, compressing the traditional coffee-to-dessert consumption window and forcing operators to rethink daypart menu engineering.
Growth Catalysts
- FDA Foreign Supplier Verification Programs:These protocols are elevating quality standards across the tapioca pearl supply base, disqualifying low-grade importers and creating premium shelf space for compliant processors.
- Popping boba texture innovation:This fruit-juice-filled sphere format is capturing trial among teens and young adults seeking novel mouthfeel experiences beyond traditional starch-based pearls.
- Asian-American population corridors in California:These demographic clusters anchor consistent baseline demand that supports specialty supplier ecosystems and trained labor pools.
Market Restraints
- Tapioca starch import concentration:Taiwan and Thailand supply the majority of US food-grade pearl inputs, exposing operators to ocean freight volatility and currency fluctuation risk.
- State health department grading systems:California and New York inspection protocols create location-specific compliance burdens that filter out undercapitalized entrants.
- Ready-to-drink tea substitution:Bottled milk tea products at grocery and convenience retail capture at-home consumption occasions that specialty shops cannot economically serve.
Strategic Opportunities
- Mobile food truck channels:These units capture disproportionate trial volume among teens and young adults in Texas and Florida secondary cities where permanent retail rents remain prohibitive.
- Vertically controlled syrup production:In-house flavor manufacturing at regional commissaries enables rapid LTO rotation and margin protection against commodity sweetener swings.
- FDA novel food ingredient pathways:Early engagement with emerging additive approval frameworks positions operators to commercialize next-generation base formulations ahead of competitors.
Industry Challenges
- Beverage equipment technician scarcity:Specialized knowledge of sealed refrigeration systems and carbonation rigs commands premium wages in tight labor markets.
- FSMA compliance timeline compression:Imported ingredient documentation requirements strain back-office capacity at multi-unit operators managing dozens of SKUs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Bubble Tea Market |
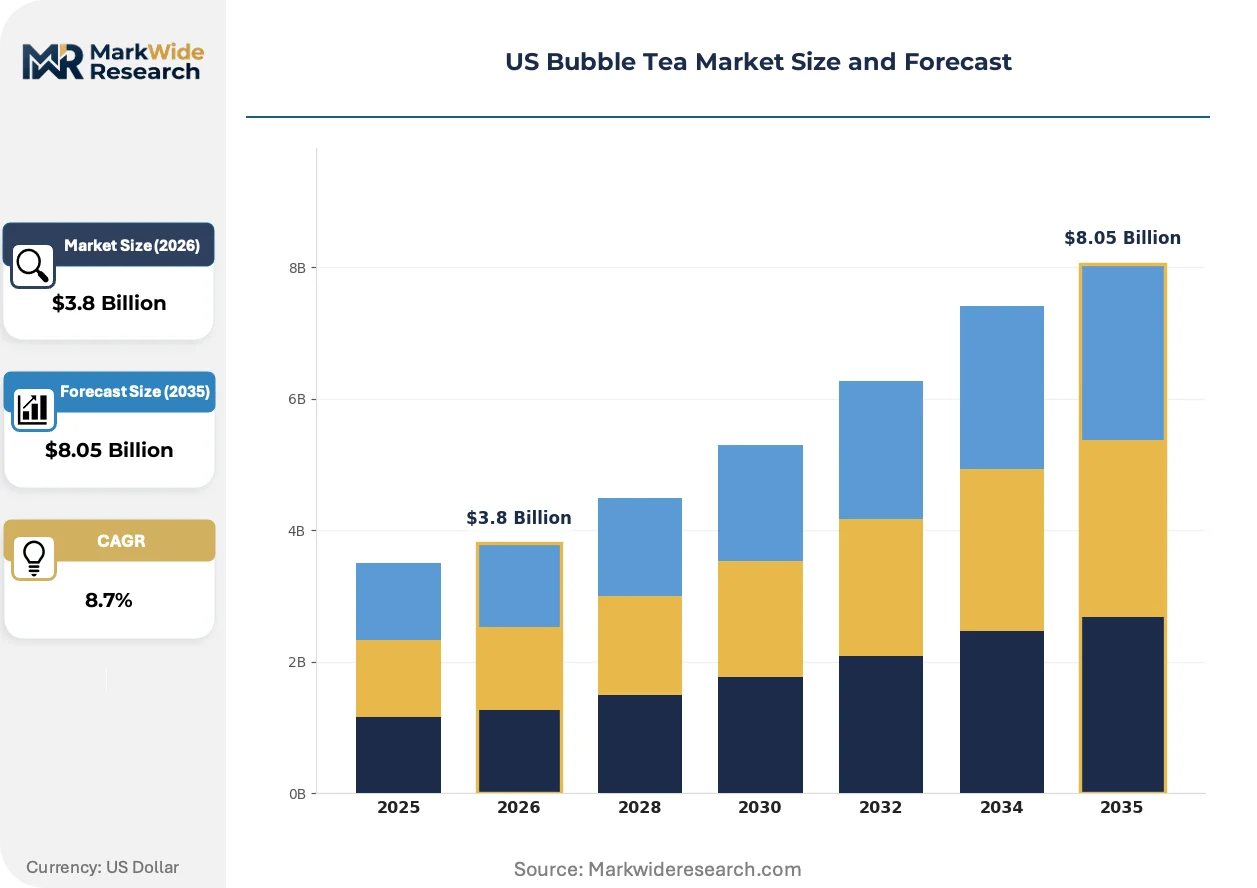
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Milk Tea, Fruit Tea, Smoothies, Slushies Ingredient Type: Tapioca Pearls, Jelly, Popping Boba, Grass Jelly Consumer Type: Teens, Young Adults, Families, Professionals Sales Channel: Online, Cafes, Retail Stores, Food Trucks |
| Companies Covered | Lollicup USA Inc., The Boba Guys, Kung Fu Tea, Sharetea, Ten Ren's Tea Time, Gong Cha, Tapioca Express, Boba Box Limited, Chatime, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Bubble Tea Market Strategic Shifts
Texture-driven menu experimentation and regulatory-driven supply chain requalification are simultaneously reshaping product development and procurement protocols across the US bubble tea landscape.
Sealed nitrogen-dosed cold brew tea bases are expanding into milk tea formulations as operators seek extended refrigerated shelf life without flavor degradation. Mid-sized chains in Texas and Arizona are adopting these systems to reduce daily prep labor. The technology is expanding into grab-and-go retail formats previously dominated by hot-brewed coffee programs.
FDA's Food Safety Modernization Act foreign supplier verification requirements are forcing direct relationships with Taiwanese starch processors rather than distributor intermediaries. Large operators now conduct on-site audits of pearl manufacturing facilities. California-based chains face the strictest documentation burdens, creating competitive separation from under-resourced independents.
Subscription-based loyalty programs are displacing traditional punch-card frequency rewards as digital-native consumers expect personalized offers tied to purchase history. Mobile-first ordering platforms capture order-ahead volume that compresses in-store dwell time. This behavioral shift concentrates in university-adjacent locations where Gen Z consumers dominate traffic patterns.
US Bubble Tea Market Segmentation
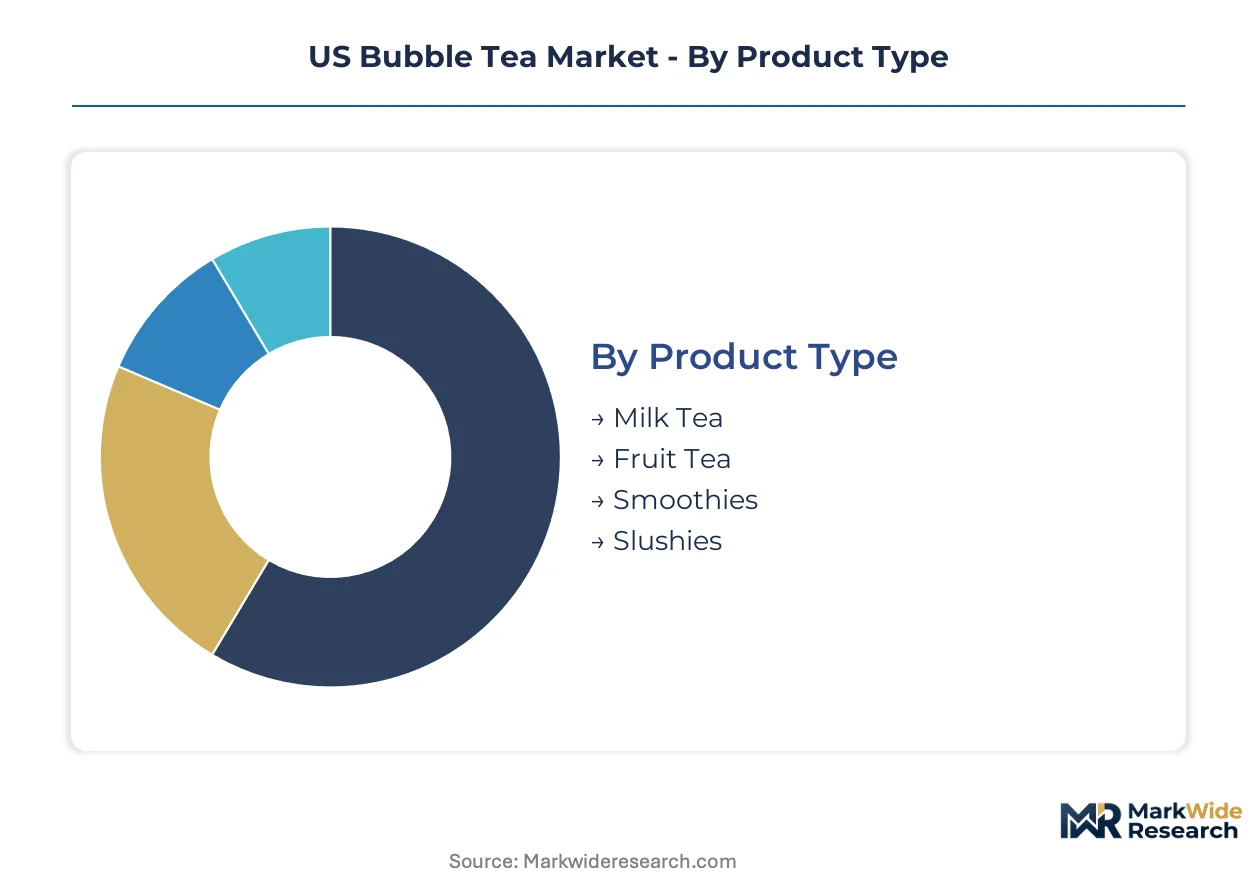
Bubble tea operators engineer menu architecture around texture preference, daypart occasion, and channel economics. Segment boundaries blur as milk tea formats absorb fruit infusions and popping boba migrates across all product types.
Product Type:
Volume concentration favors established formats while premium innovation reshapes the upper tier.
- Milk Tea:Brewed black or green tea combined with dairy or non-dairy milk and sweetener forms the baseline formulation. California and Texas college corridors sustain the highest per-capita consumption rates due to established Asian-American population clusters and repeat visit behavior.
- Fruit Tea:Tea base infused with fresh fruit puree or syrup delivers lighter calorie positioning and visual appeal through layered color gradients. Demand concentrates in urban coastal markets where health-conscious young adults seek alternatives to dairy-heavy options.
- Smoothies:Blended ice-base beverages with fruit or yogurt additions target afternoon snack occasions.
- Slushies:Finely textured frozen formats capture seasonal summer volume in Sun Belt states.
Mature deployment sits with Milk Tea. Newer deployment is concentrated in Fruit Tea.
Ingredient Type:
Texture differentiation now drives ingredient selection more than flavor alone.
- Tapioca Pearls:Traditional 8-10 millimeter starch spheres require precise cooking protocols to achieve optimal chewiness. Supply chain requalification under FDA foreign supplier verification programs has consolidated procurement toward audited Taiwanese processors.
- Popping Boba:Fruit-juice-filled spheres with thin alginate membranes deliver burst texture contrasting with chew-based alternatives. Texas and Florida food truck operators have accelerated adoption among teen demographics seeking novel mouthfeel experiences.
- Jelly:Nata de coco or agar-based cubes add structural variety to beverage builds.
- Grass Jelly:Herbal jelly inclusions target Asian-American consumers with established preference for traditional toppings.
Ingredient sourcing complexity concentrates with Tapioca Pearls. Fastest texture innovation is occurring in Popping Boba.
Consumer Type:
Frequency patterns diverge sharply between habitual daily drinkers and occasional treat purchasers.
- Young Adults:College-enrolled and early-career consumers aged 18-29 drive visit frequency through social occasion clustering and digital-native loyalty program engagement. University-adjacent locations in New York and California report the highest weekly transaction rates.
- Teens:Secondary school students generate trial volume through food truck accessibility and social media-influenced flavor chasing. Limited disposable income compresses per-transaction spend toward value-tier menu items.
- Families:Multi-generational purchasing occasions expand average party size but reduce individual customization complexity.
- Professionals:Office-adjacent locations capture morning and afternoon daypart demand seeking coffee alternatives.
Visit frequency leadership sits with Young Adults. Emerging frequency growth is concentrated in Teens.
Sales Channel:
Channel economics determine format investment and labor deployment strategies.
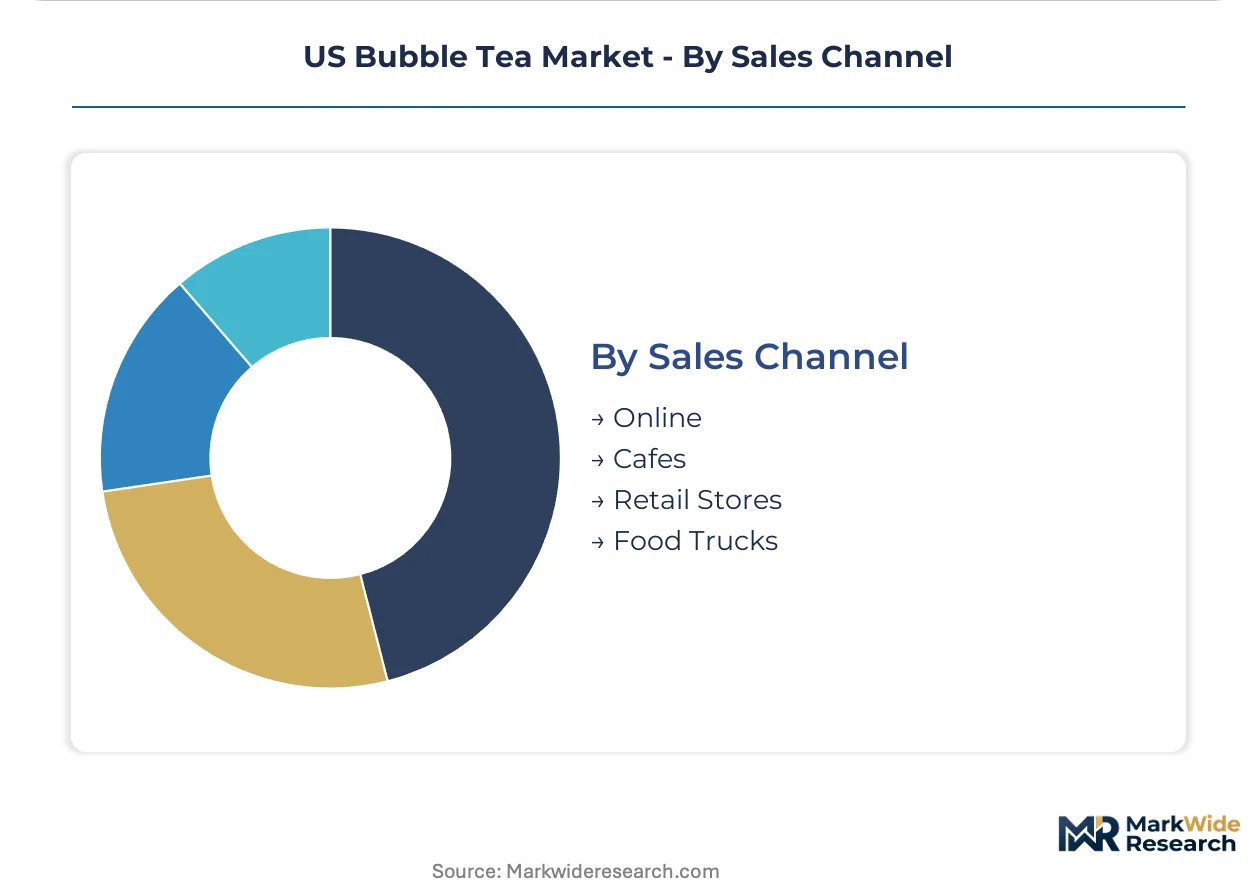
- Cafes:Permanent retail locations with seating and full menu execution command highest per-transaction averages through customization upsells and food pairing. California health department grading systems create location-specific barriers to entry that filter competition.
- Food Trucks:Mobile units with limited equipment footprints capture disproportionate trial volume in Texas and Florida secondary cities where permanent retail rents remain prohibitive. Seasonal and event-based scheduling maximizes asset utilization.
- Online:Third-party delivery platforms and native mobile ordering compress margins through commission structures but expand reach beyond walkable trade areas.
- Retail Stores:Grocery and convenience retail placement of ready-to-drink formats serves at-home consumption occasions.
Margin concentration sits with Cafes. Expansion capital is flowing fastest into Food Trucks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in three coastal states and Texas, where Asian-American population corridors and university ecosystems sustain the highest per-capita consumption rates. California, Texas, and New York together anchor the majority of specialty beverage shop density.
California
Los Angeles and Orange County clusters support the nation's largest concentration of bubble tea storefronts, with San Francisco Bay Area corridors adding premium-tier volume. The California Department of Public Health's restaurant grading system creates location-specific compliance barriers that filter undercapitalized entrants. Los Angeles County alone hosts multiple competing chains within single-mile radii around San Gabriel Valley and Koreatown districts.
Texas
Houston and Dallas-Fort Worth metroplexes drive volume through sprawling suburban development patterns and lower commercial rents that enable rapid unit expansion. The Texas Department of State Health Services maintains inspection protocols that align with FDA Food Safety Modernization Act supplier verification requirements. Austin's university corridor generates disproportionate Gen Z trial frequency through food truck accessibility and social media-driven flavor chasing.
New York
Queens and Manhattan Chinatown districts sustain baseline demand from established Asian-American communities, while Brooklyn and Flushing corridors attract younger demographics seeking novel texture experiences. The New York City Department of Health and Mental Hygiene's letter-grade system directly influences consumer traffic patterns and storefront location viability. Cornell and Columbia university-adjacent locations report the highest weekly transaction rates among East Coast operators.
Florida
Orlando and Tampa secondary cities capture emerging demand through food truck channels where permanent retail rents remain prohibitive for new entrants. The Florida Department of Health's Division of Food Safety enforces import documentation requirements for tapioca starch that mirror federal FSMA protocols. Miami-Dade County's limited bubble tea penetration relative to population density suggests untapped expansion potential for mobile-first operators.
Washington
Seattle's Eastside suburbs and university district sustain moderate volume through tech-worker demographics seeking coffee alternatives. The Washington State Department of Health coordinates with FDA on foreign supplier verification program implementation for imported flavor additives. Bellevue and Redmond corridors host emerging specialty beverage density as Asian-American population shares increase.
US Bubble Tea Market Competitive Environment
Direct sourcing agreements dominate the current landscape as chains reduce distributor intermediaries to secure tapioca pearl quality and margin protection. The vendor base spans captive Taiwanese starch relationships, vertically controlled syrup production, and multi-source procurement strategies. Three archetypes define competitive positioning: heritage chains with direct Asian supplier ties, digitally native upstarts with in-house manufacturing, and franchise-heavy networks scaling through unit economics. Geographic expansion and backward integration into ingredient processing represent the dominant competitive moves.
Among heritage chains with direct Asian supplier relationships, Kung Fu Tea and Gong Cha exemplify the archetype of operators leveraging captive Taiwanese starch processor relationships to secure consistent pearl quality. The Boba Guys occupies a distinct position within the vertically controlled production tier through its California commissary-based syrup manufacturing. These three operators collectively represent the strategic spectrum from upstream supply control to rapid LTO rotation capability.
| Leading Market Players |
|---|
| Lollicup USA Inc. |
| The Boba Guys |
| Kung Fu Tea |
| Sharetea |
| Ten Ren's Tea Time |
| Gong Cha |
| Tapioca Express |
| Boba Box Limited |
| Chatime |
| Others |
Value Chain & Pricing Dynamics
Gen Z insistence on novel texture experiences and FDA-mandated supplier requalification are forcing chains to absorb premium pearl costs or surrender margin, compressing the pricing window between value-tier independents and heritage operators with captive Taiwanese relationships.
Pricing Analysis
Volume concentration in milk tea formats sits against margin protection in popping boba and premium builds. Three-tier pricing structure across premium, standard, and economy levels separates Gong Cha and Kung Fu Tea heritage positioning from food truck value tiers. Cost compression in standard-tier milk tea is intensifying because tapioca pearl import documentation burdens fall heaviest on undercapitalized independents. Teens show highest price sensitivity, while young adults in university corridors accept premium pricing for customization complexity.
Supply Chain Analysis
Ocean freight volatility on Taiwan and Thailand routes elevates landed pearl costs unpredictably, forcing operators to build buffer inventory or absorb margin swings. The supply chain draws from Taiwanese starch processors for tapioca pearls, Thai flavor houses for syrups, and domestic California commissaries for vertically controlled production. Single-source vulnerability concentrates in Taiwanese pearl supply where FDA foreign supplier verification programs have disqualified distributor intermediaries. Distribution runs through direct sourcing agreements at large chains and foodservice distributors at independents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where FDA Food Safety Modernization Act compliance costs filter undercapitalized independents, creating acquisition opportunities for well-resourced chains with audited supplier relationships.
For Market Incumbents: Anticipate margin pressure from popping boba substitution trends by locking multi-year direct sourcing agreements with Taiwanese starch processors before competitor capacity absorbs premium supply. Defend position through backward integration into regional commissary production, mirroring The Boba Guys' California syrup manufacturing model. Channel control in university-adjacent real estate represents the priority defensive lever against mobile food truck trial capture. For New Entrants and Emerging Players: FDA Foreign Supplier Verification Programs in the US open a window for mobile-first operators in Texas and Florida secondary cities where permanent retail rents remain prohibitive and inspection protocols align with federal requirements. White-space targets concentrate in Orlando and Tampa food truck corridors and Miami-Dade County's underpenetrated density. Go-to-market through social media-influenced flavor chasing among teen demographics bypasses heritage brand loyalty. For Investors and Strategic Acquirers: The window for entry favors vertically integrated mid-cap specialists with captive Taiwanese supplier relationships and in-house commissary production. Long-term viability hinges on backward integration depth that insulates against ocean freight volatility and currency fluctuation risk. The signal to watch is FDA novel food ingredient pathway approvals for next-generation base formulations that could displace traditional milk tea formats.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Sourcing Agreement | Captive relationships with Taiwanese starch processors secure consistent pearl quality under FDA verification protocols. |
| Commissary Production | In-house syrup manufacturing at regional facilities enables rapid LTO rotation and margin protection against commodity swings. |
| Mobile Channel Expansion | Food truck deployment in Texas and Florida secondary cities captures teen trial volume where permanent retail rents remain prohibitive. |
| Digital Loyalty Platform | Subscription-based programs displace punch-card rewards as Gen Z consumers expect personalized offers tied to purchase history. |
| Novel Ingredient Engagement | Early FDA pathway participation positions operators to commercialize next-generation base formulations ahead of competitors. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with bubble tea chain procurement directors, commissary operations managers, food truck operators, and FDA compliance specialists. Triangulation combined bottom-up unit economics modeling with top-down market sizing validated against National Restaurant Association reports, FDA import alert databases, and state health department inspection records.
Segmentation granularity modeled product type at the format level, ingredient type at the texture-inclusion level, consumer type at the demographic-behavioral cluster level, and channel type at the format-economics level across the analysis window. CAGRs derived from trend extrapolation of visit frequency data, unit expansion pipelines, and per-transaction average movements. Forecast inputs incorporated Gen Z consumption pattern shifts, popping boba adoption curves, and mobile channel penetration rates.
The model assumes a particular technology adoption path; alternative pathways for sealed nitrogen-dosed cold brew tea base systems would alter the outlook if grab-and-go retail formats accelerate faster than cafe channel retention. Forecasts reflect documented assumptions about regulatory timeline compression and supplier consolidation trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Italy Bottled Water Market
Beverages
Asia-Pacific Energy Bar Market
Beverages
Japan Kombucha Market
Beverages
Blenders Market
Beverages
North America Energy Drink Market
Beverages
Saudi Arabia Bottled Water Market
Beverages
Europe Probiotic Drinks Market
Beverages
CBD-Infused Beverages Market
Beverages
Sparkling Water Market
Beverages
Hydrogen Water Dispenser Market
Beverages
Italy Probiotic Drinks Market
Beverages
Fruit and Vegetable Juice Market
Beverages
Ginger Beer Market
Beverages
Caffeinated Beverage Market
Beverages
Recovery Drinks Market
Beverages
Europe Bottled Water Processing Market