
 Gin and Tonic Tea Market | 2026-2036
Gin and Tonic Tea Market Size, Share, and Industry Trends Forecast 2026-2036
Gin and Tonic Tea Market Analytics
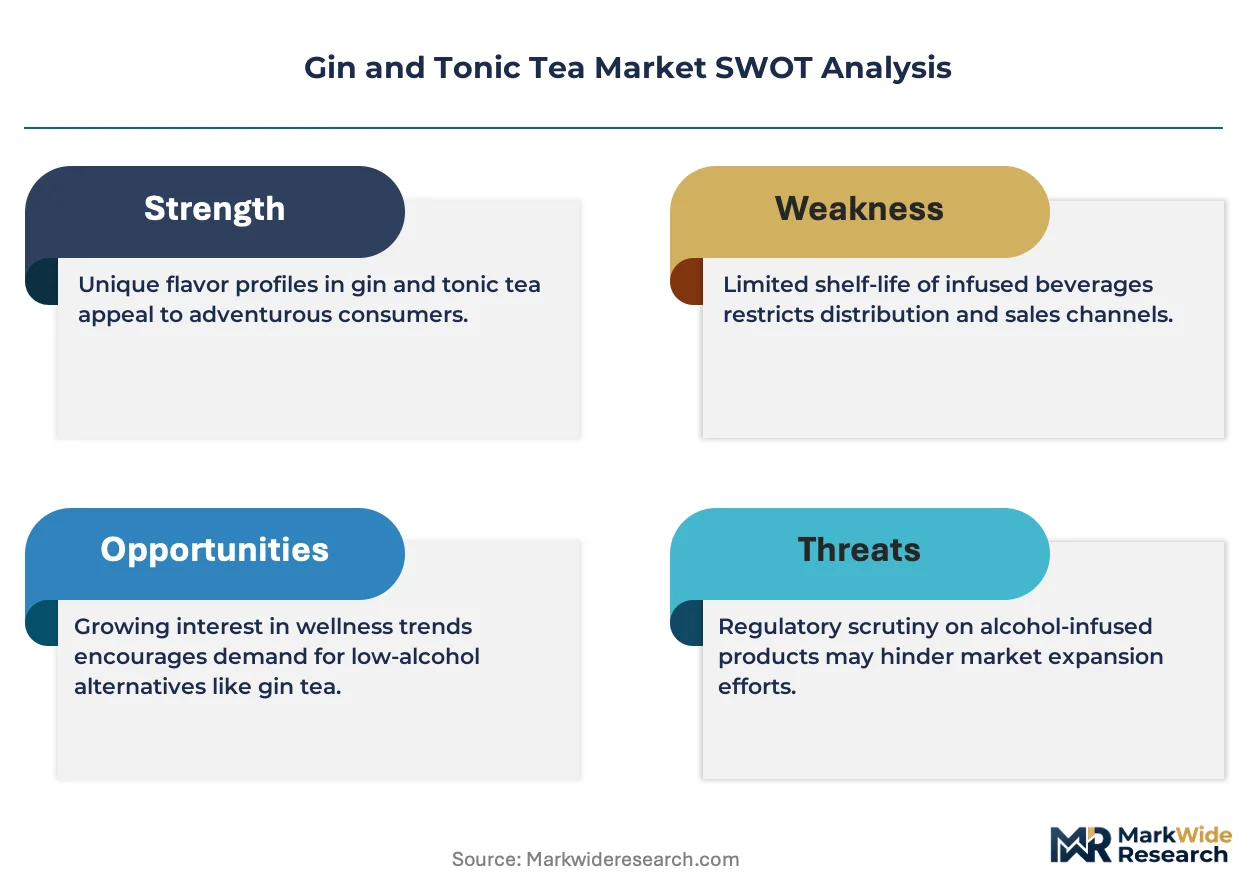
The EU Green Deal is hardening sustainability requirements for beverage packaging across European supply chains. Fortnum & Mason leverages its heritage retail network to sustain premium positioning in botanical-infused tea formats. Rosie Lea Tea anchors its competitive stance through specialized loose-leaf production. Royal Botanical Garden Kew differentiates via institutional credibility in plant-based ingredient sourcing.
Gin and tonic tea denotes a non-alcoholic infusion blending juniper berry extract, tonic water elements, and complementary botanicals into consumable tea formats, typically brewed at 90–95°C to preserve volatile aromatic compounds. The primary commercial purpose centers on delivering sophisticated flavor profiles to consumers reducing alcohol intake without sacrificing ritual or complexity. Loose leaf occupies the highest margin tier among product types due to perceived craftsmanship and lower processing overhead. Tea bags compete on convenience penetration in retail channels. Bottled formats lead volume growth through grab-and-go consumption in urban cafés and transit hubs.
The UK's Food Standards Agency governs novel food ingredient approvals, while the EU's REACH framework regulates botanical extract safety thresholds for consumer products. Germany's BfR provides additional guidance on juniper-derived compound limits that suppliers must navigate for continental market access. Stakeholders should monitor evolving caffeine-content labeling requirements and botanical health claim restrictions that will determine formulation flexibility and cross-border positioning.
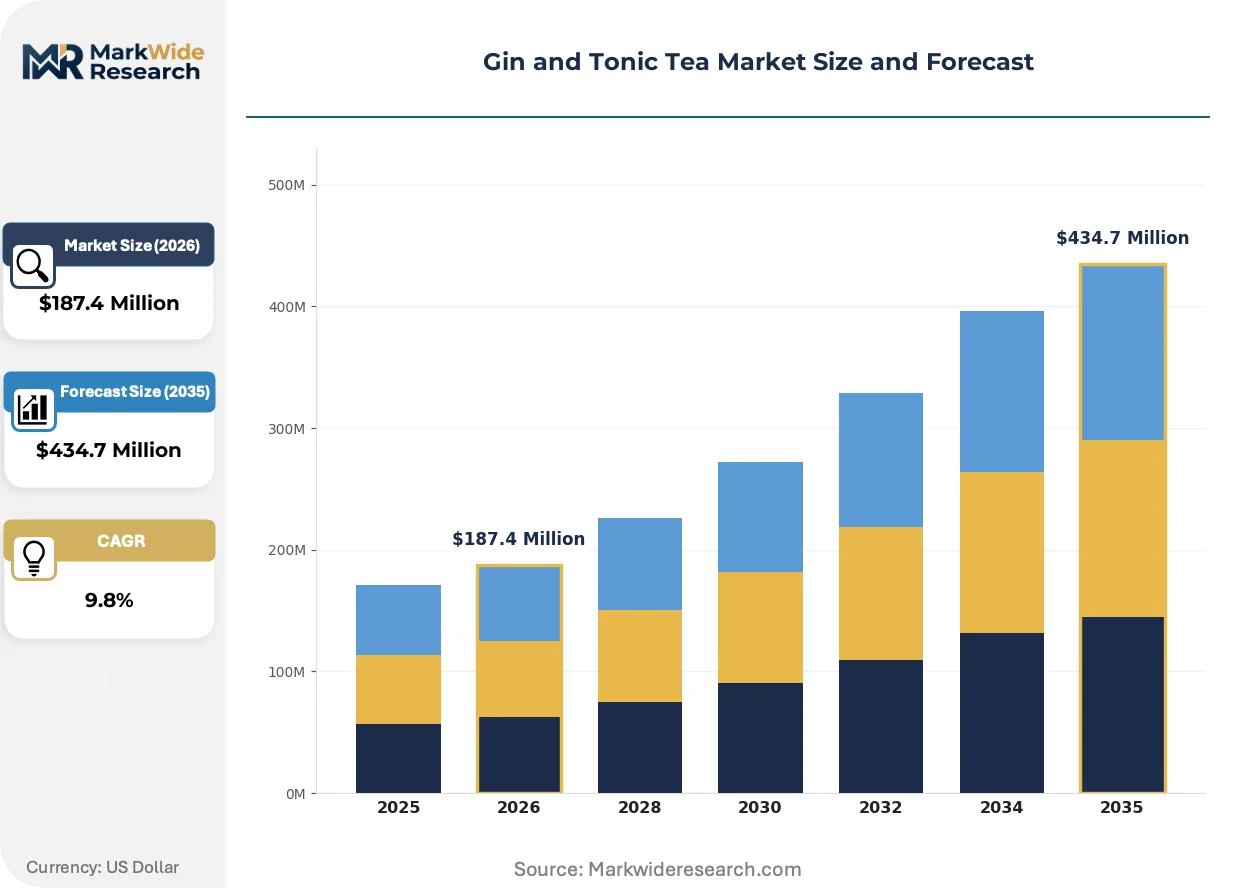
Market Dynamics
The EU Green Deal's sustainable packaging mandates are forcing reformulation of supply chains across botanical beverage categories, with juniper extract suppliers now certifying carbon footprints to retain shelf access in member states.
Growth Catalysts
- REACH framework compliance:ECHA's streamlined botanical extract safety assessments are reducing novel ingredient approval timelines for juniper-derived compounds entering EU markets.
- Specialty café channel expansion:Mixology bars in London, Berlin, and Amsterdam are building non-alcoholic menus around craft tea rituals that replicate gin service aesthetics.
- Botanical sourcing technology:Cryogenic preservation methods are extending volatile aromatic compound stability, enabling wider distribution of premium loose-leaf formats.
Market Restraints
- Juniper berry supply concentration:Wild harvest dependence in Mediterranean zones creates harvest volatility that compresses margin predictability for extract processors.
- Quinine regulatory thresholds:Germany's BfR maintains strict cinchona alkaloid limits that constrain tonic water element concentrations in finished products.
- Heritage tea substitution:Established Earl Grey and jasmine formats capture shelf space in retail channels, limiting facings for emerging botanical blends.
Strategic Opportunities
- Nordic market underpenetration:Sweden and Denmark exhibit low current adoption but strong wellness-oriented consumption patterns that align with alcohol-reduction positioning.
- EU Green Deal packaging mandates:Compostable sachet requirements create first-mover advantage for suppliers with certified biodegradable material pipelines.
- Direct-to-subscription channels:Curated monthly botanical boxes bypass retail slotting fees while building repeat purchase data for flavor preference refinement.
Industry Challenges
- Flavor chemist talent scarcity:Formulation expertise bridging traditional tea processing and modern botanical extraction remains concentrated among a limited specialist pool.
- Novel food dossier preparation:UK's Food Standards Agency approval pathways require 18-24 month investment cycles before commercial launch authorization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gin and Tonic Tea Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $434.7 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Loose Leaf, Tea Bags, Bottled, Concentrate Ingredient: Juniper Berries, Herbal Blend, Citrus Zest, Botanicals Packaging Type: Glass Bottle, Tetra Pack, Pouch, Tin Distribution Channel: Retail Stores, Online Stores, Specialty Shops, Cafés |
| Companies Covered | Fortnum & Mason, Rosie Lea Tea, Royal Botanical Garden Kew, Cornelia Bean, Keva Flavours, Charbay, Boston Beer Company, MKE Brewing Company, Eteaket, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gin and Tonic Tea Market Evolving Landscape
Automation and sustainability certification are converging to reshape how botanical teas move from raw ingredient to finished product, with quality control and traceability emerging as the primary battlegrounds for competitive differentiation.
Near-infrared spectroscopy is automating real-time analysis of juniper berry essential oil content during harvest intake. Processing facilities in Kent and Provence are deploying these systems to replace batch-based laboratory testing. This compression of quality assurance timelines is enabling just-in-time sourcing decisions that reduce working capital requirements.
REACH framework amendments are tightening documentation requirements for botanical extract impurities entering cosmetic and food-grade supply chains. ECHA's expanded substance database now flags previously exempt juniper-derived compounds for additional toxicological review. Small-batch distillers transitioning into tea manufacturing face compliance costs that favor mid-scale producers with dedicated regulatory affairs capacity.
Specialist retailers are consolidating purchasing authority through centralized procurement platforms that bypass traditional distributor networks. Fortnum & Mason and Harvey Nichols now specify carbon-labeled packaging and botanical provenance documentation as mandatory bid criteria. This concentration of buyer power is most visible in London's Mayfair and Knightsbridge districts, where heritage retail footprints command exclusive formulation partnerships.
Gin and Tonic Tea Market Segmentation
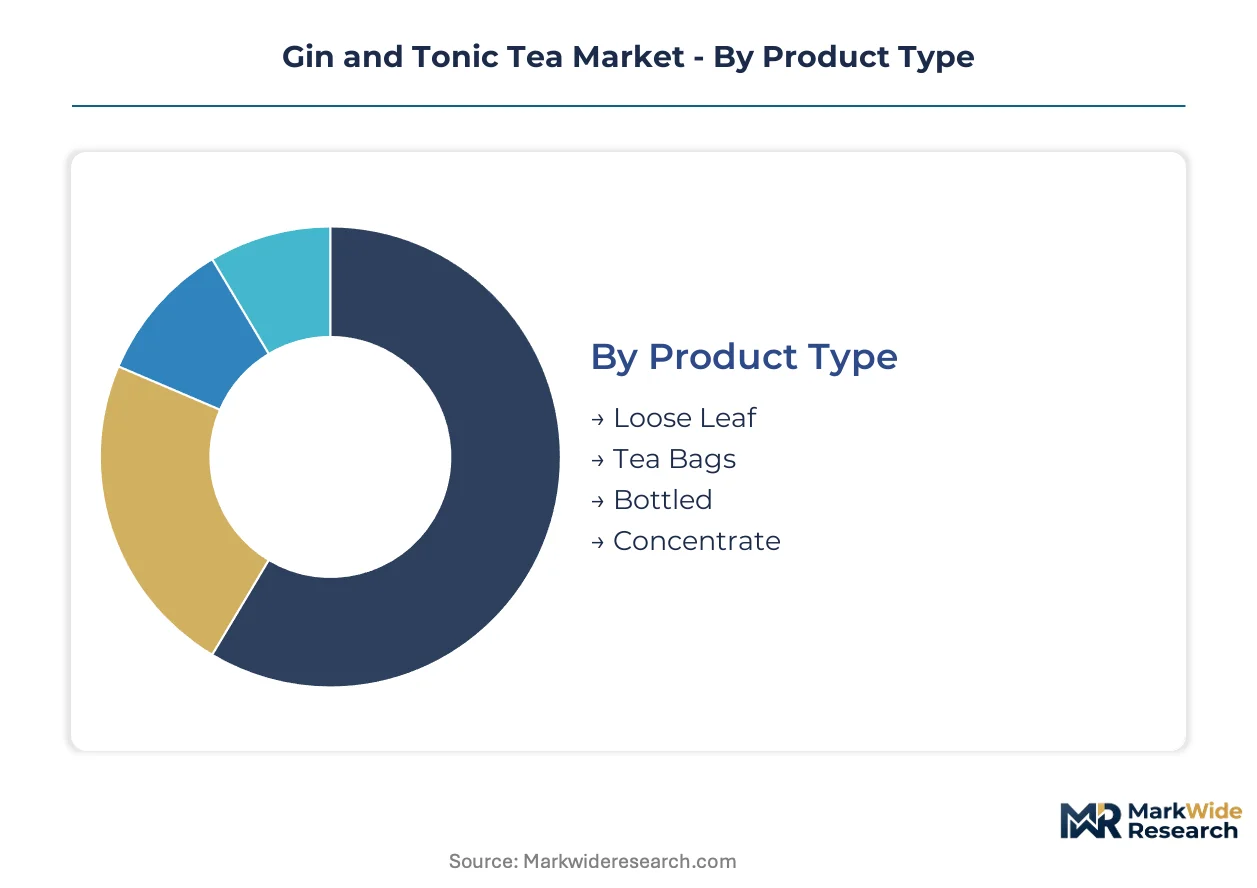
Segmentation in gin and tonic tea reveals how formulation choices, packaging formats, and channel access determine margin capture. Technical specifications around volatile compound preservation and brewing temperature requirements create natural tier boundaries that suppliers exploit for positioning.
Product Type:
Processing intensity and shelf stability requirements divide commercial formats along the value chain.
- Loose Leaf:Whole botanical pieces require 90–95°C brewing to release juniper essential oils. Specialty cafés in London and Berlin build ritual experiences around measured steeping protocols that justify premium pricing.
- Tea Bags:Filter paper enclosures standardize extraction rates for retail consumers. Convenience penetration in UK supermarkets constrains unit economics due to packaging material cost inflation under EU Green Deal mandates.
- Bottled:Ready-to-drink formats dominate grab-and-go consumption at transit hubs and urban cafés. Cold-fill aseptic lines preserve quinine bitterness profiles without thermal degradation.
- Concentrate:Liquid or powdered bases enable foodservice batch preparation. Mixology bars in Amsterdam dilute to specification for non-alcoholic cocktail menus.
Loose leaf leads on scale; bottled formats lead on momentum.
Ingredient:
Botanical sourcing geography and extraction methodology define competitive differentiation.
- Juniper Berries:Wild Mediterranean harvest supplies the signature pine-resin backbone. REACH compliance documentation for juniper-derived compounds adds 12–18 months to supplier qualification cycles.
- Herbal Blend:Chamomile, lavender, and rooibos extend flavor complexity without caffeine. German BfR guidance on novel herb combinations limits formulation flexibility for continental launch.
- Citrus Zest:Bergamot and grapefruit oils brighten the palate and mask quinine astringency. Italian Calabrian bergamot orchards supply concentrate processors in Provence.
- Botanicals:Coriander seed, angelica root, and orris powder replicate gin botanical architecture. Royal Botanical Garden Kew credentialing validates sustainable wild-harvest claims for UK retail.
Juniper berries anchor volume; botanical blends expand fastest.
Packaging Type:
Material specifications interact with EU Green Deal compostability mandates and shelf-life requirements.
- Glass Bottle:Inert barrier properties preserve volatile aromatic integrity for 18–24 months. Premium positioning in Harvey Nichols and Fortnum & Mason depends on embossed heritage branding.
- Tetra Pack:Aseptic carton formats reduce logistics weight for concentrate distribution. Swedish retail chains specify Forest Stewardship Council certification as mandatory bid criteria.
- Pouch:Flexible film reduces material mass for loose-leaf retail formats. Compostable sachet development in Kent processing facilities targets 2025 EU mandate deadlines.
- Tin:Heritage metal caddies signal gift-market positioning and enable nitrogen flushing for oxidation-sensitive whole leaves. Danish design-led retailers favor matte-finish Scandinavian aesthetics.
Glass dominates premium positioning; pouches climb fastest on sustainability compliance.
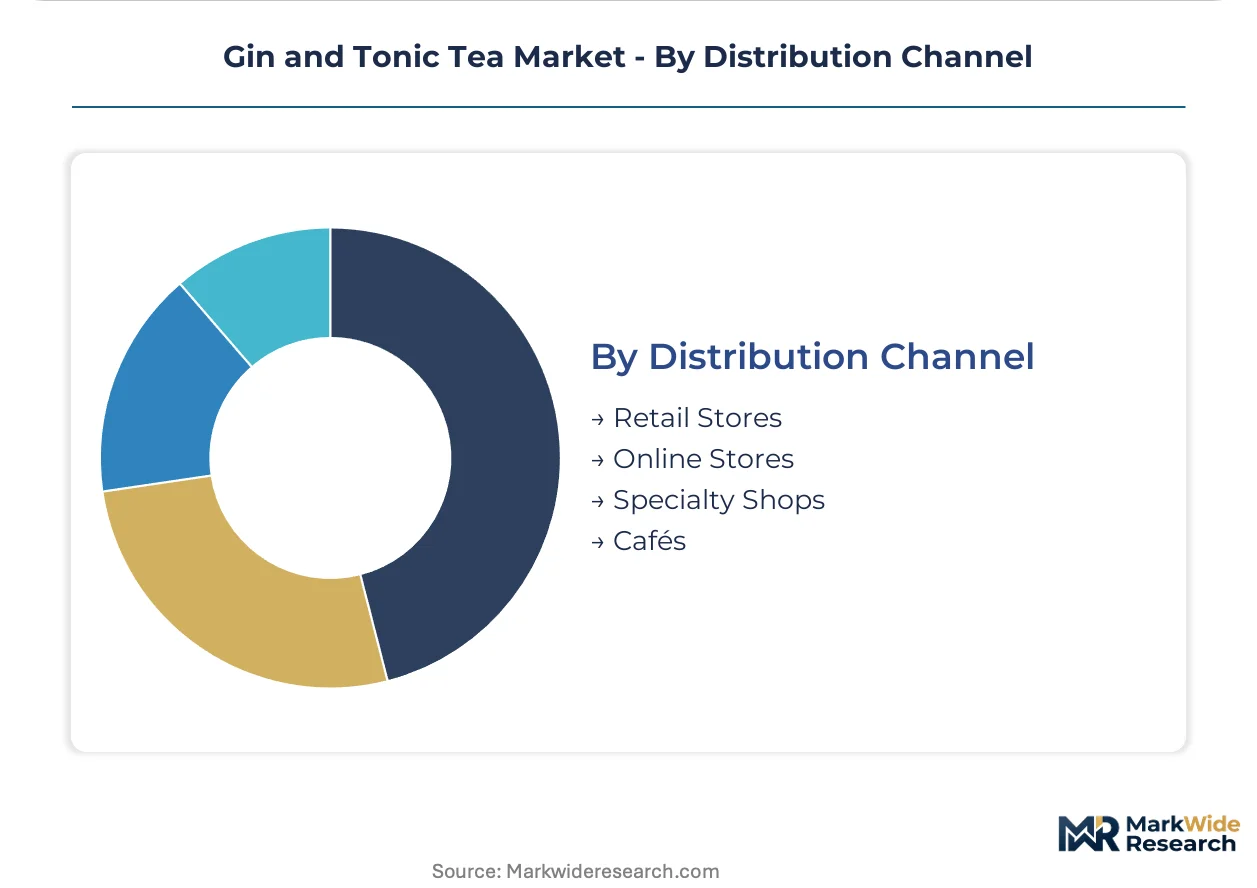
Distribution Channel:
Channel selection determines margin structure and consumer education investment requirements.
- Retail Stores:UK supermarkets allocate shelf space based on velocity thresholds that favor established Earl Grey adjacent placement. Slotting fees compress margins for emerging botanical entrants.
- Online Stores:Direct-to-subscription models bypass retail concentration and build repeat purchase data. Curated monthly boxes from Rosie Lea Tea enable flavor preference refinement without intermediary markup.
- Specialty Shops:Staff-assisted sampling justifies premium pricing through botanical provenance storytelling. Mayfair and Knightsbridge heritage retail footprints command exclusive formulation partnerships.
- Cafés:Mixology bars in London, Berlin, and Amsterdam build non-alcoholic menus around craft tea rituals. On-premise brewing equipment investments lock in supplier relationships through technical training dependencies.
Retail stores lead on volume reach; cafés expand most quickly on experience premiumization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United Kingdom pioneered gin and tonic tea as a commercial category, merging centuries of tea ceremony tradition with London's craft distilling heritage. This historical foundation established the product format and botanical sourcing standards now diffusing across European markets.
United Kingdom
Heritage retail networks and mixology bar culture sustain premium demand in London's Mayfair and Knightsbridge districts. The UK's Food Standards Agency governs novel food ingredient approvals for juniper-derived compounds entering domestic supply chains. Kent processing facilities deploy cryogenic preservation systems to extend volatile aromatic compound stability for export markets.
Germany
Berlin's specialty café sector builds non-alcoholic menus around craft tea rituals replicating gin service aesthetics. The Federal Institute for Risk Assessment maintains strict cinchona alkaloid limits that constrain tonic water element concentrations in finished products. Bavarian distributors consolidate procurement authority through centralized platforms specifying carbon-labeled packaging as mandatory bid criteria.
Netherlands
Amsterdam mixology bars anchor regional demand for concentrate formats enabling batch preparation of non-alcoholic cocktails. REACH framework compliance documentation adds 12–18 months to supplier qualification cycles for juniper extract processors. Rotterdam logistics hubs handle aseptic carton distribution for Swedish retail chains requiring Forest Stewardship Council certification.
Sweden
Wellness-oriented consumption patterns in Stockholm align with alcohol-reduction positioning for botanical infusions. EU Green Deal compostable sachet mandates create first-mover advantage for suppliers with certified biodegradable material pipelines. Danish design-led retailers favor matte-finish Scandinavian aesthetics in heritage metal caddies for gift-market positioning.
France
Provence processing facilities source Italian Calabrian bergamot oils for citrus zest formulations masking quinine astringency. ECHA's expanded substance database flags previously exempt juniper-derived compounds for additional toxicological review. Parisian specialty shops command exclusive formulation partnerships through staff-assisted sampling justifying premium pricing.
Gin and Tonic Tea Market Competitive Landscape
Capital-heavy producers with captive botanical extraction capabilities compete with asset-light designers outsourcing juniper sourcing and blending operations. The vendor base clusters around three tiers: heritage retailers leveraging institutional credibility, specialized loose-leaf processors emphasizing craftsmanship, and beverage conglomerates extending alcohol portfolios into non-alcoholic adjacencies. Dominant competitive moves include exclusive formulation partnerships with Mayfair retail footprints and backward integration into Mediterranean juniper harvest networks.
Among UK-based heritage retailers, Fortnum & Mason occupies a position exemplifying premium-channel anchoring through embossed branding and provenance documentation. Rosie Lea Tea represents the specialized loose-leaf archetype, with subscription models bypassing retail slotting fees. Royal Botanical Garden Kew anchors institutional credibility in sustainable wild-harvest validation for plant-based ingredient sourcing claims.
| Leading Market Players |
|---|
| Fortnum & Mason |
| Rosie Lea Tea |
| Royal Botanical Garden Kew |
| Cornelia Bean |
| Keva Flavours |
| Charbay |
| Boston Beer Company |
| MKE Brewing Company |
| Eteaket |
| Others |
Value Network & Pricing Analysis
Juniper berry spot prices in Mediterranean harvest zones cascade through three distinct pricing tiers, with wild-harvest volatility compressing margin predictability for extract processors while EU Green Deal packaging mandates add cost layers at each downstream conversion stage.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments buyers by ritual investment versus convenience priority. Price differentiation stems from botanical provenance documentation and compostable packaging certification under EU Green Deal mandates. Cost compression in economy tea bag tiers is intensifying because filter paper material inflation outpaces retail price elasticity. Specialty cafés in London and Berlin show least price sensitivity; UK supermarket shoppers exhibit highest.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Kent operate hub-and-spoke patterns for aseptic carton and loose-leaf formats. Mediterranean wild harvest supplies juniper berries; Italian Calabrian orchards furnish citrus zest; Provence processing facilities anchor extraction capacity. Single-source vulnerability concentrates in Mediterranean juniper zones where climate volatility disrupts harvest timing. Distribution runs through heritage retail networks in Mayfair and Knightsbridge for premium positioning, with direct-to-subscription channels bypassing intermediary markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story where consumer willingness-to-pay for alcohol-reduction ritual justifies premium positioning over commodity tea alternatives.
For Market Incumbents: Anchor defensive positioning through exclusive formulation partnerships with Mayfair heritage retail footprints and backward integration into Mediterranean juniper harvest networks. Cryogenic preservation capacity in Kent facilities locks in volatile compound stability advantages that emerging entrants cannot replicate without 18-24 month capital deployment. Monitor REACH framework amendments for juniper-derived compound reclassification risks.
For New Entrants and Emerging Players: Capture white-space in Nordic markets where Sweden and Denmark exhibit wellness-oriented consumption patterns with low current gin and tonic tea penetration. Direct-to-subscription models bypass retail slotting fees that compress margins for supermarket-facing competitors. Staff-assisted sampling in Amsterdam specialty shops enables botanical provenance storytelling without heritage brand overhead.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale processors possessing dedicated regulatory affairs capacity for novel food dossier preparation. Long-term viability hinges on EU Green Deal packaging compliance infrastructure and captive botanical extraction capabilities. Watch ECHA substance database expansion for juniper-derived compound reclassification signals as inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Juniper Harvest Networks | Mediterranean wild-harvest control secures supply stability for premium loose-leaf formats. |
| Compostable Sachet Certification Program | Kent processing facilities target EU Green Deal 2025 mandate deadlines for first-mover shelf access. |
| Direct-to-Subscription Channel Launch | Rosie Lea Tea's curated monthly boxes build repeat purchase data without retail intermediary markup. |
| Cryogenic Preservation Capacity Expansion | Volatile aromatic compound stability enables wider distribution of premium formats across export markets. |
| Exclusive Formulation Partnership | Heritage retail footprints in Mayfair command proprietary botanical blends unavailable through competing channels. |
Research Methodology
Multiple input streams — primary interviews with botanical extract processors, specialty café procurement managers, and heritage retail category buyers; secondary validation through ECHA substance databases, EU customs trade records, and FSA novel food registers; plus Nielsen retail audit data — were reconciled through bottom-up volume triangulation against top-down value estimates.
Historical volume trajectories were cross-referenced against expert panel inputs across product type, ingredient sourcing geography, packaging material tier, and distribution channel dimensions. CAGRs were derived from segment-level growth rate reconciliation with macroeconomic consumption indicators. Industry-specific forecast inputs incorporated EU Green Deal implementation timelines and REACH framework amendment schedules.
Regulatory delay in novel food approvals, juniper harvest climate volatility, and compostable packaging cost inflation are the dominant revision risks to projection assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Japan Tequila Market
Alcoholic Beverages
Bottled Craft Beer Market
Alcoholic Beverages
Cognac Market
Alcoholic Beverages
Brandy Flavor Market
Alcoholic Beverages
Canada Alcohol E-Commerce Market
Alcoholic Beverages
Uganda Spirits Market
Alcoholic Beverages
Sake and Plum Wine Market
Alcoholic Beverages
Beer Stabilizers Market
Alcoholic Beverages
Europe Kegs Market
Alcoholic Beverages
Asia-Pacific Wine Market
Alcoholic Beverages
Beer Cans Market
Alcoholic Beverages
UK Tequila Market
Alcoholic Beverages
Global Shortenings Market
Alcoholic Beverages
Premium Spirit Market
Alcoholic Beverages
Spain Alcohol E-Commerce Market
Alcoholic Beverages
Home Beer Brewing Machine Market