
 Low Alcohol Beverages Market | 2026-2036
Low Alcohol Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Low Alcohol Beverages Market Analysis
European craft brewing capacity is consolidating around sub-3% ABV lager and ale production. Heineken N.V. leverages its zero-alcohol platform and licensed brewing network to dominate continental shelf space. The Boston Beer Co. Inc. anchors the North American no-alcohol craft segment through dedicated fermentation protocols. Carlsberg Group differentiates via its Copenhagen-based R&D hub focused on enzymatic alcohol reduction.
Low alcohol beverages contain no more than 1.2% ABV in most regulatory jurisdictions, achieved through arrested fermentation, vacuum distillation, or reverse osmosis membrane separation that preserves volatile aromatic compounds. Their primary commercial purpose is to replicate the sensory and social experience of traditional alcoholic drinks without intoxicating effect. Beer commands the largest volume share among product types due to established brewing infrastructure and consumer familiarity, while spirits represent the fastest-expanding category as vacuum distillation costs decline. Online retail channels capture disproportionate margin pools through direct-to-consumer subscription models, though supermarkets still process the highest absolute transaction volumes.
FDA labeling requirements and TTB alcohol taxation thresholds in the United States create distinct formulation targets at 0.5% ABV, while EU Regulation 1169/2011 mandates nutritional declaration for beverages above that threshold. EFSA health claims scrutiny and WHO alcohol reduction frameworks are tightening permissible marketing language across member states. Stakeholders must monitor pending classification changes for dealcoholized wines in key Asian import markets.
Market Dynamics
EU Regulation 1169/2011 nutritional declaration mandates are forcing reformulation transparency across the low alcohol beverages sector, compressing time-to-market for new product launches while elevating enzymatic alcohol reduction R&D budgets.
Growth Catalysts
- EFSA Health Claims Scrutiny:Tightening permissible marketing language under WHO alcohol reduction frameworks is accelerating clean-label innovation in Germany and the United Kingdom.
- Session-Strength Pub Culture:British on-trade venues are expanding draft lineups for sub-3% ABV alternatives, normalizing reduced-intoxication social drinking occasions.
- Vacuum Distillation Cost Curves:Declining membrane separation equipment prices are enabling craft-scale dealcoholization for spirits producers previously locked out of the category.
Market Restraints
- Input Cost Volatility:Specialized enzymatic catalysts for arrested fermentation face supply concentration among Danish and Dutch specialty chemical suppliers.
- Regulatory Friction:Pending classification changes for dealcoholized wines in key Asian import markets create inventory stranding risk for exporters.
- Technical Limitation:Reverse osmosis membrane fouling during volatile aromatic compound recovery limits batch yields for premium wine alternatives.
Strategic Opportunities
- Direct-to-Consumer Subscription Models:Online retail channels capture disproportionate margin pools through curated low-alcohol discovery boxes targeting British millennials.
- TTB Threshold Arbitrage:FDA labeling requirements at 0.5% ABV create distinct formulation targets enabling premium positioning in United States retail.
- Hybrid Fermentation Protocols:Convergence of arrested fermentation and vacuum distillation is opening white space in 0.5-1.2% ABV wine alternatives.
Industry Challenges
- Flavor Chemist Talent Gap:Shortage of specialists capable of reconstructing mouthfeel and aromatic complexity in sub-0.5% ABV spirits formulations.
- Legacy System Integration:Retrofitting conventional brewing infrastructure for arrested fermentation requires capex-intensive temperature control and monitoring upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Alcohol Beverages Market |
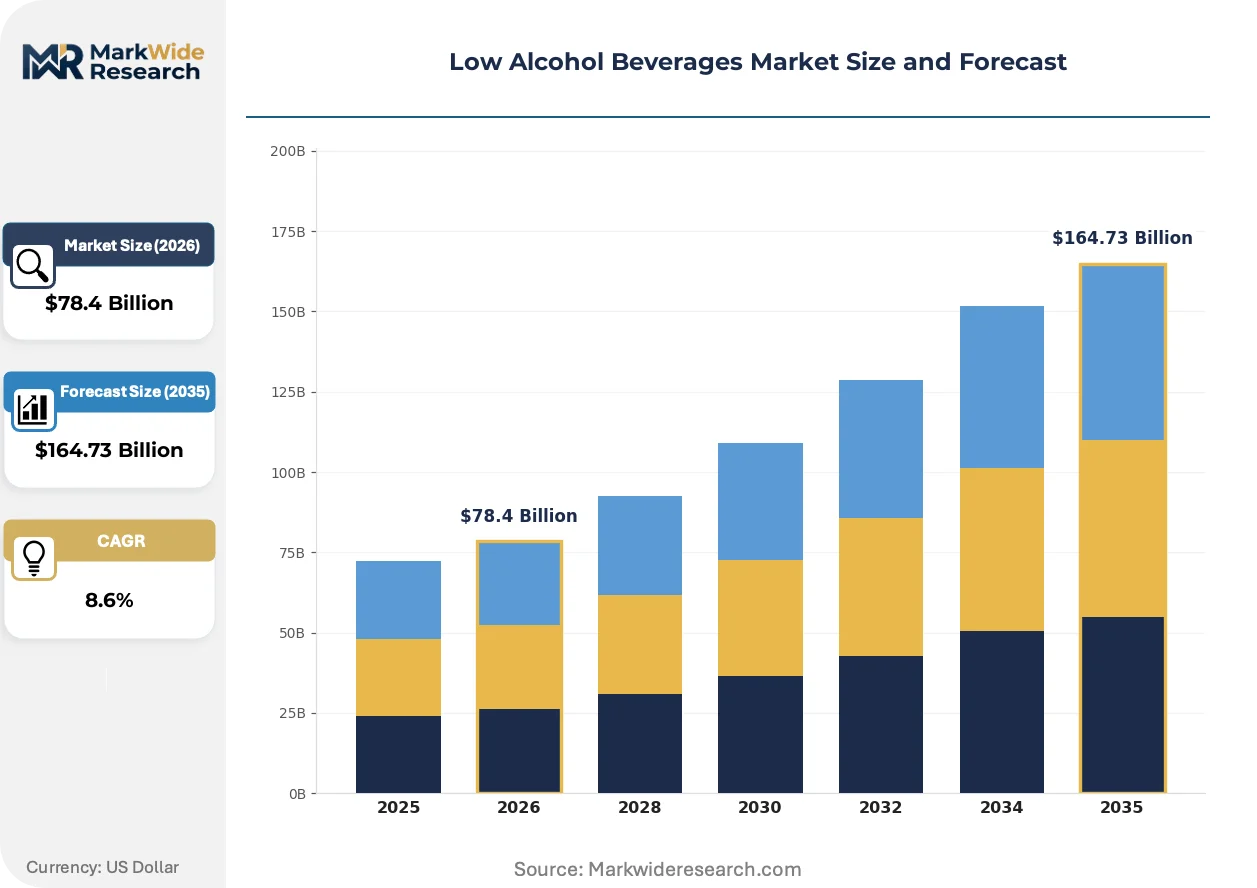
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $164.73 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beer, Wine, Spirits, Cocktails Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Bars Consumer Type: Health-Conscious Individuals, Occasional Drinkers, Social Drinkers, Young Adults Flavor Profile: Fruity, Herbal, Spicy, Sour |
| Companies Covered | Anheuser-Busch InBev, Heineken N.V., Constellation Brands Inc., Molson Coors Beverage Company, Diageo plc, Carlsberg Group, Asahi Group Holdings Ltd., The Boston Beer Co. Inc., Sapporo Breweries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Alcohol Beverages Market Emerging Trajectories
Formulation science is pivoting from alcohol removal toward sensory reconstruction, with enzymatic and membrane technologies converging to preserve volatile compounds previously lost in dealcoholization.
Membrane separation technology is absorbing capital from traditional distillation equipment as craft producers seek scalable dealcoholization. German and British brewing cooperatives are piloting reverse osmosis units at sub-1,000 hectoliter annual capacity. This technology is absorbing market share from vacuum distillation in the sub-3% ABV beer segment by preserving hop aromatics.
EU Green Deal sustainability reporting requirements under CSRD are mandating carbon footprint disclosure for beverage production. Industrial consequence includes pressure to reduce thermal energy intensity in dealcoholization processes. Spirits producers in Denmark and the Netherlands are responding with heat-recovery vacuum distillation retrofits.
Subscription-driven discovery purchasing is displacing supermarket trial purchases among health-conscious British millennials. Direct-to-consumer platforms are capturing share from traditional off-trade by offering curated low-alcohol mixed cases with detailed nutritional transparency. This shift is most visible in London and Manchester metropolitan clusters where digital-native brands have established fulfillment infrastructure.
Low Alcohol Beverages Market Segmentation
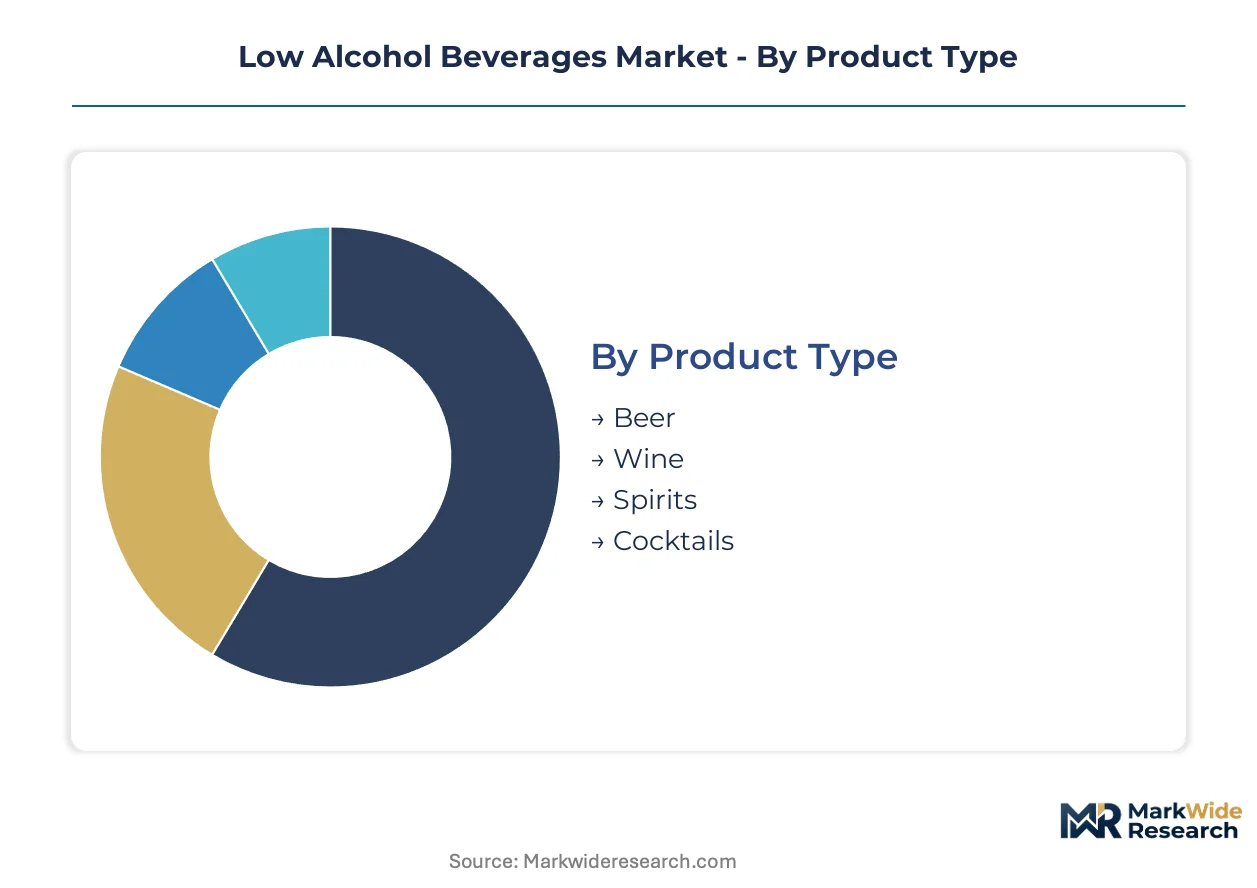
Low alcohol beverage segmentation reflects divergent technical pathways and regulatory thresholds across product categories. Each segment carries distinct formulation costs, certification burdens, and channel access requirements that determine competitive viability.
Product Type:
Beer and wine face EFSA nutritional declaration mandates above 0.5% ABV under EU Regulation 1169/2011, while spirits below that threshold trigger simplified FDA labeling in the United States. Dealcoholized wines encounter pending reclassification risks in Asian import markets.
- Beer:Arrested fermentation and vacuum distillation preserve hop aromatics in sub-3% ABV lagers and ales. Demand concentrates in British pub venues expanding draft lineups for session-strength alternatives, driven by social drinking normalization without intoxication.
- Spirits:Vacuum distillation and reverse osmosis membrane separation extract ethanol while reconstructing mouthfeel through flavor chemistry. The category expands most quickly as declining equipment costs enable craft-scale production previously locked out by capital intensity.
- Wine:Reverse osmosis membrane fouling during volatile compound recovery limits batch yields for premium alternatives. Regulatory friction in Asian import markets creates inventory stranding risk for exporters.
- Cocktails:Pre-mixed formulations leverage arrested fermentation protocols with simplified TTB threshold compliance at 0.5% ABV.
Leading the category by volume: Beer. Growing fastest: Spirits.
Distribution Channel:
Channel selection determines margin capture and consumer discovery mechanics. Direct-to-consumer platforms absorb disproportionate margin pools through subscription curation, while traditional retail processes highest absolute transaction volumes.
- Online Retail:Subscription-driven discovery purchasing displaces supermarket trial among health-conscious British millennials. Curated mixed cases with nutritional transparency capture share from off-trade in London and Manchester metropolitan clusters.
- Supermarkets:Shelf-space competition intensifies as Heineken's zero-alcohol platform dominates continental European placement through licensed brewing networks.
- Convenience Stores:Impulse purchase dynamics favor single-serve formats with immediate consumption positioning.
- Bars:On-trade venues in the United Kingdom normalize reduced-intoxication social occasions through expanded sub-3% ABV draft lineups.
Supermarkets process the highest absolute volumes. Online retail captures the steepest margin expansion.
Consumer Type:
Demographic targeting aligns with distinct consumption occasions and price sensitivity profiles. Health motivation drives premium positioning, while social context determines format and channel selection.
- Health-Conscious Individuals:Nutritional transparency and clean-label claims drive purchasing decisions among German millennials and Gen Z cohorts.
- Social Drinkers:Session-strength alternatives support extended social occasions without intoxication effects, concentrating demand in British pub culture.
- Young Adults:Digital-native discovery through curated subscription platforms displaces traditional brand loyalty formation.
- Occasional Drinkers:Reduced-ABV options lower barriers to participation in drinking occasions without full abstinence commitment.
Social drinkers anchor volume demand. Health-conscious individuals command premium pricing power.
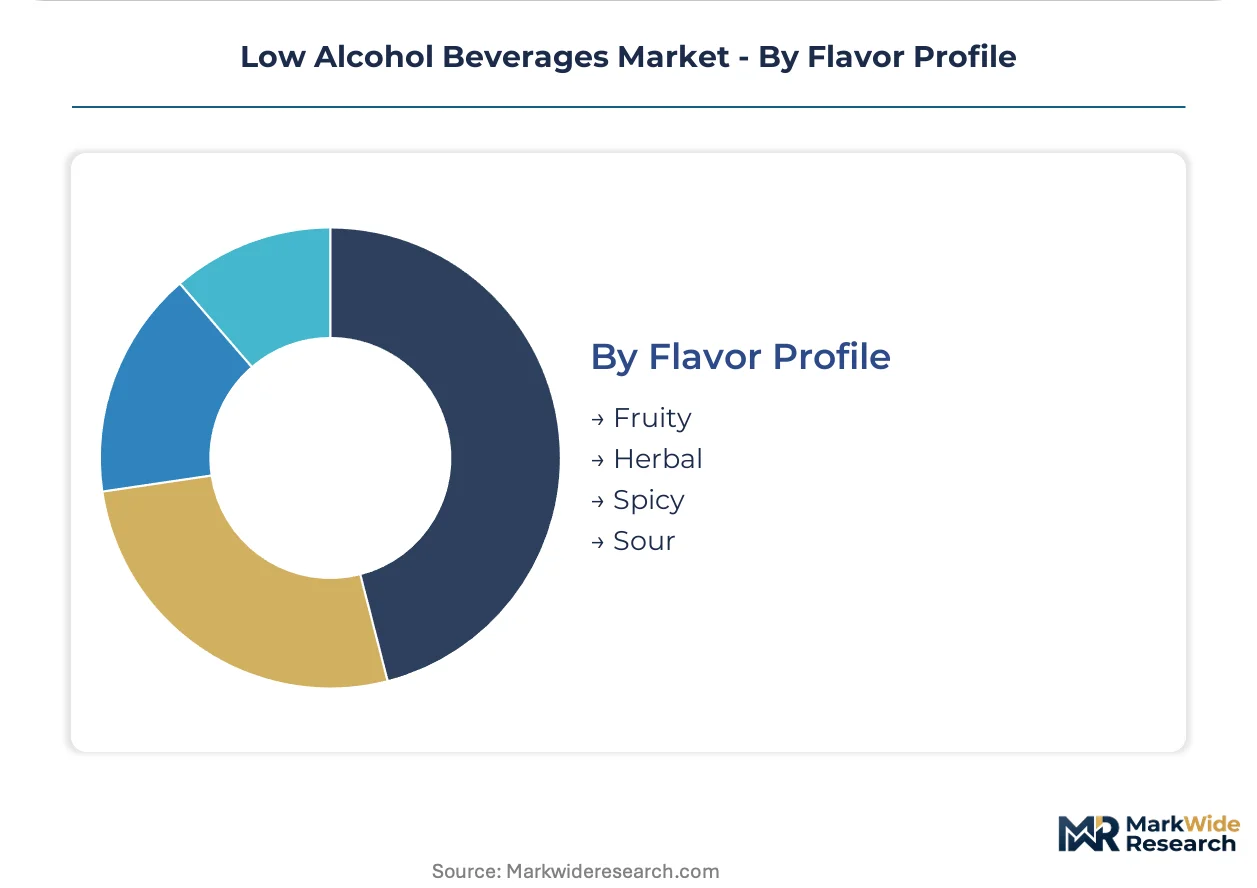
Flavor Profile:
Flavor reconstruction science determines competitive differentiation as alcohol removal strips volatile compounds. Enzymatic and membrane technologies converge to preserve aromatic complexity previously lost in dealcoholization.
- Fruity:Tropical and citrus notes mask ethanol absence in wine alternatives through natural ester preservation.
- Herbal:Botanical complexity supports premium positioning in spirits formulations through controlled extraction protocols.
- Spicy:Pepper and warming spice profiles replicate mouthfeel sensations lost with alcohol reduction.
- Sour:Controlled acidity and fermentation byproducts create perceived complexity in beer alternatives.
Fruity profiles dominate current shelf placement. Herbal formulations gain share fastest in premium spirits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Barley cultivation belts in Bavaria and Bohemia anchor European supply chains for enzymatic alcohol reduction. British malting cooperatives source from these regions for sub-3% ABV lager production. Japanese rice varieties from Niigata prefecture support sake-derived fermentation protocols for dealcoholized wine alternatives.
Germany
Health-conscious millennials in Berlin and Munich drive demand for reduced-ABV beers and transparent nutritional labeling. EFSA guidelines under EU Regulation 1169/2011 mandate caloric disclosure above 0.5% ABV, compressing formulation timelines. The Hamburg metropolitan cluster hosts brewing cooperatives piloting reverse osmosis units at sub-1,000 hectoliter scale.
United Kingdom
Session-strength pub culture normalizes extended social drinking without intoxication across London and Manchester. WHO alcohol reduction frameworks tighten permissible marketing language for health claims. The Southeast England corridor concentrates direct-to-consumer fulfillment infrastructure for curated low-alcohol subscription platforms.
United States
FDA labeling requirements at 0.5% ABV create distinct formulation targets for premium positioning in California and New York retail. TTB taxation thresholds separate non-alcoholic from reduced-alcohol classifications. The Pacific Northwest brewing cluster integrates arrested fermentation protocols with existing craft infrastructure.
Japan
MetI standards govern novel food ingredient approvals for enzymatic alcohol reduction catalysts. Tokyo and Osaka metropolitan areas concentrate demand for zero-alcohol beer alternatives in corporate drinking contexts. The Kansai region hosts fermentation technology specialists developing hybrid protocols for 0.5-1.2% ABV wine alternatives.
Netherlands
Heat-recovery vacuum distillation retrofits respond to EU Green Deal carbon footprint disclosure mandates under CSRD. Amsterdam and Rotterdam anchor logistics hubs for dealcoholized wine exports facing Asian reclassification risks. The Randstad cluster concentrates specialty chemical suppliers of enzymatic catalysts for arrested fermentation.
Low Alcohol Beverages Market Vendor Landscape
Global majors compete with regional champions across licensed brewing networks and proprietary fermentation protocols. The market structure consolidates around multinational beverage conglomerates with zero-alcohol platforms, tiered against craft-scale specialists and licensed regional producers. Three archetypes dominate: diversified brewing giants with dedicated R&D hubs, craft fermenters leveraging membrane technology cost curves, and licensed regional bottlers accessing multinational shelf-space networks. Competitive moves center on enzymatic alcohol reduction R&D expansion and direct-to-consumer subscription channel capture.
Within the diversified brewing tier, Heineken N.V. and Carlsberg Group exemplify multinational scale advantages through continental European shelf-space dominance. The Boston Beer Co. Inc. occupies a craft-specialist position, representing American independent fermentation protocol development. Asahi Group Holdings Ltd. anchors Japanese brewing technology transfer into dealcoholized formats.
| Leading Market Players |
|---|
| Anheuser-Busch InBev |
| Heineken N.V. |
| Constellation Brands Inc. |
| Molson Coors Beverage Company |
| Diageo plc |
| Carlsberg Group |
| Asahi Group Holdings Ltd. |
| The Boston Beer Co. Inc. |
| Sapporo Breweries Ltd. |
| Others |
Supply Flow & Price Mechanics
Health-conscious procurement preferences in Germany and the United Kingdom for transparent nutritional labeling under EU Regulation 1169/2011 are forcing supply chain reconfiguration toward enzymatic alcohol reduction capabilities, compressing margins for conventional arrested fermentation suppliers while rewarding membrane technology adopters with pricing power.
Pricing Analysis
Service bundling separates technical support packages from base product pricing, with enzymatic catalyst suppliers in Denmark and the Netherlands unbundling fermentation consulting from material costs. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments. Pricing pressure stems from reverse osmosis equipment cost declines enabling craft-scale competition. Health-conscious millennials in British subscription channels show least price sensitivity, while convenience store single-serve buyers anchor the economy tier.
Supply Chain Analysis
Freight cost volatility for temperature-controlled transport of enzymatic catalysts from the Netherlands and Denmark to German brewing cooperatives is elevating regional sourcing premiums. Supply concentrates in Bavarian barley belts, Dutch specialty chemical clusters, and British malting cooperatives. Raw material dependencies span Danish enzymatic inputs, German hop varieties, and Japanese rice strains for sake-derived protocols. Single-source vulnerability around membrane separation equipment from German engineering suppliers creates inventory risk. Distribution runs through licensed brewing networks for continental European shelf access, with direct-to-consumer platforms capturing margin in British metropolitan clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane separation technology is displacing vacuum distillation as the dominant dealcoholization pathway, with reverse osmosis cost curves enabling craft-scale production previously locked out by capital intensity.
For Market Incumbents: Deepen proprietary enzymatic alcohol reduction R&D investment at Copenhagen-based hubs to defend against membrane technology cost compression threatening vacuum distillation margins. Secure backward integration into specialty catalyst supply through partnerships with Dutch chemical suppliers. Expand licensed brewing network shelf-space dominance in continental Europe before craft competitors achieve scale. For New Entrants and Emerging Players: EU Regulation 1169/2011 in Germany and the United Kingdom opens a window for clean-label positioning through direct-to-consumer subscription models targeting health-conscious millennials. Target the 0.5-1.2% ABV wine alternative segment where hybrid fermentation protocols create white space between zero-alcohol and session-strength tiers. Lead with nutritional transparency and curated discovery boxes in London and Manchester fulfillment clusters. For Investors and Strategic Acquirers: The window for entry favors craft-scale membrane technology specialists with proprietary flavor chemistry capabilities over diversified brewing conglomerates facing legacy system retrofit costs. Long-term viability rests on enzymatic and membrane technology convergence enabling sensory reconstruction at sub-0.5% ABV. Watch for flavor chemist talent acquisition velocity as an inflection indicator for formulation quality differentiation.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Alcohol Reduction R&D Expansion | Carlsberg's Copenhagen hub demonstrates proprietary catalyst development as a defensive moat against membrane commoditization. |
| Direct-to-Consumer Subscription Launch | British digital-native brands capture disproportionate margin pools through curated discovery boxes with nutritional transparency. |
| Membrane Technology Licensing Agreement | Reverse osmosis equipment cost declines enable craft-scale dealcoholization previously locked out by capital intensity barriers. |
| Backward Integration into Catalyst Supply | Danish and Dutch specialty chemical supplier concentration creates vertical integration opportunities for fermentation protocol control. |
| Sustainability Repositioning Under CSRD | EU Green Deal carbon footprint disclosure mandates pressure thermal energy intensity reduction in dealcoholization processes. |
Methodological Framework
Independent corroboration across regulatory filings with EFSA, trade association fermentation technology surveys, and customs records for enzymatic catalyst imports underwrites the qualitative findings in this study. Primary interviews with brewing R&D directors, specialty chemical procurement managers, and direct-to-consumer platform operators combined with secondary validation from EU Regulation 1169/2011 implementation guidance, WHO alcohol reduction framework documents, and CSRD sustainability reporting standards. Bottom-up volume modeling from individual facility capacity announcements triangulates against top-down category spending estimates.
Comparable historical reference periods spanning pre-pandemic baseline, supply disruption recovery, and current normalization anchor the forecast window across the analysis window. Segmentation dimensions modeled include product type, distribution channel, consumer archetype, and flavor profile, with additional granularity on ABV threshold positioning relative to FDA and EU regulatory boundaries. CAGRs derive from category penetration rate assumptions and per-capita consumption shift elasticities, incorporating enzymatic catalyst cost curves and membrane equipment pricing trajectories as industry-specific inputs.
The model assumes a particular technology adoption path; alternative pathways for vacuum distillation efficiency improvements or novel biological fermentation protocols would alter the outlook. Forecasts reflect assumptions about regulatory enforcement consistency, consumer health claim receptivity, and supply chain input cost stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Hogshead Barrel Market
Alcoholic Beverages
Luxury Wines and Spirits Market
Alcoholic Beverages
South America Craft Beer Market
Alcoholic Beverages
Rum Market
Alcoholic Beverages
Wine Filling Machine Market
Alcoholic Beverages
Beer Cans Market
Alcoholic Beverages
Middle East and Africa Alcoholic Beverage Market
Alcoholic Beverages
Europe Wine Market
Alcoholic Beverages
Alcohol Gummies Market
Alcoholic Beverages
Cognac Market
Alcoholic Beverages
Global Bourbon Market
Alcoholic Beverages
Alcohol-Free Pineapple Beer Market
Alcoholic Beverages
Hip Flask Market
Alcoholic Beverages
US Frozen Cocktail Popsicles Market
Alcoholic Beverages
Brewing Supplies Market
Alcoholic Beverages
Mini Brew Fermenter Market