
 India Gin Market | 2026-2036
India Gin Market Size, Share, and Industry Trends Forecast 2026-2036
India Gin Market Insights
Skilled craft distiller availability is collapsing across India's boutique spirits sector, constraining small-batch production scaling and forcing brands to compete aggressively for trained talent. Diageo PLC sustains market leadership through its established distribution architecture and brand equity built around legacy labels. Pernod Ricard SA leverages global formulation expertise to anchor premium positioning in metropolitan retail channels. Radico Khaitan differentiates through backward integration into grain neutral spirit production, controlling input costs across its portfolio.
India gin comprises a juniper-forward neutral grain spirit distilled with botanicals including coriander, angelica, and regional variants such as Himalayan pine or mango, achieving minimum alcohol by volume thresholds set by excise authorities for classification. The spirit serves primarily as a cocktail base in commercial hospitality and as a sipping product in premium home consumption occasions. London Dry formulations dominate volume due to established consumer familiarity and bartender preference for classic cocktail construction. Flavored variants represent the fastest-expanding segment as indigenous botanical experimentation attracts younger demographics. Distribution through bars captures the highest margin pools by establishing brand prestige before retail conversion.
FSSAI mandates govern ingredient disclosure and maximum permissible additives, while state excise authorities regulate manufacturing licensing and inter-state movement under divergent tariff structures. BIS standards for packaging integrity and labeling compliance create additional compliance layers for new market entrants. Stakeholders must monitor evolving state-level excise policies and craft distillery licensing reforms that could reshape competitive access across India's fragmented regulatory landscape.
Market Dynamics
Skilled craft distiller scarcity is compressing production capacity across Maharashtra, Karnataka, and Goa, forcing brands to bid aggressively for trained talent while state excise licensing delays compound operational bottlenecks for new entrants.
Growth Catalysts
- FSSAI Labeling Modernization:Evolving disclosure standards for botanical sourcing and alcohol content are legitimizing premium positioning for domestic craft producers seeking metropolitan retail placement.
- Maharashtra Hospitality Infrastructure:Mumbai and Pune bar clusters are anchoring cocktail culture diffusion, with bartender education programs accelerating gin-forward menu adoption across tier-one hotels.
- Indigenous Botanical Experimentation:Himalayan juniper variants and mango peel infusions are attracting younger demographics previously anchored to whiskey and vodka consumption patterns.
Market Restraints
- Grain Neutral Spirit Input Volatility:Fluctuating molasses and grain feedstock costs are squeezing margin structures for brands without captive ethanol production capabilities.
- State Excise Fragmentation:Divergent inter-state movement tariffs and manufacturing licensing requirements across 28 states create compliance complexity that favors incumbents with established regulatory affairs teams.
- Whiskey Substitution Dominance:Indian single malt and premium whiskey categories retain entrenched consumer loyalty and retail shelf allocation, constraining gin's share of wallet expansion.
Strategic Opportunities
- Goa Craft Distillery Cluster:Concentrated tourism flows and relaxed excise enforcement are enabling direct-to-consumer tasting room models that bypass traditional distribution markups.
- PLI Scheme Alignment:Production-linked incentives for food processing and alcoholic beverage manufacturing could reduce capital intensity for greenfield distillery investments in designated zones.
- E-commerce Direct Channels:State-permitted alcohol delivery platforms in Karnataka and Maharashtra are opening last-mile access to home consumption occasions previously captured by retail.
Industry Challenges
- Master Distiller Talent Pipeline Collapse:Formal training programs for botanical blending and small-batch fermentation remain scarce, forcing brands to poach from rival operations or import foreign expertise.
- BIS Packaging Certification Delays:Extended testing timelines for bottle integrity and label compliance are stretching product launch schedules and freezing working capital in inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Gin Market |
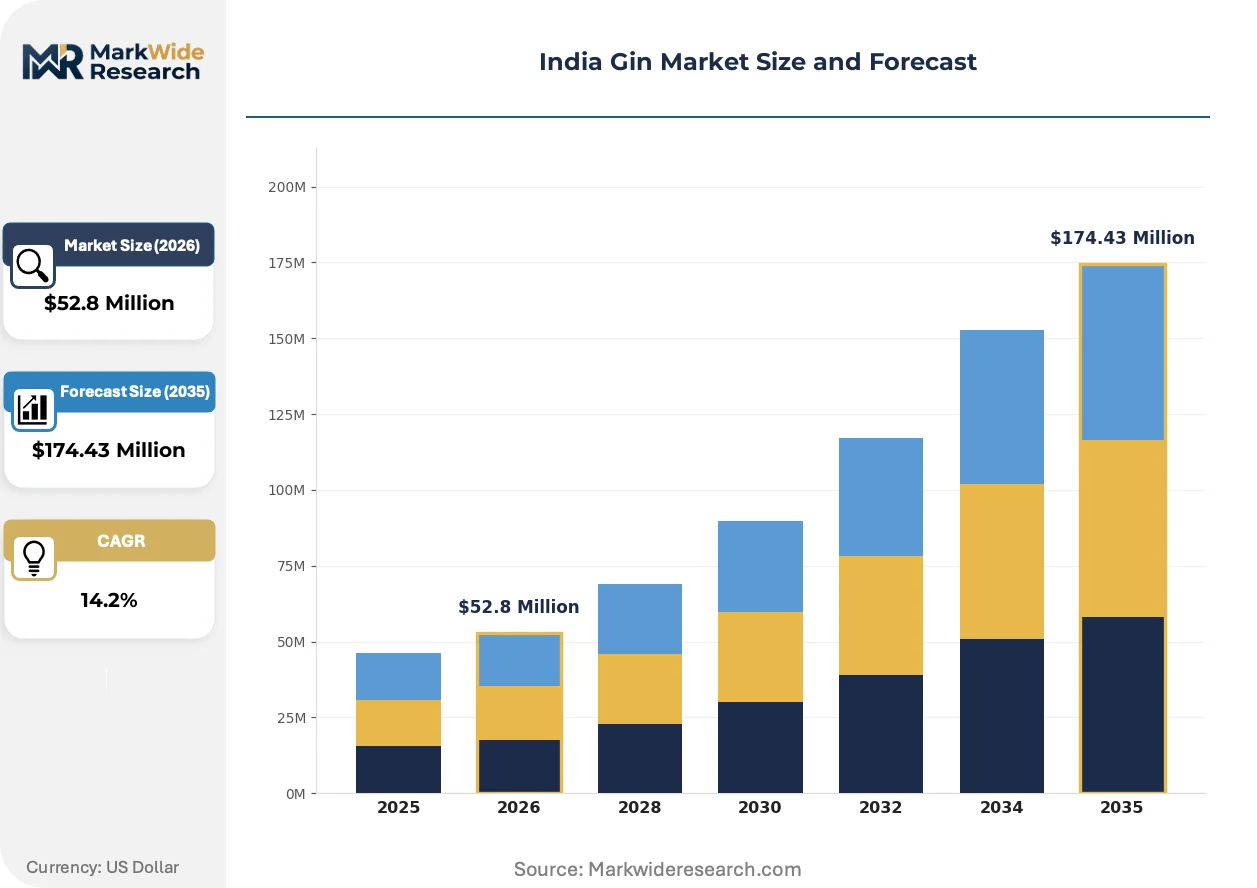
| Market Size in 2026 | $52.8 Million |
| Market Size in 2035 | $174.43 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: London Dry, Old Tom, Navy Strength, Flavored Distribution Channel: Online, Supermarkets, Specialty Stores, Bars Packaging Type: Glass Bottles, Cans, PET Bottles, Tetra Packs Customer Type: Millennials, Affluent Consumers, Casual Drinkers, Connoisseurs |
| Companies Covered | Diageo PLC, Pernod Ricard SA, Radico Khaitan, Nao Spirits, Stranger & Sons, Greater Than, Hapusa, Jaisalmer Gin, Sector Gin, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Gin Market Trends and Innovations
Converging pressures from regulatory disclosure mandates, indigenous ingredient experimentation, and channel fragmentation are compressing traditional production and distribution models across the Indian gin landscape.
Vacuum distillation and rotary evaporator technology is decomposing the conventional pot still monopoly in craft gin production. Boutique distilleries in Goa and Bengaluru are adopting these methods to preserve volatile terpenes from Himalayan botanicals. The equipment shift is compressing batch cycle times from days to hours while enabling flavor profiles previously unattainable through heat-intensive traditional methods.
FSSAI's evolving standards for additive disclosure and maximum permissible botanical concentrations are forcing reformulation across imported and domestic portfolios. Brands must now submit detailed ingredient matrices for pre-market approval, extending product development timelines. Premium labels with established compliance infrastructure are absorbing these costs more readily than new entrants, reshaping competitive access.
Home consumption occasions are fragmenting previously bar-centric brand building. Affluent consumers in Mumbai and Delhi are building personal gin collections and hosting tasting events, displacing on-premise discovery as the primary trial mechanism. E-commerce platforms with state alcohol licenses are capturing this shift through curated subscription boxes and virtual masterclass bundling.
India Gin Market Segmentation
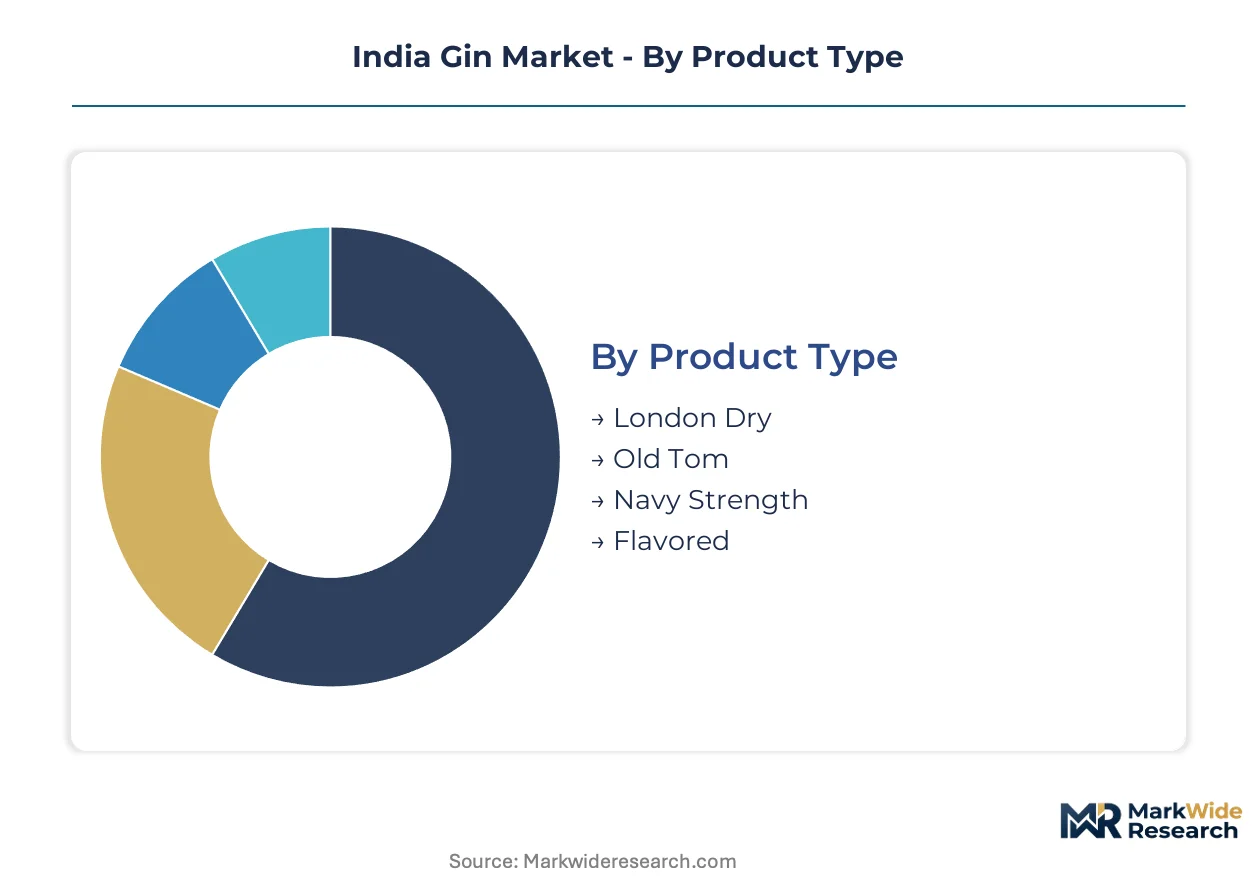
Segmentation reveals how substitution pressures and channel fragmentation are reshaping competitive priorities across India's gin landscape. Understanding where whiskey retains entrenched loyalty versus where indigenous botanicals are converting new consumers enables targeted resource allocation.
Product Type:
Whiskey substitution pressure concentrates most intensely among classic formulations, while experimental profiles face lighter competitive headwinds from incumbent spirits categories.
- London Dry:Juniper-forward neutral grain spirit with strict additive prohibitions under FSSAI guidelines. Maharashtra and Karnataka bars anchor demand as bartenders prioritize reliable cocktail construction bases. The segment faces persistent whiskey substitution at retail as consumers default to familiar brown spirits for home occasions.
- Flavored:Botanical-infused variants incorporating Himalayan pine, mango peel, or regional citrus. Younger demographics in Mumbai and Delhi are driving trial through bar discovery and e-commerce sampling packs. Indigenous ingredient experimentation is lowering the category-switching barrier from vodka and ready-to-drink cocktails.
- Old Tom:Sweeter profile with post-distillation sugar additions, historically popular in colonial-era India. Limited contemporary production constrains availability to specialty retail and heritage hotel bars.
- Navy Strength:High-proof formulation at minimum alcohol by volume thresholds exceeding standard classifications. Goa craft distilleries and naval heritage marketing anchor niche positioning among connoisseur segments.
London Dry retains volume leadership; Flavored holds the steepest expansion curve.
Distribution Channel:
Margin capture potential varies sharply across channels, with on-premise discovery commanding premium positioning power that retail struggles to replicate.
- Bars:Mumbai and Pune cocktail-forward establishments anchor brand prestige formation before consumer retail conversion. Bartender education programs and menu placement fees create high customer acquisition costs with disproportionate lifetime value returns.
- Online:State-permitted platforms in Karnataka and Maharashtra are fragmenting traditional retail control over home consumption occasions. Virtual masterclass bundling and subscription boxes are displacing bar-centric discovery for affluent urban cohorts.
- Supermarkets:Standard retail placement with FSSAI-compliant labeling requirements. Shelf allocation competition from whiskey and vodka categories constrains visibility for emerging gin labels.
- Specialty Stores:Curated selection targeting connoisseur segments with tasting events and staff education. Concentrated in metropolitan markets with established craft spirits infrastructure.
Bars dominate margin pools; Online is climbing the fastest as regulatory permissions expand.
Packaging Type:
BIS certification timelines and material cost volatility are compressing format innovation, with glass maintaining incumbent advantage despite sustainability pressures.
- Glass Bottles:Premium positioning standard with established BIS integrity testing protocols. Maharashtra and Goa distilleries favor amber and clear variants for UV protection and shelf presence.
- Cans:Emerging format for ready-to-drink gin-based cocktails targeting outdoor consumption occasions. Limited domestic canning infrastructure constrains scaling.
- PET Bottles:Cost-driven format for mass-market price tiers. FSSAI additive migration concerns and consumer perception barriers limit premium adoption.
- Tetra Packs:Experimental format for airline and hospitality miniatures. Minimal current penetration due to compatibility challenges with alcohol content thresholds.
Glass Bottles retain volume leadership; Cans hold the steepest expansion trajectory among alternative formats.
Customer Type:
Generational transition dynamics are fragmenting traditional consumption patterns, with age cohort and sophistication level intersecting unpredictably with channel preferences.
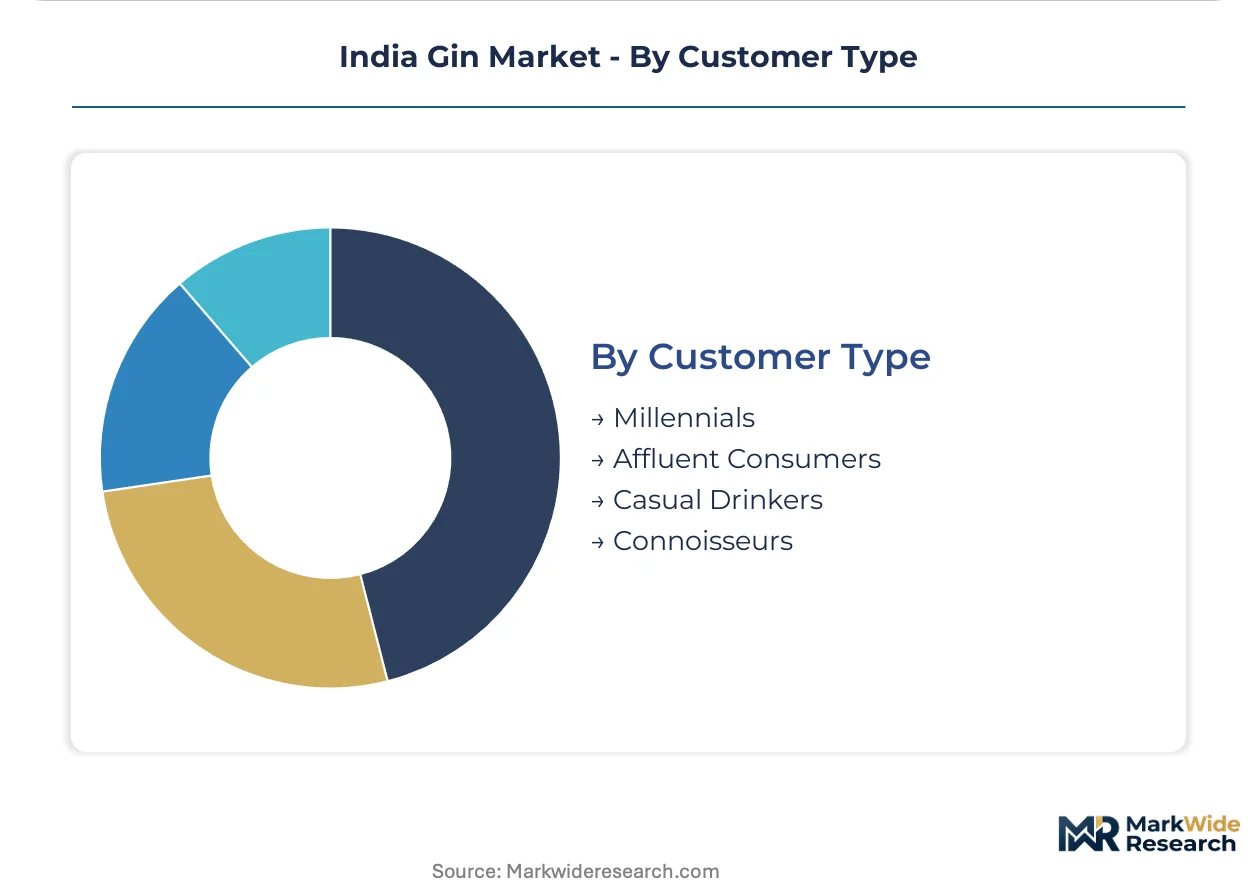
- Millennials:Digital-native cohort driving flavored variant trial through Instagram-native brand discovery and e-commerce subscription models. Mumbai and Bengaluru urban clusters concentrate demand.
- Connoisseurs:Sophisticated collectors building personal gin libraries and hosting home tasting events. Direct-to-consumer relationships with Goa craft distilleries bypass traditional markup structures.
- Affluent Consumers:Established professionals with bar-centric discovery habits converting to home consumption through premium retail. Hotel loyalty programs and airport duty-free anchor brand exposure.
- Casual Drinkers:Occasional spirits consumers with low category loyalty and high price sensitivity. Whiskey and beer default preferences constrain gin penetration.
Affluent Consumers retain volume leadership; Millennials are gaining share fastest through digital-native trial mechanisms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FSSAI standards govern national compliance, yet state-level excise regimes fragment operational reality across India's gin production landscape. Maharashtra, Karnataka, and Goa anchor concentrated demand through hospitality infrastructure and craft distillery clusters.
Maharashtra
Mumbai and Pune bar ecosystems drive cocktail-forward consumption among affluent professionals. State excise licensing under the Maharashtra State Excise Department imposes manufacturing permits and inter-state movement tariffs. Nashik and Mumbai craft distilleries scale vacuum distillation adoption for indigenous botanical preservation.
Karnataka
Bengaluru's technology workforce fuels premium home consumption and e-commerce subscription trial. The Karnataka Excise Department regulates micro-distillery licensing with evolving craft producer exemptions. Electronic City and Indiranagar clusters concentrate bartender education programs and specialty retail infrastructure.
Goa
Tourism flows sustain direct-to-consumer tasting room models bypassing traditional distribution markups. Relaxed state excise enforcement enables experimental distillery formats unavailable elsewhere. North Goa craft producers leverage vacuum distillation for Himalayan juniper terpene extraction.
Delhi-NCR
Airport duty-free and hotel loyalty programs anchor brand exposure among business travelers. Delhi Excise policy permits limited home delivery pilots expanding e-commerce access. Gurugram and Noida hospitality developments replicate Mumbai cocktail culture diffusion.
Telangana
Hyderabad's pharmaceutical-affluent demographic drives premium spirits trial through specialty retail. State excise authorities maintain restrictive manufacturing licensing limiting local craft production. Banjara Hills and Jubilee Hills concentrate high-end bar infrastructure with gin-forward menu adoption.
India Gin Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with multinational beverage conglomerates leveraging captive distribution networks against craft distilleries competing on indigenous botanical differentiation. The market structure compresses into two strategic archetypes: legacy spirits houses with backward-integrated ethanol production and boutique operators with localized ingredient sourcing. Competitive moves center on bartender education investments and direct-to-consumer channel development.
Among multinational spirits houses, Diageo PLC and Pernod Ricard SA exemplify integrated leaders with established regulatory affairs infrastructure. Radico Khaitan occupies a position representing domestic scale players with captive grain neutral spirit production. Within the craft specialist tier, Nao Spirits and Stranger & Sons exemplify indigenous botanical experimentation and direct-to-consumer relationship building.
| Leading Market Players |
|---|
| Diageo PLC |
| Pernod Ricard SA |
| Radico Khaitan |
| Nao Spirits |
| Stranger & Sons |
| Greater Than |
| Hapusa |
| Jaisalmer Gin |
| Sector Gin |
| Others |
Pricing and Supply Chain Analysis
Captive grain neutral spirit production in Maharashtra and Karnataka creates asymmetric margin capture between integrated distillers and contract-dependent competitors, compressing price floors for London Dry formulations while elevating premium tiers for indigenous botanical variants. State excise tariff fragmentation across 28 jurisdictions forces brands to absorb differential compliance costs that concentrate pricing power among incumbents with established regulatory affairs infrastructure.
Pricing Analysis
Maharashtra commands 15-20% price premiums over Goa for identical formulations due to higher state excise duties and metropolitan retail markups. Three-tier pricing structure across premium craft, standard domestic, and economy imported levels separates brands by botanical sourcing transparency and distillation method. Pricing pressure stems from molasses feedstock volatility squeezing margin structures for non-integrated producers. Casual drinkers exhibit highest price sensitivity, defaulting to whiskey at retail, while connoisseurs accept sustained premiums for limited-batch indigenous expressions.
Supply Chain Analysis
Strategic stockpiling of Himalayan juniper and regional botanicals dominates over just-in-time procurement given harvest seasonality and terpene degradation risks. Supply concentrates in India for grain neutral spirit production, with juniper sourcing extending to Nepal and Bhutan foothills. Raw material dependencies encompass molasses and grain feedstocks for ethanol, imported copper still components, and specialty yeast strains. Single-source vulnerability concentrates in master distiller talent, where formal training program scarcity forces poaching wars. Distribution runs through state-permitted wholesale networks before fragmenting into bar, retail, and emerging e-commerce channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's gin market operates as a defensive-moat structure where regulatory entrenchment through FSSAI compliance infrastructure and state excise licensing creates switching costs that favor established operators over new entrants. Network effects concentrate in bartender education relationships and hotel chain placement that lock in brand prestige before retail conversion.
For Market Incumbents: Compound regulatory affairs capabilities into adjacent state markets before craft distillery licensing reforms lower barriers. Deepen backward integration into botanical cultivation partnerships in Himalayan foothills to secure terpene-provenance claims that command premium positioning. Expand vacuum distillation capacity in Goa and Bengaluru to compress batch cycle times while whiskey substitution pressure intensifies at retail.
For New Entrants and Emerging Players: Lead with direct-to-consumer tasting room models in Goa's tourism corridor, bypassing traditional distribution markups that incumbent networks control. Target flavored variant experimentation with mango peel and regional citrus profiles where whiskey substitution pressure remains weakest. Anchor go-to-market through state-permitted e-commerce platforms in Karnataka and Maharashtra, bundling virtual masterclasses to replicate bar-centric discovery in home consumption occasions.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among craft distilleries with established direct-to-consumer relationships and proprietary botanical sourcing agreements that create ingredient moats. Long-term viability over the medium-term projection horizon rests on regulatory compliance infrastructure scalability across multiple state jurisdictions. Acquisition target archetype: boutique operators with vacuum distillation technology adoption and Himalayan juniper terpene extraction capabilities. Monitor FSSAI additive disclosure rulemaking timelines as the critical inflection signal for compliance cost absorption advantages.
| Strategic Initiative | Industry Significance |
|---|---|
| Bartender Education Program Expansion | Mumbai and Pune cocktail-forward establishments anchor brand prestige formation before consumer retail conversion occurs. |
| Backward Integration into Botanical Cultivation | Himalayan juniper and regional citrus sourcing partnerships secure terpene-provenance claims for premium positioning. |
| Vacuum Distillation Technology Adoption | Goa and Bengaluru craft producers compress batch cycle times while preserving volatile compounds from heat-sensitive botanicals. |
| Direct-to-Consumer Channel Development | State-permitted e-commerce platforms in Karnataka fragment traditional retail control over affluent home consumption occasions. |
| FSSAI Compliance Infrastructure Investment | Pre-market approval capabilities for ingredient matrices extend competitive moats against undercapitalized new entrants. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with craft distillery founders, master distillers, Maharashtra and Karnataka state excise officials, FSSAI regulatory affairs leads, Mumbai bar beverage directors, and e-commerce platform category managers. Secondary validation drew from FSSAI notification gazettes, state excise department licensing records, BIS packaging standards documentation, and customs trade data for imported botanicals. Bottom-up volume estimates from distillery production capacities triangulated against top-down consumption projections from hospitality sector procurement patterns.
Across the analysis window, the forecasting framework modeled segmentation dimensions encompassing product type, distribution channel, packaging format, and customer sophistication tier. CAGRs were derived from trend extrapolation of vacuum distillation adoption rates, indigenous botanical experimentation frequency, and state-level e-commerce regulatory permission expansion. Industry-specific inputs incorporated master distiller talent pipeline constraints, molasses feedstock price volatility indices, and bartender education program graduation rates.
Underlying assumptions cover sustained FSSAI disclosure standard evolution and stable state excise tariff differentials, with deviation risk concentrated in craft distillery licensing reform timelines and grain neutral spirit input cost spikes. Practitioners should keep alternative scenarios live as regulatory permission frameworks for direct-to-consumer channels and interstate movement tariffs evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Ouzo Market
Alcoholic Beverages
Craft Rum Market
Alcoholic Beverages
Global Spiced/Flavored Rum Market
Alcoholic Beverages
Wine Cellar Market
Alcoholic Beverages
Cabernet Sauvignon Market
Alcoholic Beverages
Asia-Pacific Wine Market
Alcoholic Beverages
RTD Cocktail Shots Market
Alcoholic Beverages
Craft Spirits Market
Alcoholic Beverages
Citrus Alcohol Market
Alcoholic Beverages
Commercial Beer Tap System Market
Alcoholic Beverages
Automated Brewing System Market
Alcoholic Beverages
Home Brew Boiler Market
Alcoholic Beverages
Smart Wine Cellar Market
Alcoholic Beverages
Wine Filling Machine Market
Alcoholic Beverages
Brewing Enzymes Market
Alcoholic Beverages
South America Alcoholic Beverages Market