
 Dairy Products Membrane Filtration Equipment Market | 2026-2036
Dairy Products Membrane Filtration Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Dairy Products Membrane Filtration Equipment Market Insights
Polymeric membranes are repositioning ceramic systems in mid-scale whey processing as suppliers cut capital outlays by roughly one-third. Alfa Laval AB leverages its dairy heritage to dominate European retrofit installations. GEA Group AG sustains technology leadership through continuous processing architectures. Koch Membrane Systems Inc specializes in spiral-wound configurations for protein fractionation.
Dairy products membrane filtration equipment encompasses pressure-driven separation systems employing semi-permeable barriers with pore sizes ranging from 0.1 nanometers to 10 micrometers to selectively retain proteins, fats, bacteria, and minerals while permitting water and dissolved salts to permeate. These systems operate at transmembrane pressures between 1 and 70 bar, serving primarily to concentrate milk solids, clarify fluids, and recover high-value whey fractions for ingredient manufacturing. Ultrafiltration captures the largest installed base owing to its centrality in cheese milk standardization and whey protein concentrate production. Cross-flow filtration technology leads new order intake because its tangential velocity profile minimizes fouling and extends membrane life in high-solids dairy streams.
EU Green Deal decarbonization mandates and REACH chemical safety protocols are tightening material specifications for membrane polymers and cleaning chemistries, compelling equipment vendors to validate bio-based alternatives. FDA pasteurized milk ordinance requirements in the United States and 3-A Sanitary Standards constrain hygienic design architectures, favoring suppliers with validated clean-in-place protocols. Stakeholders must monitor emerging EU F-Gas Regulation limits on fluorinated membrane materials, as these could force accelerated R&D timelines for polymeric substitutes without warning.
Market Dynamics
EU Green Deal decarbonization mandates are forcing simultaneous retrofits of existing whey processing lines and greenfield cheese plant construction across multiple member states, compressing equipment procurement cycles and reshaping supplier qualification criteria.
Growth Catalysts
- REACH chemical safety protocols:These ECHA mandates are accelerating membrane material substitutions toward bio-based polymers, generating replacement demand across installed European cheese processing capacity.
- Whey protein concentrate production:Sports nutrition and infant formula manufacturers are expanding fractionation capacity, pulling ultrafiltration system orders from equipment vendors with validated hygienic designs.
- Netherlands cooperative investment:Royal FrieslandCampina and regional dairy cooperatives are retrofitting aging facilities, concentrating near-term order intake in the Dutch membrane filtration market.
Market Restraints
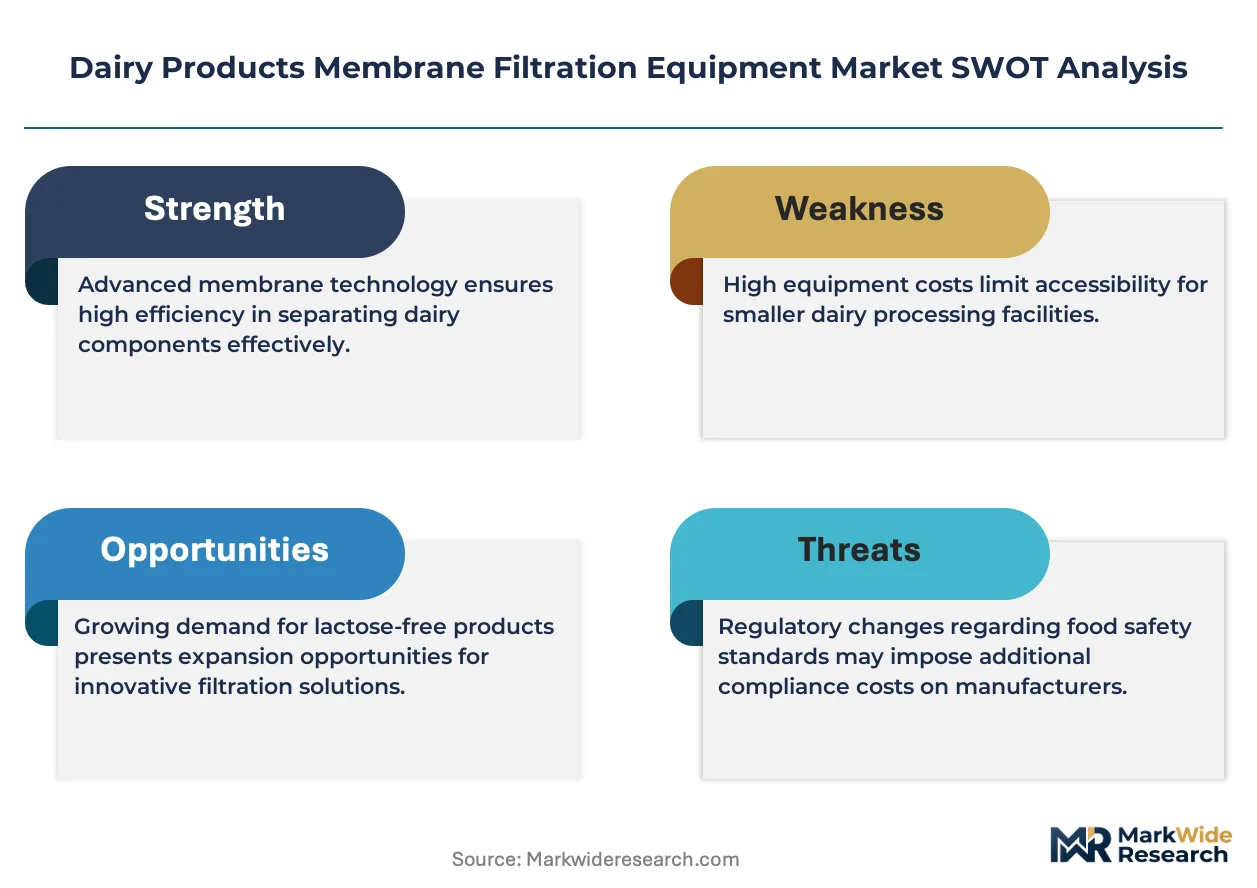
- Fluorinated polymer supply concentration:EU F-Gas Regulation limits on fluorinated membrane materials threaten input availability, forcing unplanned R&D pivots toward polymeric substitutes without guaranteed performance parity.
- High-purity ceramic membrane costs:Alumina and zirconia feedstock volatility elevates capital outlays for large-scale installations, constraining adoption outside premium whey protein isolate applications.
- Cleaning chemistry registration delays:ECHA biocidal product authorization timelines extend commissioning schedules, freezing project cash flows for processors awaiting compliance clearance.
Strategic Opportunities
- Poland and Romania dairy modernization:These EU cohesion fund recipients are building first-generation membrane capacity, creating greenfield opportunities absent legacy equipment displacement costs.
- Precision fermentation feedstock preparation:Alternative protein startups require sterile, lipid-standardized permeate streams, opening membrane filtration to non-traditional dairy adjacent demand.
- 3-A Sanitary Standards convergence:FDA and EU hygiene protocol alignment is simplifying dual-certification pathways, reducing market entry friction for equipment vendors with transatlantic ambitions.
Industry Challenges
- Membrane fouling prediction expertise:The shortage of process engineers capable of modeling protein-polysaccharide interactions in high-solids streams extends commissioning timelines and elevates service dependency on original equipment suppliers.
- Clean-in-place protocol validation:FDA pasteurized milk ordinance compliance requires documented thermal and chemical sanitization cycles, forcing processors to maintain redundant buffer capacity during qualification periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dairy Products Membrane Filtration Equipment Market |
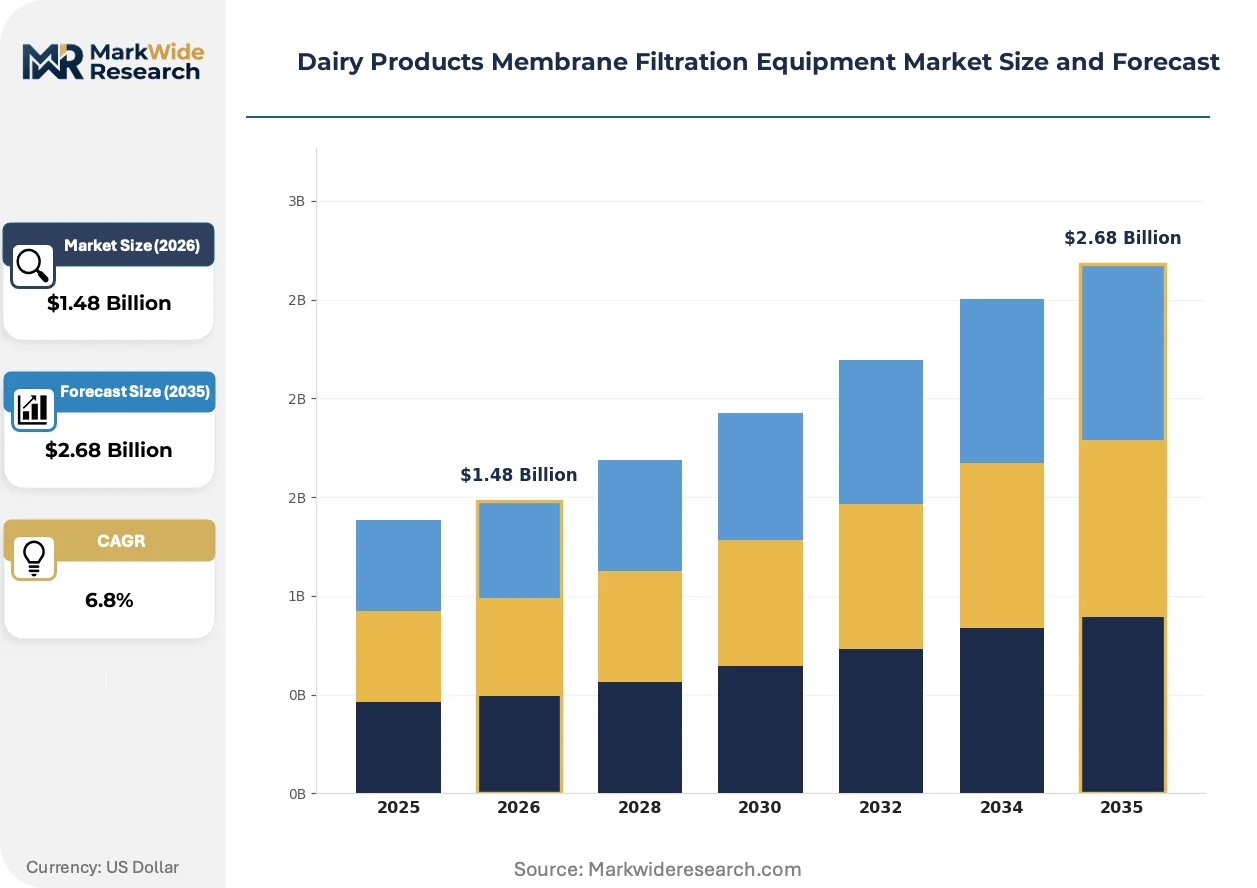
| Market Size in 2026 | $1.48 Billion |
| Market Size in 2035 | $2.68 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrafiltration, Microfiltration, Nanofiltration, Reverse Osmosis End User: Dairy Processing Plants, Food Industry, Beverage Manufacturers, Research Laboratories Technology: Cross-flow Filtration, Dead-end Filtration, Batch Processing, Continuous Processing Application: Cheese Production, Whey Processing, Milk Clarification, Water Treatment |
| Companies Covered | Alfa Laval AB, GEA Group AG, Koch Membrane Systems Inc, Pall Corporation, 3M Company, Suez Water Technologies and Solutions, SPX Flow, Inc., Veolia, Porvair Filtration Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dairy Products Membrane Filtration Equipment Market Trends and Innovations
Cross-flow filtration architectures are displacing dead-end systems as fouling mitigation becomes the decisive performance metric in high-solids dairy processing. Equipment vendors are embedding predictive analytics and modular skid designs to compress installation timelines.
Polymeric spiral-wound configurations are integrating ceramic-grade selectivity through advanced polymer grafting techniques, enabling mid-scale processors to access protein fractionation precision previously reserved for capital-intensive ceramic installations. Dutch and German cheese manufacturers are piloting these hybrid systems in whey protein concentrate lines. The technology is integrating continuous processing economics into batch-oriented plant footprints, eroding the scale advantages historically held by large cooperatives.
EU F-Gas Regulation phase-down schedules are compelling membrane suppliers to validate bio-based fluoropolymer alternatives ahead of mandated material restrictions. Equipment vendors must now submit extended performance durability data to ECHA for novel polymer formulations. Cheese processors in Germany and the Netherlands are prioritizing suppliers with demonstrated compliance roadmaps, shifting procurement criteria toward regulatory readiness and away from pure technical specifications.
After-sales service unbundling is fragmenting traditional equipment procurement into separate capital and operating expenditure decisions. Dairy cooperatives are negotiating membrane replacement subscriptions independent of initial system purchases, transferring fouling risk to vendors. This model is compressing vendor margins while expanding addressable revenue in consumables and remote monitoring. The shift is most visible in the Netherlands, where FrieslandCampina-scale buyers leverage volume concentration to dictate contract structures.
Dairy Products Membrane Filtration Equipment Market Segmentation
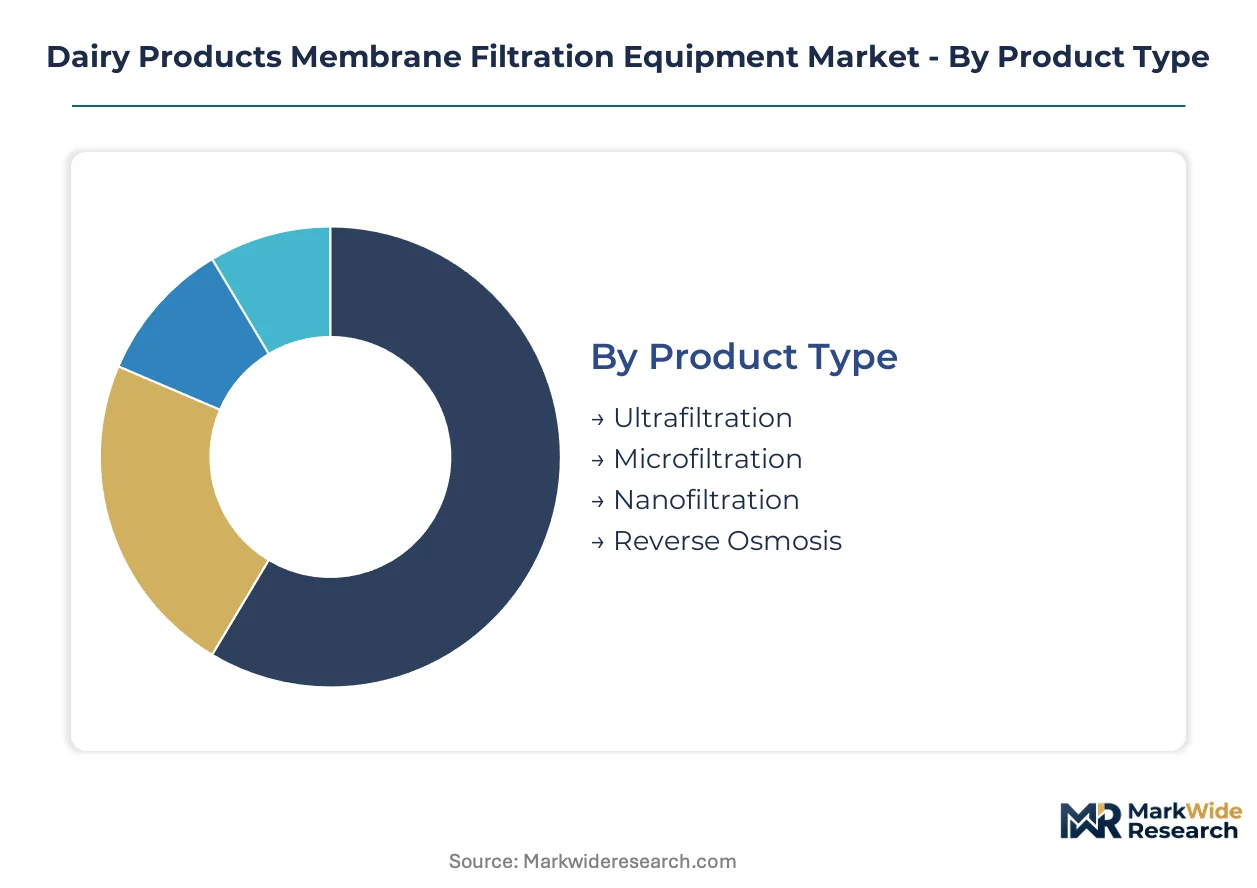
Membrane filtration equipment procurement varies sharply across technical specifications and operational contexts. Equipment vendors must align system architecture with specific protein recovery targets, regulatory compliance requirements, and plant-scale economics.
Product Type:
Capital intensity escalates from polymeric spiral-wound systems to ceramic configurations with precision-engineered pore structures. Ultrafiltration and microfiltration dominate current order books due to their centrality in standardized dairy operations.
- Ultrafiltration:Pore sizes between 1 and 100 nanometers retain proteins and fats while permitting lactose and mineral permeation. German cheese manufacturers are expanding ultrafiltration capacity to meet EU Green Deal sustainability targets for whey protein concentrate production.
- Microfiltration:Operating at 0.1 to 10 micrometers, these systems remove bacteria and spores without thermal degradation. Dutch cooperatives including Royal FrieslandCampina are retrofitting aging microfiltration lines to capture extended shelf-life milk market share.
- Nanoftration:Divalent ion selectivity enables partial demineralization of whey streams prior to drying.
- Reverse Osmosis:Near-total dissolved solids rejection supports water recovery and effluent minimization objectives.
Ultrafiltration absorbs the bulk of installed capacity; nanofiltration is expanding most quickly as processors seek demineralization efficiency without evaporative energy costs.
End User:
Customer scale and technical sophistication determine service intensity and contract structure. Large cooperatives negotiate subscription-based membrane replacement, while smaller operators prioritize capital expenditure minimization.
- Dairy Processing Plants:Integrated cheese and whey operations require multi-stage membrane trains with automated clean-in-place validation. Netherlands-based cooperatives are driving retrofit investments in whey protein concentration systems.
- Food Industry:Ingredient manufacturers demand lipid-standardized permeate streams for infant formula and sports nutrition applications. Precision fermentation feedstock preparation is opening membrane filtration to non-traditional dairy-adjacent demand.
- Beverage Manufacturers:Lactose-free milk production utilizes nanofiltration for sugar reduction without protein denaturation.
- Research Laboratories:Pilot-scale systems support membrane material validation and process optimization for commercial scale-up.
Dairy processing plants command the largest equipment footprint; food industry buyers are gaining share fastest as ingredient fractionation diversifies beyond traditional cheese economics.
Technology:
Flow regime selection governs fouling economics and membrane longevity in high-solids dairy streams. Tangential velocity profiles now dominate procurement specifications over static pressure configurations.
- Cross-flow Filtration:Tangential velocity minimizes protein-polysaccharide deposition on membrane surfaces, extending cleaning intervals. GEA Group AG sustains technology leadership through continuous processing architectures leveraging cross-flow economics.
- Dead-end Filtration:Direct perpendicular flow suits low-solids clarification with disposable membrane economics. Limited to small-scale operations or pre-filtration stages where fouling risk remains manageable.
- Batch Processing:Intermittent operation permits flexible feedstock handling but requires buffer tank capacity and extended cleaning downtime.
- Continuous Processing:Steady-state operation maximizes throughput per membrane area, reducing specific energy consumption in large installations.
Cross-flow filtration dominates new order intake; continuous processing is climbing the fastest as cooperatives seek labor efficiency and reduced cleaning chemical consumption.
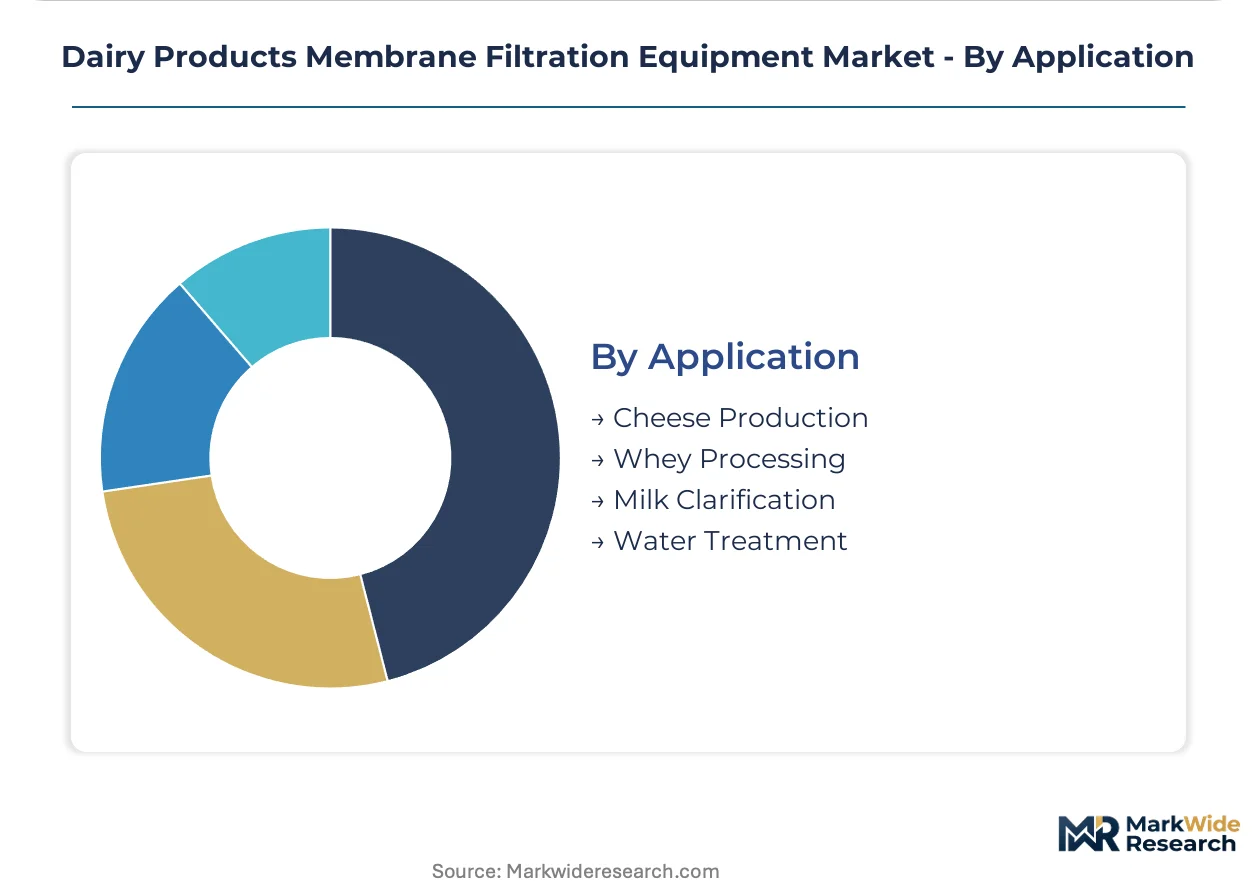
Application:
Downstream product value determines acceptable capital recovery periods and membrane replacement frequencies. Whey fractionation commands premium system specifications due to protein isolate margins.
- Cheese Production:Milk standardization via ultrafiltration adjusts protein-to-fat ratios prior to curd formation, standardizing yield and texture. Alfa Laval AB leverages its dairy heritage to dominate European retrofit installations in this segment.
- Whey Processing:Multi-stage membrane trains concentrate protein fractions while segregating lactose and minerals for separate valorization. Koch Membrane Systems Inc specializes in spiral-wound configurations for protein fractionation in this application.
- Milk Clarification:Bacteria and spore removal extends shelf life without UHT thermal degradation.
- Water Treatment:Reverse osmosis recovery of permeate water reduces dairy plant effluent volumes and freshwater intake.
Whey processing commands the highest specific equipment investment per installed square meter; water treatment is gaining share fastest as EU Green Deal mandates tighten effluent discharge standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German cheese manufacturers and Dutch cooperatives anchor equipment procurement intensity, with EU Green Deal mandates compressing retrofit timelines across both markets. Poland and Romania absorb cohesion fund allocations for first-generation membrane installations. France and Italy concentrate demand in premium whey fractionation for infant formula exports.
Germany
Cheese production facilities in Bavaria and Lower Saxony are expanding ultrafiltration capacity to meet EU Green Deal sustainability targets for whey protein concentrate output. ECHA REACH protocols are accelerating membrane material substitutions toward bio-based polymers, forcing validation cycles on replacement equipment. The Münsterland dairy cluster is retrofitting aging standardization lines with continuous processing architectures.
Netherlands
Royal FrieslandCampina and regional cooperatives are driving retrofit investments in whey protein concentration systems across Friesland and North Brabant. EU F-Gas Regulation limits on fluorinated membrane materials are compelling processors to prioritize suppliers with demonstrated compliance roadmaps. The Wageningen food valley is piloting hybrid polymeric-ceramic configurations for mid-scale fractionation.
Poland
EU cohesion fund recipients are building first-generation membrane capacity in the Greater Poland and Masovian voivodeships, creating greenfield opportunities absent legacy equipment displacement costs. ECHA biocidal product authorization timelines are extending commissioning schedules for cleaning chemistry validation. The Łódź dairy processing corridor is attracting equipment vendors with modular skid designs.
France
Infant formula manufacturers in Brittany and the Loire Valley are expanding nanofiltration capacity for demineralized whey permeate production. ANSM oversight of food contact materials is tightening membrane polymer specifications for export-bound ingredient streams. The Rennes agri-food cluster is integrating predictive analytics into multi-stage membrane trains.
Italy
Parmigiano-Reggiano and Grana Padano consortia in Emilia-Romagna are standardizing milk protein ratios through ultrafiltration ahead of protected designation of origin certification. EFSA hygiene protocol alignment with FDA pasteurized milk ordinance requirements is simplifying dual-certification pathways for equipment vendors. The Po Valley cheese district is prioritizing cross-flow filtration to minimize fouling in high-solids streams.
Dairy Products Membrane Filtration Equipment Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with heritage dairy equipment vendors commanding retrofit loyalty while membrane material suppliers capture consumables revenue. The vendor base concentrates around three strategic archetypes: integrated process technology conglomerates, membrane material specialists with spiral-wound expertise, and regional fabrication houses serving emerging markets. Competitive positioning hinges on regulatory compliance roadmaps and after-sales service unbundling into subscription-based membrane replacement contracts.
Within the integrated process technology tier, Alfa Laval AB and GEA Group AG exemplify vendors leveraging continuous processing architectures to dominate European retrofit installations. Koch Membrane Systems Inc occupies a specialist position in spiral-wound configurations for protein fractionation applications. These three companies anchor the competitive structure, with each representing distinct approaches to hygienic design validation and clean-in-place protocol development across dairy processing segments.
| Leading Market Players |
|---|
| Alfa Laval AB |
| GEA Group AG |
| Koch Membrane Systems Inc |
| Pall Corporation |
| 3M Company |
| Suez Water Technologies and Solutions |
| SPX Flow, Inc. |
| Veolia |
| Porvair Filtration Group |
| Others |
Pricing and Supply Chain Analysis
Process engineer scarcity in the Netherlands and Germany widens pricing-tier spreads between premium continuous-processing systems and economy batch configurations. Labor-cost differentials between these engineering-dense regions and emerging fabrication hubs in Poland and Romania compress margins on mid-scale equipment while sustaining premium pricing for vendor-managed service contracts.
Pricing Analysis
High-volume membrane replacement subscriptions trade margin for recurring revenue, while project-based system sales retain wider spreads. Three-tier pricing structure across premium ceramic systems, standard polymeric configurations, and economy batch units differentiates on clean-in-place validation depth and regulatory roadmap maturity. Cost compression in mid-scale polymeric equipment intensifies as Dutch cooperatives leverage volume concentration to unbundle after-sales service. Small dairy processors in Poland and Romania exhibit greatest price sensitivity, prioritizing capital expenditure minimization over compliance-ready specifications.
Supply Chain Analysis
Single-source vulnerability sits with fluorinated polymer feedstock concentrated in German and Belgian chemical manufacturing clusters. Ceramic membrane production draws from alumina and zirconia processing anchored in China, Germany, and Japan. EU F-Gas Regulation phase-down schedules threaten input availability for membrane polymers, forcing unplanned reformulation cycles. Distribution runs through integrated process technology conglomerates with captive fabrication capacity and regional assembly partners serving cohesion fund markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits in a technology-transition phase where hybrid polymeric-ceramic configurations displace legacy ceramic-only installations. Cross-flow filtration architectures are replacing dead-end systems as the decisive performance benchmark.
For Market Incumbents: Cement regulatory roadmap leadership by validating bio-based fluoropolymer alternatives ahead of EU F-Gas mandated restrictions. Deepen upstream control over membrane polymer formulation to capture replacement subscription revenue and defend against service unbundling pressure from Dutch cooperative buyers.
For New Entrants and Emerging Players: Capture greenfield installation demand in Poland and Romania where EU cohesion fund financing eliminates legacy equipment displacement costs. Target precision fermentation feedstock preparation as a non-traditional dairy-adjacent application with sterile permeate requirements and limited incumbent presence.
For Investors and Strategic Acquirers: Re-rating potential sits with membrane material specialists possessing spiral-wound protein fractionation expertise given whey protein concentrate production expansion. Long-term viability favors vendors with demonstrated ECHA compliance roadmaps and validated clean-in-place protocols. Watch EU F-Gas Regulation enforcement timing as the inflection indicator for accelerated R&D pivot requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Roadmap Validation | ECHA bio-based polymer submissions ahead of F-Gas limits secure procurement preference from German cheese manufacturers. |
| Hybrid System Piloting | Dutch and German whey processing lines test polymeric-ceramic configurations for mid-scale fractionation precision. |
| Service Unbundling Response | Membrane replacement subscriptions independent of initial purchases transfer fouling risk to equipment vendors. |
| Cohesion Fund Market Entry | Modular skid designs attract first-generation membrane capacity builds in Greater Poland and Masovian voivodeships. |
| Precision Fermentation Adjacency | Sterile lipid-standardized permeate streams open membrane filtration to alternative protein startup demand. |
Research Methodology
Independent corroboration across equipment vendor sales directors, dairy cooperative procurement leads, and ECHA regulatory affairs specialists underwrites the qualitative findings. Primary interviews with plant engineers at Netherlands and German cheese facilities, membrane material R&D directors, and aftermarket service heads combined with secondary validation from EU customs data, SEC filings of listed process technology conglomerates, and ECHA biocidal product registration databases. Bottom-up installation tracking and top-down market sizing triangulate volume estimates.
Historical reference periods anchored the forecast window to observed retrofit cycles and greenfield construction timelines across the projection horizon. Segmentation dimensions modeled include membrane pore size classification, flow regime architecture, processing mode, and end-user scale tier. CAGRs derived from equipment order intake patterns, membrane replacement frequency data, and regulatory compliance-driven upgrade cycles. Industry-specific inputs incorporate EU Green Deal decarbonization mandate implementation pace and REACH chemical safety protocol substitution timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU F-Gas Regulation phase-down acceleration, ECHA biocidal authorization delays, and ceramic feedstock price volatility. Forecasts reflect documented assumptions regarding cooperative investment continuity and precision fermentation market development. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Processing Machinery
Commercial Cheese Shredder Market
Dairy Processing Machinery
Modified Milk Powder Market
Dairy Processing Machinery
Milk Powder Analyzing Device Market
Dairy Processing Machinery
Ice Cream Making Machine Market
Dairy Processing Machinery
Whey Protein Microparticulation Systems Market
Dairy Processing Machinery
Global Milk Tank Cooling System Market
Dairy Processing Machinery
Yogurt Cup Market
Dairy Processing Machinery
Multi-Spindle Milkshake Machine Market
Dairy Processing Machinery
Dairy Filtration Systems Market
Dairy Processing Machinery
Cheese Liners Market
Dairy Processing Machinery
Commercial Milkshake Machine Market
Dairy Processing Machinery
Cream Separator Market
Dairy Processing Machinery
Milk Clarifier Market
Dairy Processing Machinery
Concentrated Whey Market
Dairy Processing Machinery
Cheese Cutting Machine Market
Dairy Processing Machinery
Dairy Machines Market