
 Europe Beer Market | 2026-2036
Europe Beer Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Beer Market Intelligence
Multi-source malt procurement is restructuring supply economics for European brewers. Heineken leverages long-term barley contracts across multiple EU growing regions to secure input stability. Carlsberg Group anchors its competitive stance through backward integration into malting operations in Denmark and Germany. Bitburger Brewery differentiates via strict adherence to German purity law sourcing, occupying a defensible position in premium lager segments.
Beer is a fermented alcoholic beverage produced from malted cereals, hops, water, and yeast, typically containing ethanol concentrations between 4% and 6% by volume, with brewing involving mashing, boiling, fermentation, and conditioning stages to achieve flavor stability and microbiological safety. Lager dominates European volume due to scalable production and broad distribution compatibility across on-trade and off-trade channels. Ale and stout segments sustain above-average margin pools in super-premium price tiers, where craft positioning and localized storytelling command price premiums. E-commerce distribution channels represent the fastest-growing access route, though on-trade still controls the highest per-unit profitability for premium and super-premium portfolios.
EU regulations including the EU Green Deal, REACH, and EFSA food labeling standards shape brewing inputs, packaging sustainability mandates, and consumer-facing nutritional disclosures across member states. Germany's national purity law tradition and the EU F-Gas Regulation on cooling emissions constrain equipment choices and refrigeration infrastructure in production facilities. Brewers must monitor evolving CSRD sustainability reporting requirements and packaging waste directives that will dictate capital allocation toward circular economy compliance.
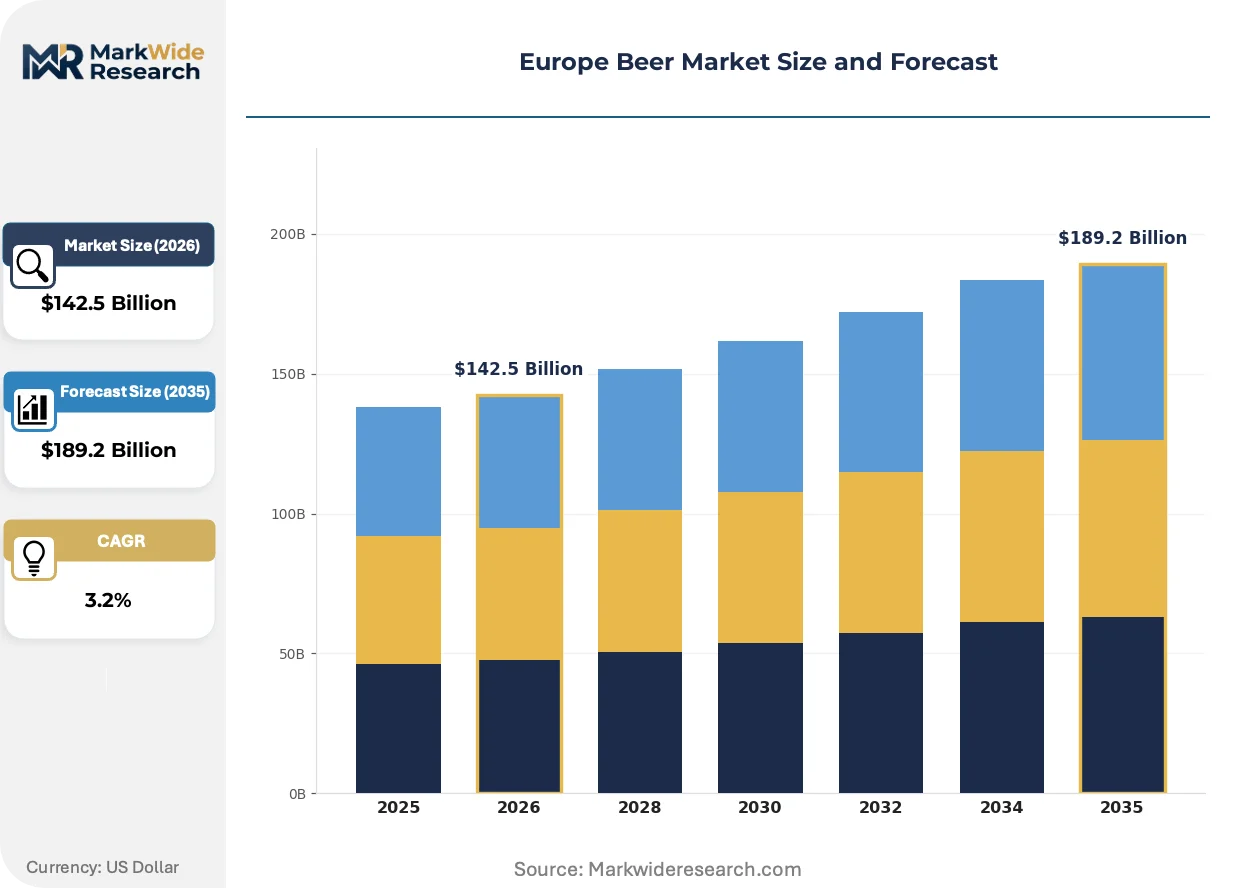
Market Dynamics
EU packaging waste directives and the EU Green Deal are forcing capital reallocation toward circular economy compliance across European brewing facilities, restructuring competitive economics between integrated and outsourced supply models.
Growth Catalysts
- CSRD sustainability reporting:Mandatory disclosures under the EU Corporate Sustainability Reporting Directive are accelerating investment in low-carbon brewing equipment and renewable energy sourcing across member states.
- Barley procurement diversification:Multi-source malt contracting across Poland, France, and Denmark is reducing input volatility for large-scale brewers with pan-European distribution networks.
- On-trade premiumization:Super-premium craft positioning in German, British, and Spanish hospitality venues commands price premiums through localized storytelling and Reinheitsgebot-certified heritage claims.
Market Restraints
- Input cost volatility:Barley and hop prices fluctuate with climate variability across major EU growing regions, compressing margin predictability for non-integrated brewers.
- F-Gas Regulation constraints:The EU F-Gas Regulation on cooling emissions limits refrigeration infrastructure choices in production facilities, extending equipment replacement cycles.
- Substitution pressure:Ready-to-drink spirits and low-alcohol alternatives are capturing occasion-based consumption in British and Spanish urban markets.
Strategic Opportunities
- E-commerce channel expansion:Direct-to-consumer platforms represent the fastest-growing access route for craft and specialty portfolios in Germany and the United Kingdom.
- EFSA labeling evolution:Nutritional disclosure mandates are creating first-mover advantage for brewers with transparent ingredient sourcing and calorie-count clarity.
- Spain's underpenetrated craft segment:Regional craft density in Andalusia and Valencia lags northern European benchmarks, offering white-space entry for heritage-positioned entrants.
Industry Challenges
- Master brewer talent scarcity:Specialized fermentation science expertise concentrates in traditional brewing regions, constraining scale-up for new market entrants.
- Legacy system integration:Retrofitting century-old facilities in Belgium and Czechia with energy-efficient brewing technology requires complex phasing without production interruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Beer Market |
| Market Size in 2026 | $142.5 Billion |
| Market Size in 2035 | $189.2 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lager, Ale, Stout, Porter Customer Type: Retail Consumers, Bars, Restaurants, Breweries Distribution Channel: On-trade, Off-trade, E-commerce, Wholesalers Price Tier: Premium, Mid-range, Budget, Super-premium |
| Companies Covered | Molson Coors Beverage Company, Oettinger Brewery, Anheuser-Busch InBev, Constellation Brands, Bitburger Brewery, Heineken, Asahi Group Holdings, Diageo plc, Carlsberg Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Beer Market Strategic Shifts & Innovations
Digital brewing control systems and precision fermentation analytics are compressing batch-to-batch variability while enabling real-time quality assurance across distributed production networks.
Precision fermentation technology is unifying yeast strain optimization with automated temperature and pH monitoring in large-scale facilities. German and Danish integrated brewers are deploying these systems fastest, replacing manual sampling protocols. The technology is unifying quality control with predictive maintenance, reducing spoilage rates and extending product shelf stability.
The EU F-Gas Regulation is tightening permissible cooling emissions thresholds for industrial refrigeration equipment used in fermentation and storage. Brewers must now specify low-global-warming-potential alternatives when replacing aging compression systems. Facilities in Germany and the Netherlands are responding fastest, driven by national enforcement schedules and energy audit requirements.
Buyer concentration in British and German grocery retail is compressing supplier negotiation leverage and accelerating private-label beer development. Discounters Aldi and Lidl are expanding own-brand lager and ale portfolios, displacing mid-tier branded volume in off-trade channels. This pattern is most visible in the United Kingdom, where retail consolidation has outpaced other EU markets.
Europe Beer Market Segmentation
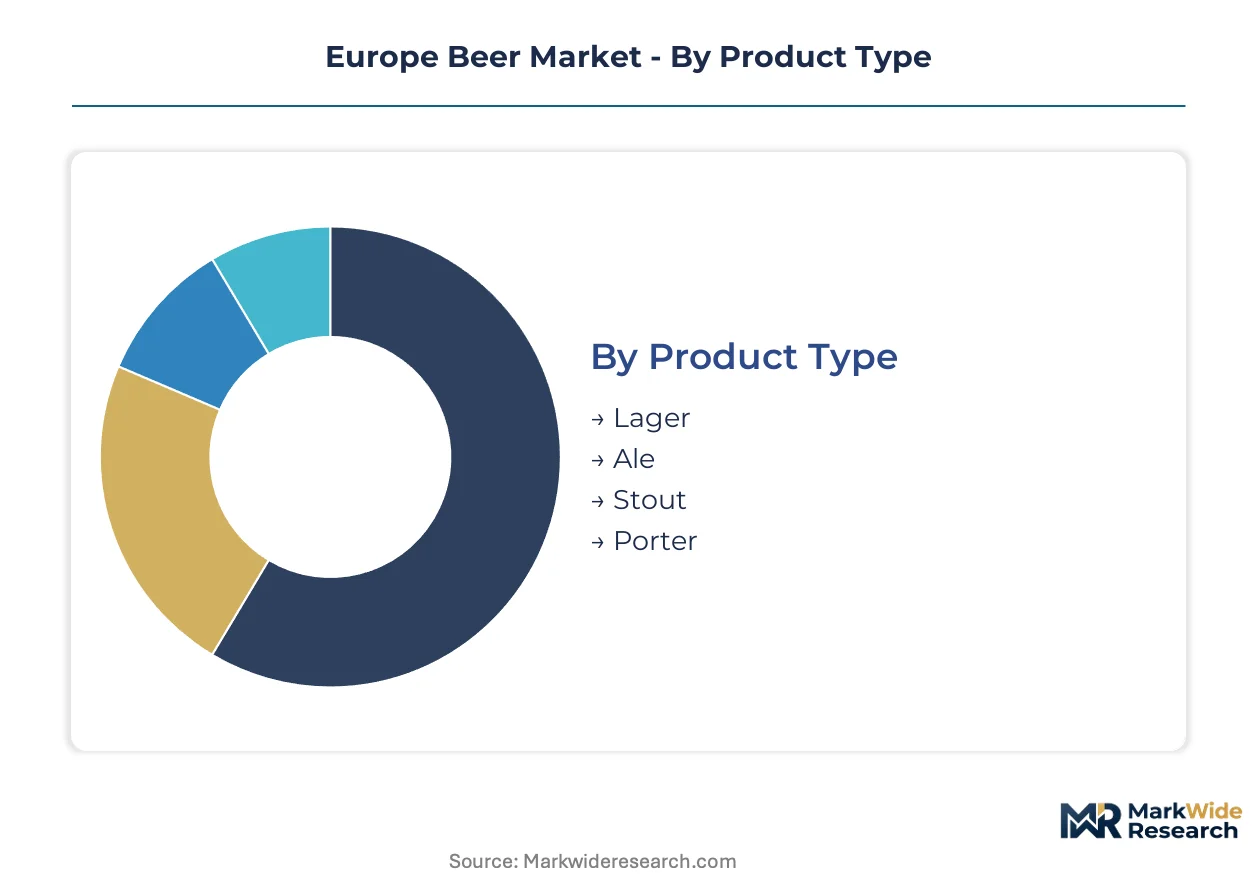
European beer segmentation reflects divergent brewing traditions, channel economics, and regulatory exposure across member states. Category boundaries increasingly blur as craft positioning penetrates mass-market portfolios and sustainability mandates reshape input specifications.
Product Type:
Fermentation temperature and yeast strain selection define the technical axis, with bottom-fermenting protocols dominating scalable production and top-fermenting methods anchoring heritage positioning.
- Lager:Cold-fermented with Saccharomyces pastorianus yeast at 7-13°C, producing clean, crisp flavor profiles with extended shelf stability. German and Czech brewing facilities concentrate volume here, driven by Reinheitsgebot compliance requirements and export-scale packaging infrastructure.
- Ale:Warm-fermented with Saccharomyces cerevisiae at 15-24°C, generating ester-forward aromatic complexity. British and Belgian craft breweries command price premiums through localized yeast strain libraries and cask-conditioning traditions.
- Stout:Dark-roasted malt varieties with nitrogen-dispensed serving protocols in Irish and British on-trade venues.
- Porter:Historic English recipe revival concentrated in London and Yorkshire microbrewery clusters.
Mature deployment sits with Lager. Newer deployment is concentrated in Ale.
Customer Type:
Purchasing scale and technical sophistication separate volume-contracting institutions from fragmented individual decision-making.
- Bars:Draught system investments and line-cleaning protocols create switching costs that lock in distributor relationships. German beer gardens and British pubcos sustain keg-flow commitments through tied-house arrangements and exclusive pouring contracts.
- Restaurants:Menu integration and sommelier training programs elevate beer-wine parity in Michelin-tier establishments across France and Spain. Margin structures here support bottle-conditioned and vintage-dated releases unavailable in retail.
- Retail Consumers:Individual purchasing decisions in supermarkets and convenience stores across Poland and Romania.
- Breweries:Contract brewing and white-label production services for brand owners without production assets.
Volume concentrates with Bars. Margin expansion concentrates with Restaurants.
Distribution Channel:
Physical proximity to consumption occasion and regulatory licensing requirements determine channel access economics.
- On-trade:Licensed premises with immediate consumption, subject to national alcohol licensing boards and local authority enforcement. German, British, and Spanish hospitality venues generate the highest per-unit profitability for super-premium portfolios through experience-based pricing.
- E-commerce:Direct-to-consumer platforms bypassing traditional three-tier distribution, fastest-climbing access route for craft and specialty portfolios in Germany and the United Kingdom.
- Off-trade:Supermarkets and convenience stores with takeaway licensing across EU member states.
- Wholesalers:Regional distribution intermediaries consolidating fragmented brewery output for retail and on-trade delivery.
Established infrastructure sits with On-trade. Steepest expansion trajectory sits with E-commerce.
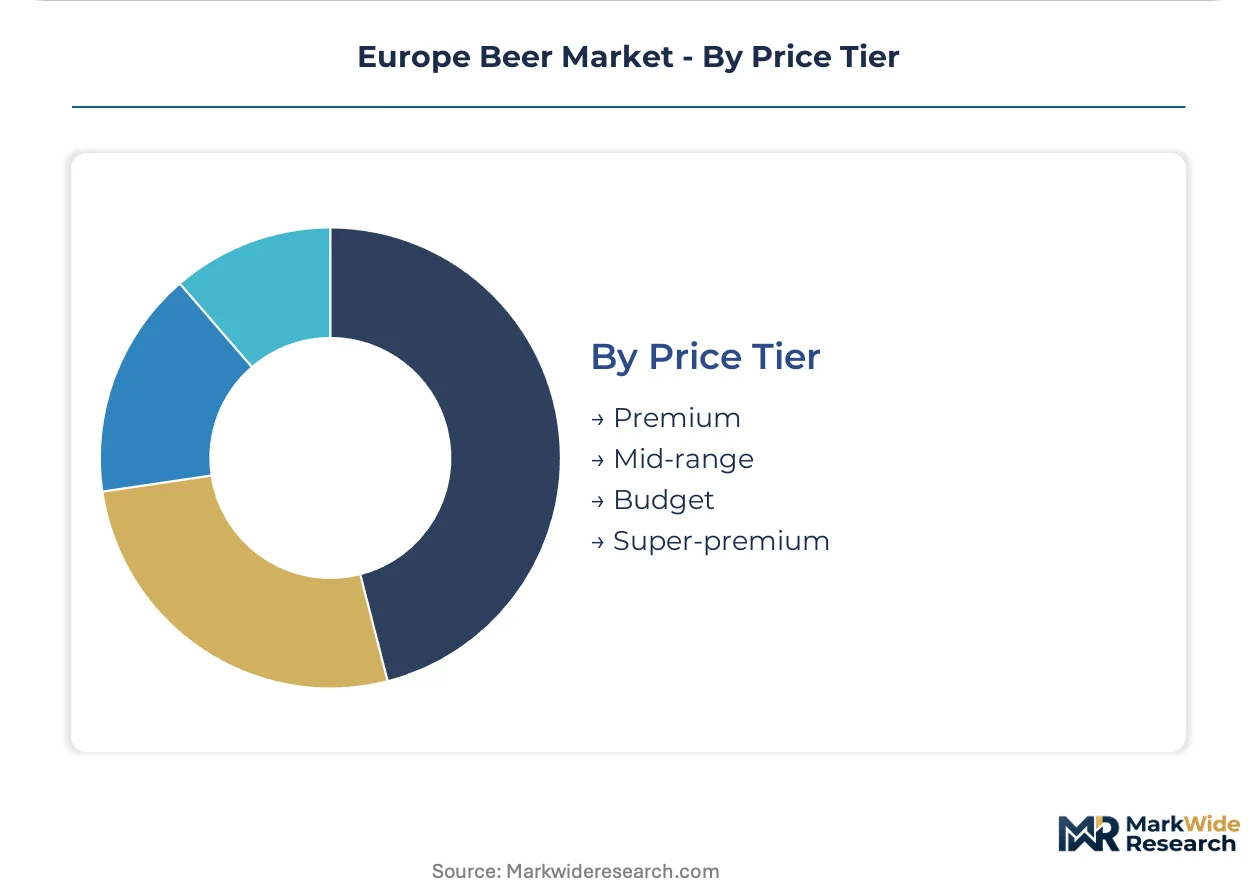
Price Tier:
Raw material grade, production batch size, and certification status stratify pricing architecture.
- Super-premium:Limited-batch releases with provenance documentation and vertical-format packaging. Belgian Trappist and German monastery breweries anchor this tier through appellation-controlled production sites and UNESCO-recognized brewing heritage.
- Premium:Reinheitsgebot-certified or equivalent quality-assured positioning with above-average malt bills and extended lagering periods. Carlsberg and Heineken deploy this tier to defend margin position against private-label displacement.
- Mid-range:Standardized recipes with regional brand recognition across multiple EU markets.
- Budget:High-volume, low-margin production for discount retail channels in Eastern Europe.
Margin defense concentrates with Premium. Volume risk concentrates with Budget.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Barley cultivation corridors across northern France, Poland, and eastern Germany anchor European brewing feedstock security. These grain belts supply maltsters serving breweries from Copenhagen to Munich. Climate variability and EU Common Agricultural Policy reforms are reshaping procurement patterns across the continent.
Germany
Reinheitsgebot-certified heritage breweries command super-premium pricing through monastery and family-owned production sites. The EU F-Gas Regulation mandates low-global-warming-potential refrigeration replacements in Bavarian and North Rhine-Westphalian facilities. Munich and Hamburg anchor integrated brewing clusters where precision fermentation analytics compress batch variability.
United Kingdom
Cask-conditioned ale traditions and craft brewery density in Yorkshire and London sustain above-average margin pools. CSRD sustainability reporting requirements accelerate low-carbon equipment investment across British production sites. Burton-upon-Trent's historic brewing infrastructure hosts heritage yeast strain preservation programs.
Spain
Andalusian and Valencian craft penetration lags northern European benchmarks, creating white-space entry for heritage-positioned entrants. EFSA nutritional labeling standards reshape packaging requirements for Madrid and Barcelona distribution centers. Basque Country microbreweries leverage localized storytelling to capture on-trade premiumization.
Belgium
Trappist appellation-controlled production sites and UNESCO-recognized brewing heritage anchor super-premium positioning. REACH chemical safety protocols govern cleaning agents and processing aids in Walloon and Flemish facilities. Brussels and Leuven concentrate specialized fermentation science expertise and legacy facility retrofitting challenges.
Netherlands
Heineken's global headquarters in Amsterdam drives pan-European procurement diversification strategies. The EU Green Deal packaging waste directives accelerate circular economy capital allocation in Dutch brewing facilities. Rotterdam's port infrastructure enables multi-source barley import logistics from Baltic and Black Sea suppliers.
Europe Beer Market Key Industry Players
Multi-source malt contracting dominates the current landscape as brewers secure input stability across climate-variable growing regions. The market structures around integrated multinationals with captive malting operations, heritage-positioned purity-law specialists, and agile craft disruptors with localized storytelling. Three archetypes prevail: scale-driven procurement optimizers, backward-integrated supply chain controllers, and terroir-certified premium defenders. M&A activity and sustainability-driven capacity retrofitting constitute the dominant competitive moves.
Among integrated multinationals, Heineken and Carlsberg Group exemplify procurement diversification and backward integration archetypes respectively. Bitburger Brewery occupies a defensible position in the purity-law specialist tier. These three anchors demonstrate how geographic origin and structural positioning shape competitive economics without requiring identical strategic postures.
| Leading Market Players |
|---|
| Molson Coors Beverage Company |
| Oettinger Brewery |
| Anheuser-Busch InBev |
| Constellation Brands |
| Bitburger Brewery |
| Heineken |
| Asahi Group Holdings |
| Diageo plc |
| Carlsberg Group |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap breweries across Bavaria and Belgium anchor pricing discipline through multi-generational equity structures that resist short-term margin compression, while their captive malting relationships and monastery-endowment financing insulate supply security from commodity volatility.
Pricing Analysis
Service bundling separates draught system maintenance contracts from keg-only transactions, with German beer gardens and British pubcos absorbing line-cleaning premiums into long-term tied-house agreements. Three-tier pricing structure across premium, standard, and economy levels stratifies by Reinheitsgebot certification status and extended lagering periods. Pricing pressure stems from Aldi and Lidl private-label expansion in British and German off-trade channels. Budget-tier retail consumers in Poland and Romania exhibit highest price sensitivity, while Michelin-tier restaurants in France and Spain accept super-premium markups for bottle-conditioned releases.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Hamburg, and Antwerp consolidate Baltic and Black Sea barley flows into hub-and-spoke patterns serving breweries from Copenhagen to Munich. Geographic supply concentration centers on Germany, France, and Poland for malting-grade barley, with Denmark and the Netherlands hosting integrated malting operations. Raw material dependencies rest on hop varieties from Hallertau and Saaz growing regions, specialty yeast strains preserved at Burton-upon-Trent, and nitrogen dispensing equipment for stout service. Single-source vulnerability concentrates in climate-exposed barley belts where drought frequency is rising. Distribution runs through wholesaler intermediaries consolidating fragmented craft output for on-trade delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation analytics and automated brewing control systems are displacing manual sampling protocols and century-old production workflows, compressing batch variability while extending shelf stability across European facilities.
For Market Incumbents: Deploy backward integration into malting operations to secure input stability against climate-driven barley volatility, while accelerating CSRD-compliant equipment retrofitting in legacy Belgian and Czech facilities to preempt regulatory penalties. Private-label displacement by Aldi and Lidl in British and German grocery retail demands premium-tier reinforcement through Reinheitsgebot-certified heritage claims.
For New Entrants and Emerging Players: Enter via Spain's underpenetrated craft segment in Andalusia and Valencia, where regional brewery density lags northern European benchmarks and localized storytelling commands on-trade premiumization. White-space exists for heritage-positioned entrants leveraging Basque Country microbrewery models. Direct-to-consumer e-commerce platforms in Germany and the United Kingdom offer the fastest-climbing access route for specialty portfolios.
For Investors and Strategic Acquirers: Distressed-cycle entries favor integrated malting operations in Denmark and Germany with captive barley contracting across multiple EU growing regions, as climate volatility compresses margin predictability for non-integrated brewers. Long-term viability hinges on circular economy compliance capital allocation under EU Green Deal packaging mandates. Monitor EFSA nutritional disclosure evolution as first-mover advantage signal for transparent ingredient sourcing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Malting | Heineken and Carlsberg secure input stability through captive supply across climate-variable EU barley belts. |
| Precision Fermentation Deployment | German and Danish integrated brewers replace manual sampling with predictive maintenance and real-time quality assurance. |
| E-commerce Channel Expansion | Direct-to-consumer platforms bypass three-tier distribution for craft portfolios in Germany and the United Kingdom. |
| CSRD Compliance Retrofitting | Low-carbon brewing equipment investment accelerates across British production sites under mandatory sustainability disclosures. |
| Heritage Certification Investment | Reinheitsgebot and Trappist appellation positioning defend super-premium margins against private-label displacement. |
Research Approach
Document review covered EU regulatory filings including EFSA labeling standards and F-Gas Regulation compliance schedules, complemented by interviews with master brewers, malt procurement directors, on-trade category managers at German beer gardens and British pubcos, and sustainability officers at integrated multinationals. Secondary validation drew from customs and trade data tracking barley flows through Rotterdam port infrastructure, SEC filings of listed beverage companies, and national brewing association production statistics. Bottom-up brewery capacity modeling and top-down consumption surveys were triangulated against channel shipment data.
Segmented outputs across fermentation type, price tier, distribution channel, and customer archetype were generated through the projection horizon, with CAGRs derived from historical volume trajectories and elasticity-adjusted price evolution. Modeling incorporated EU Common Agricultural Policy reform impacts on barley cultivation economics, CSRD-driven capital expenditure phasing, and e-commerce penetration curves for craft and specialty portfolios.
Revisions become necessary when EU packaging waste directive enforcement timelines accelerate, F-Gas Regulation thresholds tighten beyond current equipment replacement cycles, or climate variability disrupts established barley procurement patterns in northern France and eastern Germany. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Microbrewery Supplies Market
Alcoholic Beverages
Puncheon Barrel Market
Alcoholic Beverages
North America Alcoholic Beverages Market
Alcoholic Beverages
South America Wine Market
Alcoholic Beverages
Beer Fermenter Market
Alcoholic Beverages
Sake Market
Alcoholic Beverages
Global Distillation System Market
Alcoholic Beverages
E-Commerce Liquor Market
Alcoholic Beverages
Isoamyl Alcohol Market
Alcoholic Beverages
Middle East and Africa Fermented Drinks Market
Alcoholic Beverages
Barware Market
Alcoholic Beverages
Beer Line Cleaning Kit Market
Alcoholic Beverages
Hookah Charcoal Market
Alcoholic Beverages
RTD Bottled Cocktails Market
Alcoholic Beverages
Premix Bottled Cocktails Market
Alcoholic Beverages
Alcohol Gummies Market