
 Craft Brewery Equipment Market | 2026-2036
Craft Brewery Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Craft Brewery Equipment Market Insights
German stainless steel fabricators is rebalancing output toward craft-scale brewhouses as macro-brewery orders plateau. GEA Group leverages its heat-exchange engineering heritage to dominate compact wort-cooling skids for urban microbreweries. Alfa Laval anchors European supply through its centrifugal separation technology for yeast recovery and clarification. Paul Mueller Company competes aggressively in North America with custom-built fermentation tanks and regional fabrication proximity.
Craft brewery equipment encompasses vessels, controls, and ancillary systems engineered to convert malted grains into beer through mashing, lautering, boiling, fermentation, and conditioning, typically operating at 3–30 barrel batch scales with 304 or 316 stainless steel construction rated for CIP sanitation cycles. Fermenters command the largest product-type margin pool due to extended lead times and pressure-rated welding requirements. Automated control systems are displacing manual operation in mid-scale breweries as labor costs rise and batch consistency becomes a competitive differentiator. Microbreweries represent the most contested end-user segment, with equipment vendors tailoring financing and footprint options to taproom operators.
The FDA enforces Current Good Manufacturing Practice standards for brewery equipment surface finishes and cleanability, while OSHA mandates confined-space protocols for fermentation tank entry that shape vessel design and access features. The EU Machinery Directive and CE marking requirements govern equipment export eligibility into European microbreweries, creating compliance thresholds for non-European suppliers. Stakeholders must monitor evolving energy-efficiency codes and carbon-footprint disclosure rules that will increasingly influence brewhouse equipment specification and retrofit decisions.
Market Dynamics
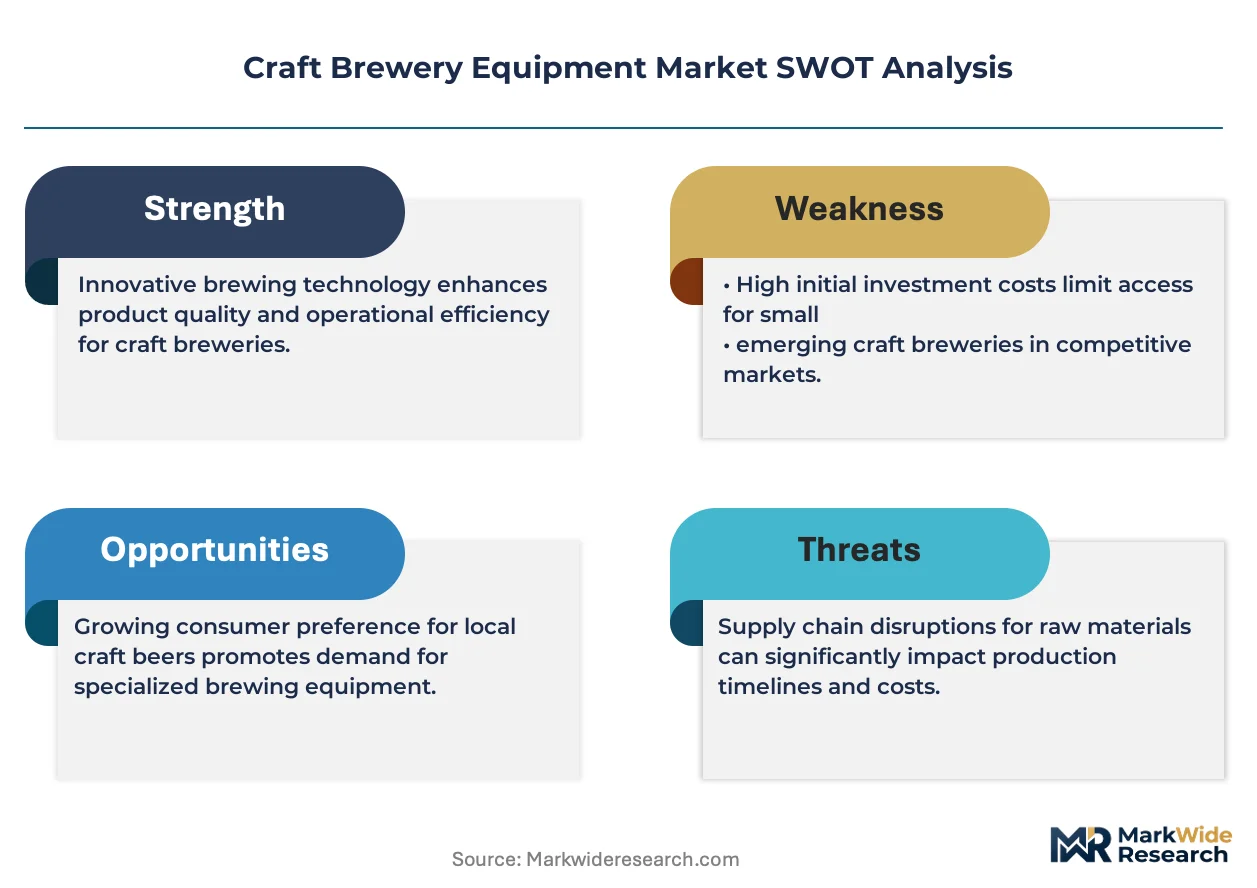
Stainless steel supply concentration in Germany and FDA surface-finish mandates are compressing equipment lead times and elevating compliance costs across craft-scale brewhouse procurement.
Growth Catalysts
- Taproom Localization:Urban microbreweries in the United States are expanding production footprints to serve on-premise consumption, driving demand for compact 3-10 barrel systems with integrated serving tanks.
- EU Machinery Directive:CE marking requirements for pressure-rated fermentation vessels are standardizing export specifications, enabling cross-border equipment trade among European fabricators.
- Heat Recovery Engineering:Wort-cooling skid efficiency gains are reducing energy intensity per batch, making automated brewhouses economically viable for sub-15 barrel operations.
Market Restraints
- 316 Stainless Premium:Molybdenum-alloyed steel price volatility adds 12-18% raw material cost exposure to pressure-rated vessel fabrication.
- Fabrication Concentration:German and Austrian metalworking clusters control 70% of European craft-scale tank supply, creating geographic single-source risk.
- OSHA Confined-Space Protocols:Fermentation tank access feature mandates extend design cycles and limit modular standardization options.
Strategic Opportunities
- India Microbrewery Liberalization:State-level excise reforms in Karnataka and Maharashtra are licensing taproom brewing, opening equipment demand from first-mover operators.
- Carbon Disclosure Mandates:EU CSRD reporting requirements will favor brewhouses with energy-recovery specifications and lifecycle-certified stainless sourcing.
- Mobile Canning Integration:Packaging line convergence with automated filling systems is enabling small-batch breweries to bypass capital-intensive bottling halls.
Industry Challenges
- Pressure-Vessel Welder Scarcity:ASME-certified TIG welding capacity constrains fermenter output expansion at mid-tier fabricators.
- Sanitary Surface Certification Lag:FDA-compliant 3-A finish validation extends equipment delivery timelines by 4-8 weeks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Craft Brewery Equipment Market |
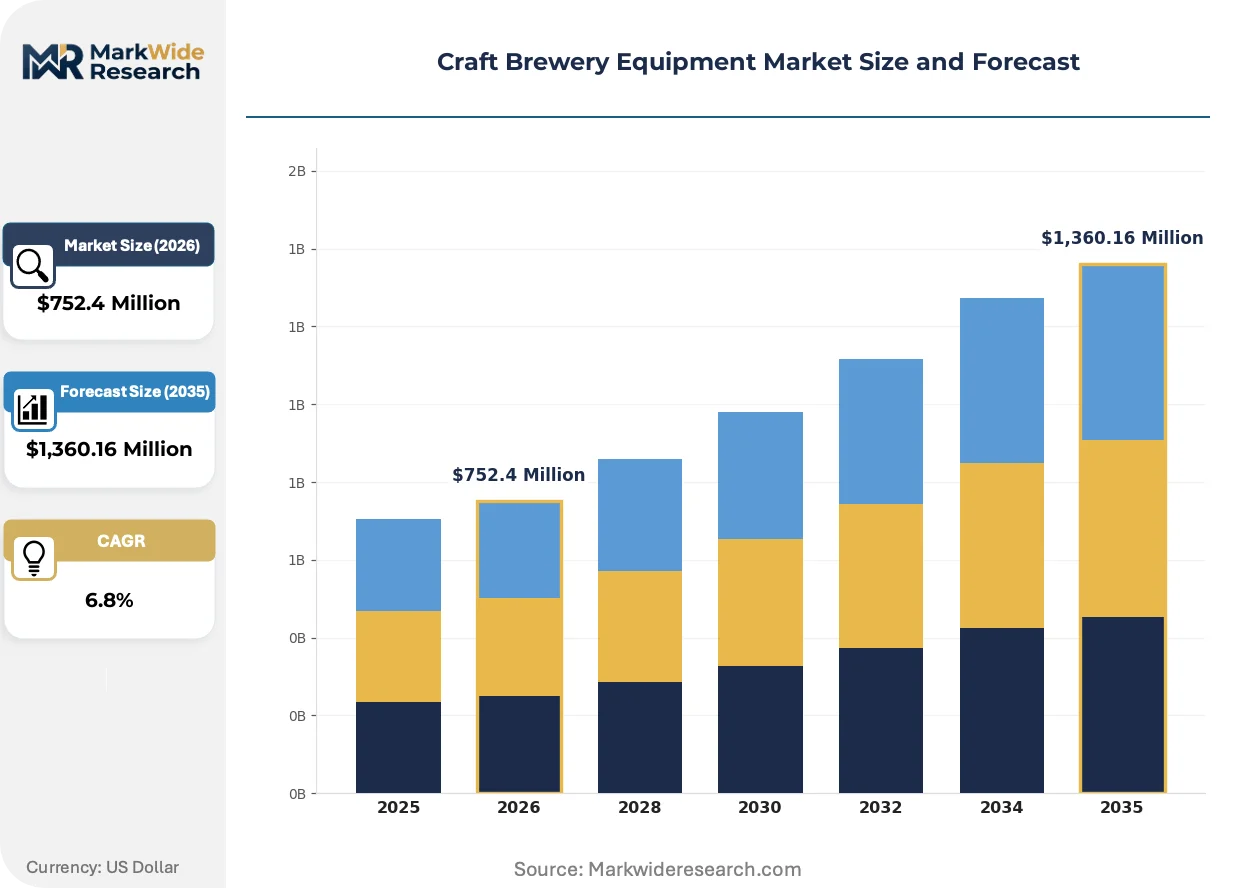
| Market Size in 2026 | $752.4 Million |
| Market Size in 2035 | $1,360.16 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mash Tuns, Fermenters, Kettles, Wort Coolers, Filtration Systems, Packaging Machines Technology: Automated Control, Manual Operation, Hybrid Systems, Temperature Regulation, Pressure Monitoring, Sanitation Equipment Application: Flavor Innovation, Batch Scaling, Quality Improvement, Efficiency Optimization, Experimental Brewing, Specialty Beer Production End User Type: Microbreweries, Brewpubs, Contract Brewers, Independent Breweries, Craft Distilleries, Beverage Startups |
| Companies Covered | Alfa Laval, GEA Group, Krones AG, Paul Mueller Company, Criveller Group, Della Toffola, KASPAR SCHULZ, BrauKon, Portland Kettle Works, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Craft Brewery Equipment Market Trends and Innovations
Digital brewing controls and energy-recovery engineering are compressing the viable scale threshold for automated brewhouse operation, while regulatory disclosure mandates reshape supplier qualification criteria.
Modular skid-mounted brewhouses are absorbing the space constraints of urban real estate by integrating mashing, lautering, and boiling into vertically stacked configurations. Taproom operators in dense metropolitan zones are specifying these systems to maximize production per square meter. The technology is absorbing demand that previously required dedicated warehouse footprints, enabling brewery launches in retail-zoned properties.
REACH chemical safety registration is tightening stainless steel surface treatment documentation requirements for equipment imported into European microbreweries. Suppliers must now disclose passivation chemistry and coating compliance to maintain CE marking eligibility. German fabricators are responding by certifying in-house electropolishing capabilities to preserve market access.
Equipment-as-a-service financing is displacing traditional capex purchase models among entry-level microbrewery founders. Leasing structures bundle fermentation tanks with maintenance and upgrade pathways, reducing initial capital barriers. This model is concentrating in the United States where regional lenders have developed specialized brewing equipment collateral expertise.
Craft Brewery Equipment Market Segmentation
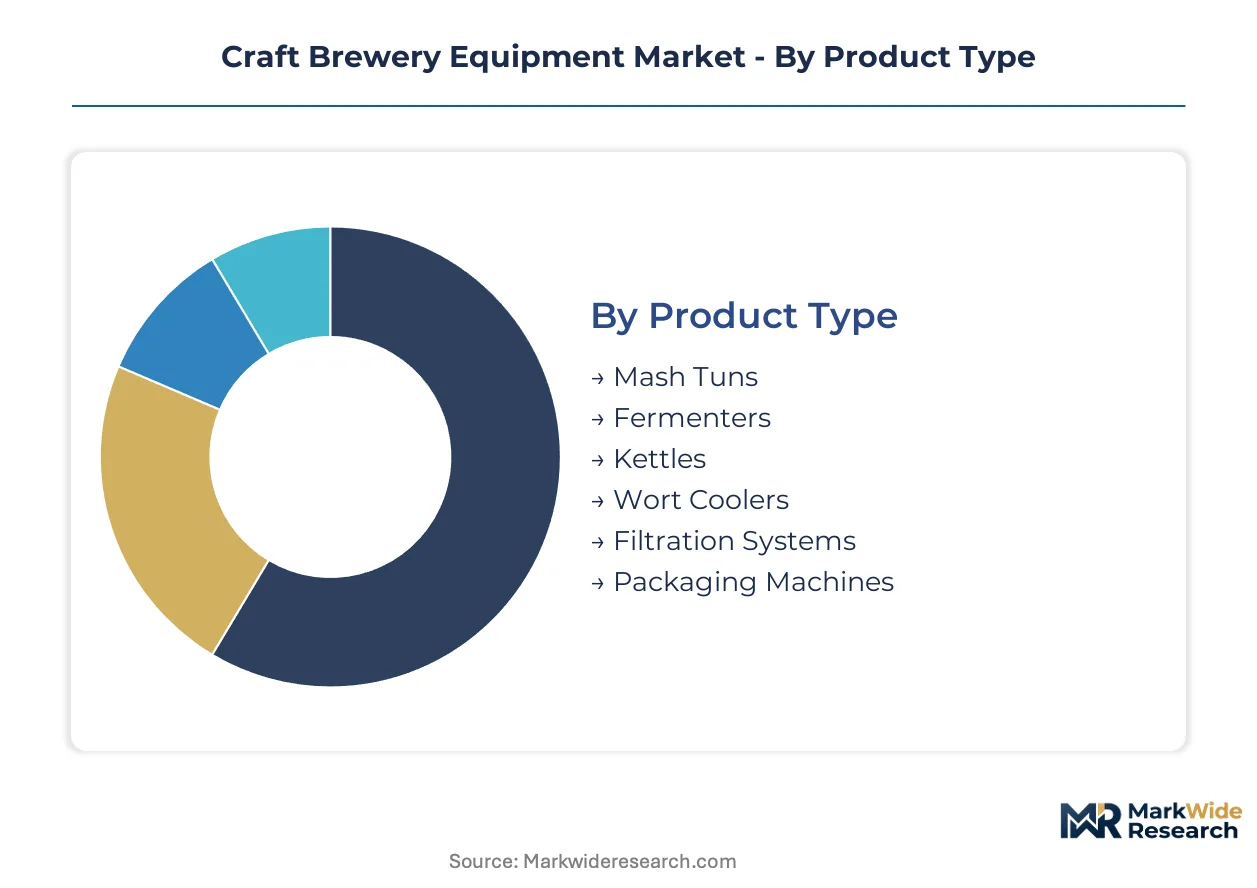
Equipment segmentation in craft brewing reflects divergent capital deployment strategies across production scales. Vendors configure product lines to match the financing constraints and floor-space limitations that separate taproom operators from regional packaging breweries.
Product Type:
Fermenters absorb the largest share of upfront equipment expenditure due to pressure-rated fabrication requirements and extended lead times.
- Fermenters:Cylindrical-conical vessels in 304 or 316 stainless steel with pressure-rated welds and CIP sprayball arrays dominate capital budgets. Demand concentrates in United States microbreweries expanding from 7-barrel to 15-barrel production to supply multiple taprooms. ASME-certified fabrication capacity constraints in North America extend delivery timelines.
- Mash Tuns:Insulated vessels with false bottoms or rakes for grain bed management require precise temperature uniformity. German fabricators supply European craft breweries seeking traditional decoction mashing capability alongside infusion flexibility. Energy recovery integration is becoming standard specification.
- Kettles:Steam-jacketed or direct-fire boiling vessels with whirlpool functionality.
- Wort Coolers:Plate heat exchangers and counterflow systems for rapid post-boil temperature reduction.
- Filtration Systems:Centrifugal separators and membrane units for clarification and yeast recovery.
- Packaging Machines:Counter-pressure fillers, canning lines, and keg washers for finished product distribution.
Most installed capacity flows through Fermenters. Expansion is steepest in Packaging Machines as microbreweries bring distribution in-house.
Technology:
Control sophistication determines labor requirements and batch consistency across production scales.
- Automated Control:PLC-based systems with recipe management, remote monitoring, and integrated data logging command premium pricing. United States mid-scale breweries adopt these systems as labor costs rise and headcount reduction becomes economically justified. ROI calculations now incorporate energy optimization algorithms.
- Temperature Regulation:Glycol-chilled jackets and automated valve arrays maintain fermentation curves within 0.5°C tolerance. European microbreweries prioritize this technology for lager production where thermal stability determines flavor profile. Integration with building management systems is emerging specification.
- Manual Operation:Traditional lever-actuated valves and sight-glass monitoring for entry-level installations.
- Hybrid Systems:Semi-automated configurations blending manual intervention with digital logging.
- Pressure Monitoring:Transducer arrays for fermenter headspace management and carbonation control.
- Sanitation Equipment:CIP skids with caustic and acid cycles for vessel sterilization.
Automated Control commands the highest average selling prices. Temperature Regulation is gaining share fastest among quality-focused operators.
Application:
Functional use cases align equipment specification with brewery business model priorities.
- Batch Scaling:Capacity expansion from pilot to production volumes drives vessel sizing decisions. United States contract brewers require flexible equipment configurations to accommodate multiple client recipes and batch frequencies. Financing structures increasingly accommodate upgrade pathways.
- Flavor Innovation:Experimental brewing applications demand rapid tank turnaround and dedicated sour beer infrastructure. German craft breweries invest in separate fermentation circuits to isolate Brettanomyces and mixed-culture programs from clean beer production. Cross-contamination prevention shapes facility layout.
- Quality Improvement:Consistency and analytical precision for brand reputation protection.
- Efficiency Optimization:Energy and water recovery for operational cost reduction.
- Specialty Beer Production:Barrel-aging infrastructure and adjunct handling systems.
- Experimental Brewing:Small-scale pilot systems for recipe development.
Batch Scaling accounts for the majority of vessel procurement volume. Flavor Innovation is expanding most quickly among differentiated regional players.
End User Type:
Customer archetypes dictate equipment packaging, financing terms, and service intensity.
- Microbreweries:Independent production facilities with taproom or limited distribution focus. United States operators in urban cores specify skid-mounted brewhouses to minimize installation footprint and landlord negotiation complexity. Equipment-as-a-service financing penetration is highest in this segment.
- Brewpubs:Restaurant-integrated brewing operations with aesthetic and noise constraints. German brewpubs favor copper-clad vessels for visual authenticity despite stainless steel construction underneath. Sightline requirements from dining areas influence vessel orientation and piping design.
- Contract Brewers:Third-party production facilities brewing client recipes.
- Independent Breweries:Regional packaging breweries with broad distribution.
- Craft Distilleries:Cross-category producers seeking brewing capability for whiskey wash production.
- Beverage Startups:First-time founders with limited operational experience and constrained capital access.
Microbreweries represent the largest addressable equipment base. Brewpubs are climbing the fastest as foodservice operators add brewing to differentiate hospitality concepts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting craft brewery equipment procurement toward jurisdictions with streamlined pressure-vessel certification pathways, as fabricators seek to bypass bottlenecks in oversaturated compliance regimes.
United States
Urban taproom proliferation in Denver, Portland, and Austin is driving compact brewhouse specifications. OSHA confined-space protocols for fermentation tank access are extending design cycles and limiting modular standardization. Chicago metalworking clusters are absorbing overflow demand as German lead times stretch.
Germany
Traditional brewing heritage intersects with craft experimentation in Bavaria and North Rhine-Westphalia. CE marking requirements under the EU Machinery Directive standardize pressure-rated vessel specifications for cross-border trade. Augsburg and Nuremberg fabricators are rebalancing output toward craft-scale systems as macro-brewery orders plateau.
India
State-level excise reforms in Karnataka and Maharashtra are licensing taproom brewing, opening equipment demand from first-mover operators. FSSAI sanitary standards for beverage production equipment are shaping import specifications. Bangalore microbrewery clusters are driving initial vessel procurement for 3-10 barrel systems.
United Kingdom
London and Manchester microbreweries are expanding production footprints to supply multiple taproom locations. REACH chemical safety registration is tightening stainless steel surface treatment documentation for imported equipment. Midlands fabrication hubs are developing ASME-certified welding capacity to serve domestic demand.
Australia
Melbourne and Sydney craft breweries are retrofitting for energy-recovery specifications ahead of anticipated carbon disclosure mandates. TGA-equivalent pressure equipment safety standards govern fermentation vessel compliance. Victorian stainless steel workshops are capturing regional demand for CIP-sanitation-rated construction.
Craft Brewery Equipment Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue equipment-as-a-service financing and modular skid configurations. The vendor base stratifies across three tiers: multinational engineering conglomerates with heat-exchange heritage, regional metalworking specialists with ASME-certified fabrication, and compact-system innovators serving urban taproom constraints. Dominant competitive moves include geographic proximity strategies for delivery timeline compression and in-house electropolishing certification to preserve CE marking eligibility.
Among European engineering conglomerates, GEA Group and Alfa Laval exemplify archetypes leveraging thermal processing heritage for compact wort-cooling and centrifugal separation applications. Paul Mueller Company anchors North American regional fabrication with custom-built fermentation tank capability. These three occupy positions spanning multinational scale, specialized engineering, and geographic proximity vectors.
| Leading Market Players |
|---|
| Alfa Laval |
| GEA Group |
| Krones AG |
| Paul Mueller Company |
| Criveller Group |
| Della Toffola |
| KASPAR SCHULZ |
| BrauKon |
| Portland Kettle Works |
| Others |
Pricing and Supply Chain Analysis
London Metal Exchange 316 stainless steel price volatility cascades through German and Austrian fabrication clusters into three-tier equipment pricing that separates ASME-certified premium vessels from standard CE-marked configurations and economy-grade manual systems lacking CIP integration.
Pricing Analysis
Distributor margins for fermentation vessels absorb 15-25% of factory gate pricing before regional metalworking specialists apply project-based quoting for custom access configurations. Three-tier pricing structure across premium, standard, and economy levels differentiates by ASME certification tier and in-house electropolishing capability. Cost compression in mid-tier configurations is intensifying because Chicago fabricators are absorbing overflow demand from stretched German lead times. Taproom operators represent the most price-sensitive buyer archetype, while regional packaging breweries prioritize certification grade over unit economics.
Supply Chain Analysis
Dual-sourcing requirements from United States microbreweries mandate qualification of both German and domestic fabrication capacity to mitigate geographic single-source risk. Supply concentrates in Germany, Austria, and emerging United States clusters, drawing from nickel, molybdenum, and specialized TIG welding consumables. Tariff exposure on European-sourced pressure vessels creates structural vulnerability for non-CE-certified suppliers. Distribution runs through direct OEM relationships for large-scale procurement and regional equipment distributors serving fragmented taproom demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where United States fabricators exploit 8-12 week delivery advantages against German lead times, while European suppliers leverage REACH-compliant surface treatment documentation to command premium positioning in disclosure-mandated procurement.
For Market Incumbents: Hedge against Chicago metalworking cluster encroachment by certifying in-house electropolishing capabilities that preserve CE marking eligibility under tightening REACH documentation requirements. Backward integration into captive 316 stainless supply contracts mitigates molybdenum price volatility exposure. Priority capacity allocation should favor automated control system bundling where labor-cost pressures justify premium positioning.
For New Entrants and Emerging Players: Equipment-as-a-service digital-channel routes enable penetration of United States taproom operators constrained by traditional capex financing limitations. White-space targets include Karnataka and Maharashtra microbrewery clusters where state-level excise reforms are licensing first-mover equipment demand. Mobile canning integration partnerships offer the most penetrable go-to-market angle for bypassing capital-intensive bottling hall competition.
For Investors and Strategic Acquirers: Asymmetric upside sits with regional fabricators developing ASME-certified welding capacity to serve domestic United States demand overflow. Long-term viability over the coming decade hinges on energy-recovery engineering integration and lifecycle-certified stainless sourcing capabilities. The signal to watch is carbon disclosure mandate adoption velocity in European procurement specifications.
| Strategic Initiative | Industry Significance |
|---|---|
| In-House Electropolishing Certification | Preservation of CE marking eligibility under tightening REACH surface treatment documentation requirements. |
| Equipment-as-a-Service Financing Launch | Reduction of capital barriers for United States taproom operators through bundled maintenance and upgrade pathways. |
| Energy-Recovery Engineering Integration | Alignment with EU CSRD reporting requirements favoring brewhouses with lifecycle-certified specifications. |
| ASME-Certified Welding Capacity Expansion | Capture of domestic United States demand overflow from constrained German fabrication lead times. |
| Mobile Canning Partnership Development | Enablement of small-batch breweries to bypass capital-intensive bottling hall infrastructure investments. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with brewery operations directors, equipment procurement managers, stainless steel fabrication plant managers, and regulatory compliance officers with secondary validation from FDA 21 CFR Part 110 filings, EU Machinery Directive technical documentation, SEC 10-K disclosures from listed engineering conglomerates, and trade flow data from national customs authorities. Bottom-up vessel shipment tallies triangulate against top-down brewery capacity expansion announcements.
Rate-of-change decomposition separates volume growth from pricing dynamics across the projection horizon, with segmentation modeling across product type, technology tier, application function, and end-user archetype. CAGRs derive from regression analysis against brewery count expansion, regulatory compliance cost indices, and raw material price trajectories. Industry-specific forecast inputs include pressure-vessel welder capacity constraints and equipment-as-a-service financing penetration rates.
The model assumes a particular technology adoption path; alternative pathways for automated control system displacement of manual operation would alter the outlook if labor-cost pressures accelerate faster than projected. Forecasts reflect documented assumptions regarding stainless steel price stability and regulatory harmonization timelines. Deviation in OSHA confined-space protocol enforcement stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Hydrostatic Steam Blancher Market
Food Processing Equipment
Plastic Processing Machinery Market
Food Processing Equipment
Deaeration Machine Market
Food Processing Equipment
Sandwich Preparation Refrigerators Market
Food Processing Equipment
Vacuum Cooling Equipment Market
Food Processing Equipment
Clean in Place Market
Food Processing Equipment
Small Brewery Equipment Market
Food Processing Equipment
Insect Protein Processing Equipment Market
Food Processing Equipment
Global Automatic Mask Production Equipment Market
Food Processing Equipment
Chewing Gum Machine Market
Food Processing Equipment
Automatic Fish Scaling Machine Market
Food Processing Equipment
Global Non-Thermal Pasteurization Market
Food Processing Equipment
Semi-Auto Egg Tart Forming Machine Market
Food Processing Equipment
De-Agglomerating Equipment Market
Food Processing Equipment
Walk-In Refrigerators & Freezers Market
Food Processing Equipment
Reach-In Freezers Market