
 Alcoholic Flavors Market | 2026-2036
Alcoholic Flavors Market Size, Share, and Industry Trends Forecast 2026-2036
Alcoholic Flavors Market Outlook
Clean-label extraction technology is narrowing the gap between synthetic and natural flavor authenticity in alcoholic applications. Givaudan leverages advanced biotech fermentation platforms to produce consistent botanical extracts for spirits makers. Kerry Group anchors its position through backward integration into raw herb and spice sourcing across multiple growing regions. Symrise AG differentiates via proprietary encapsulation systems that protect volatile flavor compounds during high-proof alcohol blending.
Alcoholic flavors comprise concentrated taste and aroma compounds formulated to enhance or modify the sensory profile of distilled spirits, liqueurs, wines, and beers, typically delivered at usage rates between 0.01% and 0.5% by volume depending on desired intensity and base alcohol character. These formulations serve primarily to standardize batch-to-batch consistency, enable seasonal product line extensions, and reduce dependency on agricultural harvest variability for flavor supply. Spirits flavors lead current value generation due to premiumization trends in whiskey and vodka segments, while fruity profiles across liqueurs and ready-to-drink cocktails represent the fastest-expanding flavor category as younger consumers gravitate toward accessible, mixology-inspired taste experiences. Herbal and spicy variants command elevated margins in craft and artisanal channels where provenance storytelling supports pricing power.
The FDA governs flavor ingredient safety through Food Additive Regulations and GRAS determinations, while the EU enforces stricter labeling via EFSA flavoring substance evaluations and Spirits Regulation geographic indication protections. Compliance divergence between these frameworks forces multinational flavor houses to maintain dual formulation portfolios, raising R&D overhead but also creating technical barriers for smaller competitors. Stakeholders must monitor evolving clean-label definitions and alcohol-adjacent flavor taxonomies, as regulatory reclassification could abruptly reshape which compounds remain commercially viable across key markets.
Market Dynamics
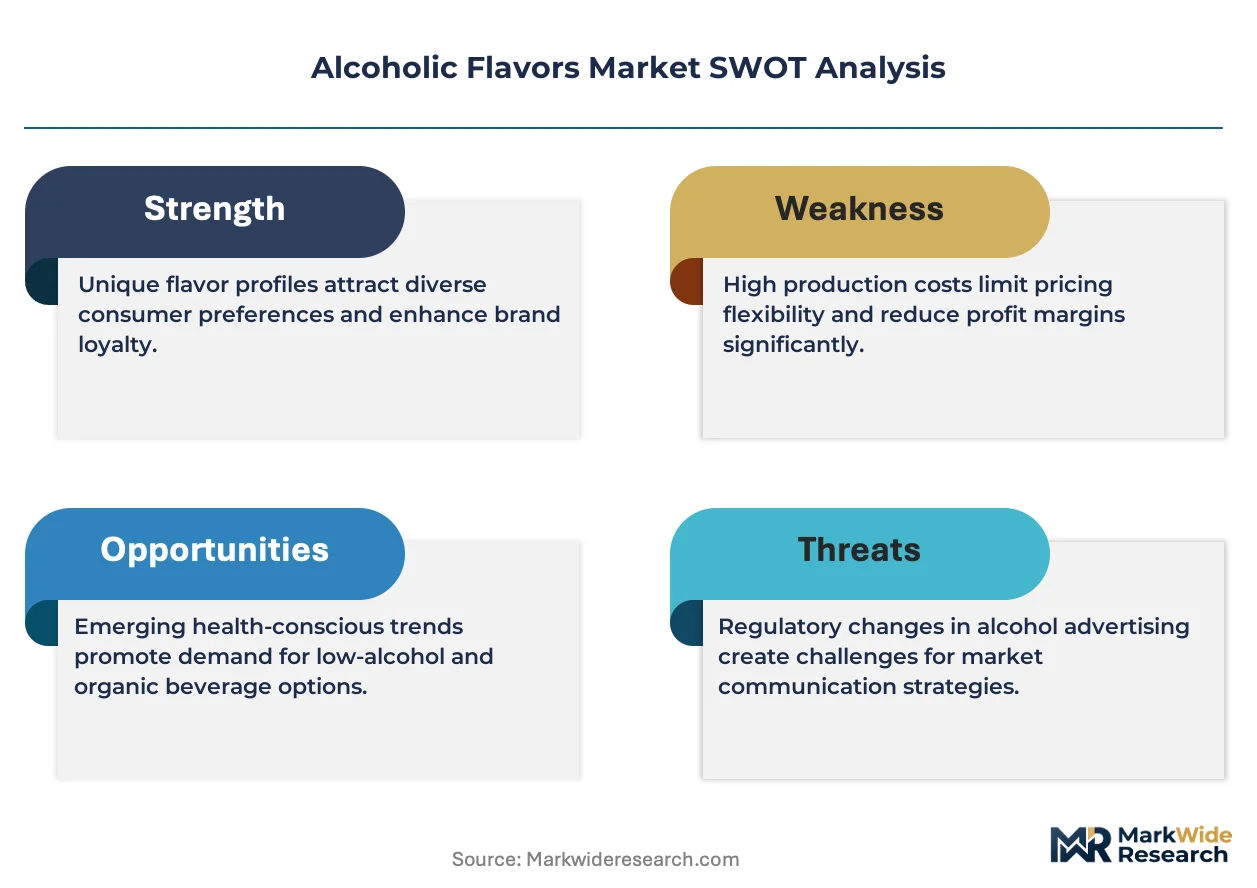
The alcoholic flavors sector faces a structural squeeze between tightening EFSA flavoring substance evaluations and craft distilleries' insistence on authentic botanical sourcing. This tension compresses formulation flexibility while elevating R&D overhead for compliance across dual regulatory portfolios.
Growth Catalysts
- Clean-label extraction platforms:Biotech fermentation systems now yield consistent botanical extracts without agricultural harvest volatility. Spirits makers in Germany's Bavaria region leverage these to modernize heritage formulations.
- EU Spirits Regulation geographic indications:Protected designation frameworks create premium pricing corridors for provenance-authenticated flavor profiles. Traditional distilleries exploit this to defend margin position against synthetic alternatives.
- Ready-to-drink cocktail expansion:Fruity flavor demand concentrates in younger consumer cohorts seeking accessible mixology experiences. Liqueur manufacturers respond with accelerated seasonal line extensions.
Market Restraints
- Raw material concentration risk:Premium herb and spice sourcing clusters in specific growing regions vulnerable to climate disruption. Kerry Group's backward integration into multiple geographies reflects this structural vulnerability.
- GRAS determination timelines:FDA safety evaluations for novel flavor compounds extend 18-36 months, freezing formulation pipelines. This regulatory friction particularly constrains innovation in high-proof alcohol applications.
- Natural-synthetic cost asymmetry:Authentic botanical extracts command 3-5x ingredient cost premiums over synthetic equivalents. Standard spirits categories absorb this poorly, compressing adoption rates outside premium tiers.
Strategic Opportunities
- Encapsulation technology convergence:Symrise AG's proprietary systems protecting volatile compounds during high-proof blending represent transferable IP. Convergence with precision fermentation unlocks entirely new flavor stability thresholds.
- Direct-to-distillery channels:Bypassing traditional distribution layers, flavor houses now embed technical service teams inside craft brewery and distillery operations. This channel innovation captures lifetime value through formulation partnership.
- US FDA labeling clarity initiatives:Anticipated guidance on alcohol-adjacent flavor taxonomies may reclassify certain compounds favorably. Early positioning around clean-label definitions secures regulatory tailwind advantage.
Industry Challenges
- Flavor chemist scarcity:Specialized expertise bridging sensory science, regulatory compliance, and alcohol chemistry remains concentrated among retiring practitioners. Training pipelines fail to replenish this talent gap.
- Dual-formulation inventory complexity:Maintaining separate compound portfolios for FDA and EFSA compliance strains quality systems and working capital. Integration complexity escalates with each regulatory divergence.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alcoholic Flavors Market |
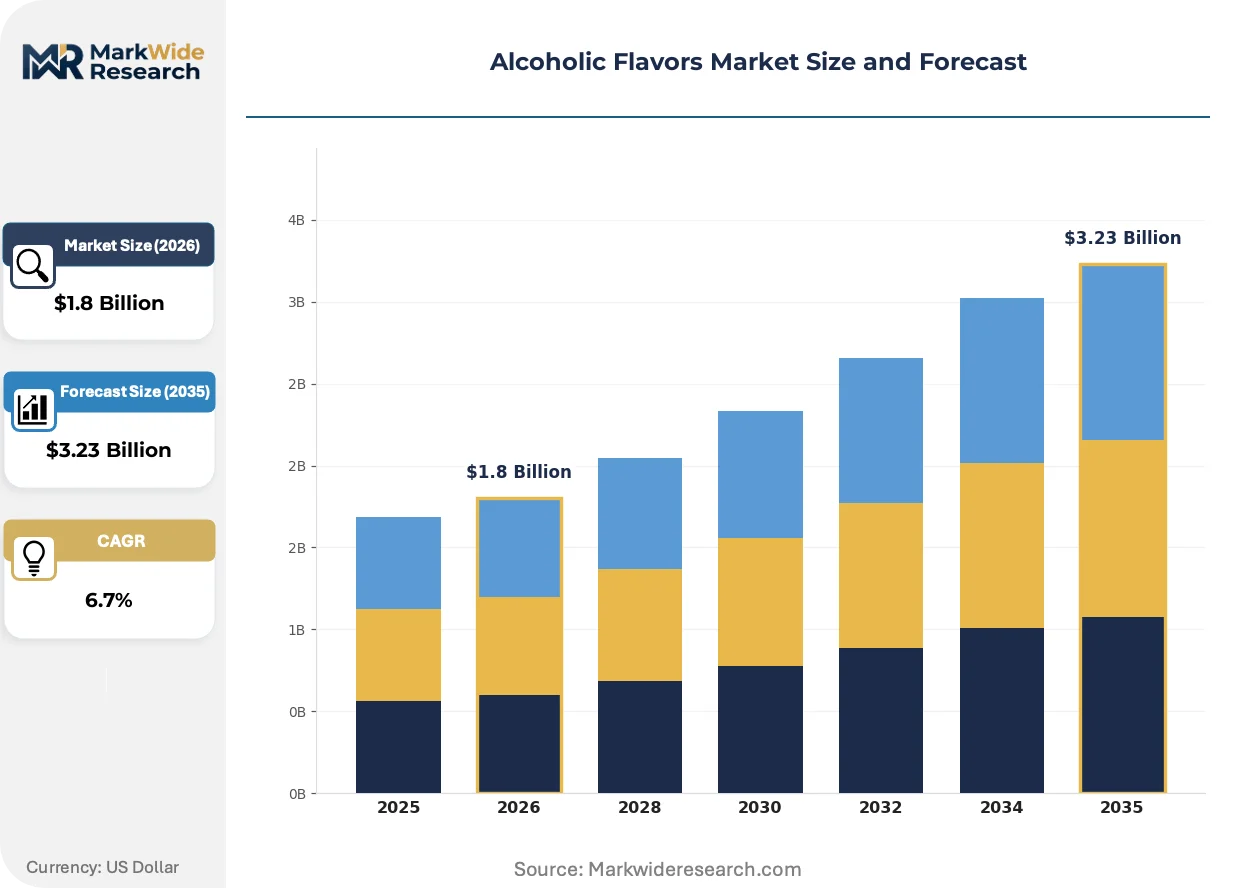
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spirits, Liqueurs, Wine, Beer Flavor Profile: Fruity, Herbal, Spicy, Smoky End User: Bars, Restaurants, Retailers, Breweries Packaging Type: Bottles, Cans, Kegs, Tetra Packs |
| Companies Covered | Givaudan, Kerry Group, International Flavors & Fragrances IFF, Sensient Technologies, Firmenich, Symrise AG, Dohler, Mane SA, T. Hasegawa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alcoholic Flavors Market Strategic Shifts
Biotechnology and precision fermentation are collapsing the authenticity gap between synthetic efficiency and natural provenance. This shift reconfigures competitive advantage around technical capability rather than agricultural access.
Precision fermentation platforms now manufacture rare terpenes and esters previously extractable only from specific botanical harvests. Mid-sized craft distilleries in North America adopt these at accelerating pace as batch consistency demands intensify. The technology is rendering obsolete traditional supply chains dependent on seasonal agricultural procurement.
EFSA's revised flavoring substance evaluation protocols are tightening purity thresholds for botanical extracts entering EU spirits applications. This regulatory compression forces reformulation of legacy products and elevates documentation burdens across the supply base. Premium whiskey and vodka segments absorb compliance costs most readily through pricing power.
Buyer concentration among mega-distilleries is consolidating procurement authority and compressing supplier rosters. Smaller flavor houses face exclusion from approved vendor lists without dedicated technical service infrastructure. This pattern concentrates most visibly in US and German markets where distillery consolidation has advanced furthest.
Alcoholic Flavors Market Segmentation
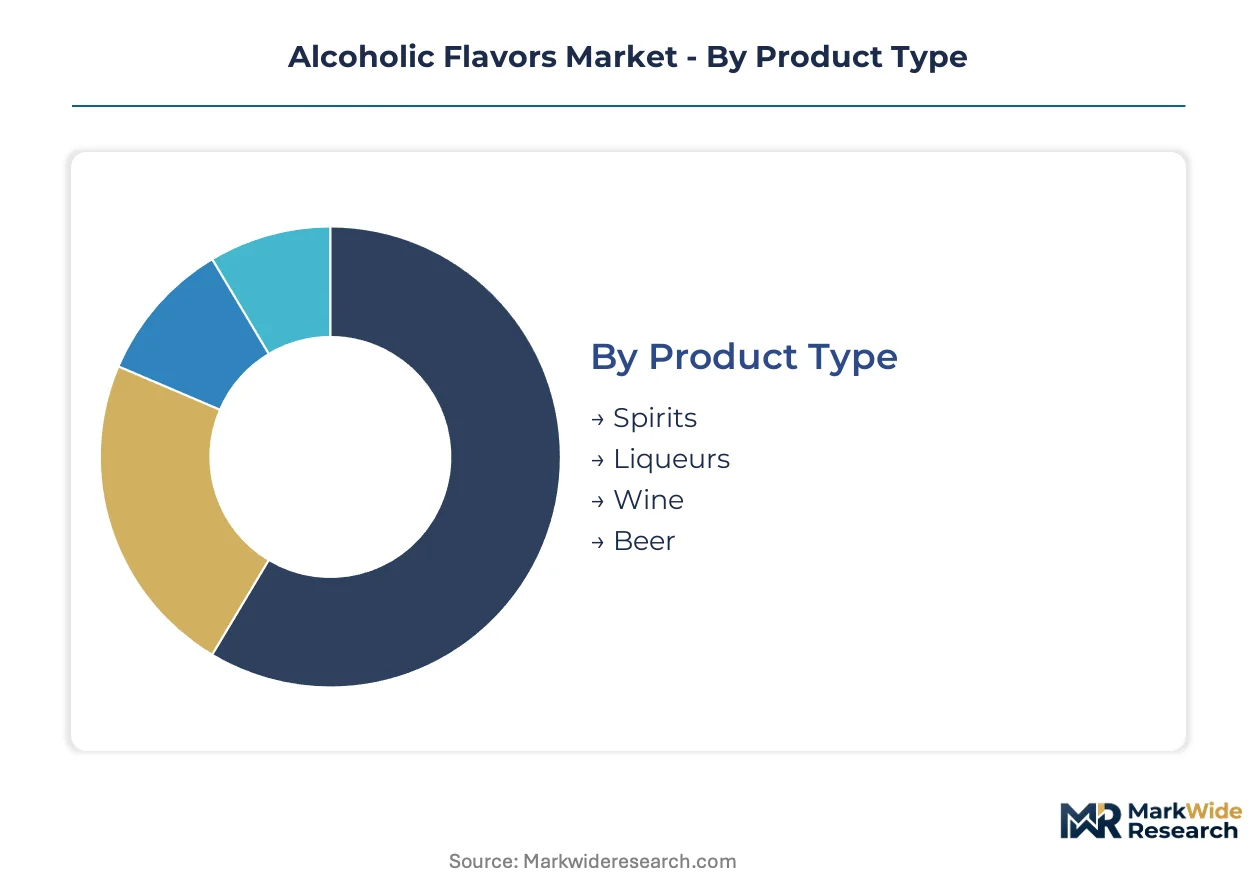
Alcoholic flavor formulation varies sharply across end-use applications, with spirits demanding high-proof stability while beer prioritizes cost-efficient batch scaling. Segmentation reveals how technical requirements and channel economics partition the addressable opportunity.
Product Type:
Product type maps directly to alcohol strength thresholds and margin structures, from premium whiskey to mass-market lager.
- Spirits:High-proof formulations require specialized encapsulation to protect volatile compounds during 40%+ ABV blending. Demand concentrates in Germany's Bavaria region where heritage distilleries modernize production while preserving geographic indication protections under EU Spirits Regulation.
- Liqueurs:Lower alcohol bases accommodate broader flavor palettes, particularly fruit-forward profiles targeting younger consumers in ready-to-drink cocktail formats. This segment absorbs seasonal line extensions most readily.
- Wine:Flavor interventions focus on oak-derived notes and fermentation enhancement rather than overt additive profiles, constrained by winemaking tradition and labeling sensitivities.
- Beer:Craft breweries across the United States deploy hop extracts and fruit essences for rotating tap offerings, though cost pressure limits adoption outside premium positioning.
Established volume favors Beer; emerging adoption favors Spirits.
Flavor Profile:
Flavor profile selection traces consumer demographic shifts and channel premiumization trajectories.
- Fruity:Citrus, berry, and tropical formulations dominate liqueur and RTD applications, with demand accelerating among 21-34 age cohorts seeking accessible entry points to mixology. EFSA's tightened botanical extract purity thresholds elevate documentation burdens for natural fruit sourcing.
- Herbal:Botanical complexity commands margin premiums in craft gin and amaro segments where provenance storytelling supports pricing power. Traditional European distilleries leverage geographic indication frameworks to defend position against synthetic alternatives.
- Spicy:Pepper, ginger, and cinnamon variants concentrate in winter seasonal releases and artisanal whiskey expressions, with supply chains vulnerable to climate disruption in specific growing regions.
- Smoky:Peat-derived and wood-smoke profiles remain niche outside Scotch whiskey and mezcal adjacencies, constrained by limited supplier expertise and high raw material costs.
Margin concentration sits with Herbal; volume expansion concentrates in Fruity.
End User:
End user channel determines formulation batch size, technical service intensity, and price realization.
- Bars:On-premise mixology programs demand rapid flavor prototyping and small-batch flexibility, with technical service teams embedding directly in high-volume urban operations.
- Restaurants:Menu-integrated cocktail programs prioritize consistency and supply security over innovation velocity, favoring established flavor house relationships.
- Retailers:Private-label spirits and RTD formulations for grocery and liquor chains concentrate procurement authority, compressing supplier rosters to those with scale documentation.
- Breweries:Craft beer producers in North America represent fragmented demand with high service overhead, though direct-to-distillery channel innovations capture lifetime formulation partnerships.
Procurement consolidation favors Retailers; technical partnership value concentrates in Bars.
Packaging Type:
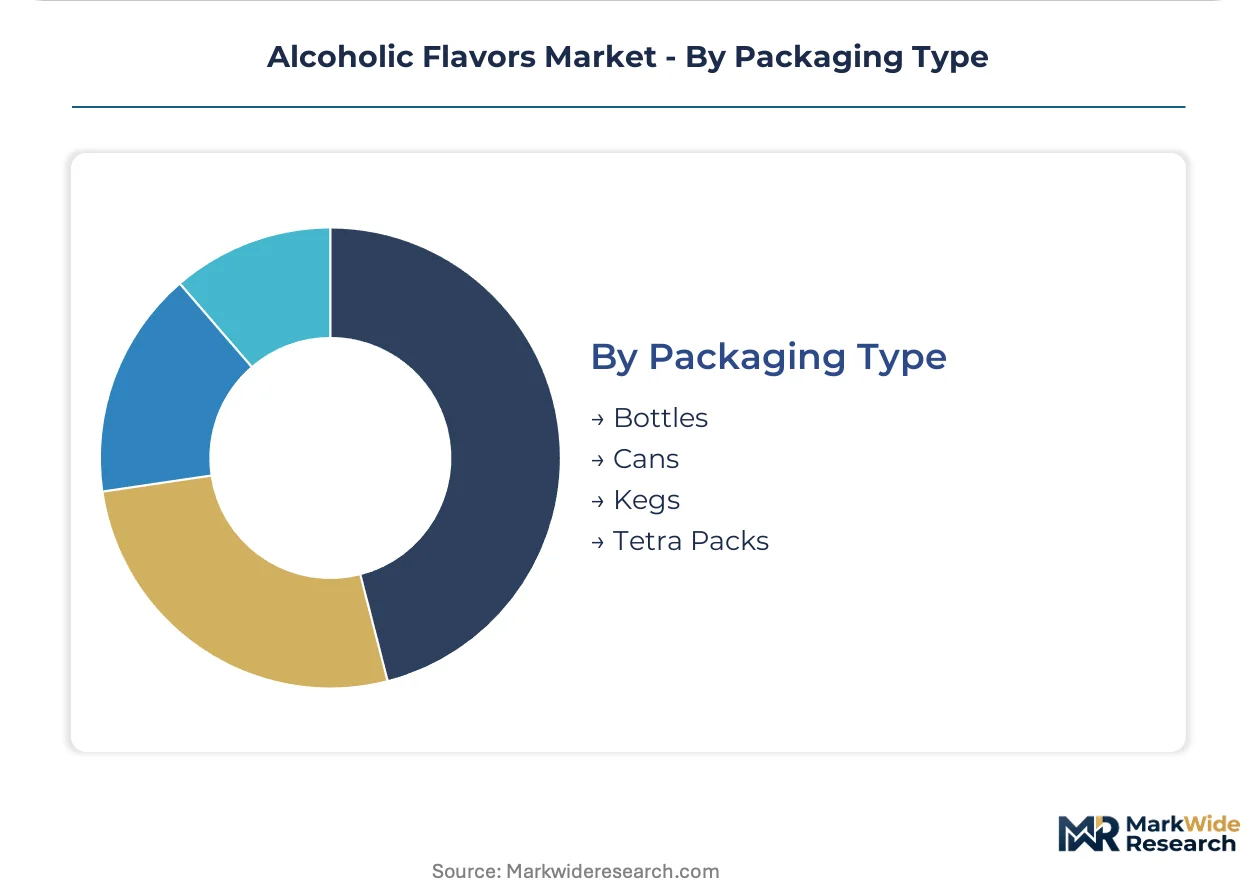
Packaging format dictates flavor stability requirements, shelf-life specifications, and logistics economics.
- Bottles:Glass packaging dominates premium spirits and wine applications, with oxygen barrier properties supporting extended flavor integrity for aged products.
- Cans:Aluminum formats for RTD cocktails and flavored beers require flavor systems compatible with high-speed filling lines and pasteurization protocols.
- Kegs:On-premise draft systems for flavored beers and ciders demand microbial stability and post-mix dilution compatibility.
- Tetra Packs:Aseptic cartons for wine and low-alcohol beverages prioritize cost efficiency and lightweight logistics, constraining flavor loadings to lower-intensity profiles.
Premium positioning favors Bottles; format innovation concentrates in Cans.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision-distilled botanical extracts to US craft distilleries and Japanese premium spirits houses, anchoring the transatlantic flavor trade corridor that supplies high-proof stability formulations.
United States
Craft breweries across Oregon and Colorado drive hop extract innovation for rotating tap portfolios. FDA GRAS determinations for novel terpene compounds extend formulation timelines but preserve safety thresholds. The Pacific Northwest cluster concentrates precision fermentation facilities serving West Coast distilleries.
Germany
Bavarian heritage distilleries modernize production while preserving EU Spirits Regulation geographic indications. EFSA tightened botanical extract purity thresholds elevate documentation burdens for traditional herb sourcing. The Munich-Stuttgart corridor hosts backward-integrated spice processors supplying premium whiskey makers.
Japan
Premium shochu and whisky segments absorb high-margin encapsulated flavor systems from domestic biotech suppliers. METI standards for food additive safety govern import approvals for European botanical extracts. The Kansai region concentrates artisanal distilleries adopting precision fermentation for batch consistency.
United Kingdom
Gin revival drives demand for complex juniper-herbal formulations across London and Scottish craft producers. Post-Brexit divergence from EU flavoring substance evaluations forces dual-formulation inventory maintenance. The Scottish Highlands cluster specializes in peat-smoke flavor profiles for export markets.
France
Cognac and liqueur houses in Charente prioritize oak-derived and fruit-forward flavor interventions for aged spirits. ANSM enforces strict additive labeling for AOC-protected appellations. The Bordeaux-Toulouse axis concentrates grape-derived extract processors serving heritage brand portfolios.
Alcoholic Flavors Market Competitive Environment
On the supply side, the industry is consolidating around technical service capabilities that embed flavor chemists directly inside distillery operations. Tiered competitive positioning separates global houses with dual-formulation portfolios from regional specialists focused on single-regulatory compliance. Two strategic archetypes dominate: precision fermentation platform operators and backward-integrated botanical sourcing networks. M&A activity concentrates on encapsulation technology acquisitions and captive herb farm purchases.
Among Swiss-origin flavor houses, Givaudan exemplifies the biotech fermentation archetype through advanced platform investments. Kerry Group anchors the backward-integration model with multi-continent raw material control. Symrise AG occupies the encapsulation specialist tier with proprietary high-proof stability systems. These three represent divergent competitive vectors within a market forcing R&D overhead escalation.
| Leading Market Players |
|---|
| Givaudan |
| Kerry Group |
| International Flavors & Fragrances IFF |
| Sensient Technologies |
| Firmenich |
| Symrise AG |
| Dohler |
| Mane SA |
| T. Hasegawa |
| Others |
Value Chain & Pricing Dynamics
Munich-Stuttgart corridor processors anchor European botanical extract supply, with their backward-integrated spice operations translating agricultural control into pricing leverage over premium whiskey makers. This geographic concentration of heritage processing infrastructure creates tiered cost structures that downstream distilleries absorb through product positioning rather than formulation compromise.
Pricing Analysis
Next-generation precision fermentation platforms command 40-60% cost premiums over conventional solvent extraction, while legacy synthetic formulations face downward pressure from clean-label substitution. Three-tier pricing structure across premium, standard, and economy levels differentiates by botanical authenticity grade and EFSA documentation depth. Cost compression in standard spirits tiers intensifies because mass-market brands cannot pass ingredient premiums to price-sensitive consumers. Craft distilleries exhibit lowest price sensitivity, absorbing encapsulation surcharges for high-proof stability.
Supply Chain Analysis
Contract manufacturing concentrates among Bavarian heritage processors and Pacific Northwest precision fermentation facilities, with Kerry Group and Givaudan operating captive production networks. Raw material flows draw from Madagascar vanilla, Indonesian cassia, and Indian cardamom growing regions. Single-source vulnerability in climate-stressed spice origins threatens batch consistency for provenance-authenticated formulations. Distribution runs through direct-to-distillery technical service teams rather than traditional ingredient brokers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in cyclical recovery as craft spirits premiumization resumes following post-pandemic inventory destocking. Distillery capital expenditure cycles and seasonal line extension velocity provide the demand pulse.
For Market Incumbents: Harden formulation portfolios against EFSA purity threshold escalation through captive herb farm acquisitions in multiple growing regions. Consolidate technical service teams inside top-20 distillery accounts to lock out precision fermentation challengers. Biotech platform entrants threaten encapsulation IP advantages; patent thickets around high-proof stability systems provide defensive moats. For New Entrants and Emerging Players: Southeast Asian craft distilleries present underpenetrated demand for fruit-forward RTD flavor systems, with local regulatory frameworks less burdensome than EU compliance. Target canned cocktail producers seeking pasteurization-compatible encapsulation without legacy supplier minimums. Go-to-market through co-manufacturing partnerships with regional beverage packagers bypasses direct distillery selling infrastructure gaps. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because flavor chemist scarcity and dual-formulation inventory complexity favor scaled technical service platforms over fragmented specialists. Acquisition targets include regional encapsulation technology holders and multi-origin herb processors with EFSA documentation libraries. Watch for FDA guidance clarity on alcohol-adjacent flavor taxonomies as regulatory reclassification catalyst.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Platform Investment | Givaudan's biotech systems collapse natural-synthetic cost asymmetry for rare terpene production. |
| Captive Herb Farm Acquisition | Kerry Group's Madagascar and Kerala sourcing estates secure supply against climate volatility. |
| Direct-to-Distillery Channel Buildout | Symrise AG embeds technical teams inside Bavarian heritage operations for lifetime formulation partnerships. |
| Encapsulation IP Licensing | Proprietary high-proof stability systems generate royalty streams from mid-sized craft distilleries. |
| EFSA Compliance Documentation Library | Pre-validated botanical extract portfolios accelerate EU market entry for spirits makers. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across this study's primary research phase, including flavor chemists at global houses, procurement directors at mega-distilleries, craft brewery founders, and regulatory affairs specialists navigating FDA GRAS and EFSA evaluations. Secondary validation drew from FDA Food Additive Regulations, EFSA flavoring substance databases, EU Spirits Regulation geographic indication registries, and customs trade flows for botanical raw materials. Bottom-up volume modeling triangulated against top-down value estimates from disclosed segment revenues.
Calibration against historical price realizations and documented formulation adoption curves anchored projections across the analysis window. Segmentation dimensions included product type (spirits, liqueurs, wine, beer), flavor profile (fruity, herbal, spicy, smoky), end-user channel (bars, restaurants, retailers, breweries), and packaging format (bottles, cans, kegs, Tetra Packs). CAGRs derived from fitted growth curves applied to base-year volume estimates, with cross-checks against distillery capacity expansion announcements and seasonal line extension frequencies.
Practitioners should monitor EFSA flavoring substance reclassification proceedings and FDA labeling guidance timelines for early signals of regulatory compression or relief. Forecasts reflect assumptions regarding craft spirits premiumization continuity and precision fermentation cost reduction trajectories. Quarterly review of botanical commodity price indices and geographic indication enforcement actions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Beer Fermenter Market
Alcoholic Beverages
Cocktail Market
Alcoholic Beverages
Turkey Tequila Market
Alcoholic Beverages
Isoamyl Alcohol Market
Alcoholic Beverages
Hip Flask Market
Alcoholic Beverages
Coffee Beer Market
Alcoholic Beverages
Specialty Beer Market
Alcoholic Beverages
East Africa Alcoholic Beverages Market
Alcoholic Beverages
Tonic Wine Market
Alcoholic Beverages
Middle East and Africa Kegs Market
Alcoholic Beverages
Canada Alcohol E-Commerce Market
Alcoholic Beverages
France Alcohol E-Commerce Market
Alcoholic Beverages
Bright Beer Tank Market
Alcoholic Beverages
Sake and Plum Wine Market
Alcoholic Beverages
Wine Aerator Market
Alcoholic Beverages
N-Hexyl Alcohol Market