
 Europe Trailer Axle Market | 2026-2036
Europe Trailer Axle Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Trailer Axle Market Analytics
Skilled welding and metallurgical engineering talent is rotating toward automated axle manufacturing hubs in Germany and Poland, tightening labor availability for smaller Czech and Romanian suppliers. SAF-Holland S.A. leverages its integrated forging and machining operations to control quality across European distribution networks. BPW Bergische Achsen KG anchors its position through deep backward integration into heat-treated axle beams. DexKo Global Inc. competes by sustaining dual-source manufacturing across German and Spanish plants.
A trailer axle is a load-bearing shaft assembly that transmits vehicle weight to wheels via hubs, bearings, and suspension mounts, typically manufactured from normalized SAE 1541 steel with induction-hardened bearing journals rated for cyclic fatigue exceeding 500,000 load cycles. Its primary commercial purpose is to distribute cargo mass safely across road surfaces while maintaining regulatory compliance for gross vehicle weight limits. Tandem axle configurations lead fleet procurement volumes across flatbed and refrigerated trailer categories, reflecting their optimal balance of payload capacity and toll-class efficiency on EU road charging networks. Heavy-duty weight capacity ratings command premium positioning in tanker and lowboy segments serving construction and bulk liquid transport, where axle fatigue life directly determines total cost of ownership.
The EU Green Deal and F-Gas Regulation reshape refrigeration trailer demand, indirectly steering axle specification toward higher load ratings for thermal-system-equipped platforms. ECHA REACH compliance and CE marking requirements govern steel alloy composition and surface coating chemistry, filtering non-compliant Asian suppliers from European procurement channels. Germany's KBA enforces axle fatigue testing protocols that exceed baseline UNECE standards, creating a de facto technical barrier for entrants lacking accredited laboratory partnerships. Fleet operators and component suppliers must monitor the EU AI Act's impending classification of predictive maintenance systems, as algorithm-enabled axle health monitoring crosses from voluntary fleet optimization toward regulated safety equipment.
Market Dynamics
EU Green Deal mandates and F-Gas Regulation compliance are redirecting refrigerated trailer procurement toward higher axle load ratings, compressing specification cycles and concentrating supplier qualification around integrated thermal-platform capabilities.
Growth Catalysts
- Pharmaceutical cold-chain expansion:Germany and Poland logistics operators are scaling refrigerated fleets to meet EU Good Distribution Practice temperature-control mandates for biologics distribution.
- EU AI Act trajectory:Predictive maintenance algorithm classification is shifting from voluntary fleet optimization toward regulated safety equipment, creating certified-system demand.
- Timber transport intensity:Nordic forestry corridors require heavy-duty axle ratings that exceed standard flatbed specifications, pulling specialized capacity into the region.
Market Restraints
- SAE 1541 steel alloy compliance:ECHA REACH restrictions on surface coating chemistry filter non-compliant Asian forging suppliers from European procurement channels.
- Metallurgical labor migration:Skilled welding talent is rotating toward automated manufacturing hubs in Germany and Poland, constraining Czech and Romanian supplier output.
- KBA fatigue testing divergence:Germany's axle fatigue protocols exceed baseline UNECE standards, creating accredited-laboratory barriers for unqualified entrants.
Strategic Opportunities
- Alpine construction corridor specialization:Lowboy and tanker segments serving Swiss and Austrian infrastructure projects command premium positioning for extreme-duty ratings.
- Dual-source manufacturing consolidation:Spanish and German plant networks offer geographic redundancy that single-source competitors cannot replicate.
- CE marking automation:Digital conformity assessment pathways are compressing certification timelines for heat-treated axle beam suppliers.
Industry Challenges
- Induction-hardening skill scarcity:Bearing journal heat-treatment expertise concentrates in legacy forging operations, constraining new production line commissioning.
- Legacy fleet integration friction:Algorithm-enabled health monitoring systems require retrofit compatibility with 500,000-cycle-rated axle architectures from prior decades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Trailer Axle Market |
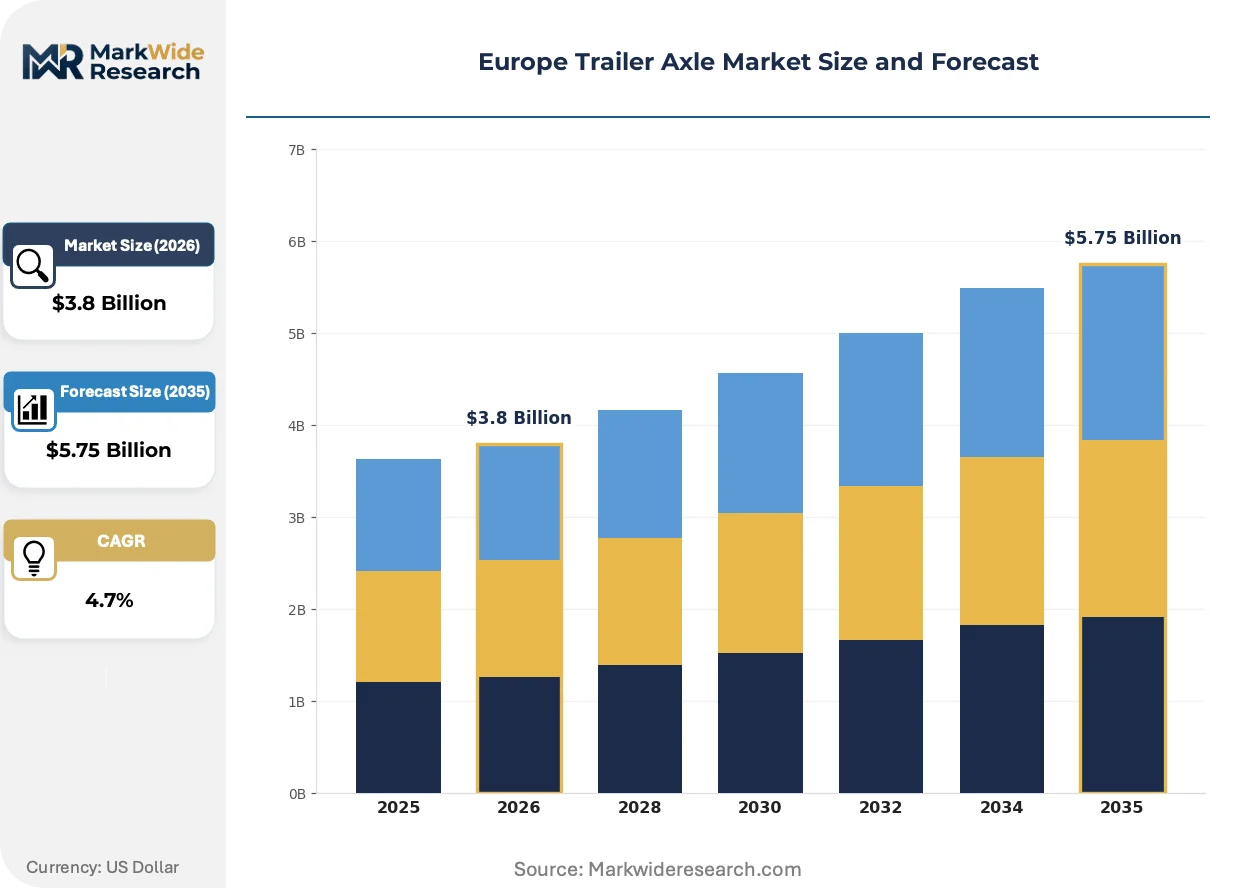
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Axle Type: Single Axle, Tandem Axle, Tri-Axle, Multi-Axle Trailer Type: Flatbed Trailers, Lowboy Trailers, Refrigerated Trailers, Tanker Trailers End User: Logistics Companies, Construction Firms, Agricultural Enterprises, Freight Carriers Weight Capacity: Lightweight, Medium Duty, Heavy Duty, Super Heavy Duty |
| Companies Covered | SAF-Holland S.A., DexKo Global Inc., Schmitz Cargobull AG, Haldex AB, Al-Ko Kober SE, BPW Bergische Achsen KG, Meritor Inc., ZF Friedrichshafen AG, JOST Werke AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Trailer Axle Market Evolving Landscape
Automation in forging and machining operations is compressing quality variance while predictive axle monitoring crosses from aftermarket add-on toward embedded safety architecture. Three developments are restructuring competitive positioning.
Induction-hardened bearing journal production is decomposing traditional batch-heat-treatment workflows into continuous-process manufacturing. German forging hubs are adopting this technology fastest, enabling real-time hardness profiling that reduces scrap rates and compresses lead times for normalized SAE 1541 supply.
F-Gas Regulation phase-down schedules are forcing refrigerated trailer OEMs to specify axles with 10-15% higher static load ratings to accommodate heavier thermal-system platforms. This regulatory pressure concentrates in German and Benelux pharmaceutical distribution fleets, where compliance deadlines are tightest.
Fleet procurement committees are consolidating axle supplier panels from multi-source configurations toward dual-qualified partnerships with integrated forging-through-distribution capabilities. Nordic timber operators and Alpine construction haulers are driving this concentration, prioritizing fatigue-life guarantees over unit cost minimization in total cost of ownership calculations.
Europe Trailer Axle Market Segmentation
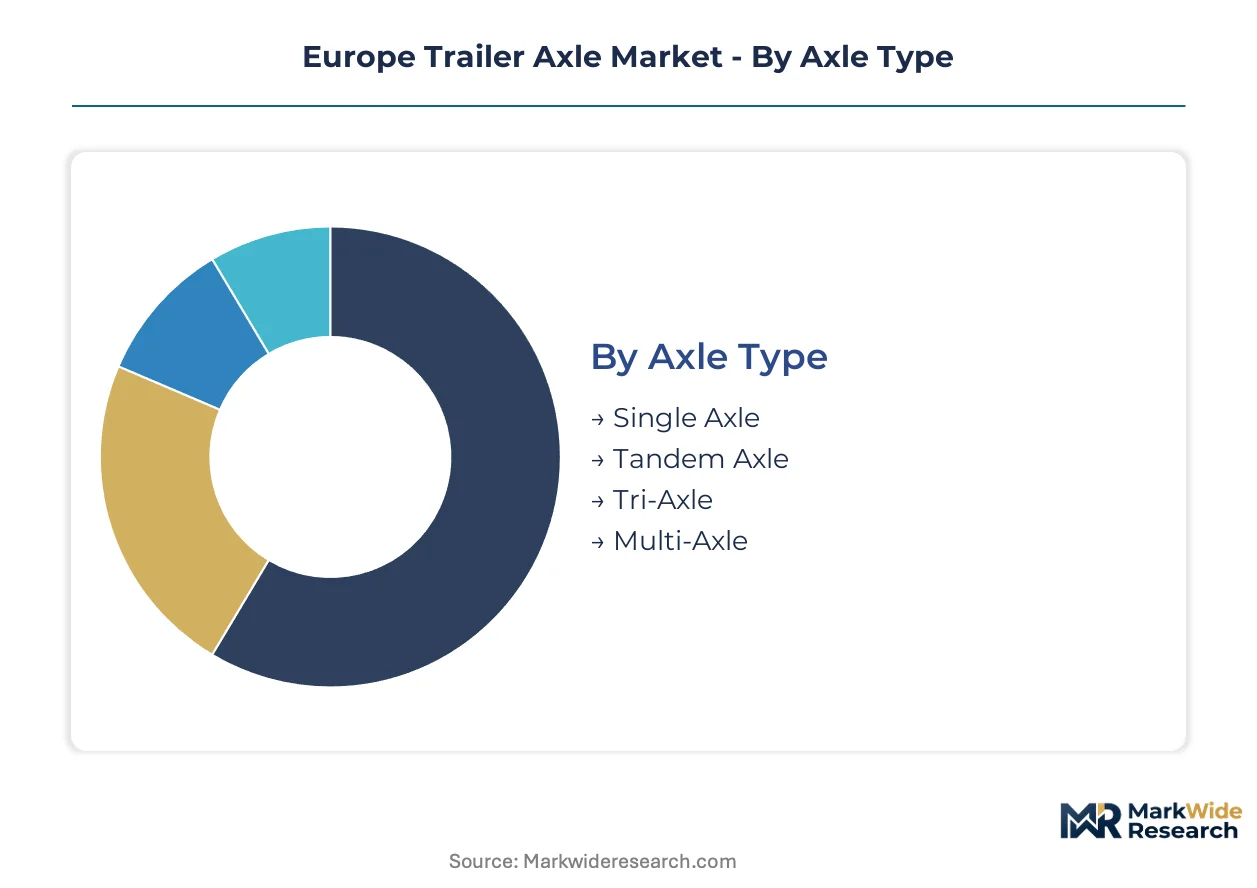
Trailer axle procurement across Europe fragments across technical specifications, trailer configurations, and operational duty cycles. Fleet operators calibrate axle selection against payload requirements, EU road charging classifications, and sector-specific regulatory burdens including cold-chain mandates and timber transport regulations.
Axle Type:
German and Polish logistics corridors drive domestic demand for multi-axle configurations, while single-axle exports concentrate in Benelux light-commercial distribution networks.
- Tandem Axle:Two-axle assemblies rated for 18-24 tonne gross vehicle weight dominate flatbed and refrigerated trailer procurement across EU toll-class networks. German pharmaceutical distributors specify tandem configurations for thermal-system-equipped platforms under F-Gas Regulation compliance timelines.
- Tri-Axle:Three-axle sets distribute concentrated loads across extended wheelbases for heavy machinery transport. Nordic timber operators in Sweden and Finland specify tri-axle ratings exceeding standard specifications for forestry corridor payloads.
- Single Axle:Light-duty units serve urban delivery trailers and small commercial platforms in Netherlands and Belgium.
- Multi-Axle:Four-plus axle configurations address specialized heavy haulage in Alpine construction corridors.
Tandem axle holds the largest share; momentum sits with tri-axle configurations serving heavy-duty Nordic and Alpine corridors.
Trailer Type:
Cost tier stratification separates premium refrigerated platforms from standard flatbed architectures, with tanker and lowboy segments commanding specialized engineering premiums.
- Refrigerated Trailers:Insulated thermal platforms require 10-15% higher static load ratings to accommodate compressor and battery systems. German and Polish pharmaceutical logistics operators are scaling refrigerated fleets under EU Good Distribution Practice temperature-control mandates.
- Flatbed Trailers:Open-deck configurations represent the volume baseline across European general freight. Tandem axle specifications dominate procurement for construction materials and containerized cargo across German autobahn networks.
- Tanker Trailers:Liquid bulk transport demands fatigue-rated axles with sealed bearing systems for chemical and food-grade compliance.
- Lowboy Trailers:Deck-height-optimized designs for heavy machinery concentrate in Swiss and Austrian infrastructure project corridors.
Flatbed configurations retain volume leadership; refrigerated trailers are climbing the fastest on pharmaceutical cold-chain expansion.
End User:
Customer type segmentation aligns procurement sophistication with fleet scale, from integrated logistics platforms to fragmented agricultural operators.
- Logistics Companies:Integrated freight operators including Deutsche Post DHL and Polish asset-light platforms consolidate supplier panels toward dual-qualified partnerships with fatigue-life guarantees.
- Freight Carriers:Independent haulage contractors prioritize unit cost minimization and standard-duty ratings for general cargo lanes.
- Construction Firms:Project-based operators in Alpine regions specify extreme-duty ratings for irregular heavy-haul cycles.
- Agricultural Enterprises:Seasonal grain and livestock transport in Eastern Europe favors medium-duty configurations with retrofit compatibility.
Logistics companies command the largest procurement volume; construction firms are gaining share fastest on infrastructure investment intensity.
Weight Capacity:
Margin concentration tracks upward through duty ratings, with super heavy-duty specifications capturing premium positioning in specialized transport segments.
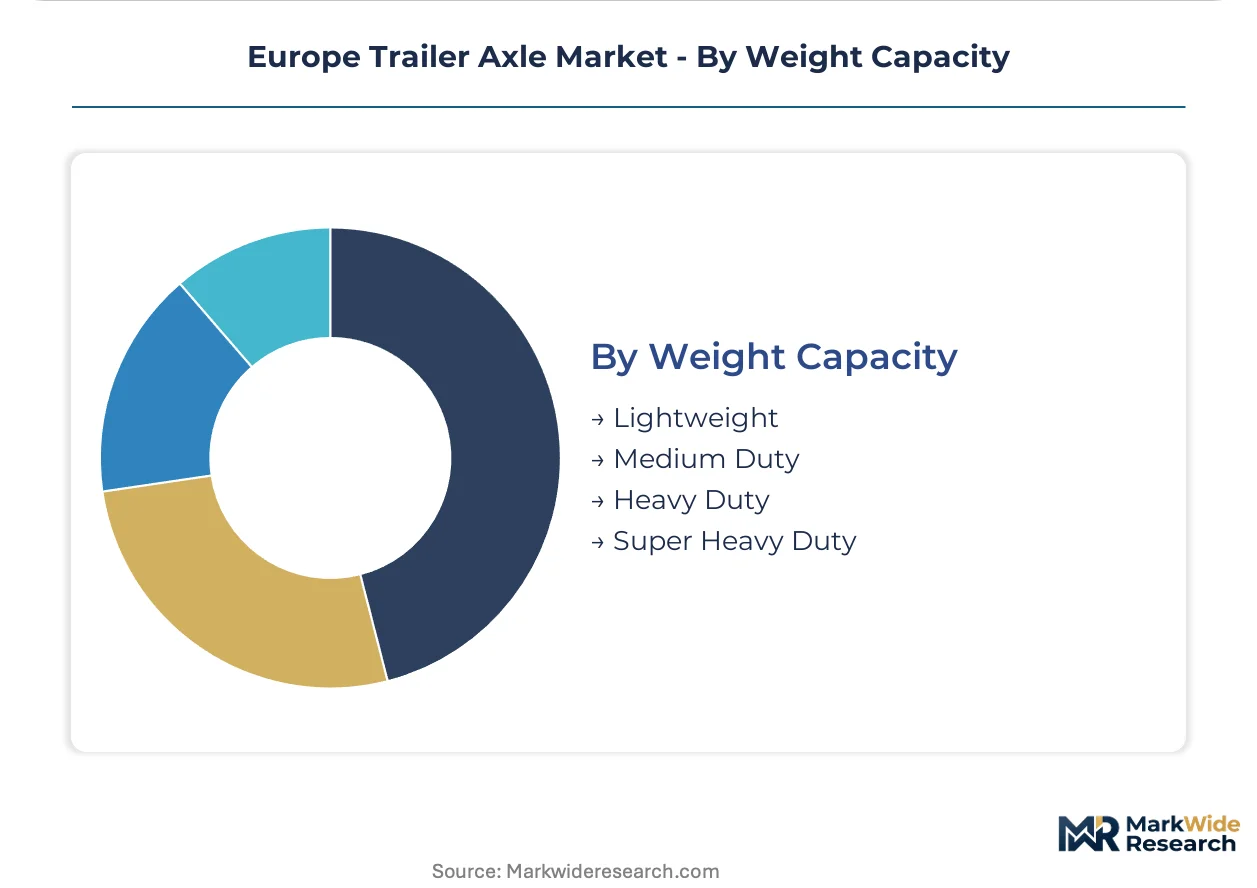
- Heavy Duty:Ratings exceeding 12 tonnes per axle serve timber transport in Nordic forestry corridors and construction equipment haulage. KBA fatigue testing protocols in Germany create accredited-laboratory barriers that filter non-compliant suppliers from this tier.
- Medium Duty:9-12 tonne ratings balance payload efficiency with toll-class optimization for standard freight lanes across Poland and Czech Republic corridors.
- Lightweight:Sub-9 tonne configurations address urban delivery restrictions and last-mile distribution in Benelux city centers.
- Super Heavy Duty:Specialized ratings for abnormal loads concentrate in Swiss heavy-haul permits and German wind turbine transport.
Medium duty retains the largest installed base; heavy duty specifications are expanding most quickly on Nordic timber intensity and Alpine construction demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
KBA fatigue testing protocols in Germany exceed baseline UNECE standards, creating accredited-laboratory barriers that filter non-compliant suppliers from heavy-duty procurement channels across the continent.
Germany
Pharmaceutical logistics operators in the Rhine-Ruhr corridor are scaling refrigerated fleets under EU Good Distribution Practice mandates. KBA enforces axle fatigue testing protocols that exceed baseline UNECE standards. Stuttgart-based forging hubs are adopting continuous-process induction-hardening technology fastest, enabling real-time hardness profiling that reduces scrap rates.
Poland
Asset-light logistics platforms are consolidating supplier panels toward dual-qualified partnerships with fatigue-life guarantees. ECHA REACH compliance governs steel alloy composition and surface coating chemistry. Silesian manufacturing clusters are absorbing skilled welding talent migrating from Czech and Romanian suppliers, tightening labor availability for smaller competitors.
Sweden
Nordic timber operators specify tri-axle ratings exceeding standard specifications for forestry corridor payloads. EU Green Deal mandates indirectly steer axle specification toward higher load ratings for thermal-system-equipped platforms. Gothenburg-area transport equipment fabricators are specializing in heavy-duty configurations for irregular payload cycles.
Switzerland
Alpine construction haulers drive premium positioning for extreme-duty ratings in lowboy and tanker segments serving infrastructure projects. Swissmedic and federal transport authorities coordinate on abnormal load permitting frameworks. Zurich-Geneva logistics corridors concentrate procurement sophistication for project-based heavy-haul cycles.
Netherlands
Benelux city centers generate demand for lightweight sub-9 tonne configurations addressing urban delivery restrictions. F-Gas Regulation phase-down schedules force refrigerated trailer OEMs to specify axles with higher static load ratings. Rotterdam port logistics clusters are optimizing toll-class efficiency on EU road charging networks.
Europe Trailer Axle Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated forging-through-distribution capabilities commanding premium positioning while scale-driven fabricators compete on unit economics. The vendor base concentrates around German and Polish automated manufacturing hubs, with smaller Czech and Romanian suppliers facing output constraints from metallurgical labor migration. Three archetypes dominate: vertically integrated specialists with captive heat-treatment operations, dual-source manufacturers with geographic redundancy, and component-assembly platforms sourcing normalized SAE 1541 steel from qualified forging networks. Competitive moves center on accredited-laboratory partnerships for KBA compliance and digital conformity assessment pathways compressing CE marking timelines.
Among Germany-based integrated specialists, SAF-Holland S.A. and BPW Bergische Achsen KG exemplify archetypes anchored in backward integration into heat-treated axle beams and forging operations controlling quality across distribution networks. DexKo Global Inc. represents the dual-source manufacturing model with plant networks offering geographic redundancy. These three occupy positions that fleet procurement committees are consolidating toward as multi-source configurations give way to dual-qualified partnerships prioritizing fatigue-life guarantees over unit cost minimization.
| Leading Market Players |
|---|
| SAF-Holland S.A. |
| DexKo Global Inc. |
| Schmitz Cargobull AG |
| Haldex AB |
| Al-Ko Kober SE |
| BPW Bergische Achsen KG |
| Meritor Inc. |
| ZF Friedrichshafen AG |
| JOST Werke AG |
| Others |
Value Network & Pricing Analysis
Automated forging capacity utilization above 85% in German and Polish hubs compresses per-unit fixed costs while elevating price floors for smaller Czech and Romanian competitors lacking equivalent scale. ECHA REACH compliance costs for SAE 1541 steel alloy certification further stratify supplier tiers, concentrating procurement volume toward integrated manufacturers with in-house heat-treatment operations.
Pricing Analysis
German axle quotations command 12-18% premiums over Polish equivalents for identical load ratings, reflecting KBA fatigue-testing accreditation costs and shorter logistics corridors to Benelux pharmaceutical fleets. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked induction-hardened units from basic UNECE-compliant configurations and unbranded Eastern European alternatives. Cost compression in the economy tier is intensifying because Silesian manufacturing clusters absorb skilled welding talent from smaller competitors. Independent freight carriers in Poland and Czech Republic corridors exhibit highest price sensitivity, while Nordic timber operators prioritize fatigue-life guarantees over unit cost minimization.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for normalized steel billets and surface coating chemicals, compressing margins for suppliers without captive forging operations. Manufacturing gravity centers on Germany, Poland, and Spain, with Silesian and Stuttgart-area clusters anchoring European capacity. Raw material feeds draw from Swedish scrap steel recyclers, Ukrainian billet suppliers, and German specialty alloy producers. Single-source vulnerability concentrates in induction-hardening equipment providers, where bearing journal heat-treatment expertise rests with legacy forging operations. Distribution runs through OEM direct procurement for refrigerated trailer platforms and aftermarket service networks for legacy fleet retrofit compatibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Induction-hardening engineering talent scarcity in Central Europe constrains new production line commissioning, privileging incumbents with legacy skill retention and accredited laboratory partnerships for KBA compliance.
For Market Incumbents: Fortify backward integration into heat-treated axle beam production to defend against dual-source manufacturers with geographic redundancy. Deepen accredited laboratory partnerships for KBA fatigue testing protocols that exceed baseline UNECE standards. Prioritize capacity addition in Polish Silesian clusters where skilled welding talent concentrates, constraining Czech and Romanian competitor output. For New Entrants and Emerging Players: Differentiate on algorithm-enabled axle health monitoring systems ahead of EU AI Act reclassification toward regulated safety equipment. Target Alpine construction corridors in Switzerland and Austrian lowboy segments where extreme-duty ratings command premium positioning absent volume competition. Pursue CE marking automation partnerships to compress certification timelines relative to legacy forging competitors. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated forging-through-distribution specialists with pharmaceutical logistics panel positions. Long-term viability hinges on thermal-system-equipped platform specialization as F-Gas Regulation phase-downs force higher load rating specifications. Acquisition target archetype: mid-cap German or Polish manufacturers with KBA-accredited laboratories and continuous-process induction-hardening technology. Watch Nordic timber transport intensity as inflection indicator for heavy-duty rating demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous-Process Induction-Hardening Adoption | Real-time hardness profiling at Stuttgart forging hubs reduces scrap rates and compresses lead times. |
| Dual-Source Manufacturing Network Consolidation | Spanish and German plant redundancy insulates pharmaceutical logistics panels from single-point disruption. |
| CE Marking Automation Partnership | Digital conformity assessment pathways compress certification timelines for heat-treated axle beam suppliers. |
| Predictive Maintenance Algorithm Certification | EU AI Act trajectory shifts algorithm-enabled health monitoring from voluntary optimization toward regulated safety architecture. |
| Accredited Laboratory Partnership Expansion | KBA fatigue testing protocols exceeding UNECE standards filter non-compliant suppliers from heavy-duty procurement channels. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across fleet procurement committees, OEM platform engineers, aftermarket service heads, and forging plant managers. Secondary validation drew from KBA technical bulletins, ECHA REACH substance registrations, UNECE regulatory frameworks, and EU Green Deal implementation timelines. Bottom-up axle shipment data triangulated against top-down trailer production estimates across German, Polish, and Benelux manufacturing clusters.
Across the analysis window, projections integrated axle type segmentation by load rating tier, trailer configuration by thermal-system integration level, and end-user sophistication by fleet scale and procurement centralization. CAGRs were derived from regression analysis against EU road charging network expansion, pharmaceutical cold-chain infrastructure investment, and Nordic forestry corridor payload intensity. Industry-specific inputs included F-Gas Regulation phase-down schedules and EU AI Act predictive maintenance classification timelines.
The analysis sits within stated boundaries; outcomes outside sustained ECHA REACH enforcement, continued German KBA protocol divergence from UNECE baselines, or accelerated EU AI Act implementation would require recalibration. Forecasts reflect assumptions on skilled welding labor mobility patterns and induction-hardening equipment commissioning lead times. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
US Automotive Sensors Market
Vehicle Components
Vehicle Radiator Market
Vehicle Components
Steering Tie Rod Market
Vehicle Components
Airport Ground Support Vehicle Market
Vehicle Components
United States Automotive Connectors Market
Vehicle Components
Sideloaders Market
Vehicle Components
Anchorage Connector Market
Vehicle Components
Navigation Light Market
Vehicle Components
Tail Lifts Market
Vehicle Components
RV Battery Market
Vehicle Components
Automotive Pyrofuse Market
Vehicle Components
Japan Automotive Pneumatic Actuators Market
Vehicle Components
Motor Lamination Market
Vehicle Components
Russia Automotive Glass Fiber Composites Market
Vehicle Components
Motorcycle Monoshock Suspension Market
Vehicle Components
Advanced Driver Assistance System (ADAS) Sensor Market