
 Australia Used Car Market | 2026-2036
Australia Used Car Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Used Car Market Analysis
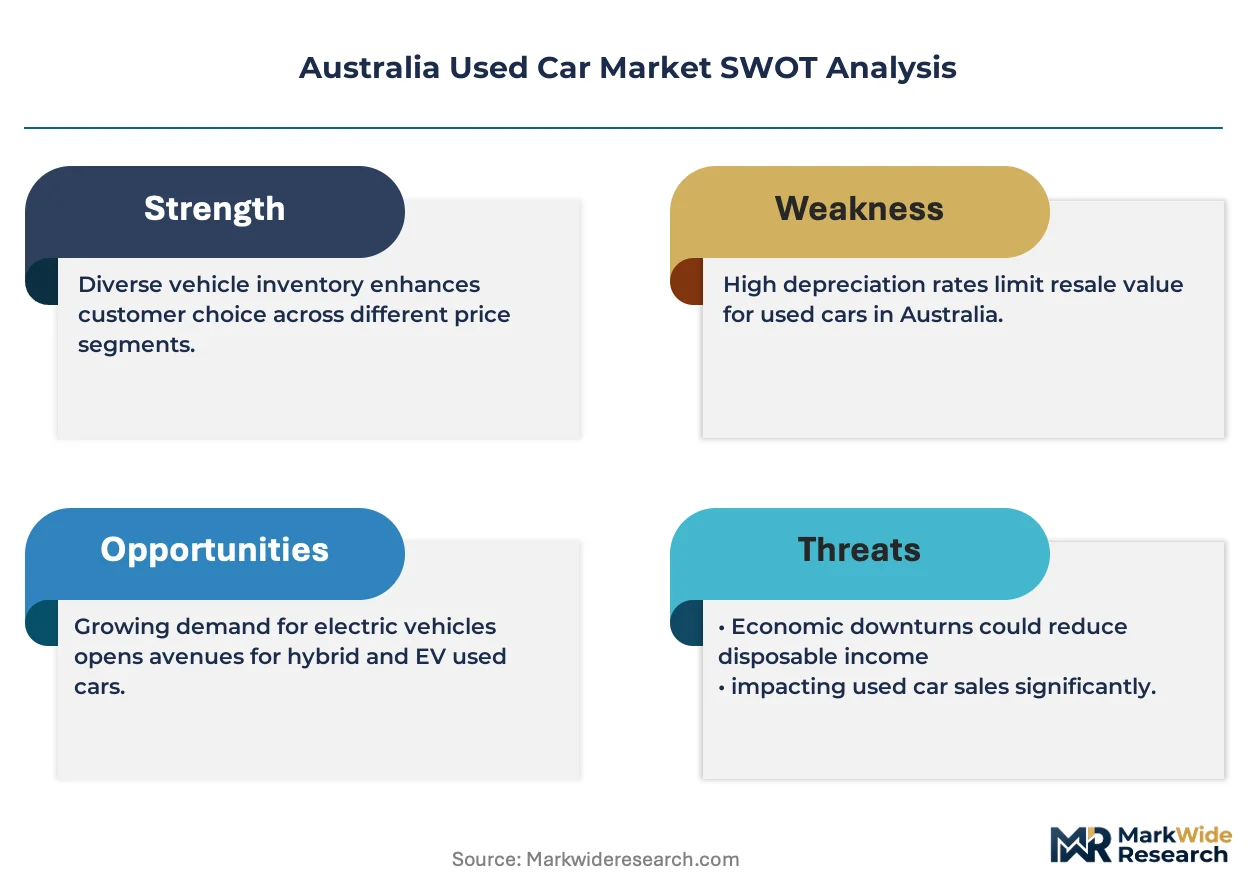
Aftermarket service revenue is tilting toward certified pre-owned programs as dealers seek recurring income streams. Eagers Automotive leverages its dealership network to sustain high-volume turnover across Queensland and Victoria. Motorama anchors its position through specialized SUV and light-commercial inventory. Zagame Automotive differentiates via premium European pre-owned vehicles in metropolitan Melbourne.
Australia used cars comprise previously registered passenger and light-commercial vehicles resold through dealer networks, auctions, or private transactions, typically assessed via standardized condition grading and odometer verification against manufacturer service records. The primary commercial purpose centers on providing affordable mobility alternatives to new vehicle purchases while capturing residual value from depreciated assets. SUV inventory leads transaction volumes as Australian buyers prioritize cargo capacity and all-weather capability across suburban and regional use cases. The 0-3 year age bracket captures the fastest turnover as near-new vehicles exit novated leases and fleet rotations. Hybrid and electric fuel types are gaining structural prominence as TGA-aligned safety inspections and state-based roadworthiness requirements elevate buyer confidence in electrified pre-owned stock.
The Australian Competition and Consumer Commission enforces mandatory fuel consumption and emissions labeling, compelling dealers to standardize disclosure practices and narrowing information asymmetries between sellers and buyers. State-based roadworthiness certificates, administered through transport authorities in New South Wales, Victoria, and Queensland, create variable compliance costs that shape interstate arbitrage patterns and inventory sourcing strategies. Stakeholders must monitor how evolving Australian Design Rule amendments for autonomous safety systems will redefine minimum equipment thresholds for registrable used vehicles.
Market Dynamics
Fleet rotation cycles and novated lease expiries are compressing the 0-3 year supply pipeline, forcing dealers to rebuild sourcing networks around corporate remarketing channels rather than traditional auction pipelines.
Growth Catalysts
- Ride-share fleet expansion:Uber and DiDi drivers in Sydney and Melbourne prioritize near-new SUVs with remaining factory warranty, creating predictable demand for certified pre-owned inventory.
- TGA-aligned safety inspections:Standardized electrified vehicle assessments in Queensland and Victoria are accelerating buyer confidence in hybrid and battery-electric used stock.
- ACCC fuel labeling mandate:Mandatory consumption disclosure is narrowing information asymmetries and compressing negotiation friction in dealer transactions.
Market Restraints
- Interstate compliance arbitrage:Variable roadworthiness certificate costs between New South Wales, Victoria, and Queensland are fragmenting inventory mobility and inflating cross-border transaction overhead.
- Semiconductor residual scarcity:Persistent chip supply constraints in new vehicle production are inflating prices for late-model used stock and compressing margin recovery for volume dealers.
- Autonomous safety equipment thresholds:Pending Australian Design Rule amendments for mandatory ADAS may render pre-2020 inventory non-registrable without costly retrofitting.
Strategic Opportunities
- Regional Queensland penetration:Mining sector FIFO workers in Mackay and Townsville generate underexploited demand for dual-cab utilities with documented service histories.
- Subscription-to-own conversion:Flexible tenure models are capturing younger buyers who lack traditional financing access or permanent address stability.
- State-based EV incentives:Stamp duty waivers in Victoria and Queensland are creating arbitrage potential for interstate sourcing of battery-electric used inventory.
Industry Challenges
- EV technician certification gaps:High-voltage system assessment competency lags behind electrified inventory growth, constraining independent dealer participation.
- Legacy DMS integration:Dealer management system fragmentation between urban franchise networks and regional independents is blocking unified inventory visibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Used Car Market |
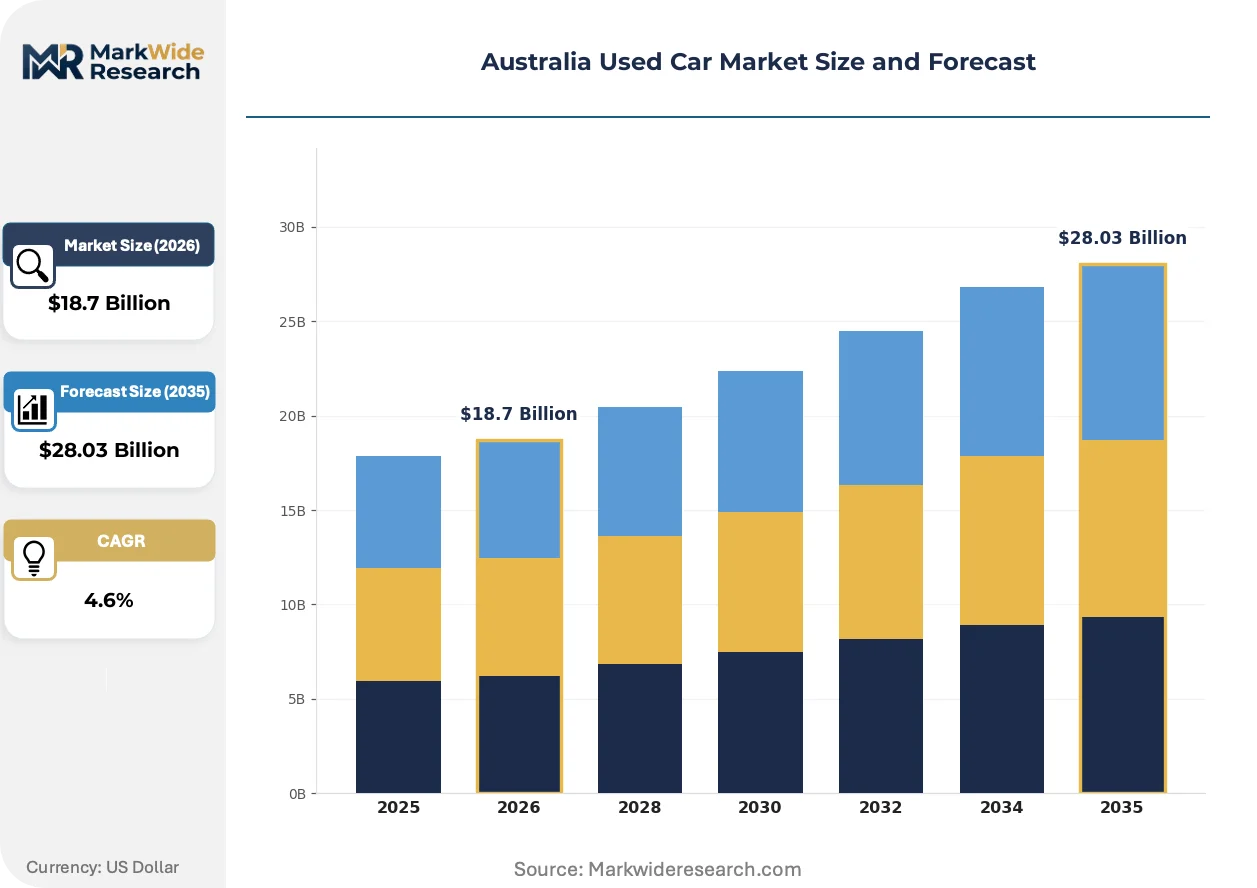
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: SUV, Sedan, Hatchback, Coupe Age Group: 0-3 Years, 4-7 Years, 8-10 Years, 10+ Years Condition: Excellent, Good, Fair, Poor Fuel Type: Petrol, Diesel, Electric, Hybrid |
| Companies Covered | Motorama, Zagame Automotive, Eagers Automotive, Penske Select, Auto League, Autosports, Essendon Fields Auto, Blinkr, Peter Warren Automotive, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Used Car Market Emerging Trajectories
Digital condition assessment tools and blockchain-based service verification are compressing trust-building timelines between anonymous transacting parties across Australia's dispersed geography.
AI-powered photographic damage detection is digitizing remote vehicle evaluation. Fleet operators in Perth and Adelaide are adopting smartphone-based condition reporting to accelerate wholesale disposal timelines. This compression of physical inspection requirements is enabling interstate arbitrage and diluting traditional auction gatekeeper roles.
The Australian Competition and Consumer Commission's mandatory fuel consumption labeling is standardizing disclosure formats across dealer networks. Compliance costs are concentrating among smaller independents who lack integrated pricing systems. Metropolitan Sydney dealers are responding by bundling labeling data into fixed-price digital listings.
Direct consumer-to-consumer platforms are displacing traditional dealer intermediation for vehicles aged 7-15 years. Regional sellers in Tasmania and South Australia are prioritizing these channels to avoid freight costs to mainland auction centers. This channel shift is fragmenting price discovery and compressing transaction transparency outside certified programs.
Australia Used Car Market Segmentation
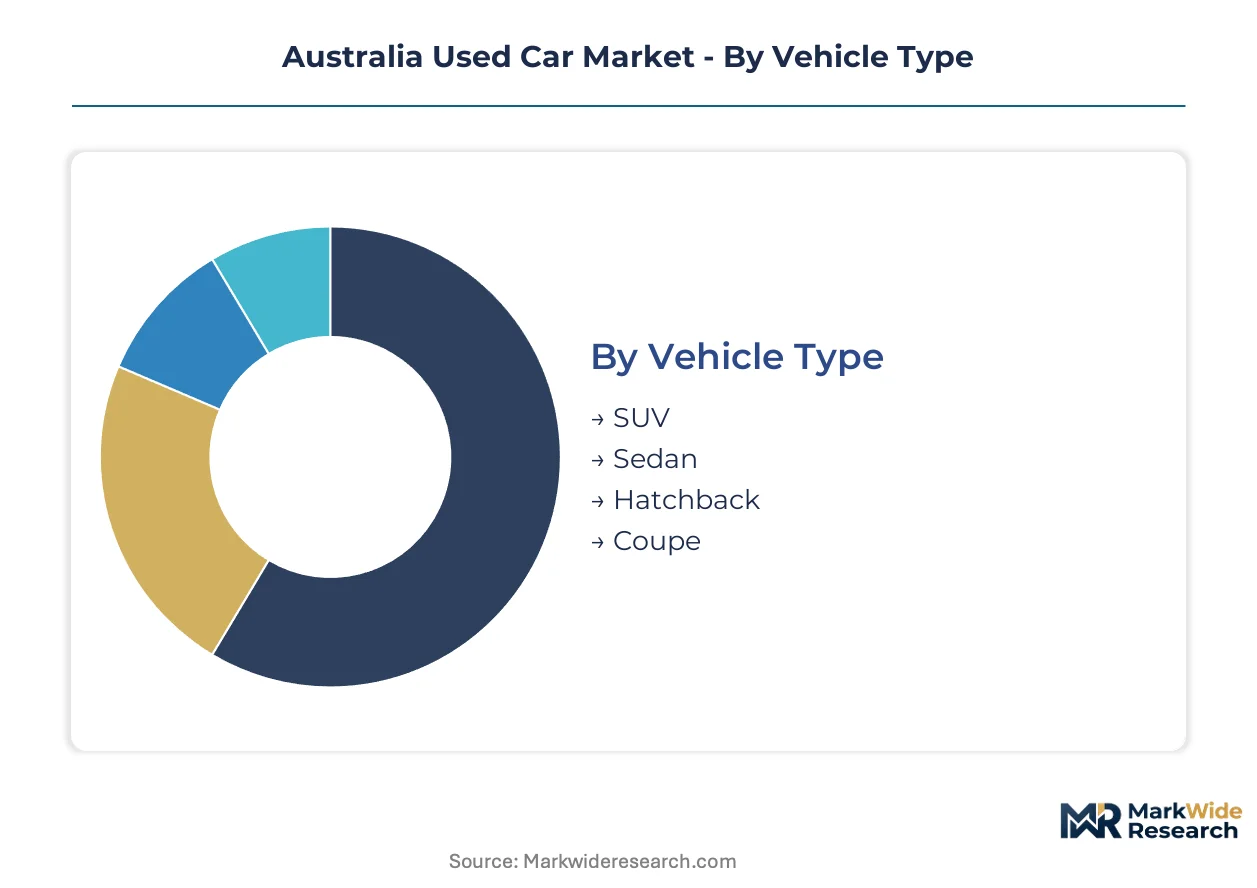
Used car segmentation in Australia reflects how depreciation curves, compliance costs, and buyer risk tolerance intersect across vehicle lifecycles. Dealers structure inventory and pricing strategies around these dimensions to match supply with divergent customer financing capacities and use-case requirements.
Vehicle Type:
Application focus determines which body styles dominate transaction flow across metropolitan and regional buyer pools.
- SUV:Higher ride height and cargo flexibility suit Australian suburban families and regional touring. Sydney and Melbourne dealers report strongest turnover for mid-size SUVs with documented service histories and remaining factory warranty coverage.
- Sedan:Traditional three-box configuration appeals to corporate fleet buyers and ride-share operators prioritizing rear passenger comfort. Melbourne-based novated lease returns feed consistent supply into this channel.
- Hatchback:Compact footprint aligns with urban parking constraints and first-time buyer budgets. Queensland's younger demographic skews demand toward this segment.
- Coupe:Two-door styling attracts discretionary purchasers seeking performance positioning. Low volume concentrates in premium dealer networks across metropolitan Melbourne.
SUV commands the established base. The steepest expansion runs through Hatchback as urban density intensifies.
Age Group:
Depreciation velocity and compliance burden vary sharply across vehicle maturity tiers, shaping margin structures for dealers.
- 0-3 Years:Near-new inventory exits corporate novated leases and fleet rotations with complete manufacturer service records. Queensland and Victoria dealers compete aggressively for this pipeline through direct remarketing relationships.
- 4-7 Years:Sweet spot balancing affordability with remaining useful life. Sydney buyers prioritize this bracket for family vehicles where warranty expiration risk is offset by lower purchase prices.
- 8-10 Years:Elevated roadworthiness compliance costs in New South Wales and Victoria compress dealer margins. Private sales channels capture volume as franchise networks avoid certification overhead.
- 10+ Years:Minimal dealer participation outside specialized budget lots. Tasmania and South Australia see higher relative activity due to lower registration cost structures.
4-7 Years anchors dealer profitability. The most rapid volume gains are occurring in 0-3 Years as fleet rotation accelerates.
Condition:
Grading standards directly determine financing access and interstate arbitrage feasibility for inventory.
- Excellent:Near-factory presentation with complete documentation enables certified pre-owned programs. Melbourne dealers leverage this tier for subscription-to-own conversion pipelines.
- Good:Minor wear acceptable to mainstream buyers seeking value positioning. Queensland volume dealers structure pricing around this grade for FIFO worker segments.
- Fair:Visible wear requiring disclosure under ACCC guidelines. Independent regional operators specialize here with lower overhead cost structures.
- Poor:Significant mechanical or cosmetic defects limiting buyer pool to cash purchasers and repair specialists. Auction disposal dominates.
Good condition vehicles move the highest absolute volume. Excellent grade inventory is climbing fastest as certification programs expand.
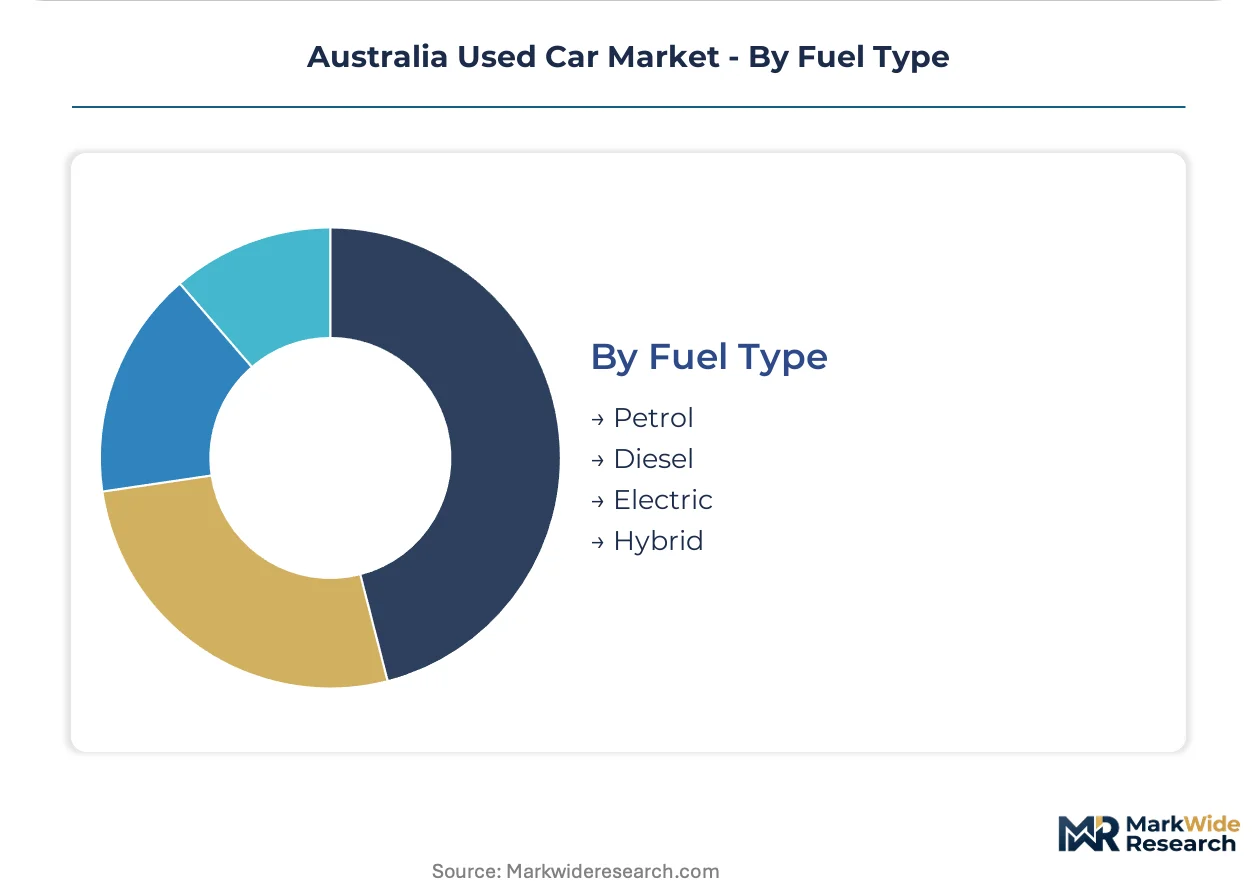
Fuel Type:
Powertrain technology is fragmenting buyer preferences as state-based incentives and infrastructure maturity diverge.
- Petrol:Dominant existing fleet with lowest maintenance complexity. Regional Queensland and Western Australia maintain strongest relative demand due to refueling infrastructure ubiquity.
- Diesel:Torque characteristics suit towing and commercial applications. Mining sector demand in Mackay and Townsville sustains premium pricing for dual-cab utilities.
- Electric:Battery-electric vehicles gain traction where state stamp duty waivers apply. Victoria and Queensland arbitrage opportunities emerge as interstate sourcing strategies develop.
- Hybrid:Toyota-dominated secondary market benefits from proven reliability records. Sydney ride-share operators prioritize hybrid SUVs for fuel cost management.
Petrol retains the largest installed base. Electric powertrains are expanding most quickly off low initial penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New South Wales and Victoria diverge from Queensland and Western Australia in fuel-type preferences, with the southeastern states accelerating electrified vehicle turnover while resource-dependent regions sustain diesel utility demand.
New South Wales
Sydney's ride-share operators and novated lease returns drive consistent 0-3 year SUV turnover. The state's roadworthiness certificate requirements under Transport for NSW elevate compliance costs for older inventory, pushing dealers toward certified pre-owned programs. Parramatta and Blacktown dealership clusters concentrate volume transactions for metropolitan families.
Victoria
Melbourne's premium European import pipeline feeds specialized pre-owned demand in inner suburbs. VicRoads safety inspection standards and stamp duty waivers for battery-electric vehicles are accelerating hybrid and EV adoption. Dandenong and Preston automotive precincts anchor wholesale remarketing activity for fleet rotation inventory.
Queensland
Mining sector FIFO workers in Mackay and Townsville generate sustained demand for dual-cab diesel utilities with documented service histories. The state's TGA-aligned electrified vehicle inspection protocols are expanding independent dealer participation in hybrid stock. Brisbane's Archerfield and Brendale clusters dominate volume turnover for suburban family SUVs.
Western Australia
Perth's geographic isolation sustains higher retention values for late-model stock as interstate sourcing costs inflate. The Department of Transport's variable roadworthiness requirements create compliance arbitrage opportunities against eastern states. Welshpool and Canning Vale automotive districts concentrate refurbishment and reconditioning capacity for regional distribution.
South Australia
Adelaide's lower registration cost structures sustain dealer participation in 8-10 year inventory segments abandoned by eastern state networks. The state's fuel consumption disclosure enforcement mirrors ACCC mandates but with reduced administrative overhead. Mile End and Edwardstown precincts handle cross-border arbitrage for Victorian and New South Wales compliance-cost refugees.
Australia Used Car Market Vendor Landscape
Capability concentration sits with premium specialized networks; scale advantage sits with multi-state dealership groups with integrated remarketing pipelines. The market structures around three tiers: volume franchise operators, specialized pre-owned independents, and digital-native disintermediation platforms. Two competitive moves dominate: direct corporate fleet remarketing relationships that bypass auction intermediaries, and certified pre-owned program expansion that captures recurring service revenue.
Within the volume-tier segment, Eagers Automotive exemplifies multi-state scale advantage through Queensland and Victoria network density. Motorama occupies a specialized position in SUV and light-commercial inventory concentration. Zagame Automotive represents the premium European pre-owned archetype within metropolitan Melbourne. These three anchors illustrate how geographic coverage, segment specialization, and brand positioning stratify competitive differentiation.
| Leading Market Players |
|---|
| Motorama |
| Zagame Automotive |
| Eagers Automotive |
| Penske Select |
| Auto League |
| Autosports |
| Essendon Fields Auto |
| Blinkr |
| Peter Warren Automotive |
| Others |
Supply Flow & Price Mechanics
Interstate compliance arbitrage risk between New South Wales, Victoria, and Queensland determines both tiered pricing spreads across certification grades and the geographic shape of dealer sourcing networks. Variable roadworthiness certificate costs fragment inventory mobility and inflate cross-border transaction overhead, compressing margins for volume operators while creating premium capture opportunities for certified pre-owned programs.
Pricing Analysis
Project-based transaction structures dominate private sales and auction channels, while subscription-to-own and fixed-price digital listings are displacing traditional negotiation frameworks in dealer networks. Price differentiation centers on certification grade under TGA-aligned inspection protocols and remaining factory warranty coverage. Cost compression in the 8-10 year bracket intensifies as Transport for NSW and VicRoads elevate compliance burdens. First-time buyers in Queensland exhibit highest price sensitivity; Melbourne premium European pre-owned purchasers show lowest elasticity.
Supply Chain Analysis
Corporate remarketing channels and fleet disposal networks hold concentrated sourcing capacity, bypassing traditional auction intermediaries. Supply draws from novated lease returns in Victoria, mining sector rotations in Queensland, and ride-share fleet turnovers in Sydney. Single-source vulnerability concentrates in semiconductor-dependent late-model inventory where chip scarcity inflates replacement costs. Distribution feeds through metropolitan dealership clusters—Parramatta, Dandenong, Archerfield—with regional refurbishment nodes in Welshpool and Mile End handling cross-border arbitrage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrified vehicle inspection standardization under TGA protocols is accelerating a high-growth disruption that redefines competitive viability for dealers lacking high-voltage assessment capability.
For Market Incumbents: Harden certified pre-owned program infrastructure to capture recurring service revenue as subscription-to-own models displace traditional financing. Invest in EV technician certification to offset independent dealer exclusion from electrified inventory pipelines. Defensive consolidation around corporate fleet remarketing relationships will bypass auction gatekeepers and secure 0-3 year supply. For New Entrants and Emerging Players: Regional Queensland FIFO worker segments in Mackay and Townsville represent the most penetrable entry point, with dual-cab diesel utilities commanding sustained mining sector premiums. Tasmania and South Australia's lower registration cost structures offer refuge from eastern state compliance overhead. Direct consumer-to-consumer platform specialization for 7-15 year inventory avoids freight costs to mainland auction centers. For Investors and Strategic Acquirers: The market sits at an electrification transition phase that favors vertically integrated dealership groups with captive remarketing pipelines. Long-term viability hinges on state-based EV incentive arbitrage capacity across Victoria and Queensland stamp duty waivers. Monitor Australian Design Rule amendment timing for autonomous safety equipment thresholds as a registration eligibility inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Pre-Owned Program Expansion | Captures recurring service revenue from Eagers Automotive and Motorama subscription pipelines. |
| EV Technician Certification Investment | Enables participation in Queensland and Victoria TGA-aligned electrified vehicle inspection protocols. |
| Corporate Fleet Remarketing Partnership | Bypasses auction intermediaries to secure 0-3 year inventory from novated lease expiries. |
| Interstate Sourcing Network Development | Exploits stamp duty waiver arbitrage between Victoria, Queensland, and South Australia. |
| Digital Condition Assessment Platform | Compresses trust-building timelines for remote transactions across Australia's dispersed geography. |
Methodological Framework
The analysis maps passenger vehicle, SUV, light-commercial, and electrified powertrain segments, each validated through dealership operations managers, fleet procurement directors, state transport authority compliance officers, and aftermarket service heads. Primary interview intelligence triangulates against vehicle registration databases, ACCC fuel labeling enforcement records, state roadworthiness certificate issuance data, and corporate fleet disposal pipeline disclosures. Bottom-up transaction volume estimates and top-down market value assessments converge across the analytical framework.
Assumptions around fleet rotation cycle velocity, novated lease expiry rates, and state-based EV incentive persistence were held fixed while semiconductor supply recovery trajectories and autonomous safety equipment mandate timing were varied across sensitivity scenarios. Segmentation dimensions span vehicle type, age bracket, condition grade, and fuel architecture. CAGRs derive from volume-weighted average price progression across the projection horizon, incorporating electrified vehicle depreciation curve divergence and compliance cost inflation in older brackets.
Stress conditions across interstate compliance cost divergence, chip supply constraint persistence, and ADAS mandate retroactivity were modeled; outcomes outside those bands fall beyond the analytical envelope. Quarterly review of TGA inspection protocol adoption rates and state transport authority rulemaking calendars is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Used Vehicles
India Used Car Market
Used Vehicles
Finland Used Car Market
Used Vehicles
Brazil Used Car Market
Used Vehicles
Poland Used Car Market
Used Vehicles
Hong Kong Used Car Market
Used Vehicles
Indonesia Used Car Financing Market
Used Vehicles
North America Used Car Market
Used Vehicles
Japan Used Car Market
Used Vehicles
Myanmar Used Car Market
Used Vehicles
Bangladesh Used Car Market
Used Vehicles
Sri Lanka Used Car Market
Used Vehicles
Germany Used Car Market
Used Vehicles
China Used Car Market
Used Vehicles
Oman Used Car Market
Used Vehicles
Used Cars in Russia Market
Used Vehicles
Nigeria Used Car Market