
 Global Bio Based and Synthetic Dimethyl Ether (DME) Market | 2026-2036
Global Bio Based and Synthetic Dimethyl Ether (DME) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bio Based and Synthetic Dimethyl Ether (DME) Market Intelligence
The traditional distribution channel, historically reliant on large-scale wholesalers, is fragmenting as smaller, specialized suppliers enter the market for bio-based variants. Major incumbents like Royal Dutch Shell PLC leverage extensive global logistics to serve high-volume fuel additive contracts. In contrast, China Energy Ltd dominates regional supply chains for synthetic DME production from coal. Specialists such as Oberon Fuels, Inc. are pioneering direct sales models for niche renewable DME applications in transportation.
Dimethyl ether is a colorless gas, chemically formulated as CH3OCH3, produced through the catalytic dehydration of methanol. Its primary industrial value stems from its high cetane number, clean-burning properties, and utility as a versatile chemical intermediate. While the synthetic production method constitutes the bulk of market volume, the bio-based segment represents the fastest-growing category. The fuel additive application is expanding at a faster rate than its established use as an aerosol propellant.
Regulations such as the EU's REACH framework and directives from the US EPA govern chemical safety and fuel specifications, setting stringent quality standards for market entry. In parallel, China's national dual carbon goals create significant incentives for lower-emission synthetic and bio-based DME production. Navigating the divergent cost structures and compliance pathways between fossil-derived and renewable feedstocks remains the central strategic challenge for all market participants.
Market Dynamics
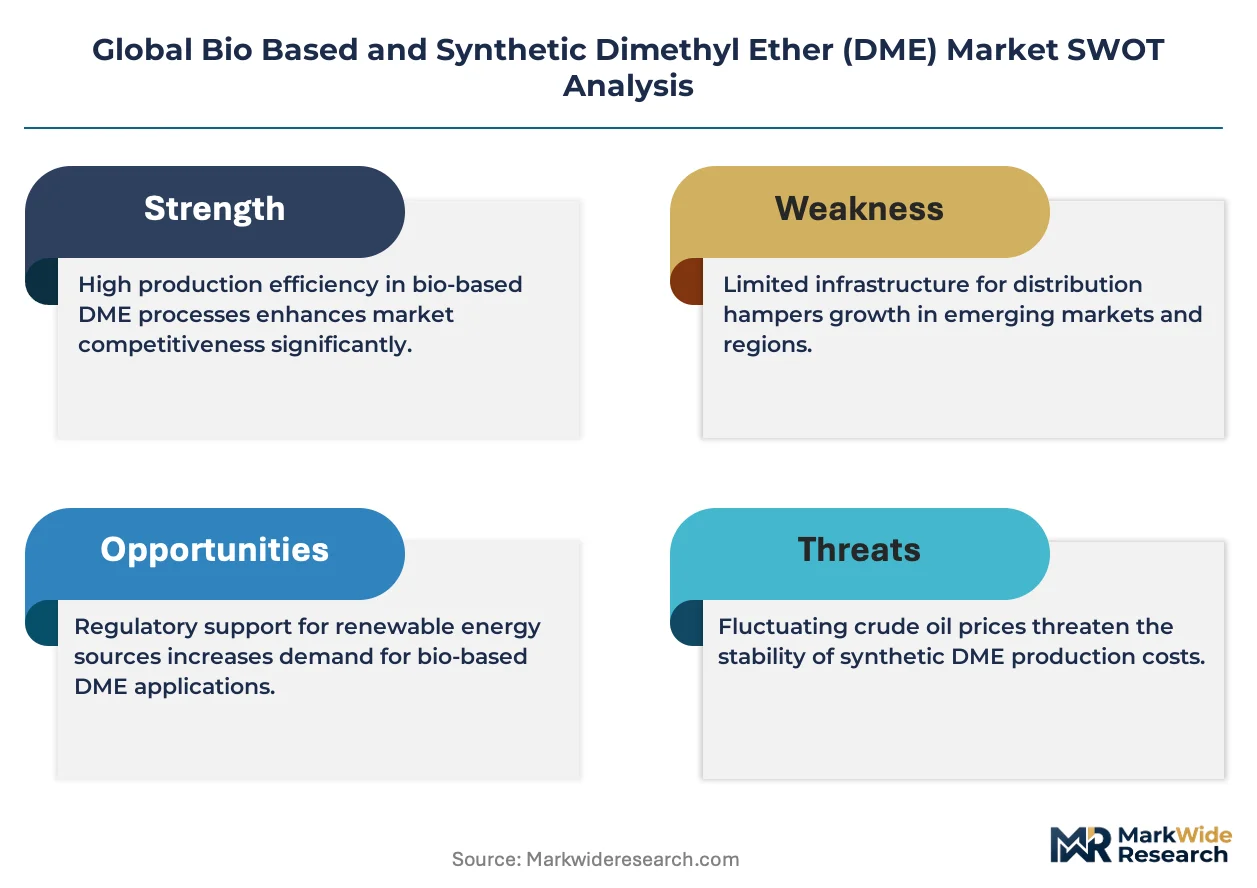
The central structural force shaping the dimethyl ether market is the bifurcation of production economics and regulatory incentives between low-cost, fossil-derived synthetic DME and high-cost, policy-driven bio-based DME, creating divergent pathways for investment and market entry.
Growth Catalysts
- Favorable Regulatory Frameworks:Government mandates like the EU Green Deal and China's dual carbon goals incentivize the substitution of conventional fuels with lower-emission alternatives, directly supporting DME adoption in the transportation and industrial sectors.
- Expanding Chemical Feedstock Demand:In China, DME serves as a crucial building block for producing olefins, acetic acid, and other high-value chemicals, sustaining large-scale synthetic production from coal and natural gas.
- Clean-Burning Fuel Properties:DME's high cetane number and soot-free combustion make it an attractive diesel substitute and a clean-burning aerosol propellant, driving adoption by end-users seeking to meet stringent air quality standards.
Market Restraints
- Feedstock Cost Volatility:The production cost for bio-based DME is directly tied to the price of renewable feedstocks like biomass and biomethanol, which exhibit greater price volatility and supply uncertainty compared to coal or natural gas.
- Substitute Fuel Competition:Liquefied petroleum gas (LPG) presents a significant substitution threat, particularly in the heating and cooking segments, due to its established infrastructure and lower switching costs for consumers.
- Infrastructure Investment Gap:Widespread adoption of DME as a transport fuel requires significant capital investment in dedicated storage tanks, dispensing equipment, and vehicle modifications, slowing its penetration into mainstream automotive markets.
Strategic Opportunities
- Emerging Hydrogen Carrier Application:DME's potential as a safe and efficient carrier for hydrogen presents a significant opportunity, allowing for the transport and storage of hydrogen in existing LPG infrastructure with minor modifications.
- Renewable Fuel Mandates in North America:Policies such as the US Inflation Reduction Act (IRA) and Canada's Clean Fuel Regulations create financial incentives for producing and using renewable DME, opening new markets for bio-based variants.
- Marine Fuel Applications:As the maritime industry faces pressure from the International Maritime Organization (IMO) to decarbonize, DME is being explored as a clean-burning alternative to heavy fuel oil for marine engines.
Industry Challenges
- Navigating Divergent Global Standards:Manufacturers face complexity in complying with a patchwork of chemical safety and fuel quality regulations, such as the EU's REACH framework and specific fuel specifications set by the US EPA.
- Capital Intensity of Production:The construction of new DME plants, particularly catalytic dehydration facilities for bio-based production, requires substantial upfront capital investment, posing a barrier for smaller, specialized entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bio Based and Synthetic Dimethyl Ether (DME) Market |
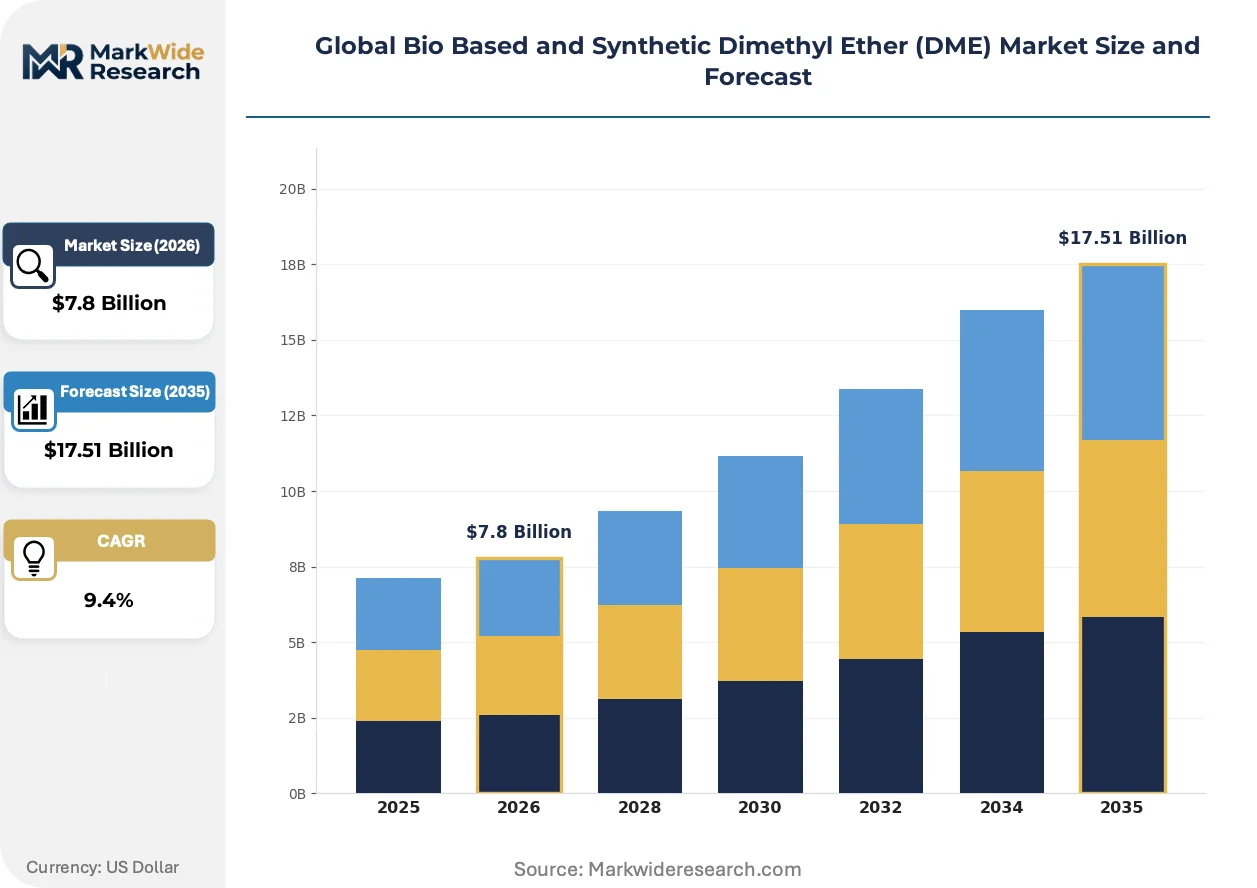
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $17.51 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Production Method: Bio Based, Synthetic, Hydrated DME, Purified DME Application: Aerosol Propellant, Fuel Additive, Chemical Feedstock, Refrigerant End User: Transportation, Chemical Manufacturing, Household Products, Industrial Applications Distribution Channel: Direct Sales, Online Sales, Wholesalers, Distributors |
| Companies Covered | China Energy Ltd, Akzo Nobel NV, Royal Dutch Shell PLC, Korea Gas Corporation, Shenhua Ningxia Coal Industry Group Co., Mitsubishi Corporation, Fuel DME Production Co. Ltd, Oberon Fuels, Inc., Grillo-Werke AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bio Based and Synthetic Dimethyl Ether (DME) Market Strategic Shifts & Innovations
The market is defined by a push toward greater process efficiency and sustainability, driven by both regulatory pressures and the pursuit of cost competitiveness. This dynamic is spurring innovation in catalytic processes for bio-based routes and advanced process controls in large-scale synthetic plants.
Advanced process control (APC) systems are becoming integral to DME production, using sensors and predictive analytics to optimize the catalytic dehydration of methanol. Synthetic DME producers, particularly in China's coal-to-chemicals industry, are the primary adopters to maximize output and reduce energy consumption. This technology is digitizing plant-level operations, enabling more precise control over reaction conditions and improving overall resource efficiency.
Compliance with the European Union's REACH regulation is a primary consideration for market participants, dictating stringent data submission and chemical safety assessment protocols. The directive forces producers to invest heavily in toxicological and environmental impact studies to secure market access. This particularly affects new bio-based DME formulations, which must demonstrate a safety profile equivalent to or better than established synthetic grades.
Direct sales from producers to end-users are disrupting traditional distribution channels for specialty DME variants. This model bypasses large-volume wholesalers, allowing bio-based DME suppliers to engage directly with commercial transportation fleets seeking to secure low-carbon fuel. This trend is most prominent in North America and Europe, where corporate sustainability goals and fleet decarbonization targets are creating demand for traceable, renewable fuel sources.
Global Bio Based and Synthetic Dimethyl Ether (DME) Market Segmentation
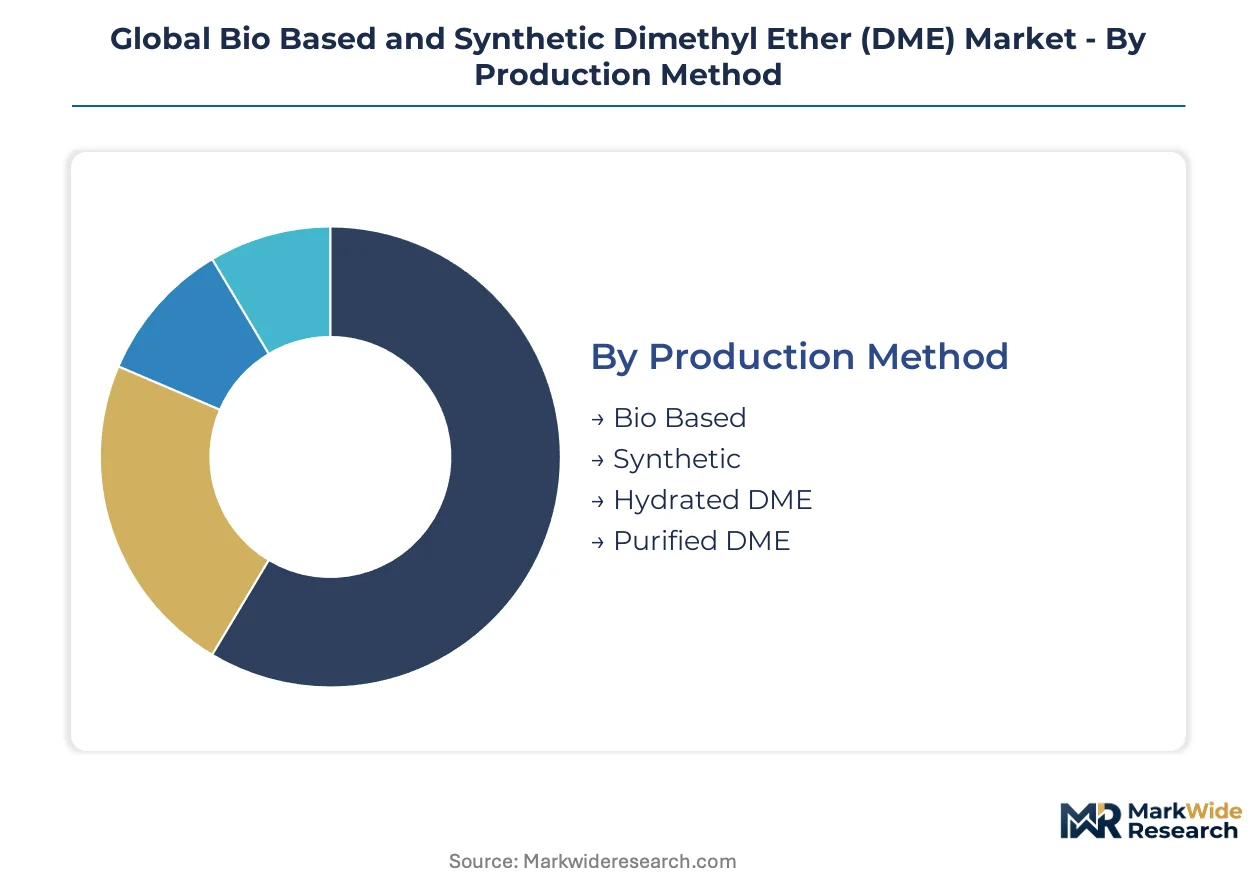
Understanding the varied segments within the dimethyl ether market is critical for identifying specific growth vectors and operational challenges. Each segment presents distinct technical requirements and market dynamics, influencing investment decisions and strategic positioning. This granular view reveals how different production methods, applications, and end-user demands shape the market's evolution.
Production Method:
The intensity of after-sales service requirements often correlates with the complexity and regulatory scrutiny of the production method itself, influencing long-term operational costs.
- Bio Based:This variant is derived from renewable feedstocks such as biomass or biomethanol, characterized by its lower carbon footprint and alignment with sustainability goals. Demand is concentrating in Europe for transport fuel applications, driven by the EU Green Deal and national decarbonization mandates.
- Synthetic:Produced primarily from fossil sources like coal or natural gas through catalytic dehydration of methanol, synthetic DME constitutes the bulk of current market volume. Its demand is significant in China, where it serves as a critical chemical feedstock for various industrial processes.
- Hydrated DME:This form of DME contains water, often as an intermediate product, requiring further processing for high-purity applications.
- Purified DME:High-purity DME is essential for specialized applications like aerosol propellants and refrigerants, demanding stringent quality control.
By volume, Synthetic DME leads the market. By growth pace, Bio Based DME is ahead.
Application:
Volume concentration across applications reflects the established industrial uses and emerging sectors where DME's unique properties offer significant advantages.
- Aerosol Propellant:DME serves as an effective, non-toxic propellant in various consumer aerosol products due to its low odor and excellent solvency.
- Fuel Additive:DME's high cetane number and clean-burning characteristics make it a compelling diesel substitute, reducing particulate matter and nitrogen oxide emissions. Adoption is expanding in the global transportation sector, driven by stringent air quality standards and decarbonization efforts.
- Chemical Feedstock:As a versatile chemical intermediate, DME is crucial for producing olefins, acetic acid, and other high-value chemicals. Demand is particularly strong in China, supporting its large-scale chemical manufacturing industry.
- Refrigerant:DME is gaining traction as an environmentally friendly refrigerant, offering a low global warming potential alternative to traditional hydrofluorocarbons.
Fuel Additive applications exhibit the most rapid expansion, while Chemical Feedstock commands significant market share.
End User:
Customer type differentiation highlights the diverse needs and regulatory environments shaping DME consumption across various industrial and consumer segments.
- Transportation:This segment utilizes DME as a clean-burning fuel in heavy-duty vehicles and marine engines, directly addressing emissions reduction goals. Regulatory frameworks like the EU Green Deal are accelerating its adoption in commercial fleets across Europe.
- Chemical Manufacturing:Chemical producers leverage DME as a fundamental building block for synthesizing a wide array of derivatives, including olefins and acetic acid. This demand anchors large-scale synthetic DME production, particularly within China's industrial complexes.
- Household Products:DME is incorporated into household aerosols, such as hairsprays and air fresheners, acting as a safe and efficient propellant.
- Industrial Applications:This broad category includes DME use in niche processes like welding gases and specialized solvent formulations across various industries.
Chemical Manufacturing represents a foundational demand base, while the Transportation sector is showing significant growth potential.
Distribution Channel:
Supply concentration patterns within distribution channels reflect both the established market structures and the emergence of specialized pathways for bio-based variants.
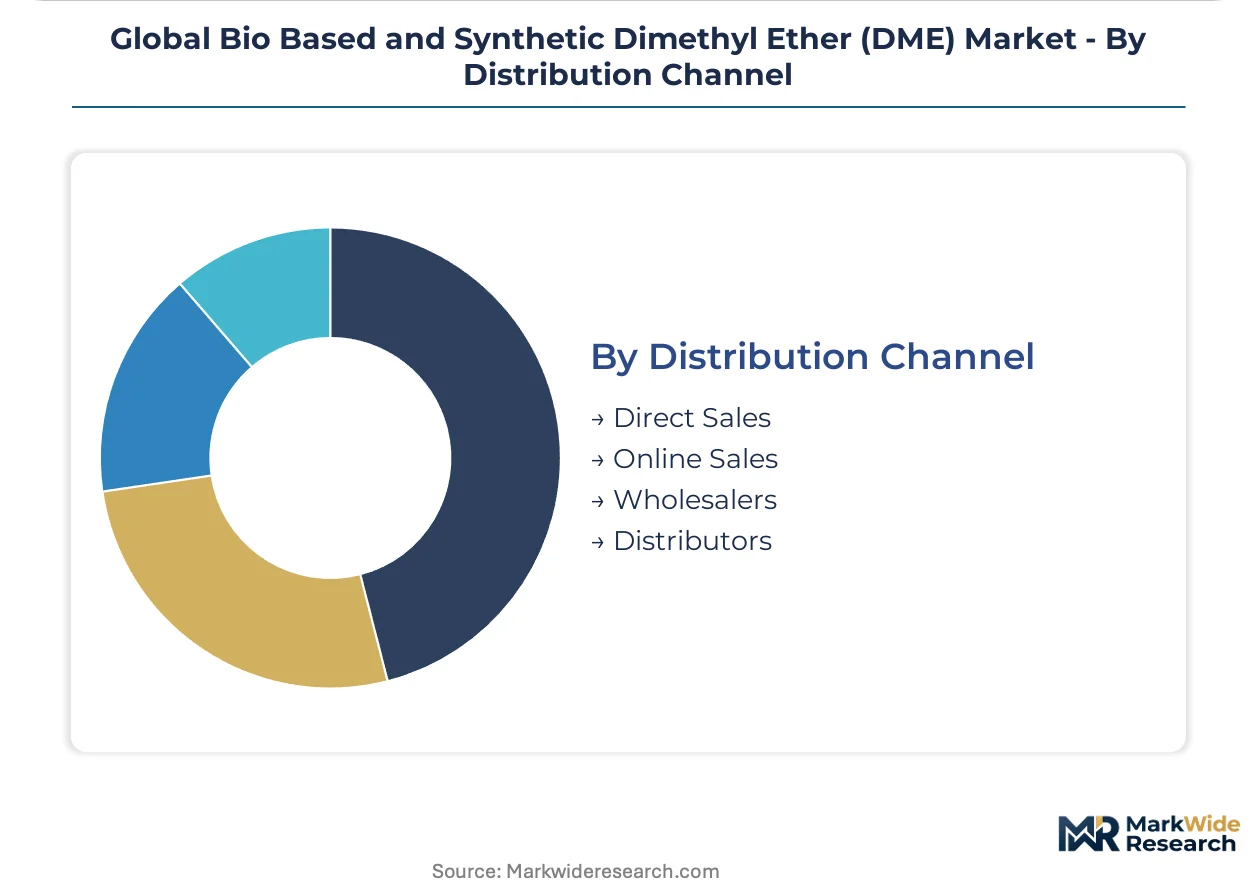
- Direct Sales:This model bypasses intermediaries, allowing bio-based DME producers to directly engage with end-users, particularly commercial transportation fleets. Companies like Oberon Fuels, Inc. utilize direct sales for niche renewable DME applications in North America.
- Online Sales:Online platforms facilitate the procurement of smaller volumes or specialized DME products, serving a fragmented customer base.
- Wholesalers:Large-scale wholesalers traditionally manage the bulk distribution of synthetic DME for industrial and fuel additive contracts. Major incumbents like Royal Dutch Shell PLC leverage these extensive global logistics networks.
- Distributors:Distributors provide regional market access and logistical support, bridging the gap between producers and smaller industrial or commercial clients.
Wholesalers remain central for bulk volumes, while Direct Sales channels are gaining share in specialized segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional pricing-power asymmetry exists between the low-cost synthetic DME production in China and the higher-cost bio-based variants in Europe. This divergence shapes investment flows and market development across different geographies. Policy incentives heavily influence the economic viability of new projects.
China
China's demand for synthetic DME as a chemical feedstock drives significant production volumes. The country's dual carbon goals incentivize lower-emission production methods, including coal-to-DME with carbon capture. Industrial clusters in Ningxia and Inner Mongolia remain central to large-scale synthetic DME manufacturing.
United States
The United States market is expanding for bio-based DME, particularly in transportation applications. The US Inflation Reduction Act (IRA) provides financial incentives for renewable fuel production and usage. Commercial transportation fleets in California and Texas are exploring DME for decarbonization targets.
Germany
Germany is a key European market for bio-based DME, driven by stringent decarbonization mandates. The EU Green Deal and national emissions standards support the transition to cleaner transport fuels. Chemical parks along the Rhine, such as Ludwigshafen, are exploring bio-DME integration.
Netherlands
The Netherlands focuses on bio-based DME for its strategic position as a European logistics hub. Regulatory frameworks under the EU Green Deal encourage the development of sustainable energy carriers. Port of Rotterdam serves as a critical entry point and distribution center for renewable fuels.
Japan
Japan's industrial sector shows interest in DME as a clean energy carrier and chemical intermediate. The Ministry of Economy, Trade and Industry (METI) supports hydrogen and alternative fuel research. Chemical manufacturing facilities in the Keihin industrial zone are evaluating DME applications.
Global Bio Based and Synthetic Dimethyl Ether (DME) Market Key Industry Players
Large-scale integrated producers and specialized bio-based innovators split the market for dimethyl ether. This bifurcation creates distinct competitive dynamics, with established players focusing on volume and new entrants targeting niche applications. Companies pursue capacity expansion and strategic partnerships to secure feedstock access and expand distribution.
Within the large-scale synthetic production segment, China Energy Ltd and Royal Dutch Shell PLC exemplify integrated operations spanning feedstock to distribution. Oberon Fuels, Inc. represents the specialized bio-based producers, focusing on renewable DME for niche transportation applications. These companies anchor different ends of the market based on production method and target end-user.
| Leading Market Players |
|---|
| China Energy Ltd |
| Akzo Nobel NV |
| Royal Dutch Shell PLC |
| Korea Gas Corporation |
| Shenhua Ningxia Coal Industry Group Co. |
| Mitsubishi Corporation |
| Fuel DME Production Co. Ltd |
| Oberon Fuels, Inc. |
| Grillo-Werke AG |
| Others |
Cost & Logistics Intelligence
Ningxia's coal-to-chemicals industrial clusters, with their vast synthetic DME capacity, exert significant influence over commodity pricing for chemical feedstock applications.
Pricing Analysis
Configured-to-order pricing for specialized bio-based DME variants contrasts sharply with standard contract-based long-term offtake agreements for bulk synthetic DME.
Price differentiation stems from feedstock origin, purity grade, and volume scale.
Pricing softness in the synthetic segment reflects intense competition from substitute fuels like LPG.
Chemical manufacturing end-users demonstrate high price sensitivity, while transportation fleets prioritize the environmental premium of bio-based options.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are prevalent for large-volume synthetic DME contracts, particularly within China's domestic market.
Geographic supply concentrates in China for synthetic variants and emerging clusters in Europe for bio-based production.
The supply chain draws from diverse raw materials including coal, natural gas, biomass, and biomethanol, creating varied cost structures.
Feedstock cost volatility, particularly for renewable sources, presents a significant structural risk, while distribution runs through established wholesalers for bulk volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Bio Based and Synthetic Dimethyl Ether Market presents a fragmentation opportunity, driven by the expanding demand for clean-burning fuel additives in the transportation sector.
For Market Incumbents: Entrench market leadership through strategic investments in advanced process control systems to optimize synthetic DME production efficiency.
Secure long-term feedstock contracts for fossil-derived methanol to mitigate price volatility, countering the rise of bio-based specialists.
Leverage extensive global logistics networks to maintain competitive pricing for high-volume fuel additive contracts, particularly against regional competitors.
For New Entrants and Emerging Players: Niche renewable DME applications in North American and European commercial transportation fleets represent the most penetrable entry point.
Target marine fuel applications and hydrogen carrier development, leveraging DME's clean-burning properties to meet decarbonization mandates.
Implement direct sales models to engage end-users seeking traceable, low-carbon fuel sources, bypassing traditional wholesale channels.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized bio-based DME producers with proprietary catalytic processes and strong intellectual property.
Long-term viability hinges on companies capable of navigating divergent regulatory frameworks and securing sustainable feedstocks, making them prime acquisition targets.
The signal to watch is the expansion of national renewable fuel mandates beyond current levels.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | China Energy Ltd expands synthetic DME facilities to meet growing chemical feedstock demand in Asia. |
| Green Manufacturing Transition | European producers invest in bio-based DME plants to align with EU Green Deal decarbonization objectives. |
| Long-term Offtake Agreements | Royal Dutch Shell PLC secures multi-year contracts for DME fuel additives with global transportation fleets. |
| Application Diversification | Oberon Fuels, Inc. develops DME for hydrogen carrier applications, unlocking new energy transport markets. |
| Infrastructure Partnerships | Companies collaborate to build dedicated DME storage and dispensing infrastructure for marine fuel use. |
Research Approach
Findings reconcile primary fieldwork against secondary review of industry association reports, government energy agency data, and company annual reports.
Interviews with plant managers, R&D directors, procurement leads, and logistics managers provided qualitative insights and market validation.
This approach ensured a robust bottom-up assessment, cross-referenced with top-down market sizing from publicly available chemical trade data.
Forecast inputs considered include production method bifurcation, evolving application demand, end-user adoption patterns, and distribution channel shifts across the analysis window.
Compound annual growth rates were derived from historical data, projected regulatory mandate intensity, and anticipated feedstock price trends.
The analytical framework modeled market evolution by segment, including regional regulatory clusters.
Macroeconomic conditions sit as an overlay; deviation in global energy prices or GDP growth would shift the trajectory.
Forecasts reflect current assumptions regarding regulatory stability and technological advancements.
Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Isopentane Market
Bulk Chemicals
Magnesium Carbonate Market
Bulk Chemicals
Polyferric Sulfate Market
Bulk Chemicals
Brazil Magnesium Phosphate Market
Bulk Chemicals
PAG Base Stock Market
Bulk Chemicals
Barium Nitrate Market
Bulk Chemicals
Europe Titanium Dioxide Market
Bulk Chemicals
Potassium Chlorate Market
Bulk Chemicals
Global Basic Chemicals Market
Bulk Chemicals
Global Ground and Precipitated Calcium Carbonate Market
Bulk Chemicals
Global Recovered Carbon Black Market
Bulk Chemicals
Pyrophyllite Powder Market
Bulk Chemicals
Trona Market
Bulk Chemicals
North America Carbon Black Market
Bulk Chemicals
Global Bitumen Market
Bulk Chemicals
Carbon Disulfide Market