
 Global Bitumen Market | 2026-2036
Global Bitumen Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bitumen Market Analysis
Polymer modification technology is rewriting how asphalt binders achieve performance grades in extreme climates. Shell plc leverages its integrated refinery network to sustain specialized bitumen supply across Middle Eastern project corridors. Exxon Mobil Corporation anchors North American demand through its proprietary polymer-blending capabilities. TotalEnergies SE differentiates via bio-based binder research targeting European decarbonization mandates.
Bitumen is a viscous, black hydrocarbon residue derived from vacuum distillation of crude oil, with penetration grades typically ranging from 15 to 450 dmm at 25°C, primarily serving as a binder and waterproofing agent in road construction and building applications. Hot mix products dominate volume flows across mature highway networks, while emulsified formulations represent the fastest-expanding category due to lower energy requirements and cold-weather workability. Paving applications capture the largest value share, though waterproofing commands premium pricing in urban commercial building markets.
The US EPA enforces volatile organic compound limits on cutback bitumen formulations, while the EU F-Gas Regulation and REACH framework constrain solvent-based processing additives across member states. India's BIS certification mandates polymer content thresholds for national highway projects, directly shaping supplier qualification requirements. Stakeholders must monitor evolving green procurement standards and low-temperature performance specifications as infrastructure resilience criteria tighten across jurisdictions.
Market Dynamics
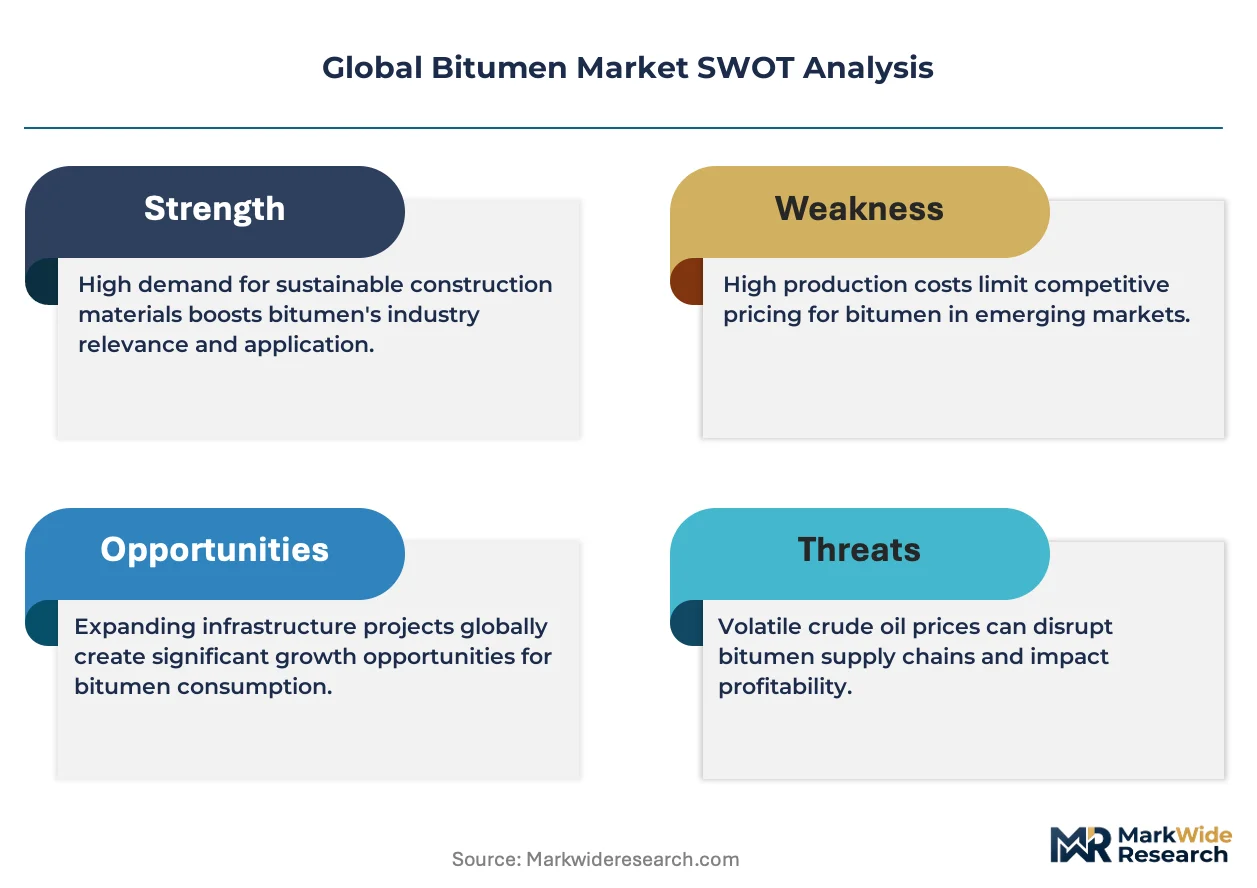
Polymer modification technology is compressing performance-grade specifications while India's PLI scheme redirects public procurement toward certified polymer-modified binders, forcing suppliers to requalify production lines.
Growth Catalysts
- Warm-mix asphalt programs:Road construction agencies across Asia-Pacific are expanding low-temperature paving protocols that reduce energy consumption and extend construction seasons.
- India's PLI scheme:The infrastructure materials incentive mandates polymer content thresholds for national highway projects, redirecting procurement toward modified grades.
- China's provincial highway corridors:Concentrated demand from provincial expansion programs anchors volume flows for penetration-grade and modified binders alike.
Market Restraints
- Crude oil feedstock volatility:Vacuum residue pricing tracks crude differentials, compressing margin predictability for integrated and merchant refiners.
- Middle Eastern supply concentration:Project corridor dependence on Gulf-based integrated producers creates geographic vulnerability for specialized grade availability.
- US EPA VOC limits:Volatile organic compound restrictions on cutback formulations constrain solvent-based processing options across North American paving markets.
Strategic Opportunities
- European bio-based binders:Decarbonization mandates under the EU Green Deal create procurement preference for renewable-content asphalt alternatives.
- Emulsified cold-mix formulations:Lower energy requirements and cold-weather workability position emulsions for seasonal extension in temperate climates.
- Waterproofing premium segments:Urban commercial building specifications command price premiums for high-performance membrane-grade materials.
Industry Challenges
- Polymer blending certification timelines:India's BIS qualification requirements for national highway projects extend supplier onboarding cycles.
- REACH additive constraints:The EU F-Gas Regulation and REACH framework limit solvent-based processing chemistry options, forcing formulation redevelopment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bitumen Market |
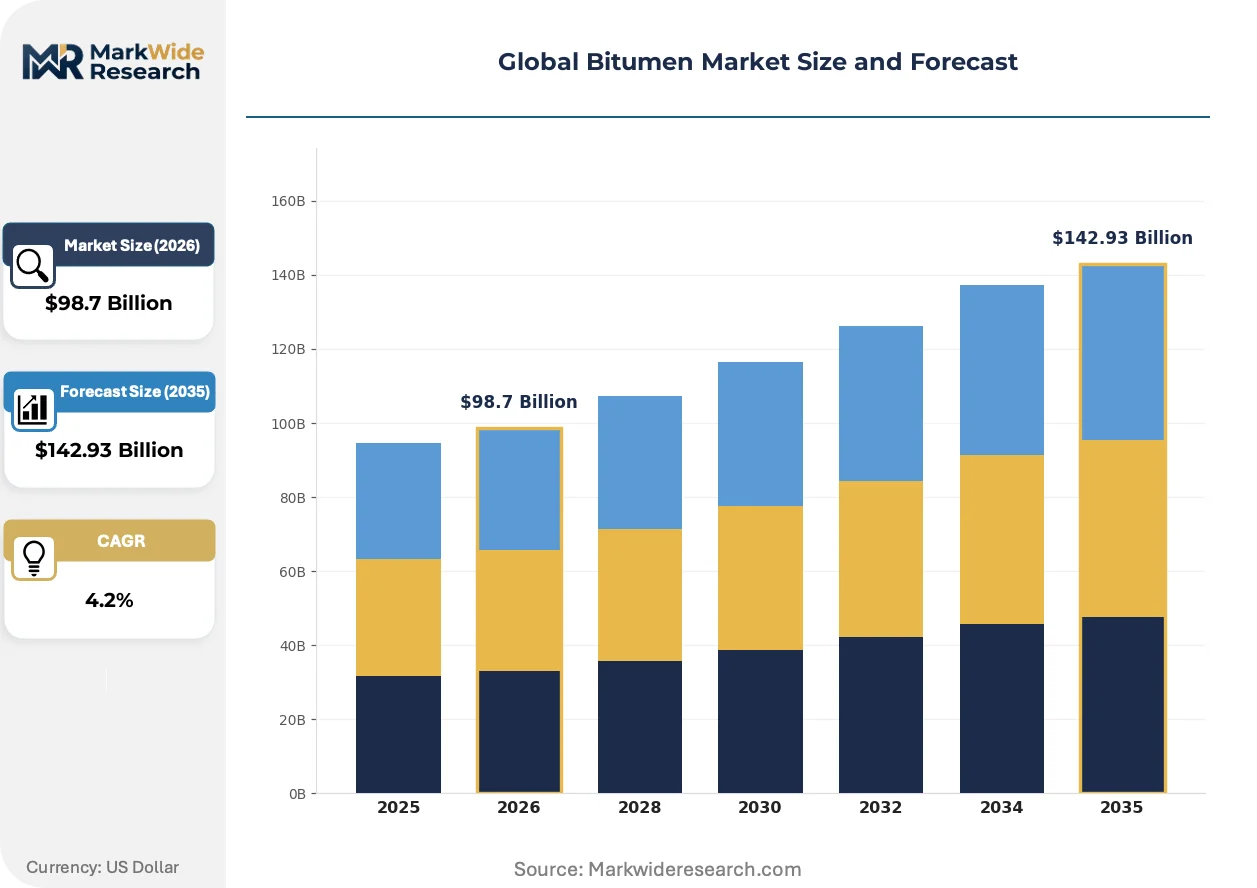
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $142.93 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hot Mix, Cold Mix, Emulsified, Cutback Application: Paving, Waterproofing, Roofing, Insulation End User: Construction, Road Maintenance, Oil & Gas, Manufacturing Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | Shell plc, Exxon Mobil Corporation, BP p.l.c., TotalEnergies SE, China Petroleum and Chemical Corporation, Nynas AB, Chevron Corporation, Gazprom Neft PJSC, Indian Oil Corporation Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bitumen Market Emerging Trajectories
Digital process control and low-carbon binder chemistry are converging to redefine production economics and procurement criteria across paving and waterproofing segments.
Sensor-integrated mixing systems are digitizing temperature and viscosity control across hot-mix asphalt plants. Large-scale paving contractors in Germany and Japan are deploying real-time monitoring to reduce thermal segregation and density variation. This precision infrastructure is digitizing quality assurance protocols that previously relied on manual sampling.
The EU F-Gas Regulation is constraining hydrofluorocarbon-based processing additives across member states. Formulators are pivoting toward bio-solvent and water-based emulsion technologies to maintain product registration. Waterproofing membrane producers in France and the Netherlands face the steepest compliance deadlines for adhesive reformulation.
Performance-based contractor payments are displacing traditional tonnage-based procurement in Australia's state road agencies. Contractors now assume binder-grade risk against measured pavement life metrics. This liability transfer is compressing supplier qualification windows and favoring vertically integrated material-paving operations.
Global Bitumen Market Segmentation
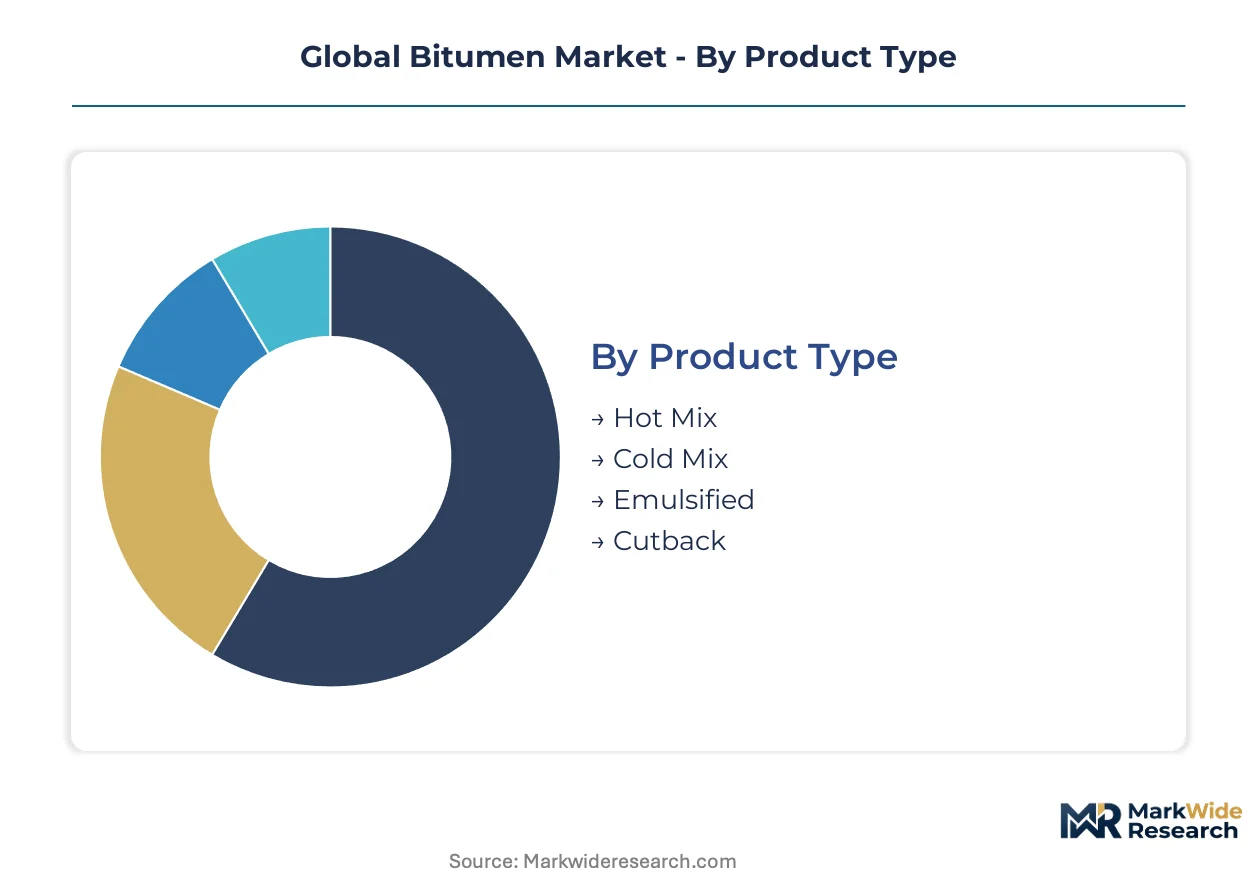
Bitumen procurement patterns diverge sharply across product formulations and end-use specifications. Understanding these fault lines reveals where margin pools concentrate and which technology transitions threaten incumbent positions.
Product Type:
Cost tier differentiation separates energy-intensive hot-processed grades from lower-temperature alternatives that reduce plant emissions and extend construction calendars.
- Hot Mix:Produced at 150-180°C through direct heating of penetration-grade binders with mineral aggregates. India's national highway expansion corridors and China's provincial road programs anchor volume demand for this established category.
- Emulsified:Water-based dispersions enable cold-temperature application without thermal degradation of polymer modifiers. German and Japanese contractors are deploying emulsion-based protocols for seasonal extension and reduced energy costs.
- Cold Mix:Pre-blended aggregates with cutback or emulsion binders for remote location paving without hot-mix plant infrastructure.
- Cutback:Solvent-thinned formulations constrained by US EPA volatile organic compound limits and EU REACH additive restrictions.
Hot Mix commands the established base. The steepest expansion runs through Emulsified.
Application:
Application focus determines pricing power, with infrastructure-scale paving contracts trading volume against building-sector waterproofing premiums.
- Paving:Road construction and airport runway surfacing consume the largest tonnage flows, with performance-based contractor payments in Australia shifting risk allocation from agencies to material-paving integrated operators.
- Waterproofing:High-performance membrane specifications for urban commercial buildings in France and the Netherlands command price premiums driven by EU F-Gas Regulation compliance deadlines for adhesive reformulation.
- Roofing:Built-up roof systems and modified bitumen membranes for industrial and residential structures.
- Insulation:Thermal and acoustic barrier applications in building envelopes and industrial equipment.
Paving captures the volume concentration. Waterproofing delivers the margin expansion.
End User:
Customer type segmentation maps procurement sophistication, from specification-driven public agencies to price-sensitive industrial buyers.
- Construction:General contractors and specialty paving firms managing project-level binder selection against performance warranties.
- Road Maintenance:Municipal and state agencies with recurring resurfacing programs, where India's BIS polymer-content thresholds are redirecting procurement toward certified modified grades.
- Oil & Gas:Pipeline coating and tank lining specifications requiring specialized corrosion-resistant formulations.
- Manufacturing:Waterproofing membrane producers and roofing material fabricators with formulation integration capabilities.
Road Maintenance anchors the demand baseline. Construction offers the technology upgrade pathway.
Distribution Channel:
Supply chain configuration separates bulk logistics for project-scale deliveries from fragmented last-mile access for maintenance and repair segments.
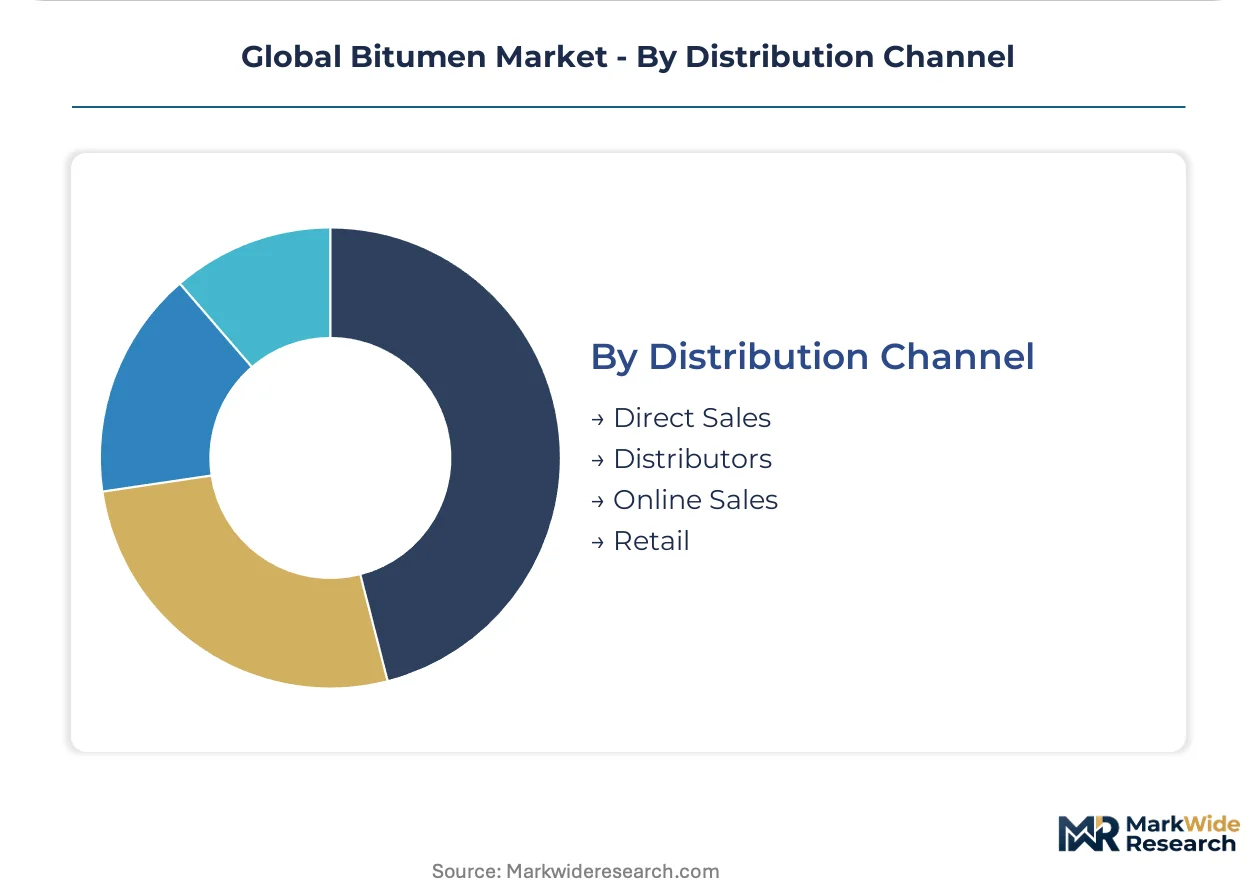
- Direct Sales:Integrated refiners supply specialized polymer-modified grades directly to national highway contractors and large paving consortiums.
- Distributors:Regional stockists bridge geographic gaps between Gulf-based production centers and project corridors across South Asia and Southeast Asia.
- Online Sales:Digital procurement platforms emerging for standardized penetration grades and small-batch emulsion orders.
- Retail:Hardware and construction supply outlets serving residential roofing and minor maintenance applications.
Direct Sales controls the premium grade flow. Distributors enable the geographic reach extension.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in bitumen track refinery capacity dispersion against infrastructure investment cycles. Gulf-based integrated producers dominate export volumes while import-dependent markets absorb specialized grades for polymer-modified specifications.
United States
State transportation departments in Texas and California sustain demand for performance-grade binders through federal highway reauthorization programs. The EPA enforces volatile organic compound limits on cutback formulations, constraining solvent-based processing options. Gulf Coast refineries near Houston anchor domestic supply chains for modified asphalt exports to Latin American project corridors.
China
Provincial highway expansion in Sichuan and Yunnan provinces drives consumption of penetration-grade and polymer-modified binders. The Ministry of Ecology and Environment implements dual carbon goals that pressure refiners to reduce emissions from hot-mix asphalt production. Yangtze River Delta manufacturing clusters near Shanghai specialize in emulsified formulations for seasonal construction extension.
India
National highway authority contracts for Delhi-Mumbai and Bangalore-Chennai corridors absorb certified polymer-modified grades under infrastructure investment programs. The Bureau of Indian Standards mandates polymer content thresholds for public procurement, redirecting supplier qualification toward modified binders. Gujarat refining complexes near Jamnagar supply specialized binders meeting BIS certification requirements.
Germany
Federal transport infrastructure plans prioritize low-temperature paving protocols across Bavaria and North Rhine-Westphalia state networks. The EU F-Gas Regulation constrains hydrofluorocarbon-based processing additives, forcing adhesive reformulation in waterproofing membrane production. Ruhr industrial clusters develop bio-solvent emulsion technologies to maintain product registration under REACH frameworks.
United Arab Emirates
Dubai and Abu Dhabi megaproject pipelines sustain demand for high-performance paving binders in desert climate specifications. The national standards body aligns with Gulf Cooperation Council technical regulations for polymer-modified grade certification. Jebel Ali industrial zones concentrate blending capacity serving export markets across South Asia and East Africa.
Global Bitumen Market Vendor Landscape
On the supply side, the industry is consolidating around integrated refinery operators with captive vacuum residue streams and specialized blending capabilities. Merchant refiners and regional distributors occupy fragmented positions in standardized penetration-grade segments. Two strategic archetypes dominate: Gulf-based integrated producers leveraging feedstock integration, and European specialty blenders targeting bio-based and polymer-modified niches. Capacity expansion and backward integration into polymer supply represent the primary competitive vectors reshaping supplier positioning.
Among integrated energy majors, Shell plc exemplifies the refinery-network archetype with positions across Middle Eastern project corridors, while TotalEnergies SE occupies a specialization tier targeting European decarbonization mandates through bio-based binder research. Indian Oil Corporation Ltd. represents the state-backed integrated model serving domestic infrastructure procurement under BIS certification frameworks.
| Leading Market Players |
|---|
| Shell plc |
| Exxon Mobil Corporation |
| BP p.l.c. |
| TotalEnergies SE |
| China Petroleum and Chemical Corporation |
| Nynas AB |
| Chevron Corporation |
| Gazprom Neft PJSC |
| Indian Oil Corporation Ltd. |
| Others |
Supply Flow & Price Mechanics
Jebel Ali industrial zones concentrate polymer-modified blending capacity that feeds downstream pricing power across South Asian and East African project corridors. Vacuum residue differentials from Gulf-based integrated refiners compress margin predictability for merchant operators serving standardized penetration-grade segments.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure across national highway programs. Three-tier pricing structure across premium polymer-modified, standard penetration-grade, and economy cutback levels separates certified BIS-compliant binders from generic imports. Cost compression in economy tiers is intensifying because crude feedstock volatility erodes merchant refiner margins. Municipal road maintenance agencies exhibit highest price sensitivity, while waterproofing membrane producers absorb premiums for REACH-compliant adhesive formulations.
Supply Chain Analysis
Integrated energy majors Shell, Exxon Mobil, and TotalEnergies hold captive vacuum residue capacity across United States, United Arab Emirates, and European refining complexes. Production draws from Venezuelan heavy crude, Canadian oil sands, and Middle Eastern sour barrels as primary feedstocks. Single-source vulnerability concentrates in Gulf-based specialized grade availability for polymer-modified specifications. Distribution runs through direct sales channels for premium grades and regional distributor networks for standardized penetration products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bitumen market functions as a regulatory-entrenchment defensive moat. India's BIS certification timelines and EU REACH additive constraints create switching costs that protect qualified supplier positions.
For Market Incumbents: Harden polymer blending certification buffers against India's extended BIS qualification cycles. Expand backward integration into SBS polymer supply to secure modifier availability during feedstock crunches. Deepen channel control through direct sales relationships with national highway contractors in China and India.
For New Entrants and Emerging Players: African road maintenance corridors offer the most penetrable white-space target, with fragmented distributor networks and limited local blending capacity. Target emulsified cold-mix formulations for seasonal extension contracts in temperate European markets. Pursue toll-manufacturing partnerships with Gulf-based integrated refiners to bypass capital-intensive vacuum distillation investments.
For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-materials consolidation play because polymer modification technology compresses the qualified supplier base to integrated operators with captive feedstock. Target regional distributors with BIS certification progress in India as acquisition candidates. Monitor India's PLI scheme disbursement velocity as the inflection signal for modified-grade demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Supply | Secures SBS modifier availability against petrochemical price volatility for integrated refiners. |
| BIS Certification Investment | Unlocks national highway procurement eligibility under India's PLI scheme mandates. |
| Emulsified Formulation Capacity Buildout | Captures seasonal extension demand from German and Japanese low-temperature paving protocols. |
| Bio-Solvent Adhesive Development | Maintains waterproofing membrane registration under EU F-Gas Regulation compliance deadlines. |
| Direct Sales Channel Expansion | Bypasses distributor margins for polymer-modified grades in concentrated project corridors. |
Methodological Framework
Operator-level perspectives from refinery operations managers, national highway procurement officers, waterproofing membrane technical directors, and regional distributor principals anchored the qualitative base. Secondary validation drew from customs trade data, Bureau of Indian Standards certification registries, EU ECHA substance databases, and SEC filings from integrated energy majors. Bottom-up volume estimates triangulated against top-down refinery capacity assessments across the analysis window.
Scenario-bracketing framed demand projections across product type, application specification, end-user procurement sophistication, and regional regulatory cluster dimensions. CAGRs derived from elasticity-adjusted infrastructure investment correlations and polymer penetration rate assumptions. Forecast inputs incorporated India's PLI scheme implementation pace and EU Green Deal procurement preference evolution.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Gulf-based integrated producers or accelerated bio-based binder substitution would shift outcomes. Quarterly review of BIS certification queue lengths, EU REACH additive restriction timelines, and crude-heavy differential movements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Hydrogen Bromide Market
Bulk Chemicals
Isovaleryl Chloride Market
Bulk Chemicals
Barium Sulphate Market
Bulk Chemicals
United States Starch Derivatives Market
Bulk Chemicals
Chlorotoluenes Market
Bulk Chemicals
Propionic Acid Market
Bulk Chemicals
US Hydrochloric Acid Market
Bulk Chemicals
Naphthalene Market
Bulk Chemicals
PAG Base Stock Market
Bulk Chemicals
United States Iodine Market
Bulk Chemicals
North America Lactic Acid Market
Bulk Chemicals
Mexico Caustic Soda Market
Bulk Chemicals
Global Persulfates Market
Bulk Chemicals
Calcium Hydrogen Sulphite Market
Bulk Chemicals
Aerospace and Defense Chemical Distribution Market
Bulk Chemicals
Europe Calcium Nitrate Market