
 Europe Titanium Dioxide Market | 2026-2036
Europe Titanium Dioxide Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Titanium Dioxide Market Insights
Premium pigment-grade sulfate and chloride products is bifurcating the competitive landscape into specification-led tiers. Venator Materials PLC leverages its integrated chloride-route capacity across northwest European sites to sustain margin-rich supply to coatings formulators. Chemours Company anchors its position through technology leadership in low-VOC titanium dioxide dispersions for architectural applications. Grupa Azoty competes on backward integration into ilmenite sourcing and captive sulfuric acid loops.
Titanium dioxide denotes a white inorganic pigment with refractive index exceeding 2.4, produced via sulfate digestion of ilmenite or chloride oxidation of synthetic rutile, valued for opacity, UV stability, and chemical inertness across surface coatings and polymer matrices. Rutile grades dominate value capture in automotive and industrial coatings due to superior durability and hiding power, while anatase retains niche strength in paper laminates and select indoor plastics where gloss control matters. The construction end-user segment channels the bulk of volume through distributor networks, though automotive direct sales are gaining traction as OEMs tighten batch consistency requirements.
REACH registration obligations and the EU Green Deal's carbon border adjustment mechanisms are tightening feedstock traceability and process emissions disclosure for all titanium dioxide importers and domestic producers. ECHA's persistent scrutiny of nano-form classifications adds compliance layering for specialty grades targeting cosmetics and food-contact plastics. Stakeholders must monitor the interplay between F-Gas Regulation phase-downs and chloride-process energy sourcing, as electricity-intensive operations face escalating carbon cost pass-through risks.
Market Dynamics
REACH registration obligations and the EU Green Deal's carbon border adjustment mechanisms are forcing titanium dioxide producers to reconfigure process emissions disclosure and feedstock traceability systems across northwest European manufacturing corridors.
Growth Catalysts
- Automotive coating corridor expansion:Germany's OEM direct procurement programs are pulling specification-grade rutile volumes away from distributor channels as batch consistency requirements tighten.
- EU Green Deal industrial decarbonization mandates:Sulfate-process retrofits and energy-efficient chloride line investments are unlocking capital deployment into lower-carbon pigment production.
- Construction chemicals belt demand:Spain's infrastructure rehabilitation programs are channeling volume through formulation houses serving waterproofing and facade systems.
Market Restraints
- Ilmenite supply concentration:Norwegian and Ukrainian feedstock disruptions expose European chloride-route producers to raw material volatility and quality inconsistency.
- F-Gas Regulation phase-downs:Electricity-intensive chloride process operations face escalating carbon cost pass-through risks as refrigerant-dependent cooling systems require replacement.
- Calcium carbonate substitution in paper:Coated paper laminates are shifting toward mineral extenders in cost-sensitive packaging applications where opacity requirements permit.
Strategic Opportunities
- Poland's underpenetrated industrial coatings sector:Automotive supplier parks near Poznan and Wroclaw lack dedicated local chloride-route pigment distribution.
- CSRD-aligned sustainability reporting:Scope 3 emissions disclosure requirements are creating preference premiums for producers with verified low-carbon process certifications.
- Waterborne dispersion technology convergence:Low-VOC architectural formulations are merging with nano-grade surface treatment advances to capture premium interior coating segments.
Industry Challenges
- Chloride-process chemical engineering talent scarcity:Specialized oxidation reactor operation expertise is concentrating among retiring workforce cohorts at northwest European sites.
- ECHA nano-form classification compliance timelines:Specialty grades targeting cosmetics and food-contact plastics face extended safety dossier preparation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Titanium Dioxide Market |
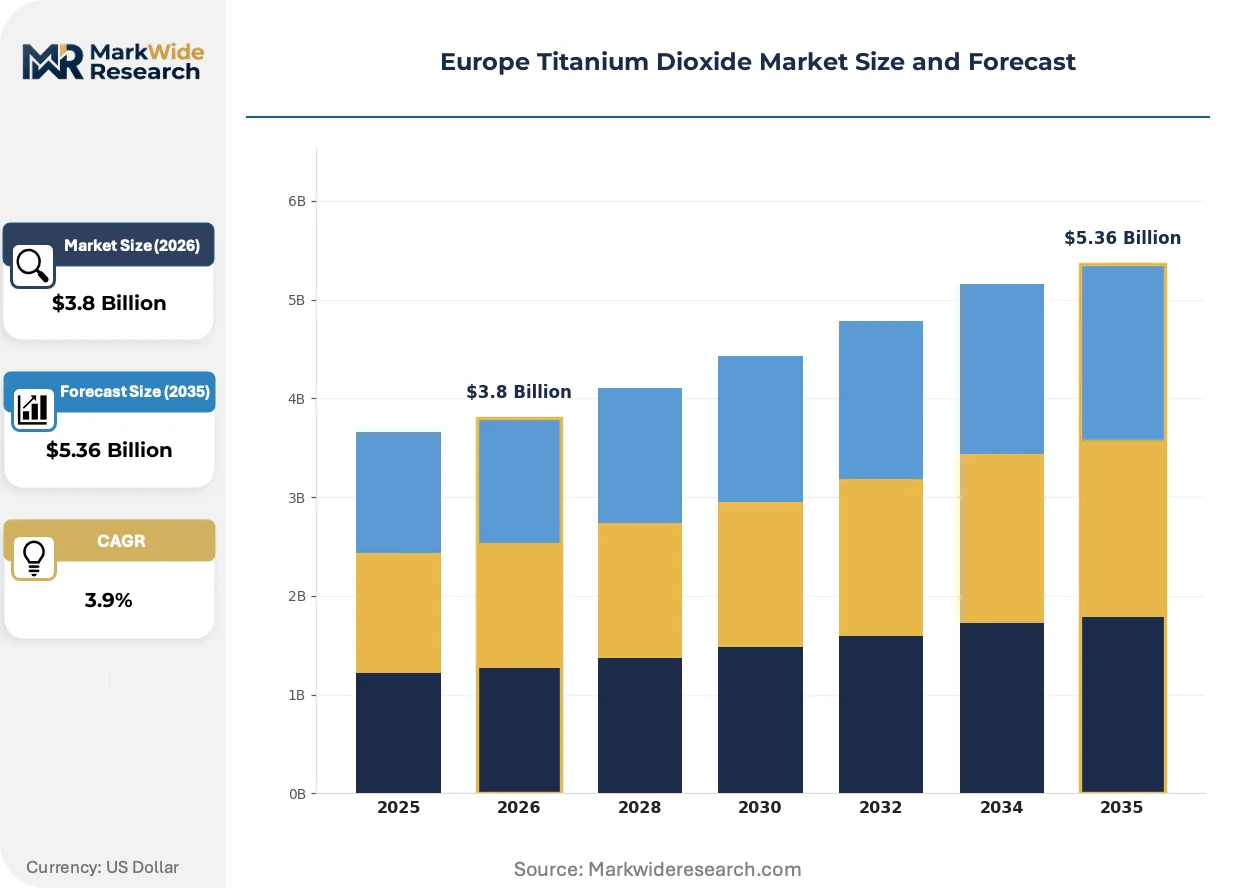
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.36 Billion |
| CAGR (2026 – 2036) | 3.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rutile, Anatase, Pigment Grade, Titanium Slag Application: Plastics, Paints, Coatings, Paper End User: Construction, Automotive, Consumer Goods, Packaging Distribution Channel: Direct Sales, Online, Distributors, Retail |
| Companies Covered | Venator Materials PLC, Precheza a.s., Chemours Company, Grupa Azoty, Cinkarna Celje d.d., Kronos Worldwide Inc., LB Group, Sachtleben Chemie GmbH, Tronox Holdings plc, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Titanium Dioxide Market Trends and Innovations
Process electrification and digital traceability systems are compressing the cost structure of low-carbon pigment production while reshaping how coatings formulators validate supply chain claims.
Chloride-route synthetic rutile feedstock is displacing sulfate-process ilmenite digestion in automotive clearcoat applications where durability specifications are tightening. German and French OEM coating shops are accelerating qualification timelines for these grades. The shift is displacing legacy anatase volumes from high-performance exterior formulations.
REACH Article 33 disclosure obligations now require full substance-of-very-high-concern traceability across titanium dioxide supply chains entering EU member states. Industrial coatings distributors are restructuring procurement documentation systems to capture batch-level chemical safety data. Automotive direct buyers in Stuttgart and Munich are demanding certified compliance packages ahead of tier-2 supplier mandates.
Formulators are consolidating supplier relationships around integrated pigment-dispersion service contracts that bundle technical support with volume commitments. Distributor networks in Iberia and Italy are losing share to direct mill relationships as batch consistency requirements intensify. The compression is most visible in Spain's construction chemicals belt where waterproofing specialists now source chloride-route rutile through nominated single-source agreements.
Europe Titanium Dioxide Market Segmentation
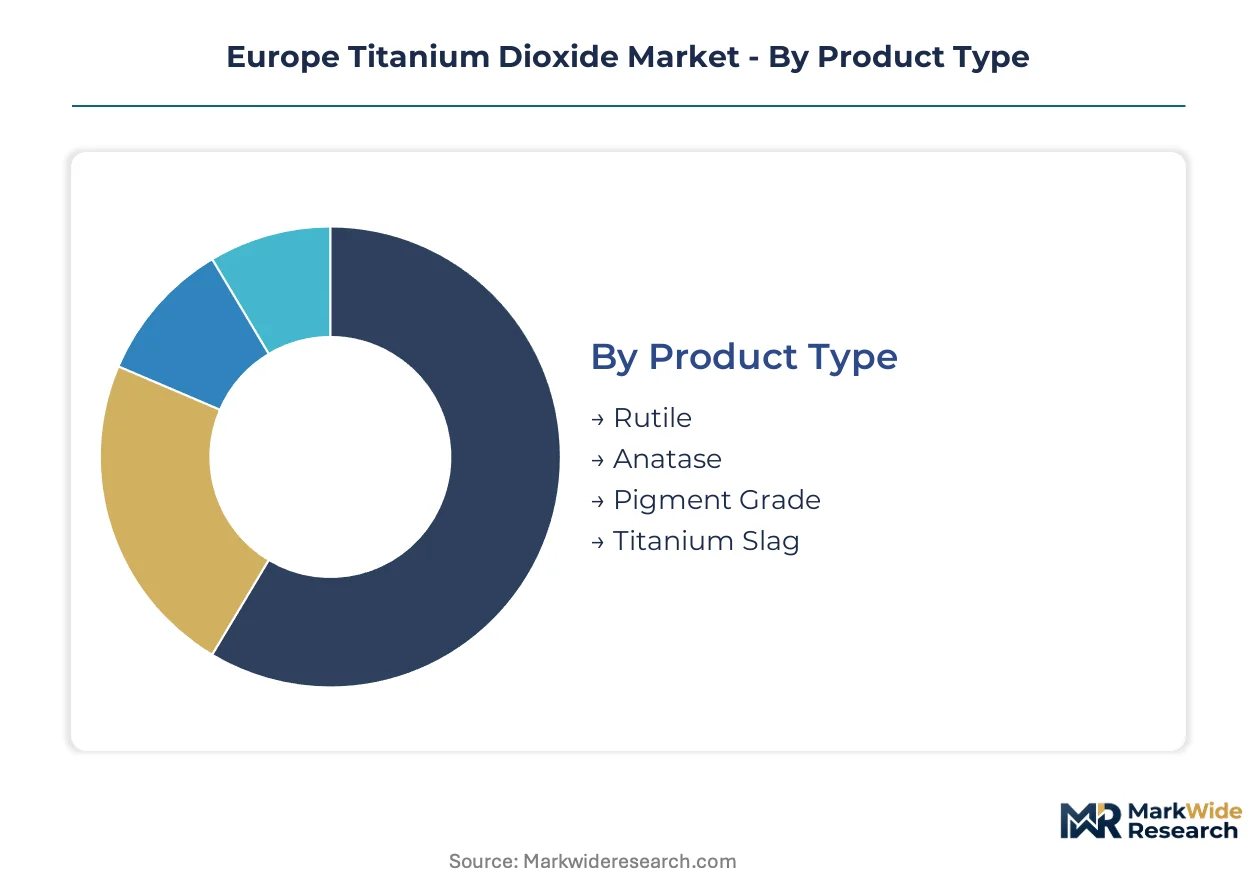
Titanium dioxide segmentation across Europe reflects divergent channel economics and specification intensity. Coatings formulators in Germany and France route high-grade chloride-process rutile through direct mill relationships, while construction distributors in Spain and Italy handle volume sulfate grades. Understanding these channel-product pairings clarifies where margin capture concentrates versus where volume flows.
Product Type:
Rutile and anatase grades split across contrasting channel architectures. Chloride-route rutile moves predominantly through direct sales to automotive OEM coating shops, while sulfate-process anatase circulates via distributor networks serving paper and indoor plastics.
- Rutile:Synthetic rutile produced via chloride oxidation delivers refractive indices above 2.7 and superior weathering resistance. German automotive coating corridors in Stuttgart and Munich pull specification-grade volumes through nominated single-source agreements as batch consistency requirements tighten.
- Anatase:Derived from sulfate digestion of ilmenite, anatase exhibits lower density and controlled gloss characteristics suited to paper laminates and interior plastics. Spain's construction chemicals belt channels these volumes through formulation houses serving cost-sensitive waterproofing systems.
- Pigment Grade:REACH-registered pigment grades with verified nano-form classifications command compliance premiums in cosmetics and food-contact applications across northwest European markets.
- Titanium Slag:Upgraded ilmenite feedstock with elevated TiO2 content serves chloride-process producers seeking to reduce slag generation and acid consumption rates.
By volume, rutile leads across European titanium dioxide consumption. By growth pace, pigment-grade certified products are climbing the fastest as CSRD-aligned disclosure requirements intensify.
Application:
Application segments stratify by formulation complexity and regulatory exposure. High-performance coatings demand documented REACH compliance packages, while paper applications face accelerating substitution pressure from mineral extenders.
- Plastics:Masterbatch compounds in automotive interior and exterior components require UV-stabilized rutile with surface treatments for polymer compatibility. France's consumer goods manufacturers are consolidating procurement around integrated pigment-dispersion service contracts.
- Paints:Architectural formulations across Germany's building renovation programs are shifting toward low-VOC waterborne dispersions. These specifications favor chloride-route rutile with nano-grade surface treatment advances.
- Coatings:Industrial protective and automotive clearcoat applications concentrate demand in specification-led tiers. OEM direct procurement programs in Munich and Stuttgart are displacing legacy distributor relationships.
- Paper:Coated paper laminates for packaging applications face calcium carbonate substitution where opacity requirements permit. Iberian paper mills are reducing titanium dioxide loading rates in cost-sensitive segments.
Coatings applications generate the highest value per ton. Plastics applications are expanding most quickly as automotive lightweighting intensifies polymer substitution for metal components.
End User:
End-user concentration patterns reveal where procurement centralization is advancing versus where distributor fragmentation persists. Automotive direct buyers are tightening supplier qualification timelines, while construction channels remain fragmented across regional formulation houses.
- Construction:Infrastructure rehabilitation programs across Spain's facade systems and waterproofing segments channel volume through formulation houses. These buyers prioritize cost efficiency over specification intensity in commodity-grade applications.
- Automotive:OEM coating shops in Germany's supplier corridors demand certified compliance packages with full SVHC traceability. ECHA's persistent scrutiny of nano-form classifications adds compliance layering for these buyers.
- Consumer Goods:Cosmetics and personal care applications require ECHA-registered grades with documented safety dossiers. French and German formulators are extending qualification timelines for specialty nano-grades.
- Packaging:Food-contact plastics face dual pressure from mineral extender substitution and regulatory compliance costs. Iberian flexible packaging converters are consolidating supplier relationships around verified low-carbon process certifications.
Construction absorbs the largest tonnage. Automotive applications are gaining share fastest as direct procurement programs displace distributor intermediation.
Distribution Channel:
Channel structure is bifurcating between specification-intensive direct relationships and volume-driven distributor networks. EU Green Deal carbon border adjustment mechanisms are forcing documentation system investments that favor larger channel partners with traceability capabilities.
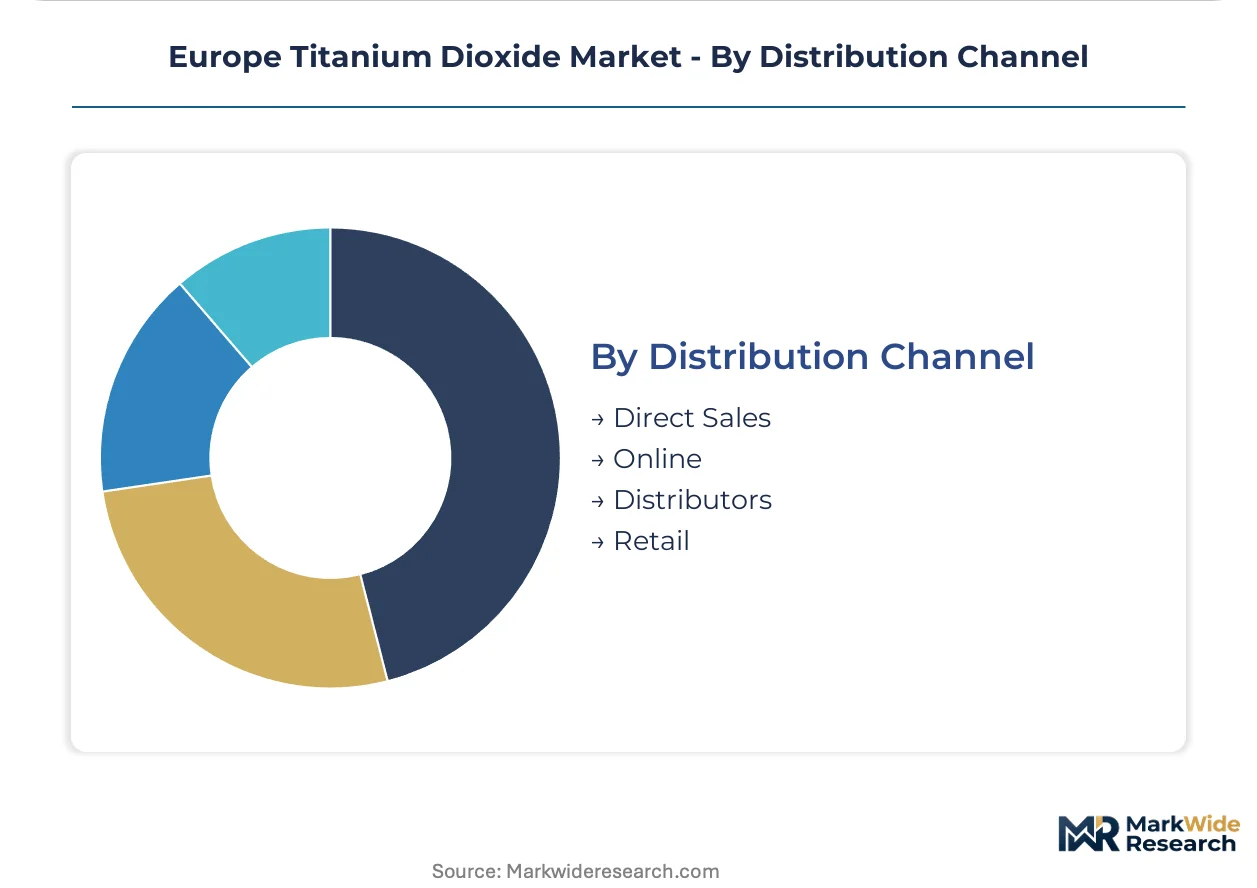
- Direct Sales:Mill-direct relationships dominate automotive and industrial coatings where batch consistency requirements and REACH documentation obligations concentrate. German OEMs in Stuttgart and Munich are mandating certified compliance packages ahead of tier-2 supplier deadlines.
- Online:Digital procurement platforms are capturing spot-market volume for standard-grade sulfate products. These channels serve smaller formulation houses in Poland's underpenetrated industrial coatings sector.
- Distributors:Traditional distributor networks retain construction chemicals volume in Iberia and Italy. Share compression is most visible in Spain's waterproofing segment where single-source agreements are displacing multi-supplier relationships.
- Retail:Small-format retail channels serve maintenance coatings and DIY architectural applications. These segments show limited growth as professional formulation consolidation advances.
Distributors still handle the greatest volume tonnage. Direct sales channels are expanding most quickly as procurement centralization and compliance documentation requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Belgian ports serve as the primary entry corridor for chloride-route feedstock moving into German automotive coating clusters. Rotterdam-Antwerp logistics corridors channel synthetic rutile from Norwegian upgrading facilities toward northwest European pigment plants. France's construction chemicals distributors pull sulfate-grade volumes through Mediterranean shipping lanes.
Germany
Automotive OEM coating shops in Stuttgart and Munich demand specification-grade chloride-process rutile with full REACH Article 33 documentation. The EU Green Deal's industrial decarbonization mandates push producers toward energy-efficient chloride line retrofits. Batch consistency requirements are tightening across Bavaria's supplier corridors as direct procurement programs displace legacy distributor relationships.
France
Architectural formulation houses in Île-de-France shift toward low-VOC waterborne dispersions requiring nano-grade surface treatment advances. ECHA's persistent scrutiny of nano-form classifications adds compliance layering for cosmetics and food-contact applications. The Auvergne-Rhône-Alpes region hosts construction chemicals specialists channeling sulfate-grade volumes into facade and waterproofing systems.
Spain
Infrastructure rehabilitation programs across Andalusia and Catalonia drive demand through formulation houses serving cost-sensitive waterproofing applications. CSRD-aligned sustainability reporting creates preference premiums for producers with verified low-carbon process certifications. Valencia's construction chemicals belt shows accelerating consolidation around single-source chloride-route agreements.
Poland
Automotive supplier parks near Poznan and Wroclaw lack dedicated local chloride-route pigment distribution, creating procurement gaps for tier-2 coating shops. The country's national environmental regulator tightens emissions disclosure requirements for imported pigment volumes. Online digital procurement platforms capture spot-market sulfate-grade volume for smaller industrial formulation houses.
Italy
Traditional distributor networks in Lombardy and Emilia-Romagna retain construction chemicals volume despite share compression from direct mill relationships. REACH registration obligations force restructuring of procurement documentation systems to capture batch-level chemical safety data. Northern Italian flexible packaging converters consolidate supplier relationships around verified low-carbon process certifications for food-contact applications.
Europe Titanium Dioxide Market Competitive Landscape
Listed leaders compete with private specialists across integrated chloride-route capacity and backward feedstock control. The vendor base splits between northwest European integrated producers with captive synthetic rutile supply and regional specialists competing on sulfate-process flexibility. Three archetypes dominate: integrated majors with chloride-oxidation technology leadership, Central European players with captive ilmenite upgrading, and niche specialists serving cosmetics-grade nano-form certifications. Capacity expansion and CSRD-aligned sustainability verification represent the dominant competitive moves reshaping procurement relationships.
Within the integrated major tier, Venator Materials PLC and Chemours Company occupy positions defined by chloride-route technology leadership across northwest European manufacturing corridors. Grupa Azoty anchors the Central European archetype through backward integration into ilmenite sourcing and captive sulfuric acid loops. These three entities exemplify how feedstock control and process technology specialization stratify competitive positioning as ECHA compliance timelines intensify.
| Leading Market Players |
|---|
| Venator Materials PLC |
| Precheza a.s. |
| Chemours Company |
| Grupa Azoty |
| Cinkarna Celje d.d. |
| Kronos Worldwide Inc. |
| LB Group |
| Sachtleben Chemie GmbH |
| Tronox Holdings plc |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at northwest European chloride-route plants shapes both supply concentration and price floors for specification-grade rutile. German automotive OEMs leverage direct procurement scale to compress margins on REACH-certified volumes, while sulfate-process producers in Central Europe absorb feedstock volatility through captive ilmenite upgrading.
Pricing Analysis
Chloride-process rutile commands substantial premiums over sulfate-process anatase across European coatings markets. Pricing stratifies across premium, standard, and economy tiers based on REACH registration status and nano-form certification levels. Cost compression in standard-grade sulfate products is intensifying because Iberian paper mills shift loading rates toward calcium carbonate extenders. Construction distributors in Spain and Italy exhibit highest price sensitivity, while automotive direct buyers in Stuttgart prioritize batch consistency over unit economics.
Supply Chain Analysis
Norwegian synthetic rutile upgrading facilities underwrite feedstock security for northwest European chloride-route producers. Geographic supply concentration centers on Norway, Ukraine, and domestic Central European ilmenite sources. Raw material dependencies encompass sulfuric acid loops, chlorine gas supply, and ilmenite concentrate quality. Single-source vulnerability persists around Norwegian feedstock corridors exposed to energy cost pass-through. Distribution runs through Rotterdam-Antwerp logistics clusters into German automotive coating corridors and Mediterranean shipping lanes serving Iberian construction chemicals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among German automotive OEMs running direct procurement programs, fragmenting distributor influence across legacy channel relationships.
For Market Incumbents: Fortify chloride-route capacity utilization through nominated single-source agreements with Munich and Stuttgart coating shops. Deepen backward integration into synthetic rutile feedstock to offset Norwegian supply volatility. Prioritize CSRD-aligned sustainability certification investments ahead of tier-2 supplier disclosure mandates. For New Entrants and Emerging Players: Differentiate on low-carbon process verification to capture preference premiums under EU Green Deal carbon border adjustment mechanisms. Poland's underpenetrated industrial coatings sector offers the most penetrable white space, with automotive supplier parks near Poznan and Wroclaw lacking dedicated chloride-route distribution. Pursue digital procurement platform partnerships to reach smaller formulation houses outside established mill-direct networks. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated producers with captive feedstock control and REACH-registered nano-form capabilities. Long-term viability over the next decade hinges on process electrification execution and ECHA compliance timeline management. Monitor F-Gas Regulation phase-down implementation as an inflection indicator for chloride-process energy cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Chloride-Route Capacity Expansion | Energy-efficient line investments unlock lower-carbon pigment production qualifying for EU Green Deal procurement preferences. |
| Backward Integration into Synthetic Rutile | Captive feedstock supply insulates margin structures from Norwegian and Ukrainian raw material volatility. |
| CSRD-Aligned Sustainability Certification | Verified Scope 3 emissions disclosure creates preference premiums among automotive direct buyers tightening supplier qualification. |
| Waterborne Dispersion Technology Convergence | Low-VOC architectural formulations merged with nano-grade surface treatments capture premium interior coating segments. |
| Direct Mill Relationship Consolidation | Single-source agreements displace distributor intermediation where batch consistency requirements intensify across German OEM corridors. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs and secondary validation workflows. Stakeholder roles encompassed coatings formulators, automotive OEM procurement leads, chloride-process plant managers, construction chemicals distributors, and ECHA regulatory affairs specialists. Secondary sources included customs and trade flow databases, Cefic industry reports, SEC 10-K filings from listed pigment producers, and REACH registration dossiers. Bottom-up volume modeling triangulated against top-down value estimates derived from production capacity and utilization assumptions.
Across the analysis window, forecasts employed segmented growth rate derivation by product grade, application end-use, and regional production hub. Modeled dimensions spanned rutile versus anatase technology generations, coatings versus plastics versus paper application splits, and direct sales versus distributor channel economics. CAGRs were computed from annual growth rate averaging across the projection horizon. Industry-specific inputs incorporated EU Green Deal carbon cost pass-through assumptions and F-Gas Regulation phase-down impacts on chloride-process energy intensity.
Material uncertainties — feedstock supply disruptions, ECHA nano-form reclassification timelines, and carbon border adjustment mechanism implementation scope — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory stability and technology adoption curves. Practitioners should keep alternative scenarios live as EU industrial decarbonization mandates and REACH compliance layering evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Lithium Bromide Market
Bulk Chemicals
Global Plastics Market
Bulk Chemicals
Potassium Carbonate Market
Bulk Chemicals
Sodium Tungstate Dihydrate Market
Bulk Chemicals
Phosphates Market
Bulk Chemicals
Ethylene and Propylene Market
Bulk Chemicals
Global Linear Alpha Olefins Market
Bulk Chemicals
Caustic Potash Market
Bulk Chemicals
Europe Hydrogen Bromide Market
Bulk Chemicals
Iodine Market
Bulk Chemicals
Europe Acetic Acid Market
Bulk Chemicals
Sodium Perborate Market
Bulk Chemicals
Japan Caustic Potash Market
Bulk Chemicals
Ammonium Nitrate Market
Bulk Chemicals
Sodium Carbonate Market
Bulk Chemicals
Caproic Acid Market