
 Carbon Disulfide Market | 2026-2036
Carbon Disulfide Market Size, Share, and Industry Trends Forecast 2026-2036
Carbon Disulfide Market Analysis
Dimethyl sulfoxide is broadening substitution pressure in solvent applications across pharmaceutical and agricultural chemical manufacturing. Arkema Group leverages backward integration into sulfur feedstocks to protect margin structure in European production. Eastman Chemical Company anchors North American supply through specialized purification capabilities for high-purity grades. Shanghai Baijin Chemical Group dominates captive consumption in viscose fiber manufacturing, linking output directly to textile sector demand.
Carbon disulfide is a volatile, flammable liquid with molecular formula CS₂, produced primarily through the direct reaction of sulfur with carbonaceous materials at elevated temperatures; it serves as the principal reagent for manufacturing cellulose xanthate in viscose rayon production and as a versatile solvent in organic synthesis. Chemical feedstocks command the largest volume share as downstream manufacturers consume bulk quantities for xanthation and thiocarbonyl compound synthesis. Laboratory reagents represent a concentrated margin pool where Merck KGaA and specialty distributors capture premium pricing through high-purity certification and controlled distribution channels.
EPA hazardous air pollutant standards under the Clean Air Act impose stringent emission controls on carbon disulfide manufacturing facilities in the United States, while REACH registration requirements in Europe mandate comprehensive toxicity documentation for commercial volumes. China's MEE enforces parallel emission discharge standards that shape operating permits for Shandong Jinling Group and Luxi Chemical Group facilities. Stakeholders must monitor regulatory divergence between jurisdictions as carbon border adjustment mechanisms and chemical hazard reclassifications threaten to fragment trade flows and relocate production economics.
Market Dynamics
REACH registration requirements in Europe are tightening toxicity documentation standards, forcing producers to restructure purification investments while viscose fiber manufacturers in Asia absorb feedstock cost volatility through captive sulfur sourcing.
Growth Catalysts
- Viscose rayon capacity expansion:Textile manufacturers in India are commissioning new xanthation lines that lock in chemical feedstock offtake. Cellulose xanthate synthesis remains the dominant volume driver.
- REACH chemical safety protocols:European handling mandates are accelerating facility upgrades that favor larger producers with compliance infrastructure. This regulatory friction is filtering out marginal capacity.
- Sulfur feedstock backward integration:Producers with captive sulfur recovery from petroleum refining are insulating margin structures against raw material swings. Shandong and Jiangsu provinces concentrate these integrated operations.
Market Restraints
- Dimethyl sulfoxide substitution:Pharmaceutical and agrochemical formulators are switching to DMSO for polar aprotic solvent applications. This technical displacement threatens volume in high-purity solvent segments.
- EPA hazardous air pollutant standards:US emission controls under the Clean Air Act impose scrubber and capture equipment costs that disadvantage smaller domestic producers. Compliance capex runs into tens of millions per facility.
- Production concentration in China:Over two-thirds of global capacity sits with Shandong Jinling Group and Luxi Chemical Group. Geographic supply clustering creates vulnerability to regional energy rationing or environmental enforcement waves.
Strategic Opportunities
- Carbon border adjustment mechanisms:European importers face embedded emissions tariffs that reward low-carbon sulfur sourcing. Producers with biogenic or recovered sulfur credentials can capture premium positioning.
- High-purity laboratory reagent channels:Merck KGaA and specialty distributors command pricing power through certification. Independent producers can wedge into this margin pool via pharmacopeia compliance investments.
- Cellulose nanomaterial synthesis:Emerging applications in advanced materials research are testing carbon disulfide for thiocarbonyl reagent chemistry. Pilot programs at German technical universities signal potential volume diversification.
Industry Challenges
- Process safety engineering talent scarcity:Volatile organic handling and pyrophoric sulfur operations require specialized expertise. European and North American facilities report gaps in experienced operations leadership.
- Legacy equipment replacement cycles:Continuous carbon disulfide reactors installed in the 1990s face integrity inspections under tightened pressure vessel codes. Replacement timelines compress against permitting delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbon Disulfide Market |
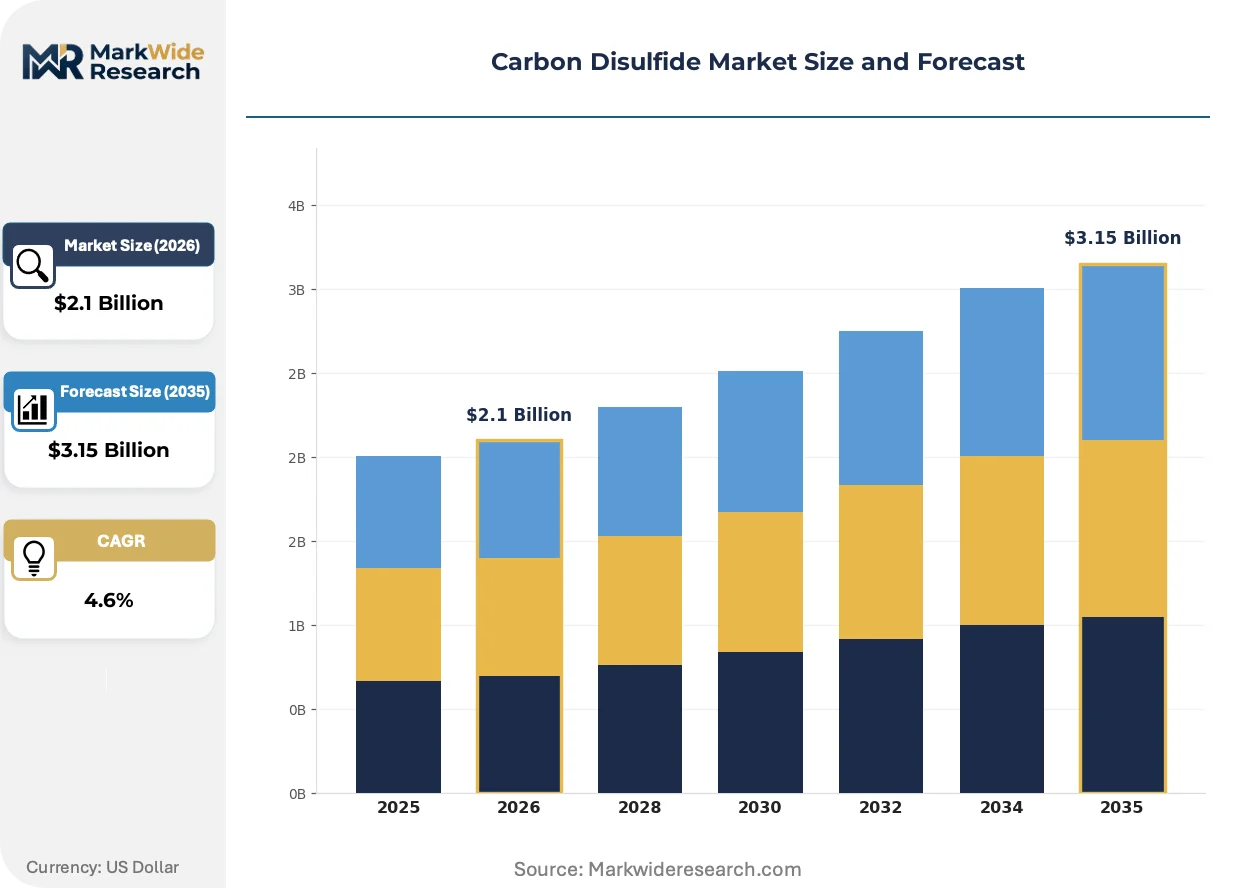
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Solvents, Chemical Feedstocks, Laboratory Reagents, Extraction Agents End Use Industry: Textiles, Pesticides, Pharmaceuticals, Rubber Form: Liquid, Gas, Solid, Aqueous Application: Solvent Cleaning, Chemical Synthesis, Rubber Processing, Pesticide Production |
| Companies Covered | Arkema Group, Eastman Chemical Company, Akzo Nobel N.V., Merck KGaA, Shanghai Baijin Chemical Group, Shandong Jinling Group, China Xingfa Group, Luxi Chemical Group, Aditya Birla Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbon Disulfide Market Emerging Trajectories
Continuous reactor technology and emission capture systems are displacing batch operations, while regulatory divergence between jurisdictions fragments trade economics and rewards compliance-first capital deployment.
Membrane separation technology for carbon disulfide purification is consolidating quality tiers in the solvent market. Pharmaceutical manufacturers in Germany and Switzerland are specifying sub-ppm impurity grades that only membrane-polished material satisfies. This technical bar is compressing spot market availability and tethering supply relationships to multi-year purification investment cycles.
China's MEE emission discharge standards are tightening particulate and sulfur compound limits for Shandong and Jiangsu production clusters. Facilities must install real-time monitoring and secondary containment that adds operating overhead. The most affected segment is merchant market supply, where smaller producers lack capital for sequential upgrade waves.
Textile sector procurement is compressing contract durations from annual to quarterly terms as viscose fiber manufacturers hedge sulfur cost volatility. This pattern concentrates in India and Bangladesh, where rayon spinners face downstream apparel pricing pressure. Suppliers with integrated sulfur positions are resisting spot exposure, forcing a restructuring of traditional offtake relationships.
Carbon Disulfide Market Segmentation
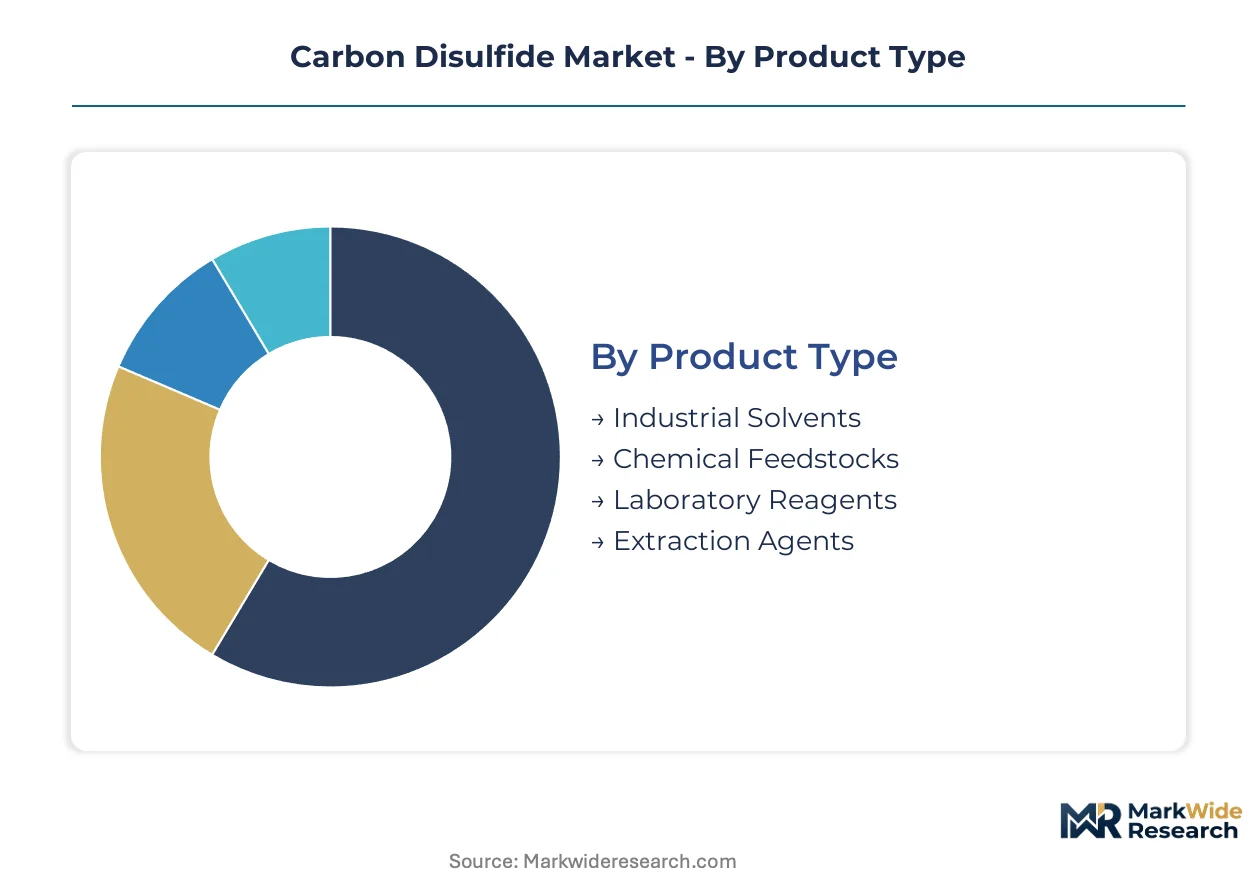
Carbon disulfide's volatility and toxicity create strict handling protocols that segment demand by purity grade and application risk profile. Manufacturers configure purification investments around end-use specifications rather than commodity volume plays.
Product Type:
Upgrade cycles in purification infrastructure are reclassifying product tiers as membrane separation technology displaces legacy distillation for high-specification grades.
- Chemical Feedstocks:Bulk-grade material with sulfur content specifications tailored for xanthation chemistry in viscose rayon manufacturing. Demand concentrates in Shandong and Jiangsu province clusters where captive sulfur integration insulates producers from raw material volatility.
- Industrial Solvents:Medium-purity grades serving rubber processing and pesticide formulation with broader impurity tolerances. Procurement runs through chemical distributors in Germany and India where REACH and BIS compliance documentation shapes supplier qualification timelines.
- Laboratory Reagents:Pharmacopeia-certified grades for analytical chemistry and pharmaceutical research.
- Extraction Agents:Food-grade and botanical extraction specifications with residual solvent testing protocols.
Volume placements concentrate in Chemical Feedstocks; the faster expansion belongs to Laboratory Reagents.
End Use Industry:
Margin structures diverge sharply between commodity textile offtake and specialty pharmaceutical contracts.
- Textiles:Viscose rayon production consumes carbon disulfide for cellulose xanthate formation, the dominant volume sink globally. Indian spinners in Tamil Nadu and Gujarat are commissioning xanthation capacity that locks in multi-year chemical feedstock commitments.
- Pharmaceuticals:High-purity solvent applications for active pharmaceutical ingredient synthesis command certification premiums. Swiss and German formulators specify sub-ppm impurity grades that only membrane-polished material satisfies, compressing qualified supplier pools.
- Pesticides:Thiocarbonyl reagent chemistry for agricultural chemical manufacturing.
- Rubber:Vulcanization accelerator production and rubber processing aids.
Revenue concentration sits with Textiles; Pharmaceuticals are climbing the fastest.
Form:
Physical state determines packaging, transport mode, and regulatory hazard classification across supply chains.
- Liquid:Standard shipping container and tanker transport for bulk industrial applications. EPA hazardous air pollutant standards and REACH registration requirements impose emission controls during loading and unloading operations at Rotterdam and Houston terminals.
- Gas:Specialized vapor recovery systems for closed-loop industrial processes.
- Solid:Stabilized formulations for laboratory and controlled-release applications.
- Aqueous:Diluted solutions for specific extraction and cleaning protocols with reduced flammability profiles.
Commercial scale favors Liquid; specialized applications are driving Aqueous formulation development.
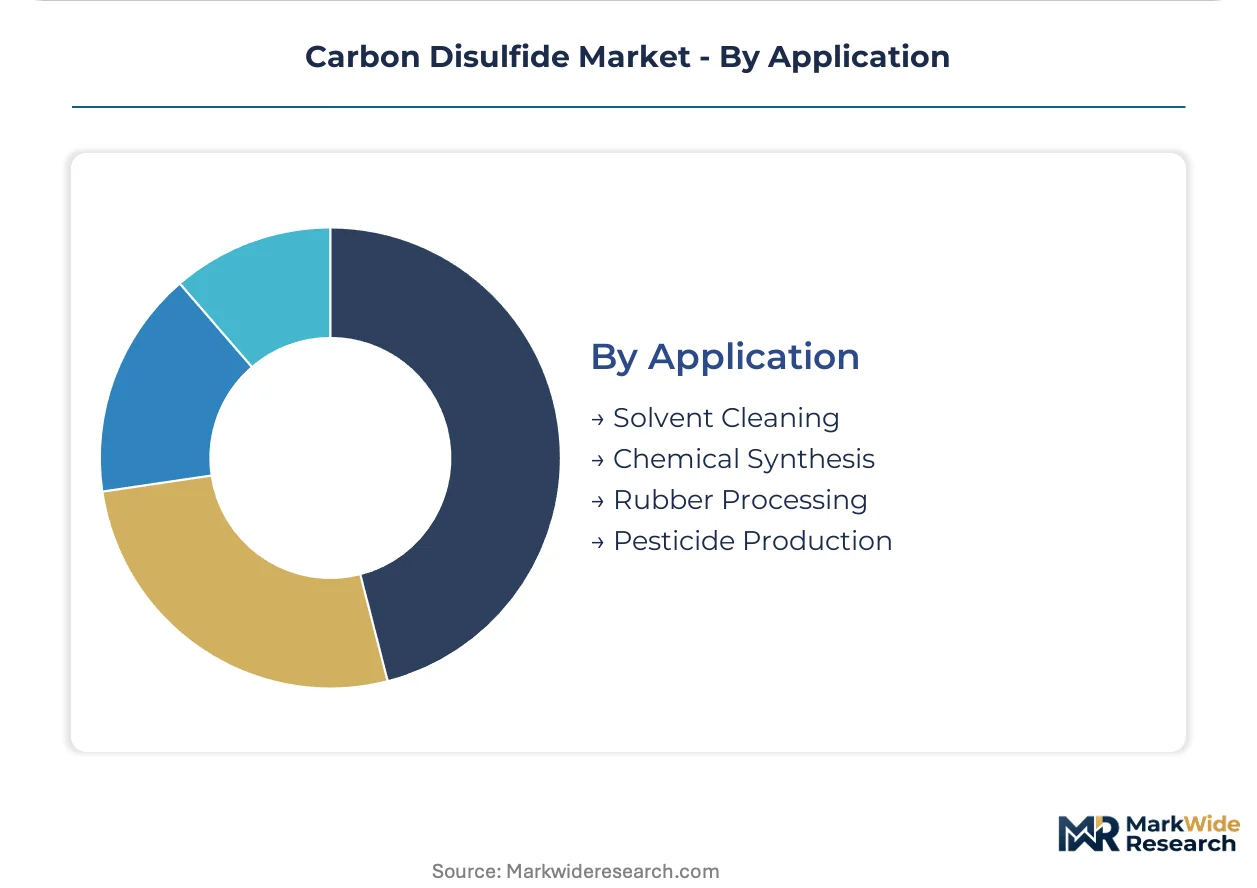
Application:
Process chemistry requirements stratify demand by solvent recovery economics and emission control intensity.
- Chemical Synthesis:Thiocarbonyl compound production and organosulfur chemistry requiring precise stoichiometric control. China's MEE enforces real-time emission monitoring for facilities running continuous reactor operations in Shandong province.
- Solvent Cleaning:Degreasing and precision cleaning with vapor recovery mandates.
- Rubber Processing:Vulcanization chemistry and accelerator manufacturing.
- Pesticide Production:Intermediate synthesis for agricultural active ingredients.
Operational scale clusters in Chemical Synthesis; regulatory compliance investments are expanding fastest in Solvent Cleaning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Viscose fiber manufacturing concentrates demand in Asia, while European regulatory stringency and North American emission controls fragment supply economics across jurisdictions.
China
Shandong and Jiangsu provinces host the dominant production clusters for carbon disulfide manufacturing, with Shandong Jinling Group and Luxi Chemical Group operating integrated facilities. MEE emission discharge standards enforce real-time monitoring and secondary containment systems that raise operating overhead for merchant market suppliers. The Yangtze River Delta corridor is witnessing consolidation as smaller producers exit under environmental compliance pressure.
India
Tamil Nadu and Gujarat are commissioning new xanthation capacity that locks in multi-year chemical feedstock commitments from viscose rayon spinners. BIS compliance documentation shapes supplier qualification timelines for industrial solvent procurement. The textile belt around Surat and Ahmedabad is absorbing feedstock cost volatility through shorter quarterly contract terms rather than annual agreements.
Germany
REACH registration requirements mandate comprehensive toxicity documentation for commercial volumes, favoring larger producers with dedicated compliance infrastructure. The Rhine-Ruhr industrial region concentrates purification investments for high-purity grades serving pharmaceutical manufacturers. Arkema Group leverages backward integration into sulfur feedstocks to protect margin structure against raw material swings.
United States
EPA hazardous air pollutant standards under the Clean Air Act impose scrubber and capture equipment costs that disadvantage smaller domestic producers. The Gulf Coast refining corridor provides captive sulfur recovery opportunities for integrated chemical producers. Houston terminals face stringent emission controls during loading and unloading operations that compress spot market availability.
Japan
METI industrial chemical guidelines align with international hazard classifications for carbon disulfide handling and transport. The Kansai region around Osaka maintains specialized purification capabilities for electronics-grade applications. Domestic producers are evaluating membrane separation technology investments to meet sub-ppm impurity specifications from pharmaceutical formulators.
Carbon Disulfide Market Vendor Landscape
Backward integration into sulfur feedstocks dominates the current landscape as producers seek insulation from raw material volatility. The market structure concentrates around integrated chemical conglomerates with captive supply chains, alongside specialized distributors serving laboratory reagent channels. Three archetypes define positioning: sulfur-integrated manufacturers, high-purity specialists, and regional merchant suppliers. Capacity expansion in Asia and compliance-driven consolidation in Europe represent the dominant competitive vectors reshaping supply economics.
Among European-based chemical conglomerates, Arkema Group exemplifies the sulfur-integrated archetype through feedstock control strategies. Eastman Chemical Company anchors North American positioning through specialized purification infrastructure. Shanghai Baijin Chemical Group represents the captive consumption model, linking production directly to downstream viscose fiber manufacturing. These three occupy distinct competitive positions without direct overlap in end-use specialization or geographic served markets.
| Leading Market Players |
|---|
| Arkema Group |
| Eastman Chemical Company |
| Akzo Nobel N.V. |
| Merck KGaA |
| Shanghai Baijin Chemical Group |
| Shandong Jinling Group |
| China Xingfa Group |
| Luxi Chemical Group |
| Aditya Birla Chemicals |
| Others |
Supply Flow & Price Mechanics
Backward integration into sulfur feedstocks anchors both supply security and pricing power for carbon disulfide producers, with Shandong Jinling Group and Luxi Chemical Group leveraging captive petroleum refining byproducts to buffer margin structures against raw material swings while commanding premium positioning in contract negotiations.
Pricing Analysis
Volume placements concentrate in chemical feedstock grades where contract durations are compressing from annual to quarterly terms, while laboratory reagents command certification premiums through pharmacopeia compliance. Price differentiation rests on purity grade and REACH documentation depth, with membrane-polished material capturing substantial premiums from Swiss pharmaceutical formulators. Cost compression in industrial solvent tiers is intensifying because of DMSO substitution pressure. Textile sector buyers in Surat and Ahmedabad exhibit highest price sensitivity, whereas German pharmaceutical procurement shows lowest elasticity due to qualification rigidity.
Supply Chain Analysis
China's MEE emission discharge standards are reshaping sourcing patterns by forcing facility upgrades that filter out marginal merchant suppliers. Production concentrates in China, India, and Germany, with raw material dependencies spanning elemental sulfur, carbonaceous feedstocks, and specialized catalysts. Single-source vulnerability runs through the Yangtze River Delta corridor where environmental enforcement waves threaten concentrated capacity. Distribution runs through Rotterdam and Houston terminals with stringent EPA and REACH emission controls during loading operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon disulfide market structure favors consolidation plays as REACH toxicity documentation requirements and MEE emission standards force subscale producers into exit, concentrating viable capacity around integrated sulfur positions and compliance-heavy purification investments.
For Market Incumbents: Deepen backward integration into sulfur recovery infrastructure to insulate margin structures against feedstock volatility, while accelerating membrane separation technology deployment to capture pharmacopeia-certified reagent premiums before Merck KGaA consolidates laboratory channels. Prioritize multi-year offtake agreements with Indian viscose spinners commissioning xanthation capacity in Tamil Nadu and Gujarat. For New Entrants and Emerging Players: Membrane purification technology offers a technology-first wedge into the high-purity solvent segment where sub-ppm impurity specifications have compressed qualified supplier pools. Target white-space in European laboratory reagent distribution where REACH documentation barriers filter incumbent expansion, and pursue carbon border adjustment mechanism positioning through biogenic sulfur sourcing credentials. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to sulfur-integrated chemical conglomerates seeking geographic footprint expansion, with financial sponsor interest limited by environmental liability exposure and capital intensity. Long-term viability hinges on regulatory compliance infrastructure rather than commodity volume positioning. Watch for MEE enforcement wave intensity in Shandong province as inflection indicator for Chinese supply rationalization timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sulfur Recovery | Captive feedstock supply from petroleum refining insulates Arkema and Shandong Jinling from raw material volatility. |
| Membrane Separation Technology Deployment | Pharmaceutical manufacturers in Basel and Frankfurt specify membrane-polished grades that legacy distillation cannot satisfy. |
| REACH Compliance Infrastructure Investment | Comprehensive toxicity documentation mandates favor larger European producers with dedicated regulatory affairs capabilities. |
| Long-term Supply Agreement Restructuring | Quarterly contract terms in Surat and Ahmedabad force suppliers to absorb sulfur cost volatility or integrate upstream. |
| Carbon Border Adjustment Positioning | Biogenic sulfur credentials enable premium positioning for European importers facing embedded emissions tariffs. |
Methodological Framework
Document review covered customs and trade flow databases, ECHA REACH registration filings, and MEE emission discharge records, complemented by interviews with plant managers at Shandong and Jiangsu production facilities, procurement leads at Indian viscose spinners, and distribution channel partners in Rotterdam and Houston. Secondary validation drew from ACC and Cefic chemical industry reports, SEC 10-K filings for listed producers, and pressure vessel code inspection databases. Bottom-up capacity modeling and top-down demand triangulation from textile sector xanthation capacity expansions were cross-referenced for convergence.
Output projections span volume and value across the analysis window, with segmentation modeling across purity grade tiers, end-use industries, packaging formats, and regional production hub classifications. CAGRs were derived from elasticity-adjusted demand forecasting incorporating viscose rayon capacity commissioning timelines and regulatory compliance cost trajectories. Key inputs included sulfur feedstock price volatility assumptions and substitution elasticity estimates for DMSO displacement in pharmaceutical solvent applications.
Several conditions sit outside the modeled scope, including unannounced MEE enforcement actions, REACH chemical hazard reclassifications, and carbon border adjustment mechanism implementation timing. Forecasts reflect documented assumptions about continuous reactor technology adoption rates and emission capture equipment deployment schedules. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
North America Glycerol Market
Bulk Chemicals
Global Acrylic Esters Market
Bulk Chemicals
Encapsulated Sodium Bicarbonate Market
Bulk Chemicals
Mercaptan Scavenger Market
Bulk Chemicals
Aluminum Chloride Hexahydrate Market
Bulk Chemicals
US Trona Market
Bulk Chemicals
Potassium Chloride Market
Bulk Chemicals
Sodium Hydrosulfide Market
Bulk Chemicals
Cresylic Acid Market
Bulk Chemicals
Ammonium Dichromate Market
Bulk Chemicals
Castor Wax Market
Bulk Chemicals
Asia-Pacific Lithium Chloride Market
Bulk Chemicals
Ammonium Carbonate Market
Bulk Chemicals
Hydrogen Bromide Market
Bulk Chemicals
Global Sebacic Acid Market
Bulk Chemicals
Hydrochloric Acid Electrolysis Market